
Canada Mechanical, Electrical, and Plumbing (MEP) Services Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
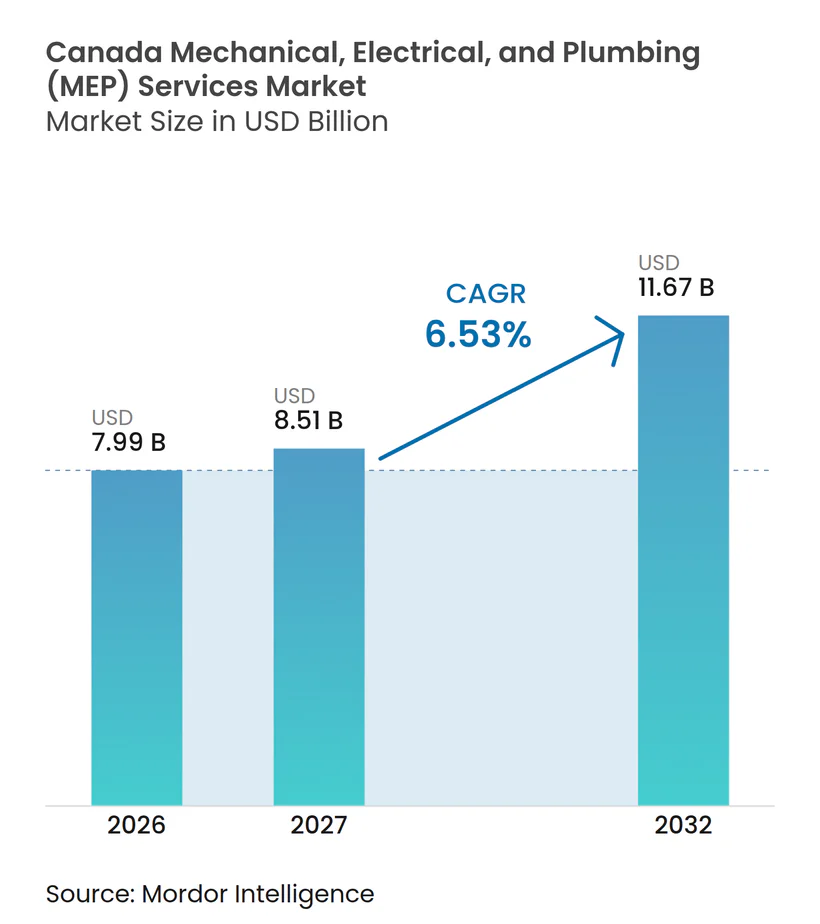
| Base Year Market Size (2026) | USD 7.99 Billion |
| Market Size (2027) | USD 8.51 Billion |
| Market Size (2032) | USD 11.67 Billion |
| Growth Rate (2027 - 2032) | 6.53 % |
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Canada Mechanical, Electrical, and Plumbing (MEP) Services Market Analysis by Mordor Intelligence
The Canada Mechanical, Electrical, And Plumbing Services Market size was valued at USD 7.99 billion in 2026 and is estimated to grow from USD 8.51 billion in 2027 to reach USD 11.67 billion by 2032, at a CAGR of 6.53% during the forecast period (2027-2032).
Federal infrastructure programs, building decarbonization rules, and data center development are changing the work available to Canadian contractors. The 2025 National Model Codes put greenhouse gas reduction requirements into the National Building Code and National Energy Code for Buildings, which raises technical requirements for both new construction and retrofits. This change favors firms that can model energy performance, coordinate systems, and commission completed projects. The Canada MEP services market is also moving toward performance-based contracts, which can shift procurement away from the lowest initial bid and toward technical capability. Labor constraints and long delivery times for electrical and mechanical equipment continue to shape bidding, scheduling, and procurement decisions across the Canada MEP services market.
Key Report Takeaways
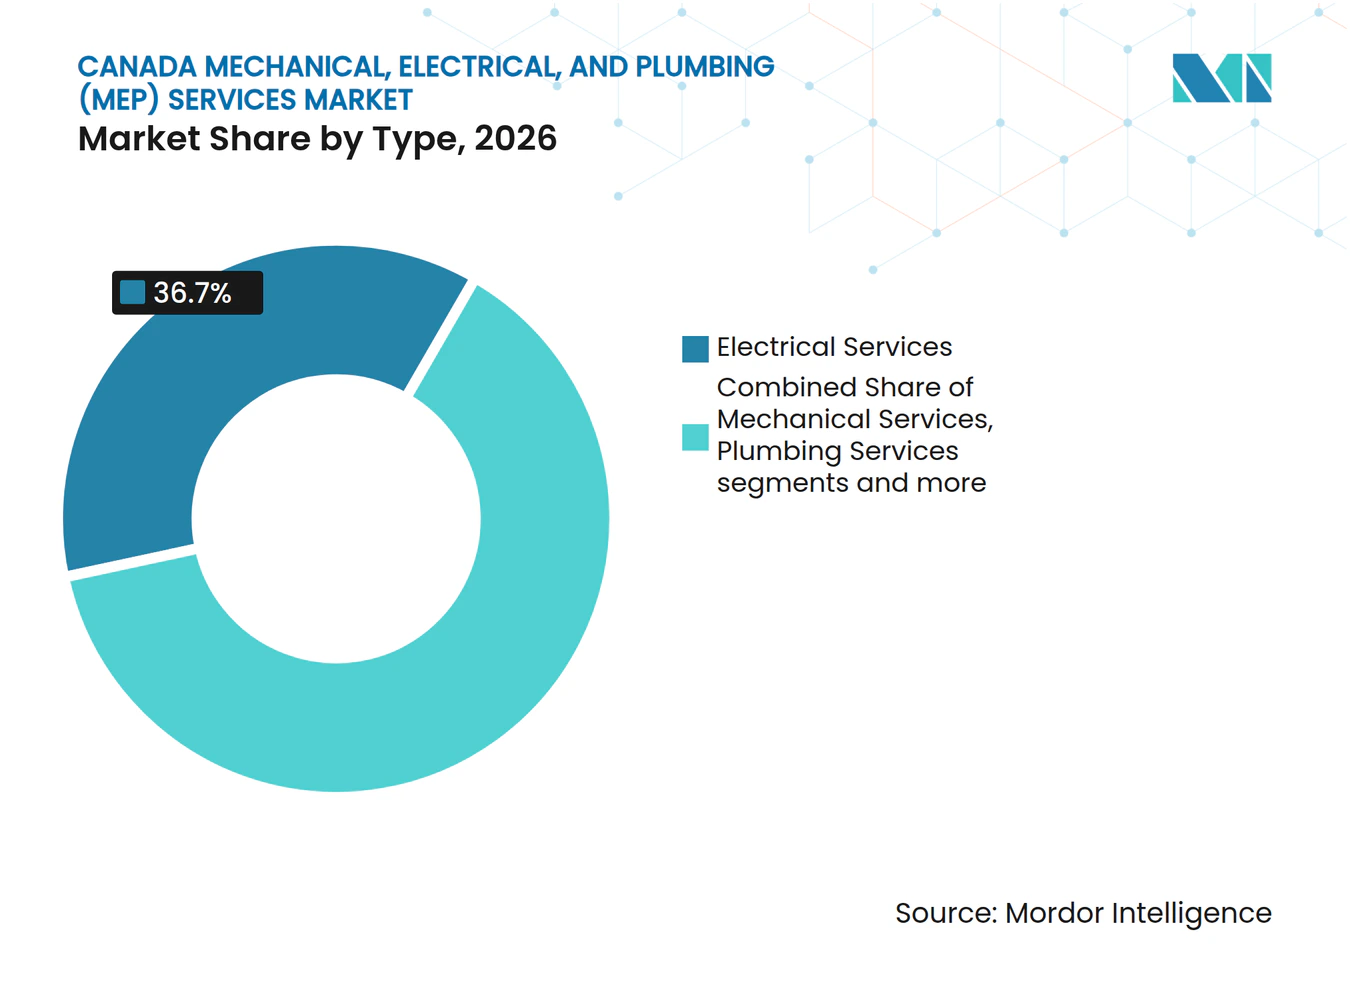
- By type, electrical services held 36.7% of the Canada MEP services market share in 2026, while integrated MEP services are forecast to grow at a 7.32% CAGR through 2032.
- By service type, design and engineering held 34.6% of the Canada MEP services market share in 2026, while managed / performance-based services are forecast to grow at a 7.45% CAGR through 2032.
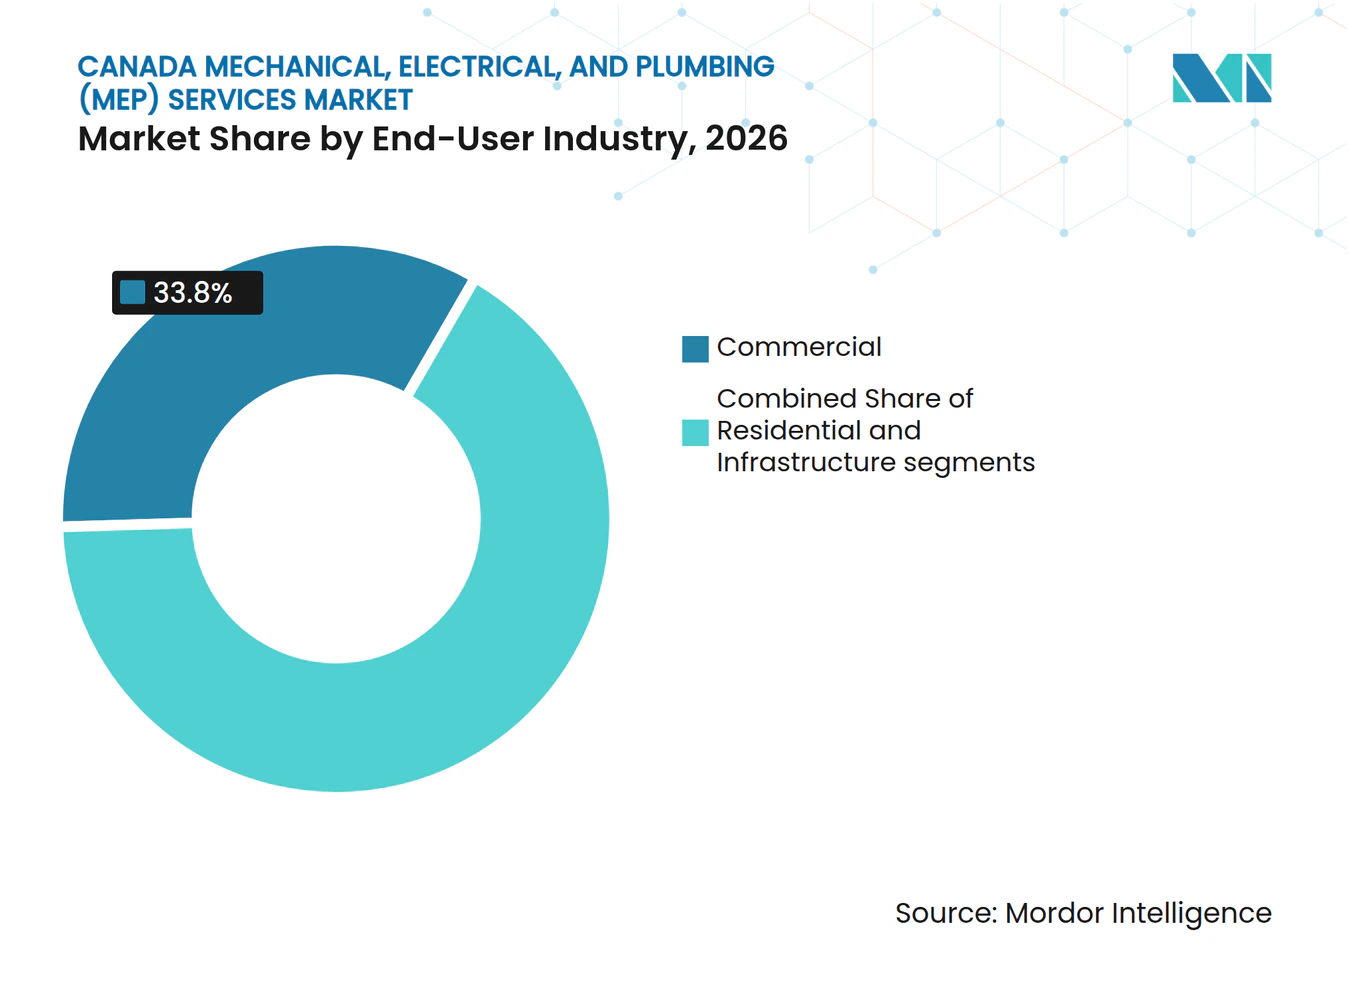
- By end-user industry, commercial accounted for 33.8% of the Canada MEP services market size in 2026, while infrastructure is forecast to grow at a 7.56% CAGR through 2032.
- By province, Ontario held 39.1% of the Canada MEP services market in 2026, while Alberta is forecast to grow at a 7.88% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Canada Mechanical, Electrical, and Plumbing (MEP) Services Market*
| Drivers | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Commercial and Industrial Construction Supporting New-Build MEP Installation Demand | +1.2% | Ontario, Alberta, British Columbia, with spillover to Quebec and Atlantic Canada | Short term (≤ 2 years) |
| Building Decarbonization Supporting HVAC Electrification | +1.1% | British Columbia, Quebec, Ontario, and the emerging demand in Alberta | Medium term (2-4 years) |
| Aging Building Stock Supporting Retrofit and Replacement Demand | +0.9% | Ontario and Quebec, particularly institutional-heavy areas | Medium term (2-4 years) |
| Stricter Energy-Efficiency Standards Raising System Requirements | +0.8% | National, with early gains in provinces adopting the 2025 National Model Codes | Long term (≥ 4 years) |
| Data Center Expansion Raising Demand for Electrical and Cooling Infrastructure | +0.7% | Alberta and Saskatchewan, with secondary demand in Quebec and British Columbia | Short term (≤ 2 years) |
| Healthcare and Institutional Investment Supporting Complex MEP Projects | +0.6% | British Columbia, Ontario, and Quebec | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Commercial and Industrial Construction Sustaining New-Build MEP Volumes
Canada’s commercial and industrial construction activity is generating steady demand for mechanical, electrical, and plumbing (MEP) installation services. Corporate office fit-outs, logistics facilities, and sustainable industrial campuses are expanding the project opportunities available to MEP contractors. JCB Construction Canada’s interior fit-out for CN Rail’s new headquarters in downtown Montreal illustrates how corporate relocations can require extensive mechanical, electrical, and plumbing upgrades across multiple floors. These projects require close coordination, as heating, cooling, lighting, power distribution, plumbing, controls, and fire protection systems must operate seamlessly within occupied office environments.
Industrial projects are also becoming more complex as developers pursue energy-efficiency and sustainability standards. MONTONI and the Fonds immobilier de solidarité FTQ are scheduled to begin construction of Écoparc Laval 15 in September 2025. The project is a multistage industrial campus in Laval, Quebec, designed to meet LEED Silver and Zero Carbon Building certification requirements. Buildings that meet these standards require efficient HVAC systems, heat recovery equipment, building controls, advanced lighting, and higher-capacity electrical infrastructure. These requirements increase the value of MEP work relative to conventional warehouses. A geographically diverse pipeline of office, logistics, and industrial projects can provide regional contractors with a more consistent flow of installation work while reducing their dependence on a limited number of large projects.
Building Decarbonization Initiatives Are Accelerating HVAC Electrification
Canada’s shift toward lower-carbon buildings is creating demand for heat pump retrofits and electrified heating, ventilation, and air conditioning (HVAC) systems. The Building Decarbonization Alliance reported in 2026 that heat pump shipments exceeded air-conditioner shipments in Canada and that heat pumps were the primary heating source in 8% of homes. Demand differs by province because incentives, grid capacity, and existing heating systems are not uniform. British Columbia and Quebec offer more established conditions for electrification work, while Alberta still has cost advantages from natural gas infrastructure. This regional difference gives contractors reason to align equipment expertise and staffing with local policy and utility conditions. The modernized National Capital Region District Energy System shows the scale of work tied to public-building decarbonization. The project replaced aging steam infrastructure with low-temperature hot water and electric chillers across more than 14 kilometers of piping[1]. Such projects require mechanical, electrical, controls, and commissioning work to be planned as one system. A 2026 Energy and Buildings study found that ground-source heat pumps reduced energy use by 29% and greenhouse gas emissions by 78% against natural-gas baselines in Canadian residential applications. These results support the technical case for electrified retrofits, even though adoption rates remain uneven.
Aging Building Stock Driving MEP Retrofit and Replacement Demand
Older commercial and institutional properties are creating demand for replacement of boiler plants, electrical switchgear, plumbing risers, and air-handling equipment. Many of these systems were installed before current energy requirements and now approach the end of their useful service lives. Retrofit work differs from new construction because contractors must protect building operations and work within limited site access. These conditions place more value on coordination, reliable schedules, and trade management than on labor cost alone. The Canada MEP services market can therefore support more specialized work in facilities that remain occupied during construction. A 2026 hospital chiller optimization project in Nanaimo illustrates this type of combined scope. The work included heat recovery chillers, revised hydronic piping, electrical panels, and structural work[2]. The different systems cannot be treated as isolated packages because each affects the others during installation and operation. Contractors with preconstruction coordination, offsite fabrication, and healthcare commissioning experience can be better placed for this work. Retrofit projects may have lower gross volume than large new buildings, but their operating constraints can reduce direct price competition.
Stricter Energy-Efficiency Standards Reshaping System Specifications
The 2025 National Model Codes make operational greenhouse gas limits part of Canadian building requirements for the first time. The codes cover the National Building Code, National Plumbing Code, National Fire Code, and National Energy Code for Buildings. Higher performance tiers require more careful specification of heat recovery, controls, ventilation, pumps, and electrical systems. The change increases the importance of current code knowledge and energy modeling during design and construction. It also raises the technical requirements for firms working on projects that seek higher National Energy Code for Buildings performance. Natural Resources Canada proposed updated product standards in Amendment 19 of the Energy Efficiency Regulations in June 2026. The proposal covers HVAC equipment, commercial refrigeration, and industrial motors[3]. Higher product standards can influence project specifications long before equipment is installed. Contractors and engineers must account for equipment availability, controls compatibility, and installation requirements when selecting systems. The Canada MEP services market is likely to favor firms that keep code and product knowledge current across provinces.
Restraints Impact Analysis of Canada Mechanical, Electrical, and Plumbing (MEP) Services Market*
| Restraints | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Skilled-Trade Shortages Limiting Contractor Capacity and Raising Labor Costs | -1.0% | National, most acute in Ontario and British Columbia | Long term (≥ 4 years) |
| Elevated Construction Costs Reduce Project Feasibility | -0.8% | Ontario and British Columbia, with structural effects in major centers | Medium term (2-4 years) |
| Long Lead Times for Specialized Electrical and Mechanical Equipment | -0.5% | Alberta and Saskatchewan data center pipeline, plus Ontario | Short term (≤ 2 years) |
| Provincial Code and Licensing Differences Increasing Compliance Complexity | -0.4% | Contractors operating across Quebec, Ontario, and British Columbia | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Skilled-Trade Shortages Constraining Contractor Capacity
Skilled-trade availability remains a central constraint on MEP delivery in Canada. It affects crew availability, bid pricing, project schedules, and the ability of contractors to accept additional work. Meeting federal housing and infrastructure goals will require 410,000 to 520,000 new tradespeople by 2030, with recruitment needs expected to increase further when retirements are considered. Those pressures make predictable staffing more valuable for firms that work across multiple projects. They also strengthen the appeal of service contracts that allow crews to be assigned over longer periods. A shortage not only affects the number of workers available on a site. It can increase the importance of training, retention, prefabrication, and careful sequencing. Firms with managed-service portfolios can spread training costs across longer customer relationships. They may also maintain steadier crew utilization than firms that depend only on one-time construction packages. This creates a practical advantage for contractors that combine installation work with maintenance and performance obligations in the Canada MEP services market.
Elevated Construction Costs Compressing Project Feasibility
Higher construction costs continue to limit the number of projects that can proceed as planned. Wage pressure, supply-chain uncertainty, and metal-price volatility can change project budgets after early cost estimates are prepared. Building owners may delay, resize, or repackage work when costs rise. This increases competition for projects that remain viable and can reduce margins on standard unit-rate work. The effect is strongest where high equipment content and imported components form a large part of a project budget. Cost pressure also changes the services that contractors seek to provide. Integrated delivery and bundled service agreements can show owners the total operating value of a system rather than only its initial installed cost. This approach can support longer revenue relationships where maintenance, controls, and energy performance are included. It does not remove affordability limits, but it can give owners a clearer basis for evaluating lifecycle costs. The Canada MEP services market, therefore, has an incentive to move toward scopes that combine design, installation, and ongoing operation.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Canada Mechanical, Electrical, and Plumbing (MEP) Services Market Segment Analysis
By Type:
Electrical Services Lead as Integrated MEP Services Gains GroundElectrical services held 36.7% in 2026, supported by spending on power distribution, switchgear, and lighting systems. Commercial buildings, healthcare campuses, and data centers need dependable electrical capacity and increasingly complex controls. Electric vehicle charging, heat pumps, and computing loads add to the need for upgrades. Contractors with high-voltage and medium-voltage engineering experience are therefore important participants in this part of the Canada MEP services industry. Electrical scope also requires early procurement because switchgear and related equipment can affect construction schedules.
Integrated MEP services are the fastest-growing type at a 7.32% CAGR through 2032. In the Canada MEP services market, clients use a single provider to reduce interface risk across mechanical, electrical, and plumbing work on complex projects. This model can improve coordination when design decisions affect multiple building systems. Mechanical services remain supported by HVAC retrofits and heat pump adoption. Plumbing services have a smaller revenue contribution, but changes to the 2025 National Plumbing Code also apply to alterations of existing buildings. Design-assist delivery and early contractor involvement favor providers that can coordinate BIM models and offsite fabrication.



By Service Type:
Managed / Performance-Based Services Accelerate as Design and Engineering Retains ScaleDesign and engineering accounted for 34.6% in 2026. Institutional, healthcare, and infrastructure projects need detailed MEP engineering before construction contracts are awarded. This work determines equipment selection, system interfaces, controls, and commissioning requirements. It can also reduce later construction changes when the design is coordinated early. WSP’s University of Ottawa Faculty of Health Sciences project showed the density of institutional work, with mechanical, electrical, civil, and information technology systems delivered under a prime-design arrangement.
Managed / performance-based services are the fastest-growing service type at a 7.45% CAGR through 2032. In the Canada MEP services market, this model uses multiyear arrangements in which contractors have ongoing responsibility for uptime and energy performance. The National Capital Region District Energy System operates through a 35-year public-private partnership that includes Equans Canada, PCL Construction, and Black & McDonald. Installation, testing, and commissioning remain tied to new buildings and large retrofits. Maintenance, repair, and retrofit work is also becoming more important as owners extend asset life and pursue energy targets. Plan Group’s work at the University of Toronto Scarborough Academy of Medicine and Integrated Health used prefabricated pump skids, boiler assemblies, and 4D BIM sequencing.
By End-User Industry:
Commercial Leads the Market While Infrastructure Records the Fastest GrowthCommercial held 33.8% in 2026, supported by office fit-outs, retail locations, healthcare facilities, and post-secondary buildings. These settings require mechanical, electrical, and plumbing work that supports occupant comfort, safety, operations, and digital systems. Many commercial properties are also addressing aging equipment and new energy performance expectations. The Canada MEP services industry benefits when owners invest in upgrades rather than only new floor space. Large urban centers retain the widest range of commercial maintenance, renovation, and fit-out work.
Infrastructure is the fastest-growing end-user segment at a 7.56% CAGR through 2032. In the Canada MEP services market, data centers, water-treatment upgrades, and transit electrification require a more engineering-intensive scope than conventional civil projects. The proposed 300 MW Saskatchewan data center development illustrates the need for high-capacity power distribution, precision cooling, and electrical redundancy. Healthcare campuses show a similar overlap between institutional and infrastructure requirements. The University of Toronto Scarborough project and hospital renewal work in Ontario and British Columbia require high uptime and detailed system coordination. Residential demand remains material, although weaker private housing starts in 2026 moderated its growth compared with infrastructure and commercial.

Geography Analysis
Ontario held 39.1% of the market share in 2026, supported by major institutional and infrastructure procurement programs. Healthcare, transit, and post-secondary projects need integrated design and construction capability, which narrows the field for the largest contracts. The province also supplies engineering capacity to work in other parts of Canada. Alberta is forecast to record the fastest provincial growth, at a CAGR of 7.88% during 2027–2032. Data center and energy infrastructure projects are expanding the need for electrical distribution, cooling, and precision mechanical systems. Alberta, therefore, offers work that differs from conventional process-plant and oil-sands contracting.
British Columbia has a sustained pipeline of all-electric institutional projects. The Quw’utsun Valley Hospital requires integrated heating and cooling systems, including water-to-water heat recovery chillers and air-source heat pumps. These system choices require contractors to coordinate equipment, controls, piping, electrical service, and commissioning. Quebec operates under a distinct labor and licensing environment administered by the Commission de la Construction du Québec. This framework can create a higher entry threshold for firms from other provinces. Continued activity in Quebec's healthcare and civil infrastructure sectors supports demand, even as parts of private investment remain cautious.
Saskatchewan, Manitoba, Atlantic Canada, and the territories made up a smaller share of the Canada MEP services market in 2026. Their project pipelines still create opportunities where specialized systems or remote delivery conditions are involved. Saskatchewan’s data center development can support future demand for high-capacity electrical and cooling work. Manitoba’s wastewater infrastructure work can draw national engineering and construction capacity. Aecon received an award in July 2026 for the City of Winnipeg’s North End Water Pollution Control Centre upgrade, with Stantec providing design services. The Atlantic provinces offer a more retrofit-heavy workload because building electrification is progressing there. Contractors with cold-climate heat-pump experience can differentiate in this setting. Regional strategies must account for local codes, labor availability, utility conditions, and equipment supply.
Competitive Landscape
Market Concentration
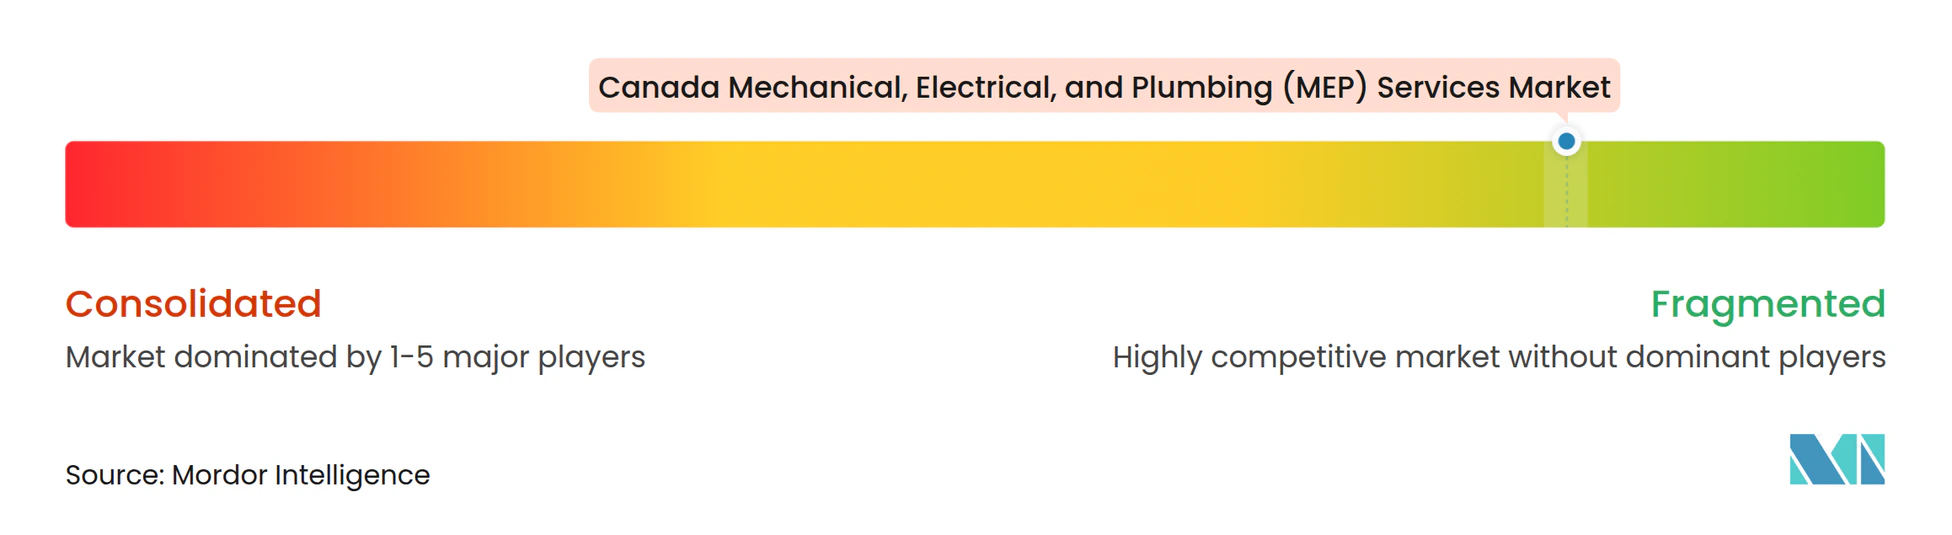
The Canada MEP services market is fragmented, with regional specialty contractors and engineering firms competing across project types. Competition is more concentrated in large institutional and infrastructure projects, which require broad technical capabilities and multiyear delivery capacity. EllisDon, Black & McDonald, Modern Niagara, Plan Group, and Equans Canada compete for design-build, managed-service, and multi-trade contracts, supported by cross-provincial operations, digital project delivery, and post-construction service capabilities.
Acquisitions are helping companies strengthen their technical capabilities. In September 2026, Englobe acquired Calgary-based Reinbold Engineering Group, adding more than 90 professionals specializing in energy modeling, commissioning, and sustainable mechanical design. This reflects demand for integrated services that connect design, construction, system performance, and commissioning. Regional specialists also compete through focused expertise and digital coordination. Plan Group's University of Toronto Scarborough project used 4D Building Information Modeling (BIM) sequencing and prefabricated mechanical assemblies.
Large performance-based contracts, such as the National Capital Region District Energy System, favor firms with the financial and operational capacity to provide continuous services. Code expertise, energy modeling tools, and commissioning credentials are becoming increasingly important in competitive bids. Opportunities remain in midmarket performance contracts and offsite MEP modules for remote and Indigenous communities. Overall, specialist firms can compete through technical differentiation and efficient project delivery, although complex contracts favor companies with broader resources.
Canada Mechanical, Electrical, and Plumbing (MEP) Services Industry Leaders
-
Ainsworth Inc.
-
Black & McDonald Limited
-
Bird Construction Inc.
-
EllisDon Corporation
-
Enersolv Design & Build Ltd.
- *Disclaimer: Major Players sorted in no particular order
Canada Mechanical, Electrical, and Plumbing (MEP) Services Market Companies Covered in this Report
- Ainsworth Inc.
- Black & McDonald Limited
- Bird Construction Inc.
- EllisDon Corporation
- Enersolv Design & Build Ltd.
- Equans Canada
- Modern Niagara Group Inc.
- Plan Group Inc.
- PCL Construction
- Stantec Inc.
- WSP Global Inc.
- AECOM Canada ULC
- MCW Group of Companies
- Williams Engineering Canada Inc.
- Smith + Andersen
- DIALOG
- Dillon Consulting Limited
- Morrison Hershfield
- AtkinsRéalis
- Jacobs
- Le Groupe Conseil Génipur Inc.
- HIDI Group
- MAGH Engineering Inc.
- D.B.K. Engineering Ltd.
- Mansour Engineering Ltd.
- Integral Group
Recent Industry Developments in Canada Mechanical, Electrical, and Plumbing (MEP) Services Market
- September 2026: Englobe acquired Reinbold Engineering Group, a Calgary-based mechanical engineering and building performance firm with more than 90 professionals. The acquisition expanded Englobe’s capacity for energy modeling, commissioning, and sustainable MEP design across Western Canada and Ontario. The acquired team has offices in Calgary, Edmonton, Vancouver, Kelowna, and Toronto, giving Englobe broader coverage across key regional project centers.
- September 2026: The Canada Infrastructure Bank (CIB) reached financial close on a CAD 100 million (approximately USD 71 million) loan with Morguard Corporation, establishing the CAD 145 million (approximately USD 103 million) Morguard ReNew Fund to support deep energy retrofits across approximately 30 multi-suite residential, retail, office, and industrial properties in Ontario and Quebec. Planned Mechanical, Electrical, and Plumbing (MEP) upgrades include mechanical system optimization, fuel switching to heat pumps, and district energy integration with NERVA Energy, designing and implementing the work targeting a minimum 30% GHG emissions reduction and approximately 35,246 tons of annual CO₂e savings.
- May 2026: Bird Construction was selected as Bell AI Fabric's preferred construction partner for a 300 MW, CAD 1.7 billion (approximately USD 1.21 billion) high-density data center in the Rural Municipality of Sherwood, Saskatchewan, the largest purpose-built data center in Canada at the time of announcement. Construction is underway across all four buildings, with two data halls targeted for service in the first half of 2027, supporting a substantial MEP scope across electrical power, cooling, and mechanical infrastructure.
Canada Mechanical, Electrical, and Plumbing (MEP) Services Market Report Scope
Segmentation Overview
| Mechanical Services |
| Electrical Services |
| Plumbing Services |
| Integrated MEP Services |
| Design and Engineering |
| Installation, Testing, and Commissioning |
| Maintenance, Repair, and Retrofit |
| Managed / Performance-Based Services |
| Residential |
| Commercial |
| Infrastructure |
| Ontario |
| Quebec |
| British Columbia |
| Alberta |
| Rest of Canada |
| By Type | Mechanical Services |
| Electrical Services | |
| Plumbing Services | |
| Integrated MEP Services | |
| By Service Type | Design and Engineering |
| Installation, Testing, and Commissioning | |
| Maintenance, Repair, and Retrofit | |
| Managed / Performance-Based Services | |
| By End-User Industry | Residential |
| Commercial | |
| Infrastructure | |
| By Province | Ontario |
| Quebec | |
| British Columbia | |
| Alberta | |
| Rest of Canada |
Key Questions Answered in the Report
What is the expected growth rate for Canada MEP services through 2032?
The Canada MEP services market is forecast to grow at a 6.53% CAGR from 2027 to 2032, reaching USD 11.67 billion.
Which service type is expected to grow fastest in Canada?
Managed / performance-based services is expected to grow at a 7.45% CAGR through 2032 as owners use longer contracts for uptime and energy performance.
Which MEP service type held the largest share in 2026?
Electrical services led by type with a 36.7% share in 2026, supported by power distribution, controls, and electrification upgrades.
Why are building retrofits important for Canadian MEP providers?
Aging facilities need replacement equipment, while decarbonization requirements increase demand for efficient heating, cooling, electrical, and control systems.
Which province offers the fastest expected growth for MEP services?
Alberta is forecast to expand at a 7.88% CAGR through 2032, supported by data center and energy infrastructure activity.
How are national building codes affecting MEP contractors?
The 2025 National Model Codes raise the importance of energy modeling, equipment selection, controls, and commissioning for code-compliant projects.