
Vietnam Contract Logistics Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
| Base Year Market Size (2026) | USD 3.5 Billion |
| Market Size (2027) | USD 3.87 Billion |
| Market Size (2032) | USD 6.25 Billion |
| Growth Rate (2027 - 2032) | 10.06 % |
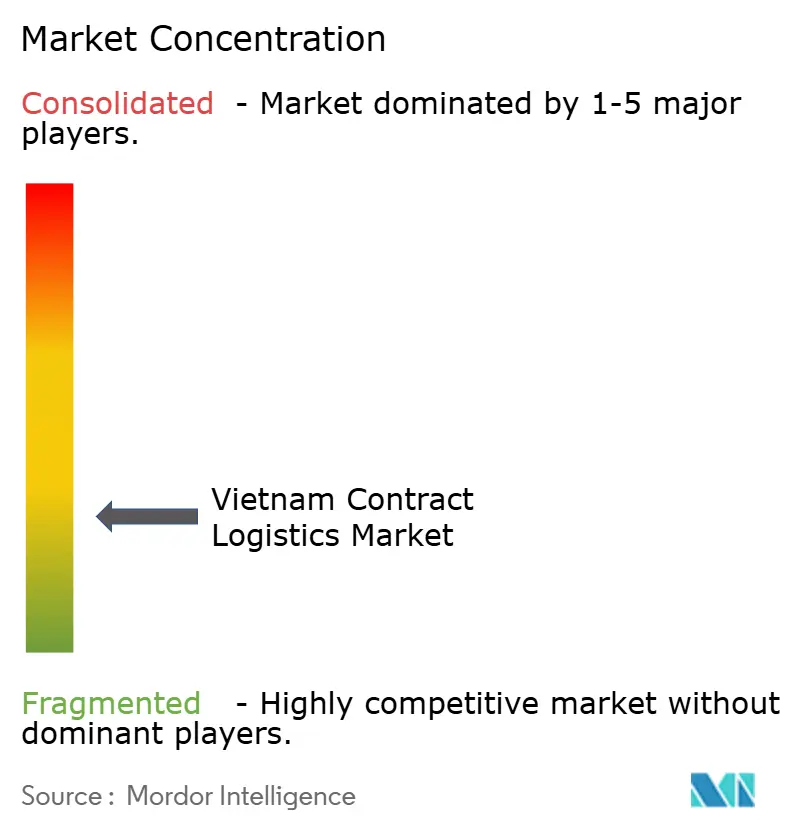
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Vietnam Contract Logistics Market Analysis by Mordor Intelligence
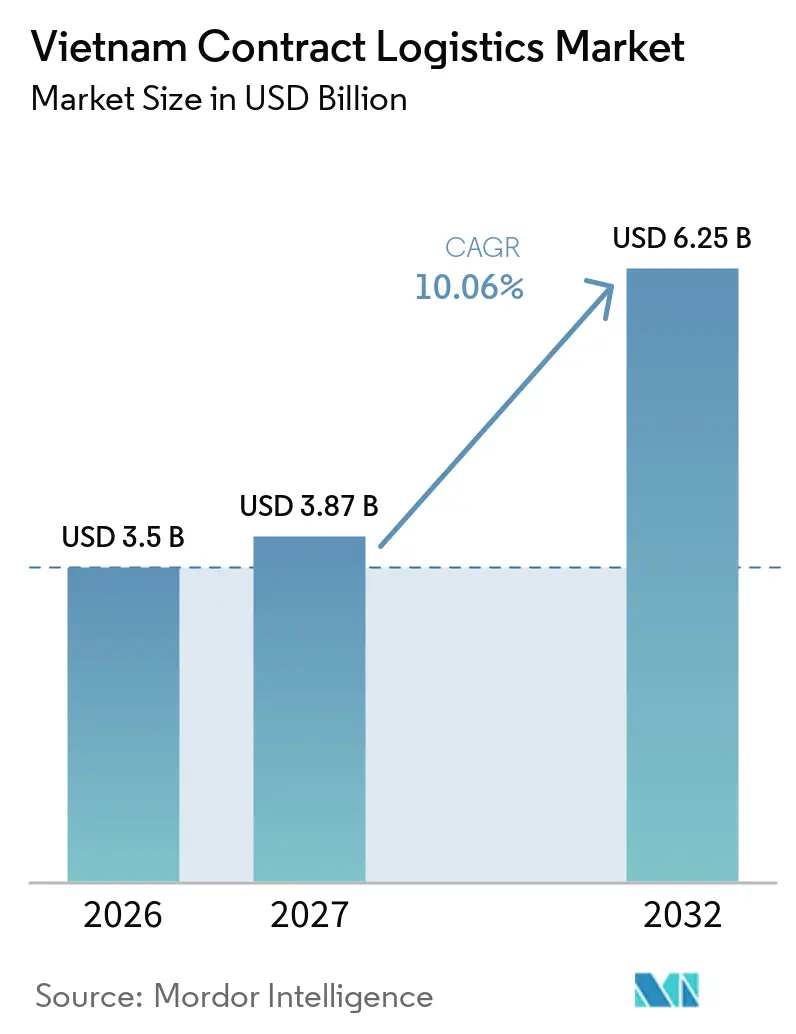
The Vietnam contract logistics market size is valued at USD 3.50 billion in 2026 and is estimated to grow from USD 3.87 billion in 2027 to reach USD 6.25 billion by 2032, at a CAGR of 10.06% during the forecast period 2027-2032.
Demand is supported by export-oriented manufacturing, retail distribution, e-commerce fulfillment, and the increasing use of outsourced warehousing and inventory management. Vietnam’s national logistics strategy, approved under Decision No. 2229/QD-TTg in October 2025, targets logistics outsourcing penetration of 70–80% and promotes digitalization, greener operations, and the development of modern logistics centers. These objectives provide a policy basis for wider adoption of outsourced logistics services. The market is shifting beyond stand-alone transportation toward integrated services that combine warehousing, inventory control, order fulfillment, packaging, labeling, kitting, and distribution. Manufacturers may outsource these functions to reduce the need for dedicated infrastructure and coordinate logistics across suppliers, production sites, and customers. Retailers and e-commerce businesses require flexible fulfillment capacity, while industrial clients often need more customized operating processes and longer-term service agreements. Providers with reliable warehouse systems, trained staff, and multi-location networks are positioned to serve customers that require consistent service levels across different regions.
Key Report Takeaways
- By service type, transportation accounts for 47.12% of the Vietnam contract logistics market share in 2026, while value-added services are forecast to register a CAGR of 11.23% through 2032.
- By contract duration, contracts above 3 years account for 61.89% of the Vietnam contract logistics market size in 2026, while 1–3-year contracts are forecast to register a CAGR of 10.91% through 2032.
- By end-user industry, retail and e-commerce accounts for 29.34% of the Vietnam contract logistics market share in 2026, while manufacturing and automotive are forecast to register a CAGR of 11.62% through 2032.
- By operating model, shared / multi-client contract logistics accounts for 59.38% of the Vietnam contract logistics market size in 2026 and is forecast to register a CAGR of 12.36% through 2032.
- By region, Southern Vietnam accounts for 47.81% of the Vietnam contract logistics market share in 2026, while Central Vietnam is projected to record an 11.98% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Vietnam Contract Logistics Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Manufacturing Relocation Driving Outsourcing Demand | +3.2% | Global, concentrated in Northern Vietnam | Medium term (2–4 years) |
| E-Commerce Expanding Fulfillment Requirements | +2.5% | National, with early gains in Ho Chi Minh City and Hanoi | Short term (≤2 years) |
| Trade Agreements Strengthening Supply Chain Integration | +1.5% | Global, including EU, CPTPP, and RCEP markets | Long term (≥4 years) |
| Modern Warehousing Supporting Contract Logistics Adoption | +1.2% | Northern and Southern Vietnam | Medium term (2–4 years) |
| Low-Carbon Requirements Raising Demand for Traceable Services | +0.8% | Global, with pressure on EU-linked supply chains | Long term (≥4 years) |
| Central Vietnam Gateways Creating New Opportunities | +0.7% | Central Vietnam | Long term (≥4 years) |
| Source: Mordor Intelligence | |||
Manufacturing Relocation Driving Outsourcing Demand
Vietnam’s role in regional manufacturing networks supports demand for outsourced inbound logistics, component storage, inventory management, and outbound distribution. Manufacturers operating across several production sites may use contract logistics providers to coordinate material flows and maintain consistent processes without investing in all the required warehouse infrastructure themselves. Suppliers serving large manufacturers can also benefit from shared facilities and outsourced handling when their volumes do not justify dedicated warehouses. As production operations become more established, recurring logistics requirements can support longer-term service agreements.
E-Commerce Expanding Fulfillment Requirements
E-commerce increases the need for accurate inventory visibility, small-order processing, packaging, returns management, and coordination between warehouses and delivery networks. Vietnam’s national logistics strategy, approved in October 2025, identifies digital transformation and modern logistics infrastructure as development priorities. These objectives are consistent with the operational needs of retailers and online sellers that must manage frequent orders across major cities and provincial markets. Contract logistics providers that combine storage with order management and distribution can support customers whose requirements extend beyond the movement of full truckloads.
Trade Agreements Strengthening Supply Chain Integration
Vietnam’s participation in trade agreements, including the EU–Vietnam Free Trade Agreement (EVFTA), CPTPP, and RCEP, supports cross-border manufacturing and distribution links. In March 2026, Vietnam’s Ministry of Industry and Trade issued Circular No. 14/2026/TT-BCT on rules of origin under the EVFTA, which took effect in May 2026[1]. Origin documentation and customs procedures can increase the need for accurate shipment records, coordinated warehousing, and reliable information flows between manufacturers and logistics providers. These requirements create opportunities for contract logistics companies that integrate physical handling with documentation and inventory systems.
Modern Warehousing Supporting Contract Logistics Adoption
Modern warehouse development gives contract logistics providers more capacity to handle inventory, order fulfillment, and customer-specific operating processes. In July 2026, DHL Supply Chain broke ground on its North Logistics Campus in Hung Yen, a facility designed with automation-ready infrastructure, rooftop solar photovoltaic systems, and energy-efficient operations[2]. The investment is intended to strengthen connections between the northern manufacturing corridor, Hanoi, and Hai Phong Port. Such facilities can support customers requiring standardized warehouse processes, distribution coordination, and capacity that can scale with production and sales volumes.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Fragmented Infrastructure Reducing Service Quality | -1.8% | National, acute in inter-regional corridors and port links | Medium term (2–4 years) |
| Skilled Labor Shortages Raising Operating Costs | -1.2% | National, most acute in Hai Phong and Ho Chi Minh City | Short term (≤2 years) |
| Uneven Digitalization Limiting Provider Integration | -0.9% | National, particularly the Mekong Delta and Central regions | Medium term (2–4 years) |
| Southern Warehousing Bottlenecks Raising Costs | -0.8% | Southern Vietnam | Short term (≤2 years) |
| Source: Mordor Intelligence | |||
Fragmented Infrastructure Reducing Service Quality and Efficiency
Differences in infrastructure quality and connectivity can complicate the coordination of warehouse, port, and road operations across Vietnam. Contract logistics providers must maintain customer service levels even when transport connections are congested or less direct, which can increase transit variability and complicate inventory planning. Vietnam’s national logistics strategy identifies infrastructure coordination, service quality, and logistics efficiency as priorities for sector development. Providers with multiple facilities, alternative routing options, and coordinated transport and warehouse operations may be better positioned to manage disruptions than operators with more limited networks.
Skilled Labor Shortages Raising Operating Costs
Access to experienced logistics personnel remains a constraint as warehouse operations become more technology-intensive. In June 2026, the Vietnam Logistics Business Association estimated that the sector would require around 2.2 million workers by 2030, including employees at logistics service providers and personnel supporting logistics operations in manufacturing and trading companies[3]. Contract logistics operations require staff who can manage warehouse systems, inventory controls, quality procedures, and customer reporting. Providers may need to invest in training and workforce development to maintain consistent service quality as accounts expand.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Service Type: Value-Added Services Support Further Integration
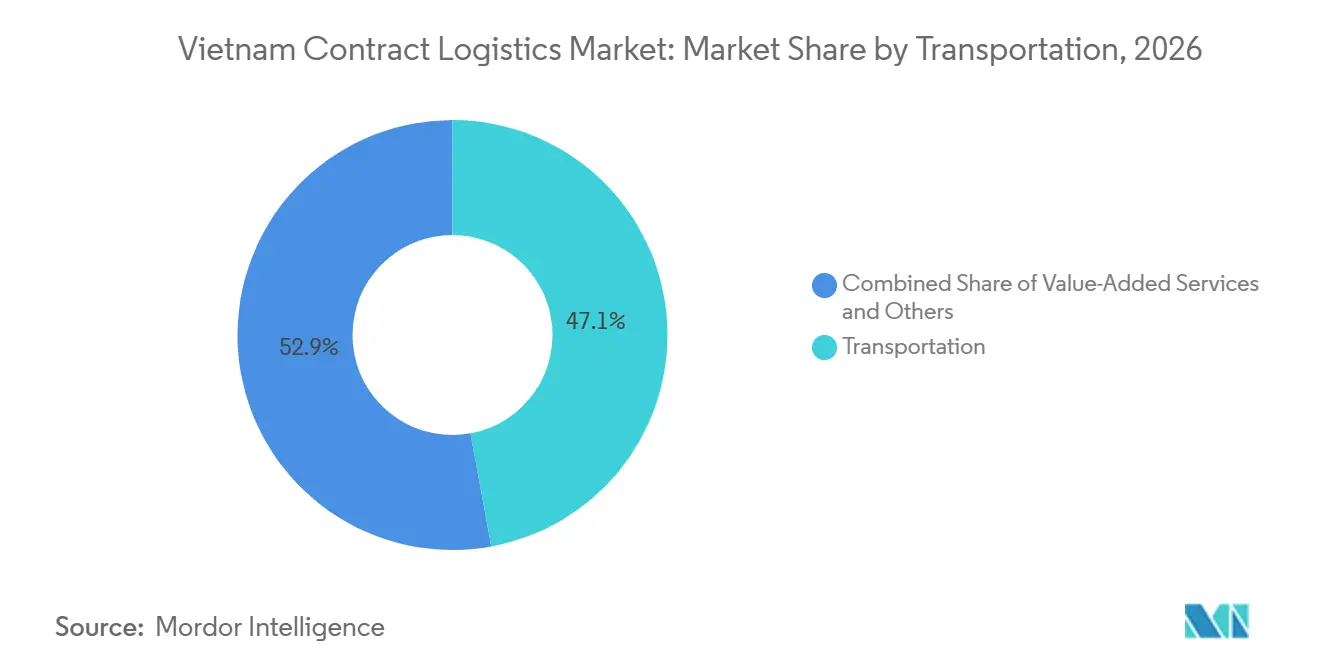
Transportation accounts for 47.12% of the Vietnam contract logistics market share in 2026. Transport remains central to contract logistics because it connects suppliers, manufacturing facilities, warehouses, distribution centers, and customers. However, the services purchased under a contract can also include inventory management, packaging, labeling, kitting, order processing, and other customer-specific tasks. These functions allow businesses to consolidate multiple logistics activities under one provider and reduce the number of operational handoffs.
Value-added services are forecast to register at a CAGR of 11.23% from 2027 to 2032. Demand is supported by manufacturers and retailers seeking services that are integrated with production schedules, product configuration, and fulfillment requirements. In April 2026, NX Vietnam’s Quang Minh Logistics Center obtained an air cargo CFS licence, allowing it to handle activities including cargo consolidation, packing, and bonded transport procedures[4].

By Contract Duration: Longer Agreements Support Operational Continuity
Contracts lasting more than 3 years account for 61.89% of the Vietnam contract logistics market size in 2026. Longer agreements can support customer-specific warehouse processes, dedicated staff, system integration, and operational planning. They can also give providers greater visibility into expected demand and the time needed to recover investment in equipment or facility adaptations. Contract duration depends on the service scope, customer requirements, and the level of infrastructure or technology dedicated to an account.
The 1–3 Years contract-duration segment is forecast to register at a CAGR of 10.91% from 2027 to 2032. Medium-duration contracts can suit customers whose distribution networks, sales volumes, or sourcing arrangements are changing and who want more frequent opportunities to reassess service requirements. Providers need to balance contract flexibility with the costs of staff, facilities, and systems, particularly when volumes vary over the term. Clear performance metrics and agreed procedures for reviewing costs can help both parties manage these risks.
By End-User Industry: Manufacturing and Automotive Drive Complex Requirements
Retail and e-commerce accounts for 29.34% of the Vietnam contract logistics market share in 2026. Retail and online sellers require inventory accuracy, replenishment, order processing, and distribution across different customer channels. Manufacturing and automotive customers have different operational priorities, including inbound component control, sequencing, production support, storage, and outbound handling. Food and beverage and healthcare customers may also require specialized handling procedures, traceability, or controlled storage depending on the products involved.
Manufacturing and automotive is forecast to register a CAGR of 11.62% from 2027 to 2032. The segment’s requirements can encourage manufacturers to outsource recurring logistics functions that need to be coordinated with production and distribution schedules. In September 2025, Kuehne+Nagel and the LEGO Group opened a regional distribution center in Dong Nai to support distribution from LEGO Manufacturing Vietnam to Asia-Pacific markets. Kuehne+Nagel’s scope included transport, customs clearance, bonded warehousing, sea freight, and onward delivery, illustrating the integrated logistics requirements associated with manufacturing and regional distribution.
By Operating Model: Shared Facilities Offer Scale and Flexibility
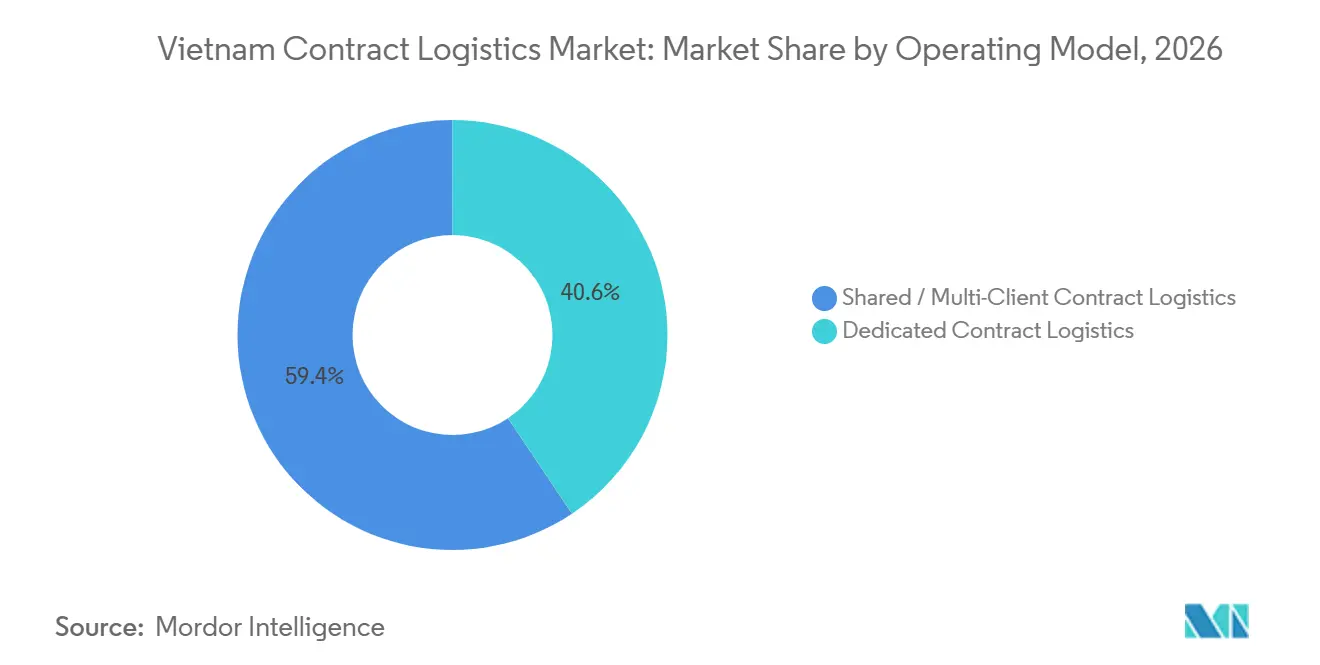
Shared / multi-client contract logistics accounts for 59.38% of the Vietnam contract logistics market in 2026. Shared facilities allow providers to spread building, technology, and labor costs across several customers. This model can suit businesses that need professional warehouse operations but do not require exclusive infrastructure. Dedicated operations can remain appropriate where customer-specific processes, product controls, security requirements, or service levels justify exclusive capacity.
Shared / multi-client contract logistics is forecast to register at a CAGR of 12.36% from 2027 to 2032. The model can support customers whose volumes fluctuate or who need to scale their logistics operations without committing to a dedicated facility. In September 2025, Kuehne+Nagel and the LEGO Group opened a regional distribution center in Dong Nai with bonded storage and value-added services, designed to support regional distribution. The facility is a customer-specific example of integrated warehousing and distribution.
Geography Analysis
Southern Vietnam accounts for 47.81% of the Vietnam contract logistics market in 2026. The region benefits from manufacturing and commercial activity around Ho Chi Minh City and Dong Nai, as well as access to major southern ports. These factors support demand for warehousing, inventory management, regional distribution, and logistics services for export-oriented manufacturers. In May 2026, LOTTE Global Logistics officially opened its Dong Nai Cold Chain Center, adding temperature-controlled logistics capacity in the south.
Northern Vietnam is an important logistics base for manufacturers serving domestic and international markets. Its connections to Hanoi, Hai Phong Port, and surrounding industrial areas support inbound components, finished-goods distribution, and regional supply chain operations. In July 2026, DHL Supply Chain broke ground on the North Logistics Campus in Hung Yen. The announced investment was VND 1.9 trillion (USD 76 million). The project includes automation-ready infrastructure and rooftop solar systems, with the aim of strengthening distribution and manufacturing supply chains in northern Vietnam.
Central Vietnam is forecast to be the fastest-growing regional segment, with a CAGR of 11.98% from 2027 to 2032. The region’s development potential is linked to port infrastructure, industrial activity, and connections between domestic markets and regional trade corridors. In April 2026, Da Nang commenced the Lien Chieu Container Terminal project, which is planned to have an overall capacity of approximately 5.7 million TEU per year. Development of the wider port and transport network may create opportunities for contract warehousing, distribution, and integrated logistics services.
Competitive Landscape
The Vietnam contract logistics market is fragmented and includes international logistics groups, domestic providers, and specialist operators serving customers with different service and geographic requirements. Competition centers on warehouse capability, distribution coverage, inventory visibility, customer-specific operating processes, and the ability to coordinate several logistics functions under one agreement. Providers may differentiate themselves through integrated warehousing and transport, bonded logistics, value-added services, technology, or sector-specific expertise.
In September 2025, Kuehne+Nagel and the LEGO Group opened a regional distribution center in Dong Nai. Kuehne+Nagel provides end-to-end logistics services for the operation, including transport, customs clearance, bonded warehousing, sea freight, and delivery to regional distribution center. In July 2026, DHL Supply Chain began construction of its North Logistics Campus in Hung Yen, adding planned warehouse capacity in the northern manufacturing corridor.
Domestic providers and joint ventures also contribute to the competitive landscape. In September 2025, ITL Corporation and Japan’s Seino Holdings launched Seino-ITL Logistics to expand less-than-truckload transport services in Vietnam. In April 2026, CJ Logistics acquired a 100% stake in CJ Gemadept Logistics, following the earlier strategic relationship between the companies. These developments reflect efforts to expand service coverage, consolidate logistics capabilities, and serve a broader range of customers. Competition is likely to remain differentiated by contract scale, industry requirements, geographic reach, and the ability to deliver reliable service across warehouse and transport operations.
Vietnam Contract Logistics Industry Leaders
-
Indo Trans Logistics Corporation (ITL)
-
Transimex Corporation
-
DHL Group
-
DSV
-
Kuehne+Nagel
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- July 2026: DHL Supply Chain broke ground on the DHL North Logistics Campus in Hung Yen province, a Grade A facility spanning 82,500 m² with a total investment of VND 1.9 trillion (USD 76 million). Phase 1 targets completion in H1 2027, with Phase 2 in H2 2028. The campus integrates rooftop solar power and infrastructure for electric material-handling equipment.
- July 2026: Vietnam Post Logistics and DSV Contract Logistics renewed a 3-year strategic cooperation agreement for B2B supply chain solutions, extending a partnership that maintained KPI fulfillment rates above 99.8% since 2021 and expanding scope to technology and manufacturing sector clients.
- April 2026: CJ Logistics acquired the remaining 49.1% stake in CJ Gemadept Logistics Holding, achieving 100% ownership via a stake swap with Gemadept. CJ plans to invest in new distribution center assets and deploy warehouse automation technology from its TES Logistics Research Institute in Korea.
- April 2026: APM Terminals and Hateco Group formalized a USD 1.7 billion agreement with Da Nang City to develop the Lien Chieu Container Terminal. The project is designed for 5.7 million TEU per year, and Phase 1 berths are targeted for operation by early 2029.
Vietnam Contract Logistics Market Report Scope
| Transportation | Road |
| Rail | |
| Air | |
| Sea | |
| Warehousing and Distribution | |
| Value-Added Services (Assembly, Labeling, Kitting) |
| 1-3 Years |
| Above 3 Years |
| Manufacturing and Automotive |
| Food and Beverage |
| Retail and E-commerce |
| Healthcare and Pharmaceuticals |
| Chemicals |
| Other Industries |
| Dedicated Contract Logistics |
| Shared / Multi-Client Contract Logistics |
| Northern Vietnam |
| Central Vietnam |
| Southern Vietnam |
| By Service Type | Transportation | Road |
| Rail | ||
| Air | ||
| Sea | ||
| Warehousing and Distribution | ||
| Value-Added Services (Assembly, Labeling, Kitting) | ||
| By Contract Duration | 1-3 Years | |
| Above 3 Years | ||
| By End-User Industry | Manufacturing and Automotive | |
| Food and Beverage | ||
| Retail and E-commerce | ||
| Healthcare and Pharmaceuticals | ||
| Chemicals | ||
| Other Industries | ||
| By Operating Model | Dedicated Contract Logistics | |
| Shared / Multi-Client Contract Logistics | ||
| By Region | Northern Vietnam | |
| Central Vietnam | ||
| Southern Vietnam |
Key Questions Answered in the Report
What is the value of the Vietnam contract logistics market in 2027?
The Vietnam contract logistics market is estimated at USD 3.87 billion in 2027 and is forecast to reach USD 6.25 billion by 2032.
What growth rate is expected through 2032?
The market is forecast to register a CAGR of 10.06% from 2027 to 2032.
Which service type has the largest market share?
Transportation accounts for 47.12% of the market in 2026. Value-added services are forecast to register a CAGR of 11.23% from 2027 to 2032.
Why are manufacturers outsourcing logistics in Vietnam?
Outsourcing allows manufacturers to coordinate inbound materials, warehousing, inventory control, and outbound distribution without operating every logistics function themselves.
Which region is forecast to grow fastest?
Central Vietnam is forecast to register a CAGR of 11.98% from 2027 to 2032, supported by potential demand associated with port and transport infrastructure development.
Which operating model is most widely used?
Shared / multi-client contract logistics accounts for 59.38% of the market in 2026 and is forecast to register at a CAGR of 12.36% from 2027 to 2032.