
United Kingdom Bathroom Vanities Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 2.5 Billion |
| Market Size (2026) | USD 2.53 Billion |
| Market Size (2031) | USD 3.27 Billion |
| Growth Rate (2026 - 2031) | 5.25 % |
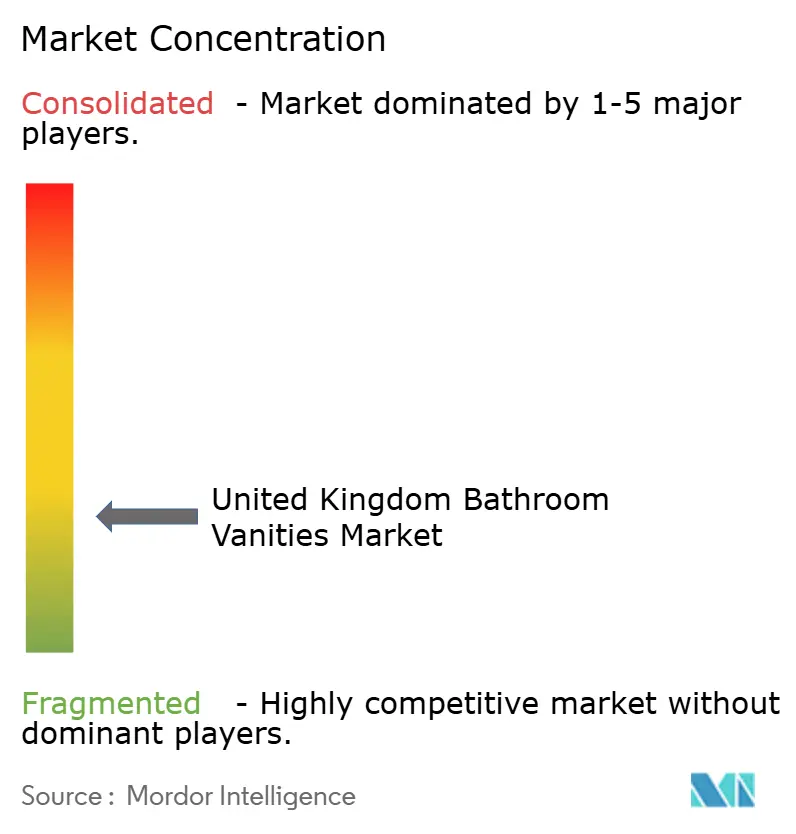
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
United Kingdom Bathroom Vanities Market Analysis by Mordor Intelligence
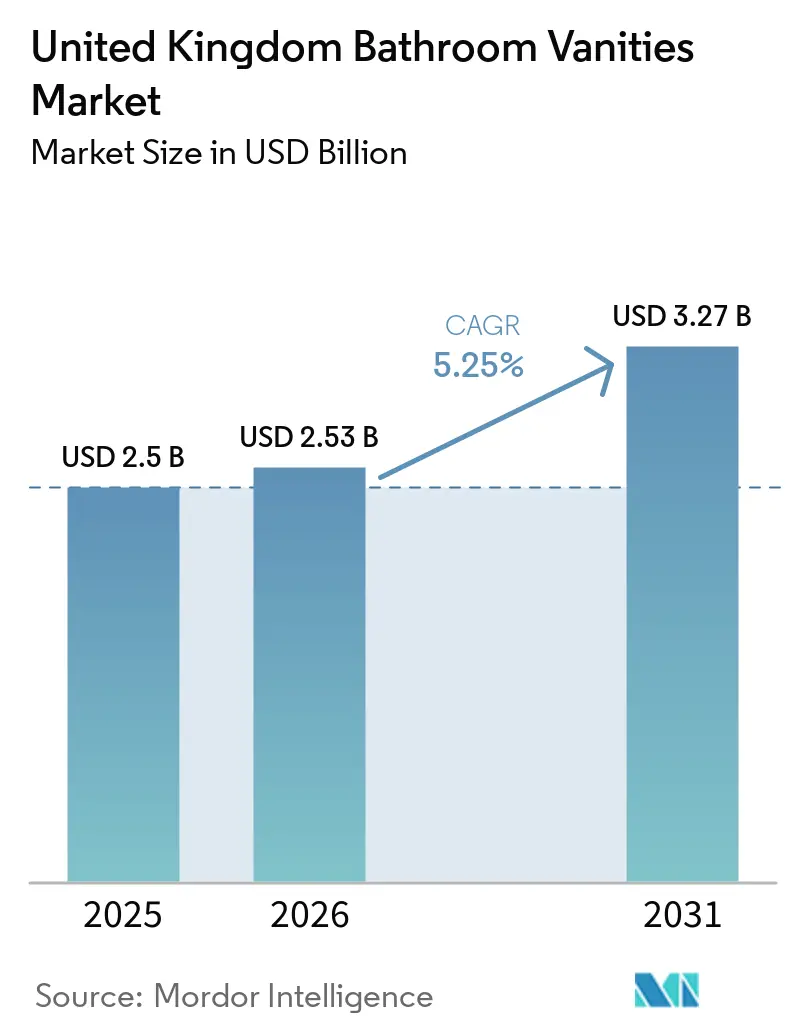
The United Kingdom bathroom vanities market size was valued at USD 2.50 billion in 2025 and is estimated to grow from USD 2.53 billion in 2026 to reach USD 3.27 billion by 2031, at a CAGR of 5.25% during the forecast period (2026-2031). Renovation activity supports demand because many homeowners replace furniture without changing the room layout. Nearly 7 million homeowners planned renovation work during the following 2 years, with an average planned budget of GBP 14,000 (USD 18,887.5) in 2025[1]. Product suppliers are balancing premium designs with lower-priced ranges as planned project budgets have declined. Digital retailers are gaining importance, while showrooms remain relevant for specifications that require material selection and design advice. The United Kingdom bathroom vanities market also benefits from public housing activity, accessible bathroom requirements, and hotel refurbishment projects.
Key Report Takeaways
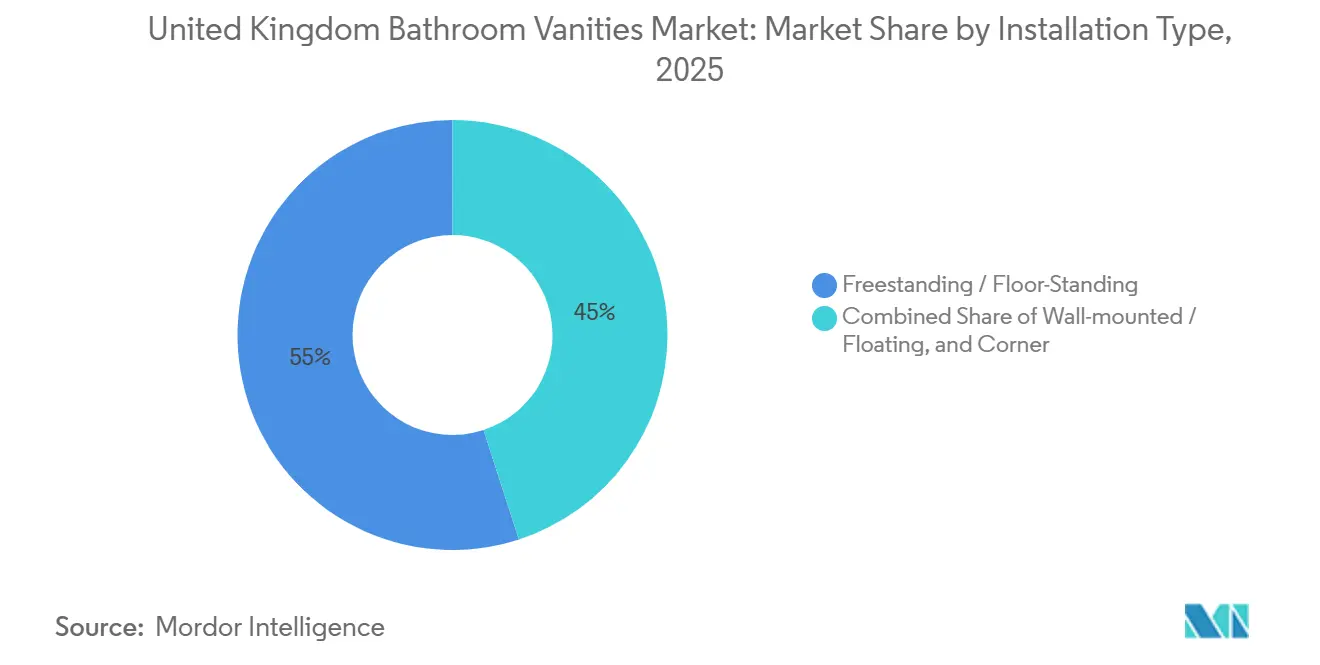
- By installation type, freestanding formats led with 55.00% of the 2025 United Kingdom bathroom vanities market share, while wall-mounted configurations are projected to grow at the fastest CAGR of 6.42% through 2031.
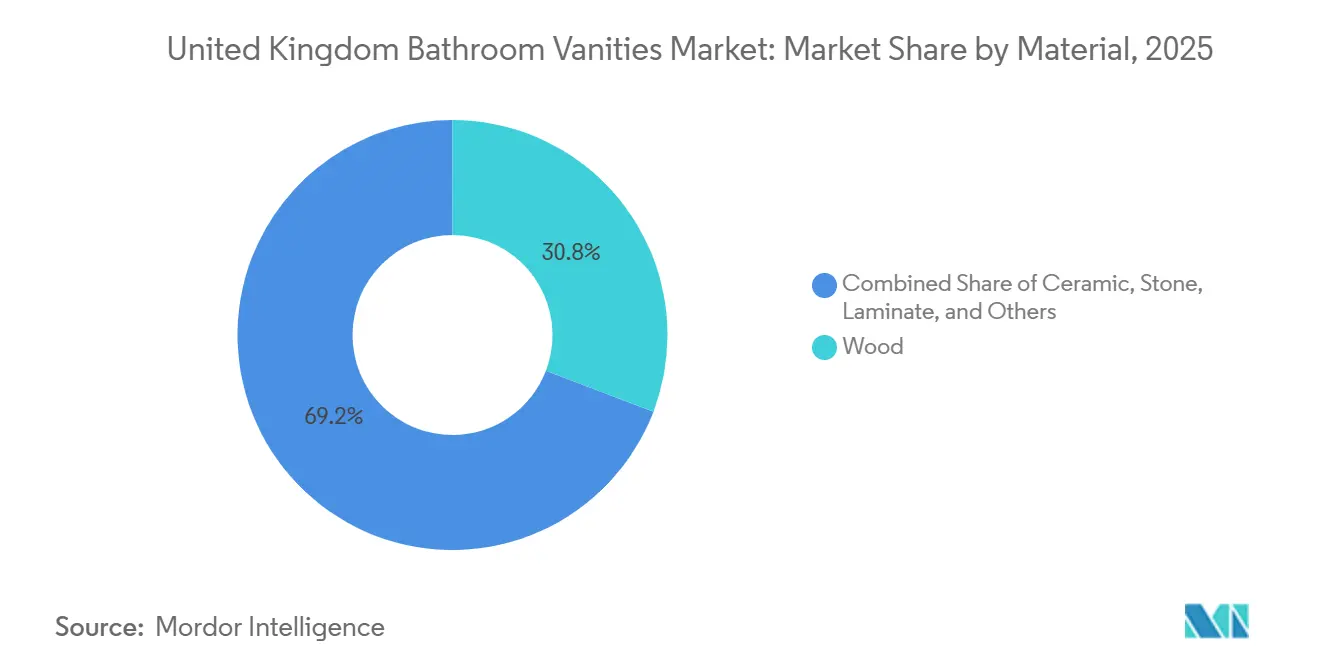
- By material, wood accounted for 30.80% of the 2025 United Kingdom bathroom vanities market share, and stone is projected to grow at the fastest CAGR of 6.84% through 2031.
- By sink configuration, single-sink units accounted for 58.91% of the 2025 United Kingdom bathroom vanities market share, while double-sink units are projected to grow at the fastest CAGR of 6.17% through 2031.
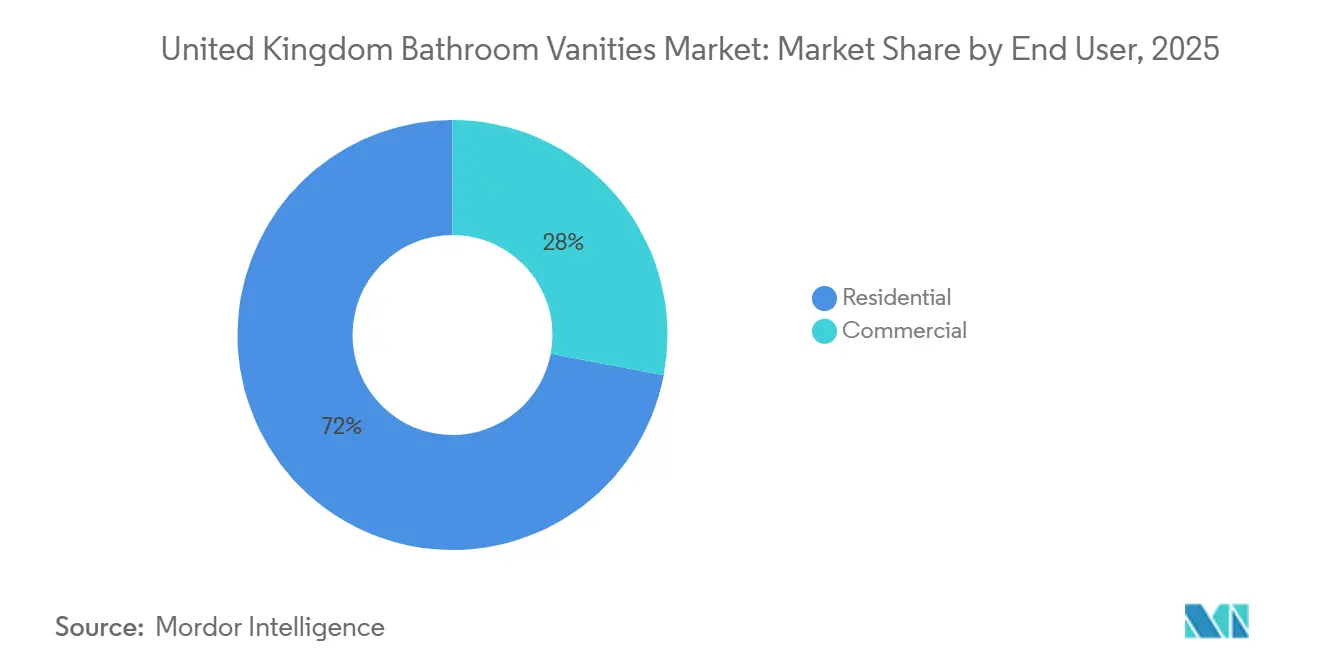
- By end-user, residential commanded 72.00% of the 2025 United Kingdom bathroom vanities market share, while commercial demand is projected to grow at the fastest CAGR of 6.68% through 2031.
- By distribution channel, B2C/retail contributed 68.00% of the 2025 United Kingdom bathroom vanities market share, while direct B2B is projected to grow at the fastest CAGR of 7.04% through 2031.
- By geography, England led with 84.00% of the 2025 United Kingdom bathroom vanities market share, while Northern Ireland is projected to grow at the fastest CAGR of 6.03% through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
United Kingdom Bathroom Vanities Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Residential Bathroom Renovation and Modernization | +2.0% | National, with concentration in London, South East England, and North West England | Short term (≤ 2 years) |
| Compact and Space-Efficient Vanity Demand | +1.2% | National, especially London, Manchester, and Edinburgh | Medium term (2-4 years) |
| Online Bathroom Retail Growth | +1.3% | National, with strong uptake in metropolitan and commuter-belt areas | Short term (≤ 2 years) |
| Premium Integrated Storage, Lighting, and Demisting | +0.9% | London and South East England, with spillover into Scotland’s Central Belt | Medium term (2-4 years) |
| Installer-Friendly Modular Vanity Systems | +0.7% | National, particularly Wales and Northern Ireland | Medium term (2-4 years) |
| Accessible and Multigenerational Bathroom Furniture | +0.8% | National, including aging coastal communities and Northern Ireland | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Residential Bathroom Renovation and Modernization Anchors Market Demand
Residential renovation remains the main source of demand for the United Kingdom bathroom vanities market. Houzz reported that 49% of surveyed United Kingdom homeowners renovated a bathroom in 2025. The same study placed median renovation spending at GBP 20,000 (USD 26,982.2)[2]. Aviva reported that nearly 7 million homeowners planned to work within 2 years. Those owners expected to spend an average of GBP 14,000 (USD 18,887.5). Houzz found that 76% of renovating homeowners did not change their bathroom footprint. This pattern makes furniture replacement easier to approve than structural bathroom work. Homeowners who intend to stay in their homes can place greater value on durable fittings. That preference supports purchases beyond entry-level cabinet replacements. It also favors coordinated units that combine storage, basins, mirrors, and lighting. The replacement cycle gives suppliers recurring opportunities to update finishes and configurations. The United Kingdom bathroom vanities market, therefore, depends less on home moves than categories tied only to new housing. Suppliers still need price points that work for households with constrained renovation budgets.
Demand for Compact and Space-Efficient Vanities Reshapes the Format Mix
Compact layouts influence product selection across the United Kingdom bathroom vanities market. Houzz found that 39% of renovated bathrooms measured below 5 square meters in 2025. Another 40% measured from 5 square meters to 9.99 square meters. These figures mean that 79% of renovated bathrooms measured below 10 square meters. Wall-mounted units can preserve visible floor area in these settings. Smaller rooms do not eliminate the need for storage. They shift demand toward shallow cabinets, integrated drawers, and coordinated wall storage. Wall-mounted formats also encourage attention to fixing systems and pipework concealment. Products that installers can fit within one visit can reduce disruption for households. Corner units address irregular rooms that cannot accommodate standard cabinet widths. This format pressure keeps space efficiency central to the United Kingdom bathroom vanities market.
Growth of Online Bathroom Retailing Accelerates Channel Change
Online retailing has become a meaningful route to market for bathroom furniture. Victorian Plumbing recorded 1,080,000 orders in FY2025[3]. The company also reported an average order value of GBP 287 (USD 387.1). Its trade revenue increased 10% to GBP 73.8 million (USD 99.5 million) during FY2025. Trade revenue represented 24% of the company’s total revenue. These results show that digital channels serve both households and installers. Online platforms widen access to product ranges that may not be stocked locally. They also make price comparisons easier for consumers. That transparency can place pressure on showroom-led retailers and suppliers. Digital tools can help customers compare widths, finishes, and basin options before ordering. Specialist showrooms still matter when customers need physical samples or detailed design advice. The United Kingdom bathroom vanities market is therefore likely to retain both online and physical routes.
Premium Integrated Storage, Lighting, and Demisting Supports Higher-Value Specifications
Bathroom furniture is increasingly purchased as part of an integrated room specification. BRG Building Solutions described storage, aesthetics, and integrated features as increasingly important in bathroom design[4]. Soft-close drawers, lighting, demisting pads, and concealed charging features add practical value. These features can support higher-value purchases where homeowners are completing broader renovations. They also make vanity units more central to the bathroom’s storage plan. The United Kingdom bathroom vanities market benefits when manufacturers offer these features across several price levels. Ideal Standard’s Eurovit+ range illustrates how suppliers combine furniture with functional features. Its La Dolce Vita Atelier Collection includes vanity units in 6 sizes and asymmetric storage options. Such ranges allow suppliers to provide more choice without treating every buyer as a luxury customer. Integrated features can distinguish
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Cost-of-Living Pressure on Discretionary Refits | −1.4% | National; most acute in high-cost urban England and lower-income households across Wales and Northern Ireland, where bathroom refits rank as deferrable expenditure | Short term (≤ 2 years) |
| Raw-Material, Freight and Imported-Component Price Volatility | −0.9% | National; Northern Ireland additionally exposed to cross-border trade complexity under the Windsor Framework affecting imported cabinetry and ceramic components | Medium term (2–4 years) |
| Weak New-Build and Construction Cycles | −0.7% | England and Wales primarily, where private housebuilding starts remain suppressed; Scotland partially insulated by separate social housing targets under the Housing to 2040 plan | Medium term (2–4 years) |
| Installer Capacity and Irregular-Bathroom Measurement Risk | −0.5% | National; structurally most acute in rural Wales, the Scottish Highlands, and Northern Ireland where certified bathroom fitter density is thin relative to renovation demand | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Cost-of-Living Pressure Compresses Renovation Scope and Trade-Up Frequency
Budget pressure is limiting the scope of some renovation projects. The 2026 Houzz and Home study placed planned median spending for 2026 projects at GBP 10,000 (USD 13,491.1). This was 29% below the GBP 14,000 (USD 18,887.5) planned for 2025 projects. The study also found that 38% of 2025 renovators exceeded their initial budgets. This creates a clearer choice between full replacement and cosmetic work. It can also move demand toward lower-priced laminate and MDF units. Budget-conscious buyers may delay integrated stone-top or premium furniture purchases. They may choose a more limited update that retains existing plumbing and layouts. This does not remove renovation demand from the United Kingdom bathroom vanities market. It does make the mix of purchased products more price sensitive. Suppliers that provide practical entry-level options can retain customers during constrained periods. Premium suppliers need clear functional reasons for higher prices.
Raw Material and Freight Volatility Erodes Supplier Margins
Import costs remain a concern for suppliers that source furniture components internationally. The Office for National Statistics reported that the Import Price Index increased 8.5% in the year to June 2026. Cabinet hardware, ceramic basins, and laminate panels can be exposed to these movements. Trojan Baths stated in 2026 that global supply chains remained under pressure. The company also noted that freight costs could move without much warning. These conditions make cost planning harder for importers. Suppliers cannot always absorb higher costs without affecting retail prices. Higher prices can steer buyers toward simpler products or postpone replacements. Businesses with United Kingdom-based or nearer European production can have more control over supply timing. They can also respond more quickly to a change in specification requirements. The United Kingdom bathroom vanities market remains exposed to imported components even when final assembly is local. Margin management, therefore, remains important alongside product design and channel development.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Installation Type: Wall-Mounted Formats Drive Format Innovation
Freestanding and floor-standing units held 55.00% share in 2025. Their position reflects compatibility with many existing bathroom layouts. Installers are familiar with their fitting requirements. This reduces complexity during standard replacement work. Floor-standing cabinets can also accommodate uneven walls and older plumbing arrangements. They remain suitable for volume residential refurbishment. Their broad availability makes comparison shopping easier for households. Their role is likely to remain important across price points. Freestanding units offer a straightforward option for buyers who do not need wall support systems.
Wall-mounted units are forecast to grow at a 6.42% CAGR through 2031. Their visual benefit is particularly relevant in smaller renovated bathrooms. They leave floor space visible and can make cleaning easier. Adjustable-height brackets can improve the suitability for some accessible bathroom designs. Cantilevered designs can also provide clear space beneath the cabinet. Corner vanities serve bathrooms with irregular shapes or limited wall runs. Specialist suppliers can use modular dimensions to address these layouts. The installation type mix in the United Kingdom bathroom vanities market will reflect room size, plumbing positions, and user needs.

By Material: Wood Serves Both Value and Premium Demand
Wood held 30.80% of the United Kingdom bathroom vanities market size in 2025. The category includes affordable MDF-core units with wood-look finishes. It also includes solid timber furniture at higher prices. This span gives wood relevance across several buyer budgets. Wood finishes such as oak, walnut, and wood-grain laminates fit current product ranges. Roper Rhodes introduced the Walcot and Faber collections with wood options in December 2025. Roca introduced Verso with 3 wood-effect surfaces in 2026. Stone is also forecast to grow at a 6.84% CAGR through 2031.
FSC certification can help manufacturers communicate material provenance to some buyers. Lusso Stone and Haddon have used certification in their product messaging. The certification may be more relevant in mid-premium and premium purchases. Laminate and MDF remain important where buyers prioritize price and retail availability. Stone-topped units serve higher-value renovation and hospitality projects. Ceramic, glass, metal, and solid surface materials retain specialist roles. Material choice depends on budget, maintenance preferences, and the intended bathroom style. The United Kingdom bathroom vanities industry uses this range of materials to serve both replacement demand and higher-specification projects.
By Sink Configuration: Double Sinks Support Higher-Specification Bathrooms
Single-sink units held 58.91% share in 2025. They fit the room sizes that dominate United Kingdom renovation projects. They are also appropriate for individual users and many couples' households. A single basin can leave more space for cabinet storage and circulation. This makes the format practical in compact bathrooms. It provides a clear entry point for a full vanity replacement. The configuration is available across a broad range of cabinet widths. It also remains accessible to buyers working within tighter budgets. Single basins will continue to support the volume base of the United Kingdom bathroom vanities market.
Double-sink units are forecast to grow at a 6.17% CAGR through 2031. Their appeal is strongest in larger master-bedroom ensuite renovations. Houzz reported that the share of renovated bathrooms above 10 square meters increased by 3 percentage points in 2025. Larger new-build bathrooms can also accommodate twin-basin specifications. Vessel and multi-bowl units remain smaller, design-led categories. Ideal Standard’s La Dolce Vita collection includes sculptural vessel basins. These options can command higher selling prices in hospitality and high-value homes. The sink configuration choice balances household use, available space, and design preference.
By End User: Residential Demand Leads While Commercial Activity Expands
Residential buyers accounted for 72.00% share in 2025. Most replacement activity begins with homeowner renovation projects. Private rental properties can add recurring demand when units are renewed between tenancies. Homeowners planning long-term occupancy may choose more durable specifications. This supports a premium subcategory within the larger residential base. Residential buyers also benefit from online range visibility and local showroom support. Their purchases often work within existing room footprints and plumbing locations. This makes standard cabinet sizes commercially important. Residential replacement will remain central to the United Kingdom bathroom vanities market.
Commercial demand is forecast to grow at a 6.68% CAGR through 2031. Hotel refurbishment and care-home upgrades contribute to this expansion. AKW stated that 29% of care-home beds lacked en-suite facilities in its 2025 guidance. The company also reported that 70% did not have a full wet room. Commercial projects can require compliance with Approved Document M and BS 8300 requirements. These requirements affect knee space, access, and fixture placement. Bespoke accessible solutions may increase the specification depth of each project. Commercial buyers, therefore, offer a smaller but faster-growing source of demand.
By Distribution Channel: Online Extends Its Structural Lead
B2C and retail channels held 68.00% share in 2025. Specialty showrooms remain relevant for mid-premium purchases. Buyers can compare finishes, storage layouts, and basin materials in person. Consultation can be useful when a room has unusual dimensions. Physical sites also support specification discussions with installers. Roper Rhodes has invested in distribution and showroom infrastructure. This indicates the continuing role of physical specification infrastructure. Retail sites can complement online research before a final purchase.
Direct B2B is forecast to grow at a 7.04% CAGR through 2031. Victorian Plumbing’s 1,080,000 FY2025 orders demonstrate the scale that a digital specialist can achieve. The company soft-launched the MFI homewares platform in July 2025. B2B channels are also using digital contractor portals and specification tools. Warehouse and entry-level retail formats remain useful for price-sensitive laminating and MDF demand. These channels can limit price increases at the lower end. Distribution choices in the United Kingdom bathroom vanities market will increasingly combine online research, showroom advice, and installer purchasing.
Geography Analysis
England held 84.00% of total category sales in 2025. Its position reflects population concentration and deeper renovation activity. London and South East England support higher renovation budgets than many other areas. The Ministry of Housing, Communities and Local Government reported 33,960 seasonally adjusted new-build dwelling starts in England during the first quarter of 2026. This was 18% higher than the same quarter a year earlier. The year to March 2026 recorded 130,170 starts, up 15% from the preceding period. Homes England delivered 42,433 housing starts in the financial year 2025-26, an 11% increase. These projects add a secondary pipeline for new bathroom installations.
Scotland has a separate public housing investment driver. Scotland’s 2026 Spending Review committed GBP 4.9 billion (USD 6.6 billion) over 4 years for 36,000 affordable homes. It included a record GBP 4.1 billion (USD 5.5 billion) in public-sector funding. This pipeline supports new bathroom installation activity. Scotland’s renovation cost structure was reported to be 2% below the United Kingdom average. This can support mid-range vanity purchases. Wales has a Disabled Facilities Grant cap of GBP 36,000 (USD 48,568). That cap is GBP 6,000 (USD 8,094.6) above England’s maximum. Accessible designs can therefore have a distinct funding route in Wales.
Northern Ireland is forecast to be the fastest-growing geography at an 6.03% CAGR through 2031. The Department for Communities reported 1,765 social-home starts in 2025-26. This was a 17% increase from the prior year. The program was supported by GBP 210 million (USD 283.3 million) in investment. The department also reported that more than 6,000 social homes were under construction. Renovation costs were reported to be 6% below the United Kingdom average. This favors mid-tier wood and laminate specifications. The 2024-2039 Housing Supply Strategy provides a longer planning framework for housing expansion.
Competitive Landscape
The United Kingdom bathroom vanities market is fragmented. No single manufacturer has pricing authority across every product tier. Victorian Plumbing operates as a large distribution aggregator rather than a manufacturer. It used 1.08 million annual orders in FY2025 to build scale in online retailing. Scale can strengthen purchasing terms and improve range visibility. It can also support trade purchasing through online channels. This position differs from a manufacturer’s focus on product engineering and brand specification. Retail scale and manufacturing depth, therefore, remain separate sources of competitive strength.
Villeroy & Boch acquired Ideal Standard in March 2024. The combined Bathroom and Wellness Division generated EUR 1,098.9 million (USD 1,292.65 million) in 2024. This combination expanded the group’s bathroom product presence across several price tiers. Roper Rhodes, Bathroom Brands Group, and Tavistock compete through service and specification relationships. Duravit reported EUR 631.2 million (USD 742.4 million) in global sales for 2024. Its currency-adjusted sales declined 2.9% that year. These companies compete through design, range breadth, logistics, and trade relationships.
Roca launched the Verso modular furniture system in March 2026. The range offered 4 lacquered colors and 3 wood-effect surfaces. Victorian Plumbing extended its MFI platform into homeware adjacencies during 2025. Suppliers also use modular dimensions and finish options to serve a wider set of room requirements. WRAS approval for plumbing-integrated components can raise the entry requirements for product families. Competition is strongest where suppliers can combine compliant products with reliable delivery and installer support. Design options must also fit practical plumbing and installation constraints.
United Kingdom Bathroom Vanities Industry Leaders
-
Victorian Plumbing Group plc
-
Utopia Bathrooms
-
Roper Rhodes
-
Crosswater
-
Roca Sanitario SAU
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- March 2026: Roca launched Verso, a modular bathroom furniture system in four lacquered colors and three wood-effect surfaces, engineered for long-term configurability and designed to accommodate changing user needs without compromising design coherence over successive renovation cycles.
- December 2025: Ideal Standard launched the La Dolce Vita Atelier Collection designed by Roberto Palomba, featuring vanities in six sizes including asymmetric storage models and sculptural flower-shaped vessel basins, compatible with the wider Ideal Standard portfolio through the Singular philosophy.
- July 2025: Victorian Plumbing soft-launched the reimagined MFI homewares platform following the acquisition of the MFI brand in May 2024 as part of the Victoria Plum transaction, with full launch planned for H1 2026 targeting homeware and furniture adjacencies to its core bathroom range.
United Kingdom Bathroom Vanities Market Report Scope
Bathroom vanities are fixtures combining a sink, countertop, and storage, designed to organize essentials and conceal plumbing while serving as a focal point in bathroom design. The United Kingdom bathroom vanities market is segmented by installation type, material, sink configuration, end user, distribution channel, and geography. By installation type, the market is segmented into freestanding, wall-mounted, and corner. By material, the market is segmented into wood, ceramic, and more. By sink configuration, the market is segmented into single sink, double sink, and others. By end user, the market is segmented into residential and commercial. By distribution channel, the market is segmented into B2C/retail and B2B/directly from manufacturers. By geography, the market is segmented into England, Scotland, and more. The report offers the market size in value terms in USD for all the above-mentioned segments.
| Freestanding / Floor-standing |
| Wall-mounted / Floating |
| Corner |
| Wood |
| Ceramic |
| Stone (Marble, Quartz, Granite) |
| Laminate / MDF |
| Others (Metal, Glass, Solid Surface) |
| Single Sink |
| Double Sink |
| Others (e.g., Vessel, Integrated Multi-bowl) |
| Residential |
| Commercial |
| B2C/Retail | Home Centers |
| Specialty Furniture Stores (including exclusive brand outlets) | |
| Online | |
| Other Distribution Channels (includes hypermarkets, supermarkets, teleshopping, warehouse clubs, departmental stores, etc.) | |
| B2B/Directly from Manufacturers |
| England |
| Scotland |
| Wales |
| Northern Ireland |
| By Installation Type | Freestanding / Floor-standing | |
| Wall-mounted / Floating | ||
| Corner | ||
| By Material | Wood | |
| Ceramic | ||
| Stone (Marble, Quartz, Granite) | ||
| Laminate / MDF | ||
| Others (Metal, Glass, Solid Surface) | ||
| By Sink Configuration | Single Sink | |
| Double Sink | ||
| Others (e.g., Vessel, Integrated Multi-bowl) | ||
| By End User | Residential | |
| Commercial | ||
| By Distribution Channel | B2C/Retail | Home Centers |
| Specialty Furniture Stores (including exclusive brand outlets) | ||
| Online | ||
| Other Distribution Channels (includes hypermarkets, supermarkets, teleshopping, warehouse clubs, departmental stores, etc.) | ||
| B2B/Directly from Manufacturers | ||
| By Geography | England | |
| Scotland | ||
| Wales | ||
| Northern Ireland | ||
Key Questions Answered in the Report
What is the projected value of United Kingdom bathroom vanities by 2031?
The category is forecast to reach USD 3.27 billion by 2031, growing at a 5.25% CAGR from 2026.
Which installation format is growing fastest in the United Kingdom?
Wall-mounted units are projected to grow at an 6.42% CAGR through 2031, supported by compact bathroom layouts.
What material has the largest share in the United Kingdom bathroom furniture?
Wood held 30.80% share in 2025 and stone is forecast to grow at a 6.84% CAGR through 2031.
What sink configuration has the largest share in the United Kingdom bathroom furniture?
Single-sink units accounted for 58.91% of the 2025 United Kingdom bathroom vanities market share, while double-sink units advanced at a 6.17% CAGR.