
Stainless Steel Powder Market Size and Share
Market Overview
| Study Period | 2022 - 2032 |
|---|---|
| Market Size (2027) | USD 0.92 Billion |
| Market Size (2032) | USD 1.15 Billion |
| Growth Rate (2027 - 2032) | 4.63 % |
| Fastest Growing Market | North America |
| Largest Market | Asia-Pacific |
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Stainless Steel Powder Market Analysis by Mordor Intelligence
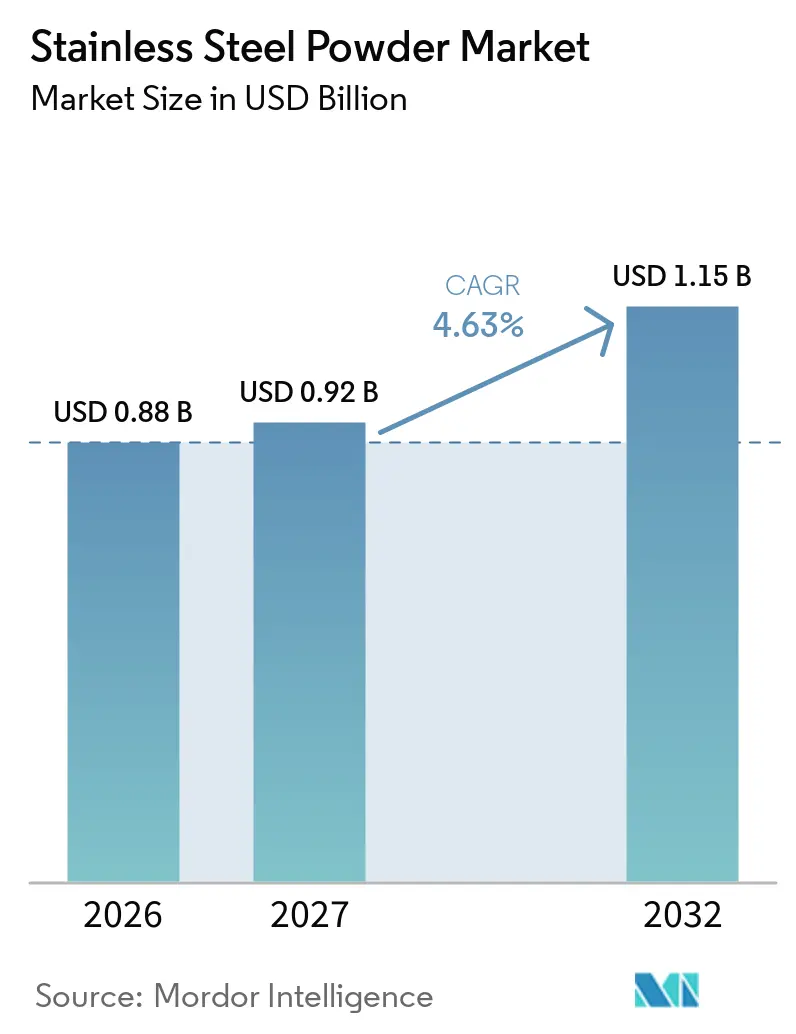
The stainless steel powder market size was valued at USD 0.88 billion in 2026 and is estimated to grow from USD 0.92 billion in 2027 to reach USD 1.15 billion by 2032, at a CAGR of 4.63% during the forecast period (2027-2032). The stainless steel powder market is being shaped by a shift from prototype production to qualified serial production in metal additive manufacturing. Demand also reflects the replacement of conventional wrought components, where powder-based production can enable lower weight, improved corrosion resistance, or more complex geometries. Regulated applications are raising expectations for traceability, documented powder properties, and repeatable manufacturing controls. Asia-Pacific supplies high demand through powder metallurgy and metal injection molding, while North America shows faster growth in qualified specialty materials. These conditions create distinct opportunities for producers serving cost-sensitive applications and for suppliers serving high-value applications with strict documentation requirements.
Key Report Takeaways
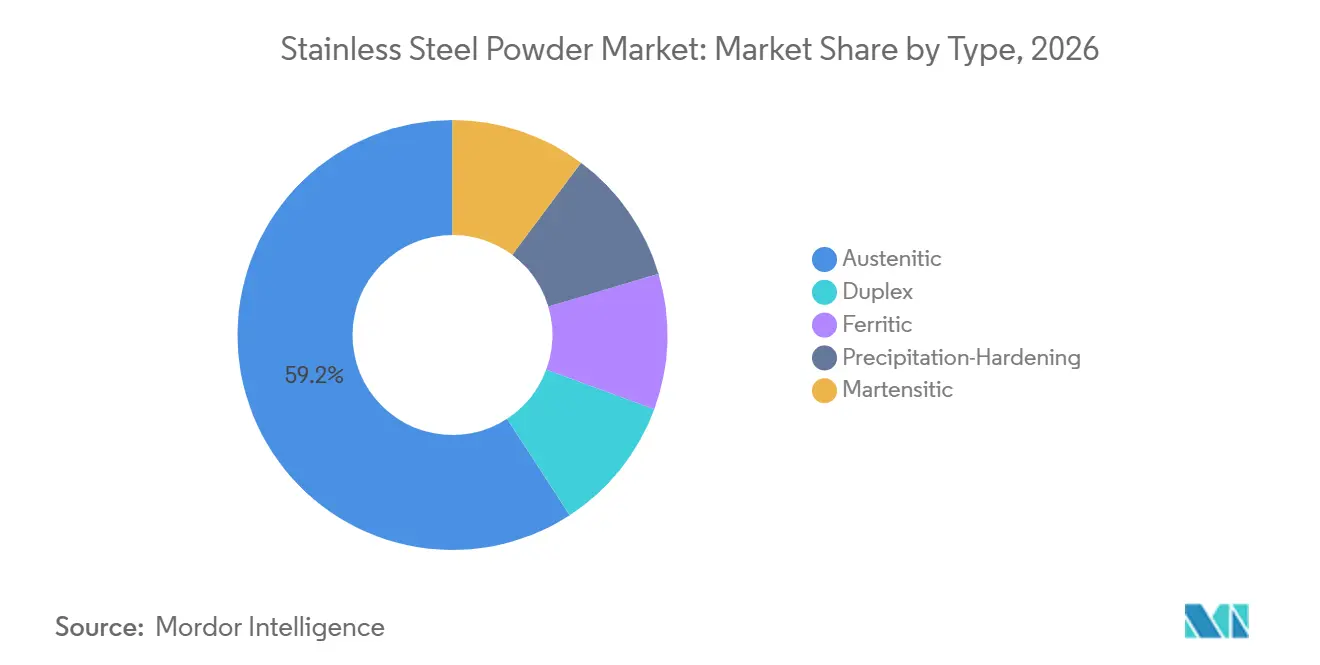
- By type, Austenitic grades held 59.17% of the stainless steel powder market share in 2026, while Duplex grades are projected to grow at a 5.25% CAGR through 2032.
- By manufacturing process, Water atomization held 39.74% of the stainless steel powder market share in 2026, while Gas atomization is projected to grow at a 5.58% CAGR through 2032.
- By application, Powder metallurgy held 40.35% of the stainless steel powder market share in 2026, while Additive manufacturing is projected to grow at a 5.61% CAGR through 2032.
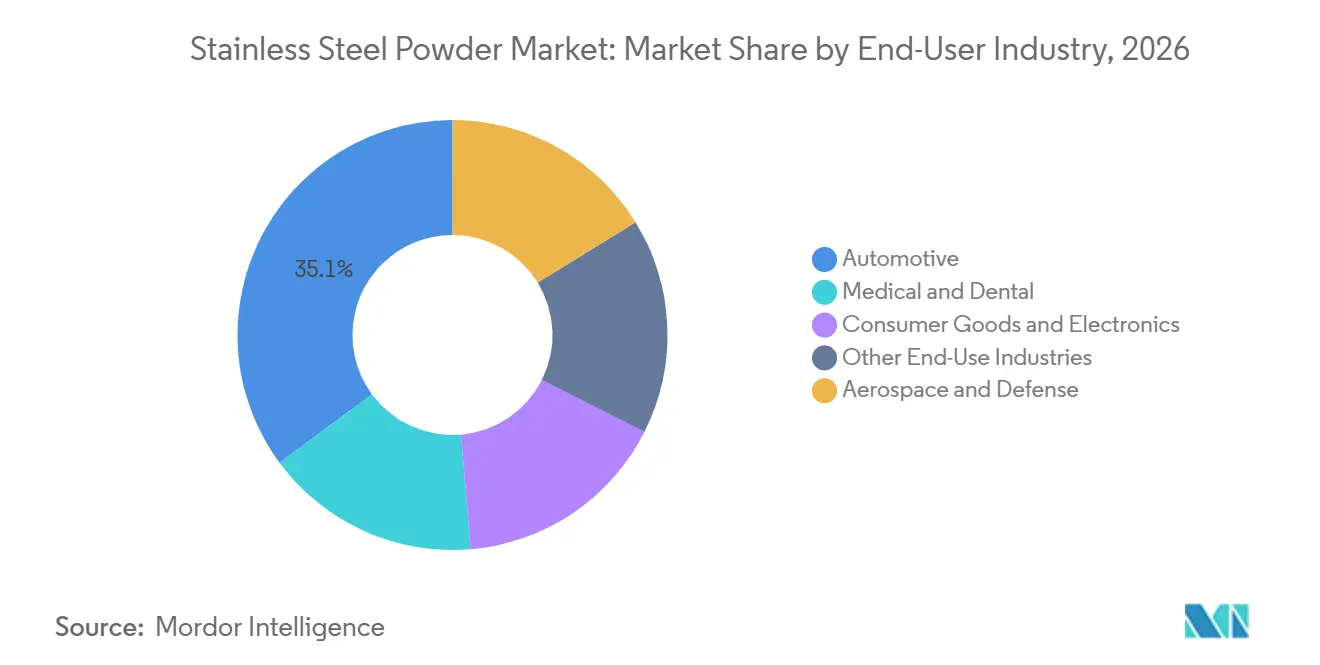
- By end-user industry, Automotive held 35.13% of the stainless steel powder market share in 2026, while Medical and dental are projected to grow at a 5.93% CAGR through 2032.
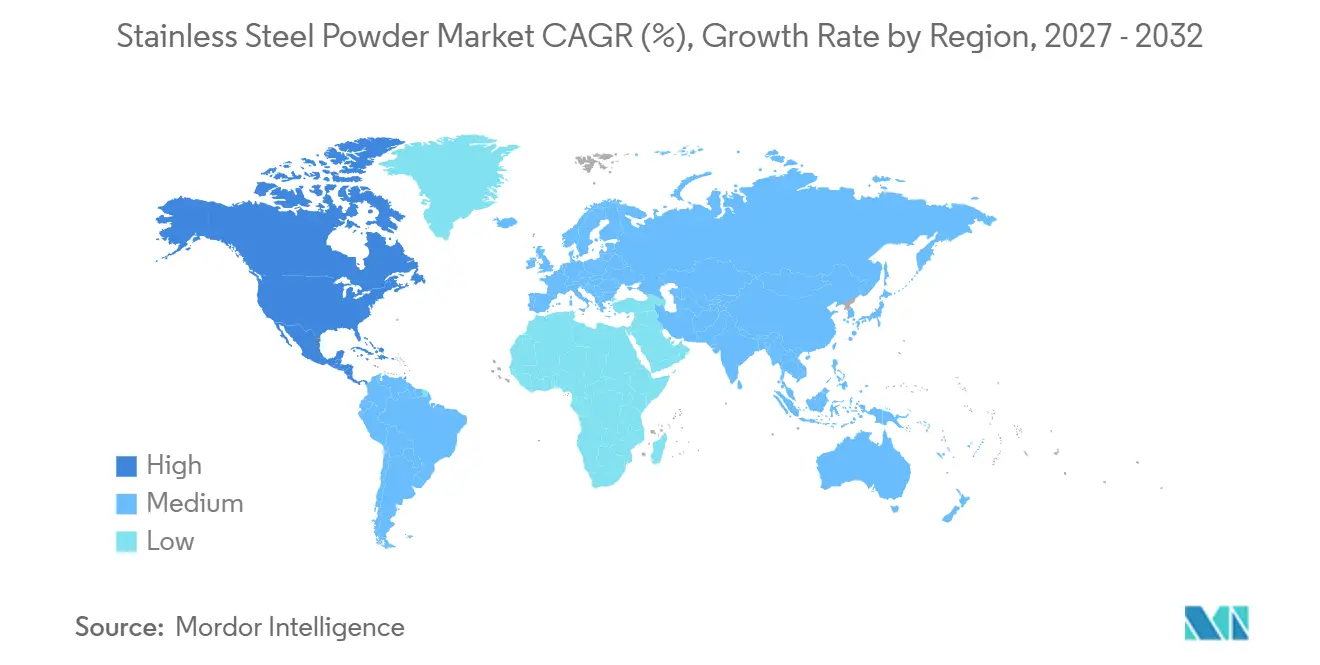
- By geography, Asia-Pacific held 43.89% of the stainless steel powder market share in 2026, while North America is projected to grow at a 5.77% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Global Stainless Steel Powder Market Trends and Insights
Drivers Impact Analysis*
| Drivers | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Expansion of Metal Additive Manufacturing | +1.80% | Global, led by North America, Europe, and the Asia-Pacific | Short term (≤ 2 years) |
| Demand for Lightweight, Corrosion-Resistant Components | +1.20% | Global, strongest in the Asia-Pacific automotive and North America aerospace | Medium term (2-4 years) |
| Growth of Metal Injection Molding in Miniaturized Components | +0.90% | Asia-Pacific, with spillover to North America and Europe | Medium term (2-4 years) |
| Increasing Aerospace and Defense Production | +0.80% | North America and Europe, with early-stage growth in the Asia-Pacific | Medium term (2-4 years) |
| Digital Qualification of Powder-to-Part Manufacturing Chains | +0.50% | North America and Europe | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Expansion of Metal Additive Manufacturing
Metal additive manufacturing is moving into serial production, which is raising demand for gas-atomized stainless grades with consistent quality. Qualified programs tend to require a stable, grade-specific supply over the life of a part design, which benefits the stainless steel powder market. In May 2025, Outokumpu delivered a new austenitic stainless powder for an aerospace heat-exchange component, positioning the material as an alternative to nickel-based alloys in laser powder bed fusion applications. This development supports the demand for spherical powders with documented lot history. ISO/ASTM 52953:2025 also establishes requirements for data registration in laser powder bed fusion process monitoring and quality control.
Rising Demand for Lightweight, Corrosion-Resistant Components
Applications requiring lower weight, corrosion resistance, and complex component geometry are driving demand in the stainless steel powder market. High-strength austenitic formulations can support weight reduction in body structures when paired with suitable manufacturing routes. Stainless steel and aluminum composite battery casings can reduce weight by 20-30% relative to pure stainless designs while meeting impact requirements. Aperam has introduced 316A, a molybdenum-reduced material intended to maintain corrosion resistance while addressing input-cost considerations in electric-vehicle applications[1]. These applications favor fine, gas-atomized powder when a complex powder-based component is required, and the choice of material can support longer component life in corrosive operating environments.
Growth of Metal Injection Molding in Miniaturized Components
Metal injection molding remains important in the stainless steel powder market because it enables the production of small, complex-shaped components. According to JH-MIM, stainless feedstock accounts for 50-69% of material use in metal injection molding. The process can produce dense parts and serve high-volume applications that are difficult to machine economically. A 2025 study reported the fabrication of a nickel-free stainless steel compact through metal injection molding for watch exterior components, supporting use in consumer wearables where material selection and surface finish are important. Fine-particle requirements in micro-metal injection molding also increase the need for controlled classification and sieving capability.
Increasing Aerospace and Defense Production
Aerospace and defense programs are adding demand for stainless powders that meet defined process and documentation requirements. In June 2025, the ASTM Additive Manufacturing Center of Excellence launched a manufacturer certification program with participation from more than 25 original equipment manufacturers, including Boeing, Lockheed Martin, and Safran. The DECSAM program, running from 2024 to 2028 with a budget of USD 48 million, links powder supply, in-process quality assurance, and digital manufacturing for aerospace serial production. These requirements support demand in the stainless steel powder market for traceable lots, particularly for 316L and 17-4PH applications.
Restraints Impact Analysis*
| Restraints | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Nickel and Chromium Price Volatility | -0.70% | Global, most acute for austenitic and duplex grade producers | Short term (≤ 2 years) |
| High Production, Classification, and Quality-Control Costs | -0.60% | Global, especially where additive manufacturing-grade specifications apply | Medium term (2-4 years) |
| Powder Traceability Requirements Across Distributed Printing Networks | -0.30% | North America and Europe, with emerging relevance in the Asia-Pacific | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Nickel and Chromium Price Volatility
Nickel and chromium costs influence the economics of austenitic and duplex powder production. Changes in the availability and pricing of these alloying metals can affect producer margins and customer purchasing decisions. Fine-particle powder production can intensify cost pressure because a narrow particle-size range limits the salable yield from atomization. The stainless steel powder market is more exposed to this issue in premium grades that require tight size control. Producers must balance material surcharges, metal availability, and customer expectations for consistent quality.
High Production, Classification, and Quality-Control Costs
Gas atomization and lot-level quality control require capital investment and ongoing operating expenditure. A 2025 Powder Technology study found that a broader acceptable powder size range improves yield and reduces both cost and carbon intensity for gas-atomized American Iron and Steel Institute (AISI) 316L powder. This creates a practical tradeoff, as laser powder bed fusion and micro-metal injection molding often require narrow particle-size specifications. The stainless steel powder market must therefore support both broad-range powder metallurgy grades and tightly classified premium grades. Aviation and medical applications may also require formal quality-system documentation. These requirements can limit participation by suppliers that lack sufficient scale or certification capability.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Type: Austenitic Grades Dominate, While Duplex Grades Gain Ground in Structural Applications
Austenitic grades held 59.17% of the stainless steel powder market share in 2026. Grades such as 316L and 304L combine corrosion resistance, biocompatibility, and formability. These properties support their use in powder metallurgy, metal injection molding, and additive manufacturing. Martensitic grades are used for cutting tools and bearing components where hardness is a priority. Ferritic grades are used for cost-sensitive sintered components, while precipitation-hardening grades, including 17-4PH, are used in high-strength aerospace parts.
Duplex grades are forecast to grow at a 5.25% CAGR through 2032. Their strength-to-weight properties support structural applications in aerospace and offshore industries. A 2025 additive manufacturing study reported a balanced austenite-ferrite microstructure and a yield strength of 735 MPa in optimized laser powder bed fusion 2507 duplex stainless steel. The same study reported pitting resistance in 3.5% sodium chloride. The stainless steel powder market supports this segment through alloy design, morphology control, and process documentation.

By Manufacturing Process: Water Atomization Holds Scale While Gas Atomization Serves Premium Uses
Water atomization accounted for 39.74% of global revenue in 2026. It is widely used in powder metallurgy compaction where cost per kilogram and compressibility are more important than particle sphericity. The process supports high-quantity production of conventional automotive and industrial components. Water-atomized powders remain relevant where stable chemistry, suitable particle size, and dependable supply are required. This manufacturing route provides a large and established demand base for the stainless steel powder market.
Gas atomization is forecast to grow at a 5.58% CAGR through 2032. It supports applications that require spherical morphology, low satellite content, and narrow particle-size distributions. A 2025 study compared nitrogen- and argon-atomized super-duplex stainless steel powders for additive manufacturing. Nitrogen atomization produced a finer particle-size distribution, while both gases delivered adequate flowability. Plasma atomization and electrode induction melting gas atomization are used in applications requiring high purity and low contamination.
By Application: Powder Metallurgy Leads by Output, While Additive Manufacturing Drives Value Growth
Powder metallurgy accounted for 40.35% of global revenue in 2026. Conventional compaction and sintering support high quantities of automotive and industrial components. Water-atomized stainless grades are used where production scale and dimensional control are central requirements. Metal injection molding is a significant secondary application, as it can produce complex stainless steel components with tight tolerances. This established application base supports consistent demand across several end uses.
Additive manufacturing is forecast to grow at a 5.61% CAGR through 2032. Demand includes aerospace heat exchangers, patient-specific devices, and defense spare parts where complex geometry adds value. Outokumpu's 2025 aerospace powder delivery illustrates the development of specialty austenitic grades for this application. Producers are expanding their portfolios beyond general-purpose 316L to include 15-5PH, 254 SMO, and duplex alloys. Thermal spray, filter media, and surface treatment remain additional applications with stable demand.
By End-User Industry: Automotive Provides the Base While Medical and Dental Set the Pace
Automotive accounted for 35.13% of global revenue in 2026. Sintered drivetrain, brake, and structural components support this position through high-quantity production. The industry also requires precise components that can be produced through established powder metallurgy methods. Electric vehicle development adds potential demand in battery casing interfaces and thermal management components.
Medical and dental are forecast to grow at a 5.93% CAGR through 2032. A 2025 study on laser powder bed fusion of 316L reported 99.97% density, 762.83 MPa tensile strength, and 253.07 HV hardness under optimized conditions. These results support the material's use in orthopedic and dental applications. Documentation requirements favor suppliers with established material traceability practices. Consumer goods and electronics continue to use stainless steel feedstock for wearables, smartphones, and precision fasteners produced via metal injection molding.
Geography Analysis
Asia-Pacific held 43.89% of the stainless steel powder market share in 2026. China accounts for the majority of regional demand, driven by powder metallurgy and metal injection molding across the automotive, consumer electronics, and construction sectors. Japan supplies high-precision demand for watches, medical instruments, and electronics. South Korea benefits from electric vehicle and semiconductor clusters, while India is developing its automotive and defense production. ASEAN countries see incremental demand for powder as industrial activity expands, although additive manufacturing remains in its early stages across much of Southeast Asia.
North America is forecast to grow at a 5.77% CAGR through 2032. Defense-related additive manufacturing and near-shoring of specialty powder supply support this outlook. Canada adds aerospace demand, while Mexico supports conventional automotive powder metallurgy output. The region combines a growing need for documented specialty grades with continued demand for conventional materials.
Europe is a market for aerospace, industrial tooling, and medical device applications. The DECSAM program connects domestic powder supply, digital manufacturing, and in-process quality assurance for laser powder bed fusion aerospace parts. South Africa's Council for Scientific and Industrial Research began developing domestic 316L stainless steel gas-atomization capability in 2025 for aerospace, medical, and oil-and-gas applications[2].
Competitive Landscape
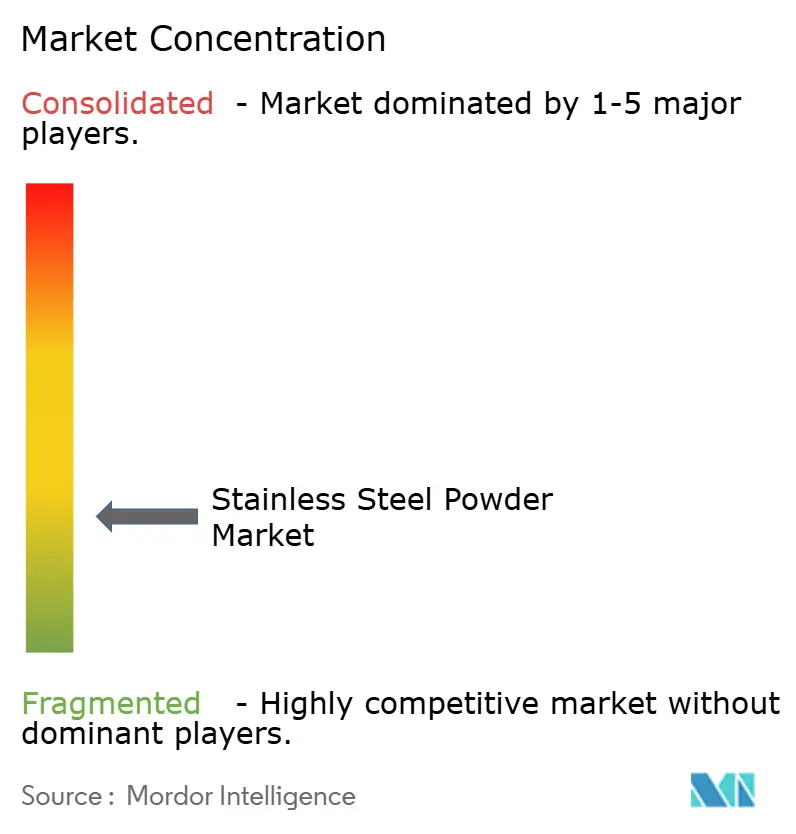
The stainless steel powder market is fragmented. Sandvik AB, Carpenter Technology Corporation, GKN Powder Metallurgy, and Outokumpu form the competitive tier. Suppliers compete on alloy range, atomization control, powder consistency, and documentation quality. These factors are most critical in aerospace, medical, and other regulated applications. Conventional powder metallurgy buyers also consider cost and supply reliability.
Höganäs launched re-Astaloy 85 Mo in June 2025, with a stated 14.00% reduction in product carbon footprint through biogas substitution. The company also partnered with Blykalla in 2025 to advance materials for small modular reactor applications. Sandvik launched the Osprey MAR 55 in August 2025 for additive manufacturing applications involving tool steel and maraging steel. These developments reflect efforts to serve both established powder metallurgy customers and specialized applications. Documentation-focused products can help suppliers meet qualification requirements for regulated applications.
The stainless steel powder market presents opportunities in nickel-free grades for medical and wearable applications, as well as in lower-carbon additive manufacturing feedstocks. Outokumpu's aerospace powder work demonstrates the potential of specialty stainless compositions for qualified uses. Chinese suppliers, including Hunan Fushel Technology and Shijiazhuang Lide Powder Material, compete in cost-sensitive powder metallurgy and metal injection molding segments. Qualification requirements can limit their access to aerospace and medical programs, maintaining the distinction between widely available grades and materials used in regulated, high-value applications.
Stainless Steel Powder Industry Leaders
-
Höganäs AB
-
Sandvik AB
-
Daido Steel Co., Ltd.
-
MITSUBISHI STEEL MFG. CO., LTD.
-
Shijiazhuang Lide Powder Material Co., Ltd.
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- September 2026: U.S. DoD Solicits 316L and 17-4PH Stainless Steel Powder for Defense AM Programs: The Department of Defense issued procurement solicitations for certified stainless steel powder for metal additive manufacturing defense components. The solicitations specified EOS M400-4 machine compatibility, alloy purity documentation, and mill test report requirements, establishing the DoD as a recurring customer for qualified domestic stainless steel powder producers.
- August 2025: Sandvik introduced Osprey MAR 55, a tool steel powder designed to bridge the gap between maraging steels and tool steels. The product delivers mechanical properties and wear resistance in the as-built condition without requiring post-build heat treatment, reducing process steps for stainless steel powder AM fabricators.
Global Stainless Steel Powder Market Report Scope
Stainless steel powder is a fine metallic material produced by converting raw stainless steel, an iron-based alloy containing at least 10% to 11% chromium, into small, uniform particles. The conversion process breaks down bulk stainless steel into powder form, which is then used across a range of industrial and manufacturing applications.
The stainless steel powder market is segmented by type, manufacturing process, application, end-user industry, and geography. By type, the market is segmented into austenitic, martensitic, duplex, ferritic, and precipitation-hardening. By manufacturing process, the market is segmented into water atomization, gas atomization, and other manufacturing processes. By application, the market is segmented into powder metallurgy, metal injection molding, additive manufacturing, and other applications. By end-user industry, the market is segmented into automotive, aerospace and defense, medical and dental, consumer goods and electronics, and other end-use industries. The report also covers market sizes and forecasts for the stainless steel powder across 15 countries in major regions. The market sizes and forecasts are provided in terms of value (USD).
| Austenitic |
| Martensitic |
| Duplex |
| Ferritic |
| Precipitation-Hardening |
| Water Atomization |
| Gas Atomization |
| Other Manufacturing Processes |
| Powder Metallurgy |
| Metal Injection Molding |
| Additive Manufacturing |
| Other Applications |
| Automotive |
| Aerospace and Defense |
| Medical and Dental |
| Consumer Goods and Electronics |
| Other End-Use Industries |
| Asia-Pacific | China |
| India | |
| Japan | |
| South Korea | |
| ASEAN Countries | |
| Rest of Asia-Pacific | |
| North America | United States |
| Canada | |
| Mexico | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| NORDIC Countries | |
| Rest of Europe | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Middle East and Africa | Saudi Arabia |
| South Africa | |
| Rest of Middle East and Africa |
| By Type | Austenitic | |
| Martensitic | ||
| Duplex | ||
| Ferritic | ||
| Precipitation-Hardening | ||
| By Manufacturing Process | Water Atomization | |
| Gas Atomization | ||
| Other Manufacturing Processes | ||
| By Application | Powder Metallurgy | |
| Metal Injection Molding | ||
| Additive Manufacturing | ||
| Other Applications | ||
| By End-User Industry | Automotive | |
| Aerospace and Defense | ||
| Medical and Dental | ||
| Consumer Goods and Electronics | ||
| Other End-Use Industries | ||
| By Geography | Asia-Pacific | China |
| India | ||
| Japan | ||
| South Korea | ||
| ASEAN Countries | ||
| Rest of Asia-Pacific | ||
| North America | United States | |
| Canada | ||
| Mexico | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| NORDIC Countries | ||
| Rest of Europe | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Middle East and Africa | Saudi Arabia | |
| South Africa | ||
| Rest of Middle East and Africa | ||
Key Questions Answered in the Report
What is current market size of Stainless Steel Powder Market?
The stainless steel powder market size was valued at USD 0.88 billion in 2026 and is estimated to grow from USD 0.92 billion in 2027 to reach USD 1.15 billion by 2032, at a CAGR of 4.63% during the forecast period (2027-2032).
Which application is expanding fastest for stainless powder?
Additive manufacturing is forecast to grow at a 5.61% CAGR through 2032, supported by aerospace, medical, and defense uses.
Which end-user sector is expected to grow fastest?
Medical and dental are projected to grow at a 5.93% CAGR through 2032, supported by patient-specific devices and stainless materials with documented quality.
Which region leads demand for stainless steel powder?
Asia-Pacific leads with 43.89% share in 2026, while North America has the fastest projected growth at a 5.77% CAGR through 2032.