
South America Data Center Testing, Inspection, and Certification Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
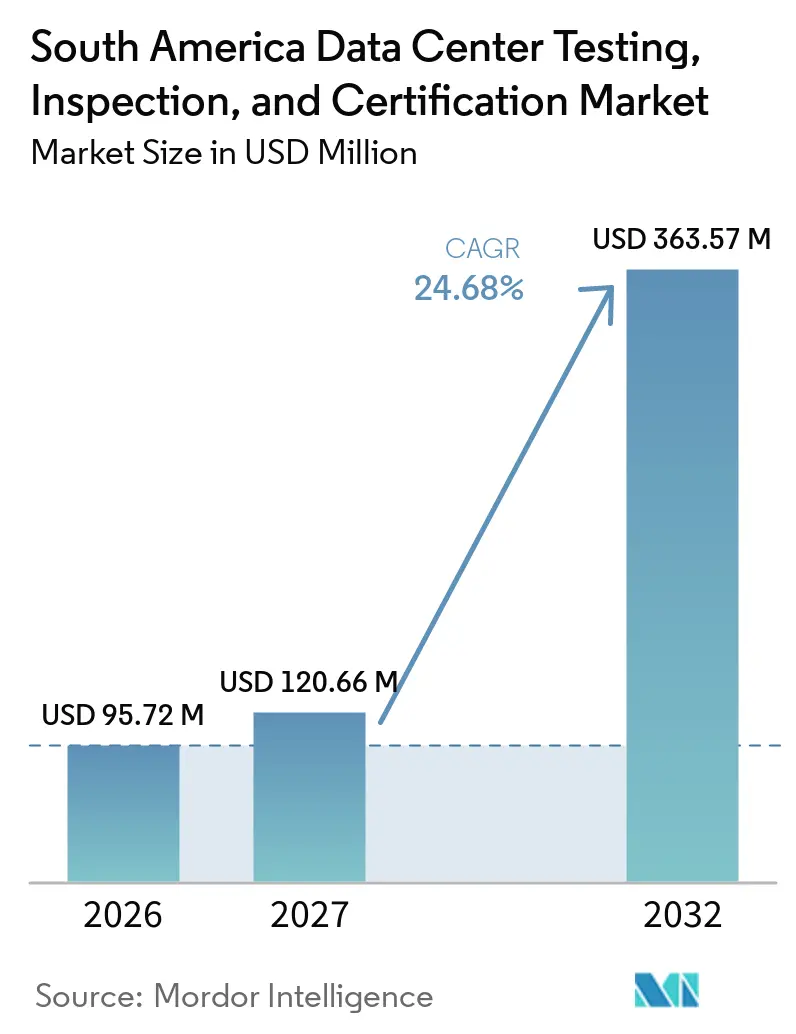
| Base Year Market Size (2026) | USD 95.72 Million |
| Market Size (2027) | USD 120.66 Million |
| Market Size (2032) | USD 363.57 Million |
| Growth Rate (2027 - 2032) | 24.68 % |
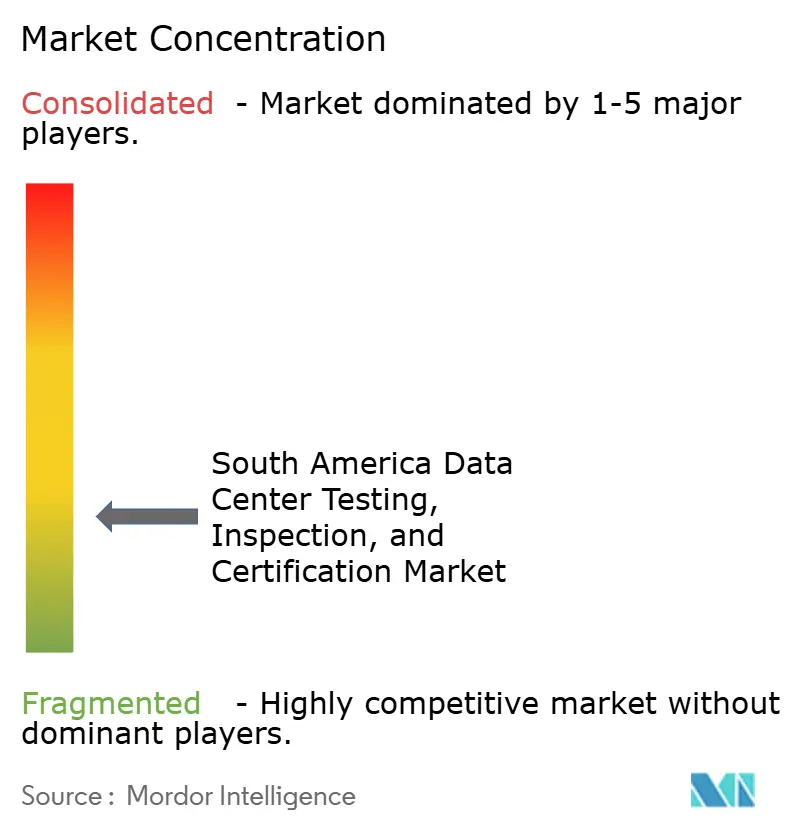
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
South America Data Center Testing, Inspection, and Certification Market Analysis by Mordor Intelligence
The South America data center testing, inspection, and certification market size is valued at USD 95.72 million in 2026 and is forecast to reach USD 363.57 million by 2032, registering a CAGR of 24.68% during 2027-2032. The South America data center testing, inspection, and certification market is being shaped by a large pipeline of new facilities, which increases the need for independent acceptance testing before commercial service begins. Higher power densities in AI-oriented facilities also require more detailed validation of power, cooling, and control systems. Regulatory requirements in Brazil and Chile are adding formal compliance checks to project planning and operating procedures. Providers with regional accreditation, skilled commissioning teams, and the ability to combine inspection with certification are better placed to serve larger projects. The opportunity extends beyond construction because operators require periodic reviews of security, energy, resilience, and environmental practices.
Key Report Takeaways
- By service type, testing held 40.21% of the South America data center testing, inspection, and certification market share in 2026, while compliance and assurance services are projected to expand at a 24.89% CAGR through 2032.
- By data center lifecycle, construction, installation, and commissioning accounted for 57.31% of the South America data center TIC market revenue share in 2026, while operations, maintenance, and recertification are projected to expand at a 24.93% CAGR through 2032.
- Within the infrastructure system, electrical infrastructure accounted for 37.79% of revenue in 2026, while IT, network, and cybersecurity infrastructure are projected to expand at a 25.14% CAGR through 2032.
- By data center type, colocation data centers accounted for 40.98% revenue share in 2026, while edge and modular data centers are projected to expand at a 25.22% CAGR through 2032.
- By tier type, Tier 3 facilities held 61.78% revenue share in 2026, while Tier 4 facilities are projected to expand at a 24.94% CAGR through 2032.
- By geography, Brazil held 58.44% of the South America data center testing, inspection, and certification market share in 2026, while Peru is projected to expand at a 25.34% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
South America Data Center Testing, Inspection, and Certification Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Hyperscale and AI Workload Commissioning Intensity | +6.5% | Brazil, Chile, Colombia, Peru | Short term (≤ 2 years) |
| Expansion of Outsourced Mission-Critical Assurance | +4.8% | Brazil, Chile | Medium term (2-4 years) |
| Data Sovereignty and Local Compliance Requirements | +3.9% | Brazil primary, spillover to Chile and Colombia | Medium term (2-4 years) |
| Renewable Power and Sustainability Certification Demand | +3.2% | Chile, Brazil, Colombia | Long term (≥ 4 years) |
| Remote Inspection and Continuous Assurance Adoption | +2.1% | South America | Medium term (2-4 years) |
| Failure Cost Avoidance in High-Density Facilities | +1.8% | Brazil, Chile | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Hyperscale and AI Workload Commissioning Intensity
The South America data center testing, inspection, and certification market benefits when large facilities move from design into commissioning. A new high-capacity site needs testing of generators, uninterruptible power systems, cooling equipment, and integrated controls before it can receive commercial load. AI workloads make this work more demanding because dense racks place greater pressure on electrical and thermal systems. Independent providers can assess performance without the conflict that may arise when the equipment supplier also verifies its own work. Brazil's Ministry of Mines and Energy authorized the power connection ramp-up for Scala AI City in May 2025, supporting a long construction pipeline that will require technical review and commissioning services.
Expansion of Outsourced Mission-Critical Assurance
The South America data center testing, inspection, and certification market is supported by developers that use independent specialists for commissioning and quality control. Outsourcing allows developers to bring in personnel who understand factory acceptance tests, site acceptance tests, fire safety checks, and integrated systems tests. SGS describes data center services that cover testing, inspection, and compliance work across the asset lifecycle. SGS Bureau Veritas also offers data center and telecommunications services that span technical assurance needs for critical facilities.[1] Larger providers can apply common methods across several countries, which is useful when operators follow the same standards across regional campuses. This service model also gives clients a clearer record of independent checks during project handover.
Data Sovereignty and Local Compliance Requirements
The South America data center testing, inspection, and certification market gains support when data governance and telecommunications rules require auditable controls. Brazil's government outlined a new data governance policy in 2025 that emphasizes stronger governance practices for public-sector data.[2] Brazil's telecommunications framework has also placed data centers connected to telecommunications networks under closer regulatory attention. Providers that can evaluate information security, resilience, electromagnetic compatibility, and operational documentation are positioned to support operators through these requirements. The proposed Brazilian legislation on efficiency and sustainability for data centers would require annual reporting and recognize renewable-energy compliance practices. These rules make local knowledge and recognized certifications more important in procurement decisions.
Renewable Power and Sustainability Certification Demand
The South America data center testing, inspection, and certification market is also linked to sustainability credentials that data center clients request from operators. Renewable energy documentation helps operators demonstrate the source and traceability of purchased electricity. Atlas Renewable Energy and ODATA announced an agreement in January 2025 to supply I-REC-certifiable renewable energy to ODATA's Chilean facilities. This type of arrangement creates a need to verify energy claims and retain supporting records. Brazil's REDATA incentive regime also connects eligibility to documented clean-energy, water-efficiency, and research obligations. Sustainability assurance can therefore become part of routine compliance work rather than a separate voluntary exercise.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Shortage of Local High-Voltage and Commissioning Specialists | -1.5% | South America | Medium term (2-4 years) |
| Fragmented Country-Level Permitting and Compliance Rules | -1.2% | National level, with acute impact in Brazil, Chile, Colombia | Medium term (2-4 years) |
| Liquid-Cooling Protocols Outpacing Local Test Capability | -0.9% | Brazil, Chile | Long term (≥ 4 years) |
| Budget Pressure Among Smaller Enterprise Facilities | -0.7% | Argentina, Rest of South America | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Shortage of Local High-Voltage and Commissioning Specialists
The availability of qualified people can limit the pace of the South America data center testing, inspection, and certification market. High-voltage testing, integrated commissioning, and liquid-cooling validation require practical experience as well as formal training. Vertiv expanded its Latin America Academy in Barueri during 2025 and added hands-on liquid-cooling training for data center professionals.[3] Training programs improve the local skills base, but experienced personnel remain necessary for complex live projects. Operators in smaller cities may still rely on teams from larger markets, which can raise costs and extend project schedules. The gap is most visible where projects combine high-density computing with new power and cooling designs.
Fragmented Country-Level Permitting and Compliance Rules
The South America data center testing, inspection, and certification market operates across countries with distinct approval procedures and accredited bodies. A standard recognized in one country may not remove the need for a separate local assessment in another. Brazil's accreditation system recognizes organizations that demonstrate competence for conformity assessment activities. This structure supports rigor but can increase documentation work for operators with facilities in several countries. Smaller providers may find it harder to maintain the necessary range of local accreditation and technical staff. The complexity favors organizations that can coordinate certification, inspection, and project records across national requirements.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Service Type: Testing Holds the Largest Share While Compliance Services Lead Growth
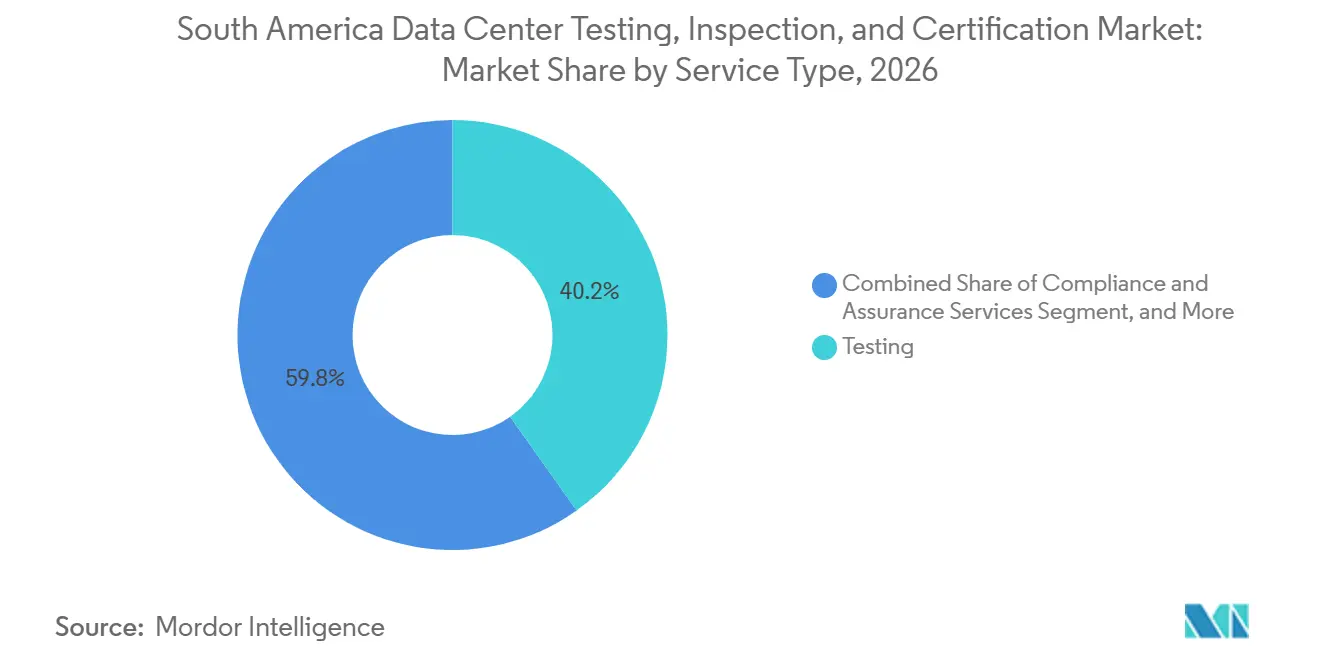
Testing accounted for 40.21% of the South America data center testing, inspection, and certification market in 2026. It is required throughout commissioning, from checks on individual equipment to integrated reviews of the power and cooling chain. Factory acceptance testing can identify issues before equipment reaches the site. Site acceptance testing then confirms that installed systems perform under project conditions. These activities are important for generators, uninterruptible power systems, switchgear, cooling equipment, and the control systems that connect them. The testing role becomes more detailed when operators deploy high-density computing loads.
Compliance and assurance services are projected to expand at a 24.89% CAGR through 2032. This segment benefits from recurring assessment needs rather than a single construction event. Operators may seek reviews against ISO/IEC 27001, ISO 14001, ISO 50001, TIA-942, and other applicable standards. TÜV Rheinland identifies data center infrastructure certification as a service that addresses facility reliability and related operational requirements. Inspection services remain relevant for structural, electrical, and fire-safety work. Certification is increasingly combined with advisory and documentation support because clients want one coordinated compliance process.

By Data Center Lifecycle: Construction and Commissioning Lead While Recertification Builds a Recurring Base
Construction, installation, and commissioning held 57.31% of the South America data center TIC market in 2026. New builds require formal checks before equipment can support commercial operations. The work starts with design review and supplier verification, then continues through installation and integrated testing. This concentration reflects the scale of planned facilities and the need to establish performance evidence before handover. Commissioning specialists also help ensure that procedures, test records, and corrective actions are complete. A construction-led profile can create substantial demand but also makes service activity sensitive to project schedules.
Operations, maintenance, and recertification are projected to expand at a 24.93% CAGR through 2032. Facilities that entered service in prior construction cycles will need continuing reviews of their resilience, information security, and operating practices. Uptime Institute explains that its Tier Certification program evaluates key aspects of data center infrastructure performance. Operating teams can use these assessments to maintain evidence for clients, insurers, and internal governance. Pre-construction services also have value because early design reviews can reduce later rework. Retrofit and modernization activities will become more relevant where older sites need upgrades for higher rack density or new cooling methods.
By Infrastructure System: Electrical Systems Lead While Cybersecurity Testing Expands Fastest
Electrical infrastructure held 37.79% of the South America data center testing, inspection, and certification market in 2026. The segment includes high-voltage interfaces, substations, generators, switchgear, and uninterruptible power systems. These systems need careful testing because failures can affect the full facility. Power equipment is examined during factory acceptance testing and again after installation. Integrated testing then checks whether equipment transfers and control sequences operate as intended. Electrical work remains central to both traditional enterprise facilities and large colocation campuses.
IT, network, and cybersecurity infrastructure is projected to expand at a 25.14% CAGR through 2032. Information security and operational technology are increasingly assessed together, particularly in facilities that support telecommunications traffic and cloud workloads. Brazil's policy and regulatory environment increases the importance of governance and documented cybersecurity controls. Mechanical, cooling, and fire-safety systems remain essential because AI equipment increases thermal loads. Testing providers that understand both facility systems and digital controls may offer more comprehensive services to project owners. Structural and physical-security testing continues to provide a steady base of activity for regional providers.
By Data Center Type: Colocation Leads While Edge and Modular Facilities Expand Quickly
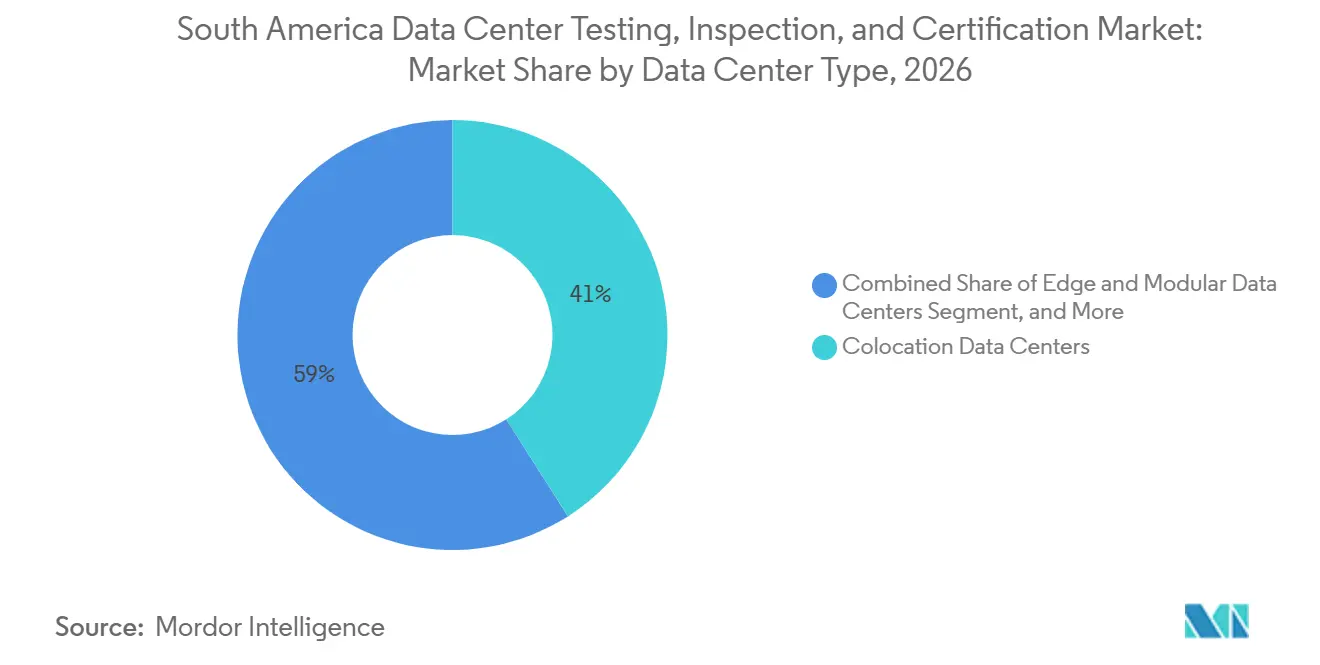
Colocation data centers accounted for 40.98% of the South America data center TIC market in 2026. These facilities host several customers and often operate under detailed service and resilience expectations. Their scale can create repeat testing work as new halls, power systems, and cooling capacity are added. Shared facilities also require clear operating procedures, as failures can affect multiple tenants. The presence of large cloud customers increases scrutiny of commissioning evidence and certification records. Colocation operators, therefore, have an incentive to use independent providers that can work across construction and operations.
Edge and modular data centers are projected to expand at a 25.22% CAGR through 2032. These smaller facilities can support local workloads in secondary cities and may be deployed more frequently than a large centralized campus. Each site still needs documented checks for power, cooling, safety, and communications. The South America data center testing, inspection, and certification market can benefit from providers that have local field teams and repeatable assessment methods. Hyperscale facilities generate high-value assignments, but their project awards are concentrated among a small number of owners. Enterprise facilities remain important, although some operators may select narrower service scopes when budgets are limited.
By Tier Type: Tier 3 Is the Mainstream Standard While Tier 4 Gains Demand
Tier 3 facilities held 61.78% of the South America data center TIC market in 2026. This classification is widely used for facilities that require concurrent maintainability. Uptime Institute describes Tier Certification as a framework for evaluating infrastructure topology and its expected performance. Tier 3 requirements are relevant to cloud, colocation, financial services, and other workloads where outages have material consequences. The category provides a practical balance between resilience objectives and the cost of redundant infrastructure. Its large share shows that operators are prioritizing dependable service without universally adopting the most complex topology.
Tier 4 facilities are projected to expand at a 24.94% CAGR through 2032. This classification is relevant to use cases that require fault-tolerant design and higher redundancy. Financial services and public-sector digital services can place a premium on this level of resilience. The South America data center testing, inspection, and certification market requires experienced professionals to validate these more complex arrangements. Tier 1 and Tier 2 facilities continue to serve the needs of smaller enterprises and regional networks. Their assurance needs are often narrower, with greater emphasis on selected quality or safety checks than on full infrastructure certification.
Geography Analysis
Brazil held a 58.44% revenue share in the South America TIC market in 2026. The country's scale creates demand for commissioning, inspection, and recurring certification across several facility types. REDATA, issued in September 2025, conditions tax incentives on documented obligations related to clean energy, water efficiency, and research investment. These requirements make auditable records important for operators seeking the incentive. Brazil also has a mature base of conformity assessment organizations and multinational technical service providers. This combination supports larger and more frequent assignments than elsewhere in the region.
Chile is an important secondary location because of the availability of renewable energy and cloud investment, which support new facility construction. Atlas Renewable Energy and ODATA's 2025 agreement provides a documented route to I-REC-certifiable energy for Chilean data centers. Colombia offers a distinct opportunity through its established digital infrastructure and formal accreditation system. Gtd Colombia renewed the Uptime Institute Tier III Gold Certification of Operational Sustainability for its El Poblado facility in January 2026. This shows how operational certifications can generate recurring assessment activity after a facility is built. Argentina remains relevant for operators seeking energy-efficiency and management-system credentials.
Peru is projected to expand at a 25.34% CAGR through 2032 within the South America data center testing, inspection, and certification market. Its demand is linked to the development of digital infrastructure for financial services, public institutions, and colocation customers. A newly commissioned carrier-neutral facility in Lima received Tier III Certification of Design Documents in July 2025, which illustrates the type of reliability credential sought by newer facilities. This type of certification can set expectations for competing sites that seek comparable reliability credentials. Ecuador, Uruguay, Paraguay, Bolivia, and Venezuela remain earlier-stage locations for specialized assurance work. Their activity is generally tied to telecommunications operators and selected enterprise projects. The geographic mix allows providers with regional coverage to balance high-volume work in Brazil with emerging assignments in other countries.
Competitive Landscape
The South America data center testing, inspection, and certification market is fragmented because clients require different combinations of testing, inspection, certification, and technical advice. Global providers have an advantage on complex projects because they can combine multiple accreditations with specialized engineering resources. Bureau Veritas, SGS, TÜV Rheinland, Intertek, DEKRA, Applus+, and MISTRAS are among the relevant providers identified in the source material. Their offers differ by geography, technical specialization, and the depth of local delivery teams. No combined share for the leading firms is provided in the source material. The available evidence, therefore, supports a fragmented competitive structure rather than a concentrated one.
Bureau Veritas and DEKRA position their data center services across the project lifecycle, including design review, construction support, and operational needs. In 2026, SGS announced a data center offering that integrates performance, reliability, and compliance across project stages. TÜV Rheinland offers certification for data center infrastructure and supports operators that want to document reliability-related practices. These moves show that providers are seeking longer-term client relationships rather than isolated inspection assignments. Multi-standard service packages can simplify administration for operators managing several compliance obligations.
Competitive opportunities are strongest in liquid-cooling validation, cybersecurity controls, sustainability assurance, and continuous monitoring. These areas need both technical expertise and credible documentation. Applus+ presented integrated commissioning, quality assurance, quality control, and factory-inspection services for critical infrastructure at DCPI LATAM 2026. Providers can differentiate by helping clients manage evidence from remote systems alongside on-site tests. Smaller local firms can compete by offering faster access to local engineers or country-specific approval support. Larger firms retain an edge where a project needs coordinated delivery across several South American countries. A market concentration score is not calculated because the draft does not provide combined market shares for the top players.
South America Data Center Testing, Inspection, and Certification Industry Leaders
-
Bureau Veritas
-
SGS SA
-
TÜV Rheinland
-
UL Solutions
-
Intertek Group plc
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- September 2026: At DCD Connect LATAM, Bureau Veritas Mission Critical presented its approach to data-center quality assurance, quality control, and commissioning across Latin America, including projects in Brazil and Chile. The focus on design reviews, construction QA/QC, and commissioning reflects the need to verify that critical infrastructure performs as intended before operations begin.
- September 2026: Ascenty’s São Paulo 05 facility received ANSI/TIA-942-C Constructed Facility certification at Rating 3 on September 17. This is a verified certification milestone, although the public registry does not establish which independent assessment company conducted the certification.
- August 2026: Claro Trujillo’s data center received ANSI/TIA-942-C Design certification at Rating 2 on August 4. The milestone demonstrates demand for independent design verification in Peru; it should not be interpreted as a new contract announced by a TIC provider.
- April 2026: Cirion’s SAN2 hyperscale data center in Chile obtained Tier III of Design Documents certification from Uptime Institute, publicly reported in late April 2026. This validates design resilience and provides a clear example of third-party certification activity in the regional hyperscale segment.
South America Data Center Testing, Inspection, and Certification Market Report Scope
The South America Data Center Testing, Inspection, and Certification Market comprises independent third-party services that verify the safety, performance, reliability, and regulatory compliance of data center infrastructure across its full lifecycle from design review and construction through commissioning, operation, and modernization.
The South America Data Center Testing, Inspection, and Certification Market is Segmented by Service Type (Testing, Inspection, Certification, and Compliance), Data Center Lifecycle (Pre-Construction and Design, Construction, Installation and Commissioning, Operations, Maintenance and Recertification, and Retrofit and Modernization), Infrastructure System (Electrical Infrastructure, Mechanical, Cooling and Fire-Safety Infrastructure, Structural, Building and Physical Security Systems, and IT, Network and Cybersecurity Infrastructure), Data Center Type (Hyperscale and Cloud Service Provider Data Centers, Colocation, Enterprise, Edge and Modular), Tier (1 and 2, 3, 4), and Geography (Brazil, Chile, Argentina, Colombia, Peru, Rest of South America). The Market Forecasts are Provided in Terms of Value (USD).
| Testing |
| Inspection |
| Certification |
| Compliance and Assurance Services |
| Pre-Construction and Design |
| Construction, Installation and Commissioning |
| Operations, Maintenance and Recertification |
| Retrofit and Modernization |
| Electrical Infrastructure |
| Mechanical, Cooling and Fire-Safety Infrastructure |
| Structural, Building and Physical Security Systems |
| IT, Network and Cybersecurity Infrastructure |
| Hyperscale and Cloud Service Provider Data Centers |
| Colocation Data Centers |
| Enterprise Data Centers |
| Edge and Modular Data Centers |
| Tier 1 and Tier 2 |
| Tier 3 |
| Tier 4 |
| Brazil |
| Chile |
| Argentina |
| Colombia |
| Peru |
| Rest of South America |
| By Service Type | Testing |
| Inspection | |
| Certification | |
| Compliance and Assurance Services | |
| By Data Center Lifecycle | Pre-Construction and Design |
| Construction, Installation and Commissioning | |
| Operations, Maintenance and Recertification | |
| Retrofit and Modernization | |
| By Infrastructure System | Electrical Infrastructure |
| Mechanical, Cooling and Fire-Safety Infrastructure | |
| Structural, Building and Physical Security Systems | |
| IT, Network and Cybersecurity Infrastructure | |
| By Data Center Type | Hyperscale and Cloud Service Provider Data Centers |
| Colocation Data Centers | |
| Enterprise Data Centers | |
| Edge and Modular Data Centers | |
| By Tier Type | Tier 1 and Tier 2 |
| Tier 3 | |
| Tier 4 | |
| By Geography | Brazil |
| Chile | |
| Argentina | |
| Colombia | |
| Peru | |
| Rest of South America |
Key Questions Answered in the Report
What is the size of the South America data center testing, inspection, and certification market?
The sector is valued at USD 95.72 million in 2026 and is forecast to reach USD 363.57 million by 2032, at a 24.68% CAGR during 2027-2032.
What is driving demand for testing and certification services in South American data centers?
New facility construction, AI-related power density, independent commissioning requirements, and compliance obligations are supporting demand.
Which service type has the largest revenue share?
Testing leads with a 40.21% revenue share in 2026 because new facilities require structured commissioning before they begin commercial operations.
Which data center lifecycle stage is expanding fastest?
Operations, maintenance, and recertification is projected to expand at a 24.93% CAGR through 2032 as the installed base requires ongoing reviews.
Which country has the largest share in the region?
Brazil leads with 58.44% revenue share in 2026, supported by its large project pipeline and documented requirements linked to REDATA incentives.
What technical capability will matter most for providers?
Providers will need strong skills in high-voltage commissioning, cybersecurity assurance, liquid-cooling validation, and sustainability documentation.