
Prostate Biopsy Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Market Size (2027) | USD 2.20 Billion |
| Market Size (2032) | USD 3.18 Billion |
| Growth Rate (2027 - 2032) | 7.66 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Prostate Biopsy Market Analysis by Mordor Intelligence
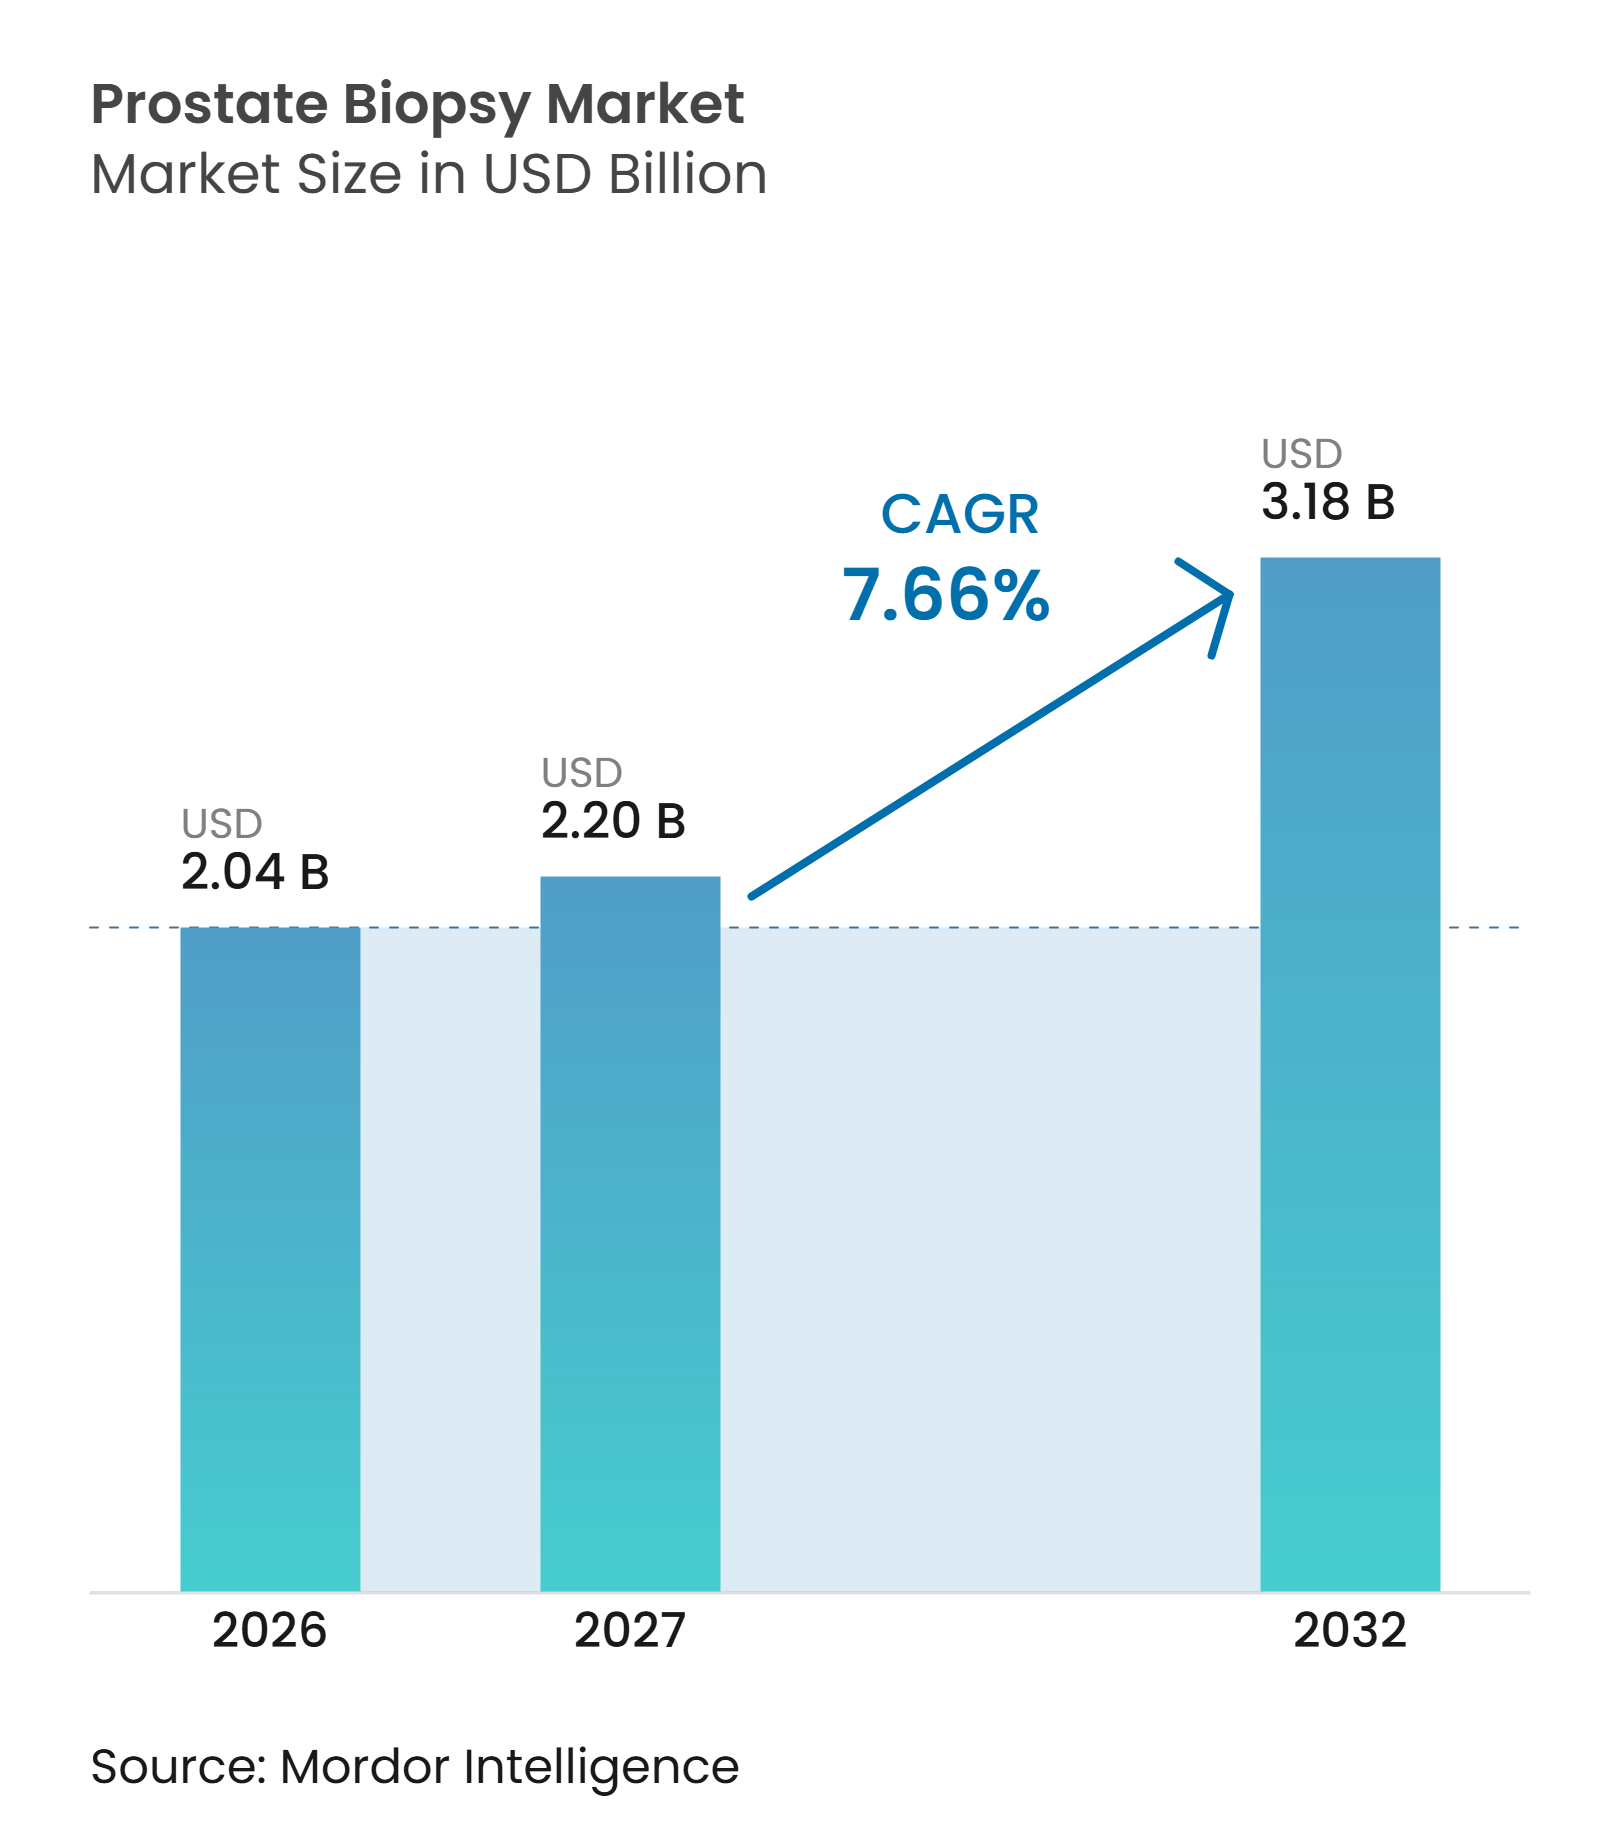
The Prostate Biopsy Market size was valued at USD 2.04 billion in 2026 and is estimated to grow from USD 2.20 billion in 2027 to reach USD 3.18 billion by 2032, at a CAGR of 7.66% during the forecast period (2027-2032).
Rising prostate cancer diagnoses continue to drive demand for biopsy procedures, while active surveillance increases the need for follow-up testing among selected patients. The prostate biopsy market is shifting toward MRI-informed targeting, transperineal access, and workflows suitable for outpatient settings. New U.S. reimbursement codes for transperineal, in-bore MRI-guided, and MRI-ultrasound fusion procedures support investment in advanced guidance platforms. However, high equipment costs, limited MRI capacity, and shortages of trained radiologists and urologists may constrain adoption in lower-resource settings. The strongest near-term opportunities lie with suppliers offering targeted sampling, efficient workflows, and practical training support.
Key Report Takeaways
- By biopsy type, prostate needle biopsy held 85.67% of the prostate biopsy market share in 2026, while prostate liquid biopsy is projected to grow at a 9.28% CAGR through 2032.
- By guidance technology, ultrasound-guided biopsy accounted for 51.45% of the prostate biopsy market share in 2026, while MRI-ultrasound fusion-guided biopsy is projected to expand at a 10.12% CAGR through 2032.
- By product type, biopsy needles held 55.67% of revenue in 2026, while biopsy guidance and navigation systems are projected to grow at an 11.23% CAGR through 2032.
- By end user, hospitals accounted for 56.89% of revenue in 2026, while ambulatory surgical centers are projected to advance at a 10.45% CAGR through 2032.
- By geography, North America held 39.88% of revenue in 2026, while Asia-Pacific is projected to expand at a 9.88% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Prostate Biopsy Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising prostate cancer incidence and biopsy confirmation demand | +2.0% | Global | Long term (≥ 4 years) |
| Pre-biopsy mPMRI adoption and targeted sampling | +1.5% | North America and Europe | Medium term (2-4 years) |
| Shift toward transperineal biopsy to reduce infection risk | +1.2% | North America, Europe, and Australia | Medium term (2-4 years) |
| Dedicated reimbursement codes for fusion and transperineal biopsy | +1.0% | North America | Short term (≤ 2 years) |
| AI-assisted lesion detection and prostate volume measurement | +0.8% | North America, Europe, and Asia-Pacific | Medium term (2-4 years) |
| Compact and local-anesthesia-compatible workflows | +0.5% | Global | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Rising Prostate Cancer Incidence and Biopsy Confirmation Demand
Tissue biopsy remains the definitive method for confirming prostate cancer following suspicious screening or imaging findings. GLOBOCAN 2024 recorded 1,546,112 new prostate cancer diagnoses worldwide, representing a 5% increase from the 2022 baseline, and annual incidence is projected to reach 2,626,735 cases by 2045. North America records the highest age-standardized incidence rate at 80.82 cases per 100,000 population, while expanded testing access is increasing diagnosed caseloads across parts of Asia and Africa.[1] The prostate biopsy market benefits as tissue assessment remains essential for cancer grading and risk classification, while active surveillance generates recurring demand for confirmatory procedures. Lower-cost, portable systems may improve access in regions with limited diagnostic infrastructure and high mortality-to-incidence ratios, creating new opportunities for growth across the prostate biopsy industry.
Pre-Biopsy mpMRI Adoption and Targeted Sampling
Pre-biopsy multiparametric MRI (mpMRI) is reshaping the diagnostic pathway for men with suspicious PSA results. The 2026 EAU guidance recommends MRI before biopsy decisions and supports targeted sampling for appropriate patients. The MIRAGE study of 912 patients identified clinically significant cancer in 41% of participants receiving targeted and perilesional biopsies, with perilesional sampling increasing detection by 3.6%.[2] The prostate biopsy market is therefore shifting toward tools that integrate MRI findings with real-time ultrasound imaging and enable precise needle placement. The ProBIOPSY consensus supports targeted biopsy strategies across most clinical settings, encouraging providers to prioritize platforms that support MRI-led workflows without increasing operational burden and shaping adoption priorities across the prostate biopsy industry.
Shift Toward Transperineal Biopsy to Reduce Infection Risk
The shift from transrectal to transperineal access is changing procedure design and product demand in the prostate biopsy market. Evidence reviewed in 2026 indicates that both approaches offer comparable cancer detection rates, while transperineal biopsy carries a lower risk of infection. A 2025 prospective cohort study found clinically significant cancer in 44.7% of patients receiving transperineal cognitive fusion biopsy, compared with 25.6% of those receiving systematic biopsy. Local anesthesia can enable suitable procedures to move from operating rooms to ambulatory surgical centers and urology clinics.[3] This trend favors transperineal needle guides, access systems, and imaging tools while supporting antimicrobial stewardship through reduced reliance on antibiotic prophylaxis.
Dedicated Reimbursement Codes for Fusion and Transperineal Biopsy
The U.S. coding update scheduled for 2026 is expected to provide clearer reimbursement recognition for advanced prostate biopsy procedures. Effective January 1, 2026, CPT code 55700 is scheduled to be retired and replaced by nine Category I codes covering transrectal, transperineal, in-bore MRI-guided, and MRI-ultrasound fusion-guided procedures. The codes bundle imaging guidance and establish a defined reimbursement structure for advanced workflows. CPT 55713 and CPT 55714 for in-bore MRI-guided procedures carry a higher ambulatory payment classification than standard procedures, supporting investment by hospitals and ambulatory surgical centers.[4] The prostate biopsy market may experience faster adoption if commercial payers follow this framework, while Germany’s 2026 S3 guidance also recommends MRI-guided or MRI-fusion-guided biopsy for PI-RADS 3 or higher lesions.
Restraints Impact Analysis of Prostate Biopsy Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High capital cost and MRI infrastructure dependence | -0.9% | Asia-Pacific core, with spillover to the Middle East, Africa, and South America | Long term (≥ 4 years) |
| Recurring software, service, and accessory costs | -0.7% | Global | Medium term (2-4 years) |
| Uneven commercial reimbursement for advanced procedures | -0.6% | North America and selected international markets | Short term (≤ 2 years) |
| Shortage of mPMRI-experienced professionals and procedure learning curve | -0.6% | Global | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
High Capital Cost and MRI Infrastructure Dependence
MRI-guided and fusion biopsy systems require substantial capital investment, which many community hospitals and outpatient practices cannot readily absorb. Costs for MRI-ultrasound fusion platforms, AI-enabled software, and procedure-specific accessories increase the initial financial burden. These programs also depend on access to 1.5T or 3T MRI systems, timely imaging, and radiology interpretation. Limited infrastructure in parts of sub-Saharan Africa, South and Southeast Asia, and Latin America may prolong reliance on ultrasound-guided procedures, resulting in deferred upgrades rather than limited long-term demand for precision-guidance systems.
Recurring Software, Service, and Accessory Costs
Advanced biopsy care involves recurring costs beyond the initial equipment purchase, including service contracts, software licenses, single-use transperineal accessories, and maintenance. These expenses can constrain budget planning, particularly for facilities with modest procedure volumes. Suppliers must demonstrate that workflow improvements and clinical benefits justify the total cost of ownership. Uncertain consumable costs and inadequate reimbursement for all procedural elements may delay facility upgrades. Long-term adoption will depend on procurement models that align with the financial requirements of high-volume centers and smaller practices.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Prostate Biopsy Market Segment Analysis
By Biopsy Type:
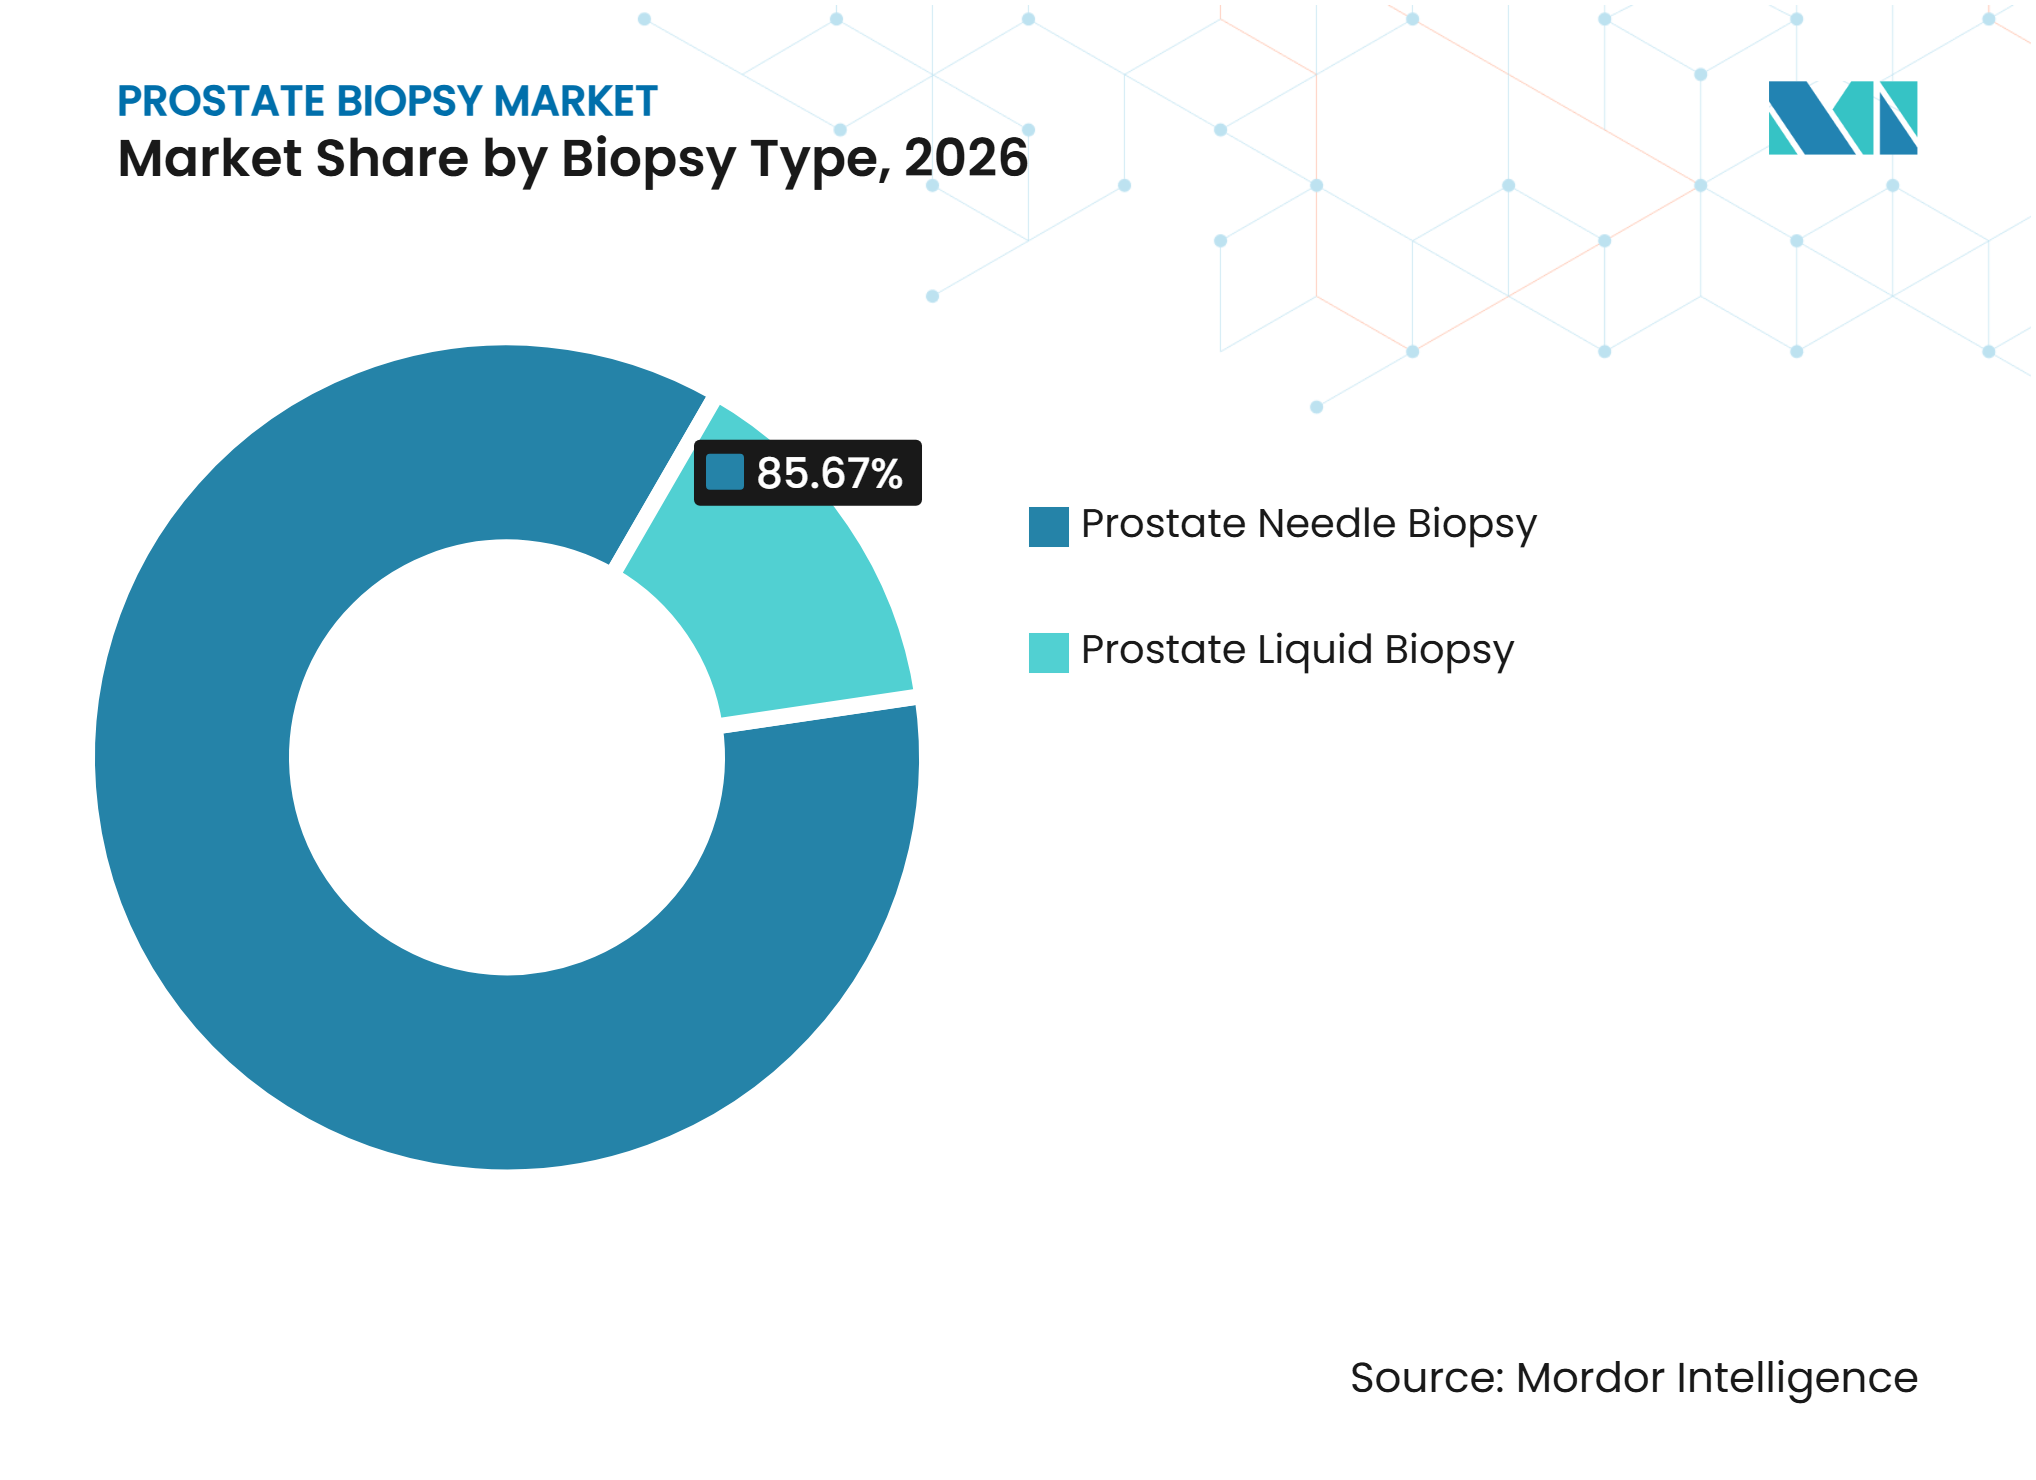
Needle Volumes Sustain Revenue While Liquid Biopsy AcceleratesProstate needle biopsy held 85.67% of the prostate biopsy market share in 2026, as tissue histopathology remains critical for diagnosis, grading, and risk stratification. More than 1 million prostate biopsies are performed annually in the United States, supporting consistent demand for procedure-related consumables. The shift from transrectal to transperineal access is changing demand for guides, needle systems, and accessories. Suppliers offering solutions for both routes can maintain their market position as clinical practices evolve.
Prostate liquid biopsy is forecast to grow at a CAGR of 9.28% through 2032. FDA approval of IsoPSA in December 2025 and its inclusion in the NCCN 2025 Early Detection Guideline support its role in pre-biopsy risk stratification. Liquid biopsy remains an adjunct to tissue biopsy and also supports minimal residual disease detection and treatment-response monitoring. It may reduce low-value procedures while directing tissue biopsy demand toward cases requiring definitive confirmation.


By Guidance Technology:
Ultrasound Anchors Volumes as Fusion Redefines StandardsUltrasound-guided biopsy accounted for 51.45% of the prostate biopsy market size in 2026. Its established installed base, lower cost, and suitability for office-based settings support continued adoption across community urology practices. It remains important in regions with limited MRI access and for systematic sampling pathways. Ultrasound also serves as the procedural foundation for MRI-ultrasound fusion-guided targeted biopsy.
MRI-ultrasound fusion-guided biopsy is forecast to grow at a CAGR of 10.12% through 2032. The technology combines MRI findings with real-time ultrasound to improve targeting of suspicious lesions. A 2025 cohort study reported clinically significant cancer detection rates of 44.7% for transperineal cognitive fusion biopsy, compared with 25.6% for systematic biopsy. The new CPT structure provides a clearer economic foundation for facilities adopting advanced guidance pathways.
By Product Type:
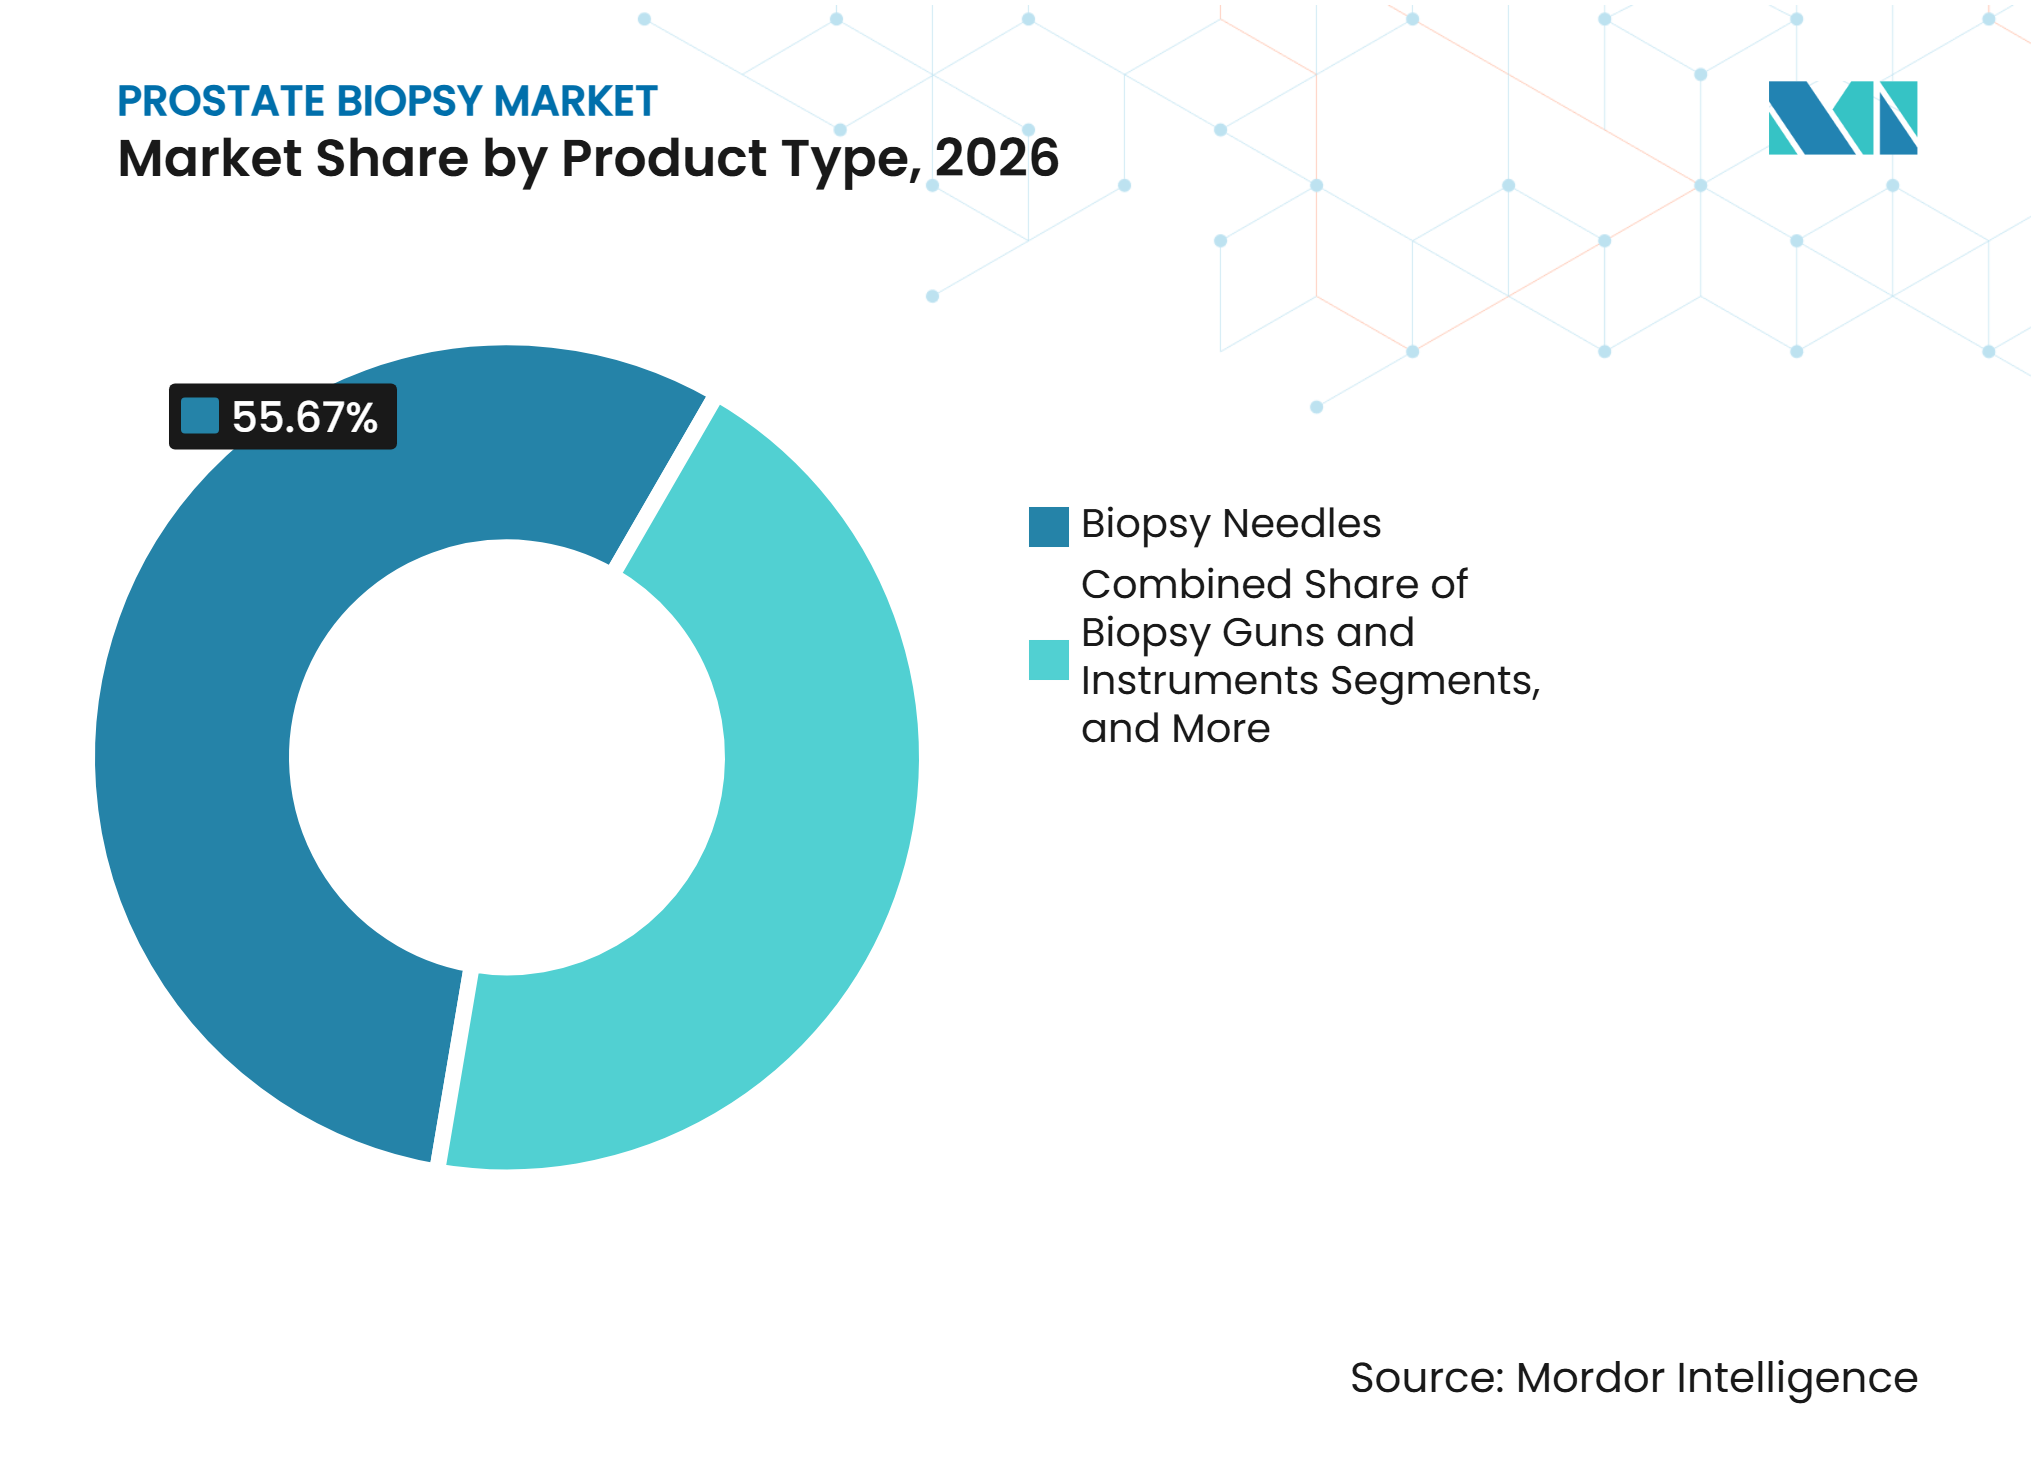
Needles Lead Revenue but Navigation Systems Lead GrowthBiopsy needles held 55.67% of revenue in 2026 because every tissue-based procedure requires needle-based sample collection. This high-volume consumable role supports stable demand despite changes in guidance technologies. Manufacturers are focusing on improved sampling reliability, lower infection risk, and integration with imaging workflows. Infection-prevention features are becoming increasingly relevant as providers adopt transperineal and other risk-reduction approaches.
Biopsy guidance and navigation systems are forecast to expand at a CAGR of 11.23% through 2032. Clinical programs are investing in fusion and robotic platforms that support biopsy procedures and focal therapy planning. In July 2025, Philips received FDA 510(k) clearance for an updated UroNav system integrating pre-procedural MRI, real-time ultrasound, and focal therapy planning workflows. These platforms help standardize targeting, improve documentation, and support integrated clinical workflows.


By End User:
Hospitals Anchor Volume While ASCs Drive Structural ChangeHospitals accounted for 56.89% of revenue in 2026 because they manage a substantial share of complex and imaging-intensive biopsy procedures. They offer MRI capacity, coordinated radiology and urology teams, and anesthesia support when required. Academic centers are also establishing outpatient transperineal programs that reduce dependence on conventional operating room settings. Hospitals will remain central to challenging cases and advanced imaging pathways.
Ambulatory surgical centers are forecast to grow at a CAGR of 10.45% through 2032. Local-anesthetic transperineal biopsy reduces facility requirements for selected patients, while the 2026 reimbursement framework supports fusion and transperineal procedures in ASC settings. Diagnostic and imaging centers may expand their role in pre-biopsy MRI interpretation and coordinated in-office pathways. Compact systems that reduce reliance on external equipment can improve adoption across ASCs, imaging centers, and clinics.
Geography Analysis
North America
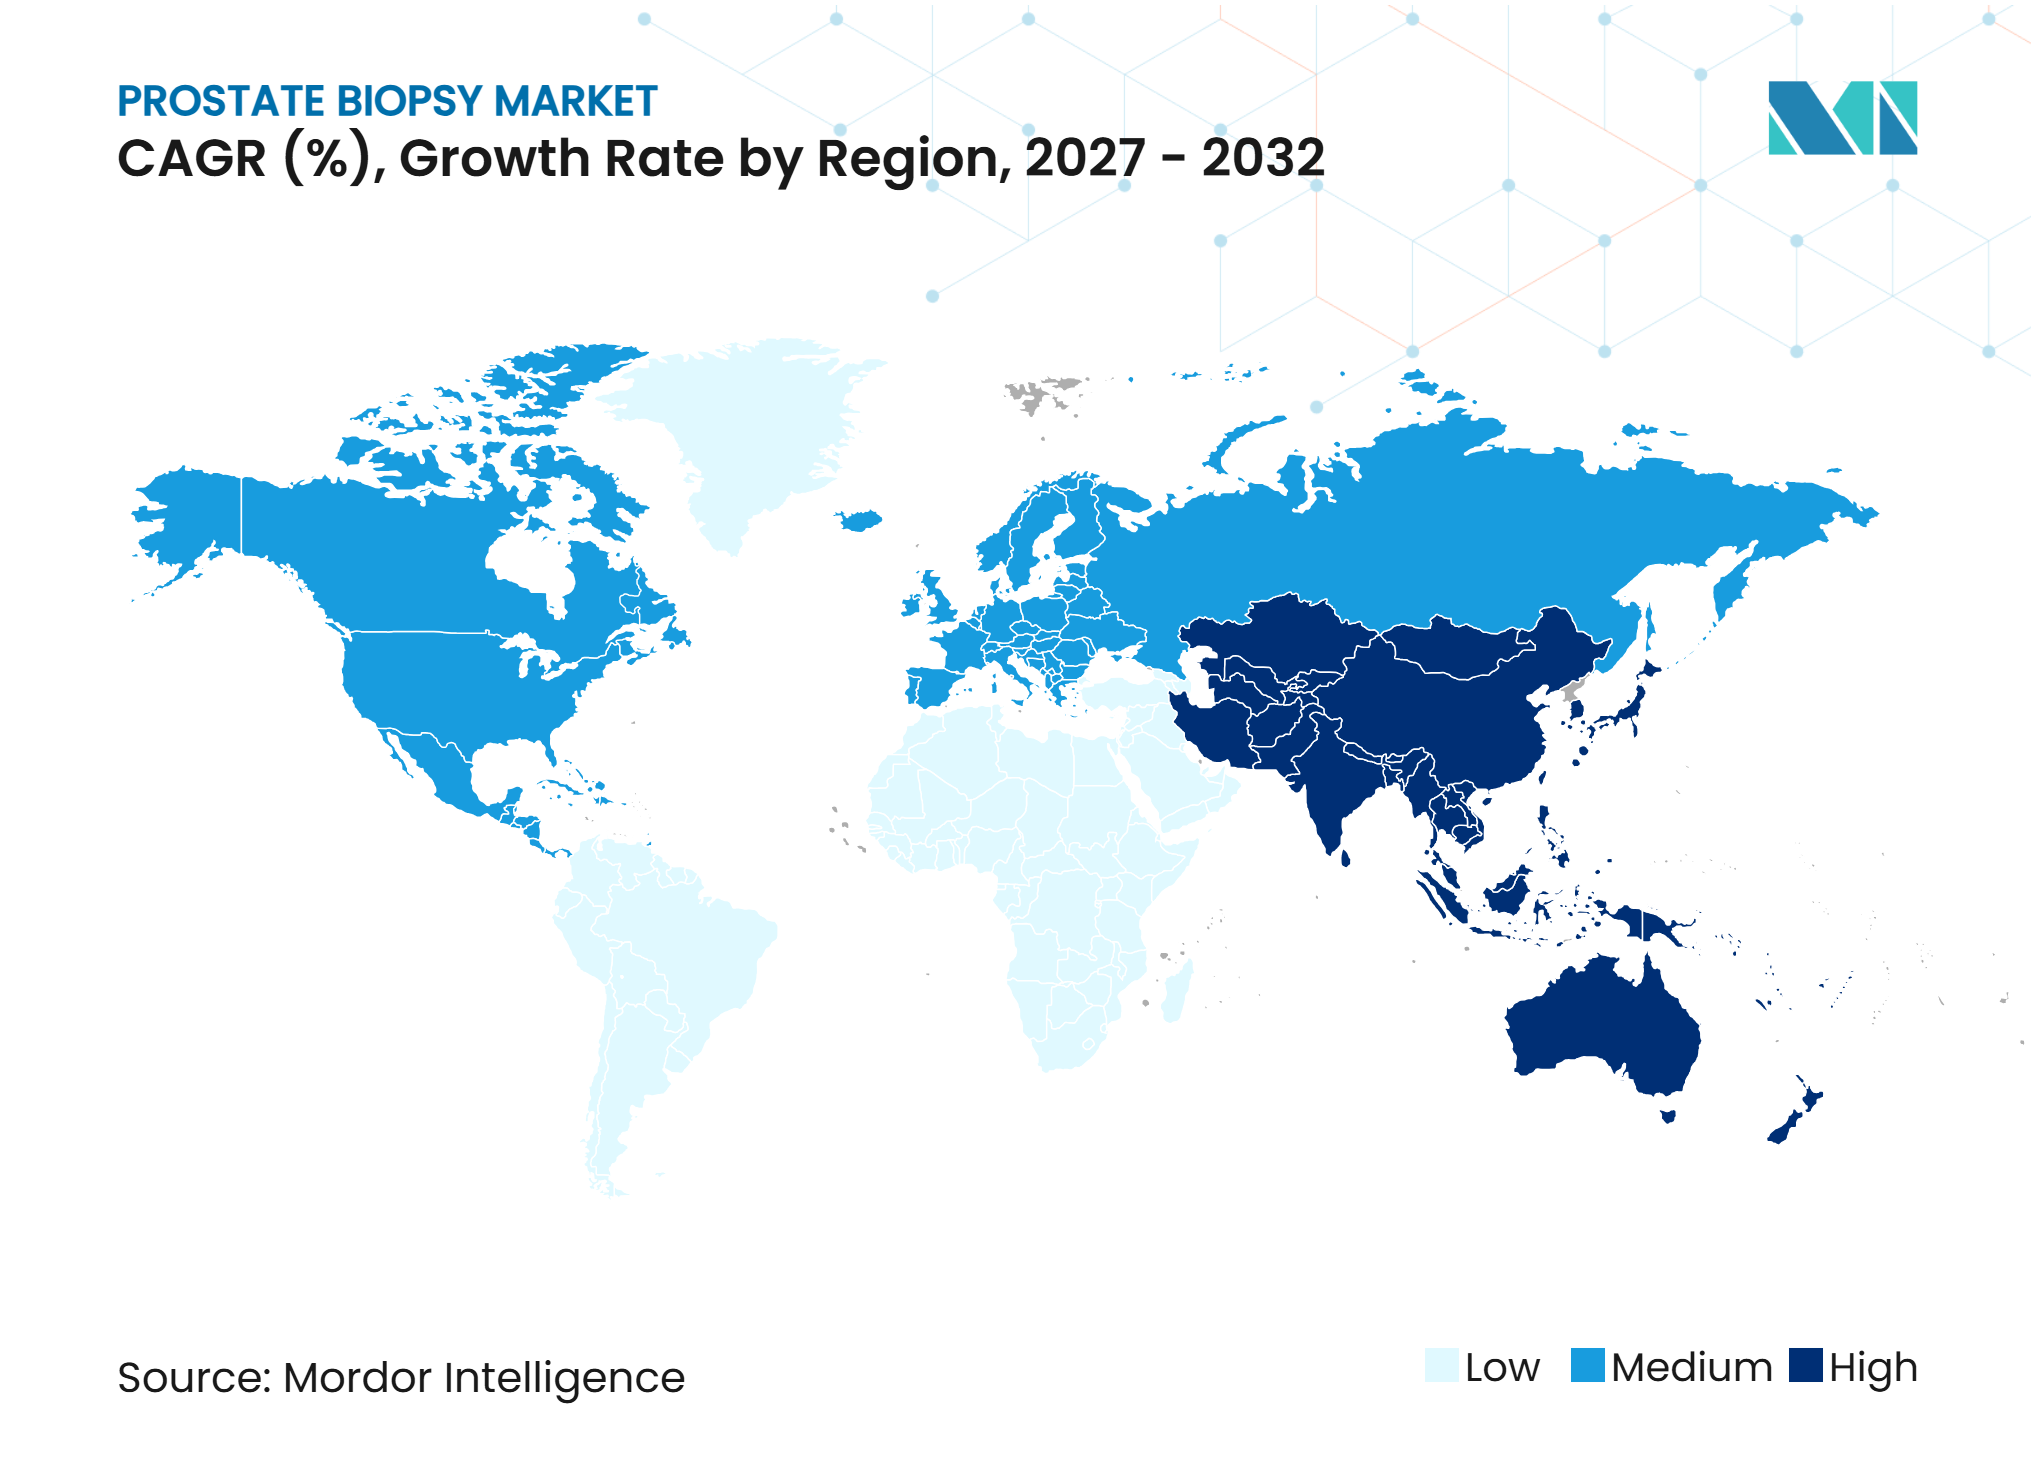
North America is projected to account for 39.88% of the prostate biopsy market share in 2026. The region has an age-standardized prostate cancer incidence rate of 80.82 per 100,000 population and performs more than 1 million prostate biopsies annually in the United States. The 2026 CPT code structure differentiates reimbursement for transrectal, transperineal, in-bore MRI-guided, and MRI-ultrasound fusion-guided procedures, supporting the shift toward targeted biopsies. FDA-cleared AI tools and Medicare coverage for IsoPSA support integrated diagnostic workflows and more targeted biopsy utilization. Compliance with FDA requirements and evolving payer policies remains critical, while Canada and Mexico offer additional growth opportunities as urology capacity expands.
Asia-Pacific
Asia-Pacific is forecast to expand at a CAGR of 9.88% from 2027 to 2032. Rising prostate cancer incidence in China, India, and South Korea, combined with broader screening coverage and healthcare investment, supports market growth. Japan’s aging male population drives demand for precise diagnostic pathways, while India and South Korea benefit from government-backed detection initiatives and expanding private hospital capacity. Uneven MRI access and specialist availability will influence adoption, sustaining demand for lower-cost ultrasound-guided procedures. Suppliers offering compact technologies, training, and flexible procurement models may gain a competitive advantage, although local registration and reimbursement requirements will continue to shape market entry.
Europe, South America, and the Middle East and Africa
European providers are increasingly aligning diagnostic practices with the 2026 EAU guidance on pre-biopsy MRI and targeted sampling. Germany’s S3 guideline recommends MRI-guided or MRI-fusion-guided biopsy for PI-RADS 3 or higher lesions, supporting reduced reliance on unnecessary systematic sampling. In South America, Brazil anchors demand as prostate cancer remains a significant cause of cancer mortality. The Middle East and Africa show varying levels of access, with GCC countries investing in advanced fusion platforms while underserved areas face limited diagnostic capacity. Portable, lower-cost systems may address late-diagnosis challenges, while infrastructure, reimbursement, and clinical training continue to shape market development.
Competitive Landscape
Market Concentration
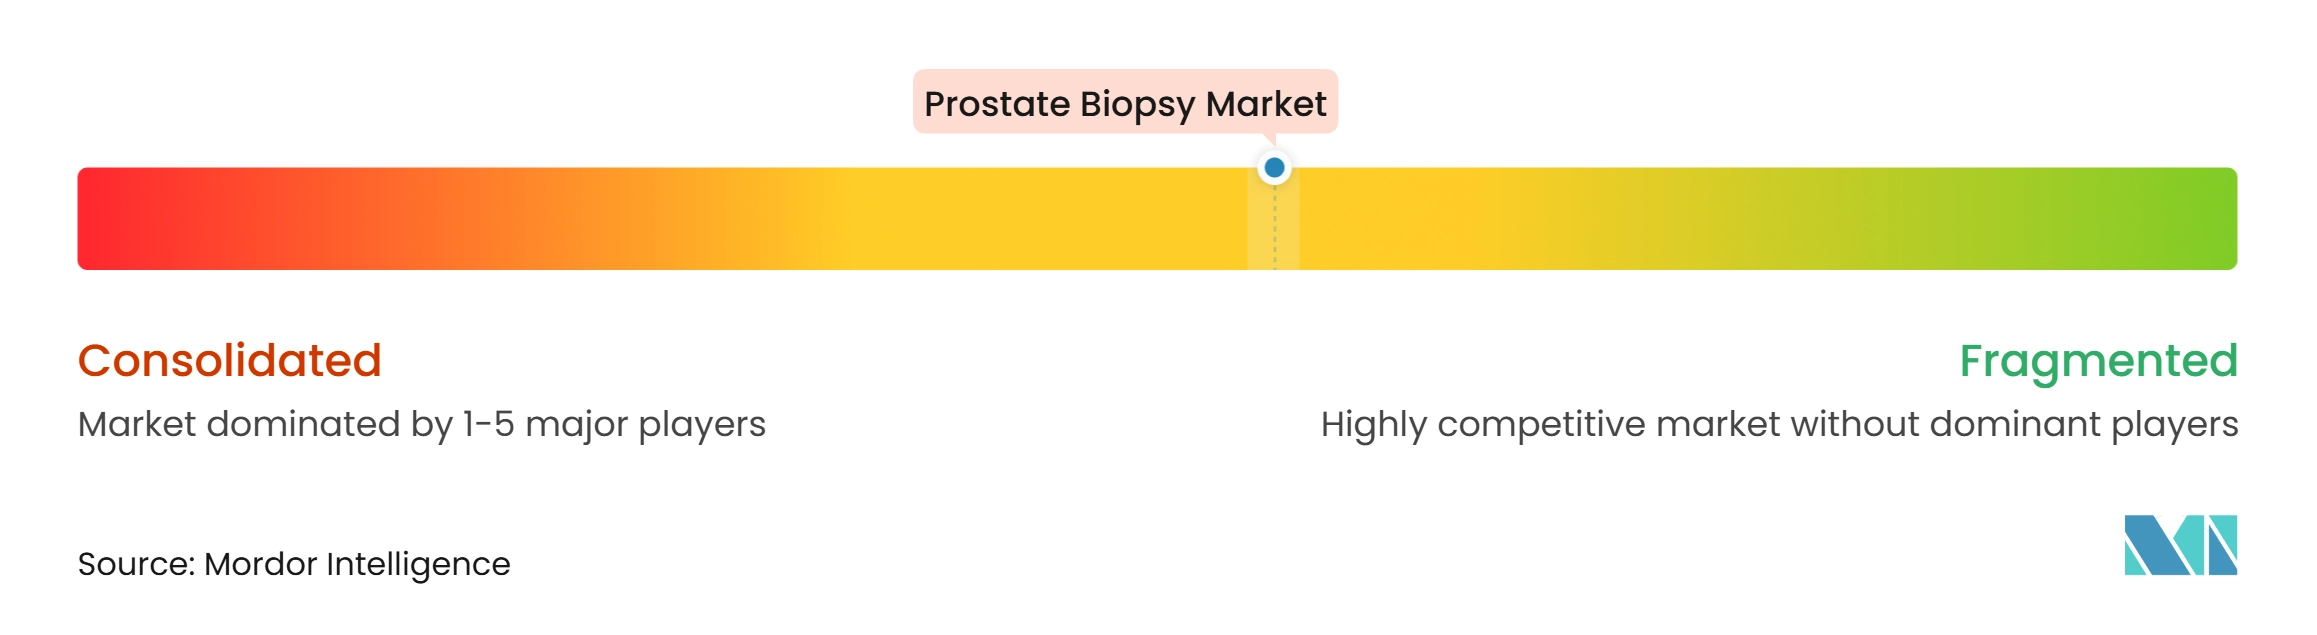
The prostate biopsy market demonstrates moderate concentration, with multinational imaging companies competing alongside specialized needle, navigation, and procedure workflow providers. Siemens Healthineers, Koninklijke Philips, GE HealthCare, and Canon Medical offer imaging and guidance platforms, while Becton Dickinson, Argon Medical Devices, B. Braun, and Cook Group serve the high-volume consumables segment. KOELIS, Exact Imaging, Focal Healthcare, and Biobot Surgical provide integrated systems for ambulatory and office-based settings. Competition centers on workflow integration, targeted sampling accuracy, and support for biopsy and focal therapy planning.
AI integration remains a key product differentiation strategy. In April 2025, KOELIS announced a partnership with Bot Image to integrate its Trinity MRI fusion system with ProstatID AI for automated lesion detection, classification, and 3D contouring. Ibex and Quibim have used FDA clearances to position their software tools in pathology and MRI workflows, while Philips has advanced its FDA-cleared UroNav platform for navigation and focal therapy planning. These developments enhance the value of installed hardware by integrating imaging, targeting, and reporting processes. Smaller companies can also use partnerships to add AI capabilities without developing all components internally.
Transperineal system design represents another important competitive area. In July 2025, Exact Imaging transitioned to a direct U.S. sales model to expand the reach of its ExactVu micro-ultrasound system across independent practices, Veterans Affairs facilities, and integrated delivery networks. CIVCO Medical Solutions received CE marking in 2025 for TP Pivot Pro, a single-use transperineal needle guide that can reduce adoption barriers for smaller facilities. FDA clearance, CE marking under the EU Medical Device Regulation, and ISO 13485 certification remain significant barriers to entry. Although combined market-share data are not available, the market structure supports a moderate concentration assessment.
Prostate Biopsy Industry Leaders
-
Becton, Dickinson and Company
-
Boston Scientific Corporation
-
Siemens Healthineers AG
-
Koninklijke Philips N.V.
-
Cook Group Incorporated
- *Disclaimer: Major Players sorted in no particular order
Prostate Biopsy Market Companies Covered in this Report
- Argon Medical Devices
- B. Braun
- Beckton Dickinson
- Biobot Surgical Pte. Ltd.
- Boston Scientific
- Canon
- Cook Group
- ESAOTE S.p.A.
- Exact Imaging Inc.
- Focal Healthcare Inc.
- FUJIFILM
- GE HealthCare Technologies Inc.
- KOELIS SAS
- Koninklijke Philips
- MedCom GmbH
- Medtronic
- Siemens Healthineers
Recent Industry Developments in Prostate Biopsy Market
- January 2026: CMS implemented nine new CPT Category I codes for prostate biopsy and retired CPT code 55700. The new codes differentiated transrectal, transperineal, in-bore MRI-guided, and MRI-ultrasound fusion-guided procedures, with imaging guidance bundled into each code; CPT 55713 and 55714 received higher ambulatory payment classifications.
- December 2025: Cleveland Diagnostics received PMA approval for IsoPSA, a blood-based in vitro diagnostic test for men aged 50 years or older with elevated PSA levels. The NCCN 2025 Early Detection Guideline included the test, and Medicare and an increasing number of commercial payers covered it to help reduce unnecessary U.S. prostate biopsies.
- November 2025: EAU-EANM-ESTRO-ESUR-ISUP-SIOG published the 2026 Prostate Cancer Guidelines, Part I, formalizing risk-adapted MRI-based strategies. The guidelines recommended pre-biopsy multiparametric MRI with targeted and regional biopsies, introduced a five-tier EAU classification system, and confirmed active surveillance for eligible low- and intermediate-risk cases.
- July 2025: Royal Philips received FDA 510(k) clearance for the latest UroNav MRI-ultrasound fusion navigation system. The system added an annotation workflow for focal therapy planning and delivery using DynaCAD Urology, while Northwell Health reported a 30% improvement in high-risk prostate cancer diagnosis versus standard biopsy.
Global Prostate Biopsy Market Report Scope
As per the scope of the report, a prostate biopsy is a medical procedure that removes small tissue samples from the prostate gland so they can be examined under a microscope for cancer or other cellular abnormalities.
The prostate biopsy market is segmented by biopsy type, guidance technology, product type, end user, and geography. By biopsy type, the market is segmented into prostate needle biopsy and prostate liquid biopsy. By guidance technology, the market is segmented into ultrasound-guided biopsy, MRI-guided biopsy, MRI-ultrasound fusion-guided biopsy, cognitive fusion-guided biopsy, CT-guided biopsy, and other guidance technologies. By product type, the market includes biopsy needles, biopsy guns and instruments, biopsy guidance and navigation systems, biopsy accessories and consumables, and other product types. By end user, the market is segmented into hospitals, ambulatory surgical centers, diagnostic and imaging centers, urology clinics and physician offices, and other end users. By geography, the market is analyzed across North America, Europe, Asia-Pacific, the Middle East and Africa, and South America. The report also covers the estimated market sizes and trends for 17 countries across major regions globally. The report offers market sizes and forecasts in terms of value (USD) for the above segments.
Segmentation Overview
| Prostate Needle Biopsy |
| Prostate Liquid Biopsy |
| Ultrasound-Guided Biopsy |
| MRI-Guided Biopsy |
| MRI-Ultrasound Fusion-Guided Biopsy |
| Cognitive Fusion-Guided Biopsy |
| CT-Guided Biopsy |
| Other Guidance Technologies |
| Biopsy Needles |
| Biopsy Guns and Instruments |
| Biopsy Guidance and Navigation Systems |
| Biopsy Accessories and Consumables |
| Other Product Types |
| Hospitals |
| Ambulatory Surgical Centers |
| Diagnostic and Imaging Centers |
| Urology Clinics and Physician Offices |
| Other End Users |
| North America | United States |
| Canada | |
| Mexico | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Spain | |
| Rest of Europe | |
| Asia-Pacific | China |
| India | |
| Japan | |
| Australia | |
| South Korea | |
| Rest of Asia-Pacific | |
| Middle East and Africa | GCC |
| South Africa | |
| Rest of Middle East and Africa | |
| South America | Brazil |
| Argentina | |
| Rest of South America |
| By Biopsy Type | Prostate Needle Biopsy | |
| Prostate Liquid Biopsy | ||
| By Guidance Technology | Ultrasound-Guided Biopsy | |
| MRI-Guided Biopsy | ||
| MRI-Ultrasound Fusion-Guided Biopsy | ||
| Cognitive Fusion-Guided Biopsy | ||
| CT-Guided Biopsy | ||
| Other Guidance Technologies | ||
| By Product Type | Biopsy Needles | |
| Biopsy Guns and Instruments | ||
| Biopsy Guidance and Navigation Systems | ||
| Biopsy Accessories and Consumables | ||
| Other Product Types | ||
| By End User | Hospitals | |
| Ambulatory Surgical Centers | ||
| Diagnostic and Imaging Centers | ||
| Urology Clinics and Physician Offices | ||
| Other End Users | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Spain | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| India | ||
| Japan | ||
| Australia | ||
| South Korea | ||
| Rest of Asia-Pacific | ||
| Middle East and Africa | GCC | |
| South Africa | ||
| Rest of Middle East and Africa | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
Key Questions Answered in the Report
What is driving growth in the prostate biopsy market?
Rising prostate cancer diagnoses, greater use of pre-biopsy MRI, transperineal procedures, and clearer reimbursement for advanced guidance are supporting growth. The report projects a 7.66% CAGR from 2027 to 2032.
What is the projected value of the prostate biopsy market by 2032?
The prostate biopsy market is projected to reach USD 3.18 billion by 2032, increasing from USD 2.20 billion in 2027.
Which biopsy type has the largest revenue share?
Prostate needle biopsy held 85.67% of revenue in 2026 because tissue histopathology remains central to cancer confirmation, grading, and risk stratification.
Which guidance technology is growing fastest?
MRI-ultrasound fusion-guided biopsy is forecast to grow at a 10.12% CAGR through 2032 as providers adopt more targeted sampling pathways.
Why are transperineal prostate biopsies gaining use?
Transperineal biopsy is gaining use because it can lower infection risk and can be performed under local anesthesia in appropriate outpatient settings.
Which region is expected to grow fastest?
Asia-Pacific is forecast to grow at a 9.88% CAGR through 2032, supported by expanding screening, healthcare investment, and aging populations.