
Printed Circuit Board Market Analysis by Mordor Intelligence
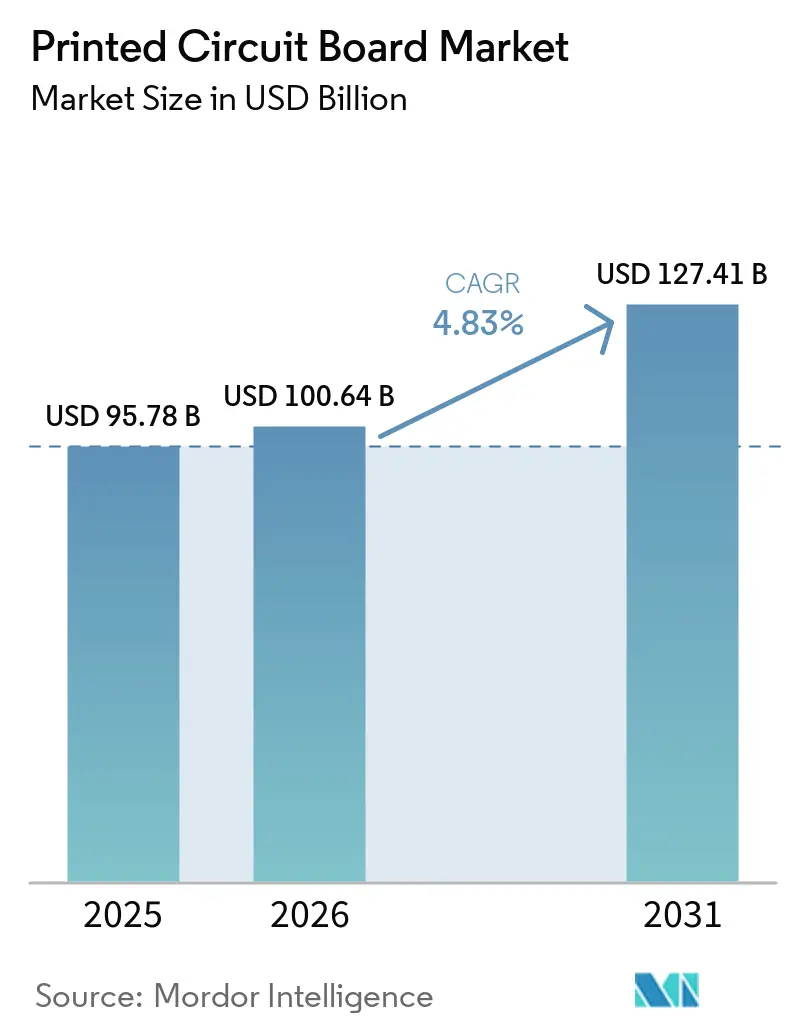
The printed circuit board market size is projected to expand from USD 100.6 billion in 2026 and USD 105.5 billion in 2027 to USD 136 billion by 2032, registering a CAGR of 5.21% between 2027 and 2032.
AI hardware production and Germany’s electric-drive programs connect rising system output with recurring demand for electronics. Chiplet packaging and low-loss board requirements add a manufacturing challenge that more specialized capacity can address. Capacity investment therefore offers a differentiated route to business, but raw-material costs and design-talent constraints can slow the shift from customer programs to board revenue. The strongest commercial position combines the required process capability with an executable production program, so additional factory space must translate into deliverable interconnects.
Key Report Takeaways
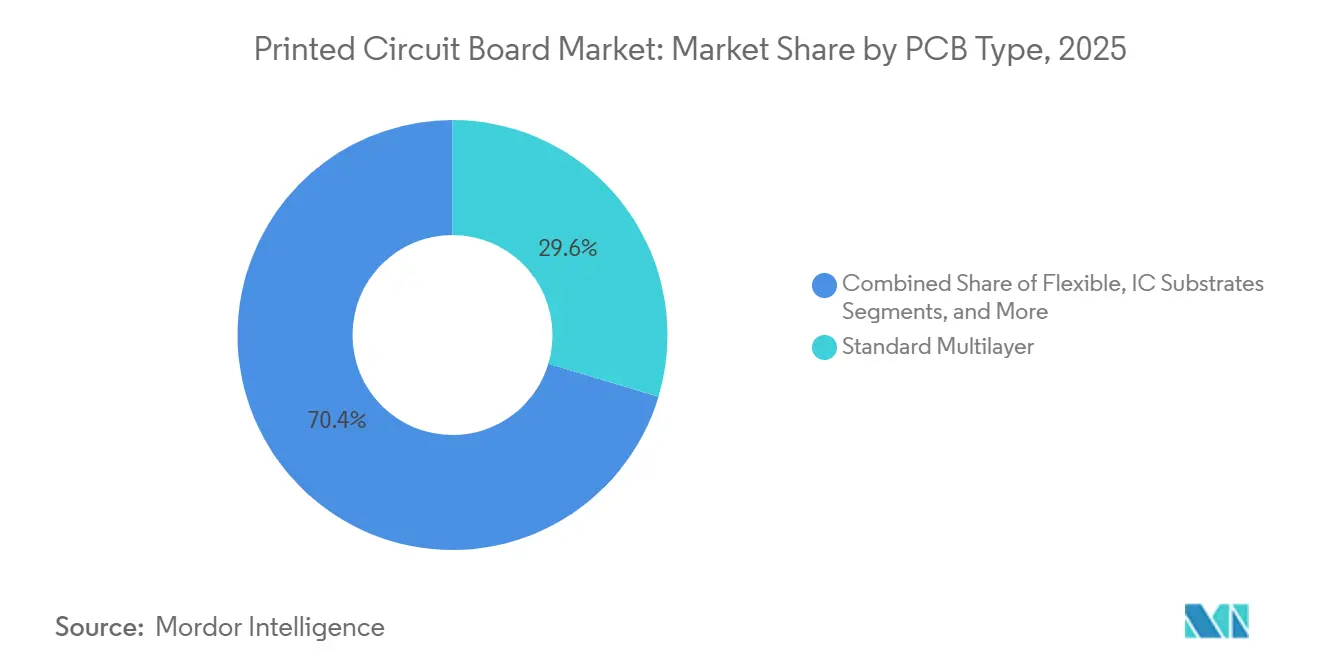
- By PCB type, standard multilayer (non-HDI) boards led with a 29.48% printed circuit board market share in 2026, while flexible circuits (FPC) are projected to grow fastest at a 5.79% CAGR between 2027 and 2032.
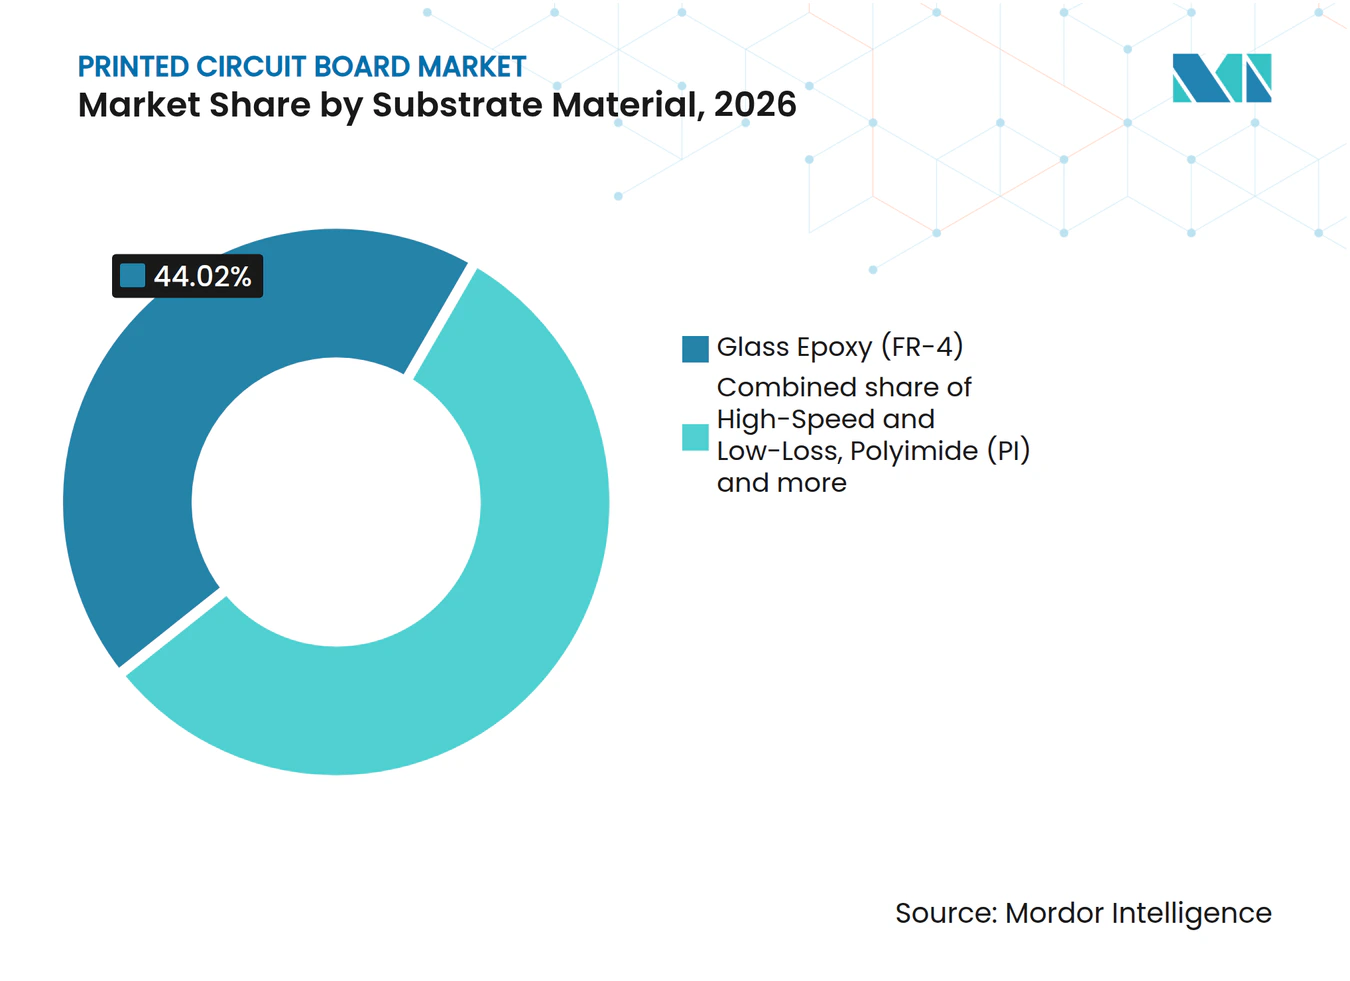
- Across substrate materials, glass epoxy (FR-4) led with a 44.02% share of the printed circuit board market size in 2026, and high-speed and low-loss materials are forecast to grow fastest at a 5.78% CAGR between 2027 and 2032.
- Among end-user industries, consumer electronics led with a 41.82% share of PCB revenue in 2026, while the telecommunications and 5G segment is forecast to grow fastest at a 5.75% CAGR between 2027 and 2032.
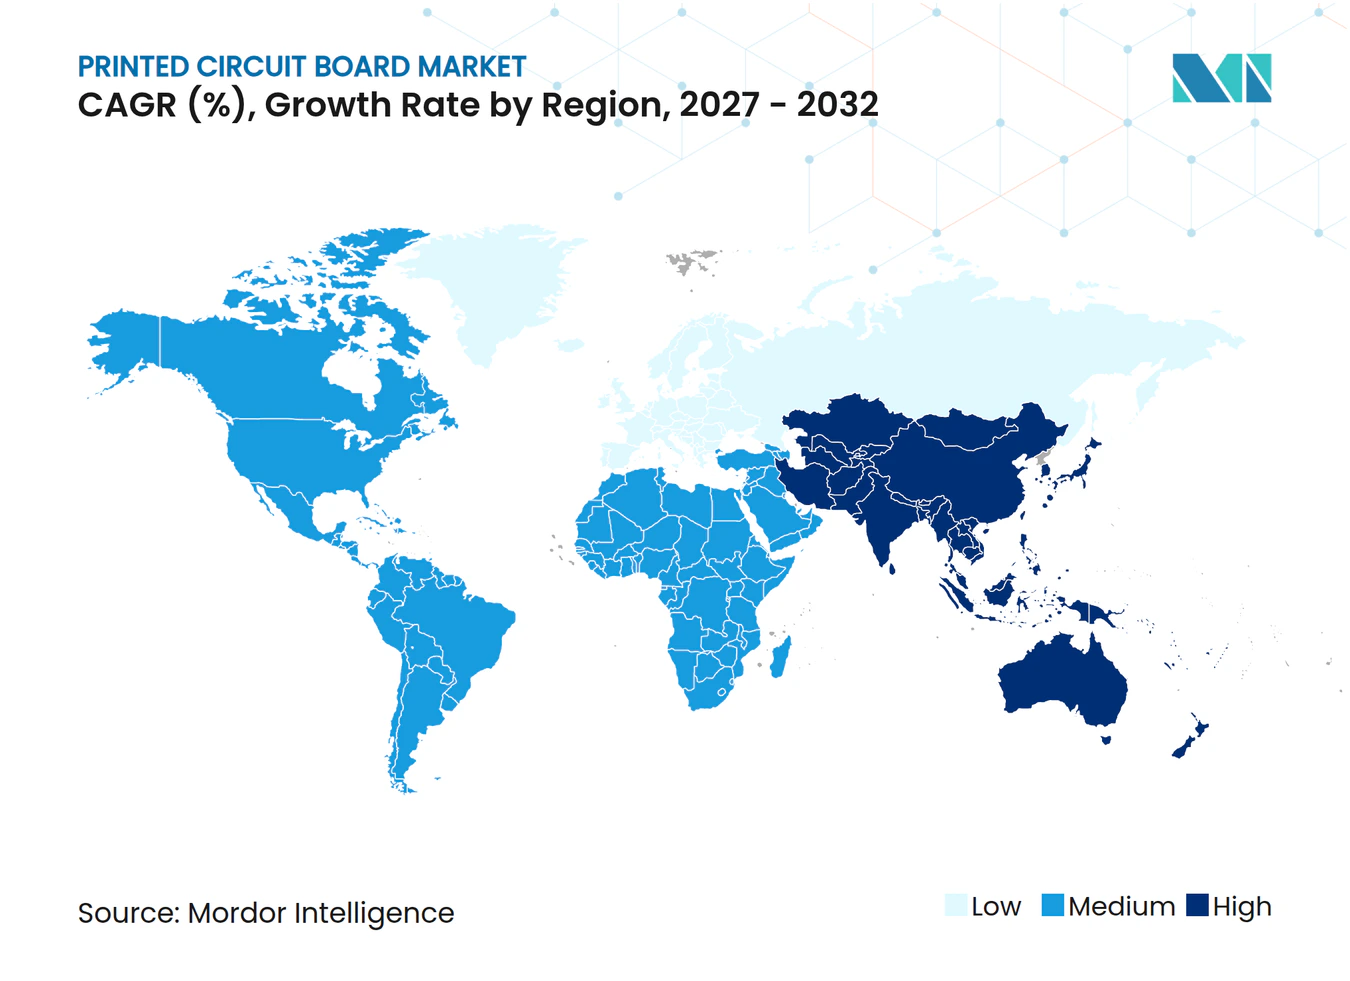
- Geographically, Asia-Pacific led with an 82.66% share of global PCB revenue in 2026 and is forecast to grow fastest at a 5.25% CAGR between 2027 and 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Printed Circuit Board Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Surge in AI Server and High-Performance Computing Demand | +2.6% | North America, Europe and Asia-Pacific | Short term (≤ 2 years) |
| Accelerated EV Power Electronics Content | +1.5% | Germany and China | Medium term (2-4 years) |
| 5G Deployment and 6G Prototyping Boosting HDI Adoption | +1.3% | Asia-Pacific, Europe and North America | Medium term (2-4 years) |
| Shift Toward Advanced IC Substrates for Chiplet Integration | +1.2% | Asia-Pacific and North America | Long term (≥ 4 years) |
| Re-shoring Incentives in U.S. and EU for Critical PCB Supply Chains | +0.6% | United States of America | Medium term (2-4 years) |
| Adoption of Ultra-Low-Loss Materials for 112-224 Gbps per Lane Signaling | +0.4% | People’s Republic of China | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Surge in AI Server and High-Performance Computing Demand
AI server demand is expanding through physical system deliveries as well as new orders. Dell Technologies reported USD 16.4 billion in AI-optimized server revenue in its fiscal 2027 second quarter ended July 31, 2026, up 100% year over year.[1] Increased unit sales drove most of that growth, with higher average selling prices contributing less. Dell also booked record AI server orders of USD 60.9 billion during the quarter. The shipment-led expansion gives PCB producers a demand mechanism beyond higher equipment prices. Converting the larger order pipeline into board sales will depend on server production schedules, making delivery capacity commercially more valuable than exposure to order announcements alone.
Accelerated EV Power Electronics Content
EV power-electronics demand expands through both higher drive output and commercial inverter programs. Volkswagen Group Components’ Kassel plant increased electric-drive production by around 24% year on year to over 850,000 units in 2025.[2] Its integrated network covers electric-drive engineering, industrialization and power electronics, with Kassel helping bring drives and pulse inverters into series production. In September 2025, Schaeffler reported volume production in Tianjin, China, of a high-voltage inverter submodule intended for a leading Chinese automaker’s new EV models. These production examples connect the electronics opportunity to both integrated drive systems and specialized modules. For PCB suppliers, participation in such manufacturing programs can turn a design application into recurring production demand.
5G Deployment and 6G Prototyping Boosting HDI Adoption
Broad commercial 5G adoption gives the HDI opportunity an established service base alongside next-generation development. The International Telecommunication Union (ITU) estimated that 5G coverage reached 55% of the world’s population in 2025.[3] Ericsson reported that global 5G subscriptions increased by 162 million in the first quarter of 2026, reaching 3.1 billion. Together, wide network coverage and rising service adoption favor an emphasis on commercial 5G equipment programs. That commercial scale makes equipment for operating networks the nearer-term customer focus for HDI suppliers, while next-generation development follows a separate commercialization path.
Shift Toward Advanced IC Substrates for Chiplet Integration
Chiplet integration makes substrate capability part of the commercial opportunity created by a change in semiconductor architecture. In 2025, Intel reported that AI and high-performance computing accelerated a shift toward interconnected chiplet designs integrated through advanced packaging. Demand for higher computational performance and greater power efficiency underpinned that shift. Intel said disaggregated designs often require advanced substrates and introduce additional design and manufacturing complexity compared with single-tile architectures. Manufacturing execution can consequently become central to a substrate producer’s participation in chiplet programs, since the opportunity follows the package design and its technical requirements.
Restraints Impact Analysis of Printed Circuit Board Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Prolonged Copper and Epoxy Resin Price Volatility | -1% | People’s Republic of China | Short term (≤ 2 years) |
| Talent Shortages in Advanced PCB Design and Process Engineering | -0.7% | Asia-Pacific, North America and Europe | Medium term (2-4 years) |
| Escalating ESG Compliance Costs for Wastewater and PFAS Regulation | -0.5% | People’s Republic of China | Medium term (2-4 years) |
| Geopolitical Export Controls Limiting Advanced Substrate Equipment | -0.2% | Asia-Pacific and North America | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Prolonged Copper and Epoxy Resin Price Volatility
Material-cost variability can constrain PCB expansion even when manufacturers protect access to supply. Kunshan Wanyuantong Electronics Technology Co., Ltd. reported gross profit margins of 21.7% in 2024 and 19.7% in 2025. Its profitability reflected combined product-price adjustments, product mix and cost pressures that included raw-material fluctuations. For producers facing those pressures, additional sales offer less room to absorb an adverse change in material costs. The company maintains multiple qualified suppliers for key materials and aligns flexible procurement with production plans to mitigate supply risk and price volatility. Even with diversified supply, uncertain input costs raise the earnings hurdle for committing to additional production.
Talent Shortages in Advanced PCB Design and Process Engineering
Limited access to PCB designers can constrain the flow of new products into fabrication before installed factory capacity becomes relevant. In January 2025, the Printed Circuit Engineering Association (PCEA) Magazine reported that an aging workforce and high demand left insufficient trained specialists available for PCB design. When that mismatch persists, adding machinery alone cannot increase the number of designs ready to enter production. The constraint can therefore affect a supplier’s ability to convert customer development activity into executable board orders. It also creates a different expansion problem from increasing output on an existing design. Design shortages can consequently delay revenue from new board programs even when fabrication equipment is already installed.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Printed Circuit Board Market Segment Analysis
By PCB Type:
Established Multilayer Scale Meets FPC SpecializationStandard multilayer (non-HDI) boards accounted for a 29.48% share of the printed circuit board market size in 2026. The largest segment serves designs that require multiple circuit layers without specifying high-density interconnect technology. Additional interconnect density has commercial value for these programs when the intended design requires it, making a change in board architecture a distinct product decision. Maintaining standard multilayer capability therefore preserves a supplier’s ability to serve programs on their specified terms, with commercial relevance tied to the board architecture and the requirements of the intended electronic product.
Flexible circuits (FPC) are the fastest-growing segment, with a projected 5.79% CAGR between 2027 and 2032. Flexium Interconnect Inc. reported that FPCs accounted for 94.91% of its operating revenue in 2025. The group’s business covers FPC design, development, manufacturing and sales, as well as module assembly. This concentration puts FPC performance at the center of the supplier’s commercial exposure, while its activities extend beyond fabrication alone. Serving programs across design and production can consequently give an FPC specialist a broader role in the customer’s product cycle, with module assembly representing an additional business capability.



By Substrate Material:
Glass-Epoxy Capacity and Low-Loss DemandGlass epoxy (FR-4) represented a 44.02% printed circuit board market share in 2026. Kingboard Laminates reported that its existing glass-epoxy laminate plants operated close to full capacity in 2025. The group said further growth depended on additional capacity through plant expansion, construction or acquisition, and gave no assurance that its planned increases would be achieved. For the largest segment, this illustrates how maintaining a large operating base can make incremental capacity the commercial constraint, with additional laminate sales dependent on turning new investment into productive output.
High-speed and low-loss materials are the fastest-growing segment, with a projected 5.78% CAGR between 2027 and 2032. In June 2026, PCEA Magazine reported strong AI-server demand for large-format PCBs with more than 40 layers and ultra-low-loss characteristics. The magazine linked that demand to growth in both volumes and pricing in the copper-clad laminate sector. The commercial opening therefore combines material throughput and performance requirements, making the ability to serve complex AI-server board programs as important as the amount of laminate capacity added to meet expanding production needs.

By End-User Industry:
Consumer Scale Meets Telecom ConstructionConsumer electronics was the largest segment, with a 41.82% share of global PCB revenue in 2026. Apple reported USD 54.3 billion in iPhone net sales for the 3 months ended June 27, 2026. In its combined consumer-electronics and computer-board business, Avary Holding (Shenzhen) Co., Ltd. said it was advancing development and mass production of edge-AI products, including AI glasses, in 2025. These activities place established device sales and developing edge-AI programs within the same broad end-user category. Emerging edge-AI programs therefore offer a product-renewal path within consumer electronics, allowing suppliers to broaden the applications served by that established business.
Telecommunications and 5G are projected to be the fastest-growing segment, with a 5.75% CAGR between 2027 and 2032. China’s 5G network had 4.84 million base stations at the end of 2025, after a net addition of 588,000 during the year. China also had 1.2 billion 5G mobile users at year-end 2025, representing 65.9% of its mobile users. New base-station construction provides a physical route into telecom board production, making network additions a more specific commercial signal for fabricators than service penetration alone.
Geography Analysis
Asia-Pacific Printed Circuit Board Market
Asia-Pacific, the largest geography, accounted for 82.66% of the printed circuit board market size in 2026 and is projected to be the fastest-growing geography, with a 5.25% CAGR between 2027 and 2032. Zhen Ding Technology Holding Ltd.’s group began small-volume ABF substrate production for advanced packaging at Kaohsiung Park, Taiwan, in the first half of 2026. The company expected a second-half 2026 ramp-up and had repurposed capacity designated for intelligent high-density interconnect and high-layer-count rigid PCBs for higher-specification probe-card products. Delton Technology (Guangzhou) Inc., a multilayer and high-layer-count PCB producer, reported that its Thailand subsidiary began production in June 2025. Regional growth can therefore combine specialized substrate production with new multilayer-board locations, while capacity reallocation makes product mix as important as factory footprint.
The U.S.-China Economic and Security Review Commission’s 2025 report described U.S. producers as mainly making low-volume specialty boards for industrial, medical, defense and aerospace products, with many dependent on defense contracts for continued operations. In Canada, FTG Circuits negotiated and ratified a new 4-year collective agreement with represented employees at its Toronto facility in the third quarter of 2026, expiring in July 2030. In Europe, AT&S AG opened its IC-substrate research and production center in Leoben, Austria, in June 2025, with 420 new employees already working there. In North America, longer agreed workforce terms can reduce one element of operating uncertainty, while the European center links IC-substrate development to local production.
Rest of World includes project-linked PCB procurement and local manufacturing, illustrated by Brazil. In March 2025, Fundação Instituto Nacional de Telecomunicações contracted Griffus PCB to supply boards for its Sebrae Trivale VOT project. SGS do Brasil certified Griffus PCB’s management system for PCB manufacturing under ISO 9001:2015, with validity from February 18, 2025, to February 18, 2028, subject to satisfactory surveillance audits. The buyer’s project-linked funding tied the procurement to a defined program and its institutional purchasing decision. For project-oriented fabricators, revenue opportunities consequently follow the institutional program’s purchasing decisions, while certification describes a separate aspect of the supplier’s manufacturing organization.
Regional Editions
Regulatory Framework and Outlook
The selected jurisdictions compare environmental requirements for PCB facility operators, with Medium current ratings reflecting the defined operating compliance work. The United States direction assessment concerns operations without chromium electroplating, while Germany’s additional management-system duties under relevant best available techniques (BAT) conclusions depend on the covered installation and its transition category. China’s national PCB discharge requirements applied to new facilities from July 1, 2021, and existing facilities from January 1, 2024, with provinces permitted to set stricter standards. Germany’s relevant Industrial Emissions Directive (IED) surface-treatment category covers electrolytic or chemical treatment of metals or plastics with treatment vats exceeding 30 m³.
Regulatory Table of Printed Circuit Board Market
| Decision factor | United States | Germany | China |
|---|---|---|---|
| Primary authority | U.S. Environmental Protection Agency | Regierungspräsidium Freiburg for qualifying industrial sites in its district | Ministry of Ecology and Environment; Jiangmen Ecology and Environment Bureau and Taishan branch for the local project example |
| Key instruments or direction | 40 CFR Part 433; exclusions for existing indirect-discharging job shops and independent PCB manufacturers covered by Part 413 | Wastewater Ordinance Annex 40 for wastewater mainly from PCB manufacture and associated processing; EU IED Article 14a framework | GB 39731-2020 and stricter provincial standards where applicable |
| Commercial effect | Process-discharge compliance for covered manufacturing and associated listed operations | Water-law permitting for district sites with EU industrial-emissions or major-accident installations; Annex 40 excludes cooling, operating-water-treatment and rainwater streams | Monitoring and discharge controls, with stricter applicable national/provincial limits for the approved Jiangmen project |
| Current policy attractiveness | Medium | Medium | Medium |
| Future direction of policy attractiveness | No change | Hardening | No change |
| Source: Mordor Intelligence | |||
For United States PCB operations without chromium electroplating, applicable Part 433 duties provide continuity while the 2026 PFAS agenda action is listed at the proposed-rule stage for chromium wastewater. Germany’s hardening assessment reflects the EU’s July 1, 2027, deadline for covered Chapter II operators to prepare and implement environmental management systems aligned with sector BAT conclusions, excluding Directive (EU) 2024/1785 Article 3(4) installations. This deadline is distinct from Article 14(1)(ba) permit requirements for certain existing installations, which follow the amending directive’s separate Article 3(2) transition triggers. China’s current standard and Jinchengda Circuit’s December 2025 Taishan approval support continuity under stricter applicable national/provincial limits, using direct-discharge conditions initially and indirect-discharge conditions if centralized treatment becomes operational.
Value Chain Stages
The comparison follows copper foil, copper-clad laminates and board fabrication through the products suppliers sell and the constraints on added output. Co-Tech Development Corporation reported that electrolytic copper foil represented 100% of its business mix in 2025. Kingboard Laminates’ Laminates Division revenue increased 10% in 2025. These examples distinguish specialized material supply from the conversion stages that turn upstream inputs into finished-board supply.
Value Chain Analysis Table of Printed Circuit Board Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Copper-foil production | Copper-foil producers such as Co-Tech Development Corporation | Copper-foil sales | HVLP4 supply growth lagging AI demand, according to Co-Tech | Phase high-grade capacity additions with downstream material requirements |
| Copper-clad laminate production | Laminate producers such as Kingboard Laminates Holdings Limited | Laminate sales | Coordination of specialized foil supply and laminate capacity | Align laminate expansion with the availability of required foil grades |
| PCB fabrication | PCB manufacturers such as TTM Technologies Inc. and Unimicron Technology Corp. | Board sales | Scaling the processes required for advanced interconnect products | Pair fabrication investment with equipment-provider processing and service support |
| Source: Mordor Intelligence | ||||
Co-Tech’s 2025 annual report attributed the HVLP4 supply-demand gap to high technical barriers and difficult capacity expansion. Additional fabrication equipment alone cannot resolve a shortage of the particular foil grade needed upstream. In AI-oriented production, specialized foil capacity can therefore determine how much downstream investment becomes productive, shifting the commercial importance of expansion toward the required material capability.
Competitive Landscape
Market Concentration
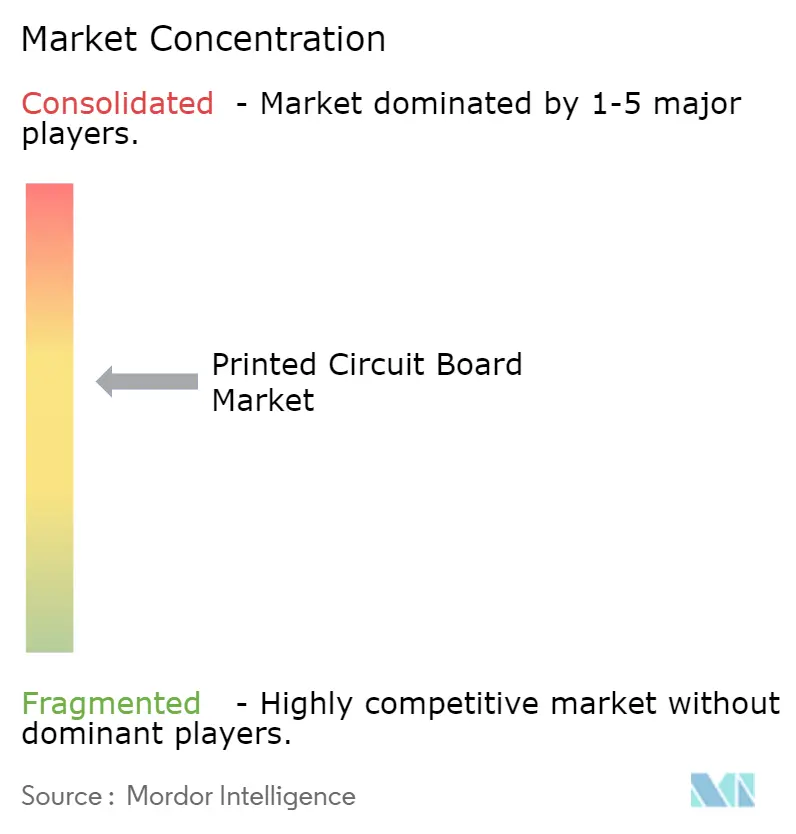
A moderately fragmented field includes Zhen Ding Technology Holding Ltd.’s group, which supplies PCBs, substrates and modules to brand and electronics manufacturing services customers. Unimicron Technology Corp. competes in commercial PCB fabrication, while Tripod Technology Corporation reported 11.54% growth in 2025 consolidated revenue and identified PCBs as its principal product. TTM Technologies Inc. serves aerospace and defense programs with Ultra-HDI PCB and advanced-packaging capability. MEKTEC Corporation (formerly Nippon Mektron Ltd.), part of the NOK Group, supplies FPCs primarily to automakers from its European development and production sites. This mix gives buyers alternatives in portfolio breadth and application focus, making the ability to serve a particular board program an important basis of competition.
TTM opened its 215,000-square-foot Ultra-HDI facility on its Syracuse, New York, campus on June 22, 2026. The purpose-built facility combines PCB and advanced-packaging production for aerospace and defense programs, giving those programs an additional U.S. manufacturing option. At the company level, TTM said facility security clearance was required to win and perform classified Department of War and certain other U.S. government contracts. For challengers seeking the same classified work, competition therefore requires both the offered interconnect capability and the applicable security standing, raising the entry task beyond building equivalent factory space for general commercial PCB production.
MEKTEC’s European strategy illustrates a different route to improving the commercial organization around an existing FPC production base. Effective January 1, 2025, it consolidated 3 German group companies into Mektec Europe GmbH, centralizing German production and sales. The company said the move was intended to speed decisions and strengthen its response to the European market. For automotive FPC customers, that organization can provide a single German entity for production and sales coordination. Competitive differentiation can therefore come from consolidating the route between an automaker’s requirements and regional FPC production, even when the underlying manufacturing locations are already established.
Printed Circuit Board Industry Leaders
-
Zhen Ding Technology Holding Ltd.
-
Unimicron Technology Corp.
-
Tripod Technology Corporation
-
TTM Technologies Inc.
-
MEKTEC Corporation
- *Disclaimer: Major Players sorted in no particular order
Printed Circuit Board Market Companies Covered in this Report
- Zhen Ding Technology Holding Ltd.
- Unimicron Technology Corp.
- MEKTEC Corporation
- TTM Technologies Inc.
- Samsung Electro-Mechanics Co., Ltd.
- Compeq Manufacturing Co., Ltd.
- Tripod Technology Corporation
- Shennan Circuits Co., Ltd.
- Young Poong Electronics Co., Ltd.
- Ibiden Co., Ltd.
- HannStar Board Corp.
- AT&S AG
- LG Innotek Co., Ltd.
- Kinwong Electronic Co., Ltd.
- DSBJ (Dongshan Precision)
- Kingboard Holdings Ltd.
- Shinko Electric Industries Co., Ltd.
- Flexium Interconnect Inc.
- Nan Ya PCB Corp.
- Isola Group
Key Opportunities for Market Participants
These opportunities compare specialization for AI-server PCBs with capital and local-input strategies for multilayer PCB production. Uttar Pradesh’s component policy covers qualifying multilayer PCB projects and is effective from April 1, 2025, through March 31, 2031. The commercial test differs between delivering more demanding boards and organizing a qualifying manufacturing project around its financing and material supply.
Market Opportunities Table of Printed Circuit Board Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Specialized AI-server PCBs | AI-related board specification upgrades | Computing and Data Centers | Qualify high-layer-count, low-loss PCB platforms | Achieving the required layer complexity and signal-loss performance | Advanced multilayer PCB fabricators |
| Modernized multilayer PCB production | Capital-support provisions for qualifying units | Eligible existing PCB units in Uttar Pradesh | Stage capital upgrades against the applicable subsidy terms | Financing and commissioning upgraded production equipment | Qualifying multilayer PCB manufacturers |
| Locally integrated multilayer PCB production | Additional incentive for qualifying laminate sourcing or manufacturing | Multilayer PCB manufacturing in Uttar Pradesh | Build board production around qualifying local laminate supply | Coordinating laminate availability with PCB production | Eligible PCB producers with local material integration |
| Source: Mordor Intelligence | |||||
The local laminate provision adds 1% for qualifying in-state sourcing or manufacturing, subject to other eligibility conditions. The policy limits the state incentive to 50% when the qualifying source is outside Uttar Pradesh, and partial sourcing is treated pro rata. Eligible units not covered or approved under India’s ECMS scheme have a separate 20% capital-subsidy path. The central opening is manufacturing capability that satisfies a defined board specification or a qualifying local-production model, with financial support complementing the work needed to establish saleable PCB output.
Recent Industry Developments in Printed Circuit Board Market
- Oct 2026: TTM Technologies Inc. announced a planned USD 400 million AI-specific PCB capacity expansion across 4 Chinese facilities and its Penang, Malaysia, plant, additional to its previously disclosed USD 1.2 billion 2025-2029 commitment.
- Jun 2026: Uttar Pradesh’s chief minister and India’s electronics minister laid foundation stones at Jewar for 2 electronics manufacturing projects whose facilities would manufacture advanced multilayer PCBs.
- Jun 2026: TTM Technologies Inc. opened a 215,000-square-foot facility on its Syracuse, New York, campus for Ultra-HDI PCBs and advanced packaging serving aerospace and defense programs.
Printed Circuit Board Market Report Scope and Research Methodology
Market Definition and Coverage
Printed circuit board market measures annual spending on fabricated printed circuit boards and IC package substrates sold in the Global market. Value is measured at the PCB producer's selling price before board assembly.
Scope exclusions: Printed circuit board assemblies, separately sold substrate inputs including copper-clad laminates, copper foil, and resins, separately sold mounted electronic components including semiconductors, and finished electronic products are excluded.
Segments Covered in This Report
- By PCB Type
- Standard Multilayer (non-HDI)
- Rigid 1-2 Sided
- High-Density Interconnect (HDI)
- Flexible Circuits (FPC)
- IC Substrates (Package Substrates)
- Rigid-Flex
- Other PCB Types
- By Substrate Material
- Glass Epoxy (FR-4)
- High-Speed and Low-Loss
- Polyimide (PI)
- Packaging Resins (BT and ABF)
- Other Substrate Materials
- By End-User Industry
- Consumer Electronics
- Computing and Data Centers
- Telecommunications and 5G
- Automotive and EV
- Industrial and Power
- Healthcare and Medical
- Aerospace and Defense
- Other End-User Industries
- By Geography
- North America
- United States
- Rest of North America
- Europe
- Germany
- United Kingdom
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Taiwan
- Japan
- India
- South Korea
- Southeast Asia
- Rest of Asia-Pacific
- Rest of World
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Public sources such as the European Commission Joint Research Centre's PCB process reference, Eurostat's PRODCOM guidance, ITU's mobile network coverage series and TechNews's reporting on PCB industry data provide technical production context, comparable sold-production measures, downstream connectivity indicators and reported industry results. These sources can help relate board output and product mix to end-market demand while keeping electronics shipments separate from PCB producer sales.
Company annual reports, regulatory filings, investor materials, and reputable trade press can supplement these sources by checking reported capacity, product mix, material costs, and customer applications against industry indicators. The named sources are illustrative rather than exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
Structured interviews and survey responses would be sought from PCB fabricator executives, sales and planning leaders, package-substrate specialists, and electronics procurement or design managers across the global supply chain. These respondents can check secondary estimates of producer sales, product mix, pricing, capacity, and regional demand, while unresolved gaps are compared with independent company disclosures and industry series. Conflicting evidence would be followed up with relevant respondents and retained as a range for analyst review where a single supported point is not available.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 25% | CXOs: 20% | APAC: 50% |
| Mid tier: 55% | Functional/Unit leaders: 35% | EMEA: 25% |
| Smaller Players: 20% | Managers: 45% | Americas: 25% |
Market-Sizing & Forecasting
The analyst estimates global annual value at the PCB producer's ex-factory selling price, starting with reported global board and package-substrate sales and checking the total against production, trade, and supplier evidence. Key indicators include fabricated-board shipments, average selling prices by board type, package-substrate producer sales, end-market equipment output in computing, telecommunications and automotive, and regional manufacturing output. These help distinguish changes in volume, product mix, pricing, and location. Reported segment shares are assembled from supplier and industry breakdowns and checked across PCB type, substrate material, end-user industry, and region, with each category tied to the sale of the finished board or substrate. A multivariate regression can project total value from historical sales and these demand and pricing indicators, with scenario analysis for material-cost swings, capacity additions, and demand changes where historical relationships are unstable. Selective supplier roll-ups and sampled average selling price times shipment checks test the top-down total. Missing or overlapping disclosures are reconciled against published totals and comparable company periods, with unsupported cells left out of the point estimate. Respondents with relevant production, procurement, or design responsibility can challenge individual assumptions and forecast drivers, and analyst review resolves differences against the documentary record.
Data Validation & Update Cycle
Analysts triangulate market totals and segment shares across industry series, producer disclosures, trade measures, and demand indicators, then investigate material variances, unit mismatches, duplicate sales, and unusual year-to-year movements before sign-off. A second review checks definitions, calculation links, source dates, and consistency between the global total and its product, customer, and regional splits. Re-contact is triggered when a key input conflicts with a respondent's documented operating context or a new disclosure changes an assumption. The model is refreshed annually, updated between cycles after material events such as major capacity changes or demand shocks, and given a fresh source and calculation review before delivery.
Mordor Intelligence's Printed Circuit Board Market Size Measured Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. Printed circuit board market measures annual spending on fabricated printed circuit boards and IC package substrates sold in the Global market.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Key indicators include fabricated-board shipments, average selling prices by board type, package-substrate producer sales, end-market equipment output in computing, telecommunications and automotive, and regional manufacturing output.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 105.5 B (2027) | |
| Global Consultancy A | USD 85.8 B (2025) | At its 2025 base, this estimate is 18.7% below this report's 2027 value of USD 105.5 B, 2 years later. The published measure is explicitly the bare-board PCB market, while this report also counts finished IC package substrates. |
| Global Consultancy B | USD 82.7 B (2025) | At its 2025 base, this estimate is 21.6% below this report's 2027 value of USD 105.5 B, 2 years later. Its published 2025 base precedes this report's 2027 comparison year. Its stated product groupings do not establish package-substrate treatment. |
Mordor Intelligence's analysts triangulate market totals and segment shares across industry series, producer disclosures, trade measures, and demand indicators, then investigate material variances, unit mismatches, duplicate sales, and unusual year-to-year movements before sign-off.
Key Questions Answered in the Report
What is the Printed Circuit Board market size and growth outlook?
Size is projected to rise from USD 105.5 billion in 2027 to USD 136 billion by 2032, at a 5.21% CAGR between 2027 and 2032.
What is driving demand for circuit boards?
AI-server production, electric-drive programs and chiplet integration support demand. Dell reported USD 16.4 billion in AI-optimized server revenue in its fiscal 2027 second quarter ended July 31, 2026.
Which PCB type generates the largest revenue share?
Standard multilayer (non-HDI) boards led with a 29.48% share of global PCB revenue in 2026.
Which companies compete in the PCB industry?
Major suppliers include Zhen Ding Technology Holding Ltd., Unimicron Technology Corp., Tripod Technology Corporation, TTM Technologies Inc. and MEKTEC Corporation.
What constraint could slow PCB expansion?
Input-cost uncertainty can constrain expansion. Kunshan Wanyuantong Electronics Technology Co., Ltd. reported a 19.7% gross margin in 2025, with raw-material fluctuations among several profitability pressures.
Which region leads PCB revenue and growth?
Asia-Pacific held 82.66% of global PCB revenue in 2026 and is forecast to grow fastest, at a 5.25% CAGR between 2027 and 2032.