
Plastic Packaging Market Analysis by Mordor Intelligence
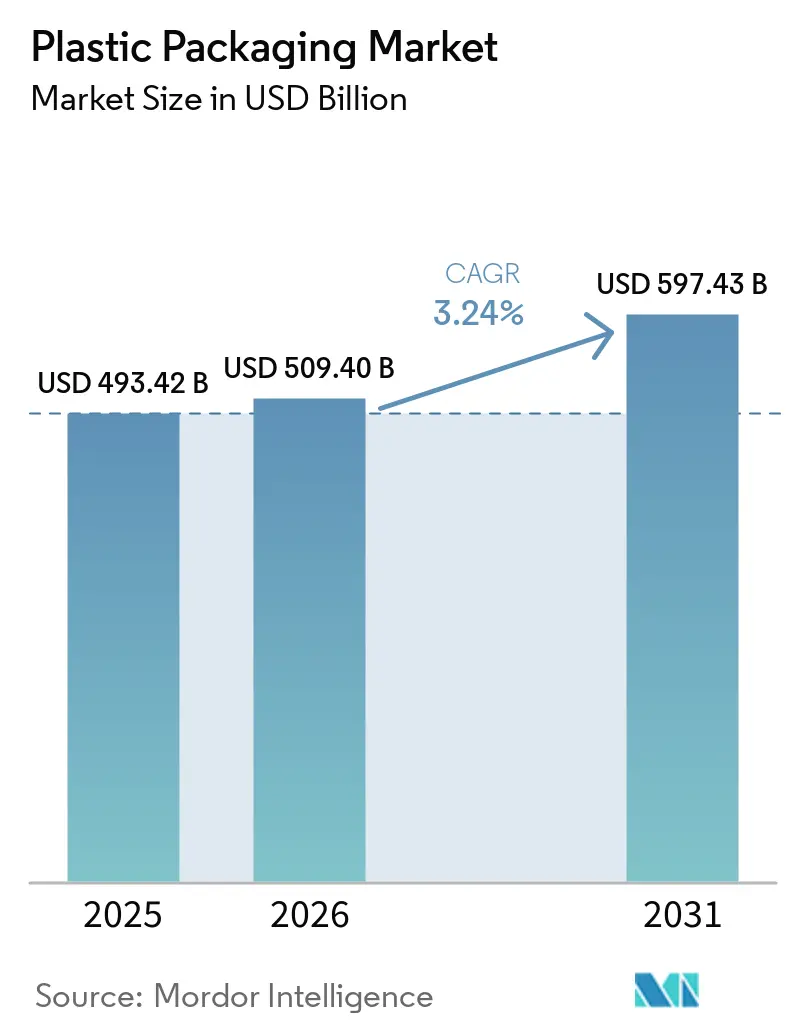
The plastic packaging market size is projected to expand from USD 509.4 billion in 2026 and USD 525.9 billion in 2027 to USD 623.4 billion by 2032, registering a CAGR of 3.46% between 2027 and 2032.
Convenience-food demand in Japan and expanding e-commerce shipments support recurring packaging needs across food and delivery applications. Suppliers respond through mono-material films and integrated recycled-feedstock routes that connect packaging design with material availability. The Iran conflict disrupted shipping in the Strait of Hormuz from March 2026, adding resin-cost pressure that can reach converter margins before contract pass-through recovers it. England's restrictions on specified polystyrene containers, the United Kingdom's recycled-content tax rules, and the European Union's future recycled-content requirements make permitted formats and qualifying material inputs part of the same design decision. The commercial opening lies in qualified pack designs backed by reliable material supply and the ability to recover changing input costs.
Key Report Takeaways
- Packaging type was led by flexible packaging, which held a 54.66% plastic packaging market share in 2026 and is forecast to grow fastest at a 4.54% CAGR between 2027 and 2032.
- Among materials, polyethylene held a 41.61% share of the plastic packaging market size in 2026, while polypropylene is forecast to grow fastest at a 5.72% CAGR between 2027 and 2032.
- By end-user industry, food led with 27.95% of the market in 2026, while healthcare and pharmaceuticals are forecast to be the fastest-growing segment at a 6.4% CAGR between 2027 and 2032.
- Distribution channels were led by direct sales, with 64.25% of the market in 2026, while indirect sales are forecast to grow fastest at a 4.78% CAGR between 2027 and 2032.
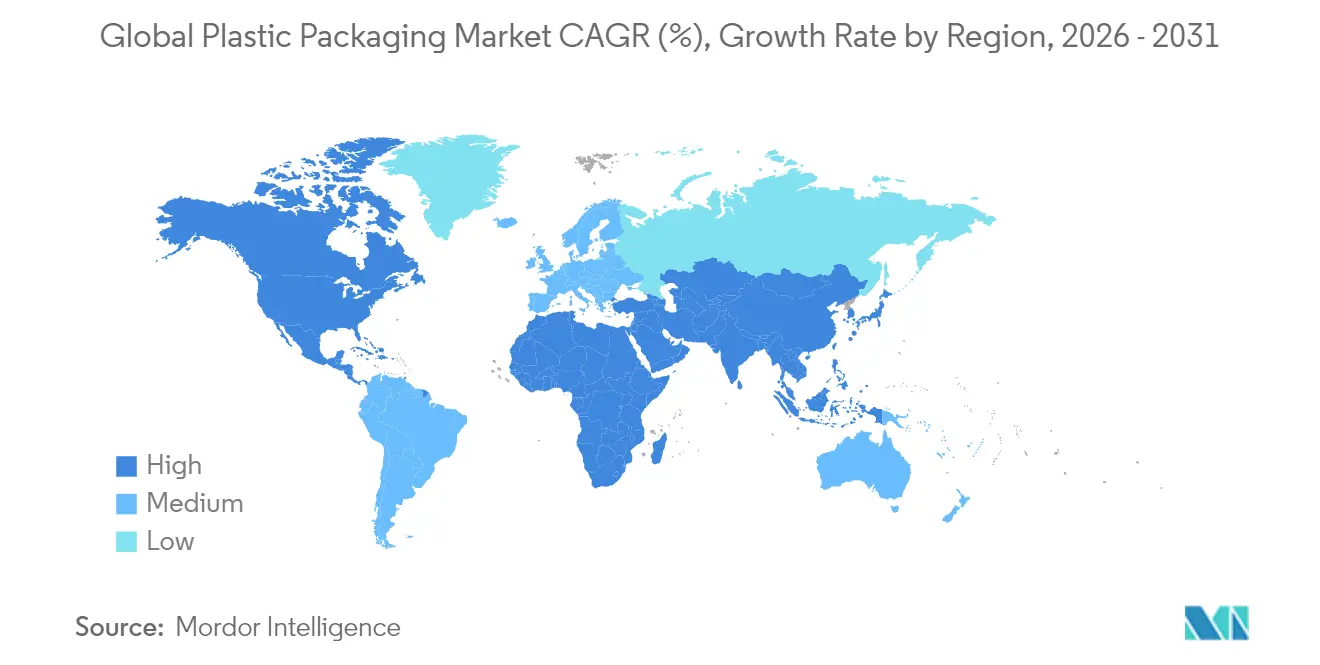
- Across geographies, Asia-Pacific led with 42% of the market in 2026 and is also forecast to be the fastest-growing region at a 6.9% CAGR between 2027 and 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Plastic Packaging Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| E-commerce boom demanding durable last-mile packs | +1.3% | Across European countries | Short term (≤ 2 years) |
| Surge in convenience-food and beverage consumption | +1.4% | United States and Japan | Short term (≤ 2 years) |
| Cost-competitive performance versus alternate substrates | +1% | Within the Canadian market | Medium term (2-4 years) |
| Expansion of chemical-recycling infrastructure | +0.8% | Within the Austrian market | Long term (≥ 4 years) |
| Shift to mono-material films for EPR compliance | +0.6% | European Union member states | Medium term (2-4 years) |
| EU tethered-cap rule driving specialty closures volume | +0.3% | European Union member states | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
E-commerce boom demanding durable last-mile packs
Expanding e-commerce parcel flows enlarge the potential shipment base for flexible plastic packaging. Geopost handled 2.24 billion parcels worldwide in 2025, up 5% from 2024, and reported a 9% increase in B2C volumes. During its 2025 peak period, the operator delivered 392 million parcels across Europe, up 9.1% from the corresponding 2024 period. Geopost's busiest day, December 1, 2025, reached 12.2 million parcels against a daily average above 8 million, illustrating the scale of individual dispatches. Beauty retailer Sa Sa International Holdings Limited used 8,149 kg of plastic bubble wrap in online delivery in FY2024/25, up 50% from FY2023/24, and attributed the increase to protecting glass products ordered by customers. Protecting glass products provides a specific plastic-packaging use within online retail, while expanding parcel networks offer a larger shipment pool that suppliers could serve.
Surge in convenience-food and beverage consumption
Prepared foods can create packaging demand for components of a meal as well as complete ready-to-eat dishes. In 2026, FMI, the Food Industry Association, reported that 56% of US households combined home preparation with foods prepared outside the home for dinner at least weekly. Japan's prepared-food market value grew 3.7% in 2025, according to the Japan Delicatessen Association. The Japanese association linked sustained demand to growth in single-person and dual-earner households and population aging, alongside a preference for meal quality with less preparation. Hybrid dinners extend the opportunity for converters to packs for prepared meal components, which retain a role even when shoppers continue cooking at home.
Cost-competitive performance versus alternate substrates
For fresh-produce packers, replacing plastic can change both the cost of the pack and the economics of the packing line. A 2025 Canadian study estimated that paper or fiber packaging materials typically cost 4 times as much as existing plastic packaging for 6 fresh-produce items comprising lemons, apples, grapes, onions, carrots, and tomatoes.[1] It also estimated approximately 20% lower packing-line run rates and 20% more packing labor for the same produce volume. A lower run rate means fewer packs per hour, so maintaining output would require more line time. A packer switching to fiber would therefore absorb the premium in materials and labor together, giving plastic a cost advantage that extends beyond the packaging purchase in these applications.
Expansion of chemical-recycling infrastructure
Chemical recycling creates an additional feedstock route for packaging producers seeking material from collected plastic waste. OMV started up a scaled-up ReOil plant at its Schwechat refinery in Austria in March 2025, with capacity to process up to 16,000 metric tons of hard-to-recycle mixed plastic waste annually. OMV processes the resulting pyrolysis oil into base chemicals for new plastics, including feedstock suitable for contact-sensitive packaging. Its 2025 operating disclosure described ISCC PLUS-certified post-consumer waste supplied by value-chain partners, including mechanical recyclers. Feedstock suitable for contact-sensitive packs gives converters a route to serve future EU recycled-content demand in covered applications, provided the material qualifies for the relevant minimum.
Restraints Impact Analysis of Plastic Packaging Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Global single-use plastic bans and taxes | -0.9% | United Kingdom and India | Short term (≤ 2 years) |
| Volatile petro-feedstock prices | -0.6% | Within the United States | Short term (≤ 2 years) |
| Brand owners pivoting to paper-based flexibles | -0.3% | China and Slovakia | Medium term (2-4 years) |
| Refill/reuse models cannibalizing volume growth | -0.2% | Within the French market | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Global single-use plastic bans and taxes
Packaging converters face different commercial risks when regulation raises a product's cost or removes its permitted use. The United Kingdom taxes finished plastic packaging components containing less than 30% recycled plastic when suitable for moving goods from manufacturer to end user or used only once by consumers. Export reliefs and specified exemptions narrow that taxable population. England bans sales and supply of single-use expanded and extruded polystyrene containers for food or drink ready to consume without further preparation. This restriction removes an outlet for the affected formats, while the tax changes the economics of qualifying components. Increasing recycled content can address the tax threshold, but it cannot restore the prohibited container's sales route.
Volatile petro-feedstock prices
Resin-cost volatility exposes film converters to margin losses even when contractual cost recovery exists. Strait of Hormuz shipping disruptions during the Iran conflict began in March 2026 and increased Tredegar's resin costs. Tredegar's advanced packaging films are predominantly manufactured and sold in the United States. The business incurred a USD 0.7 million contribution-margin charge from the pass-through lag in Q2 2026, versus no charge or benefit in Q2 2025.[2] In its Q2 2026 results, Tredegar reported maintaining customer pass-through mechanisms and having experienced no supply issues to date. The constraint was therefore timing rather than availability, because higher resin costs reached contribution margin before pass-through recovered them.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Plastic Packaging Market Segment Analysis
By Packaging Type:
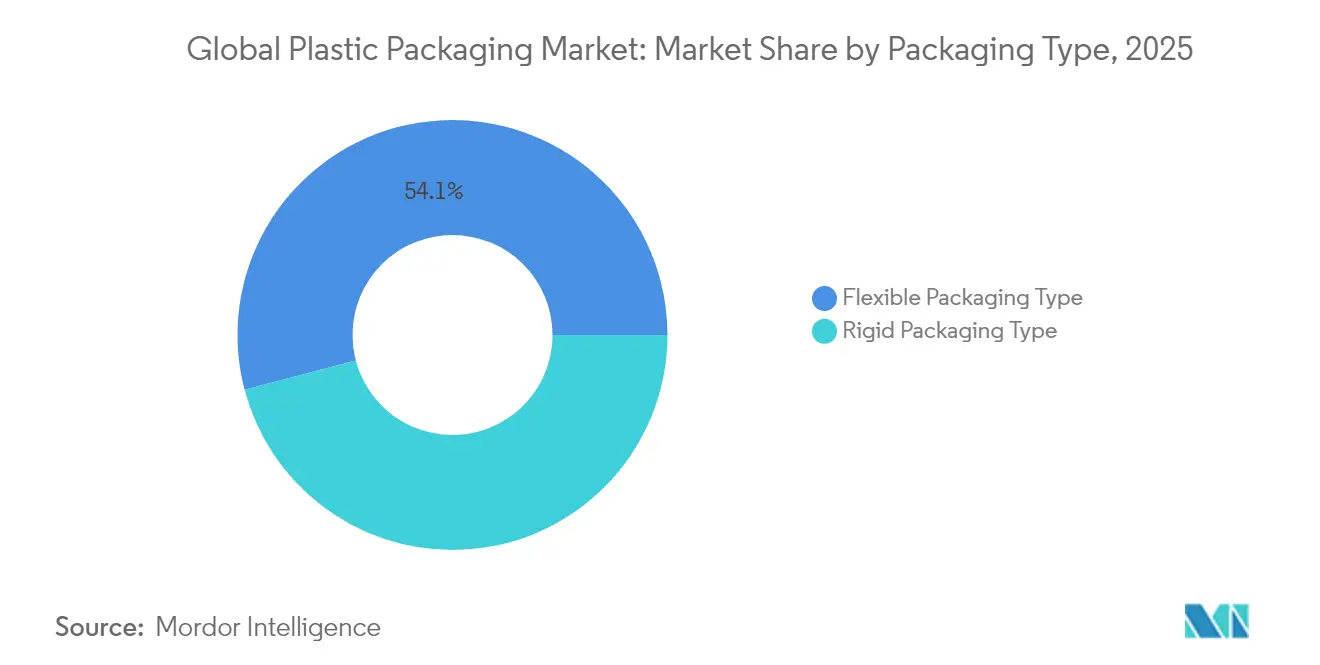
Installed Scale and Application-Specific FilmsFlexible packaging accounted for a 54.66% share of the plastic packaging market size in 2026, making it the largest segment, and is forecast to be the fastest-growing segment with a 4.54% CAGR between 2027 and 2032. ABIEF, the Brazilian flexible plastic packaging industry association, reported production of 2.32 million metric tons in 2025, down 0.5% from 2024, while industry revenue in reais rose 6.2%. Capacity utilization in that Brazilian industry was 70.4% in 2025. Lines running at 70.4% of installed capacity leave Brazilian converters room to raise output on existing equipment before adding new capacity.
Flexible-packaging producer Coveris completed an upgrade of its Halle facility in Germany in 2025 that included a new cast-film extrusion line. The line entered full production after successful material qualification. Its applications included recyclable monofilms for thermoforming and medical packaging. Coveris linked the investment to greater flexibility in material development and the production of customized packaging solutions. Qualification before full production ties the new line's output to specific thermoforming and medical film grades.

By Material:
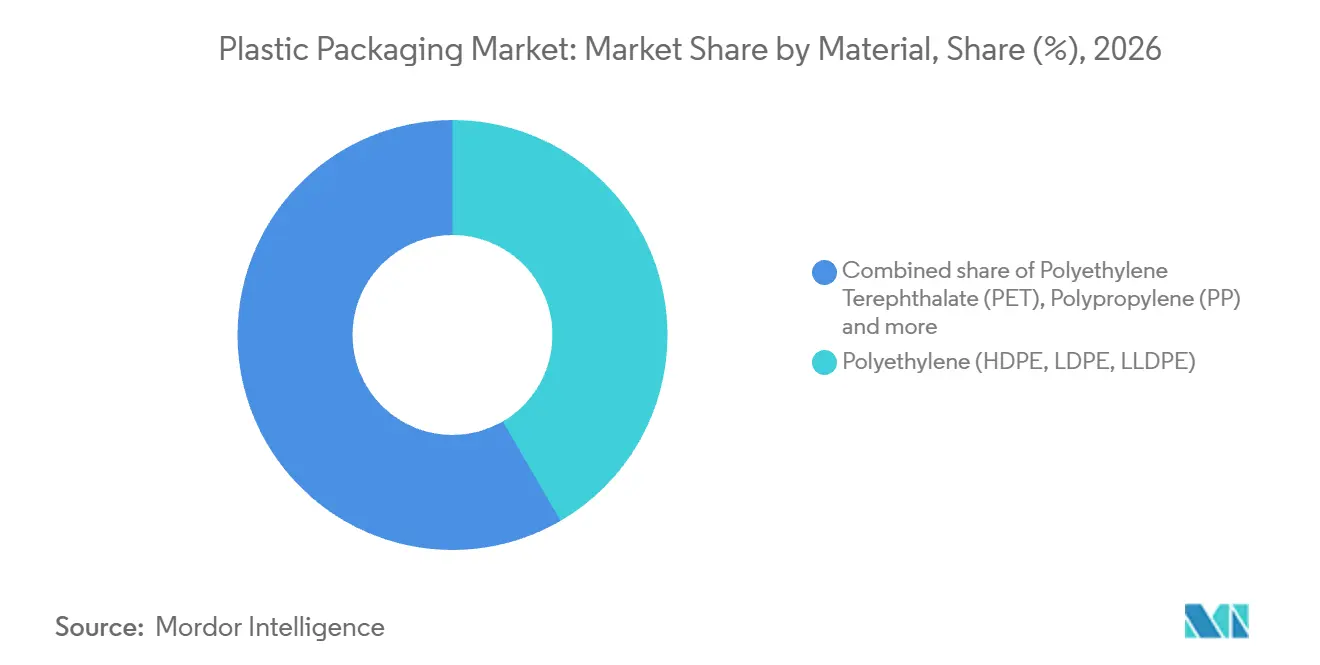
Polyethylene Scale and Polypropylene InvestmentPolyethylene (HDPE, LDPE, and LLDPE) represented a 41.61% plastic packaging market share in 2026, making it the largest segment. As of March 31, 2026, TCPL Packaging Limited reported capacity of more than 300 metric tons per month for a 5-layer blown-film line in India.[3] Its installed line enabled mono-material all-PE films as an alternative to complex multi-polymer laminate structures in FY2025-26. The example separates layer count from polymer variety, showing how a converter can develop a layered film while retaining a single polymer family as the material base.
Polypropylene (PP) is forecast to be the fastest-growing segment, with a 5.72% CAGR between 2027 and 2032. In May 2026, UFlex Limited reported that it was setting up a biaxially oriented polypropylene (BOPP) packaging-film line in Dharwad, India, with planned annual capacity of 54,000 metric tons and commissioning expected during FY2027-28. UFlex linked the investment to rising demand for BOPP packaging films in the Indian market. The expected FY2027-28 commissioning places the planned 54,000 metric tons of annual capacity beyond Indian BOPP buyers' immediate supply options.
By End-user Industry:
Food Scale and Healthcare Process ControlFood was the largest segment by end-user industry, accounting for 27.95% of the market in 2026. Sealed Air's Food business generated USD 3.59 billion in net sales in 2025, providing a producer-level example of commercial scale serving food applications. Reported sales rose 0.3% from 2024, as positive price and foreign-currency effects offset a negative volume-and-product-mix contribution. Food sales fell 0.1% on a constant-currency basis in 2025, leaving this producer's large food-packaging business without revenue expansion once currency translation is removed.
The healthcare and pharmaceuticals segment is forecast to be the fastest-growing segment, with a 6.4% CAGR between 2027 and 2032. Amcor inaugurated a new line at its Sira facility in India on June 3, 2026, expanding healthcare-packaging capacity for ophthalmic containers, injectable vials, and other applications. The investment introduced fully automated online vision systems intended to enhance quality and consistency. Amcor identified a customer base ranging from global pharmaceutical companies to emerging local businesses. Pairing the added Sira capacity with automated online vision inspection gives pharmaceutical customers, from global companies to emerging local ones, the same quality and consistency controls.
By Distribution Channel:
Direct Supply Contracts and Intermediary ReachDirect sales were the largest segment, accounting for 64.25% of the market in 2026. On June 5, 2025, independent shareholders of Tingyi, the Chinese food and beverage group behind the Master Kong brand, approved a proposed 2026-2028 agreement to buy flexible plastic packaging materials and plastic products from manufacturer Tingzheng and its subsidiaries. Tingzheng is a connected supplier beneficially owned by family members and relatives of Tingyi executives. The approved agreement specifies a 3-year term from January 1, 2026 to December 31, 2028 for purchases from the manufacturer and its subsidiaries, a direct buyer-to-producer route rather than a distributor sale.
Indirect sales are forecast to be the fastest-growing segment, with a 4.78% CAGR between 2027 and 2032. Belgian wholesaler GAASCH PACKAGING NV/SA estimated 541 B2B customers in 2025, with that customer record covering 83% of its reported sales spend. Its primary-packaging portfolio included plastic beverage bottles and food jars alongside glass packaging. Offering glass alongside plastic makes material selection part of GAASCH's distribution offer, so access to its business customers does not reserve their packaging orders for plastic.
Geography Analysis
Asia-Pacific Plastic Packaging Market
Asia-Pacific, the largest and fastest-growing region, accounted for 42% of the plastic packaging market size in 2026 and is forecast to register a 6.9% CAGR between 2027 and 2032. China exported plastic-packaging products worth USD 19.41 billion in 2025, down 1.6% from 2024, illustrating an established export supply base. In September 2025, Mainetti opened a 5,000-square-meter factory in Hung Yen Province, Vietnam, described as expanding flexible-packaging supply for regional and international retail brands. Vietnamese production creates an in-region sourcing option for retail brands, so new capacity can serve Southeast Asian customers alongside the region's established export business.
In February 2025, Evertis announced a planned USD 100 million PET multilayer-film plant in Columbia, South Carolina, to serve North American packaging buyers. The project was scheduled to begin operations in Q2 2028, with first commercial sales anticipated later in 2028. In Europe, Dutch plastic-packaging producer Royal Hordijk reserved multiyear access to Avantium's future licensed-plant polyethylene furanoate (PEF) volumes in June 2025 for trays and injection-molded packaging. Neither arrangement adds supply before its plant operates, since Evertis's plant was scheduled for Q2 2028 and Hordijk's PEF volumes depend on future licensed plants.
Within the Middle East and Africa, Mpact's Plastics business manufactured bins, crates, and rigid plastic packaging in southern Africa in 2025. Its market coverage included beverage, personal-care, homecare, pharmaceutical, agricultural, and retail applications, linking the manufacturing base to several end-use industries. In South America, Brazilian agribusiness demand for flexible plastic packaging grew 9.7% to 316,000 metric tons in 2025. Flexible-packaging demand from Brazil's food industry declined 3% in the same year. Regional expansion depends on end-use exposure as much as location, since Brazilian agribusiness demand rose while food-industry demand fell and southern African production served several industries.
Regulatory Framework and Outlook
This comparison assesses selected jurisdictions from the perspective of a single-use plastic packaging manufacturer, with the United States assessed through California's SB 54 program. These producers face end-of-life financing, registration, recyclability, and recycled-content duties that differ by jurisdiction, so each rating reflects the design change and cost a manufacturer must absorb. Germany's Verpackungsrecht-Durchführungsgesetz took effect on August 12, 2026, replacing its former Packaging Act and supporting the EU Packaging and Packaging Waste Regulation (PPWR). India's producer content targets reference annual packaging manufacture, with Category III multilayer calculations limited to plastic-layer weight and documented exemptions where recycled plastic is legally prohibited.
Regulatory Table of Plastic Packaging Market
| Decision factor | United States | Germany | India | Brazil |
|---|---|---|---|---|
| Primary authority | CalRecycle for California | Central Agency Packaging Register (register duties); Umweltbundesamt (supervision) | Central Pollution Control Board portal; State Pollution Control Boards or Committees for registrations in 1 or 2 states | Ministry of the Environment and Climate Change |
| Key instruments or direction | California SB 54; permanent regulations effective May 1, 2026 | PPWR; Verpackungsrecht-Durchführungsgesetz; limits for covered PFAS-containing food-contact packaging | Plastic Waste Management Rules and extended producer responsibility guidelines; 2026 content amendment | Decree 12,688/2025 on plastic-packaging reverse logistics and recovery targets |
| Commercial effect | Producer end-of-life responsibility and 2032 single-use packaging targets | Food-contact restrictions; future market access requires recyclability grades A, B, or C | Category-specific producer targets; exemption claims need supporting instruments or standards in annual returns | Covered supply-chain participants must operate and finance reverse logistics |
| Current policy attractiveness | Low | Medium | Medium | Low |
| Future direction of policy attractiveness | Hardening | Hardening | Hardening | Hardening |
| Source: Mordor Intelligence | ||||
The United States rating reflects California's SB 54 end-of-life producer responsibility and required 25% reduction in sales or distribution of single-use plastic packaging and plastic food service ware by 2032 from 2023. Germany's Medium rating combines defined register administration and food-contact restrictions with grade-based access from January 1, 2030, or 24 months after the relevant delegated acts enter into force, whichever is later, subject to Article 6(10). India's Medium rating reflects defined registration responsibilities and category-specific producer targets that rise from 2026-27 to 2027-28, with annual-return evidence required for statutory exemption claims. Brazil's Low rating reflects financed reverse logistics and national recovery targets rising from 32% in 2026 to 37% in 2030 against prior-fiscal-year packaging mass placed on the market.
Value Chain Stages
The comparison follows polymer supply, packaging conversion, and recovery into recycled resin, separating the sources of supplier earnings. On October 14, 2026, Plastipak Packaging Inc., a subsidiary of Plastipak Holdings Inc., opened its PET Material Center in Verbania, Italy, which manufactures PET resin with 30% recycled content. The investment illustrates how material composition can be defined upstream of the finished packaging product.
Value Chain Analysis Table of Plastic Packaging Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Polymer resin production | Resin producers such as LyondellBasell and Plastipak Packaging Inc. | Polymer resin sales | Grade selection for container and film applications | Qualify resin grades for the intended packaging application |
| Packaging conversion | Packaging converters such as Amcor PLC and Plastipak Packaging Inc. | Finished-packaging sales | Pack-specific forming and conversion expertise | Develop pack design and production processes together |
| Recovery into recycled resin | Recycled-resin producers such as Plastipak Packaging Inc. | Recycled-resin and recycled-content packaging sales | Controlling the chosen recycled-content blend | Integrate material recovery with resin formulation |
| Source: Mordor Intelligence | ||||
Embedding recycled content in resin production creates a different technical entry requirement from mastering pack forming or barrier conversion. Amcor's high-barrier coating and conversion expertise provides an example of differentiation through the production process. Integration links material recovery with a saleable resin specification, while specialist converting capabilities create a separate basis for packaging-product revenue.
Competitive Landscape
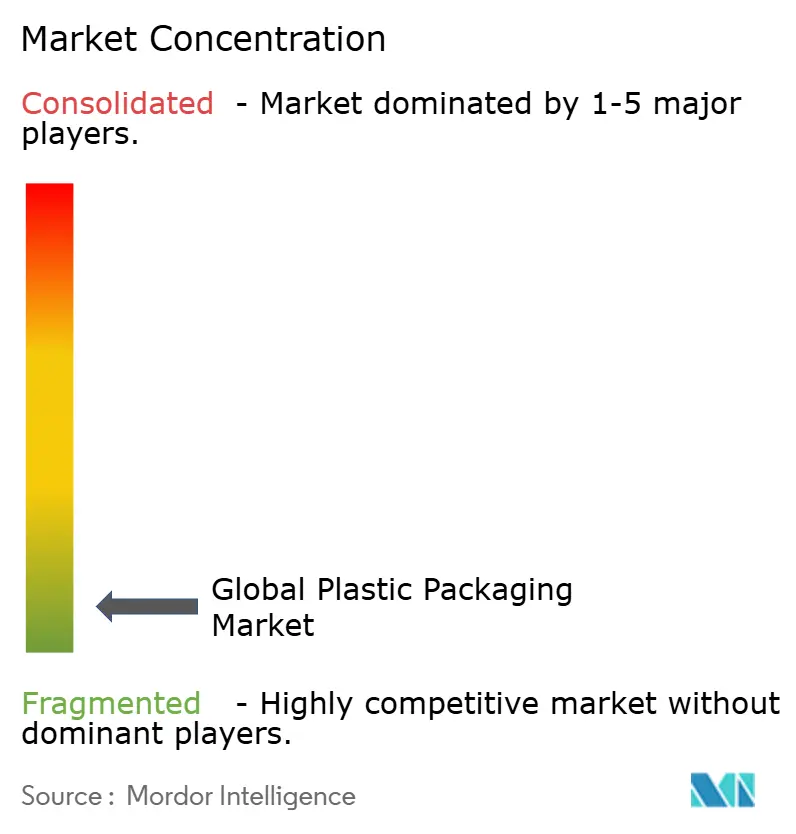
Competition is moderately fragmented across packaging applications, with diversified groups operating alongside more specialized plastic-product capabilities. Mondi PLC offers polymer-based flexible packaging, and Huhtamaki Oyj operates a flexible-packaging business. Amcor PLC completed its all-stock combination with Berry Global on April 30, 2025, bringing together their consumer and healthcare packaging businesses. Sealed Air Corporation, owned by funds affiliated with Clayton, Dubilier & Rice (CD&R), supplies food and protective packaging, while Sonoco Products Company offers industrial and specialty plastic products including in-mold labeled containers. Sonoco's specialty containers, Sealed Air's food and protective lines and Amcor's combined consumer and healthcare portfolio address different buyer applications.
Huhtamaki Oyj's flexible-packaging segment reported 5% comparable net sales growth in the first half of 2026. Its adjusted earnings before interest and taxes (EBIT), which excluded items affecting comparability, increased 25% from the first half of 2025. For the second quarter of 2026, the company said volume growth supported segment net sales while it passed on raw-material cost increases, and cost savings plus volume growth drove adjusted EBIT growth. Together, cost recovery and savings create an operating route to stronger competitive earnings, a capability distinct from adding product breadth through a packaging portfolio combination.
On October 15, 2026, Sealed Air announced that it had expanded closed-cell polyethylene foam capacity in Madera, California, to support fabricators, distributors, and end users across North America and Latin America. Mondi launched re/loop FlowWrap with 35% post-consumer recycled content for wet wipes packaging on June 2, 2026. EU post-consumer recycled-content minimums for covered plastic packaging start on January 1, 2030, or 3 years after the relevant implementing act takes effect, whichever is later. Minimums vary by type and format, using annual manufacturing-plant averages and Article 7(4) exemptions for specified medical, food, pharmaceutical, compostable plastic, and dangerous-goods transport packaging. Because minimums use annual manufacturing-plant averages, a product-level share such as re/loop FlowWrap's 35% post-consumer recycled content cannot alone establish compliance, which depends on the applicable plant-year average.
Plastic Packaging Industry Leaders
-
Mondi PLC
-
Huhtamaki Oyj
-
Amcor PLC
-
Sealed Air Corporation
-
Sonoco Products Company
- *Disclaimer: Major Players sorted in no particular order
Plastic Packaging Market Companies Covered in this Report
- Amcor PLC
- Mondi PLC
- Sealed Air Corporation
- ALPLA Group
- International Paper
- Pact Group
- Plastipak Holdings Inc.
- Huhtamaki Oyj
- UFlex Limited
- Constantia Flexibles
- Tetra Pak International SA
- Novolex
- Anchor Packaging LLC
- Liquibox (Sealed Air Corporation)
- Quadpack Industries SA
- Dart Container Corporation
- American Packaging Corporation
- Printpack Inc.
- Winpak Ltd.
- Sigma Plastics Group
- Sonoco Products Company
- Transcontinental Inc.
- Greif, Inc.
- Coveris Group
- Nampak Ltd.
Key Opportunities for Market Participants
The comparison evaluates recycled-content packaging opportunities for suppliers serving European Union and United Kingdom buyers. The EU Packaging and Packaging Waste Regulation began applying in phases on August 12, 2026, and includes future recycled-content duties for covered plastic packaging. From 2027, UK Plastic Packaging Tax policy will introduce mass-balance accounting for chemically recycled plastic and remove pre-consumer waste from recycled-content calculations.
Market Opportunities Table of Plastic Packaging Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Recycled-content pack redesign | Phased EU packaging requirements | Buyers of covered plastic packaging in the EU | Develop pack designs around qualifying recycled inputs | Qualifying inputs for the intended package | Converters offering qualifying recycled-content packs |
| Replacement of pre-consumer inputs | Change in UK recycled-content eligibility | UK packaging manufacturers using pre-consumer recycled material | Reformulate packs around eligible replacement inputs | Demonstrating eligibility of replacement material | Pack makers able to replace excluded inputs |
| Chemically recycled-content packaging | UK recognition of mass-balance attribution | Suppliers and buyers of chemically recycled-content packs | Combine packaging supply with package-specific content attribution | Establishing qualifying mass-balance attribution | Suppliers connecting recycled feedstock to documented packaging claims |
| Source: Mordor Intelligence | |||||
From 2027, pre-consumer waste will no longer count as recycled content under the UK tax policy, so qualifying content will depend on input origin as well as quantity. Replacing an excluded input presents a different commercial task from attributing chemically recycled content to packaging. The nearest-term opening lies with UK-facing pack makers able to document eligible inputs, including mass-balance-attributed chemically recycled material, because UK eligibility changes begin in 2027 and EU minimums start no earlier than 2030.
Recent Industry Developments in Plastic Packaging Market
- Oct 2026: On October 15, Sealed Air Corporation, owned by funds affiliated with CD&R, announced expanded closed-cell polyethylene foam manufacturing capacity at Madera, California. The expansion supports fabricators, distributors, and end users across North America and Latin America.
- Jul 2026: Plastic-packaging producer Plastikpack Maroc inaugurated a plastic-injection production unit in Sidi Bou Othmane, Morocco, on July 7.
- Jun 2026: On June 3, Amcor inaugurated a new production line at its Sira facility in India, increasing capacity for ophthalmic containers, injectable vials and other healthcare packaging.
Plastic Packaging Market Report Scope and Research Methodology
Market Definition and Coverage
The plastic packaging market measures annual spending on packaging products made primarily from plastic polymers and sold to protect, store, or transport goods. It covers sales globally across packaging types, materials, end-user industries, distribution channels, and regions.
Scope exclusions: Paper, glass, and metal packaging, plastic resins and pellets sold before conversion into packaging, packaging machinery and standalone packaging services, and non-packaging plastic products including building materials, furniture, and durable goods are excluded.
Segments Covered in This Report
- By Packaging Type
- Rigid Packaging Type
- Bottles and Jars
- Caps and Closures
- Trays and Containers
- Other Product Types
- Flexible Packaging Type
- Pouches and Bags
- Films and Wraps
- Other Product Types
- Rigid Packaging Type
- By Material
- Polyethylene (HDPE, LDPE, LLDPE)
- Polyethylene Terephthalate (PET)
- Polypropylene (PP)
- Polystyrene and EPS
- Polyvinyl Chloride (PVC)
- Others (EVOH, Bioplastics, etc.)
- By End-user Industry
- Food
- Beverage
- Healthcare and Pharmaceuticals
- Cosmetics and Personal Care
- Other End-user Industry
- By Distribution Channel
- Direct Sales
- Indirect Sales
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Public sources such as Eurostat's packaging-waste data and plastic-packaging recycling release, European Commission packaging-waste guidance, Regulation (EU) 2025/40, and Agriculture and Agri-Food Canada's fresh-produce cost study provide indicators of material use, recovery, recycled-content requirements, and substitution economics. These sources frame evidence across resin, product type, end use, channel, and geography without treating waste tonnage as producer sales. To distinguish actual producer sales from waste measures and locate policy shifts that affect pack specifications, analysts use these publications as separate context checks.
Company filings, investor presentations, and reputable packaging trade reporting can cross-check producer revenue, capacity, product mix, investment, and resin pass-through against demand indicators. These sources are illustrative and not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
The primary research plan uses interviews and structured surveys with packaging producers and converters, resin and material specialists, distributors, and large packaging buyers across APAC, EMEA, and the Americas. Respondents would test secondary estimates for producer selling values, pack formats, material and end-use mix, channel routes, and changes in resin pass-through, while targeted follow-up would address missing company or country coverage. Analysts would compare these accounts with filings, trade indicators, and producer or association data, then document a range or apply a comparable proxy where evidence remains incomplete.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 20% | APAC: 42% |
| Mid tier: 45% | Functional/Unit leaders: 35% | EMEA: 30% |
| Smaller Players: 25% | Managers: 45% | Americas: 28% |
Market-Sizing & Forecasting
A top-down annual revenue model estimates global sales of finished plastic packaging at producer or converter ex-factory values, then allocates value across packaging type, polymer material, end-user industry, sales route, and region using observed product mix, producer revenue, and shipment evidence. Historical inputs include resin price trends, packaging output and capacity, activity in food, beverage, healthcare and personal care markets, parcel volumes linked to e-commerce, and regulatory changes affecting material or format choice. Each indicator informs selling value, demand volume, or the likely mix of products. A multivariate regression can relate historical market revenue to these indicators and extend the relationships through 2032, with scenarios for changes in resin costs, end-market demand, and packaging rules. Segment shares are built from category revenue, shipment volumes and product mix, with the resulting categories reconciled to the market total. Interviews can challenge variable-level assumptions and explain changes in conversion, pass-through, and buyer preference. Selective bottom-up checks use supplier revenue roll-ups or sampled average selling price times estimated volume to test the top-down result. Where a supplier roll-up or shipment series is incomplete, analysts use a comparable-company indicator or estimate range and test it against the top-down total.
Data Validation & Update Cycle
Analysts triangulate producer sales and filings against independent trade, production, end-use, and regulatory signals, then check year-over-year movements, segment shares, regional totals, and forecast inputs for anomalies or unexplained variance. A second review traces each adjustment to its source and tests whether the evidence fits the market boundary, while a senior review resolves remaining differences before sign-off. Analysts re-contact respondents when answers conflict materially, a key input changes, or a missing segment could alter the estimate. The model is refreshed annually, updated between cycles after material events, and reviewed again in a fresh pre-delivery pass.
Mordor Intelligence's Plastic Packaging Market Size Compared Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The plastic packaging market measures annual spending on packaging products made primarily from plastic polymers and sold to protect, store, or transport goods.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Historical inputs include resin price trends, packaging output and capacity, activity in food, beverage, healthcare and personal care markets, parcel volumes linked to e-commerce, and regulatory changes affecting material or format choice.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 525.9 B (2027) | |
| Global Consultancy A | USD 416.5 B (2025) | At its 2025 base, this estimate is 20.8% below this report's 2027 value of USD 525.9 B, 2 years later. Its intervening-year revenue estimate remains below this report's comparison point, and its published growth path is slower, contributing directionally to the lower estimate. |
| Global Consultancy B | USD 413.4 B (2025) | At its 2025 base, this estimate is 21.4% below this report's 2027 value of USD 525.9 B, 2 years later. Its intervening-year revenue estimate remains below the comparison point, while its faster published growth path would narrow the gap. The earlier base year is the documented downward contributor. |
Mordor Intelligence's analysts triangulate producer sales and filings against independent trade, production, end-use, and regulatory signals, then check year-over-year movements, segment shares, regional totals, and forecast inputs for anomalies or unexplained variance.
Key Questions Answered in the Report
What is the plastic packaging market size and forecast growth?
The size is projected to rise from USD 509.4 billion in 2026 and USD 525.9 billion in 2027 to USD 623.4 billion by 2032, with a 3.46% CAGR between 2027 and 2032.
What is supporting demand for plastic packs?
Convenience foods and e-commerce shipments support demand. In 2026, FMI, the Food Industry Association, reported that 56% of US households mixed home preparation with foods prepared outside the home for dinner at least weekly.
Which plastic-packaging format holds the largest share?
Flexible packaging held 54.66% of the market in 2026 and is forecast to grow fastest at a 4.54% CAGR between 2027 and 2032.
Which companies are major plastic-packaging suppliers?
Mondi PLC, Huhtamaki Oyj, Amcor PLC, Sealed Air Corporation, and Sonoco Products Company are major suppliers.
What regulatory cost challenge affects plastic-packaging suppliers?
The United Kingdom taxes finished plastic packaging components with less than 30% recycled plastic when suitable for moving goods from manufacturer to end user or used only once by consumers, subject to reliefs and exemptions.
Which region leads the plastic-packaging industry?
Asia-Pacific held 42% of the market in 2026 and is forecast to grow at a 6.9% CAGR between 2027 and 2032, making it the largest and fastest-growing region.