
Organic Coconut Water Market Size and Share
Market Overview
| Study Period | 2022 - 2032 |
|---|---|
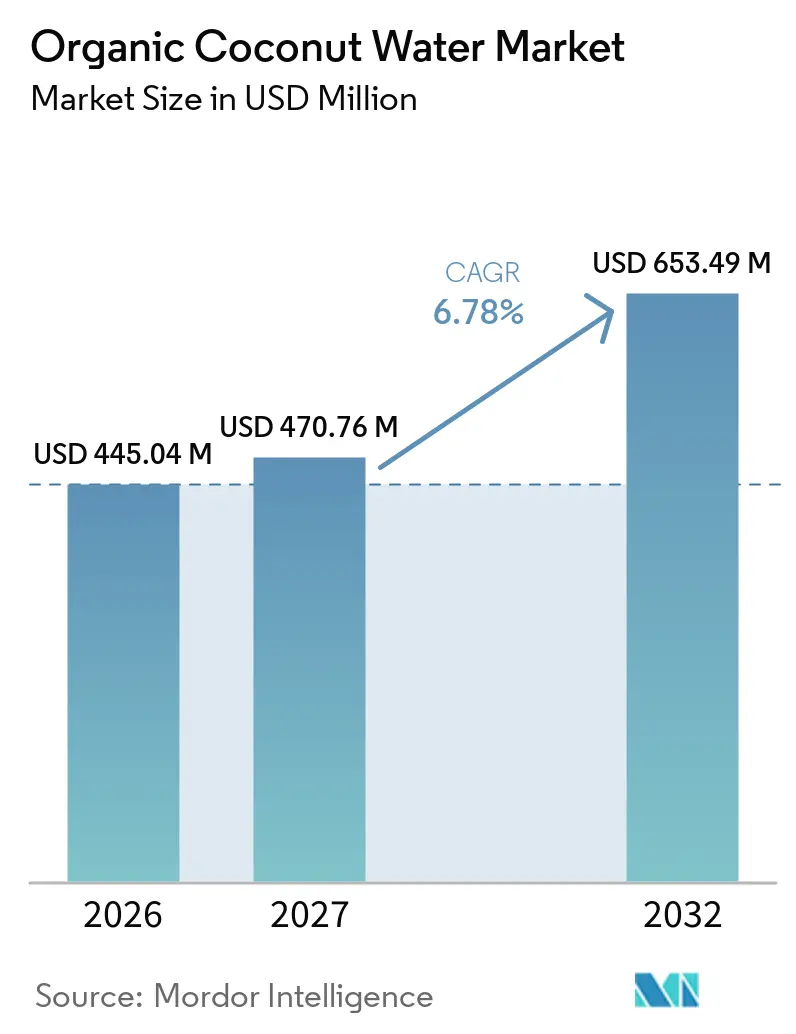
| Market Size (2027) | USD 470.76 Million |
| Market Size (2032) | USD 653.49 Million |
| Growth Rate (2027 - 2032) | 6.78 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Organic Coconut Water Market Analysis by Mordor Intelligence
The organic coconut water market size is expected to grow from USD 445.04 million in 2026 to USD 470.76 million in 2027 and is forecast to reach USD 653.49 million by 2032 at a 6.78% CAGR over 2027-2032. The market is supported by growing consumer interest in natural beverages, clean-label ingredients, and products aligned with health-conscious lifestyles. Demand is further encouraged by the premium positioning of organic beverages and increasing availability across retail and digital distribution channels. Regional growth varies according to consumer awareness, purchasing preferences, retail infrastructure, and proximity to coconut production. Product differentiation, packaging innovation, and convenient purchasing options continue to shape competitive strategies across the market.
Key Report Takeaways
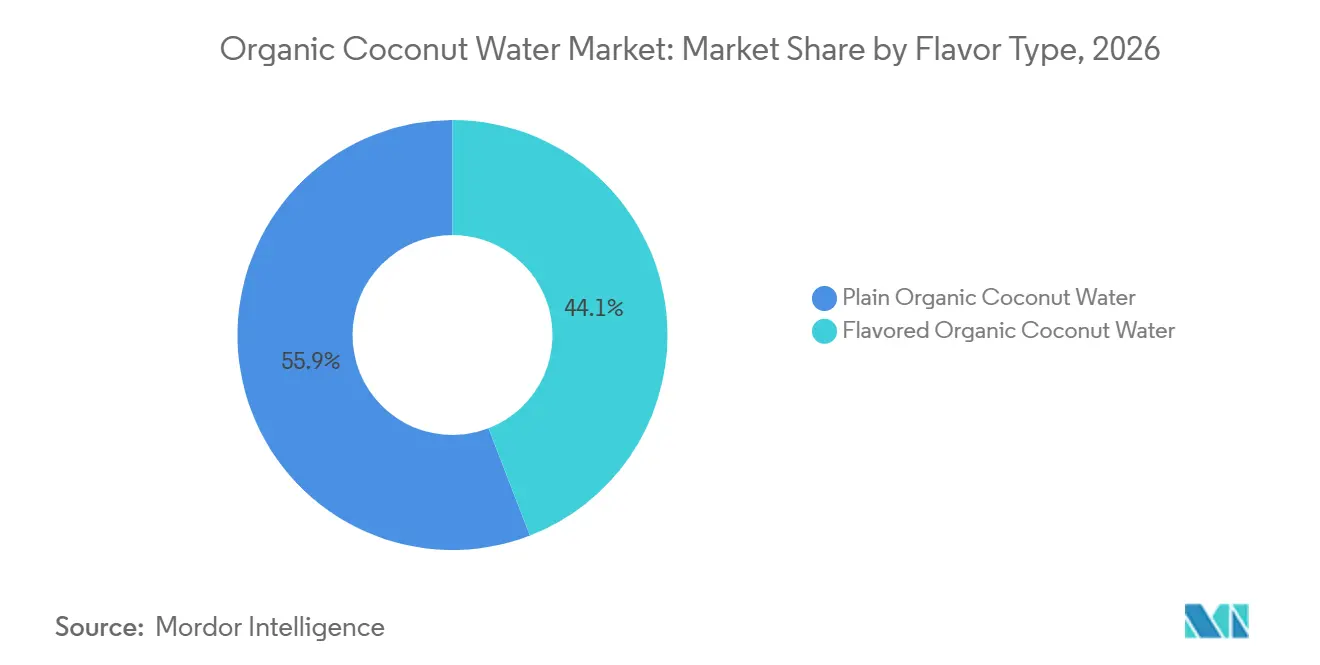
- By flavor type, plain organic coconut water held 55.86% of revenue in 2026, while flavored organic coconut water is projected to record an 8.24% CAGR from 2027 to 2032.
- By packaging type, Tetra Pack held 52.43% of revenue in 2026, while PET/glass bottles are projected to record an 8.08% CAGR from 2027 to 2032.
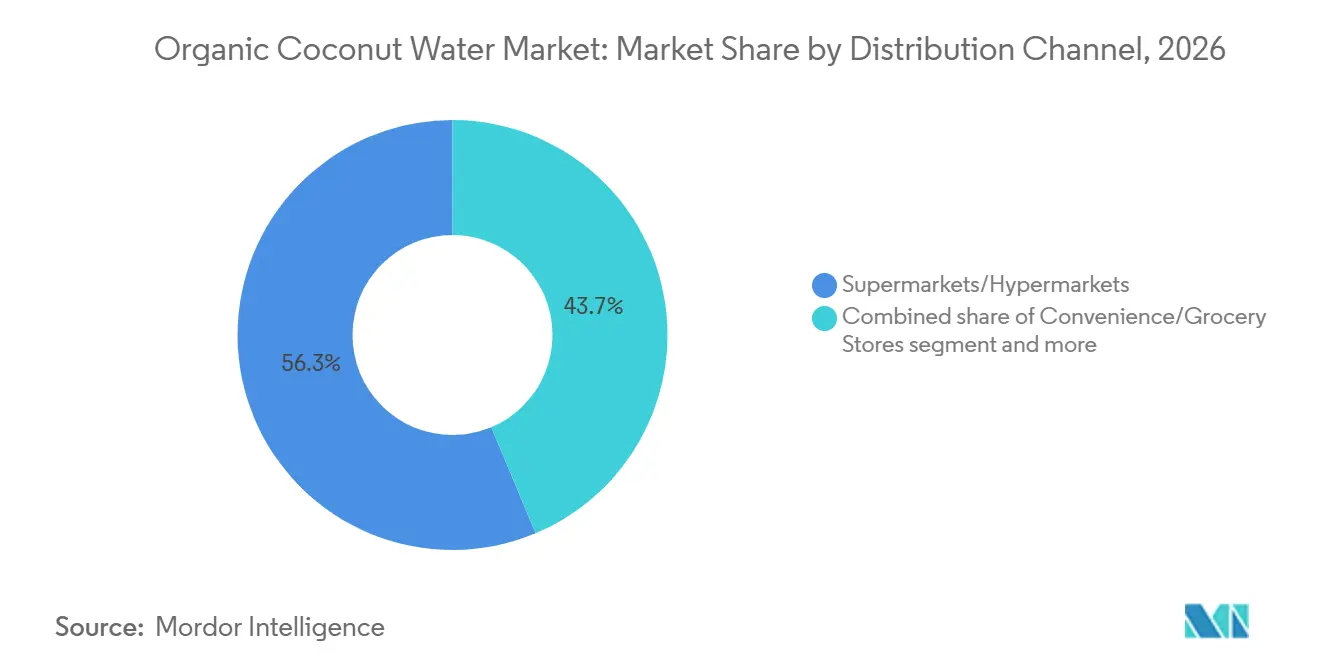
- By distribution channel, supermarkets/hypermarkets held 56.32% of revenue in 2026, while online retail stores are projected to record an 8.48% CAGR from 2027 to 2032.
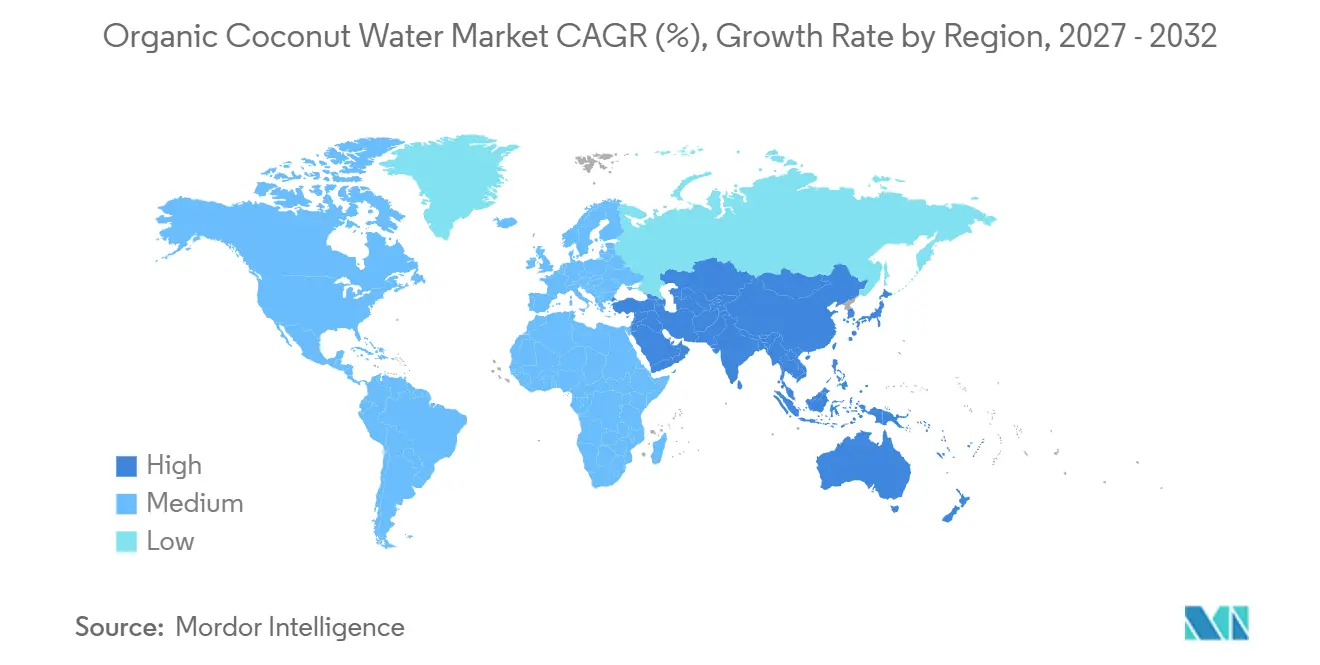
- By geography, North America held 31.09% of revenue in 2026, while Asia-Pacific is projected to record an 8.55% CAGR from 2027 to 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Organic Coconut Water Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Growing preference for clean-label and minimally processed beverages | +1.2% | North America and Europe core; spill-over to Asia-Pacific and Middle East and Africa | Short term (≤ 2 years) |
| Expanding demand for certified organic beverages | +1.1% | Global, with concentration in North America and Western Europe | Medium term (2–4 years) |
| Rising demand for natural hydration among active consumers | +1.0% | North America, Europe, Australia | Short term (≤ 2 years) |
| Increasing importance of organic certification and supply-chain transparency | +0.8% | Global; regulatory influence highest in Europe and North America | Medium term (2–4 years) |
| Product innovation through flavours and organic-compatible ingredients | +0.7% | North America, Asia-Pacific; emerging in Middle East and Africa | Medium term (2–4 years) |
| Expansion of convenient, shelf-stable organic coconut water products | +0.6% | Global; highest impact in South America and Asia-Pacific logistics corridors | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Growing Preference for Clean-Label and Minimally Processed Beverages
Growing consumer interest in ingredient transparency and simpler formulations is encouraging beverage manufacturers to offer products with recognizable ingredients and fewer unnecessary additives. The International Food Information Council's 2025 Food and Health Survey found that 41% of Americans looked for natural food production claims when making food and beverage purchasing decisions[1]. This preference is encouraging manufacturers to emphasize product composition, straightforward ingredient lists, and limited processing in beverage development and marketing. Organic coconut water aligns with this necessity through its simple product formulation, appealing to consumers who prioritize clarity about what their beverages contain. This shift is strengthening the importance of ingredient-focused product positioning across the beverage industry.
Expanding Demand for Certified Organic Beverages
Growing consumer interest in certified organic beverages is encouraging manufacturers to expand product portfolios that meet recognized organic production standards. According to the Organic Trade Association's 2026 organic market report, sales of organic products in the United States increased by 6.1% in 2025, reflecting continued demand for organically produced goods[2]. This broader shift is encouraging beverage manufacturers and retailers to strengthen their organic offerings and improve product availability. For organic coconut water producers, this creates opportunities to reach consumers who actively seek certified products when making beverage choices. Wider availability of certified organic options across retail channels may further support product visibility and consumer adoption.
Rising Demand for Natural Hydration Among Active Consumers
Growing participation in fitness activities is creating opportunities for beverages positioned around everyday hydration and active lifestyles. According to the Health and Fitness Association's 2026 United States Health and Fitness Consumer Report, 81 million Americans belonged to a gym, fitness studio, or other fitness facility in 2025, representing a 5.2% increase from the previous year[3]. This growing engagement with structured exercise supports demand for convenient beverages that fit into consumers' active routines. Organic coconut water can appeal to this audience as a plant-derived beverage option for everyday refreshment. Increasing attention to hydration before, during, and after physical activity may further strengthen interest in naturally positioned beverages among fitness-conscious consumers.
Increasing Importance of Organic Certification and Supply-Chain Transparency
Growing emphasis on product authenticity and responsible sourcing is increasing the importance of organic certification and supply-chain transparency in the organic coconut water market. Consumers and retailers increasingly expect clear information about ingredient origins, production methods, and compliance with recognized organic standards. These requirements encourage manufacturers to strengthen supplier verification, maintain traceable sourcing records, and implement consistent quality-control procedures throughout production and distribution. For organic coconut water producers, credible certification and transparent sourcing practices can help establish consumer confidence and distinguish products from conventional alternatives.
Restraints Impact Analysis of Organic Coconut Water Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Higher prices of organic coconut water | -1.1% | Global; most acute in South America, Middle East and Africa, and price-sensitive Asia-Pacific markets | Short term (≤ 2 years) |
| Competition from conventional coconut water and alternative hydration beverages | -0.9% | North America, Europe | Medium term (2–4 years) |
| Limited availability of certified organic coconut supplies | -0.8% | Global supply; compliance factors sharpest in Europe-facing export corridors | Medium term (2–4 years) |
| Costs and complexity of organic certification and regulatory compliance | -0.6% | Asia-Pacific producing markets, Latin American smallholders | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Higher Prices of Organic Coconut Water
Organic coconut water generally carries a price premium over conventional alternatives because of the additional costs associated with organic sourcing, certification, production controls, and supply-chain management. These higher costs can limit affordability among price-sensitive consumers, particularly in markets where conventional beverages are widely available at lower prices. Manufacturers may also face challenges in maintaining competitive retail pricing while meeting organic production requirements and preserving product quality. This price difference can restrict adoption among consumers who are interested in organic beverages but prioritize affordability in their purchasing decisions. Consequently, higher prices may constrain market penetration, particularly in price-sensitive consumer segments.
Competition from Conventional Coconut Water and Alternative Hydration Beverages
The organic coconut water market faces competition from conventional coconut water and a broad range of alternative hydration beverages that cater to similar consumer needs. Conventional products often benefit from lower prices, wider availability, and established distribution networks, making them accessible to a broader consumer base. Other beverages also compete through varied flavors, functional positioning, convenience, and established brand recognition. These alternatives can make it more difficult for organic coconut water brands to differentiate their offerings and justify premium pricing. As a result, market growth depends partly on communicating the distinct value of organic products while remaining competitive in an increasingly diverse beverage landscape.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Organic Coconut Water Market Segment Analysis
By Flavor Type:
Plain Formats Anchor Revenue, Flavoured Variants Attract IncrementallyPlain Organic Coconut Water accounted for the largest share of the market in 2026, at 55.86%, reflecting consumer preference for simple formulations and minimally processed beverages. Its single-ingredient composition aligns with demand for products that offer straightforward ingredient lists and clear product positioning. The segment also benefits from established consumer familiarity with unflavored coconut water as a refreshing beverage. Manufacturers can appeal to health-conscious consumers by emphasizing the product's natural origin and organic status. These factors support the continued prominence of plain organic coconut water across the market.
Flavored Organic Coconut Water is projected to record the fastest growth, at a compound annual growth rate of 8.24% over 2027–2032, as manufacturers broaden product appeal through flavor innovation. Tropical fruit and other flavor combinations offer consumers greater variety while retaining coconut water as the product base. This approach can attract buyers seeking alternatives to conventional flavored waters and sports beverages. Product launches featuring distinctive flavor profiles also provide opportunities for brands to differentiate their offerings in a competitive beverage landscape. Continued innovation and expanding consumer interest in flavored natural beverages are expected to support segment growth.
By Packaging Type:
Tetra Pack Holds Structural Advantages While PET/Glass PremiumisesTetra Pak accounted for the largest share of the market in 2026, at 52.43%, reflecting the advantages of aseptic packaging for storage, transportation, and distribution. Its ability to preserve products without continuous refrigeration supports distribution across markets where cold-chain infrastructure is limited. The format also enables manufacturers to supply organic coconut water across geographically dispersed export markets while maintaining product stability throughout transportation. These logistical benefits make carton packaging suitable for producers seeking to expand international distribution and reach diverse consumer markets. Its established role in coconut water supply chains and compatibility with large-scale processing operations support the segment's continued market prominence.
PET and glass bottles are projected to record the fastest growth, at a compound annual growth rate of 8.08% over 2027–2032, supported by premium product positioning and demand for packaging associated with freshness. Refrigerated bottle formats can help brands differentiate products through quality-focused positioning and product attributes. These formats also provide opportunities to appeal to consumers seeking premium alternatives to conventional beverage packaging. Meanwhile, aluminium cans and pouches offer additional options for manufacturers targeting convenience and recyclable packaging preferences. Continued packaging innovation and diversification across product tiers are expected to support growth in alternative formats, particularly as brands seek to distinguish their products through packaging choices.
By Distribution Channel:
Supermarkets Hold Value Share as Online Stores Accelerate FastSupermarkets and hypermarkets accounted for the largest share of the market in 2026, at 56.32%, reflecting their importance as regular purchasing destinations for household consumers. These outlets offer broad product assortments and allow organic coconut water to reach shoppers alongside other natural and wellness-oriented beverages. Dedicated beverage sections and established retail distribution networks also support product visibility and repeat purchases. Retailers introducing certified organic private-label products further demonstrate the channel's role in expanding category availability while intensifying competition for branded manufacturers. These factors reinforce the importance of supermarkets and hypermarkets in product distribution and consumer access.
Online retail stores are projected to record the fastest growth, at a compound annual growth rate of 8.48% over 2027–2032, supported by the convenience of digital purchasing and opportunities to compare products across brands. Online platforms allow consumers to explore organic beverage options and access products beyond the assortment available at nearby physical stores. Meanwhile, convenience and grocery stores serve consumers seeking quick purchases and beverages for consumption on the go. Manufacturers are also expanding their presence across these outlets to reach additional purchasing occasions beyond routine household shopping. Continued development of digital retail and broader distribution across smaller-format stores is expected to support growth across these channels.

Geography Analysis
North America Organic Coconut Water Market
North America accounted for the largest share of the organic coconut water market in 2026, at 31.09%, supported by established demand for premium beverages, developed retail infrastructure, and consumer familiarity with organic products. The United States serves as the region's primary demand centre, with Canada and Mexico providing additional opportunities for market expansion. Well-established supermarket networks, specialist natural food retailers, and online platforms support product availability and consumer access. The region also benefits from strong brand presence and growing product differentiation across organic beverage portfolios. However, sourcing costs, import conditions, and competition from conventional coconut water may influence pricing and supplier selection across the region.
APAC Organic Coconut Water Market
Asia-Pacific is projected to record the fastest growth, at a compound annual growth rate of 8.55% over 2027–2032, supported by its dual role as a major coconut-producing region and an expanding consumer market. Countries such as Thailand, Indonesia, the Philippines, Vietnam, and Sri Lanka provide access to raw materials and established coconut-processing industries, creating opportunities to develop organic coconut water production and exports. Rising interest in packaged beverages, expanding modern retail networks, and the growth of online grocery platforms are supporting greater consumer access across regional markets. China and India offer additional opportunities as packaged beverage consumption develops and distribution channels broaden. Nevertheless, the availability of certified organic raw materials and compliance with export-market requirements will influence the pace of regional expansion.
EMEA and South America Organic Coconut Water Market
Europe, South America, and the Middle East and Africa represent additional opportunities for organic coconut water producers, with growth shaped by retail development, consumer preferences, and sourcing capabilities. European markets, including Germany, the United Kingdom, France, and the Netherlands, benefit from established organic retail channels and consumer familiarity with certified products, although regulatory compliance can increase requirements for imported goods. South America, particularly Brazil, benefits from coconut production and processing capabilities that support the broader coconut beverage industry, while certified organic supply offers scope for further development. In the Middle East and Africa, demand opportunities are supported by premium retail channels and increasing availability of imported natural beverages, particularly in Gulf markets and South Africa. Across these regions, market development will depend on distribution expansion, competitive pricing, and reliable access to certified organic products.
Competitive Landscape
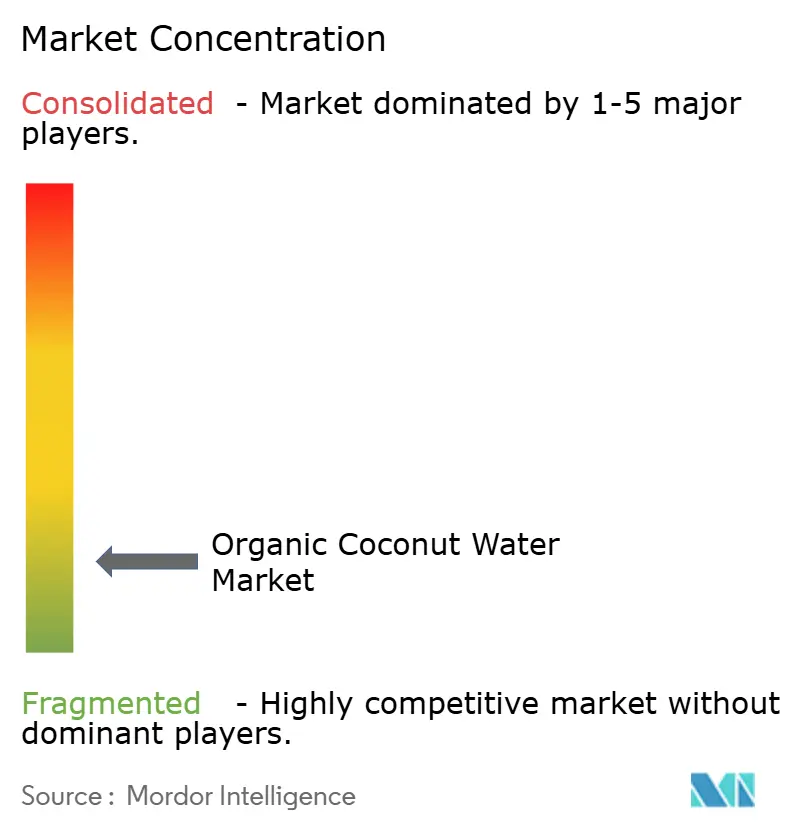
The organic coconut water market is fragmented, with competition distributed across established beverage companies and specialised organic coconut water producers. The five leading players are The Vita Coco Company, Inc., Harmless Harvest, Inc., C2O Coconut Water, PepsiCo, Inc., and Wichy Plantation Company (Pvt) Ltd. Competition is shaped by brand recognition, product positioning, distribution reach, and access to coconut sourcing networks. While larger beverage companies benefit from established distribution capabilities, specialised producers focus on organic credentials and coconut-based product offerings.
The Vita Coco Company, Inc. has an established presence in the broader coconut water category, supported by international distribution and a diversified product portfolio. Harmless Harvest focuses on organic coconut water, while PepsiCo participates through its wider beverage portfolio. C2O Coconut Water adds a dedicated coconut water brand to the competitive landscape. Wichy Plantation Company (Pvt) Ltd differentiates its offering through organic coconut water sourced from Sri Lanka, alongside flavoured varieties such as hibiscus, soursop and lime, and passion fruit. These companies illustrate the range of brand, product, and sourcing strategies adopted by the leading competitors.
Other market participants and emerging brands contribute to competition through regional specialisation, product innovation, and alternative positioning. Potential areas of differentiation include new flavour combinations, convenient packaging formats, and organic formulations tailored to specific consumer preferences. Products combining organic coconut water with botanical ingredients or other functional components may also provide opportunities for portfolio development. However, establishing a stronger market presence depends on securing reliable supplies of certified organic coconuts, maintaining consistent product quality, and expanding distribution while remaining competitive on price.
Organic Coconut Water Industry Leaders
-
The Vita Coco Company, Inc.
-
Harmless Harvest, Inc.
-
C2O Coconut Water
-
PepsiCo, Inc.
-
Wichy Plantation Company (Pvt) Ltd
- *Disclaimer: Major Players sorted in no particular order
Organic Coconut Water Market Companies Covered in this Report
- PepsiCo, Inc.
- The Vita Coco Company, Inc.
- Harmless Harvest, Inc.
- GOYA Foods, Inc.
- Taste Nirvana International, Inc.
- Oka Products LLC
- C2O Coconut Water
- GraceKennedy Limited
- Raw C
- Bai Brands, LLC
- Thai Coconut Public Company Limited
- Thai Agri Foods Public Company Limited
- Wichy Plantation Company (Pvt) Ltd
- Axelum Resources Corp.
- Celebes Coconut Corporation
- Sambu Group
- Silvermill Group
- Nara Cocoland
- Ducoco Produtos Alimentícios S.A.
- Nam Viet Foods and Beverage JSC
Recent Industry Developments in Organic Coconut Water Market
- September 2026: Real Coco launched Organic Pure Coconut Water in a 480-millilitre can. The new format expands the brand's packaging options for its single-ingredient, United States Department of Agriculture-certified organic coconut water. Sourced from Vietnam's Mekong Delta and bottled at source, the product contains no added sugar and is not made from concentrate. The launch strengthens the brand's offering for consumers seeking convenient organic beverages.
- June 2026: Tom Brady and Gopuff launched Good Nut organic coconut water. The new brand was introduced as a premium organic coconut water range made using coconuts sourced from Vietnam and launched exclusively through Gopuff. The portfolio includes chocolate and sparkling coconut water, with the chocolate variant positioned as a certified organic option made with three ingredients and no added sugar. The launch introduces new flavour and formulation options to the organic coconut water category.
- March 2026: Real Coco expanded its retail distribution through a nationwide launch at ALDI in the United States. The brand introduced its Organic Pure Coconut Water and Organic Pressed Coconut Water across approximately 2,700 ALDI stores nationwide. The expansion increases access to its organic coconut beverage portfolio through a major grocery retail network. The products are sourced from family farms in Vietnam's Mekong Delta and are bottled at source without added sugars or concentrates.
- November 2025: CocoGen expanded into Australia following its launch in Singapore. The brand entered Australian retail after launching in Singapore, where it became available at more than 110 retail locations. Its range includes organic coconut water products formulated with added electrolytes, magnesium, or collagen. The Australian launch extends the brand's geographic reach and introduces its functional organic beverage positioning to another market.
Global Organic Coconut Water Market Report Scope
The organic coconut water market covers the production, packaging, and distribution of coconut water derived from organically grown coconuts and marketed in accordance with applicable organic standards. The market is segmented by flavor type into plain organic coconut water and flavored organic coconut water, by packaging type into polyethylene terephthalate and glass bottles, tetra pak, and others, by distribution channel into supermarkets and hypermarkets, convenience and grocery stores, and other channels, and by geography into North America, Europe, Asia-Pacific, South America, and the Middle East and Africa. The market forecasts are provided in terms of value in USD.
Segmentation Overview
| Plain Organic Coconut Water |
| Flavored Organic Coconut Water |
| Pet/Glass Bottles |
| Tetra Pack |
| Others |
| Supermarkets/Hypermarkets |
| Convenience/Grocery Stores |
| Online Retail Stores |
| Other Distribution Channels |
| North America | United States |
| Canada | |
| Mexico | |
| Rest of North America | |
| Europe | Germany |
| United Kingdom | |
| Italy | |
| France | |
| Spain | |
| Netherlands | |
| Rest of Europe | |
| Asia-Pacific | China |
| India | |
| Japan | |
| Australia | |
| Indonesia | |
| Rest of Asia-Pacific | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Middle East and Africa | South Africa |
| Saudi Arabia | |
| United Arab Emirates | |
| Rest of Middle East and Africa |
| By Flavor Type | Plain Organic Coconut Water | |
| Flavored Organic Coconut Water | ||
| By Packaging Type | Pet/Glass Bottles | |
| Tetra Pack | ||
| Others | ||
| By Distribution Channel | Supermarkets/Hypermarkets | |
| Convenience/Grocery Stores | ||
| Online Retail Stores | ||
| Other Distribution Channels | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| Rest of North America | ||
| Europe | Germany | |
| United Kingdom | ||
| Italy | ||
| France | ||
| Spain | ||
| Netherlands | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| India | ||
| Japan | ||
| Australia | ||
| Indonesia | ||
| Rest of Asia-Pacific | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Middle East and Africa | South Africa | |
| Saudi Arabia | ||
| United Arab Emirates | ||
| Rest of Middle East and Africa | ||
Key Questions Answered in the Report
What is the forecast for organic coconut water through 2032?
The forecast places the market at USD 653.49 million by 2032, following a 6.78% CAGR from 2027 to 2032.
Which flavor type leads sales?
Plain organic coconut water led overall sales with 55.86% of revenue in 2026.
Which packaging format has the largest share?
Tetra pack held a major share of 52.43% in 2026.
Which sales channel is growing fastest?
Online retail stores are projected to grow at an 8.48% CAGR from 2027 to 2032.