
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
| Base Year Market Size (2026) | USD 241.25 Million |
| Market Size (2027) | USD 257.19 Million |
| Market Size (2032) | USD 354.20 Million |
| Growth Rate (2027 - 2032) | 6.61 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Oman Diabetes Drugs Market Analysis by Mordor Intelligence
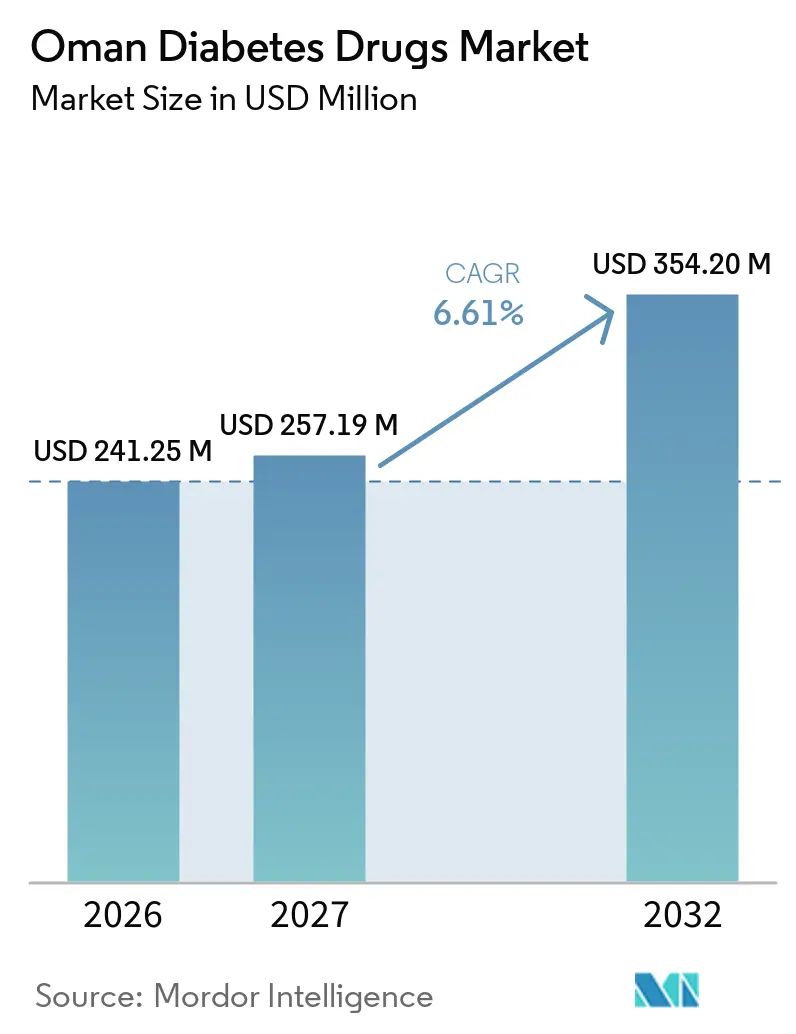
The Oman Diabetes Drugs Market size is expected to increase from USD 241.25 million in 2026 to USD 257.19 million in 2027 and reach USD 354.20 million by 2032, growing at a CAGR of 6.61% over 2027-2032.
Diabetic drugs are medicines developed to stabilize and control blood glucose levels amongst people with diabetes. Diabetic drugs are commonly used to manage diabetes. Diabetic drugs have been potential candidates for treating diabetic patients affected by SARS-CoV-2 infection during the COVID-19 pandemic. Although the current numbers show that the existence of diabetes is comparatively lesser in Oman, the growth rate of the diabetic population is projected to be higher in the country.
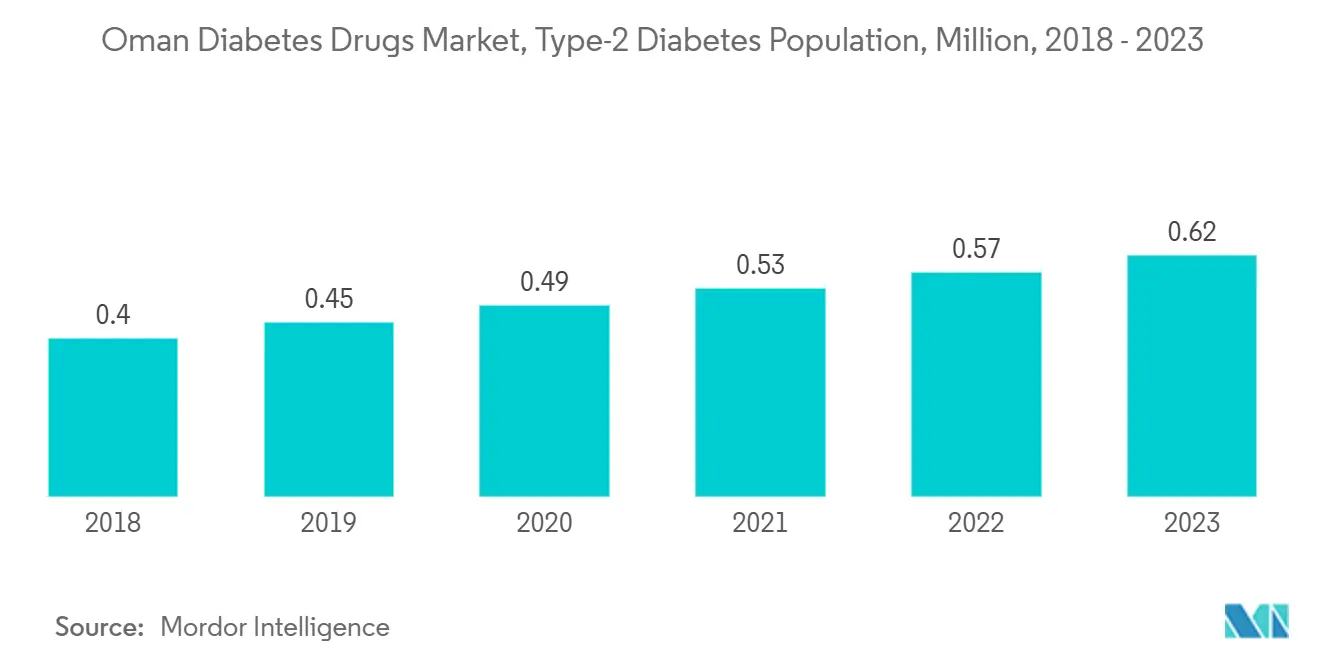
According to Mordor Intelligence, the diabetic population in Oman is expected to reach 0.84 million by 2027. Diabetes is associated with many health complications. Patients with diabetes require many corrections throughout the day to maintain nominal blood glucose levels, such as administering additional insulin or ingesting additional carbohydrates by monitoring their blood glucose levels. Diabetes poses an emerging healthcare burden across the country and is one of the leading causes of premature death, morbidity, and loss of economic growth.
Oman, Ministry of Health, recently participated in the virtual launch of the WHO Global Diabetes Compact, organized jointly by the World Health Organization and the government of Canada aimed at raising awareness level about diabetes as a global disease, in addition to expanding prevention and treatment as part of primary health care and universal health coverage.
Therefore, owing to the aforementioned factors the studied market is anticipated to witness growth over the analysis period.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
The oral anti-diabetic drugs segment holds the highest market share in the Oman Diabetes Drugs Market in the current year
The oral anti-diabetic drugs segment holds the highest market share of about 88.8% in the Oman Diabetes Drugs Market in the current year.
Oral Anti-Diabetic Drugs are available internationally and are recommended for use when escalation of treatment for type 2 diabetes is required, along with lifestyle management. Oral agents are typically the first medications used in treating type 2 diabetes due to their wide range of efficacy, safety, and mechanisms of action.
In September 2024, the Oman Ministry of Health published updated medication guidelines for diabetic patients and a national diabetes care guide covering treatment approaches, medication use, and disease management, reflecting the country's continued focus on improving diabetes care and supporting the adoption of antidiabetic therapies across healthcare settings.
According to Oman Diabetes Association, diabetes is a costly chronic illness that needs control of blood sugar levels. It imposes a challenge for low-income and social security patients. Thus, an initiative is designed to reduce the burden on these targeted groups, consequently promoting sugar control. Moreover, the number of new cases among children is about 60 annually. According to local studies and reports on good diabetes control, the rate in adult patients ranges from 32-35%, whereas it reaches 10-12% among children and adolescents. The Government is working on increasing awareness of diabetes and access to medicines to improve good diabetes control.
Owing to the rising rate of obesity, growing genetic factors for type-2 diabetes, the increasing prevalence, and the factors above, the market will likely continue to grow.

Metformin is expected to dominate the Oman Diabetes Drugs Market over the forecast period
Metformin is expected to dominate the Oman Diabetes Drugs Market and register a CAGR of around 6.91% over the forecast period.
Demand for metformin in Oman is being reinforced by the growing number of patients requiring long-term glycemic management and the drug's continued presence across different stages of diabetes treatment. Unlike several newer therapies that are primarily reserved for specific patient groups, metformin remains relevant for a broad diabetic population, enabling higher prescription volumes and recurring usage throughout the treatment journey, thereby supporting segment growth.
Diabetes reduces lifespan, and people with the disease are likely to experience blindness and be hospitalized for amputations, kidney failure, heart attacks, strokes, and heart failure. Metformin is the first-line choice for the management of hyperglycemia in T2DM. Besides being an important glucose-lowering agent, metformin also includes significant anti-inflammatory properties. Other options must be considered when metformin is contraindicated or not tolerated or when treatment goals are not achieved after three months of use at the maximum tolerated dose. Dipeptidyl peptidase-4 inhibitors, sodium-glucose cotransporter-2 inhibitors, and glucagon-like peptide-1 agonists are generally used to supplement treatment with metformin.
The Ministry of Health, Oman is strategically planning to contain the growing burden of diabetes and invest in all means to control it, stating, 'Our work needs to ensure equitable and affordable access to treatment, and it is essential that we advocate for investments in diabetes education and prevention programs.' Risk factors such as insufficient physical activity and the consumption of unhealthy diets are contributing to the development and progression of the disease.
Owing to the factors above, the market is expected to grow during the forecast period.
Competitive Landscape
Market Concentration
The Oman Diabetes Drugs Market is consolidated, with major manufacturers, namely Eli Lilly, Sanofi, Novo Nordisk, AstraZeneca, and other generic players, holding a presence in the region. A major share of the market is held by manufacturers concomitant with strategy-based M&A operations and constantly entering the market to generate new revenue streams and boost existing ones.
Oman Diabetes Drugs Industry Leaders
-
AstraZeneca
-
Boehringer Ingelheim
-
Novo Nordisk A/S
-
Sanofi Aventis
-
Eli Lilly and Company
- *Disclaimer: Major Players sorted in no particular order
Oman Diabetes Drugs Market Companies Covered in this Report
- Novo Nordisk
- Takeda Pharmaceuticals
- Pfizer
- Eli Lilly and Company
- Janssen
- Astellas Pharma
- Boehringer Ingelheim
- Merck
- AstraZeneca
- Bristol-Myers Squibb
- Julphar
- Novartis
- Sanofi
Recent Industry Developments in Oman Diabetes Drugs Market
- November 2023: Novo Nordisk's initiation of a Phase III comparative trial for their pipeline drug CagriSema against the recently approved Zepbound suggests the potential for direct competition between the two drugs upon Novo Nordisk's candidate entering the market.
- June 2023: The United Arab Emirates Ministry of Health and Prevention (MoHAP) announced initiatives to strengthen local pharmaceutical manufacturing and enhance the country's healthcare self-sufficiency through strategic collaborations with domestic and international healthcare companies. These efforts are aimed at expanding production capabilities, improving access to essential medicines, including diabetes drugs, and supporting innovation in the healthcare sector.
Oman Diabetes Drugs Market Report Scope
Diabetes Drugs are used to manage diabetes mellitus by lowering the glucose level in the blood. The Oman Diabetes Drugs Market is segmented into drugs. The report offers the value (in USD) and volume (in Units) for the above segments.
Segmentation Overview
Insulins
| Basal or Long Acting Insulins | Lantus (Insulin Glargine) |
| Levemir (Insulin Detemir) | |
| Toujeo (Insulin Glargine) | |
| Tresiba (Insulin Degludec) | |
| Basaglar (Insulin Glargine) | |
| Bolus or Fast Acting Insulins | NovoRapid/Novolog (Insulin Aspart) |
| Humalog (Insulin Lispro) | |
| Apidra (Insulin Glulisine) | |
| Traditional Human Insulins | Novolin/Actrapid/Insulatard |
| Humulin | |
| Insuman | |
| Biosimilar Insulins | Insulin Glargine Biosimilars |
| Human Insulin Biosimilars |
Oral Anti-diabetic drugs
| Biguanides | Metformin |
| Alpha-Glucosidase Inhibitors | Alpha-Glucosidase Inhibitors |
| Dopamine D2 receptor agonist | Bromocriptin |
| SGLT-2 inhibitors | Invokana (Canagliflozin) |
| Jardiance (Empagliflozin) | |
| Farxiga/Forxiga (Dapagliflozin) | |
| Suglat (Ipragliflozin) | |
| DPP-4 inhibitors | Onglyza (Saxagliptin) |
| Tradjenta (Linagliptin) | |
| Vipidia/Nesina(Alogliptin) | |
| Galvus (Vildagliptin) | |
| Sulfonylureas | Sulfonylureas |
| Meglitinides | Meglitinides |
Non-Insulin Injectable drugs
| GLP-1 receptor agonists | Victoza (Liraglutide) |
| Byetta (Exenatide) | |
| Bydureon (Exenatide) | |
| Trulicity (Dulaglutide) | |
| Lyxumia (Lixisenatide) | |
| Amylin Analogue | Symlin (Pramlintide) |
Combination drugs
| Insulin combinations | NovoMix (Biphasic Insulin Aspart) |
| Ryzodeg (Insulin Degludec and Insulin Aspart) | |
| Xultophy (Insulin Degludec and Liraglutide) | |
| Oral Combinations | Janumet (Sitagliptin and Metformin) |
| Insulins | Basal or Long Acting Insulins | Lantus (Insulin Glargine) |
| Levemir (Insulin Detemir) | ||
| Toujeo (Insulin Glargine) | ||
| Tresiba (Insulin Degludec) | ||
| Basaglar (Insulin Glargine) | ||
| Bolus or Fast Acting Insulins | NovoRapid/Novolog (Insulin Aspart) | |
| Humalog (Insulin Lispro) | ||
| Apidra (Insulin Glulisine) | ||
| Traditional Human Insulins | Novolin/Actrapid/Insulatard | |
| Humulin | ||
| Insuman | ||
| Biosimilar Insulins | Insulin Glargine Biosimilars | |
| Human Insulin Biosimilars | ||
| Oral Anti-diabetic drugs | Biguanides | Metformin |
| Alpha-Glucosidase Inhibitors | Alpha-Glucosidase Inhibitors | |
| Dopamine D2 receptor agonist | Bromocriptin | |
| SGLT-2 inhibitors | Invokana (Canagliflozin) | |
| Jardiance (Empagliflozin) | ||
| Farxiga/Forxiga (Dapagliflozin) | ||
| Suglat (Ipragliflozin) | ||
| DPP-4 inhibitors | Onglyza (Saxagliptin) | |
| Tradjenta (Linagliptin) | ||
| Vipidia/Nesina(Alogliptin) | ||
| Galvus (Vildagliptin) | ||
| Sulfonylureas | Sulfonylureas | |
| Meglitinides | Meglitinides | |
| Non-Insulin Injectable drugs | GLP-1 receptor agonists | Victoza (Liraglutide) |
| Byetta (Exenatide) | ||
| Bydureon (Exenatide) | ||
| Trulicity (Dulaglutide) | ||
| Lyxumia (Lixisenatide) | ||
| Amylin Analogue | Symlin (Pramlintide) | |
| Combination drugs | Insulin combinations | NovoMix (Biphasic Insulin Aspart) |
| Ryzodeg (Insulin Degludec and Insulin Aspart) | ||
| Xultophy (Insulin Degludec and Liraglutide) | ||
| Oral Combinations | Janumet (Sitagliptin and Metformin) | |
Key Questions Answered in the Report
How big is the Oman Diabetes Drugs Market?
The Oman Diabetes Drugs Market size is expected to reach USD 241.25 million in 2026 and grow at a CAGR of 6.61% to reach USD 354.20 million by 2032.
What is the Oman Diabetes Drugs Market size in 2027?
In 2027, the Oman Diabetes Drugs Market size is expected to reach USD 257.19 million.
Who are the key players in Oman Diabetes Drugs Market?
AstraZeneca, Boehringer Ingelheim, Novo Nordisk A/S, Sanofi Aventis and Eli Lilly and Company are the major companies operating in the Oman Diabetes Drugs Market.
What years does this Oman Diabetes Drugs Market cover, and what was the market size in 2025?
In 2025, the Oman Diabetes Drugs Market size was estimated at USD 226.29 million. The report covers the Oman Diabetes Drugs Market historical market size for years: 2021, 2022, 2023, 2024, 2025, and 2026. The report also forecasts the Oman Diabetes Drugs Market size for years: 2027, 2028, 2029, 2030, 2031, and 2032.