
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Market Size (2026) | USD 111.67 Billion |
| Market Size (2031) | USD 141.43 Billion |
| Growth Rate (2026 - 2031) | 4.84 % |
| Fastest Growing Market | Middle East and Africa |
| Largest Market | Asia-Pacific |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Mining Equipment Market Analysis by Mordor Intelligence
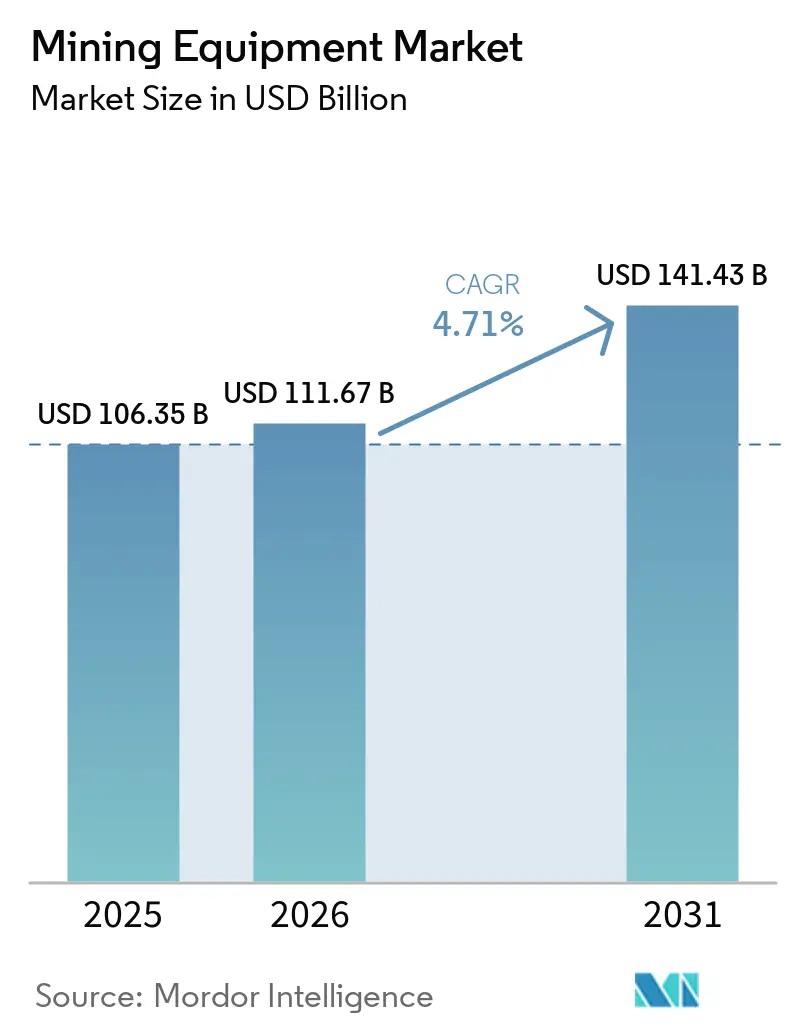
The Mining Equipment Market size was valued at USD 106.35 billion in 2025 and is expected to reach USD 111.67 billion in 2026 and is projected to reach USD 141.43 billion by 2031, growing at a CAGR of 4.84% over 2026-2031. Greenfield approvals, electrification requirements, and supply security policies are moving equipment procurement beyond a simple response to commodity volumes. Mine owners are increasingly selecting fleets based on energy use, automation readiness, and service support. This favors suppliers that can combine equipment, digital systems, and long-term maintenance coverage. Demand is strongest where copper, lithium, cobalt, nickel, and iron ore projects are moving from planning into construction. The mining equipment market is therefore being shaped by technology specifications as well as by mine output.
Key Report Takeaways
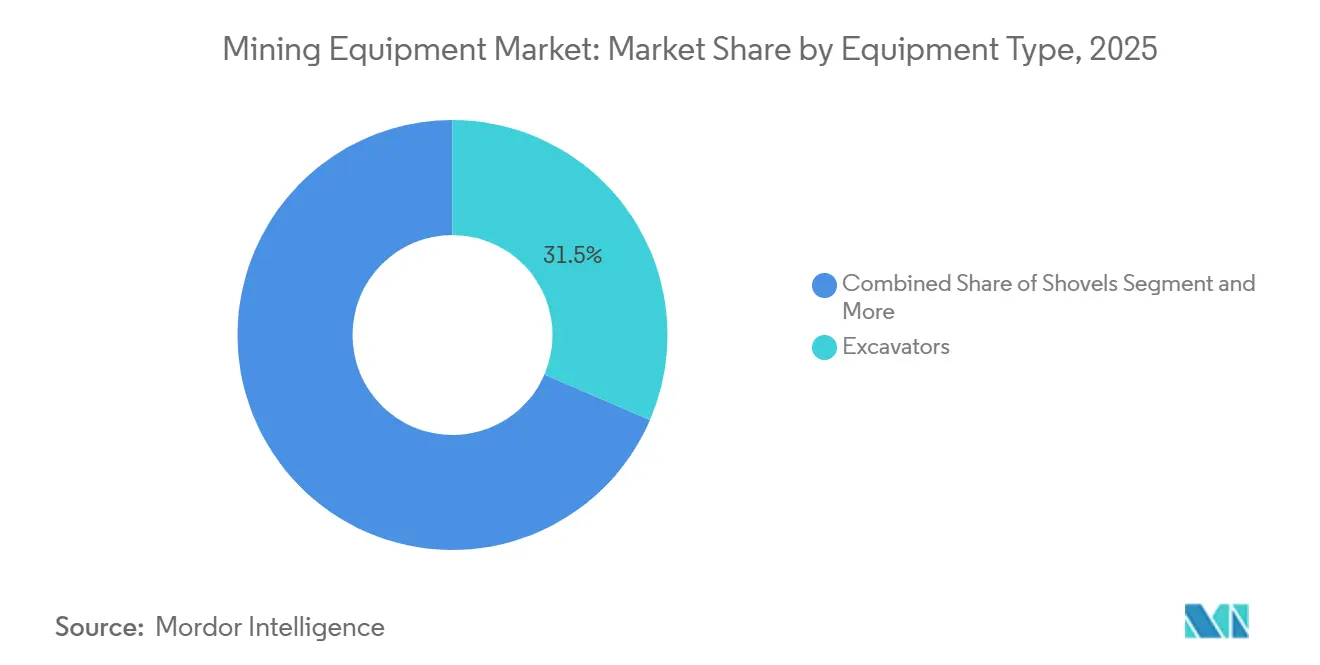
- By equipment type, excavators held 31.46% of the mining equipment market share in 2025, while shovels are forecast to grow at a 5.62% CAGR through 2031.
- By automation level, manual equipment held 69.11% of the mining equipment market share in 2025, while fully autonomous equipment is forecast to grow at a 12.51% CAGR through 2031.
- By powertrain type, internal combustion engine vehicles held 89.68% of the mining equipment market share in 2025, while battery-electric vehicles are forecast to grow at a 13.71% CAGR through 2031.
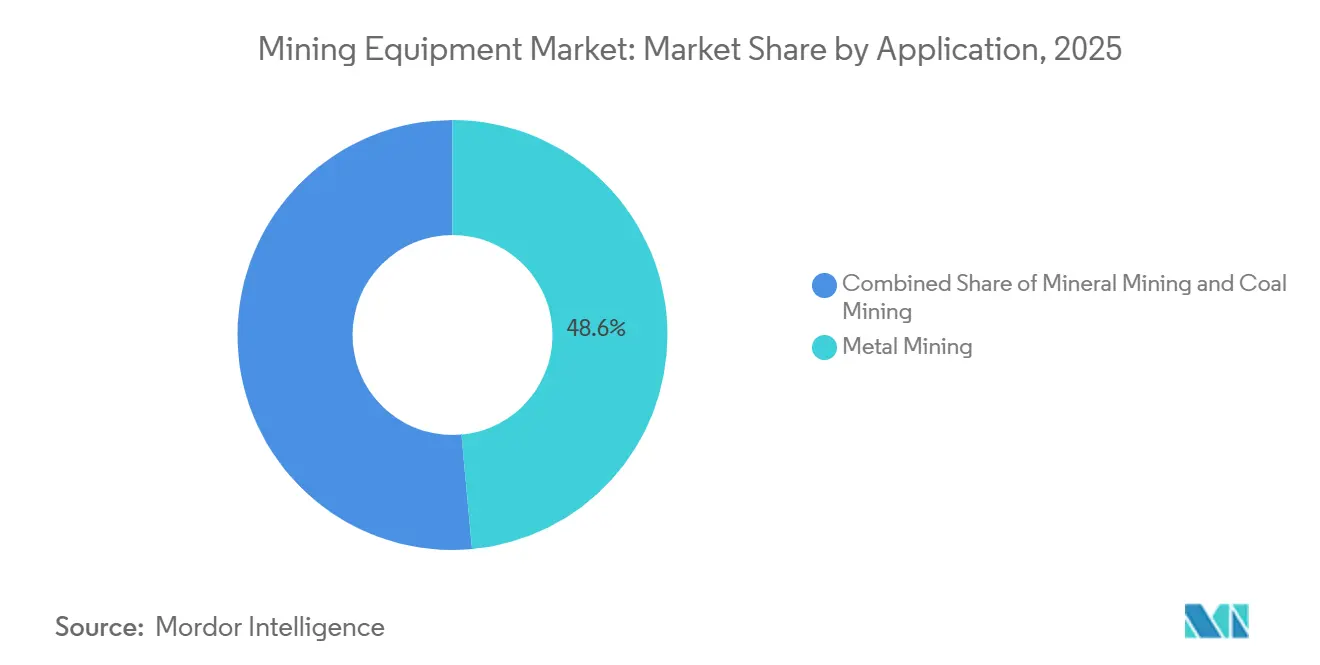
- By application, metal mining accounted for 48.55% of the mining equipment market share in 2025 and is projected to grow at a CAGR of 5.29% through 2031.
- By mining type, surface mining held 61.75% of the mining equipment market share in 2025, while underground mining is forecast to grow at a 5.68% CAGR through 2031.
- By geography, Asia-Pacific held 61.17% of the mining equipment market share in 2025, while the Middle East and Africa are forecast to grow at a 5.88% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Mining Equipment Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Surging demand for critical minerals for battery supply chains (Asia and the United States) | +1.2% | Global, concentrated in Asia-Pacific and North America | Medium term (2–4 years) |
| Accelerated mine electrification mandates in Canada, Chile, and Australia | +0.8% | North America, South America, Asia-Pacific | Medium term (2–4 years) |
| Sustained capex up-cycle in African copper, cobalt, and lithium projects | +0.7% | Middle East and Africa, spill-over to South America | Long term (≥ 4 years) |
| Recovery of greenfield iron-ore projects in Western Australia and Brazil | +0.5% | Asia-Pacific, South America | Long term (≥ 4 years) |
| Emissions-linked financing lowering cost of capital for electric fleets | +0.4% | North America, Europe, Australia | Medium term (2–4 years) |
| Shift to predictive maintenance driving aftermarket parts pull-through | +0.3% | Global | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Surging Demand for Critical Minerals for Battery Supply Chains
Battery supply policies are supporting mine development in ways that short-term commodity pricing does not fully show. The International Energy Agency identified risks of future copper and lithium supply gaps despite the announced project pipeline, underscoring the need for continued investment in new mine capacity. [1] The U.S. Department of Energy committed USD 1 billion in 2025 to mining, processing, and recycling technologies, and USD 500 million to commercial-scale battery-mineral processing. [2] These programs create a direct route from industrial policy to orders for loading, hauling, drilling, and processing equipment. Supply diversification efforts also favor projects in newer mining areas with less developed infrastructure. Such projects commonly require more equipment and support assets per ton of capacity, which broadens opportunities for the mining equipment market.
Accelerated Mine Electrification Mandates in Canada, Chile, and Australia
Government funding and mine-level commitments are turning fleet electrification into a replacement cycle rather than a voluntary pilot program. Canada supported critical mineral production and associated low-carbon mine investment in 2025, while Glencore’s Onaping Depth development is designed as an all-electric underground mine. Codelco completed a 680-kilometer pilot of an all-electric SANY truck on a strategic northern Chile route in April 2026. [3] Australia also funded BluVein’s dynamic charging work for heavy mining trucks in 2025. Underground battery-electric fleets can reduce ventilation and cooling demand, which improves the ownership case where power infrastructure is sufficient. These conditions support the rapid expansion projected for battery-electric vehicles within the mining equipment market.
Sustained Capex Up-Cycle in African Copper, Cobalt, and Lithium Projects
African copper, cobalt, and lithium projects are generating a wider set of equipment orders than in the previous commodity investment cycle. Ivanhoe Mines guided Kamoa-Kakula copper production of 290,000 to 330,000 tonnes for 2026, demonstrating the scale of current development in the Democratic Republic of the Congo. Sandvik announced an order for 19 Toro trucks and loaders for the Kamoa-Kakula complex in 2026. Epiroc reported orders from Africa for autonomous and electric drilling equipment in 2026, indicating that new projects are also adopting advanced fleet specifications. The U.S.-Congo minerals partnership and investment in the Lobito Corridor improve the case for additional regional projects. New funding sources can also widen access for Western suppliers and their local service networks.
Recovery of Greenfield Iron Ore Projects in Western Australia and Brazil
Large iron ore developments in Australia and Brazil are adding a second source of demand alongside critical mineral projects. Rio Tinto and Hancock Prospecting committed USD 1.6 billion to Hope Downs 2 in June 2025, with the project targeting 31 Mtpa and first ore in 2027. ITOCHU announced the full development of the Minera Norte iron ore deposit in July 2026. These projects require earthworks, haul roads, and fleet deliveries before commercial production begins. Procurement is therefore concentrated during the construction period, often 24 to 36 months before first ore. Rio Tinto’s wider Pilbara investment program confirms that replacement mines and extensions remain important to the mining equipment market.
Restraints Impact Analysis of Mining Equipment Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Ore-grade deterioration inflating total cost-of-ownership | -1.0% | Global; particularly South America, Indonesia, West Africa | Long term (≥ 4 years) |
| Grid constraints at remote mines delaying BEV deployment | -0.7% | Australia, Chile, Africa | Medium term (2–4 years) |
| Talent shortage for autonomous haul-truck operations | -0.5% | Global | Medium term (2–4 years) |
| Uneven permitting timelines for new surface mines (EU and United States) | -0.4% | North America and Europe | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Ore-Grade Deterioration Inflating Total Cost of Ownership
Declining ore grades are increasing energy, water, and equipment consumption per unit of metal produced. Mines must move and process larger volumes of material, increasing tire wear, machine operating hours, and maintenance requirements. This pressure can constrain fleet renewal at marginal operations, even when commodity prices remain supportive. Conversely, it encourages high-grade operations to adopt larger, more productive equipment and predictive maintenance practices to protect operating margins.
Grid Constraints at Remote Mines Delaying BEV Deployment
Remote power infrastructure remains a major barrier to battery-electric fleet deployment. Queensland redirected funding toward a USD 200 million hybrid microgrid fund after the CopperString transmission project's cost and timing changed. Kalgoorlie has faced capacity and reliability issues on its long transmission connection as local mine power needs increase. Mine owners may need to develop generation, storage, transmission, and charging systems in addition to buying vehicles. This increases the initial investment and may delay electrification in areas with limited power supply. The mining equipment market will therefore see the fastest adoption of battery-electric systems at sites with secure, high-capacity electricity access.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Mining Equipment Market Segment Analysis
By Equipment Type:
Excavators Lead, Shovels Support New Large-Pit CapacityExcavators held 31.46% of the mining equipment market share in 2025, reflecting their central role in stripping and material handling at surface mines. They are used across coal, iron ore, and metal operations, which provides a broad installed base. Large open-pit projects in Asia-Pacific and Africa continue to rely on excavator-truck combinations for primary production. Shovels are forecast to grow at a 5.62% CAGR through 2031 as new copper and iron ore mines seek greater payload per cycle. The mining equipment market size for large loading equipment benefits when operators prioritize lower cost per ton at high-volume sites.
In May 2025, Komatsu Germany Mining Division (KGM) and SMS Equipment officially handed over the first Komatsu PC9000 hydraulic mining excavator at Suncor’s Fort Hills mine in Canada. This delivery highlights the shift among large mining sites toward high-capacity loading equipment. Drills and breakers also benefit when greenfield projects begin construction in the Pilbara and the Democratic Republic of the Congo. Crushers see increased demand when lower-grade ore requires greater throughput to maintain metal output. Motor graders and scrapers remain tied more closely to haul-road maintenance than to major mine expansions.



By Automation Level:
Manual Fleets Remain Large While Autonomous Adoption AcceleratesManual equipment accounted for 69.11% of the mining equipment market share in 2025 because conventional diesel fleets remain widespread in coal and bulk commodity operations. This installed base does not fully describe the direction of current procurement. Fully autonomous equipment is forecast to expand at a 12.51% CAGR through 2031. Mine owners are extending deployment beyond the first large iron ore and oil sands operations. Automation is increasingly specified alongside electric propulsion, remote operations, and equipment health monitoring.
Komatsu commissioned its 1,000th autonomous ultra-class haul truck in April 2026, which illustrates the broader maturity of autonomous haulage. Semi-autonomous equipment remains a practical bridge for mines that are developing supervisory and data-management capabilities. Workforce training remains a constraint because autonomous operations require different operating and maintenance skills. That requirement may slow adoption in regions where technical labor supply is limited, even when equipment economics are favorable.
By Powertrain Type:
ICE Retains Scale While Battery-Electric Vehicles AdvanceInternal combustion engine vehicles held 89.68% of the mining equipment market share in 2025, supported by decades of fleet investment and established fuel supply systems. Diesel equipment also remains reliable at remote, high-altitude, and extreme-temperature sites. Battery-electric vehicles are forecast to grow at a 13.71% CAGR through 2031. The gap in growth rates reflects underground fleet replacement, emission requirements, and larger site deployments. This part of the mining equipment market is supported by charging systems, renewable power contracts, maintenance capabilities, and vehicle orders.
Codelco’s 2026 electric-truck pilot in Chile provided practical range and payload data for future mine procurement. Hybrid vehicles remain relevant when grid limitations or duty cycles make full electrification difficult. They can reduce fuel use while avoiding an immediate need for large charging infrastructure. Underground equipment has a particularly strong case for battery-electric propulsion because reduced ventilation requirements can lower site operating costs. The continued need for reliable power connections means that powertrain selection will remain site-specific rather than uniform across the mining equipment industry.
By Application:
Metal Mining Leads Equipment DemandMetal mining accounted for 48.55% of the mining equipment market share in 2025 and recorded the highest growth rate of 5.29% through 2031. Copper, gold, iron ore, nickel, lithium, and cobalt projects require large fleets and sophisticated processing support. Critical mineral demand is sustaining capital spending across several metal groups simultaneously. The International Energy Agency has highlighted the strategic importance of secure critical mineral supply chains. Mineral mining adds demand from lithium, phosphate, and rare-earth projects in Australia, Latin America, and Africa.
Coal mining remains important in terms of equipment volume in China and Indonesia, but it represents a smaller share of incremental investment as financing conditions change. Lower grades are increasing the number of tonnes that must be moved and processed at several metal mines. That can create competing effects for equipment providers. Marginal mines may postpone purchases, while productive assets may invest in high-payload fleets, automation, and service programs. The mining equipment market size for metal mining is therefore supported by both new project construction and productivity upgrades at existing mines.

By Mining Type:
Surface Mining Leads While Underground Mining Grows FasterSurface mining accounted for 61.75% of the mining equipment market share in 2025 because open-pit operations dominate production of iron ore, coal, copper, and gold. These mines require large excavators, shovels, trucks, and road-maintenance equipment. Western Australia’s replacement and extension projects remain a major source of demand for these fleets. Underground mining is forecast to grow at a 5.68% CAGR through 2031 as mature copper, nickel, and gold deposits extend deeper. The mining equipment market favors underground battery-electric equipment where ventilation and cooling savings offset the added capital cost.
Surface fleets are moving toward larger payloads and longer autonomous operating windows. Underground fleets are moving more directly toward battery-electric loaders, trucks, and drills. Sandvik states that suitable brownfield underground operations can reduce cash cost per ton by using battery-electric equipment instead of comparable internal-combustion equipment. This can change the default specification for new underground orders. However, mine access, charging design, and power supply still determine whether the operating case is viable. Both mining types will remain important to the mining equipment market, but their technology needs are diverging.
Geography Analysis
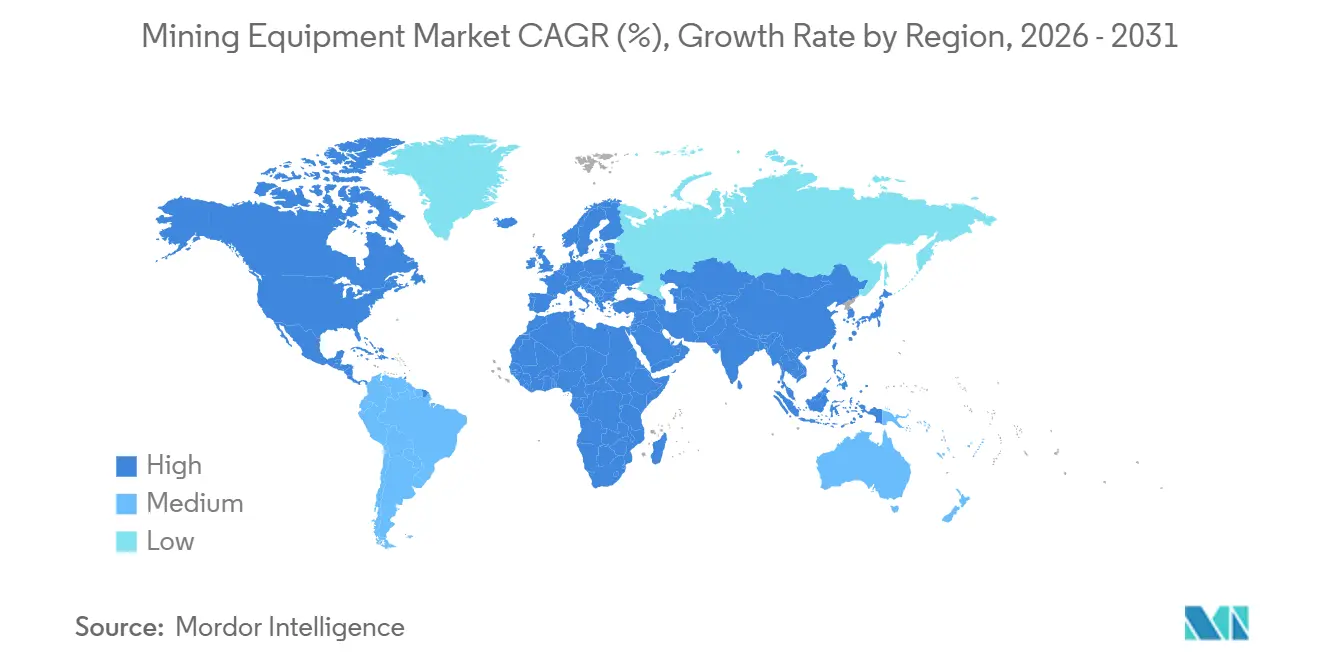
Asia-Pacific held 61.17% of the mining equipment market share in 2025, supported by China’s coal and iron ore fleets, Indonesia’s nickel operations, and Australia’s replacement projects. China has a large autonomous mining truck base, while Australia contributes high equipment values at individual iron ore sites. Epiroc’s Roy Hill project showed that autonomous haulage can be deployed across an entire large-scale fleet. India's demand is rising as domestic mining and construction investment expands, while the local supply of specialist underground equipment remains limited. The mining equipment market size in the region is therefore supported by both fleet replacement and capacity expansion.
North America benefits from public support for critical minerals, technology development, and low-carbon production. Canada also has a substantial base of autonomous haulage activity and a growing pipeline of electric fleets. South American demand is led by Chilean copper and lithium projects, where Codelco is testing electric heavy equipment and power-transfer systems. Brazil adds iron ore demand through the Amapá project and planned green iron development.
The Middle East and Africa are forecast to grow at a 5.88% CAGR through 2031, the highest rate among the listed regions. Copper and cobalt projects in the Democratic Republic of the Congo, Botswana’s copper belt, Zambian refining activity, and South African platinum-group-metal mining all support demand for equipment. Epiroc’s African autonomous and electric drilling order, together with Sandvik’s Kamoa-Kakula fleet order, shows the shift toward higher-value equipment specifications. Europe faces more complex permitting and public opposition to new surface mines. It nevertheless remains important for underground electric equipment, with Scandinavian operators setting demanding standards for electric and autonomous haulage. The mining equipment market has a different regional profile in Europe, where technology renewal can matter more than new mine construction.
Regional Editions
Competitive Landscape
Market Concentration
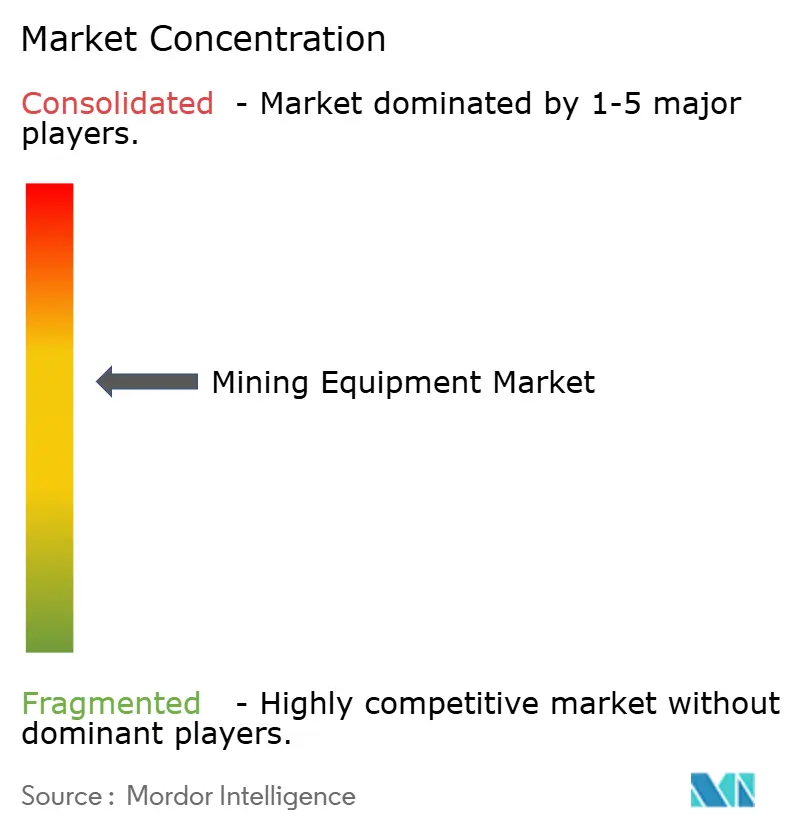
The mining equipment market has moderate concentration in premium surface and underground machinery. Caterpillar, Komatsu, Sandvik, Epiroc, and Liebherr have strong positions in high-payload fleets and specialist underground equipment. Chinese suppliers XCMG and SANY are expanding their presence in the excavator and mid-tier truck markets. Competition is no longer based only on machine purchase prices. Suppliers are seeking to protect installed bases through automation platforms, fleet data systems, parts availability, and service contracts.
Caterpillar acquired Skycatch in July 2026 to expand its mining technology and spatial data capabilities. The acquisition enhanced the digital capabilities of its MineStar offering and strengthened its ability to deliver integrated mine workflows. Sandvik completed its acquisition of Diemme Filtration in September 2026, expanding its dewatering and filtration offerings. In 2025, Epiroc signed a five-year contract with Fortescue covering autonomous and electric mining equipment, highlighting the growing importance of large-scale, long-duration fleet programs.
These strategies increase switching costs because mine operators must consider equipment, software, training, infrastructure, and lifecycle service together. Machine safety standards and autonomous-vehicle operating requirements also raise the qualification threshold for suppliers. New entrants may compete most effectively in specific product classes or regional markets before building a broad support network. The mining equipment industry remains open to price competition, especially in conventional equipment, but premium contracts increasingly favor proven fleet integration and operational support. No combined market share for the top suppliers was provided, so the available material does not support a calculated concentration score at this stage.
Mining Equipment Industry Leaders
-
Caterpillar Inc.
-
Liebherr-International AG
-
Epiroc AB
-
Komatsu Ltd.
-
Sandvik AB
- *Disclaimer: Major Players sorted in no particular order
Mining Equipment Market Companies Covered in this Report
- Caterpillar Inc.
- Komatsu Ltd.
- Sandvik AB
- Liebherr-International AG
- Epiroc AB
- Hitachi Construction Machinery Co., Ltd.
- Atlas Copco Group
- Volvo Construction Equipment (Volvo CE)
- Metso Corporation
- Astec Industries Inc.
- BEML Limited
- Xuzhou Construction Machinery Group Co., Ltd.
- Sany Heavy Industry Co., Ltd.
- HD Hyundai Construction Equipment Co., Ltd.
- Terex Corporation
- CNH Industrial N.V.
- JCB Ltd.
Recent Industry Developments in Mining Equipment Market
- October 2026: BEML Ltd unveiled India’s first indigenously developed 60-ton-class battery-electric dump truck, the BH60-EV, for the mining and infrastructure sectors. It features a Permanent Magnet Synchronous Motor (PMSM), a rugged gearbox, and a 1,000 kWh high-voltage lithium-ion battery pack for heavy-duty applications.
- September 2026: Volvo Construction Equipment India launched the EC650, a 65-ton excavator, as its flagship entry into India’s heavy mining excavator segment. The EC650 features a 435-horsepower Volvo D13E engine, a heavy-duty boom and arm, a reinforced undercarriage, and advanced hydraulics designed for mass excavation and mining operations in demanding conditions.
- January 2026: Metso secured an order to supply a complete gold processing line for Ma’aden’s Ar Rjum project in Saudi Arabia. The scope includes crushing, grinding, leaching, tailings management, and automation systems.
- December 2025: Develon unveiled a new lineup of electric excavators. The company introduced the expanded electric range in phases, beginning with the DX160WE-7 electric wheeled excavator, followed by the DX230LCE-7 and DX250LCE-7 electric crawler excavators.
Mining Equipment Market Report Scope and Research Methodology
Market Definition and Coverage
Our study defines the global mining equipment market as the value of new, factory-built machinery and vehicles, including excavators, haul trucks, loaders, drills, crushers, and mineral-processing systems, that are purchased for surface or underground extraction and material handling across metal, mineral, and coal operations.
Scope exclusion: Refurbished machines, equipment leased or rented, consumable wear parts, and standalone software licenses are not counted.
Segments Covered in This Report
- By Equipment Type
- Loaders
- Excavators
- Mining Trucks
- Motor Graders
- Shovels
- Scrapers
- Crushers
- Drills and Breakers
- Others
- By Automation Level
- Manual Equipment
- Semi-Autonomous Equipment
- Fully Autonomous Equipment
- By Powertrain Type
- Internal Combustion Engine Vehicles
- Battery-Electric Vehicles
- Hybrid Vehicles
- By Application
- Metal Mining
- Mineral Mining
- Coal Mining
- By Mining Type
- Surface Mining
- Underground Mining
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Chile
- Peru
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Sweden
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Indonesia
- Rest of Asia-Pacific
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Egypt
- Turkey
- Rest of Middle East and Africa
- North America
Data Sources, Market Sizing, and Validation
Primary Research
Structured discussions with procurement heads at iron-ore, copper, and coal producers in Asia-Pacific, the Americas, and Africa, together with senior product managers at dealer networks, validated utilization cycles, average selling prices, and emerging demand for sub-500 HP battery-electric loaders.
Follow-up surveys of equipment-finance specialists refined replacement-rate assumptions.
Desk Research
Analysts compiled baseline data from open sources such as UN Comtrade shipment codes for HS-84 mining machinery, the International Council on Mining and Metals production tables, USGS mineral statistics, and national safety-agency equipment registries.
Additional context came from World Bank commodity price series, OECD gross fixed capital formation, and OEM investor filings.
Subscription resources, notably D&B Hoovers for company financials and Dow Jones Factiva for news on capacity additions, supplemented the public record.
The sources cited here illustrate the range; many others informed data collection, cross-checks, and clarification.
Market-Sizing & Forecasting
A top-down production and trade rebuild established 2025 demand volumes; then selective bottom-up roll-ups of sampled OEM unit shipments multiplied by verified ASPs cross-checked totals.
Key inputs include the top-40 miners' capital expenditure outlook, average copper and thermal coal prices, drilled meterage split between surface and underground sites, horsepower mix, and battery-electric penetration.
Forecasts to 2031 are generated through multivariate regression combined with scenario analysis so price elasticity and commodity cycle swings adjust growth paths.
Where bottom-up gaps appeared, regional import data and capacity utilization curves bridged differences before final reconciliation.
Data Validation & Update Cycle
Each draft model runs through anomaly screens that compare outputs with historical replacement curves and ICMM safety inspection counts.
Variances greater than five percent trigger re-verification with sources or fresh calls to respondents.
Reports refresh annually, with interim updates when events such as major mine closures, regulatory shifts, or large fleet electrification orders materially change demand.
How Mordor Intelligence's Mining Equipment Market Size Compares to Other Published Estimates
Published estimates often differ because firms adopt varying scopes, price bases, and refresh timings, and because some fold in rental or service revenue while others do not.
Key gap drivers include differing inclusion of used equipment sales, treatment of maintenance contracts as equipment revenue, currency conversion practices, and the commodity basket chosen to project future investment.
Benchmark comparison
| Market Size | Anonymized source | Primary gap driver |
|---|---|---|
| USD 106.35 B (2025) | Mordor Intelligence | |
| USD 148.74 B (2024) | Global Consultancy A | Counts rental and aftermarket services, relies mainly on vendor revenue disclosures |
| USD 141.31 B (2023) | Trade Journal B | Combines used equipment sales and applies uniform ASP uplift without geography weighting |
The comparison shows that Mordor's disciplined scope selection, variable-level validation, and yearly refresh cycle deliver a balanced and transparent baseline that decision-makers can trace to clear inputs and repeatable steps.
Key Questions Answered in the Report
What is the projected value of the mining equipment market by 2031?
The mining equipment market is projected to grow from USD 111.67 billion in 2026 to USD 141.43 billion by 2031, at a CAGR of 4.84%. Growth will be driven by greenfield projects, fleet replacements, electrification requirements, and capacity additions for critical minerals.
Which equipment category will hold the largest share in 2025?
Excavators accounted for 31.46% of the mining equipment market revenue in 2025, driven by their use in surface stripping and material handling. The mining equipment market continues to use excavator and truck systems across coal, iron ore, and metal operations.
Which mining equipment powertrain is growing fastest?
Battery-electric vehicles are forecast to grow at a 13.71% CAGR through 2031, supported by underground applications and electrification programs. The mining equipment market is also affected by mine power capacity, charging design, and renewable energy supply.
Why is underground mining equipment growing faster than surface equipment?
Underground mining is forecast to grow at a 5.68% CAGR through 2031, as mature deposits deepen and battery-electric fleets can reduce ventilation and cooling needs. This part of the mining equipment market depends on operating conditions, mine design, and reliable access to electricity.
Which region is expected to record the fastest growth in the mining equipment market?
The Middle East and Africa are forecast to grow at a 5.88% CAGR through 2031, led by copper, cobalt, lithium, and platinum-group-metal projects. The mining equipment market in the region is supported by fleet orders for advanced drilling, loading, and haulage assets.
How are autonomous systems changing mine equipment purchases?
Mine owners are increasingly assessing automation in terms of software, workforce skills, and service support, rather than as a stand-alone vehicle purchase. The mining equipment market increasingly rewards suppliers that can support fleet integration over the equipment lifecycle.