
Managed Digital Mailroom Services Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Market Size (2027) | USD 2.95 Billion |
| Market Size (2032) | USD 4.37 Billion |
| Growth Rate (2027 - 2032) | 8.16 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Managed Digital Mailroom Services Market Analysis by Mordor Intelligence
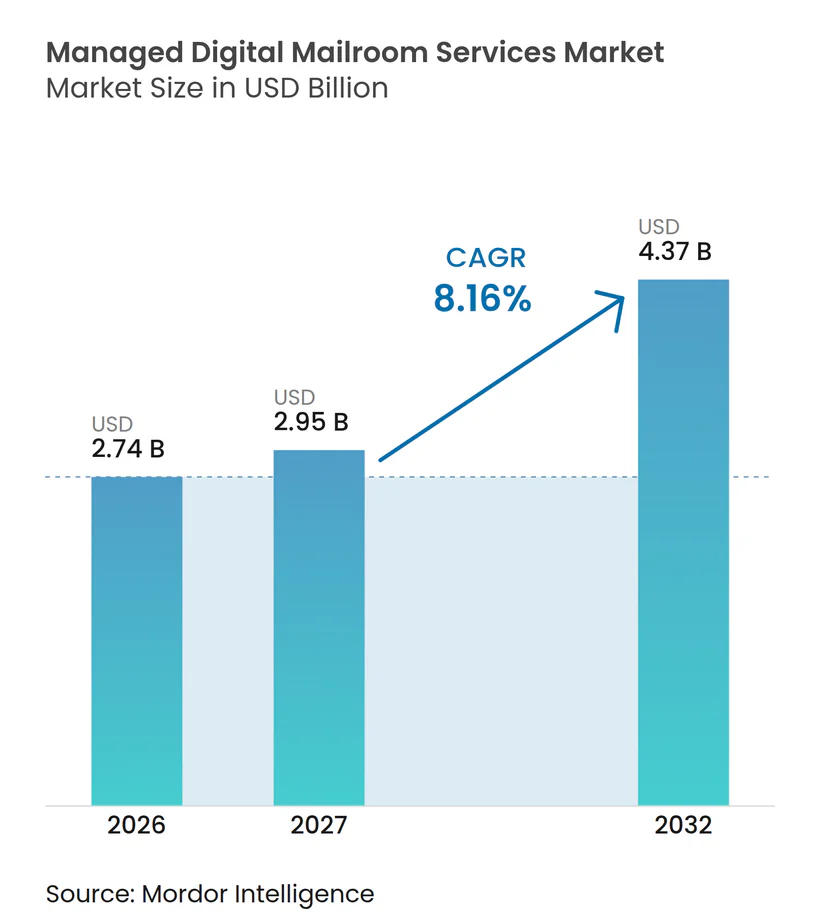
The Managed Digital Mailroom Services Market size is projected to expand from USD 2.74 billion in 2026 to USD 4.37 billion by 2032, registering a CAGR of 8.16% between 2027 and 2032. Enterprise buyers increasingly treat inbound correspondence as structured information rather than a back-office logistics task. This shift favors providers that combine physical-to-digital conversion, AI-assisted routing, and enterprise system integration within a controlled custody process. Iron Mountain reported that its internally deployed Digital Mail solution reduced document processing cycle time by 60% and cost-to-serve by 25% in 2026, which has made measurable operational results more important in procurement discussions. The Managed Digital Mailroom Services Market also benefits when organizations need remote access to time-sensitive documents and stronger audit controls. Cybersecurity exposure, data residency requirements, and difficult integration with established business systems remain important limits on adoption.
Key Report Takeaways
- By service type, mail scanning and image capture held 24.32% of the Managed Digital Mailroom Services Market share in 2026, while data capture and extraction is projected to expand at a 9.12% CAGR through 2032.
- By service delivery model, off-site outsourced managed service held 46.21% of the Managed Digital Mailroom Services Market share in 2026, while hybrid co-managed service is projected to expand at a 9.33% CAGR through 2032.
- By end user, banking, financial services, and insurance held 26.23% revenue share in 2026, while healthcare is projected to expand at a 9.42% CAGR through 2032.
- By geography, North America held 38.21% revenue share in 2026, while Asia-Pacific is projected to expand at a 9.63% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Managed Digital Mailroom Services Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| AI-Enabled Intelligent Document Processing and Routing | +2.1% | Global, most pronounced in North America and Europe | Medium term (2–4 years) |
| Hybrid Work and Remote Mail Access | +1.8% | Global, with high concentration in North America, the United Kingdom, and Australia | Short term (≤ 2 years) |
| Lower Document Cycle Times and Cost-to-Serve | +1.4% | Global | Short term (≤ 2 years) |
| Outsourcing in Regulated Document Operations | +1.1% | North America and Europe, with growing traction in Asia-Pacific | Medium term (2–4 years) |
| Auditable Records and Data Privacy Requirements | +0.9% | North America and the European Union, with spillover to the United Kingdom and Asia-Pacific | Medium term (2–4 years) |
| Physical-to-Digital Sustainability and Space Optimization | +0.5% | Global, strongest in Western Europe and Australia and New Zealand | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
AI-Enabled Intelligent Document Processing Reshapes Straight-Through Routing Economics
Generative AI and large language models are expanding document processing beyond optical character recognition and basic classification. These tools can handle unstructured, multilingual, and mixed-format correspondence with less reliance on predefined templates. The Managed Digital Mailroom Services Market gains from this capability because difficult correspondence can move into wider automation workflows, including legal claims and multi-jurisdiction filings that previously required greater manual review. Baloise used Liberty IDP to raise the straight-through processing rate for inbound communications from 15% to 65% by 2025 across an intake operation handling 11,000 documents each day.[1] This result reduced the level of daily manual intervention needed for document handling. Providers are therefore moving away from labor-based pricing toward contracts tied to data quality, processing outcomes, and downstream workflow speed.
Hybrid Work Creates Structural Demand for Remote Mail Access
Hybrid work has made physical mail backlogs an ongoing operational concern for organizations with time-sensitive legal, financial, and compliance correspondence. Iron Mountain reported that 79% of U.S. employees work in a hybrid or remote capacity, which can leave distributed teams unable to access documents delivered to a central office.[2] The Managed Digital Mailroom Services Market benefits when organizations use digital intake as a primary access channel rather than a secondary support process, particularly where documents need prompt review by staff working from different locations. This change can expand the scope of managed service agreements because scanning, routing, access controls, and user adoption must work together. DocSolid launched Airmail2 Cloud for hybrid workplaces in January 2025 and later released a mobile application for secure daily mail access. Organizations that postponed digital mailroom programs are shortening their implementation schedules to address this access gap.
Lower Document Cycle Times and Cost-to-Serve Strengthen Enterprise ROI Cases
The value case for outsourced digital mailrooms is more tangible when operators publish operating results. Iron Mountain reported a 60% reduction in document processing cycle time, a 25% reduction in cost-to-serve, a 40% improvement in audit trail completeness, and USD 750,000 in annual cost avoidance from its 2026 internal deployment. Conduent states that its document processing services deliver 30% average cost savings and index and classify 14 billion documents annually.[3] Cycle time matters especially where response deadlines are required under contracts or regulation. The Managed Digital Mailroom Services Market can also gain as digitized mail data reveals volume spikes, sender patterns, and exception rates that manual processes do not readily show. These visible patterns support demand for analytics and reporting services within larger operating agreements.
Outsourcing in Regulated Document Operations Expands Service Scope
The Managed Digital Mailroom Services Market benefits as regulated sectors externalize mailroom activities where compliance requirements and specialist processing skills create a high internal burden. Iron Mountain received a USD 142 million U.S. Internal Revenue Service bridge contract in May 2025 for scanning and digitalization services that covered up to 50 million mail items annually. The contract included tax returns, correspondence, remittances, indexing, scanning, and optical character recognition. The International Legal Technology Association reported that 88% of surveyed law firms operated primarily cloud-based document management environments in 2025. Digital intake is more relevant in these environments because it links first receipt with downstream records governance. Healthcare also supports demand because payer remittances, prior authorizations, and patient communications continue to require controlled handling.
Restraints Impact Analysis of Managed Digital Mailroom Services Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Cybersecurity and Cross-Border Data Governance Risk | -1.3% | Global, highest impact in the European Union and North America | Short term (≤ 2 years) |
| Legacy ERP, CRM, and Content-System Integration Complexity | -1.0% | Global, most acute in large enterprises and the public sector | Medium term (2–4 years) |
| Implementation and Change-Management Costs for Smaller Buyers | -0.7% | Global, with highest sensitivity in small and medium-sized enterprise markets | Short term (≤ 2 years) |
| Human Review Needs for Low-Quality and Unstructured Documents | -0.4% | Global | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Cybersecurity and Cross-Border Data Governance Risk Constrain Off-Site Aggregation
Centralized off-site processing can create an attractive target for cyber intrusion because it brings sensitive correspondence into a shared operating environment. The Managed Digital Mailroom Services Market requires providers to maintain encryption, role-based access controls, immutable audit trails, SOC 2 Type II attestation, and ISO 27001 certification where clients require them. Cross-border data rules add further complexity for operators that serve regulated customers across several jurisdictions and need to demonstrate where information is received, processed, stored, and accessed. GDPR transfer restrictions, the European Union Digital Operational Resilience Act, and U.S. state privacy rules can require geographically distributed processing instead of volume consolidation. Financial services and healthcare customers remain accountable for failures by third-party processors under their own compliance responsibilities. This makes the Managed Digital Mailroom Services Market dependent on verifiable custody procedures and clear data handling controls during provider selection.
Legacy ERP, CRM, and Content-System Integration Complexity Slows Large-Enterprise Adoption
Digital mailroom platforms can be difficult to connect with established enterprise systems, particularly customized on-premises ERP and CRM environments. Organizations with systems acquired through mergers and acquisitions may have several data models and normalization needs. Extracted details such as counterparty names, invoice numbers, and case references often need custom middleware before they can enter receiving systems. This additional work can lengthen deployment schedules and increase total ownership costs for Managed Digital Mailroom Services Market buyers that have complex legacy application stacks. Existing content management platforms can also use taxonomies that do not match a new provider's metadata schema, requiring classification mapping and migration work before operations can begin. Banks, insurers, and public agencies face this issue most often because they commonly operate complex legacy environments while also representing high-value buyers.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Managed Digital Mailroom Services Market Segment Analysis
By Service Type:
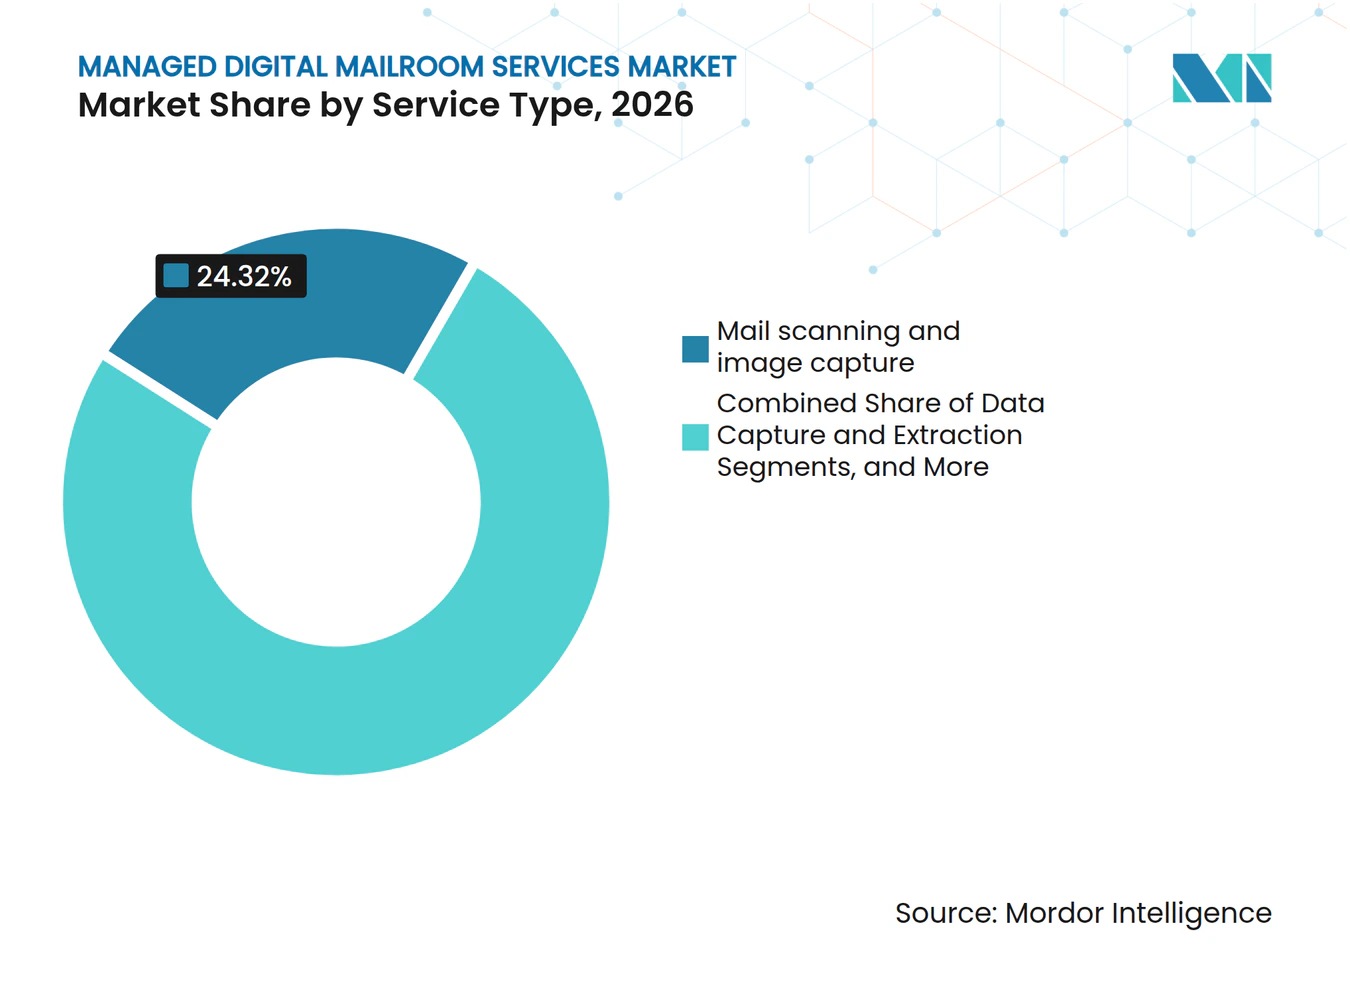
Data Extraction and AI Automation Expand the Service StackMail scanning and image capture held 24.32% of the Managed Digital Mailroom Services Market share in 2026 because it forms the intake layer for downstream services. Scanning by itself, however, has less commercial value when clients can obtain extraction, classification, and routing under the same agreement. Data capture and extraction is projected to expand at a 9.12% CAGR through 2032. This service produces structured, system-ready information rather than image files that require manual re-entry. That difference supports organizations that need data to move into ERP, claims management, and customer relationship systems.
Document sorting and classification are becoming more useful as machine learning models are trained on industry-specific document types. Workflow automation and enterprise integration are also moving from discrete implementation projects into ongoing service arrangements. Clients need routing rules to change with their application environments and internal workflows. Digital archiving and records disposition add a compliance element to the Managed Digital Mailroom Services Market. These services are relevant for broker-dealers subject to SEC Rule 17a-4 WORM storage requirements and for organizations managing SOX seven-year retention obligations.



By Service Delivery Model:
Hybrid Configuration Gains Relevance as Risk Profiles DivergeOff-site outsourced managed service held 46.21% of the Managed Digital Mailroom Services Market share in 2026. Secure third-party facilities can process high mail volumes with scale in scanning, indexing, and document destruction. This model is suited to standardized correspondence that does not need to remain inside a client location. Hybrid co-managed service is projected to expand at a 9.33% CAGR through 2032. This model reflects a different risk approach, where enterprises outsource high-volume and lower-sensitivity mail while retaining control over selected sensitive categories.
Legal notices, regulatory correspondence, and executive communications are examples of mail that enterprises may prefer to process on site. The Managed Digital Mailroom Services Market therefore needs delivery models that can accommodate different sensitivity levels within one client environment. On-site outsourced managed service remains relevant for government agencies and defense contractors where mail cannot leave the premises. Providers with cloud-native configurations can support on-site, off-site, and hybrid arrangements under one agreement. This flexibility reduces the need to manage several vendors as security, compliance, or volume requirements change.
By End User:
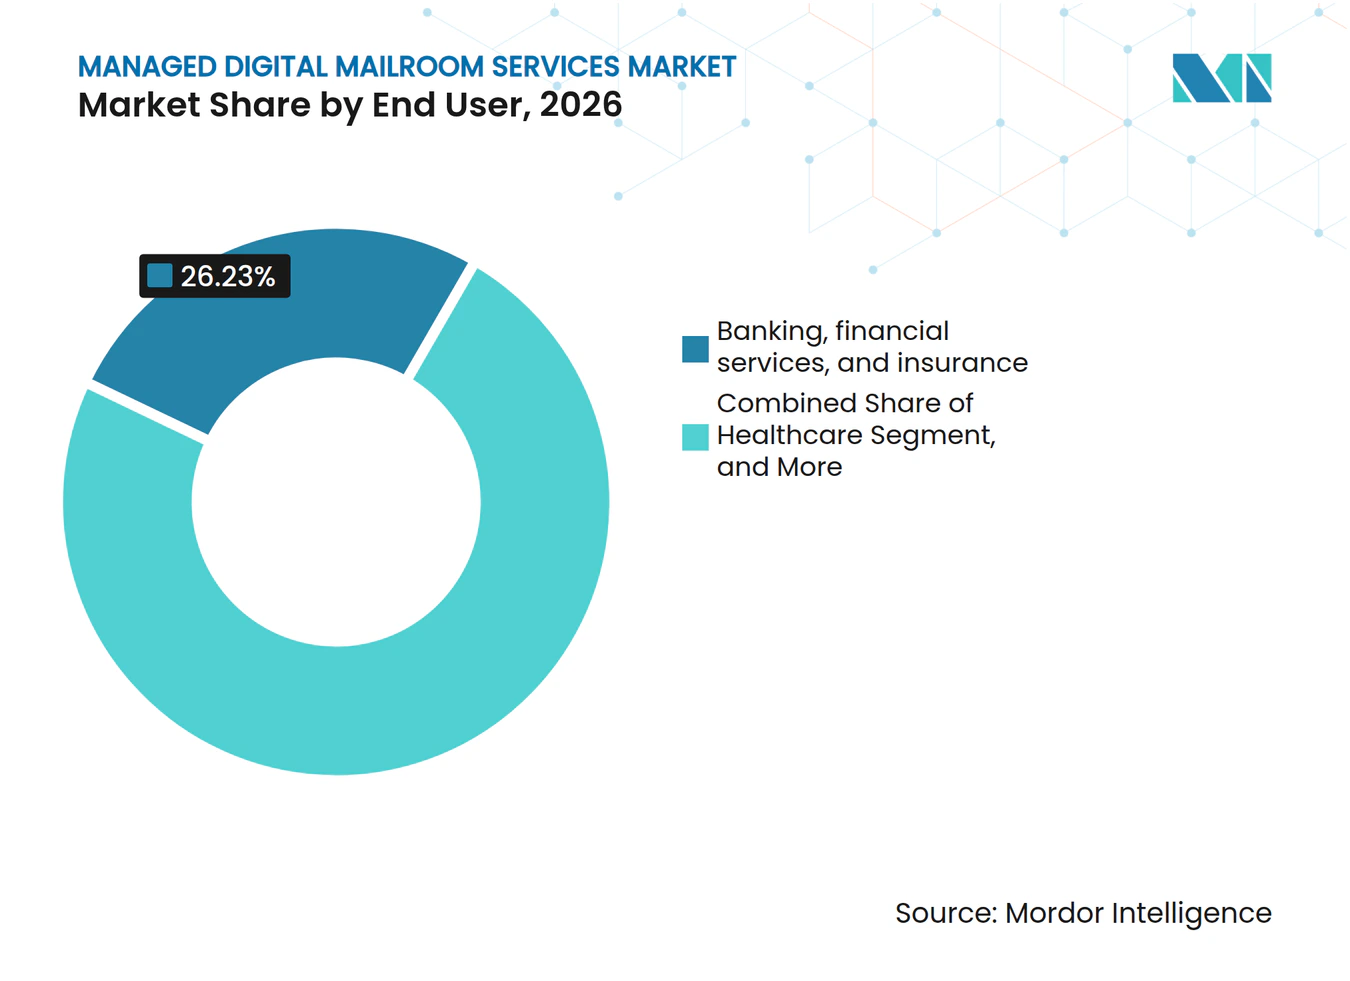
BFSI Anchors Revenue While Healthcare Expands on Compliance NeedsBanking, financial services, and insurance held 26.23% of the Managed Digital Mailroom Services Market share in 2026. The sector continues to receive loan documents, insurance claims, customer correspondence, and regulatory filings through physical channels. Financial institutions also need traceable handling where service deadlines and regulatory requirements apply. Healthcare is projected to expand at a 9.42% CAGR through 2032. The segment handles persistent paper flows that include payer remittances, prior authorizations, and patient communications requiring HIPAA-aligned controls.
Government and public-sector bodies create another substantial opportunity because large programs need repeatable and auditable document processing. The U.S. Internal Revenue Service contract awarded in 2025 demonstrates the scale of potential outsourcing for government mail intake. Legal and professional services are also increasing demand for controlled intake as cloud document management becomes more common. The International Legal Technology Association survey found that 88% of respondents operated primarily cloud-based document management environments in 2025. Retail and e-commerce, transportation and logistics, energy and utilities, education, nonprofit organizations, and associations contribute through transactional correspondence at varying volume levels.

Geography Analysis
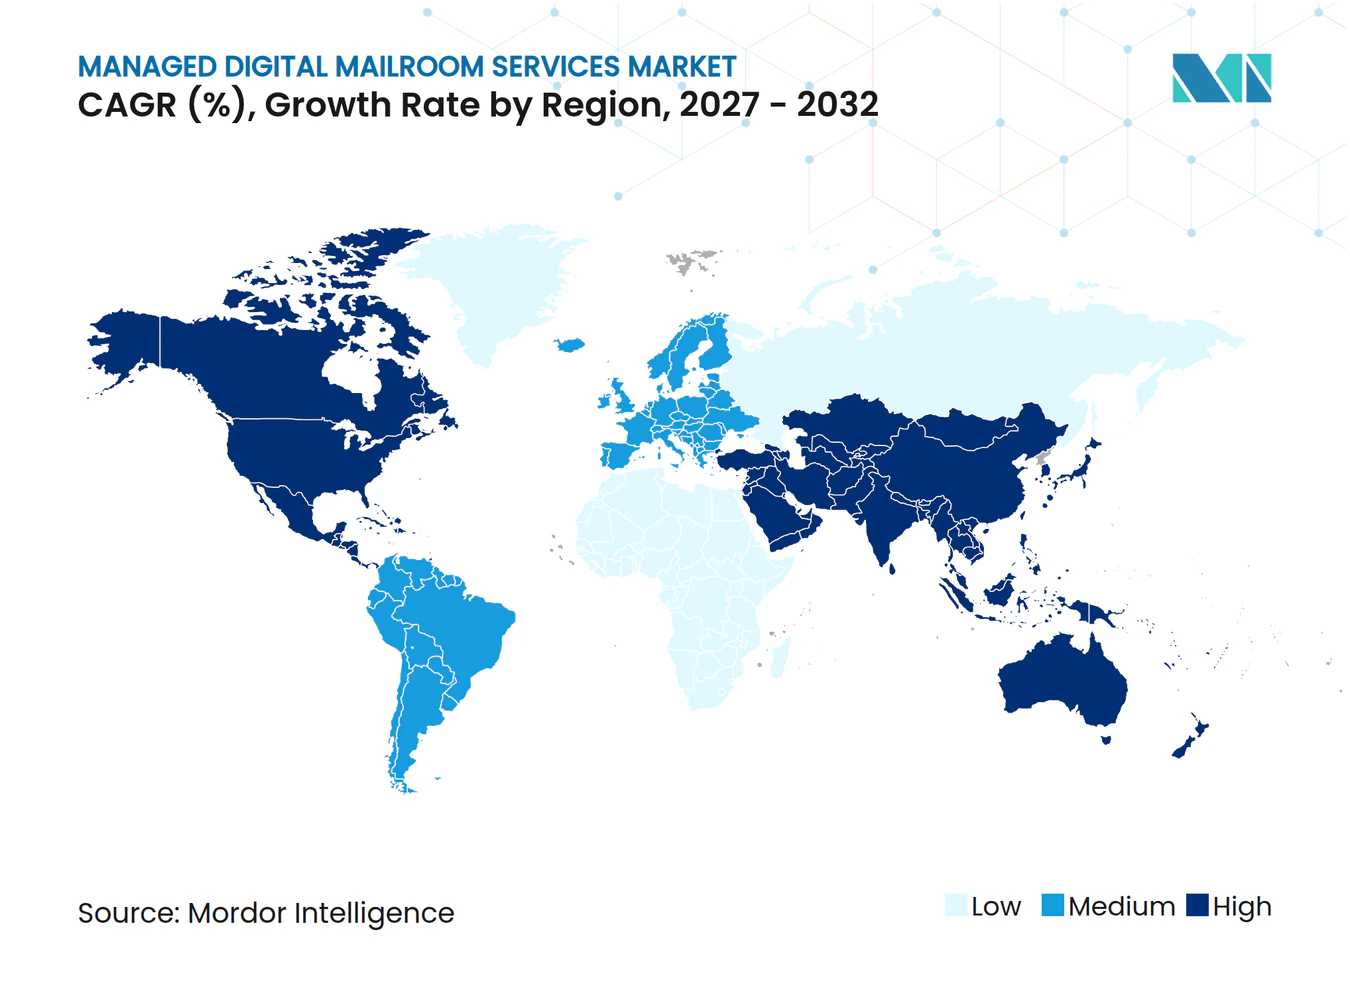
North America held 38.21% of the Managed Digital Mailroom Services Market share in 2026, supported by enterprise demand in banking, financial services, insurance, healthcare, and federal contracting. The United States represents most regional revenue because buyers often seek integrated technology and managed service arrangements. HIPAA, SOX, GLBA, and state data protection laws create explicit handling and audit requirements. Iron Mountain began work on a U.S. Department of the Treasury digitization contract in June 2025 after the award in April 2025, and the Internal Revenue Service contract adds a separate reference point for large-scale federal mail digitalization. Canada and Mexico provide additional demand through regulated sectors and public-sector digitization work.
Europe is the second-largest regional contributor to the Managed Digital Mailroom Services Market, with Germany, the United Kingdom, and France as the principal revenue contributors. GDPR has made auditable document handling a regular procurement requirement, which supports specialized managed service offerings. NHS England reported a 97.8% reduction in carbon emissions per appointment letter for its digital approach compared with paper correspondence in April 2025. Ricoh UK started a 4-year print and mail services contract with the London Borough of Camden in January 2026, valued at GBP 4.8 million, which was reported as USD 5.9 million. The United Kingdom Digital Document Solutions framework, which runs through March 2027, provides a structured route for public-sector procurement.
Asia-Pacific is projected to expand at a 9.63% CAGR through 2032, making it the fastest-growing geography. India, China, Japan, South Korea, and Southeast Asia are increasing demand for cloud-delivered and multilingual document processing, supported by electronic records mandates and e-governance initiatives. Multinational enterprises also need support for jurisdiction-specific data residency requirements across the region. South America remains a smaller contributor with Brazil and Colombia leading adoption, while the Middle East and Africa are earlier-stage markets supported by demand in the United Arab Emirates, Saudi Arabia, Nigeria, Egypt, and South Africa.
Competitive Landscape
Market Concentration
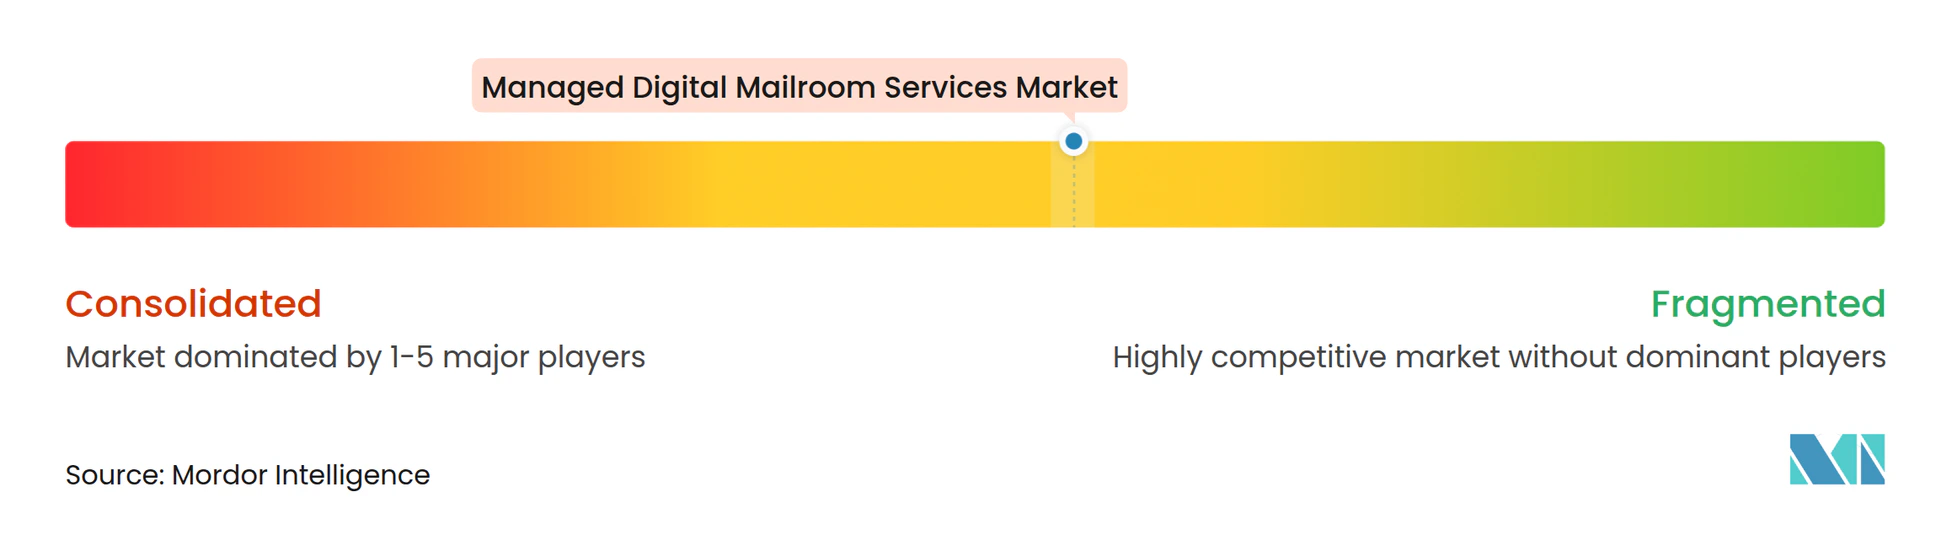
The Managed Digital Mailroom Services Market is moderately concentrated among information management specialists with significant enterprise and government contract capability. These providers benefit from processing scale, compliance certifications, and the ability to integrate with established enterprise systems. Competition below this group remains fragmented among regional providers and vertical specialists. These companies compete on price, turnaround times, and workflow templates designed for particular industries. The main competitive pattern is service stack expansion beyond scanning and delivery through AI-assisted intelligent document processing, analytics dashboards, and application programming interfaces.
Ricoh was named a Leader in the 2026 worldwide mailroom solutions and services assessment cited by the company. Ricoh attributed the recognition to its cloud-native Intelligent Business Platform and physical and digital delivery architecture across on-site, off-site, and hybrid models. Iron Mountain has used its internal Digital Mail deployment to demonstrate cycle-time, cost, and audit trail outcomes. DocSolid introduced Airmail2 Cloud in January 2025 for legal organizations managing paper scanning in hybrid workplaces. These examples show that Managed Digital Mailroom Services Market providers compete through controlled access, workflow depth, and measurable process outcomes.
White-space opportunities are present among mid-sized enterprises that lack resources to assess integrated platforms and in areas with limited managed service infrastructure, including Southeast Asia and the Gulf states. MetaSource, DATAMARK, and XBP Global compete in healthcare, government, and document processing niches through workflow customization and faster implementations. Enterprise content management and intelligent document processing software vendors also offer managed service layers around their technology, which blurs the boundary between software subscriptions and outsourced mailroom operations. The Managed Digital Mailroom Services Market will favor providers able to demonstrate strong straight-through automation rates and use per-document or value-based pricing rather than competing only on labor and facilities.
Managed Digital Mailroom Services Industry Leaders
-
Iron Mountain Incorporated
-
Xerox Corporation
-
Ricoh Company, Ltd.
-
Conduent Incorporated
-
DATAMARK, Inc.
- *Disclaimer: Major Players sorted in no particular order
Managed Digital Mailroom Services Market Companies Covered in this Report
- Iron Mountain Incorporated
- Xerox Corporation
- Ricoh Company, Ltd.
- Conduent Incorporated
- DATAMARK, Inc.
- OPEX Corporation
- Pitney Bowes Inc.
- Canon Inc.
- SPS Holding AG
- Quadient, Inc.
- XBP Global Holdings, Inc.
- Restore plc
- Kodak Alaris Inc.
- MetaSource, LLC
- Exela Technologies, Inc.
- Konica Minolta, Inc.
- Swiss Post Solutions AG
- Williams Lea Limited
- Epiq Systems, Inc.
- Kofax, Inc.
- ABBYY USA Software House, Inc.
- DocuWare GmbH
- Hyland Software, Inc.
- ibml, Inc.
- Canon Solutions America, Inc.
Recent Industry Developments in Managed Digital Mailroom Services Market
- October 2026: Pitney Bowes Inc. launched the SendPro CX Series, a next-generation sending platform for mid-volume mailers, offering faster processing speeds, simplified user experience, and integration with the Shipping 360 multi-location visibility platform. The launch extends Pitney Bowes' investment in core mailing product innovation following its April 2026 IL4 Provisional Authorization for the SendPro 360 platform for U.S. Department of Defense applications, signaling its push into regulated government mailing environments.
- July 2026: Ricoh USA, Inc. was named a Leader in the IDC MarketScape: Worldwide Mailroom Solutions and Services 2026 Vendor Assessment, the first IDC MarketScape for this category. The recognition highlighted Ricoh's unified physical-digital delivery architecture, its cloud-native Intelligent Business Platform, and its managed mailroom coverage across 200 countries serving 1.4 million customers.
- March 2026: Iron Mountain published a case study documenting its internal deployment of AI-powered Digital Mail at its Global Business Services organization, reporting a 60% reduction in document cycle time, a 25% reduction in cost-to-serve, a 40% improvement in audit trail completeness, and USD 750,000 in annual cost avoidance across 2 high-volume North American mail centers.
- January 2026: Ricoh UK Ltd commenced a 4-year print and mail services contract with the London Borough of Camden valued at GBP 4.8 million (USD 5.9 million), including hybrid mail, technical print, and inbound mail scanning for housing, revenue, and parking services.
Global Managed Digital Mailroom Services Market Report Scope
The Managed Digital Mailroom Services Market comprises outsourced and technology-enabled services that digitize, capture, classify, process, route, store, and manage incoming physical and electronic business correspondence on behalf of organizations.
The Managed Digital Mailroom Services Market Report is Segmented by Service Type (Mail Scanning and Image Capture, Document Sorting and Classification, Data Capture and Extraction, Workflow Automation and Enterprise Integration, Digital Archiving and Records Disposition, and Outbound Mail and Interoffice Redelivery), Service Delivery Model (Off-Site Outsourced Managed Service, On-Site Outsourced Managed Service, and Hybrid Co-Managed Service), End User (Banking, Financial Services, and Insurance, Healthcare, Government and Public Sector, Legal and Professional Services, Retail and E-Commerce, Transportation and Logistics, Energy and Utilities, and Other End Users), and Geography (North America [United States, Canada, and Mexico], South America [Brazil, Argentina, Colombia, and Rest of South America], Europe [Germany, United Kingdom, France, Italy, Spain, and Rest of Europe], Asia-Pacific [China, Japan, India, South Korea, Southeast Asia, Australia, and Rest of Asia-Pacific], Middle East [Turkey, Saudi Arabia, United Arab Emirates, Israel, and Rest of Middle East], and Africa [South Africa, Nigeria, Egypt, and Rest of Africa]). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Mail Scanning and Image Capture |
| Document Sorting and Classification |
| Data Capture and Extraction |
| Workflow Automation and Enterprise Integration |
| Digital Archiving and Records Disposition |
| Outbound Mail and Interoffice Redelivery |
| Off-Site Outsourced Managed Service |
| On-Site Outsourced Managed Service |
| Hybrid Co-Managed Service |
| Banking, Financial Services, and Insurance |
| Healthcare |
| Government and Public Sector |
| Legal and Professional Services |
| Retail and E-Commerce |
| Transportation and Logistics |
| Energy and Utilities |
| Other End Users |
| North America | United States |
| Canada | |
| Mexico | |
| South America | Brazil |
| Argentina | |
| Colombia | |
| Rest of South America | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Spain | |
| Rest of Europe | |
| Asia-Pacific | China |
| Japan | |
| India | |
| South Korea | |
| Southeast Asia | |
| Australia | |
| Rest of Asia-Pacific | |
| Middle East | Turkey |
| Saudi Arabia | |
| United Arab Emirates | |
| Israel | |
| Rest of Middle East | |
| Africa | South Africa |
| Nigeria | |
| Egypt | |
| Rest of Africa |
| By Service Type | Mail Scanning and Image Capture | |
| Document Sorting and Classification | ||
| Data Capture and Extraction | ||
| Workflow Automation and Enterprise Integration | ||
| Digital Archiving and Records Disposition | ||
| Outbound Mail and Interoffice Redelivery | ||
| By Service Delivery Model | Off-Site Outsourced Managed Service | |
| On-Site Outsourced Managed Service | ||
| Hybrid Co-Managed Service | ||
| By End User | Banking, Financial Services, and Insurance | |
| Healthcare | ||
| Government and Public Sector | ||
| Legal and Professional Services | ||
| Retail and E-Commerce | ||
| Transportation and Logistics | ||
| Energy and Utilities | ||
| Other End Users | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| South America | Brazil | |
| Argentina | ||
| Colombia | ||
| Rest of South America | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Spain | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| Japan | ||
| India | ||
| South Korea | ||
| Southeast Asia | ||
| Australia | ||
| Rest of Asia-Pacific | ||
| Middle East | Turkey | |
| Saudi Arabia | ||
| United Arab Emirates | ||
| Israel | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Nigeria | ||
| Egypt | ||
| Rest of Africa | ||
Key Questions Answered in the Report
What is the size of the managed digital mailroom services sector?
The managed digital mailroom services sector is valued at USD 2.74 billion in 2026 and is projected to reach USD 4.37 billion by 2032, registering a CAGR of 8.16% from 2027 to 2032. Demand is driven by enterprise requirements for integrated document intake, workflow routing, secure access controls, and auditable records management.
Which service type has the highest share in managed digital mailroom services?
Mail Scanning and Image Capture holds the largest market share at 24.32% in 2026, serving as the foundational intake process that enables downstream document extraction, classification, routing, storage, and records management activities.
Which delivery model is expanding most quickly?
Hybrid Co-Managed Service is projected to grow at the fastest rate, with a 9.33% CAGR through 2032, as organizations increasingly combine internal oversight of sensitive processes with outsourced handling of routine document volumes.
Which end users generate the strongest demand for these services?
Banking, Financial Services, and Insurance (BFSI) leads the market with a 26.23% share in 2026, while Healthcare is expected to grow at a 9.42% CAGR through 2032. Both sectors rely heavily on secure processing of high volumes of sensitive and compliance-intensive documents.
Which region is expected to expand most quickly?
Asia-Pacific is forecast to record the highest growth, with a 9.63% CAGR through 2032, supported by large-scale digital transformation initiatives, rising demand for multilingual document processing, cloud-based service adoption, and evolving data residency regulations.
What limits adoption of managed digital mailroom services?
Key adoption barriers include cybersecurity and cross-border data governance risks, legacy ERP, CRM, and content management system integration complexities, human review requirements for low-quality or unstructured documents, and implementation and organizational change-management costs, particularly for large enterprises operating across multiple locations and business units.