
Industrial Electrical Wiring Accessories Market Size and Share
Market Overview
| Study Period | 2022 - 2032 |
|---|---|
| Market Size (2027) | USD 16.59 Billion |
| Market Size (2032) | USD 22.59 Billion |
| Growth Rate (2027 - 2032) | 6.36 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | Asia-Pacific |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Industrial Electrical Wiring Accessories Market Analysis by Mordor Intelligence
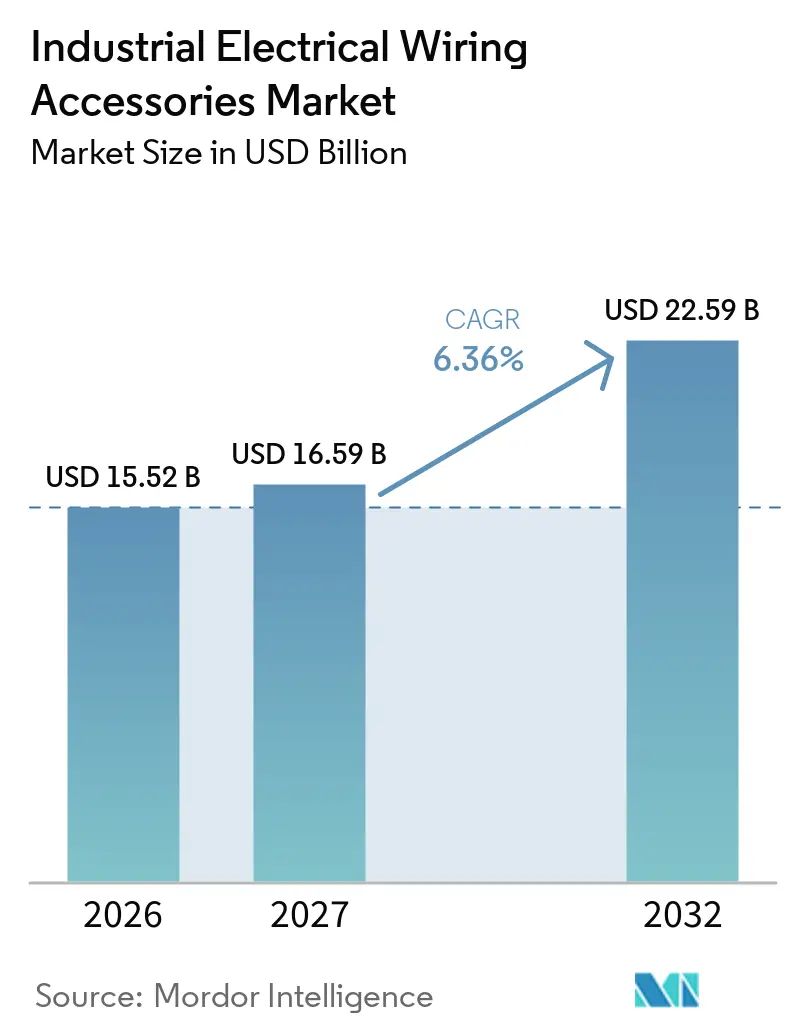
The Industrial Electrical Wiring Accessories Market size is projected to expand from USD 15.52 billion in 2026 and USD 16.59 billion in 2027 to USD 22.59 billion by 2032, at a CAGR of 6.36% between 2027 and 2032. Industrial automation, grid renewal, data center construction, and renewable power projects are widening the installed base that needs switches, connectors, cable glands, conduits, and related equipment. New projects require higher wiring density and stronger protection against vibration, moisture, heat, and electrical faults. This shifts purchasing toward certified products that can operate in demanding industrial settings. Suppliers with broad certification coverage, digital features, and local availability can protect pricing in the industrial electrical wiring accessories market. Cost pressure from metals and the need to meet different national standards still limit the ability of smaller suppliers to compete across regions.
Key Report Takeaways
- By product type, switches held 24.3% share in 2025, while switch socket combinations are expected to grow at a CAGR of 6.5% through 2032.
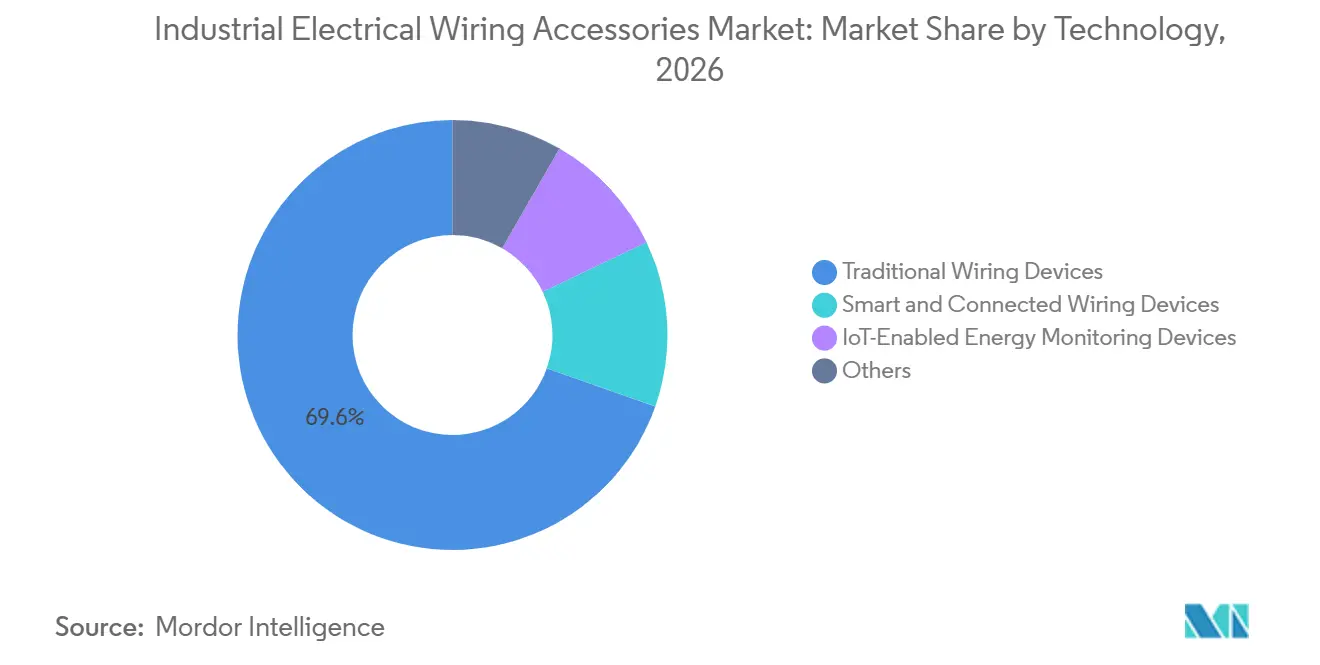
- By technology, traditional devices held 69.6% share in 2025, while smart and connected devices are projected to record the highest CAGR at 9.2% through 2032.
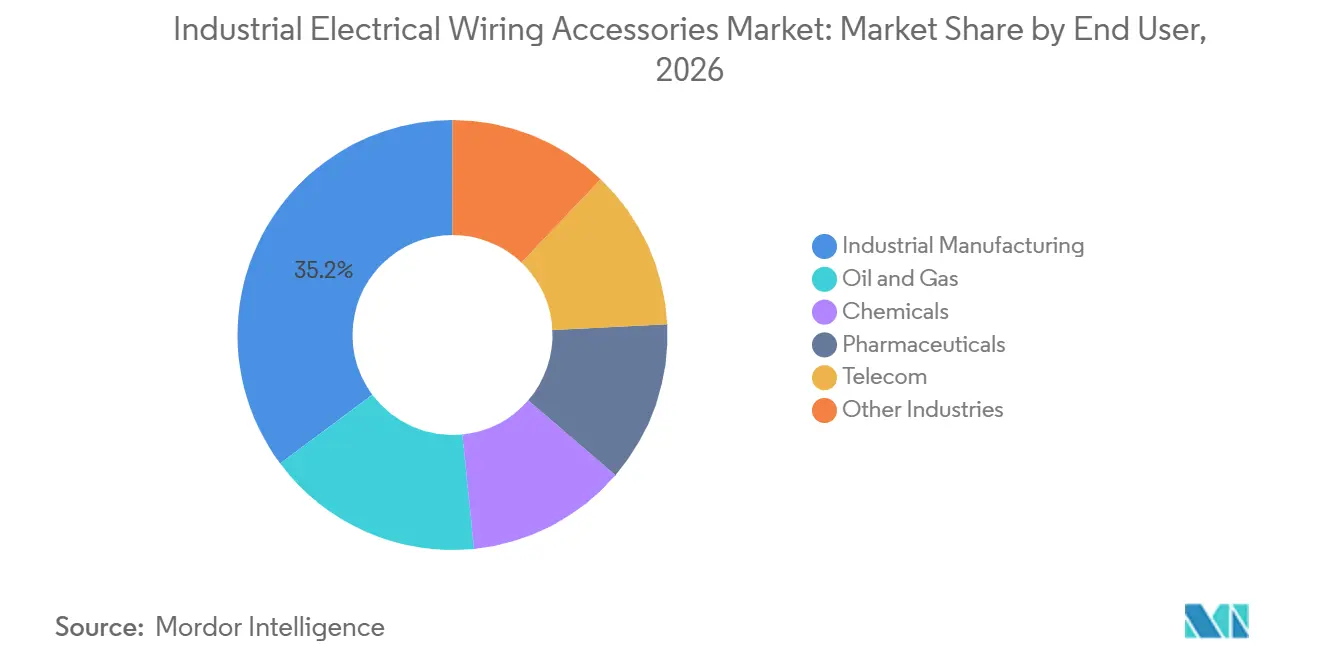
- By end user, industrial manufacturing held 35.2% share in 2025, while pharmaceuticals are projected to record the highest CAGR at 8.1% through 2032.
- By geography, the Asia Pacific held 39.4% share in 2025 and is projected to record the highest CAGR at 7.3% through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Industrial Electrical Wiring Accessories Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Industrial Automation and Industry 4.0 Adoption | +1.50% | Global; core concentration in China, Germany, United States, Japan, South Korea | Short term (≤ 2 years) |
| Grid Modernization and Electrification Investment | +1.30% | North America, Europe, APAC; spill-over to Middle East and Africa | Medium term (2–4 years) |
| Renewable Energy and Energy Storage Deployment | +0.90% | APAC dominant; expanding to Europe, North America, MEA | Medium term (2–4 years) |
| Expansion of Data Centers and High-Density Electrical Infrastructure | +1.20% | North America primary; APAC and Europe secondary | Short term (≤ 2 years) |
| Demand for Certified Harsh-Environment and Hazardous-Location Devices | +0.70% | Global; strongest in MEA oil/gas, APAC chemical clusters, North America LNG facilities | Long term (≥ 4 years) |
| Retrofit Demand from Aging Industrial Electrical Assets | +0.60% | North America, Europe | Medium term (2–4 years) |
| Source: Mordor Intelligence | |||
Industrial Automation and Industry 4.0 Adoption
Industrial automation raises the number and specification level of wiring points in each production installation. Automated machines need dependable terminations, shielded connectors, and cable glands that can withstand wash down cycles, vibration, and regular maintenance. Control cabinet layouts are moving toward more distributed arrangements as edge computing and connected equipment are adopted. This can reduce the physical footprint of a machine while increasing the number of protected electrical connections required within it. Such design changes provide a clear growth path for the industrial electrical wiring accessories market. The industrial electrical wiring accessories market, therefore, benefits from demand for compact products that support reliable data and power connections in the same operating environment.
Grid Modernization and Electrification Investment
Grid investment creates demand for accessories used across transmission, distribution, industrial interconnection, and supporting control systems. The industrial electrical wiring accessories market gains when infrastructure programs require new switchgear bays, electrical cabinets, and qualified connection products. The U.S. Department of Energy announced USD 5.3 billion for 31 grid improvement projects in 26 states in September 2026, including reconductoring over 1,500 miles of transmission lines and grid-enhancing technologies across nearly 21,000 miles[1]. The Council of the European Union agreed on its position on the European Grids Package in June 2026 to support faster permitting and greater interconnection. Projects of this scale increase demand for certified components around new switchgear, substations, industrial panels, and connection points. Long project schedules also favor suppliers that can maintain product availability and certification support throughout installation and commissioning.
Expansion of Data Centers and High Density Electrical Infrastructure
Data center construction creates concentrated demand for cable entry systems, cable glands, circuit protection, and closely managed wiring paths. The global data center wire and cable market was stated at USD 22.6 billion in 2026 and is forecast to reach USD 32.9 billion by 2031, which indicates the scale of the related electrical buildout. Southwire committed more than USD 2 billion to modernize capacity for data center electrical demand, including a USD 256 million expansion in Starkville, Mississippi[2]. Dense project activity in Northern Virginia, Singapore, Frankfurt, and Tokyo rewards suppliers that can provide local stock, technical service, and approved products without disruption. This requirement supports higher value sales in the industrial electrical wiring accessories market because electrical uptime and installation quality are central to data center operations.
Certified Harsh Environment and Hazardous Location Device Demand
Utility-scale solar, wind, and battery projects require products that differ from standard factory accessories. Outdoor systems need connectors and cable glands that resist ultraviolet exposure, corrosion, water ingress, and high direct current voltage. Amphenol Industrial Operations expanded its H4 Plus connector family with a 2,000V DC product in 2026, reflecting the higher voltage requirements of utility-scale photovoltaic systems[3]. This direction raises the importance of product testing and application-specific certification for suppliers serving renewable installations. It also gives established manufacturers an opportunity to offer higher specification products for solar and storage projects rather than relying only on conventional industrial demand.
Restraints Impact Analysis of Industrial Electrical Wiring Accessories Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Volatility in Copper, Brass, Aluminum, and Engineering-Polymer Costs | -0.80% | Global; most acute in North America and APAC manufacturing hubs | Short term (≤ 2 years) |
| Fragmented Standards and Country-Specific Certification Requirements | -0.50% | Global; most pronounced in APAC, MEA, and Latin America | Long term (≥ 4 years) |
| Counterfeit and Non-Compliant Products in Price-Sensitive Channels | -0.40% | APAC, MEA, South America; spill-over to Eastern European distribution | Medium term (2–4 years) |
| Cybersecurity and Firmware-Update Liability for Connected Devices | -0.30% | Global; concentrated risk in North America and Europe | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Copper, Brass, Aluminum, and Engineering Polymer Cost Volatility
Material costs have become an important constraint for suppliers that assemble products from purchased conductors, metal housings, and engineered polymers. Copper, brass, aluminum, and polymers affect the cost of connectors, cable glands, conduits, terminals, and related accessories. Suppliers with long-term supply arrangements or integrated conductor operations have more protection against short-term input changes. Smaller assemblers that purchase materials on the spot market can face frequent changes in bid costs and margins. The industrial electrical wiring accessories market needs a reliable material supply to preserve product availability and pricing. The resulting difference in cost control can affect product availability and pricing across the industrial electrical wiring accessories market.
Fragmented Standards and Country Specific Certification Requirements
Different safety and product approval systems can delay launches and increase testing costs for a supplier operating across several countries. Hazardous location products may need to meet separate requirements under IECEx, ATEX, and U.S. electrical frameworks. The IEC published Edition 8 of IEC 60079-0 in June 2026, adding requirements that affect factory wiring between enclosures, plugs, sockets, cable glands, and temperature marking in explosive atmospheres[4]. These requirements make certification expertise a purchasing advantage for companies that serve oil and gas, chemical, pharmaceutical, and other high-risk facilities. They also place a larger administrative and testing burden on smaller manufacturers with limited compliance resources.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Industrial Electrical Wiring Accessories Market Segment Analysis
By Product Type:
Switches Lead Volume While Combinations Gain Specification GroundSwitches held 24.3% of the industrial electrical wiring accessories market share in 2025 because they are used across panel boards, motor control centers, and machinery enclosures. Rotary cam, selector, push button, and limit switch products support a wide range of industrial control tasks. Their use across many verticals produces replacement demand as equipment is upgraded or maintained. The breadth of the category also allows suppliers to offer several ratings and enclosure options for different operating conditions. Switch socket combinations are forecast to grow at a 6.5% CAGR through 2032 as compact cabinet designs seek to reduce installation space and the number of wiring entry points.
Switch socket combinations also reduce the assembly steps needed within space-limited panels and machine enclosures. Schneider Electric selected Weidmüller SNAP IN connection technology for a new TeSys motor control series in June 2026, with the companies stating that it can cut installation time by up to 75%. Sockets and receptacles, plugs and adapters, connectors and terminals, and cable management products continue to address different application needs. IEC 60309 pin and sleeve devices remain relevant where wet or demanding locations require protected multi-rated connections. Cable glands and conduits support project volume in chemical plants, oil and gas sites, and data center construction, where cable routing and sealing are part of the installation scope.
By Technology:
Traditional Devices Retain Volume While Smart Penetration AcceleratesTraditional devices accounted for 69.6% share in 2025, supported by long replacement cycles in established industrial facilities. Many plants in North America and Europe still use systems installed before connected equipment became a standard procurement requirement. These sites need compatible replacements that fit existing conduits, panel dimensions, and operating practices. Traditional products, therefore, retain a large role in maintenance and retrofit spending. The industrial electrical wiring accessories market can retain steady replacement demand even as smart and connected devices advance at a 9.2% CAGR through 2032.
Connected devices can provide circuit-level information that feeds energy management systems and maintenance decisions. This changes the value proposition from a single physical component to a product that can support monitoring and control. IEC PAS 62443-1-6:2025 provides an IEC framework for applying industrial cybersecurity requirements to IIoT applications. Compliance expectations create additional development and support requirements for manufacturers selling connected accessories to regulated industrial customers. Established suppliers that can support secure product updates and vulnerability management are better placed to meet those expectations.
By End User:
Industrial Manufacturing Anchors Demand While Pharmaceuticals Raise Specification RequirementsIndustrial manufacturing represented 35.2% share in 2025, reflecting the size of its installed equipment base and ongoing replacement needs. Automotive, electronics, food and beverage, and heavy industry each use electrical control and connection products across production lines. Equipment changes in automotive and electronics can lead to broad upgrades of machinery, panels, and power distribution systems. This maintains demand for switches, cable glands, terminals, conduits, and certified protection components. The industrial electrical wiring accessories market gains from this broad replacement base, while pharmaceuticals are expected to post an 8.1% CAGR through 2032 because cleanroom and controlled production environments require more stringent electrical equipment specifications.
Pharmaceutical facilities need wiring products that can support cleanable surfaces, protected enclosures, controlled contamination risk, and documented operating standards. Electrical installations in these sites may require stainless steel cable tray systems, appropriate enclosure ratings, and products that match cleanroom requirements. This creates a higher specification purchasing environment than general industrial construction. Oil and gas and chemicals also support demand for certified accessories because hazardous area protection is central to site design. Telecom, mining, water treatment, and transportation projects add further demand for the industrial electrical wiring accessories market through cable management, base station installations, process equipment, and infrastructure upgrades.
Geography Analysis
APAC Industrial Electrical Wiring Accessories Market
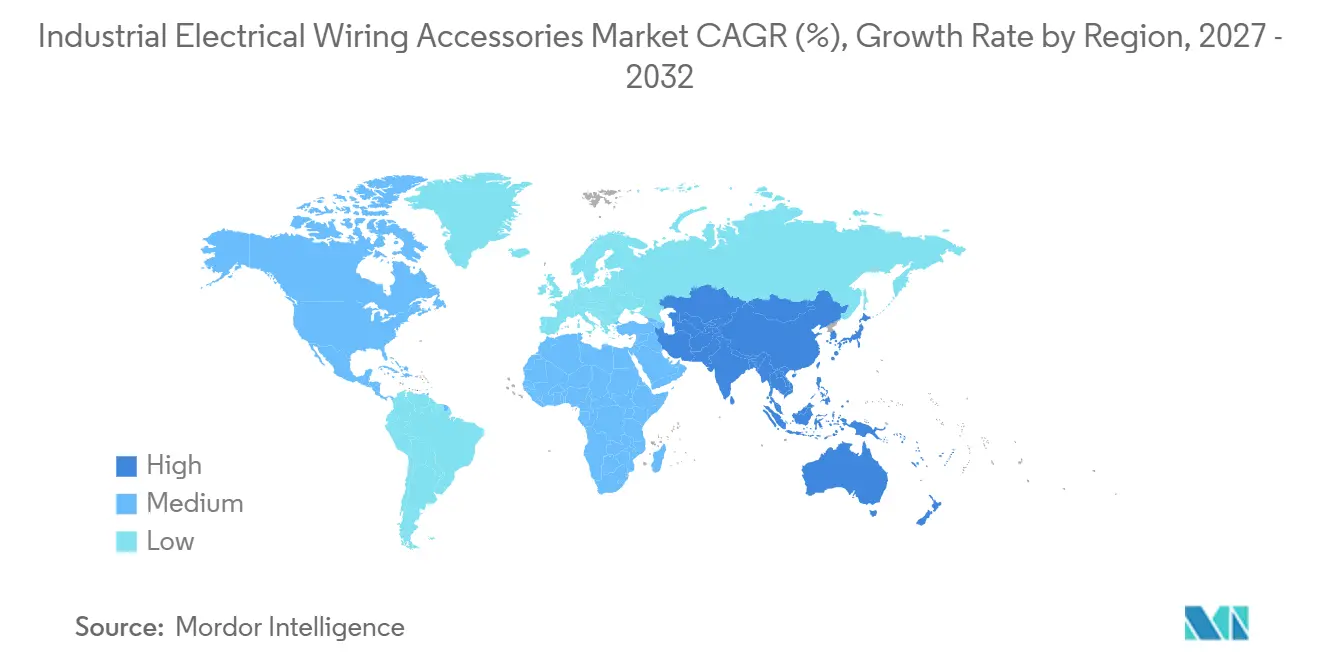
Asia Pacific accounted for 39.4% of the industrial electrical wiring accessories market share in 2025 and is forecast to grow at a 7.3% CAGR through 2032. China, India, and Southeast Asia combine industrial expansion with investment in power systems and manufacturing capacity. China is directing investment toward renewable integration, grid digitalization, and industrial electrification, which require extensive electrical connections and protection equipment. ABB stated in 2026 that it planned to invest USD 75 million in India after spending USD 35 million in 2025, reflecting supplier interest in the country’s industrial and power demand. Manufacturing diversification in Vietnam, Indonesia, and Thailand supports both initial electrical fit-out and replacement demand for standardized and higher specification devices.
North America and Europe Industrial Electrical Wiring Accessories Market
North America and Europe are mature regions, but both continue to modernize industrial and electricity assets. The U.S. Department of Energy’s 2026 grid funding supports replacement and expansion activity across transmission systems and related facilities. In Europe, the Council’s 2026 position on the European Grids Package supports grid modernization and interconnection. These markets favor products that support retrofit work, safety compliance, energy monitoring, and modernized electrical control systems in the industrial electrical wiring accessories market. Local channel coverage and country specific compliance support remain important because these markets combine replacement work with new investment.
MEA and South America Industrial Electrical Wiring Accessories Market
South America and the Middle East and Africa offer lower overall volumes but have targeted demand opportunities. Brazil supports regional activity through petrochemicals and energy transition investment. Gulf markets continue to invest in downstream oil and gas, industrial diversification, and related infrastructure that requires ATEX and IECEx certified devices. Countries outside South Africa and Morocco are at earlier stages of industrial electrification, but industrial zones and data center projects create selected opportunities for the industrial electrical wiring accessories market through suppliers with appropriate distribution coverage.
Competitive Landscape
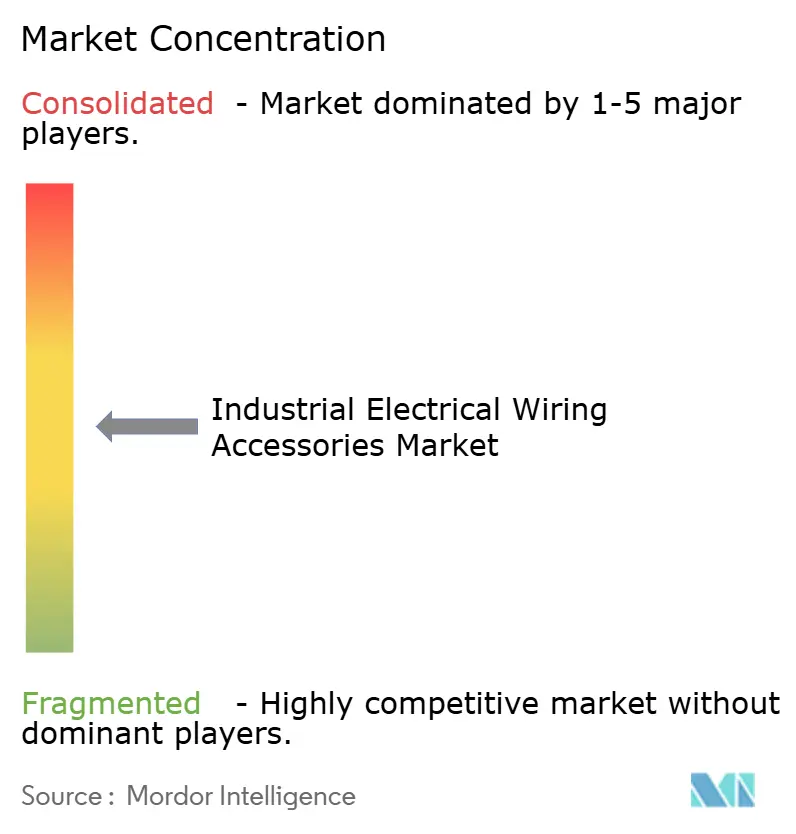
The industrial electrical wiring accessories market has moderate concentration in the premium tier. Schneider Electric, ABB, Legrand, Eaton, Siemens, and Hubbell compete through certification coverage, digital integration, product breadth, and distribution reach. Their position is stronger in applications where site owners place a high value on technical support and documented compliance. Mid-market and price-sensitive channels are more fragmented because regional assemblers can compete on basic product availability and lower prices. This creates a clear difference between premium applications and standardized replacement demand.
Hubbell completed its USD 3.0 billion acquisition of NSI Industries in June 2026, adding more than 15,000 branded products and access to more than 2,000 North American distributors. The move expanded Hubbell’s product range and distribution access in electrical markets. Schneider Electric’s use of SNAP IN technology in its TeSys series shows the parallel focus on reducing installation time through product design. Siemens expanded its SENTRON ECPD range in March 2026 with residual current monitoring that supports continuous fault monitoring in applications such as data centers, pharmaceuticals, conveyors, elevators, and uninterruptible power systems.
The competitive focus is moving beyond basic switches and sockets toward products that combine protection, monitoring, and connection functions. Digital features can make a component more valuable where users need energy data and early fault detection. Connected products also introduce security and update responsibilities, which favor suppliers with established engineering and compliance resources. Specialists such as Marechal Electric, MENNEKES, SCAME, WAGO, and Weidmüller remain competitive in narrow product areas where application knowledge and certification depth are important. Their selective product focus limits direct price comparison with full line providers in the industrial electrical wiring accessories market.
Industrial Electrical Wiring Accessories Industry Leaders
-
Schneider Electric SE
-
ABB Ltd.
-
Legrand SA
-
Siemens AG
-
Eaton Corporation plc
- *Disclaimer: Major Players sorted in no particular order
Industrial Electrical Wiring Accessories Market Companies Covered in this Report
- ABB Ltd.
- Amphenol Corporation
- Atkore Inc.
- Eaton Corporation plc
- Emerson Electric Co.
- Gewiss S.p.A.
- Hager Group
- HellermannTyton Group
- Honeywell International Inc.
- Hubbell Incorporated
- Legrand SA
- Leviton Manufacturing Co., Inc.
- Lutron Electronics Co., Inc.
- Marechal Electric Group
- MENNEKES Elektrotechnik GmbH and Co. KG
- Molex LLC
- OBO Bettermann Holding GmbH and Co. KG
- Panduit Corp.
- Phoenix Contact GmbH and Co. KG
- SCAME Group S.p.A.
- Schneider Electric SE
- Siemens AG
- TE Connectivity Ltd.
- WAGO Kontakttechnik GmbH and Co. KG
- Weidmüller Interface GmbH and Co. KG
Recent Industry Developments in Industrial Electrical Wiring Accessories Market
- June 2026: Hubbell Incorporated completed its USD 3.0 billion acquisition of NSI Industries, adding over 15,000 branded electrical products, including Bridgeport fittings, Polaris connectors, and Tork timers, and access to more than 2,000 North American distributors.
- June 2026: Schneider Electric selected Weidmüller’s SNAP IN toolless connection technology for its new TeSys series of motor control products, enabling original equipment manufacturers and panel builders in North America to cut motor control installation time by up to 75%.
- March 2026: Siemens announced the expanded SENTRON ECPD with integrated residual current monitoring, enabling 24/7 leakage current surveillance without downtime. A three-phase 400V version targets conveyor, elevator, and uninterruptible power supply applications.
- February 2026: Legrand announced the acquisition of Kratos Industries alongside a strategic investment in Accelsius for two-phase liquid cooling technology, advancing Legrand’s data center power infrastructure strategy.
Global Industrial Electrical Wiring Accessories Market Report Scope
Industrial electrical wiring accessories are components used to connect, control, protect, route, and secure electrical wiring systems in industrial facilities such as manufacturing plants, factories, oil and gas facilities, warehouses, and processing plants. These accessories include cable glands, cable lugs, connectors, junction boxes, conduits, wiring ducts, terminal blocks, cable ties, and industrial switches and sockets. They ensure safe, reliable, and organized electrical connections while supporting efficient power distribution, equipment operation, and compliance with industrial electrical safety standards.
The Industrial Electrical Wiring Accessories Market is segmented by product type, technology, end user, and geography. By product type, the market is segmented into switches, sockets, plugs, switch-socket combinations, connectors, cable glands, conduits, and other products. By technology, the market is segmented into traditional, smart and connected, IoT-enabled, and other technologies. By end user, the market is segmented into manufacturing, oil and gas, chemicals, pharmaceuticals, telecommunications, and other industries. The report also covers the market size and forecasts for the global industrial electrical wiring accessories market across 26 countries in key regions. For each segment, market sizing and forecasts are provided on the basis of value (USD).
Segmentation Overview
| Switches |
| Sockets and Receptacles |
| Plugs and Adapters |
| Switch-Socket Combinations |
| Connectors and Terminals |
| Cable Glands and Cable Fittings |
| Conduits and Conduit Fittings |
| Extension Leads and Power Strips |
| Other Wiring Accessories |
| Traditional Wiring Devices |
| Smart and Connected Wiring Devices |
| IoT-Enabled Energy Monitoring Devices |
| Others |
| Industrial Manufacturing |
| Oil and Gas |
| Chemicals |
| Pharmaceuticals |
| Telecom |
| Other Industries |
| North America | United States |
| Canada | |
| Mexico | |
| Europe | Germany |
| France | |
| Italy | |
| Spain | |
| United Kingdom | |
| Poland | |
| Russia | |
| Rest of Europe | |
| Asia-Pacific | China |
| India | |
| Japan | |
| South Korea | |
| Australia | |
| Indonesia | |
| Vietnam | |
| Thailand | |
| Rest of Asia-Pacific | |
| South America | Brazil |
| Argentina | |
| Chile | |
| Rest of South America | |
| Middle East and Africa | Saudi Arabia |
| United Arab Emirates | |
| Egypt | |
| South Africa | |
| Morocco | |
| Rest of Middle East and Africa |
| By Product Type | Switches | |
| Sockets and Receptacles | ||
| Plugs and Adapters | ||
| Switch-Socket Combinations | ||
| Connectors and Terminals | ||
| Cable Glands and Cable Fittings | ||
| Conduits and Conduit Fittings | ||
| Extension Leads and Power Strips | ||
| Other Wiring Accessories | ||
| By Technology | Traditional Wiring Devices | |
| Smart and Connected Wiring Devices | ||
| IoT-Enabled Energy Monitoring Devices | ||
| Others | ||
| By End User | Industrial Manufacturing | |
| Oil and Gas | ||
| Chemicals | ||
| Pharmaceuticals | ||
| Telecom | ||
| Other Industries | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| Europe | Germany | |
| France | ||
| Italy | ||
| Spain | ||
| United Kingdom | ||
| Poland | ||
| Russia | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| India | ||
| Japan | ||
| South Korea | ||
| Australia | ||
| Indonesia | ||
| Vietnam | ||
| Thailand | ||
| Rest of Asia-Pacific | ||
| South America | Brazil | |
| Argentina | ||
| Chile | ||
| Rest of South America | ||
| Middle East and Africa | Saudi Arabia | |
| United Arab Emirates | ||
| Egypt | ||
| South Africa | ||
| Morocco | ||
| Rest of Middle East and Africa | ||
Key Questions Answered in the Report
What is driving demand for industrial electrical wiring accessories?
Industrial automation, grid modernization, data center construction, and renewable energy projects are increasing demand for connection, protection, and cable management products.
How large is the industrial electrical wiring accessories market?
The industrial electrical wiring accessories market is projected to reach USD 22.59 billion by 2032, growing at a 6.36% CAGR from 2027 to 2032.
Which product category leads industrial electrical wiring accessories sales?
Switches led with a 24.3% share in 2025 because they are widely used in panel boards, machinery enclosures, and motor control centers.
Why are smart and connected wiring devices growing quickly?
Smart and connected devices are forecast to grow at a 9.2% CAGR through 2032 because industrial users need energy monitoring, predictive maintenance support, and connected control systems.
Which region has the strongest outlook for industrial electrical wiring accessories?
Asia Pacific held 39.4% of sales in 2025 and is forecast to grow at a 7.3% CAGR through 2032, supported by manufacturing, power, and infrastructure investment.
Which end user is expected to grow the fastest?
Pharmaceuticals are projected to grow at an 8.1% CAGR through 2032 because controlled manufacturing environments require higher specification electrical equipment.