
Grafted Polyolefins Market Size and Share
Market Overview
| Study Period | 2022 - 2032 |
|---|---|
| Market Size (2027) | USD 4.38 Billion |
| Market Size (2032) | USD 5.56 Billion |
| Growth Rate (2027 - 2032) | 4.87 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | Asia-Pacific |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Grafted Polyolefins Market Analysis by Mordor Intelligence
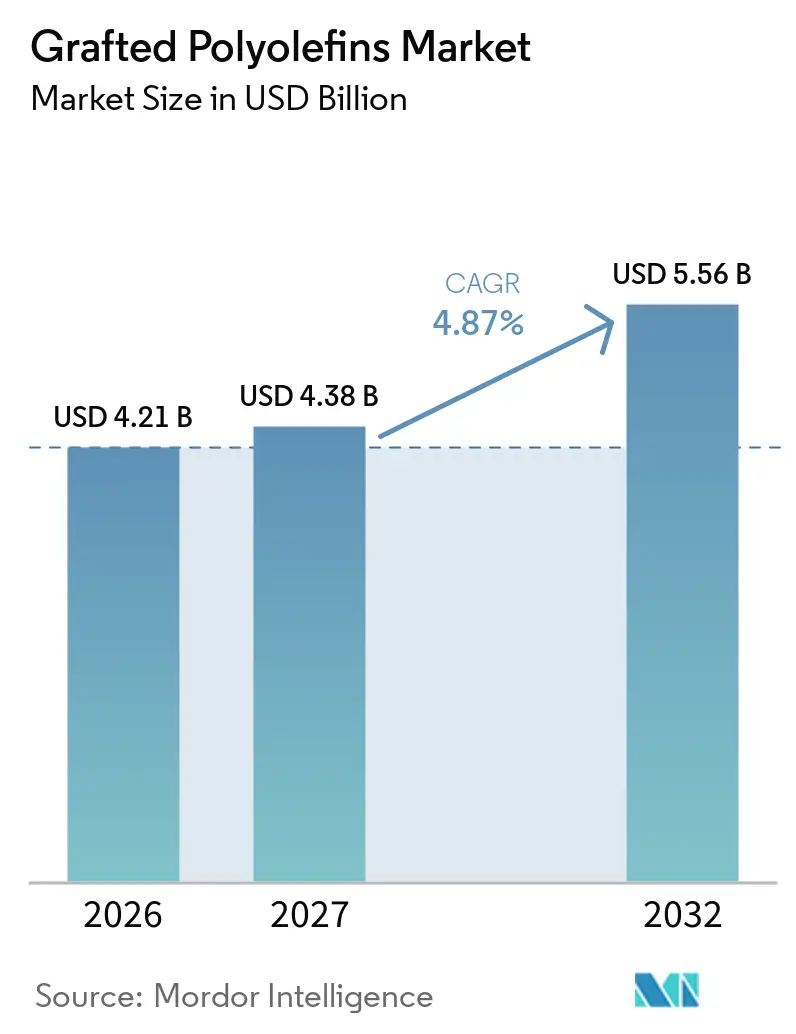
The Grafted Polyolefins Market size was valued at USD 4.21 billion in 2026 and is estimated to grow from USD 4.38 billion in 2027 to reach USD 5.56 billion by 2032, at a CAGR of 4.87% during the forecast period (2027-2032). The grafted polyolefins market is supported by the need to bond materials that would otherwise separate in multilayer films, polymer compounds, and coated components. Demand also benefits from lighter vehicle designs and from packaging formats that require barrier layers. Circular material targets are increasing the need for compatibilizers that improve the performance of mixed recycled polyethylene and polypropylene streams. Producers are differentiating through grades designed for recycling, automotive compounds, and demanding film applications. Asia-Pacific remains central to the grafted polyolefins market because it combines polymer processing, vehicle manufacturing, packaging conversion, and new petrochemical capacity.
Key Report Takeaways
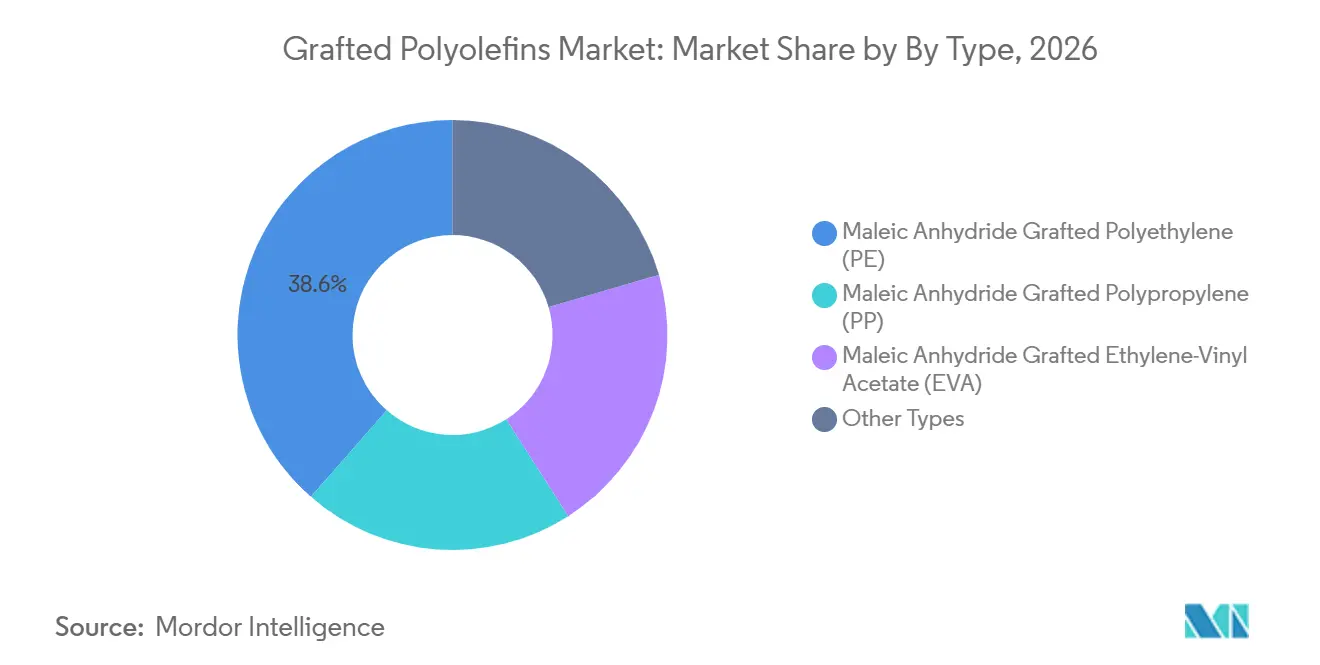
- By type, maleic anhydride grafted polyethylene (PE) held 38.56% of the grafted polyolefins market share in 2026, while maleic anhydride grafted polypropylene (PP) is forecast to advance at a 5.21% CAGR through 2032.
- By application, adhesion promotion held 31.12% of the grafted polyolefins market share in 2026, while compatibilization is forecast to advance at a 5.34% CAGR through 2032.
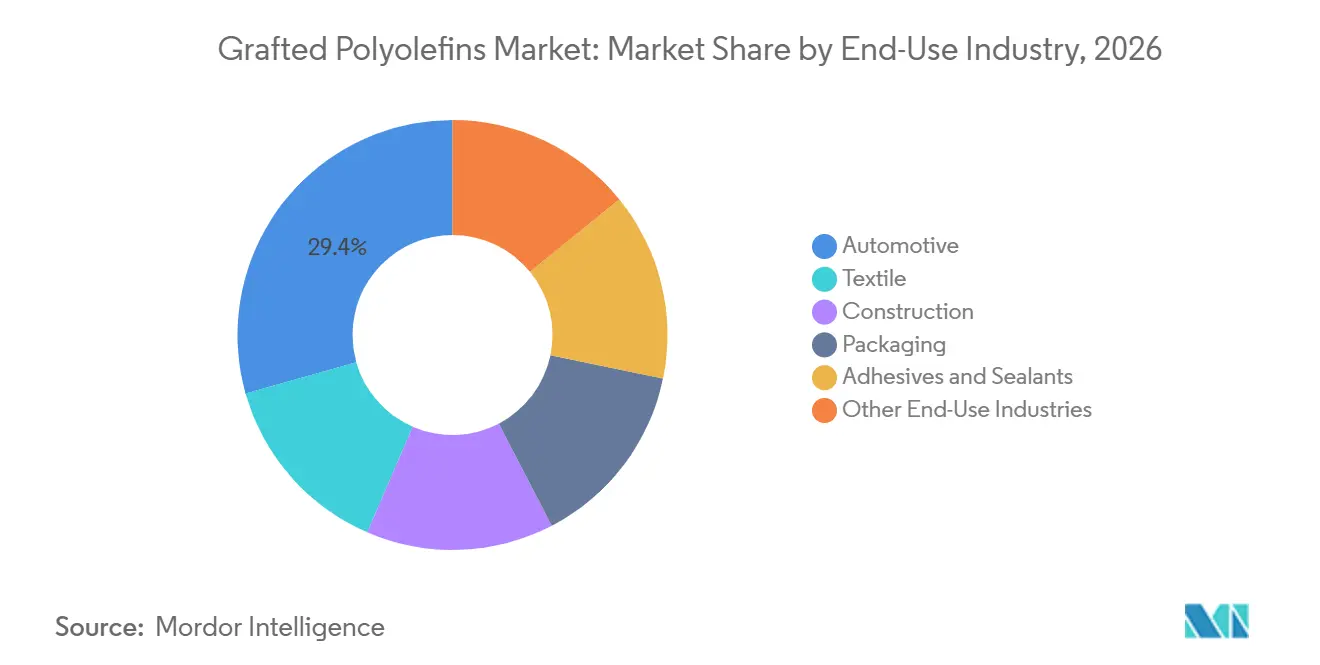
- By end-use industry, automotive held 29.38% of the grafted polyolefins market share in 2026 and is forecast to advance at a 5.86% CAGR through 2032.
- By geography, Asia-Pacific held 45.86% of the grafted polyolefins market share in 2026 and is forecast to advance at a 5.73% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Grafted Polyolefins Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Automotive Lightweighting and EV Material Substitution | +1.8% | Global, with core demand in China, Germany, and South Korea | Long term (≥ 4 years) |
| Multilayer Packaging and Tie-Layer Demand | +1.2% | Global; strongest in Asia-Pacific and North America | Medium term (2–4 years) |
| Recycled-Polyolefin Compatibilization | +0.9% | EU-led, spilling over to North America and APAC | Medium term (2–4 years) |
| Expansion of Plastics Processing in Asia-Pacific | +0.6% | APAC core; spillover to MEA and South America | Long term (≥ 4 years) |
| Digital Control of Reactive Extrusion | +0.3% | Global, initially concentrated in Europe and North America | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Automotive Lightweighting and EV Material Substitution
Electric vehicle adoption is creating a stronger need for materials that link polypropylene with glass fibers and other polar fillers. Global electric-car sales exceeded 20 million units in 2025 and represented more than 25% of car sales worldwide[1]. Maleic anhydride grafted polyethylene and polypropylene support bonding within battery enclosures, underbody shields, and high-voltage connector housings. Electric vehicles use more polymer composites than comparable internal-combustion vehicles, raising grafted-material demand per vehicle. Natural-fiber interior panels create a related opportunity because grafted polypropylene can improve the bond between cellulosic fibers and the polymer matrix. The grafted polyolefins market, therefore, benefits when vehicle programs move from metal parts toward reinforced or recycled polymer assemblies.
Multilayer Packaging and Tie-Layer Demand
Multilayer flexible packaging is a major outlet because food packs often need oxygen and moisture barriers. Maleic anhydride grafted polyethylene is used as a tie layer between polyolefin substrates and ethylene vinyl alcohol (EVOH) or polyamide barrier layers. This chemistry can be effective at low layer loadings, while still influencing pack integrity through thermal processing. Regulation (EU) 2025/40 sets recycled-content requirements for plastic packaging from 2030, ranging from 10% to 35% by packaging category, with higher requirements for 2040[2]. These requirements support work on film structures that can balance barrier performance, recycled content, and later separation. LyondellBasell Industries Holdings B.V. added Plexar PX3990, a tie-layer grade for oriented-film applications, to its portfolio in 2025.
Recycled-Polyolefin Compatibilization
Mixed polyethylene and polypropylene recyclate can lose strength and impact resistance when the two phases do not bond effectively. Research published in 2025 described a graft-copolymer route that compatibilizes polyethylene and polypropylene blends at loadings as low as 2.5 wt%. Grafted polyolefins reduce the mismatch between these polymers and can improve the usable quality of the recycled blend. The grafted polyolefins market gains from this need because recycled-content targets create a practical reason to qualify compatibilizer grades before regulations apply. Toyoda Gosei reported a 2026 horizontal-recycling technology that uses polypropylene recovered from end-of-life vehicles in new automotive parts at more than 50% post-consumer recycled content. The same material needs extend from mechanical recycling to preparation steps for some chemical-recycling feedstocks.
Expansion of Plastics Processing in Asia-Pacific
Asia-Pacific held 45.86% of the grafted polyolefins market share in 2026, supported by its broad polymer-processing base. New upstream capacity can improve local access to the ethylene and propylene used in polyolefin production. BASF reached mechanical completion of the steam cracker and downstream plants at its Zhanjiang Verbund site in October 2025, including a steam cracker with an annual ethylene capacity of 1 million metric tons. Greater local availability can support compounders that formulate maleic anhydride grafted polypropylene and polyethylene grades. China, Japan, South Korea, India, and ASEAN markets each add demand through different combinations of vehicles, electronics, packaging, and film conversion. Process monitoring and tighter extrusion control can also improve consistency at plants that are moving into higher-performance grades.
Restraints Impact Analysis of Grafted Polyolefins Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Formulation Cost Premium and Feedstock Volatility | -0.5% | Global, most acute in Europe and Northeast Asia | Short term (≤ 2 years) |
| Long OEM Qualification and Validation Cycles | -0.4% | Global; primarily affecting automotive and aerospace end-use | Long term (≥ 4 years) |
| Variable Recyclate Composition and Process Stability | -0.3% | EU and North America | Medium term (2–4 years) |
| Source: Mordor Intelligence | |||
Formulation Cost Premium and Feedstock Volatility
Grafted grades cost more than base polyolefins because they require functionalization and tighter process control. The cost gap is influenced by maleic anhydride prices and the markets for n-butane and benzene feedstocks. A change in regional capacity, trade flows, or upstream demand can still affect contracts for specialty grades. Producers that import maleic anhydride have less flexibility when their downstream customers require fixed-price supply agreements. The grafted polyolefins market can therefore face uneven margins even when end-use demand remains stable.
Long OEM Qualification and Validation Cycles
Automotive customers assess new polymer grades through extended thermal-aging, ultraviolet-resistance, dimensional-stability, and crash-performance testing. The process can take 24 to 36 months for automotive applications. That timing delays growth for new battery-enclosure and connector grades. Dual-sourcing requirements increase the challenge because another qualified supplier may be needed for the same material. Smaller suppliers can be at a disadvantage when established producers already have approvals across vehicle platforms. Packaging-grade materials can move faster because their qualification cycle is shorter, allowing the grafted polyolefins market to capture recycling-related packaging demand sooner.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Grafted Polyolefins Market Segment Analysis
By Type:
Maleic Anhydride Grafted Polyethylene (PE) Leads Revenue, While Maleic Anhydride Grafted Polypropylene (PP) ExpandsMaleic anhydride grafted polyethylene accounted for 38.56% of the grafted polyolefins market share in 2026. Its adhesion properties support tie layers in multilayer films, cable jacketing, and mineral-filled polyolefin compounds. It is compatible with EVOH and polyamide barrier layers used in packaging structures. Its lower melting point can also suit a wide installed base of coextrusion equipment. Maleic anhydride grafted ethylene-vinyl acetate serves applications that require low-temperature flexibility. Its ester content can improve bonding to polar substrates in hot-melt adhesives and specialty laminates. Other types include functionalized polyolefin elastomers and silane-grafted grades. These materials are used in wire and cable products and moisture-crosslinking applications.
Maleic anhydride grafted polypropylene is the fastest-growing type, and its grafted polyolefins market size is projected to increase at a 5.21% CAGR through 2032. Its higher service temperature supports use in glass-fiber and mineral-reinforced polypropylene compounds. These compounds are relevant to automotive structural parts, under-hood systems, and battery enclosures. The material can also bridge the mismatch between natural fibers and polypropylene in vehicle interior panels. COACE Chemical Company Limited presented polypropylene-graft-maleic anhydride (PP-g-MAH) at CHINAPLAS 2026 and provided formulation consultations for automotive, packaging, and construction customers. The 2025 American Chemical Society (ACS) study on graft copolymers supports continued work on compatibility in recycled polyethylene and polypropylene blends. This gives polypropylene-based grafted grades exposure to both vehicle compounds and recycled-material applications.

By Application:
Adhesion Promotion Leads Revenue, While Compatibilization Expands FasterAdhesion promotion accounted for 31.12% of the grafted polyolefins market share in 2026. It remains important in coextruded packaging films and painted automotive exterior panels. In these uses, the material helps connect a polyolefin substrate with a more polar layer or finish. Bonding is a related application in hot-melt adhesives and laminate adhesives for construction and specialty industrial products. Tighter limits on solvent-based adhesives support interest in alternatives based on polymer formulations. Impact modification uses grafted polyolefin elastomers in polyamide and polypropylene systems that require better low-temperature toughness. Wire and cable coupling, wood-plastic composites, and textile bonding are included in other applications. These uses broaden the addressable base beyond packaging and automotive parts.
Compatibilization is the fastest-growing application, with the grafted polyolefins market size forecast to advance at a 5.34% CAGR through 2032. Regulation (EU) 2025/40 establishes a clear direction for recycled content in plastic packaging. Mixed post-consumer polyethylene and polypropylene streams require chemical support if they are to achieve more consistent performance. Grafted compatibilizers are a viable option at industrial throughput because they improve bonding between otherwise separate polymer phases. The use case applies to established mechanical recycling as well as some chemical-recycling preparation steps. Demand is therefore linked not only to the quantity of recycled material but also to the quality level required by converters. The grafted polyolefins market is positioned to benefit as higher-value recycled applications move beyond simple downcycling.
By End-Use Industry:
Automotive Combines Scale and Faster GrowthAutomotive held 29.38% of the market share in 2026 and is forecast to grow at a 5.86% CAGR through 2032. Electric vehicle components use reinforced polypropylene in battery enclosures, high-voltage connectors, thermal-management systems, and structural subframes. Japan's Environment Research and Conservation Agency stated in 2025 that automotive interior parts can technically use up to 25% recycled polypropylene under current automotive standards. This supports a broader role for compatibilization inside automotive applications. Qualification requirements remain important because materials must meet stringent functional and safety expectations.
Packaging provides a steady demand base through multilayer films for food, pharmaceutical, and industrial applications. Tie-layer grades help preserve the structure of films that combine materials with different properties. Textile applications use grafted polyolefins for fiber-to-matrix bonding in nonwoven composites and technical textiles. The polar functionality can support dye uptake and lamination adhesion in these materials. Adhesives and sealants require performance-critical formulations. Construction applications include material combinations where strong joining and resistance to service conditions are important. These varied applications reduce dependence on a single demand center. They also create opportunities for the grafted polyolefins market, where customers need tailored grades rather than standard base resins.
Geography Analysis
APAC Grafted Polyolefins Market
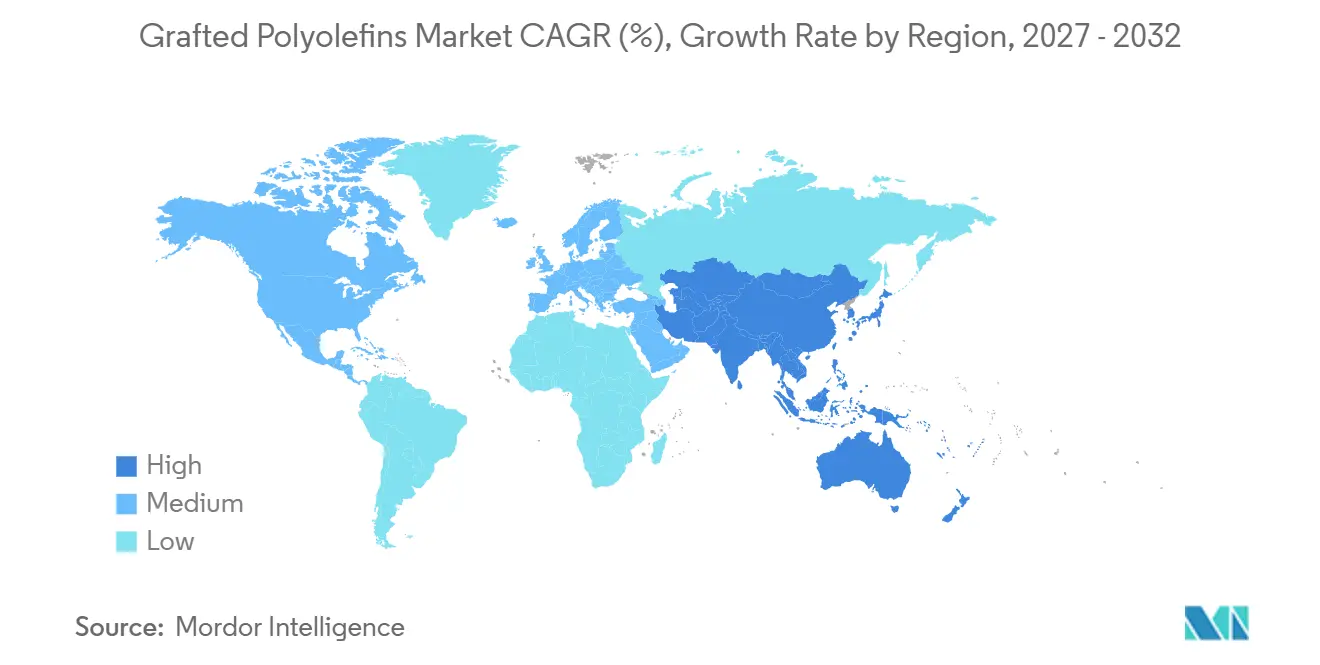
Asia-Pacific accounted for 45.86% of the grafted polyolefins market share in 2026 and is projected to grow at a 5.73% CAGR through 2032. China is a key center for electric-vehicle production, plastics conversion, and polymer compounding. The IEA reported that China accounted for more than 70% of global electric-vehicle production and that electric vehicles approached 60% of its domestic car sales in 2025. India, South Korea, Japan, and ASEAN markets add demand through automotive, packaging, electronics, and high-precision film applications. BASF's completed Zhanjiang project adds to the region's chemical base. Local producers such as Guangzhou Lushan New Materials and COACE compete in mid-performance grades, while international suppliers retain positions in specialized recycling and electric-vehicle applications.
The Americas Grafted Polyolefins Market
North America has a different demand profile that combines packaging, large-vehicle production, and recycled-content obligations. Mexico's electric-vehicle production doubled in 2024 compared with 2023, according to the IEA. This strengthens the regional supply chain for automotive-grade materials. Formosa Plastics USA started a 250,000 metric ton annual polypropylene plant in Point Comfort, Texas, in September 2025 using Japan Polypropylene Corporation's Horizone technology. This adds to the polypropylene base available to downstream compounders. South America remains smaller, with Brazil and Argentina providing emerging demand through packaging and vehicle assembly.
EMEA Grafted Polyolefins Market
Europe is shaped by requirements for circular plastics, and Regulation (EU) 2025/40 requires 10% to 35% post-consumer recycled content in plastic packaging from 2030. Germany, France, Italy, and the United Kingdom remain important for automotive material specifications. The Nordic countries offer applications in bio-based and natural-fiber composites. Borealis GmbH announced more than EUR 100 million of investment in September 2025 to expand and upgrade polypropylene compounding capacity in Schwechat, Austria. The new line is scheduled to start in H2 2026 and targets electric-vehicle lightweighting, recyclable foams, and infrastructure applications. The Middle East and Africa are the smallest regions, but downstream specialty-polymer investment is creating early demand in packaging and infrastructure pipes.
Competitive Landscape
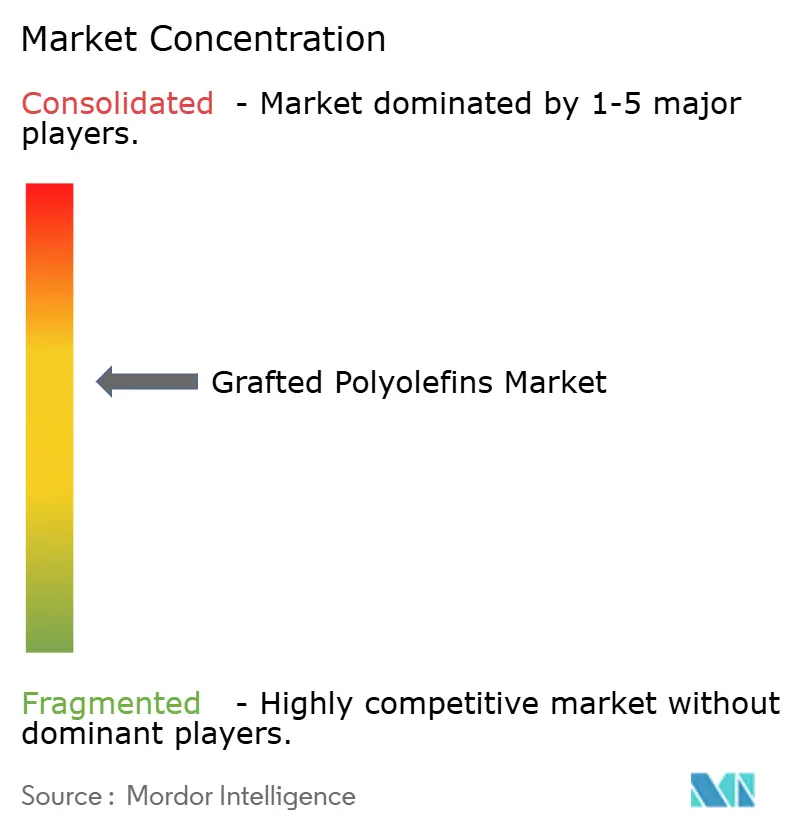
The grafted polyolefins market is moderately concentrated, with the top five players including CLARIANT, Mitsui Chemicals, Inc., Dow, Arkema, and LyondellBasell Industries Holdings B.V. Their portfolios serve applications including automotive parts, multilayer films, and recycled polymer compounds. Regional suppliers such as COACE Chemical Company Limited, Guangzhou Lushan New Materials, and Sanyo Chemical Industries, Ltd. compete through local service and cost positioning. This leaves global suppliers focused on applications that require validated performance, broader approvals, or specialized technical support.
Product and process development are central to competition in the grafted polyolefins market. Dow filed a U.S. patent application in October 2025 for a process using methyl or dimethyl maleic anhydride to reduce yellowing in grafted polyolefins. This quality issue matters in interior automotive trim and medical applications. CLARIANT launched AddWorks PPA in June 2025 as a per- and polyfluoroalkyl substances (PFAS)-free polymer processing-aid line for polyolefin extrusion. The Compound Company represents a related model by selling finished compounds that include grafted polyolefins rather than only the additive. This approach can capture value from both material chemistry and formulation work.
LyondellBasell Industries Holdings B.V. agreed in June 2025 to sell four European olefins and polyolefins assets to AEQUITA as part of its European strategic assessment. The move reflects an emphasis on technology-intensive and higher-value offerings. LyondellBasell Industries Holdings B.V. also licensed multiple polyolefin technologies to Shaanxi Coal and Chemical Industry Group (SHCCIG), Yulin Chemical for a new complex in China. Mitsui Chemicals, Inc., Idemitsu Kosan, and Sumitomo Chemical signed a definitive agreement in December 2025 to integrate Sumitomo Chemical's polypropylene and linear low-density polyethylene businesses into Prime Polymer. These actions show that portfolio choices, licensing, and domestic consolidation are shaping the competitive environment. The grafted polyolefins market remains moderately consolidated among leading international suppliers, while regional specialists maintain relevant positions in local and mid-performance applications.
Grafted Polyolefins Industry Leaders
-
CLARIANT
-
Mitsui Chemicals, Inc.
-
Dow
-
Arkema
-
LyondellBasell Industries Holdings B.V.
- *Disclaimer: Major Players sorted in no particular order
Grafted Polyolefins Market Companies Covered in this Report
- Arkema
- BASF
- Borealis GmbH
- CLARIANT
- COACE Chemical Company Limited
- Dow
- Eastman Chemical Company
- Evonik Industries AG
- Exxon Mobil Corporation
- Guangzhou Lushan New Materials
- LyondellBasell Industries Holdings B.V.
- Mitsui Chemicals, Inc.
- Polyram Plastic Industries Ltd.
- Sanyo Chemical Industries, Ltd.
- The Compound Company
Recent Industry Developments in Grafted Polyolefins Market
- May 2026: COACE Chemical Company Limited showcased its PP-g-MAH (maleic anhydride-grafted polypropylene) and POE-g-MAH (maleic anhydride-grafted polyolefin elastomer) products at CHINAPLAS 2026, alongside customized compatibilizers, tougheners, and coupling agents. These products support the grafted polyolefins market by improving adhesion and compatibility between polymers and other materials in plastics compounding.
- January 2026: Arkema successfully started operations at its new Rilsan Clear transparent polyamide unit in Singapore, an investment of approximately USD 20 million that tripled its global production capacity for the material. The expansion supports the grafted polyolefins market by strengthening the supply of high-performance polymers used alongside functionalized polyolefins in demanding automotive, medical, and industrial applications.
Global Grafted Polyolefins Market Report Scope
Grafted polyolefins are modified polyolefin materials produced by chemically attaching functional groups to polymer chains to improve adhesion, compatibility, and interfacial bonding. They are used to enhance the performance of polymer blends, multilayer structures, and composite materials across various industrial applications.
The Grafted Polyolefins Market is segmented by type, application, end-use industry, and geography. By type, the market is segmented into maleic anhydride grafted polyethylene (PE), maleic anhydride grafted polypropylene (PP), maleic anhydride grafted ethylene-vinyl acetate (EVA), and other types. By application, the market is segmented into adhesion promotion, bonding, compatibilization, impact modification, and other applications. By end-use industry, the market is segmented into automotive, packaging, textile, adhesives and sealants, construction, and other end-use industries. The report also covers the market size and forecasts for grafted polyolefins across 15 countries. For each segment, the market sizing and forecasts have been done on the basis of value (USD).
Segmentation Overview
| Maleic Anhydride Grafted Polyethylene (PE) |
| Maleic Anhydride Grafted Polypropylene (PP) |
| Maleic Anhydride Grafted Ethylene-Vinyl Acetate (EVA) |
| Other Types |
| Adhesion Promotion |
| Bonding |
| Compatibilization |
| Impact Modification |
| Other Applications |
| Automotive |
| Packaging |
| Textile |
| Adhesives and Sealants |
| Construction |
| Other End-Use Industries |
| Asia-Pacific | China |
| India | |
| Japan | |
| South Korea | |
| ASEAN Countries | |
| Rest of Asia-Pacific | |
| North America | United States |
| Canada | |
| Mexico | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| NORDIC Countries | |
| Rest of Europe | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Middle East and Africa | Saudi Arabia |
| South Africa | |
| Rest of Middle East and Africa |
| By Type | Maleic Anhydride Grafted Polyethylene (PE) | |
| Maleic Anhydride Grafted Polypropylene (PP) | ||
| Maleic Anhydride Grafted Ethylene-Vinyl Acetate (EVA) | ||
| Other Types | ||
| By Application | Adhesion Promotion | |
| Bonding | ||
| Compatibilization | ||
| Impact Modification | ||
| Other Applications | ||
| By End-Use Industry | Automotive | |
| Packaging | ||
| Textile | ||
| Adhesives and Sealants | ||
| Construction | ||
| Other End-Use Industries | ||
| By Geography | Asia-Pacific | China |
| India | ||
| Japan | ||
| South Korea | ||
| ASEAN Countries | ||
| Rest of Asia-Pacific | ||
| North America | United States | |
| Canada | ||
| Mexico | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| NORDIC Countries | ||
| Rest of Europe | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Middle East and Africa | Saudi Arabia | |
| South Africa | ||
| Rest of Middle East and Africa | ||
Key Questions Answered in the Report
What is the size of the grafted polyolefins market?
The grafted polyolefins market size was valued at USD 4.21 billion in 2026 and is estimated to grow from USD 4.38 billion in 2027 to reach USD 5.56 billion by 2032, at a CAGR of 4.87% during the forecast period (2027-2032).
Which product type is forecast to expand fastest through 2032?
Maleic anhydride grafted polypropylene (PP) is forecast to expand at a 5.21% CAGR through 2032, supported by reinforced polypropylene compounds and recycling applications.
Why are grafted polyolefins used in packaging?
They help join polyolefin layers with ethylene vinyl alcohol (EVOH) or polyamide barriers in multilayer films, supporting pack integrity and material performance.
What is driving demand in recycling applications?
Recycled-content rules and the weaker performance of mixed polyethylene and polypropylene streams support the use of compatibilizers.