
Europe Data Center Water Management Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
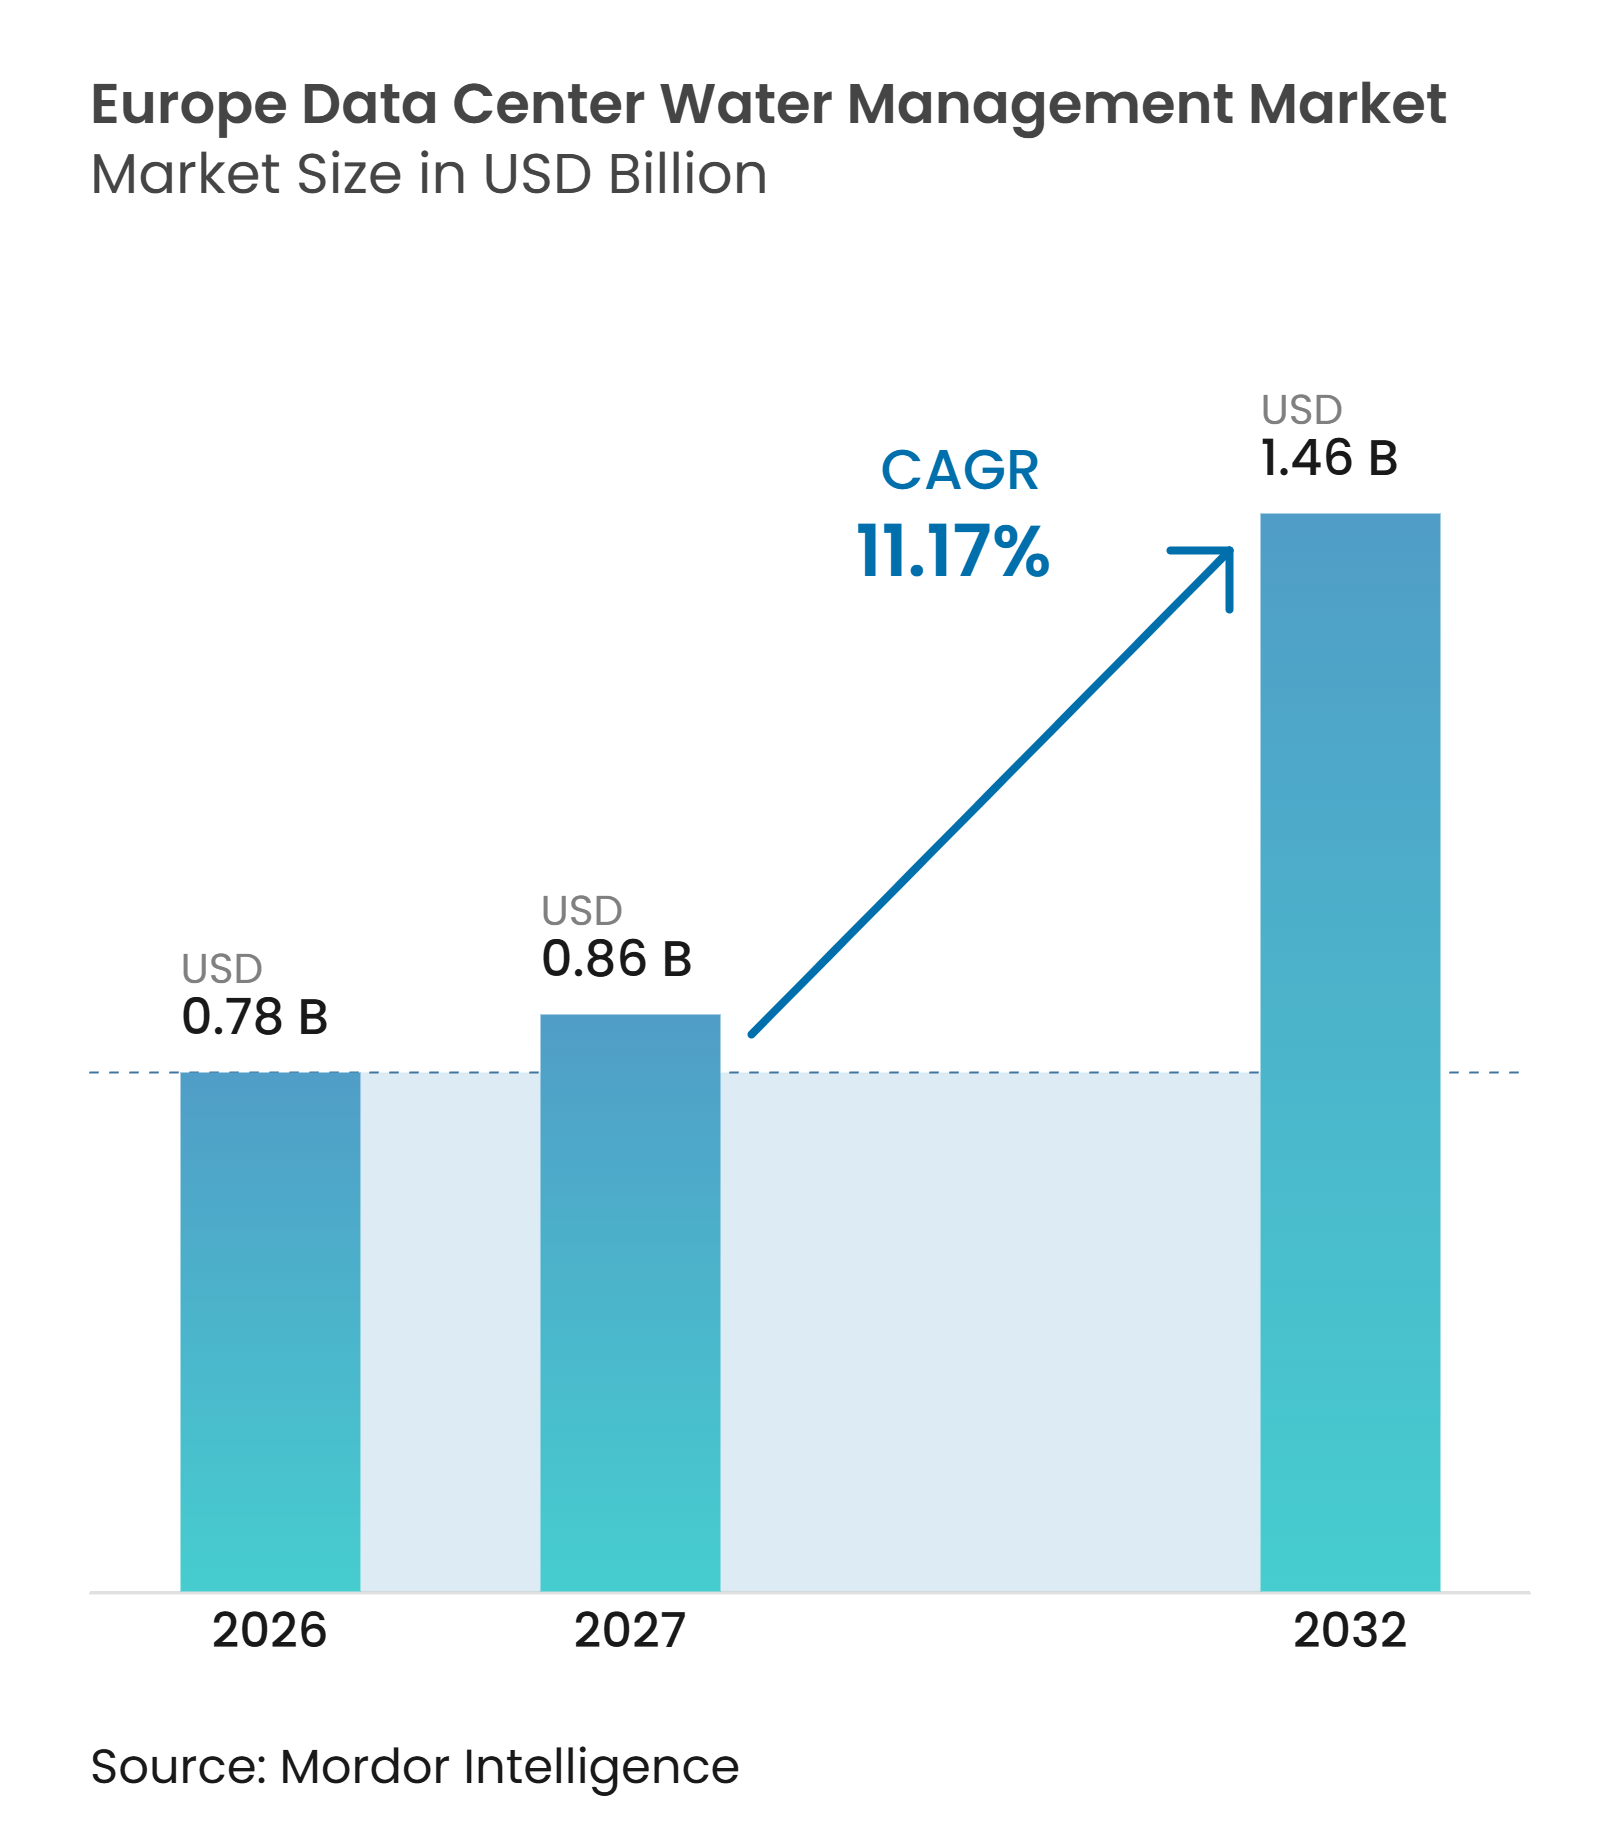
| Base Year Market Size (2026) | USD 0.78 Billion |
| Market Size (2027) | USD 0.86 Billion |
| Market Size (2032) | USD 1.46 Billion |
| Growth Rate (2027 - 2032) | 11.17 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Europe Data Center Water Management Market Analysis by Mordor Intelligence
The Europe data center water management market size is projected to expand from USD 0.78 billion in 2026 and USD 0.86 billion in 2027 to USD 1.46 billion by 2032, registering a CAGR of 11.17% between 2027 to 2032. The Europe data center water management market is being shaped by larger AI workloads, which require more intensive cooling and more consistent control of water quality. Operators are also preparing for annual water reporting and tighter permitting requirements across Europe. These conditions are shifting spending from basic utility connections toward monitoring, treatment, leak detection, reuse, and reporting systems. Corporate commitments to reduce freshwater use are supporting multi-year service contracts for water treatment and management. The Europe data center water management market also benefits from the movement toward closed-loop liquid cooling, where water chemistry and equipment reliability require closer attention.
Key Report Takeaways
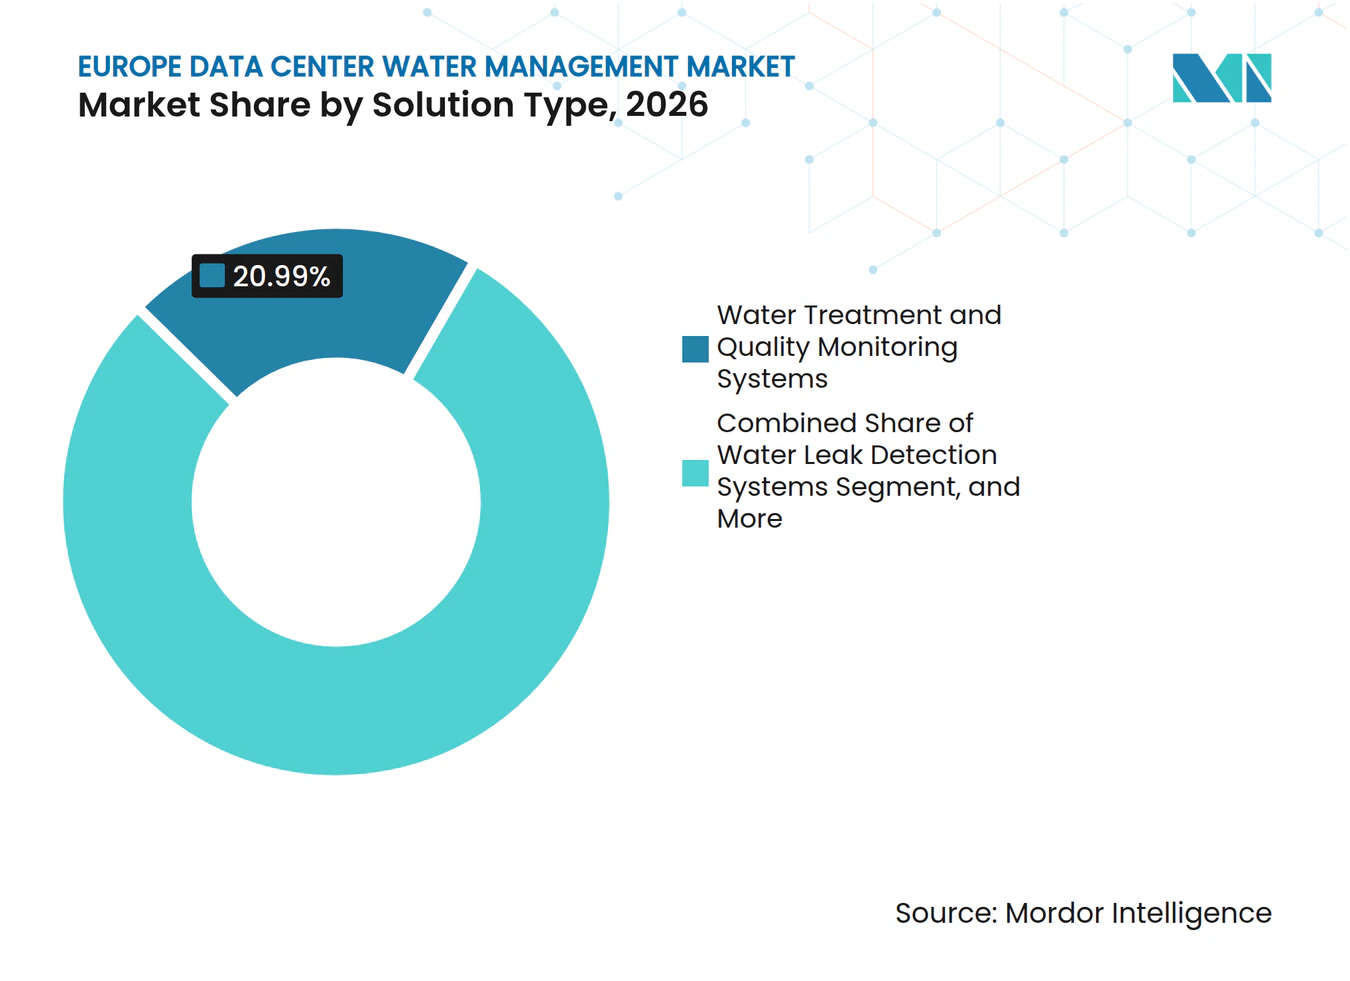
- By solution type, water treatment and quality monitoring held 20.99% of the Europe data center water management market share in 2026, while water recycling and reuse management is projected to expand at an 11.46% CAGR through 2032.
- By water management application, cooling system water management accounted for 47.26% of the Europe data center water management market size in 2026, while water recycling and reuse is projected to expand at an 11.38% CAGR through 2032.
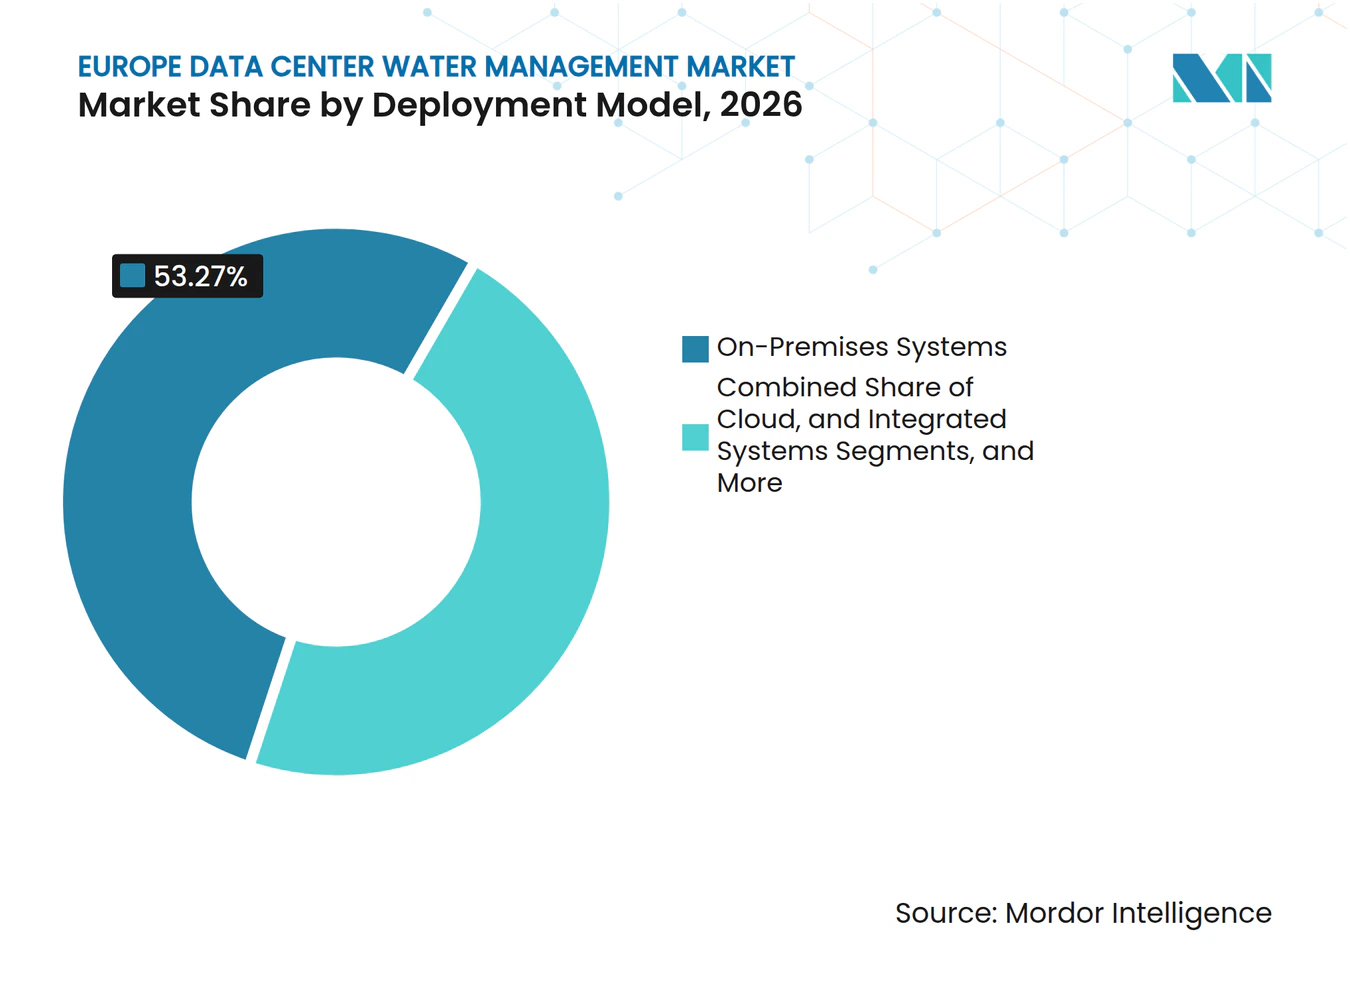
- By deployment model, on-premises systems held 53.27% share in 2026, while integrated and hybrid systems are projected to expand at an 11.57% CAGR through 2032.
- By service type, monitoring and maintenance services held 37.83% share in 2026, while managed water management services are projected to expand at an 11.66% CAGR through 2032.
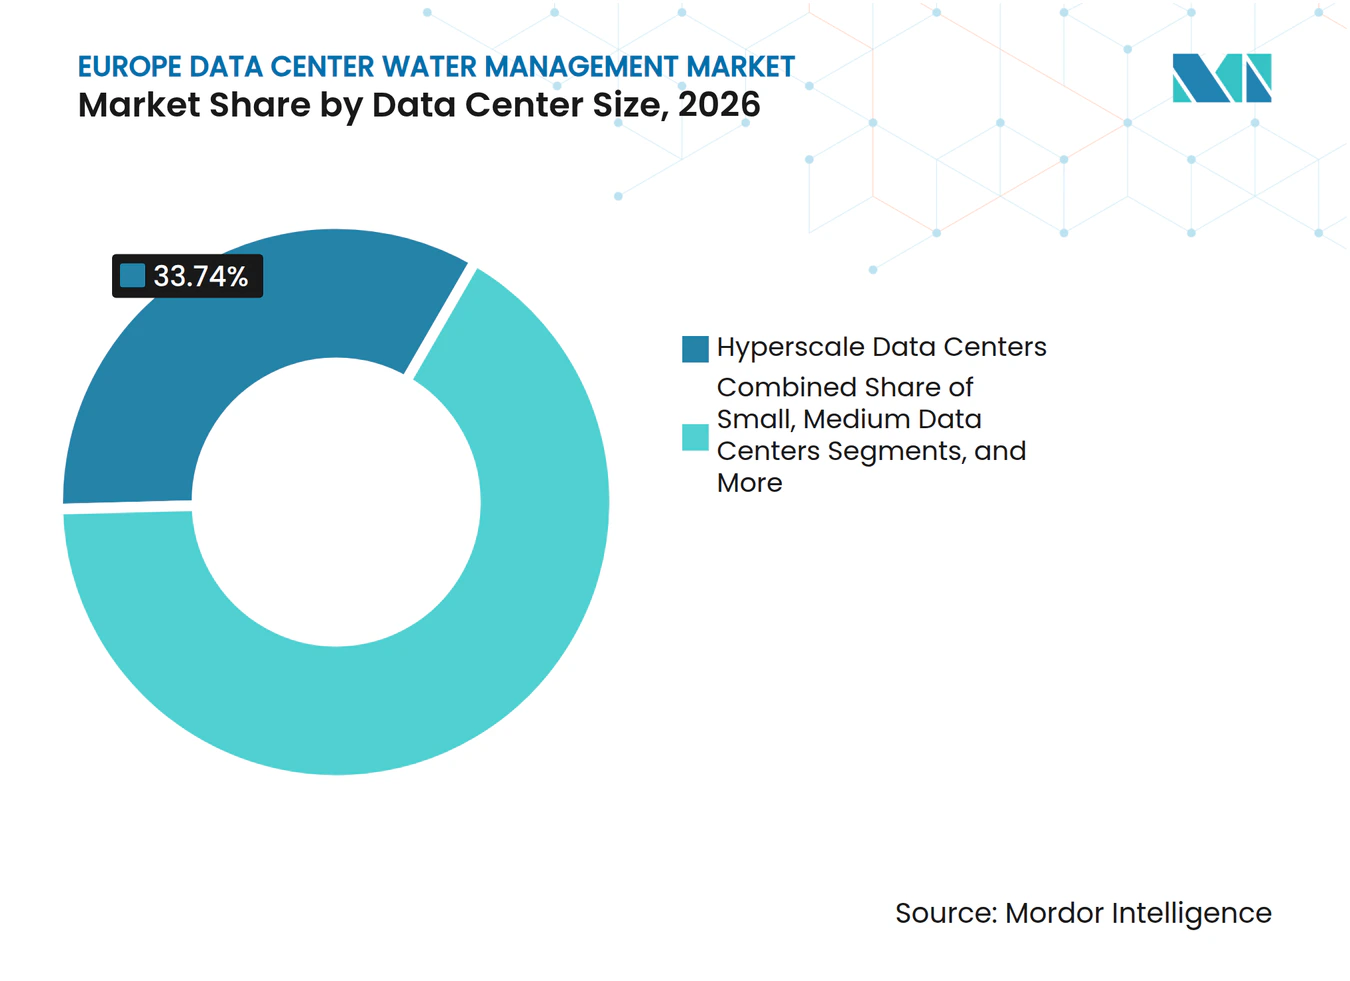
- By data center size, hyperscale facilities held 33.74% share in 2026 and are projected to expand at an 11.49% CAGR through 2032.
- By data center type, colocation data centers held 38.66% share in 2026, while cloud service providers are projected to expand at an 11.77% CAGR through 2032.
- By geography, the United Kingdom held 16.77% share in 2026, while Ireland is projected to expand at an 11.84% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Europe Data Center Water Management Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| AI and Hyperscale Data Center Expansion | +3.5% | Europe, with priority demand in Frankfurt, London, Amsterdam, Paris, and Dublin | Short term (≤ 2 years) |
| Direct-to-Chip Liquid Cooling Adoption | +2.5% | Europe, particularly the United Kingdom, France, and Germany | Medium term (2-4 years) |
| Water-Use Disclosure and Permitting Requirements | +2% | European Union member states | Short term (≤ 2 years) |
| Water-Positive and ESG Commitments | +1.5% | Ireland, the Netherlands, the United Kingdom, and the Nordics | Medium term (2-4 years) |
| Reclaimed-Water Infrastructure for Cooling | +1% | Spain, Italy, and Ireland | Long term (≥ 4 years) |
| Higher Rack Densities and Closed-Loop Cooling | +0.8% | United Kingdom, Germany, France, the Netherlands, and Ireland | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
AI and Hyperscale Data Center Expansion
The Europe data center water management market is supported by the planned expansion of AI-ready capacity across major European hubs. The European Commission has identified the need to expand data center capacity as part of Europe’s AI infrastructure agenda.[1] Dense AI racks place more heat within each facility footprint and require cooling systems with dependable water control. This requirement brings chemical dosing, particulate monitoring, and leak detection into facility specifications earlier in the development process. New campuses can include treatment and monitoring equipment at commissioning rather than adding it after cooling issues arise. The Europe data center water management market therefore has a broader addressable base across greenfield projects and upgrades to older cooling infrastructure.
Rising Direct-to-Chip Liquid Cooling Adoption
Direct-to-chip liquid cooling places fluid loops close to high-value computing equipment and raises the importance of continuous water-quality control. Research presented at IEEE ITHERM 2025 identified erosion, corrosion, and clogging as key risks in liquid-cooled data center loops.[2] Control of pH, inhibitor levels, and particulates is necessary to limit these risks in mixed-metal systems. Ecolab introduced Cooling as a Service in November 2025, combining 3D TRASAR monitoring with smart coolant distribution units.[3] Global Switch opened a liquid cooling showcase in London in June 2025 with Liquidstack and SuperMicro. These developments support recurring monitoring and maintenance demand within the Europe data center water management market.
Mandatory Water-Use Disclosure and Permitting Requirements
Commission Delegated Regulation (EU) 2024/1364 requires data centers with installed IT power demand of at least 500 kW to report total water input, potable water input, and Water Usage Effectiveness. The reporting framework makes water use more visible to regulators, investors, customers, and local communities. Separate reporting of potable and total water input encourages operators to consider reclaimed water, rainwater, and other non-potable sources. Continuous instrumentation is needed to produce credible data for annual submissions. The Europe data center water management market consequently gains demand for meters, monitoring platforms, maintenance, and reporting support. The European Commission’s water resilience agenda also places data centers within a wider effort to improve water efficiency.
Corporate Water-Positive and ESG Commitments
Water-positive targets are encouraging cloud operators to link facility operations with local water replenishment work. Microsoft states that its newer data center designs use closed-loop cooling systems that avoid evaporation and can save more than 125,000 cubic meters of water annually per facility. AWS reported progress toward its water-positive target and operates facilities using reclaimed water. These commitments require credible measurement of withdrawals, recycling, and replenishment activity. They also make external verification and auditable water data more important in supplier selection. Veolia’s partnership with Amazon on containerized reclaimed-water cooling systems shows how large operators can apply water programs across multiple sites. This shift favors service providers that can combine treatment, digital monitoring, and reporting.
Restraints Impact Analysis of Europe Data Center Water Management Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Drought, Groundwater Caps, and Rising Water Tariffs | -2.5% | Spain, Italy, Greece, Ireland, and high-density European hubs | Short term (≤ 2 years) |
| High Capital Cost of Reuse and Zero-Liquid-Discharge Systems | -1.8% | Europe, with greater pressure in Southern European markets | Long term (≥ 4 years) |
| Water-Chemistry Failure Risk in Direct-to-Chip Loops | -1% | United Kingdom, Germany, France, and the Netherlands | Medium term (2-4 years) |
| Permitting Delays and Community Opposition | -0.8% | Ireland, the Netherlands, and Spain | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Drought, Groundwater Caps, and Rising Water Tariffs
Water scarcity can affect site selection, cooling design, utility contracts, and community acceptance for the Europe data center water management market. Facilities in water-stressed locations may face more restrictive conditions on potable supply and groundwater abstraction. This situation increases interest in treated wastewater, rainwater harvesting, and closed-loop designs. These alternatives can reduce exposure to supply restrictions, but they can also require more equipment and operating controls. The pressure is especially material where high-density campuses are concentrated near communities with limited water resources. Operators must therefore balance expansion plans with local water availability and verifiable conservation measures.
High Capital Cost of Reuse and Zero-Liquid-Discharge Systems
Advanced reuse and zero-liquid-discharge systems can reduce wastewater and support compliance goals, but they require substantial initial investment. Treatment systems may need reverse osmosis, ion softening, civil works, process controls, and specialist services. These costs can be difficult for smaller facilities to spread across their available IT capacity. Veolia describes treatment technologies designed to support water reuse in industrial cooling applications. The Europe data center water management market may therefore see earlier uptake among hyperscale facilities with larger capital budgets. Modular systems and managed-service contracts can lower the entry barrier for smaller data center operators over time.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Europe Data Center Water Management Market Segment Analysis
By Solution Type:
Treatment and Monitoring Anchor Revenue While Recycling Systems Lead GrowthWater treatment and quality monitoring held 20.99% of the Europe data center water management market share in 2026. These systems protect cooling equipment against corrosion, biofouling, scaling, and contamination. Their importance spans cooling towers, closed-loop systems, and hybrid cooling designs. Operators are increasingly adopting connected sensors instead of relying only on periodic manual sampling. This allows chemical dosing to respond to changing water conditions. The approach can reduce the chance that an undetected chemistry issue damages cooling equipment.
Water recycling and reuse management is projected to expand at an 11.46% CAGR through 2032. The segment is supported by interest in reducing potable-water dependence and meeting reporting requirements. Membrane treatment and modular reverse osmosis systems can make reuse more practical for facilities with limited space. Monitoring, metering, leak detection, and optimization platforms serve related needs across the same water cycle. The Europe data center water management industry increasingly requires these systems to work together rather than as separate equipment purchases. Ecolab’s monitoring platform illustrates the movement toward connected oversight of cooling water conditions.



By Water Management Application:
Cooling Remains the Volume Anchor While Recycling Reshapes PrioritiesCooling system water management accounted for 47.26% of the Europe data center water management market size in 2026. Thermal management remains the main water-related operating function in many data centers. Higher rack density makes cooling design more important for facility availability. Smart systems can adjust water flow and operating settings as demand changes. The World Economic Forum notes that circular approaches can help data centers improve water management and reduce use of freshwater resources. These capabilities are particularly relevant for large facilities with continuous cooling requirements.
Water recycling and reuse is projected to expand at an 11.38% CAGR through 2032. Separate disclosure of potable and total water input gives operators a reason to consider non-potable supplies. Wastewater management also gains attention where cooling tower blowdown is subject to discharge requirements. Supply and distribution management helps maintain the flow of usable water through the facility. Leak prevention and consumption reporting provide supporting operational control. The Europe data center water management market is therefore moving toward application portfolios that combine cooling reliability with documented water efficiency.
By Deployment Model:
On-Premises Leads Securely as Integrated and Hybrid Systems Drive GrowthOn-premises systems held 53.27% share of the Europe data center water management market in 2026. Cooling towers, dosing systems, sensors, and treatment units are normally installed within or beside the data center. Many operators also treat cooling telemetry as sensitive operational information. Local control supports immediate action if a leak or water-quality issue is detected. It also aligns with the physical design of integrated cooling infrastructure. On-premises systems will remain important where physical equipment must be managed at the facility.
Integrated and hybrid systems are projected to expand at an 11.57% CAGR through 2032. These systems combine local sensing and control with centralized data analysis. They allow operators to compare Water Usage Effectiveness across several sites without giving up facility-level oversight. OVHcloud introduced an AI-powered cooling architecture that combines sensors, predictive maintenance, and centralized data processing. This model is relevant as operators add second and third European campuses. The Europe data center water management market can benefit as multi-site operators seek common reporting processes alongside local operating control.

By Service Type:
Monitoring Anchors Recurring Revenue While Managed Services AccelerateMonitoring and maintenance services held 37.83% share in 2026. Cooling water treatment requires ongoing chemical dosing, sensor calibration, flushing, and equipment checks. These activities create recurring service needs that are less dependent on individual construction projects. Annual water reporting also requires dependable measurement throughout the year. Providers that maintain installed systems can support both data quality and equipment reliability. The Europe data center water management market share of monitoring services reflects this continuing operational requirement.
Managed water management services are projected to expand at an 11.66% CAGR through 2032. Operators are seeking contracts that focus on Water Usage Effectiveness targets, availability, and treatment outcomes. This approach can limit the need to coordinate separate suppliers for chemistry, instrumentation, and reporting. Installation and integration services remain important for new facilities and cooling retrofits. Water auditing also supports disclosure obligations and local permit discussions. The Europe data center water management industry can consequently generate more service revenue as cooling systems become more complex.
By Data Center Size:
Hyperscale Leads Both Share and Growth, Defining Market DynamicsHyperscale data centers held 33.74% of the Europe data center water management market share in 2026. They are also projected to expand at an 11.49% CAGR through 2032. Large campuses in Ireland, the United Kingdom, the Netherlands, Germany, and France require extensive treatment, monitoring, and reuse capabilities. Their continuous operations make system reliability and verified reporting central operating concerns. These facilities can also justify premium systems that may be difficult for smaller sites to fund. Hyperscale projects therefore shape purchasing patterns across the Europe data center water management market.
Large data centers form another important demand base, particularly where operators upgrade older open-loop cooling systems. Medium and small facilities face a different cost structure because advanced monitoring and reuse equipment has fixed costs. Providers are responding with modular systems and subscription-based offerings. These formats can reduce upfront spending while adding specialist maintenance support. They also allow operators to improve water visibility in stages. The Europe data center water management industry can use these models to reach facilities outside the largest cloud campuses.
By Data Center Type:
Colocation Commands the Largest Share While Cloud Operators Invest FastestColocation data centers held 38.66% share of the Europe data center water management market in 2026. These facilities serve multiple tenants with different computing loads and cooling needs. London, Amsterdam, Frankfurt, and Dublin contain dense colocation estates with extensive shared building infrastructure. Facility operators must monitor water systems at the building level even when tenants control much of their IT equipment. This creates demand for facility-wide monitoring and clear reporting processes. Colocation operators also need reliable water systems to maintain service commitments across diverse customer workloads.
Cloud service providers are projected to expand at an 11.77% CAGR through 2032. New cloud campuses are being designed with more advanced cooling and water-reuse requirements than many legacy sites. Enterprise and edge facilities add a separate demand stream as organizations consolidate smaller server rooms. Government and institutional facilities also face public expectations for transparent resource use. The Europe data center water management market gains demand from each type, although their procurement needs vary by facility size and operating model. Company water commitments can make reuse and monitoring more visible criteria in cloud-facility design.
Geography Analysis
The United Kingdom held 16.77% of the Europe data center water management market share in 2026. London’s deep colocation ecosystem drives substantial demand for cooling-water treatment and monitoring. The market also includes expanding hyperscale campuses in the wider London area. Operators are responding to customer and investor expectations for better disclosure of resource use. This supports demand for real-time monitoring, efficient cooling, and managed water services.
Germany and France are major capacity markets where AI expansion is increasing the need for reliable cooling systems. In Germany, water management is becoming a more important consideration in planning and sustainable operation. The Netherlands is pursuing circular water solutions for data centers in areas with dense infrastructure. The Dutch Data Center Association describes initiatives to move from water consumption toward active water management. France also has demand for high-capacity liquid-cooling systems in new AI-focused projects.
Ireland is projected to expand at an 11.84% CAGR through 2032, the fastest country rate in the Europe data center water management market. Its role as a hub for North American cloud operators makes water use a closely watched operational issue. The concentration of facilities around Dublin intensifies the need for local monitoring, reporting, and reuse options. Spain presents a different combination of strong hyperscale interest and water availability constraints. The Nordics offer lower water stress and cool ambient conditions, which can reduce active cooling needs during much of the year. Italy and the Rest of Europe add demand as new data center locations develop under local utility and permitting requirements.
Competitive Landscape
Market Concentration
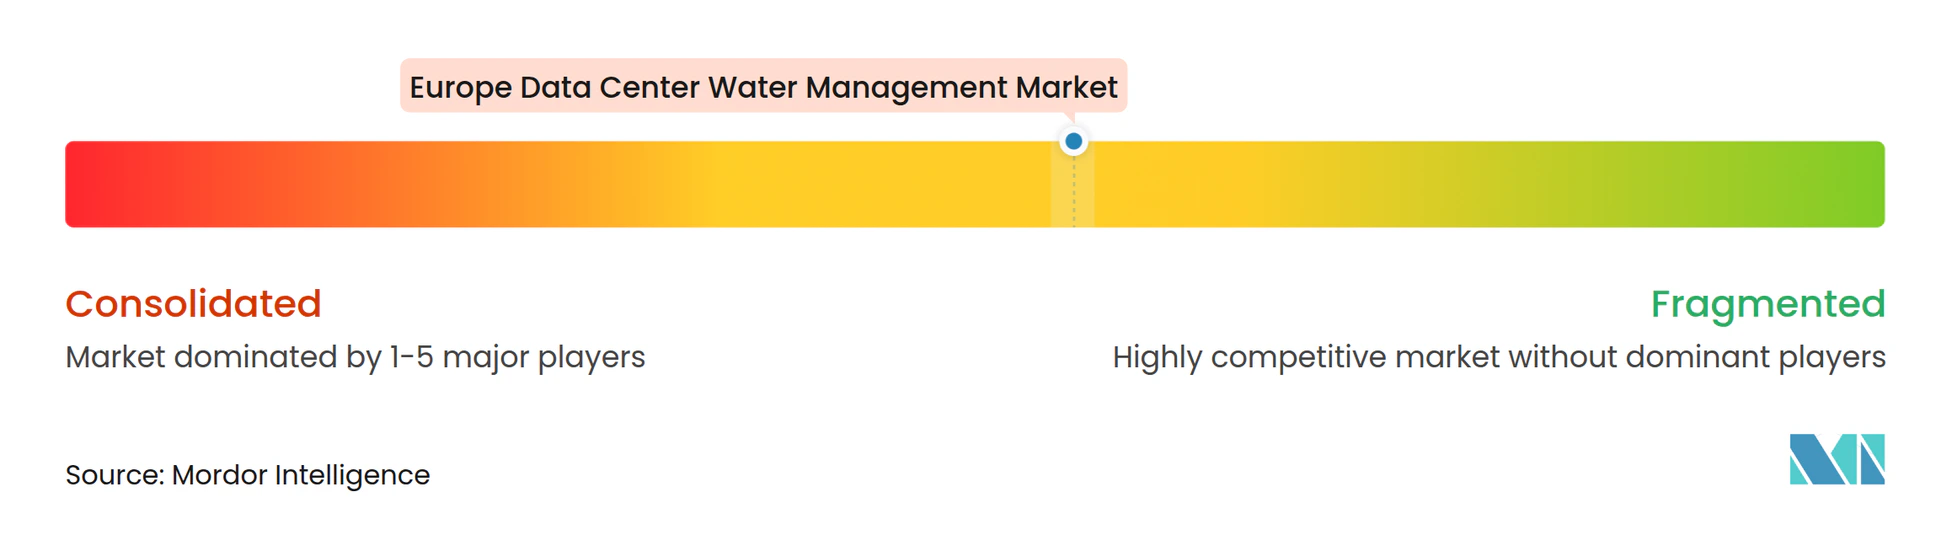
The Europe data center water management market is moderately fragmented across water technology suppliers, thermal infrastructure companies, and data center operators. Integrated water technology providers include Ecolab, Veolia, Xylem, SUEZ, Kurita Water Industries, and Veralto. Thermal infrastructure companies include Schneider Electric, Vertiv, Johnson Controls, Carrier, and Modine Manufacturing. Digital Realty, Equinix, and major cloud operators also develop or manage water-related capabilities within their facilities. Competition is increasingly based on service quality, digital monitoring, treatment performance, and system integration. No provider has a leading position across every solution type.
Veolia launched Data Center Resource 360 in April 2026 as an integrated offering for water, energy, and waste management in data centers. The offering brings water auditing, treatment, digital monitoring, and replenishment support into one platform. Ecolab’s Cooling as a Service program combines monitoring technology with coolant distribution equipment. These moves show how providers are moving beyond one-time equipment sales toward longer service relationships. Global Switch’s London liquid-cooling showcase also demonstrates the practical use of direct-to-chip and immersion cooling in colocation settings.
Opportunities remain for compact treatment systems, multi-site Water Usage Effectiveness reporting platforms, and containerized reclaimed-water solutions. Modular products may be useful for smaller facilities that cannot fund large site-specific treatment projects. Providers that can demonstrate dependable water data can support permit applications and sustainability reporting. Industry efforts are also putting more attention on common measures of water performance. The Climate Neutral Data Centre Pact includes a Water Usage Effectiveness target for new data centers by 2030. The Europe data center water management market will remain competitive because customers need solutions that can operate across different local regulations and water conditions.
Europe Data Center Water Management Industry Leaders
-
Veolia Environnement S.A.
-
Ecolab Inc.
-
Xylem Inc.
-
Solenis LLC
-
Kemira Oyj
- *Disclaimer: Major Players sorted in no particular order
Europe Data Center Water Management Market Companies Covered in this Report
- Ecolab Inc.
- Veolia Environnement S.A.
- Xylem Inc.
- SUEZ S.A.
- Gradiant Corporation
- ChemTreat, Inc.
- Aquatech International LLC
- Black & Veatch Holding Company
- Carollo Engineers, Inc.
- H2O Innovation Inc.
- Kurita Water Industries Ltd.
- Veralto Corporation
- Schneider Electric SE
- Vertiv Group Corp.
- Johnson Controls International plc
- Carrier Global Corporation
- Modine Manufacturing Company
- Microsoft Corporation
- Amazon Web Services, Inc.
- Google LLC
- Meta Platforms, Inc.
- Digital Realty Trust, Inc.
- Equinix, Inc.
- QTS Realty Trust, LLC
- CyrusOne Inc.
- Switch, Inc.
- Iron Mountain Data Centers, LLC
- NTT Global Data Centers Americas, Inc.
- STACK Infrastructure, Inc.
- Vantage Data Centers, LLC
- CoreSite Realty Corporation
Recent Industry Developments in Europe Data Center Water Management Market
- September 2026: Drees and Sommer SE published analysis confirming that Germany's accelerating data center capacity expansion is making water management, alongside energy access, a decisive determinant of operational viability and site-selection outcomes, with the company highlighting that sustainable water credentials are becoming an informal prerequisite in several German state planning processes.
- April 2026: Veolia launched Data Center Resource 360 in London, a global integrated platform targeting up to 75% water footprint reduction, 20% energy reuse improvement, and 95% waste recycling. The company simultaneously announced a target of over EUR 1 billion (approximately USD 1.10 billion) in annual revenue from the data center and chip production markets by 2030.
- April 2026: Veolia and Amazon announced a formal partnership to develop containerized reclaimed-water cooling systems for Amazon's data center operations, with the first facility expected to be operational by 2027 and modular designs explicitly intended for replication at European sites where potable water abstraction is under increasing regulatory constraint.
- November 2025: Ecolab launched its Cooling as a Service program, integrating 3D TRASAR technology for real-time direct-to-chip coolant monitoring with smart Coolant Distribution Units to create a continuous managed-service model for AI-driven data center cooling water management at global scale.
Europe Data Center Water Management Market Report Scope
The Europe Data Center Water Management Market comprises technologies and services that help data center operators monitor, manage, conserve, and optimize water use across facility operations. It focuses on improving water efficiency, reducing wastage, supporting sustainable cooling practices, ensuring water quality, and meeting environmental compliance requirements. The market enables organizations to enhance operational resilience, lower resource consumption, and achieve sustainability goals through advanced monitoring, automation, analytics, and water conservation strategies, supporting the growing demand for environmentally responsible and resource-efficient digital infrastructure.
The Europe Data Center Water Management Market Report is Segmented by Solution Type (Water Monitoring and Metering Systems, Water Leak Detection Systems, Water Usage Optimization and Control Systems,Water Recycling and Reuse Management Systems,Water Treatment and Quality Monitoring Systems, and Water Management Software and Analytics), Water Management Application (Cooling System Water Management, Water Supply and Distribution Management, Wastewater Management, Water Recycling and Reuse, Leak Prevention and Detection, and Water Consumption Reporting and Optimization), Deployment Model (On-Premises Systems, Cloud-Based Systems, and Integrated and Hybrid Systems), Service Type (System Installation and Integration, Monitoring and Maintenance, Water Auditing and Efficiency Consulting, and Managed Water Management Services), Data Center Size (Small, Medium, Large, and Hyperscale), Data Center Type (Colocation, Cloud Service Providers (CSPs), Enterprise and Edge, and Government and Institutional Data Centers), and Geography (United Kingdom, Germany, France, Netherlands, Ireland, Spain, Italy, Nordics, and Rest of Europe). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Water Monitoring and Metering Systems |
| Water Leak Detection Systems |
| Water Usage Optimization and Control Systems |
| Water Recycling and Reuse Management Systems |
| Water Treatment and Quality Monitoring Systems |
| Water Management Software and Analytics |
| Cooling System Water Management |
| Water Supply and Distribution Management |
| Wastewater Management |
| Water Recycling and Reuse |
| Leak Prevention and Detection |
| Water Consumption Reporting and Optimization |
| On-Premises Systems |
| Cloud-Based Systems |
| Integrated and Hybrid Systems |
| System Installation and Integration |
| Monitoring and Maintenance |
| Water Auditing and Efficiency Consulting |
| Managed Water Management Services |
| Small Data Centers |
| Medium Data Centers |
| Large Data Centers |
| Hyperscale Data Centers |
| Colocation Data Centers |
| Cloud Service Providers |
| Enterprise and Edge Data Centers |
| Government and Institutional Data Centers |
| United Kingdom |
| Germany |
| France |
| Netherlands |
| Ireland |
| Spain |
| Italy |
| Nordics |
| Rest of Europe |
| By Solution Type | Water Monitoring and Metering Systems |
| Water Leak Detection Systems | |
| Water Usage Optimization and Control Systems | |
| Water Recycling and Reuse Management Systems | |
| Water Treatment and Quality Monitoring Systems | |
| Water Management Software and Analytics | |
| By Water Management Application | Cooling System Water Management |
| Water Supply and Distribution Management | |
| Wastewater Management | |
| Water Recycling and Reuse | |
| Leak Prevention and Detection | |
| Water Consumption Reporting and Optimization | |
| By Deployment Model | On-Premises Systems |
| Cloud-Based Systems | |
| Integrated and Hybrid Systems | |
| By Service Type | System Installation and Integration |
| Monitoring and Maintenance | |
| Water Auditing and Efficiency Consulting | |
| Managed Water Management Services | |
| By Data Center Size | Small Data Centers |
| Medium Data Centers | |
| Large Data Centers | |
| Hyperscale Data Centers | |
| By Data Center Type | Colocation Data Centers |
| Cloud Service Providers | |
| Enterprise and Edge Data Centers | |
| Government and Institutional Data Centers | |
| By Country | United Kingdom |
| Germany | |
| France | |
| Netherlands | |
| Ireland | |
| Spain | |
| Italy | |
| Nordics | |
| Rest of Europe |
Key Questions Answered in the Report
What is the Europe data center water management market size?
The Europe data center water management market size is projected to reach USD 1.5 billion by 2032 from USD 0.9 billion in 2027, at an 11.2% CAGR.
What is driving demand for data center water management in Europe?
AI-ready capacity, liquid cooling, water-use reporting, and water-positive commitments are increasing demand for treatment, monitoring, reuse, and reporting systems.
Which solution type has the largest share?
Water treatment and quality monitoring holds the largest solution-type share at 20.99% in 2026.
Which data center type has the largest share?
Colocation data centers hold the largest type share at 38.66% in 2026, reflecting their role in Europes major connectivity hubs.
Which country leads the European sector?
The United Kingdom leads with 16.77% share in 2026, supported by Londons large colocation base and expanding campus activity.
Which country is expanding fastest?
Ireland is projected to expand at an 11.84% CAGR through 2032 because of its concentration of hyperscale cloud infrastructure.