
Egypt Construction Market Analysis by Mordor Intelligence
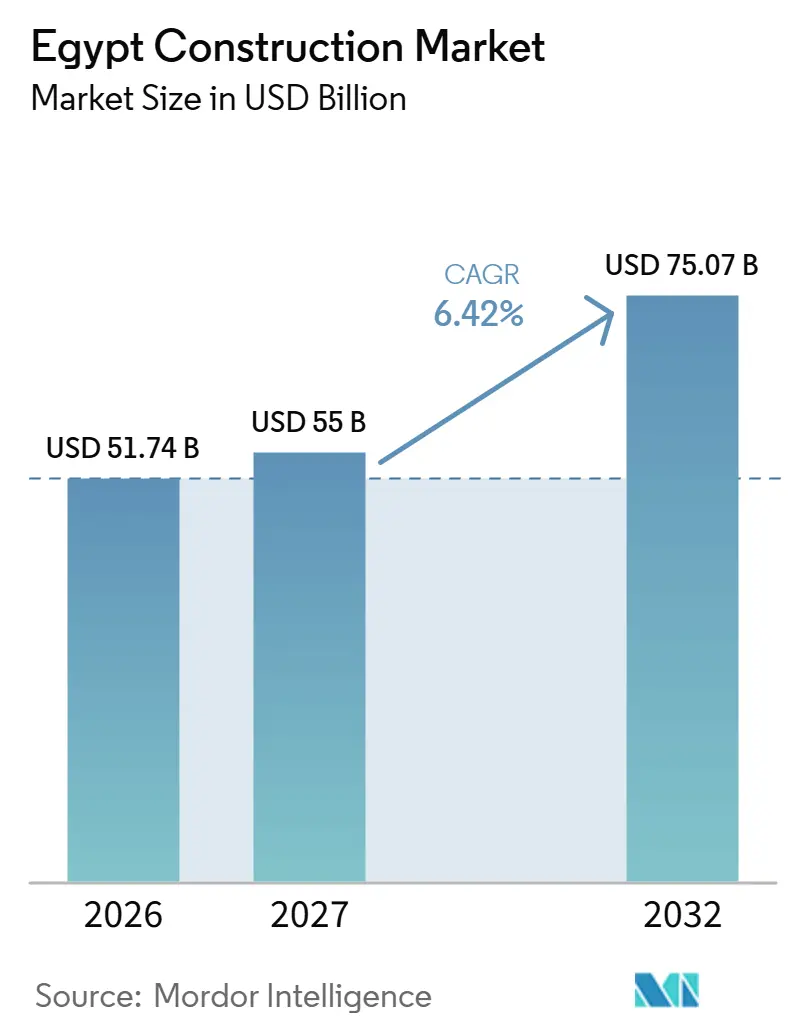
The Egypt construction market size is estimated at USD 51.74 billion in 2026 and is projected to be USD 55 billion in 2027, reaching USD 75.07 billion by 2032, growing at a CAGR of 6.42% from 2027 to 2032.
In Egypt, state-backed housing and utility programs convert urban expansion into demand for homes and the services that make them usable. Renewable-energy and transport investment adds engineered construction packages, creating room for consortia and specialist contractors to deliver connected assets. Private partnerships broaden participation by joining master developers with project developers under defined commercial relationships. Currency exposure and approval delays constrain how quickly this pipeline can become profitable, executable work. State-backed programs favor contractors able to absorb currency swings and approval-related holding costs without interrupting delivery.
Key Report Takeaways
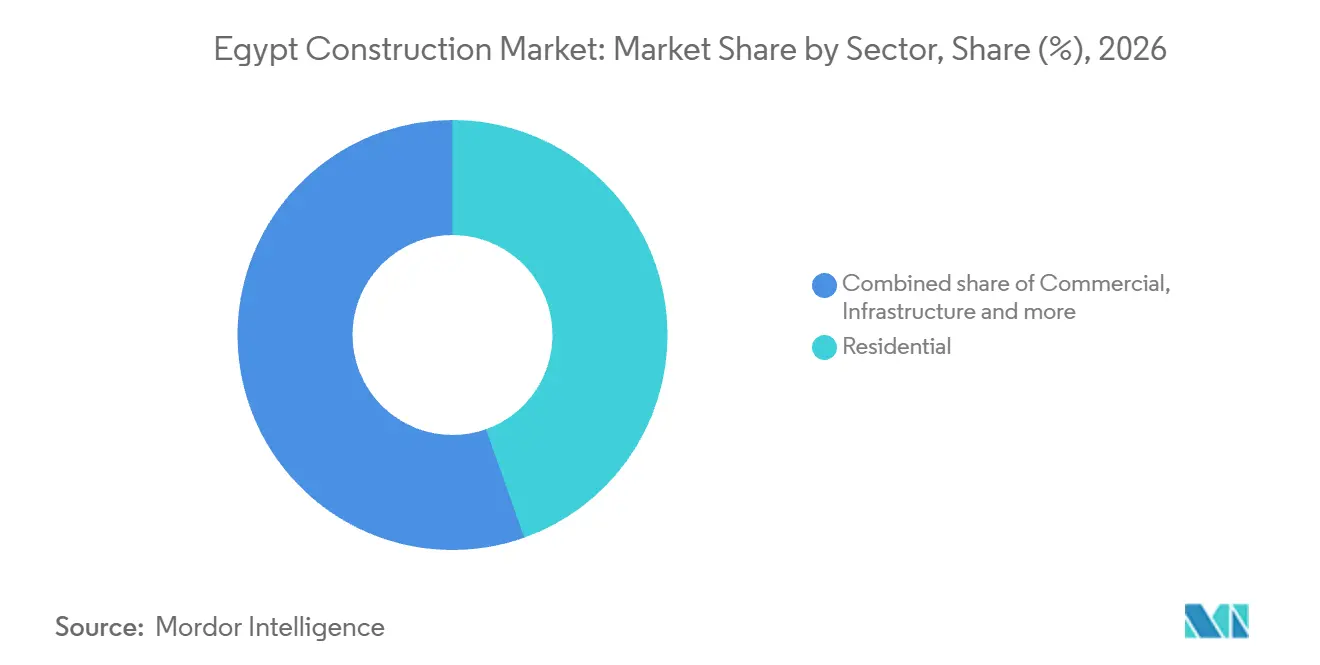
- By sector, residential held a 44.58% Egypt construction market share in 2026, while infrastructure is the fastest-growing segment, with a 9.3% CAGR forecast from 2027 to 2032.
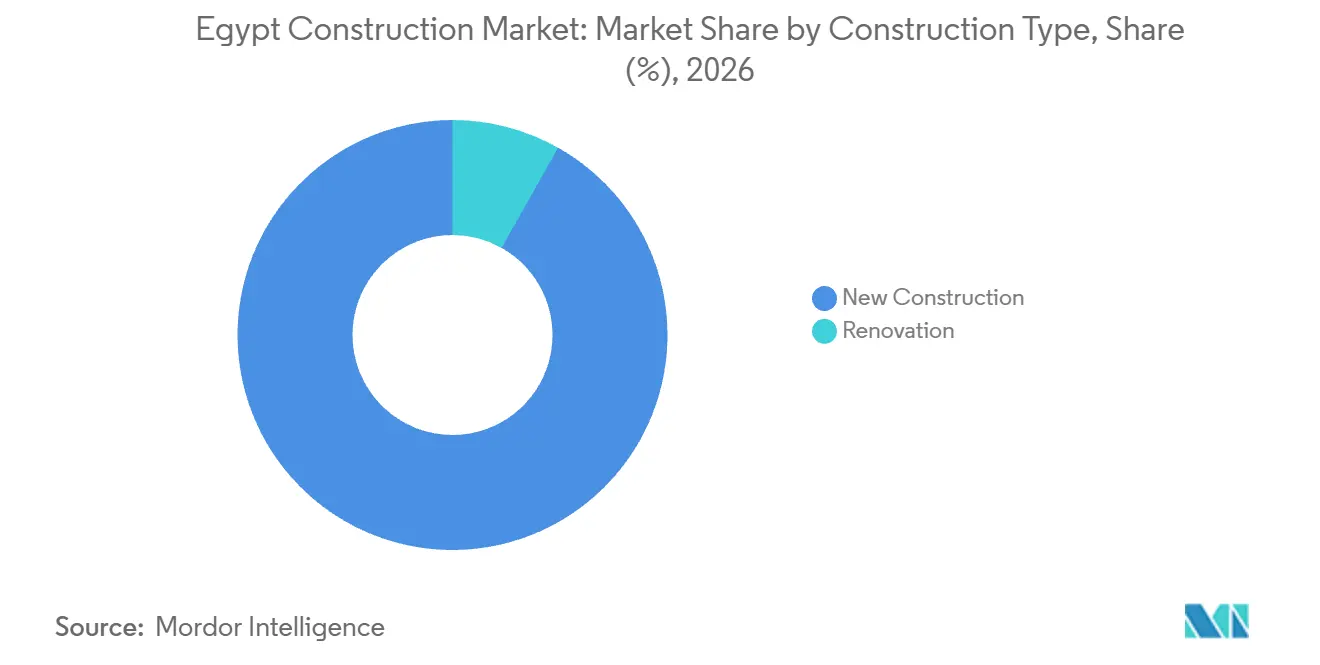
- New construction led construction type with a 91.83% share of the Egypt construction market size in 2026, and renovation is the fastest-growing segment, with an 8.7% CAGR forecast from 2027 to 2032.
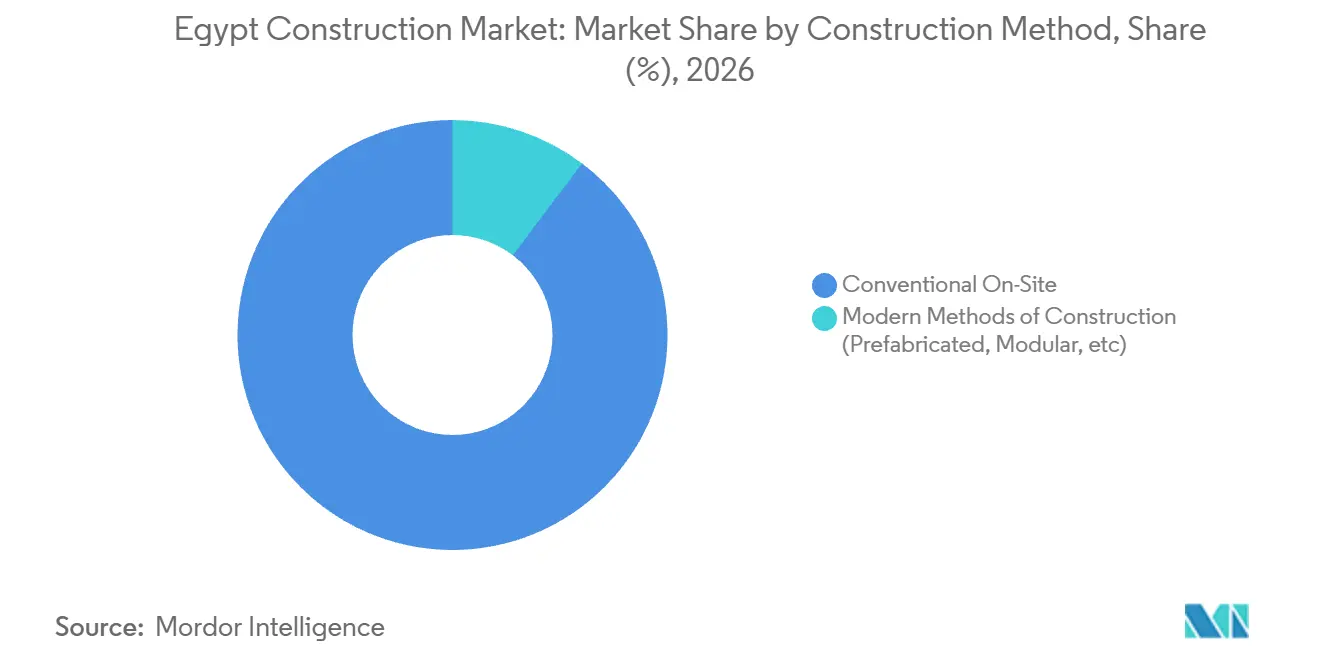
- Conventional on-site construction led the method mix with an 89.7% share in 2026, while modern methods of construction, including prefabricated and modular approaches, are forecast to grow fastest at a 9.7% CAGR from 2027 to 2032.
- By investment source, public funding held a 71.03% share in 2026, and private investment is the fastest-growing segment, with a 10.1% CAGR forecast from 2027 to 2032.
- Greater Cairo led the geographic mix with a 49.25% share in 2026 and is also the fastest-growing geography, with a 9.3% CAGR forecast from 2027 to 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Egypt Construction Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Proliferation of Government-Led Urban Expansion and Smart City Initiatives | +2.1% | New Aswan City | Long term (≥ 4 years) |
| Accelerated Energy Infrastructure Growth Driven by Decarbonization Goals | +2% | Nationwide | Medium term (2-4 years) |
| Expansion of Multimodal Transport Networks Enhancing Connectivity and Regional Trade | +1.8% | North Sinai and Arish Port | Medium term (2-4 years) |
| Rising Demand for Affordable and Middle-Income Housing Supported by State Financing and PPP Models | +1.5% | Nationwide | Short term (≤ 2 years) |
| Increasing Foreign Investment in Industrial Zones, Logistics, and Infrastructure through Strategic Alliances | +1.1% | Ain Sokhna, East Port Said, Alexandria | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Proliferation of Government-Led Urban Expansion and Smart City Initiatives
Government-led expansion creates construction work in both utility networks and the buildings those networks serve. In September 2025, the New Urban Communities Authority (NUCA) awarded Giza General Contracting and Real Estate Investment electricity-network works for 176 plots in New Aswan City. A network award spanning many plots can create a coordinated construction package that supports their development into usable urban land. In September 2026, NUCA offered 10,000 rent-to-own housing units, including about 5,000 completed units and another 5,000 planned for construction. The planned units represent a prospective building requirement, while the announced utility award provides a direct route to contractor work. For electrical-infrastructure specialists, the relevant opportunity is a separate network package inside a larger urban-development program.
Accelerated Energy Infrastructure Growth Driven by Decarbonization Goals
Renewable generation expansion sustains demand for constructing new assets alongside an expanding operating base. Data from the New and Renewable Energy Authority (NREA) put Egypt's installed renewable energy capacity at approximately 9.1 GW in FY2025/26, up from approximately 8.6 GW in FY2024/25.[1] Its July 2026 data also identified approximately 20.8 GW of projects under construction or development through 2030. The operating-capacity increase demonstrates delivered infrastructure, while the mixed-stage pipeline spreads potential construction work across several years. The roughly 0.5 GW added in FY2025/26 is small beside the approximately 20.8 GW pipeline, so the volume of work still ahead depends on how quickly development-stage schemes reach construction.
Expansion of Multimodal Transport Networks Enhancing Connectivity and Regional Trade
Transport connections generate construction demand at the interfaces between rail routes, stations, and ports. At a Ministry of Transport meeting, Egypt Maritime Ports Company's chair reported that the Rail Container Station handled 13,695 TEUs on 129 train journeys in H1 2026, up 354% from H1 2025. In a separate North Sinai construction program, Prime Minister Mostafa Madbouli reviewed advancing work on the 83-kilometer section between Bir al-Abd and Arish and 7 planned stations on April 19, 2026. Egyptian national companies were carrying out the works, and the inspection also covered a 12-kilometer link to Arish Port. The inspection included construction of 9 overpasses, a railway bridge, and 2 tunnels. Crossings and stations on the Arish line are the civil scopes that turn the rail-port connection into a usable freight route.
Rising Demand for Affordable and Middle-Income Housing Supported by State Financing and PPP Models
State-supported mortgage channels help turn housing need into financed purchases, supporting the commercial case for affordable building programs. The Social Housing and Mortgage Finance Support Fund's 2024/25 annual-achievements report identified cumulative low-income housing-finance channels involving 22 banks and 8 financing companies. For middle-income housing finance, it reported 10 banks and 4 financing companies. Separately, the Fund reported 54,600 Green Housing Program units delivered to low-income beneficiaries by December 2025. Credit availability supports access to ownership, while delivered units show that the program also has a physical housing output base. That financing network gives affordable-unit programs a defined household-buyer channel to organize delivery around.
Restraints Impact Analysis of Egypt Construction Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Persistent Currency Volatility Impacting Import-Dependent Supply Chains and Contractor Profitability | -1.1% | Nationwide | Short term (≤ 2 years) |
| Structural Bureaucratic Delays in Land Titling, Permitting, and Approvals Slowing Project Pipelines | -0.6% | Nationwide | Medium term (2-4 years) |
| Chronic Skilled Labor Deficit in High-Demand Specializations Hindering Quality and Timelines | -0.4% | Nationwide | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Persistent Currency Volatility Impacting Import-Dependent Supply Chains and Contractor Profitability
Foreign-currency exposure makes input repricing a direct risk to the economics of construction work already underway. In June 2026, Egyptian Federation for Construction and Building Contractors head Mohamed Sami Saad estimated that no less than 40% to 50% of project funds covered foreign-currency imports of supplies, equipment, or electromechanical works. Ezz Steel raised its local factory-gate rebar price for October 2026 amid currency depreciation and higher imported raw-material costs. For contractors, such exposure can increase the cost of delivering a priced scope when imported inputs are acquired later. Rising input bills can strain contractors' cash flow before contract receipts arrive, even when the quantity of work commissioned has not changed.
Structural Bureaucratic Delays in Land Titling, Permitting, and Approvals Slowing Project Pipelines
Approval delays separate a developer's decision to build from the point when construction work can legally begin. A September 2025 account by the Official Egyptian Real Estate Platform described permit, license, and approval processes that can take months, especially when multiple government bodies are involved. The same account linked these processes to project delays and higher costs. By December 2025, Administrative Capital for Urban Development (ACUD) had completed the first phase of an online licensing and approvals system for the New Administrative Capital. Each month between committing resources and obtaining permission to build can add holding costs before productive work begins.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Egypt Construction Market Segment Analysis
By Sector:
Housing Volume Anchors Activity While Rail Awards Expand InfrastructureResidential accounted for a 44.58% share of the Egypt construction market size in 2026. CAPMAS recorded 211,993 implemented residential units in 2024/25, compared with 158,939 in 2023/24. The national total covers implementation by government, public or public-business, and private sectors. For building and finishing contractors, this broad delivery base can support recurring packages across several housing-provider channels. That is a 33.4% increase in implemented units in one year, which widened the base of completions that building and finishing work can draw on.
Infrastructure is the fastest-growing segment, with a 9.3% CAGR forecast from 2027 to 2032. Commercial construction has a distinct mixed-use outlet, illustrated by Majid Al Futtaim's June 2026 groundbreaking and enabling works at JUNCTION in West Cairo, combining offices, retail, food services, and a hotel. An Alstom-led consortium with Rowad Modern Engineering and Concrete Plus signed 4 contracts with Egyptian National Railways in June 2026 to modernize the 6th of October to Alexandria corridor and the Belbes to 10th of Ramadan line.[2] These contracts bring several routes into one national railway buyer's modernization program.

By Construction Type:
New Facilities Dominate While Village Upgrades Broaden RenovationNew construction represented a 91.83% Egypt construction market share in 2026. In December 2025, Hassan Allam Construction, a subsidiary of Hassan Allam Holding, was awarded a USD 250 million contract to build Afreximbank's African Trade Centre in Egypt's New Capital. The turnkey project was intended to host the bank's global headquarters. Purpose-built institutional complexes can aggregate work into one commissioning relationship, giving contractors a coherent scope across several building functions.
Renovation is the fastest-growing segment, with an 8.7% CAGR forecast from 2027 to 2032. In June 2025, the Ministries of Social Solidarity and Local Development, Haya Karima Foundation, Misr El Kheir Foundation, and Al Orman Association signed a housing-rehabilitation protocol. It targeted about 80,000 homes of families most in need in 1,477 villages across 20 governorates within Haya Karima's first phase. The protocol anticipated that most rehabilitation work would use workers from the villages. Village-based labor would distribute execution opportunities among existing homes, allowing renovation providers to participate at a local scale within the larger rehabilitation target.
By Construction Method:
On-Site Breadth Coexists With Component-Level PrefabricationConventional on-site construction was the largest segment, with an 89.7% share in 2026. A 2024 study identified traditional construction as the dominant method in Egyptian residential projects, ranging from low-income and social housing to high-end and luxury developments. A method used in both social and luxury housing can serve projects with different buyer requirements, making site-level execution capability transferable across residential price tiers.
Modern methods of construction, including prefabricated and modular approaches, are the fastest-growing segment, with a 9.7% CAGR forecast from 2027 to 2032. In early March 2025, El Dabaa Unit 2 installed the second tier of its inner containment shell using 12 petal blocks manufactured at the construction site. The tier forms part of a shell designed to house the reactor and primary-circuit equipment. Producing the 12 petal blocks at the El Dabaa site shows component fabrication being organized inside a major infrastructure project's own site operations.
By Investment Source:
Public Funding Provides Scale While Partnerships Expand Private ParticipationPublic investment led with a 71.03% share of the market in 2026. The FY2025/26 electricity and renewable energy plan assigned about 73% of that sector's planned investment to public funding. This planned allocation gives public infrastructure buyers a substantial role in shaping the volume and sequencing of projects offered to contractors.
Private investment is the fastest-growing segment, with a 10.1% CAGR forecast from 2027 to 2032. Egypt's housing ministry reported 100 private-sector partnerships in housing and urban development during FY2024/25, 25% more than the previous fiscal year. In June 2026, master developer MIDAR signed a partnership with Majid Al Futtaim for MADA, New Cairo. An earlier February 2025 agreement paired MIDAR with project developer Emaar Misr on a revenue-sharing residential project in MADA, East Cairo. Under that revenue-sharing model, the project developer's commercial exposure extends beyond construction execution to the receipts generated by the development.
Geography Analysis
Greater Cairo Construction Market
Greater Cairo held a 49.25% share of the Egypt construction market size in 2026 and is also the fastest-growing geography, with a 9.3% CAGR forecast from 2027 to 2032. In July 2026, Cairo Governorate reported a cumulative 9,238 development projects in Cairo over the 12 years of President Abdel Fattah El-Sisi's leadership. In December 2025, Qatari Diar Egypt awarded Concrete Plus a New Cairo construction package covering 300 residential units and infrastructure works. The award covered one of CityGate's main construction packages, with delivery announced over 30 months. A single package pairing 300 homes with infrastructure works over an announced 30-month delivery window shows New Cairo residential work being contracted as a multiyear tranche.
In Alexandria, the prime minister inaugurated the 5-kilometer eastern Corniche expansion on June 7, 2026, combining marine protection with road capacity and beach access. The project between Montazah and Al-Mahrousa Hotel provided 5 traffic lanes in each direction, up from 3, alongside 17 beach-access gates and drainage. In Giza, the housing minister's August 29, 2026 review of Sheikh Zayed City's New Zayed expansion reported ongoing works on 132 kilometers of sewers and 80% completion of 95 kilometers of water networks. The commercial distinction is between delivering a protected coastal transport corridor and building the services needed for a new urban area, each with its own construction interfaces.
Rest of Egypt includes a rural utility-construction role illustrated by Haya Karima projects in Upper Egypt. In August 2026, the housing minister reviewed water and sanitation works including new pumping stations in Sohag and wastewater treatment plants serving several villages in Assiut. Reports from the National Authority for Potable Water and Sewage also identified advanced triple-treatment plants in Minya. Serving several villages through common treatment infrastructure shifts the delivery challenge toward connecting dispersed communities with shared facilities. Sohag's pumping stations, Assiut's village treatment plants, and Minya's triple-treatment plants show the program spreading across 3 governorates rather than concentrating in one.
Regulatory Framework and Outlook
This comparison of selected jurisdictions examines the national regime and Cairo Governorate's local permit process from a compliant private developer's perspective. Building Law 119/2008 requires permits for specified building work and conformity with approved planning conditions, Egyptian codes, and safety requirements. Local processing therefore has commercial importance because project documentation and technical review must align before authorized work can advance.
Regulatory Table of Egypt Construction Market
| Decision factor | Egypt | Cairo Governorate |
|---|---|---|
| Primary authority | Housing Ministry and competent local planning and organization authorities | Local-unit technology centers and planning and organization offices |
| Key instruments or direction | Building Law 119/2008, Articles 38-39; Housing Ministry Decision 943/2024 | Cairo Governorate's 2025 building-permit guide |
| Commercial effect | Permits and technical compliance required; ownership evidence accepted without a notarized-contract requirement | Guide gives 26 business days without an insurance-document requirement; 40 business days when required |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | No change | No change |
| Source: Mordor Intelligence | ||
The national medium rating balances simplified ownership documentation with mandatory permission and technical compliance. Cairo also rates medium because its guide defines a local processing sequence whose stated duration depends on insurance requirements. A March 2025 ministry draft paired simpler procedures with structural-safety and unauthorized-construction controls, while a separate MP-sponsored bill was referred to committees in March 2026. The continuity judgment for both reflects the operative permit-and-code framework and the combination of procedural simplification with continuing control objectives.
Value Chain Stages
The chain runs from cement and ready-mix supply through main construction contractors to mechanical, electrical, and plumbing (MEP) installers, each earning from its own sales or contract payments. Heidelberg Materials and Holcim Egypt produce cement and operate in ready-mixed concrete supply in Egypt. Gleeds reported that Egypt's April 2025 fuel-price increase affected construction delivery and budgeting, prompting developers and contractors to reassess pricing and risk-sharing mechanisms.
Value Chain Analysis Table of Egypt Construction Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Building-material production and supply | Cement and ready-mix producers such as Heidelberg Materials and Holcim Egypt | Cement, aggregate, and concrete sales | Fuel-sensitive transport costs | Match delivery schedules with transport-cost adjustment terms |
| Main construction execution | Construction contractors such as GAMA Construction and CRC Dorra | Construction contract payments | Coordination of civil and specialist interfaces | Assign interface responsibilities before releasing work packages |
| MEP and infrastructure installation | MEP contractors such as EMCOTECH | Installation and integration contract payments | Alignment of technical designs with installation sequencing | Coordinate drawings and staged acceptance points |
| Source: Mordor Intelligence | ||||
EMCOTECH's role in its New Alamein project is MEP and infrastructure work, with Palm Hills Developments as client and CRC Dorra as main contractor. That arrangement places the MEP specialist between development requirements and main-contractor execution, where unresolved interfaces can delay usable delivery. Unsettled design interfaces can therefore put the MEP specialist's installation earnings at risk even when its own technical work meets specification.
Competitive Landscape
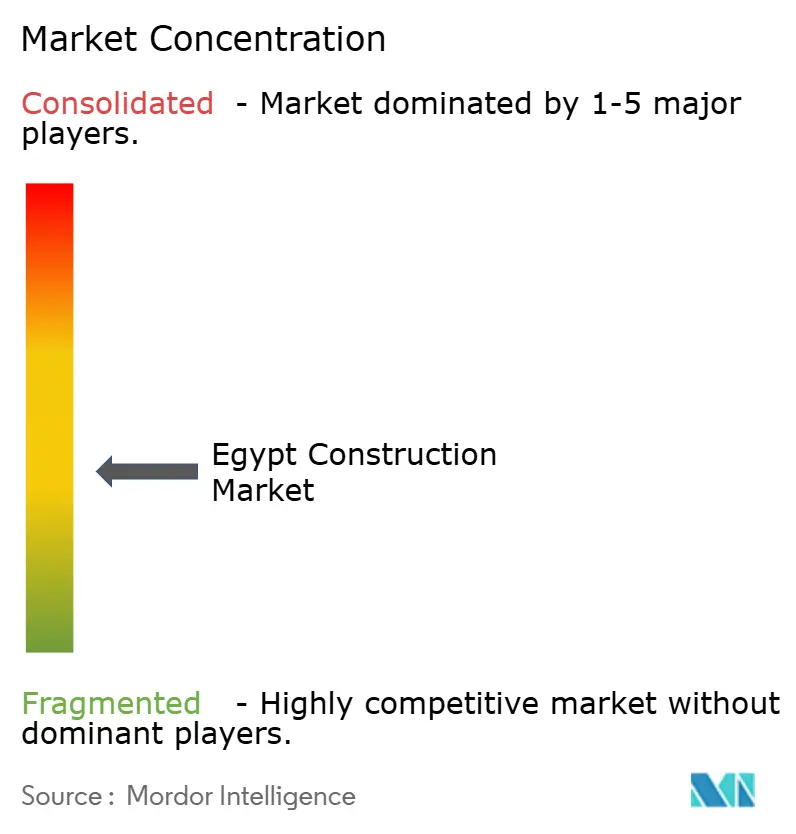
Competition combines a broad contractor base with a core of large firms able to assemble project-specific delivery partnerships. The Arab Contractors builds water purification plants, wastewater networks, and tunnels, while Orascom Construction PLC focuses on infrastructure and Egypt's new cities and national projects. They compete alongside Hassan Allam Holding, Elsewedy Electric (Engineering & Construction), and Petrojet. Egypt accounted for 54.3% of Orascom Construction PLC's consolidated backlog by geography as of December 31, 2025.[3] With Egypt holding more than half of the backlog, Orascom's revenue conversion depends more on Egyptian project delivery than on any other market in its order book.
In May 2025, Hassan Allam Construction, a subsidiary of Hassan Allam Holding, and The Arab Contractors won a joint venture contract to design, implement, and rehabilitate Alexandria's Raml Tram. The National Authority for Tunnels signed the agreement, whose scope covers a 13.2-kilometer line, 24 stations, a new maintenance depot, and elevated viaducts at key junctions. The combined scope joins route works with station and maintenance facilities, creating interfaces that require coordination across the delivery partnership. The award gives the public buyer one contracting group answerable for stations, depot, and viaducts together.
Elsewedy Electric's T&D unit energized the 66 kV system at Phase 1 of the El Menia Maqousa 220/66/11 kV substation on May 24, 2026. The project was implemented on a turnkey engineering, procurement, and construction basis. For a power-infrastructure buyer, the completion point is a functioning electrical system, which puts engineering scope and integration at the center of the contractor's proposition. Under Article 85 of Public Contracts Law 182/2018, administrative entities must maintain contractor and supplier registers, verify annual updates at least one month before the fiscal year, and verify and approve portal data before contracting. A turnkey contractor's proposition combines responsibility for an energized stage with documented eligibility wherever public procurement rules govern the award.
Egypt Construction Industry Leaders
-
The Arab Contractors
-
Orascom Construction PLC
-
Hassan Allam Holding
-
Elsewedy Electric (Engineering & Construction)
-
Petrojet
- *Disclaimer: Major Players sorted in no particular order
Egypt Construction Market Companies Covered in this Report
- The Arab Contractors
- Orascom Construction PLC
- Hassan Allam Holding
- Talaat Moustafa Group (TMG) Holding
- Palm Hills Developments
- SODIC
- Al Ahly Sabbour
- Elsewedy Electric (Engineering & Construction)
- GAMA Construction
- Redcon Construction
- Rowad Modern Engineering
- Samcrete Egypt
- Concord for Engineering & Contracting
- Dorra Group
- Osman Group
- Construction & Reconstruction Engineering Co. (CRC)
- China State Construction Engineering Corporation Egypt
- Petrojet
- SIAC Construction
- Misr Concrete Development Co.
- H.A. Construction (HAC)
Key Opportunities for Market Participants
These opportunities compare utility construction with phased mixed-use development, where funding structures and release conditions shape access to work. Public-private partnership (PPP) consortia provide a route to large public utility projects, while staged commercial development calls for preparation around conditional releases. Across both, a contractor's proposition depends on joining physical delivery to the financing or sequencing requirement of the buyer.
Market Opportunities Table of Egypt Construction Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Desalination-plant civil construction | September 2026 PPP offerings in Suez and Port Said planned a combined 1 million cubic meters per day over 2 phases | Public utility PPP sponsors | Form financing and construction consortia for phased plant works | Large financing and delivery commitments | Infrastructure contractors such as Orascom Construction PLC |
| Industrial wastewater construction packages | September 2026 planned PPP portfolio included 4 projects in Amreya, Abu Rawash, Port Said, and Wadi El Natrun | Public utility sponsors serving industrial areas | Offer repeatable civil packages adapted to each site | Coordinating separate project locations and implementation sequences | Water-works contractors such as The Arab Contractors |
| Phased retail and entertainment buildings | June 2026 MIDAR and Majid Al Futtaim agreement in MADA City, New Cairo provided for gradual later retail and entertainment development | Mixed-use master developers | Prepare building and infrastructure packages for future phased releases | Later retail development depends on construction progress and surrounding residential occupancy | New-city infrastructure contractors such as Orascom Construction PLC |
| Source: Mordor Intelligence | |||||
Utility construction offers the clearest route to demand where a public program has reached an offering stage. The September 2026 offerings named 2 desalination plants with a combined planned capacity of 1 million cubic meters per day over 2 phases. This phased capacity gives construction consortia a defined plant-stage opportunity within a broader planned water-infrastructure portfolio that also included 4 industrial wastewater projects.
Recent Industry Developments in Egypt Construction Market
- Oct 2026: Scatec, in partnership with EDF power solutions, started construction of the 900 MW Shadwan onshore wind project in Egypt on October 1.
- Jun 2026: MIDAR and Majid Al Futtaim signed a partnership on June 22 for an integrated urban development in MADA, New Cairo.
Egypt Construction Market Report Scope and Research Methodology
Market Definition and Coverage
The Egypt construction market measures annual nominal project-owner spending on new construction and major renovation projects in Egypt, including building and infrastructure works. The value covers on-site labor, materials, professional services, and contractor margins on publicly or privately funded projects delivered through conventional or modern construction methods.
Scope exclusions: Small-ticket repair and maintenance work, second-hand equipment rental, and off-shore engineering design performed outside Egypt are excluded.
Segments Covered in This Report
- By Sector
- Residential
- Apartments/Condominiums
- Villas/Landed Houses
- Commercial
- Office
- Retail
- Industrial and Logistics
- Others
- Infrastructure
- Transportation Infrastructure (Roadways, Railways, Airways, others)
- Energy & Utilities
- Others
- Residential
- By Construction Type
- New Construction
- Renovation
- By Construction Method
- Conventional On-Site
- Modern Methods of Construction (Prefabricated, Modular, etc)
- By Investment Source
- Public
- Private
- By Geography
- Greater Cairo
- Alexandria
- Giza
- Rest of Egypt
Data Sources, Market Sizing, and Validation
Desk Research
Official sources such as the Ministry of Planning, Economic Development and International Cooperation's 2025/2026 development plan and public-investment portal, its quarterly GDP note, and the New and Renewable Energy Authority's 2024 annual-report release provide information on public and private investment allocations, public spending by economic activity, construction growth and cement and steel sales as activity checks, and installed renewable capacity and generation statistics for the infrastructure pipeline.
Listed contractor filings and investor materials, including Orascom Construction's FY2025 results, can help cross-check revenue, backlog and awards without treating company revenue as market size. Reputable Egyptian project and cost reporting can help verify award dates, delivery stages and input-price changes. These sources are not exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
The fieldwork plan would cover project owners, public agencies, developers, contractors, engineering consultants, construction-material suppliers and financiers active in Egypt, with CXOs, functional or unit leaders, and managers represented. Interviews and structured surveys would test project budgets, timing, funding, cost and segment assumptions against documentary evidence, then investigate and reconcile material gaps before analysts update the estimate.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 15% | |
| Mid tier: 50% | Functional/Unit leaders: 35% | |
| Smaller Players: 20% | Managers: 50% |
Market-Sizing & Forecasting
The analyst estimates Egypt's annual nominal project-owner outlays in USD, counts each project's labor, materials, local professional services and contractor margins once, and builds the national total from construction activity and funded project programs. Construction activity growth and cement and steel sales indicate delivered work and material intensity. Public and private investment allocations, project awards and announced budgets indicate funding and timing. Renewable installed capacity and project pipelines help place infrastructure work, while labor, material and exchange-rate movements inform nominal cost growth. Analysts assign project values to the building or infrastructure sector, new construction or major renovation, construction method, funding source and Egyptian geography, then derive segment shares from classified project values. Scenario analysis carries the forecast forward using funded or awarded project schedules, expected private participation and plausible changes in costs and currency, with separate assumptions for projects whose timing or budget is less certain. Where announced awards can be linked to project budgets and delivery stages, the analyst uses them to check the national estimate through selective project roll-ups. If a sampled project budget or supplier roll-up is incomplete, the model uses a supported range, removes overlapping subcontractor or supplier invoices, and retains the unresolved item for analyst review rather than filling it with an unsupported value. Primary respondents can test timing, cost and funding assumptions for each forecast variable, while analysts compare their explanations with official indicators and project evidence before changing a scenario.
Data Validation & Update Cycle
Analysts triangulate official investment and construction activity data, project awards, company filings and market interviews. Independent signals such as cement and steel sales are checked against reported starts, completions and budget releases. Analysts investigate outliers, inconsistent units, duplicate project values and variances from prior periods, document the source and reason for each adjustment, and review the calculation and segment totals in successive analyst checks before sign-off. Analysts re-contact a respondent when a material project changes status, a reported budget or schedule conflicts with another source, or an unresolved gap could change the estimate. The team refreshes the model annually, revisits it between cycles after material funding, currency or project-pipeline events, and completes a fresh source and calculation review before delivery.
Mordor Intelligence's Egypt Construction Market Size Versus Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The Egypt construction market measures annual nominal project-owner spending on new construction and major renovation projects in Egypt, including building and infrastructure works.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Primary respondents can test timing, cost and funding assumptions for each forecast variable, while analysts compare their explanations with official indicators and project evidence before changing a scenario.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 55 B (2027) | |
| Regional Market Research Firm A | USD 1.31 B (2025) | At its 2025 base, this estimate is 97.6% below this report's 2027 value of USD 55 B, 2 years later. Its stated market covers residential and non-residential building construction, whereas this report also counts infrastructure project spending. |
| Global Market Research Firm B | USD 29.32 B (2025) | At its 2025 base, this estimate is 46.7% below this report's 2027 value of USD 55 B, 2 years later. Its page forecasts continued market growth, so the published value precedes this report's later measurement year. |
Mordor Intelligence's analysts triangulate official investment and construction activity data, project awards, company filings and market interviews.
Key Questions Answered in the Report
What is the Egypt construction market size and growth outlook?
The size is projected at USD 55 billion in 2027 and USD 75.07 billion by 2032, with a 6.42% CAGR from 2027 to 2032.
What drives construction demand in Egypt?
Egypt's renewable capacity reached approximately 9.1 GW in FY2025/26, while public housing finance and transport projects also support construction demand.
Which sector leads construction activity in Egypt?
Residential construction held the largest sector share at 44.58% in 2026.
Which companies lead construction activity in Egypt?
Leading contractors include The Arab Contractors, Orascom Construction PLC, Hassan Allam Holding, Elsewedy Electric (Engineering & Construction), and Petrojet.
What is the main cost challenge for Egyptian construction contractors?
An Egyptian contractors' association head estimated in June 2026 that no less than 40% to 50% of project money went to imported supplies, equipment, or electromechanical works in foreign currency. That leaves costs exposed to exchange-rate movements.
Which area leads construction activity in Egypt?
Greater Cairo held 49.25% of the market in 2026 and is the fastest-growing geography, with a 9.3% CAGR forecast from 2027 to 2032.