
Automotive Die Casting Lubricants Market Size and Share
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
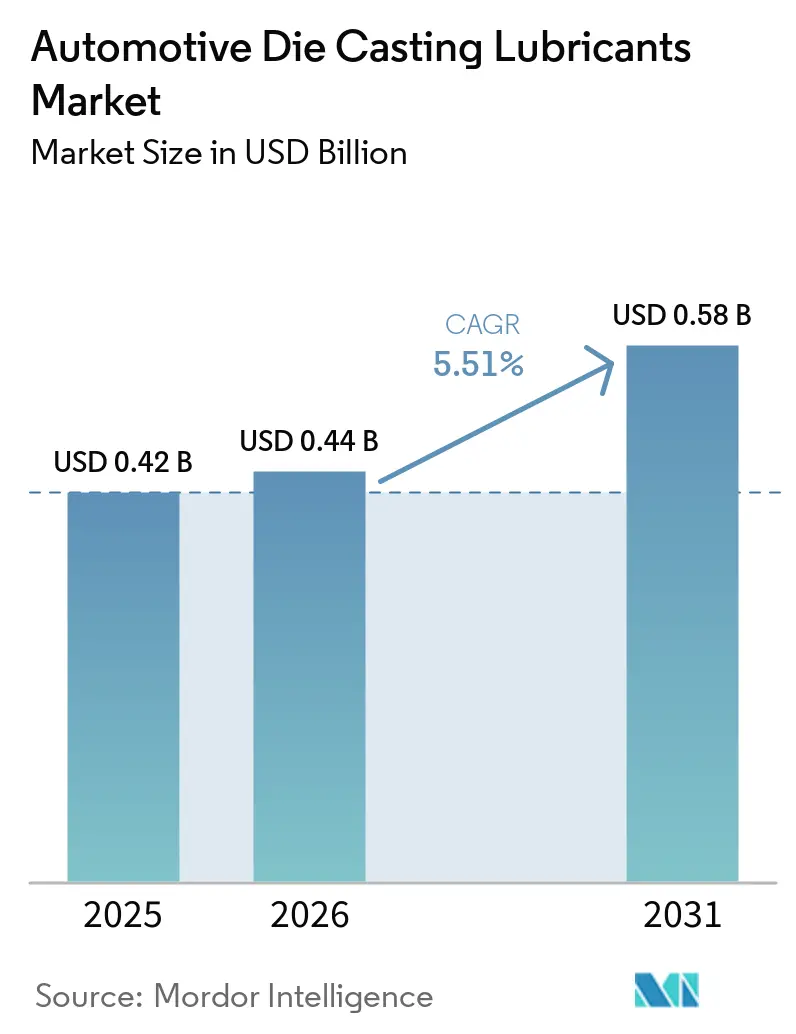
| Market Size (2026) | USD 0.44 Billion |
| Market Size (2031) | USD 0.58 Billion |
| Growth Rate (2026 - 2031) | 5.51 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | Asia-Pacific |
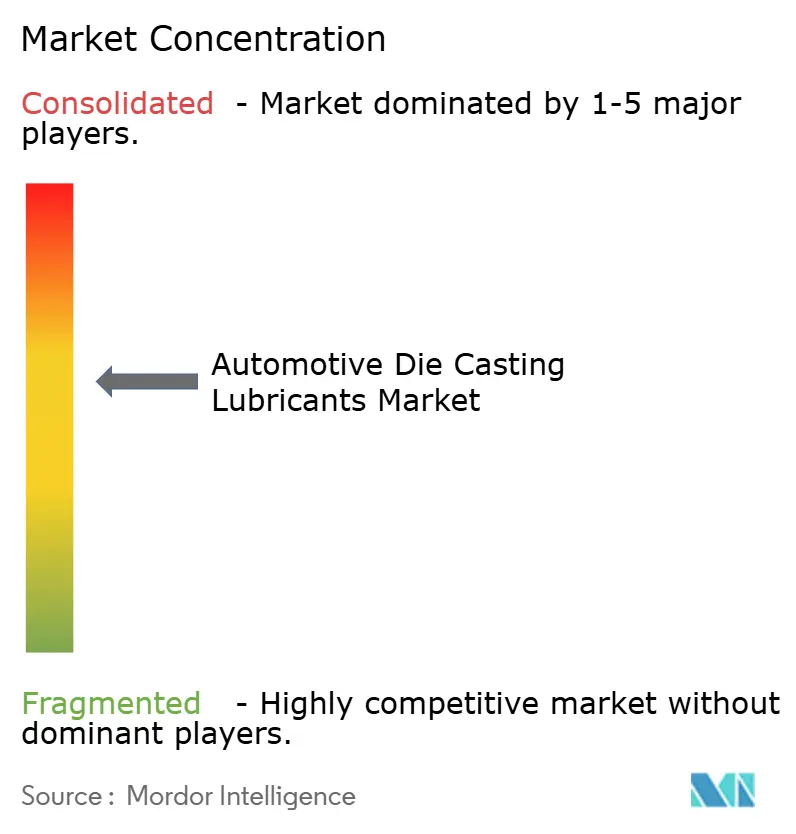
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Automotive Die Casting Lubricants Market Analysis by Mordor Intelligence
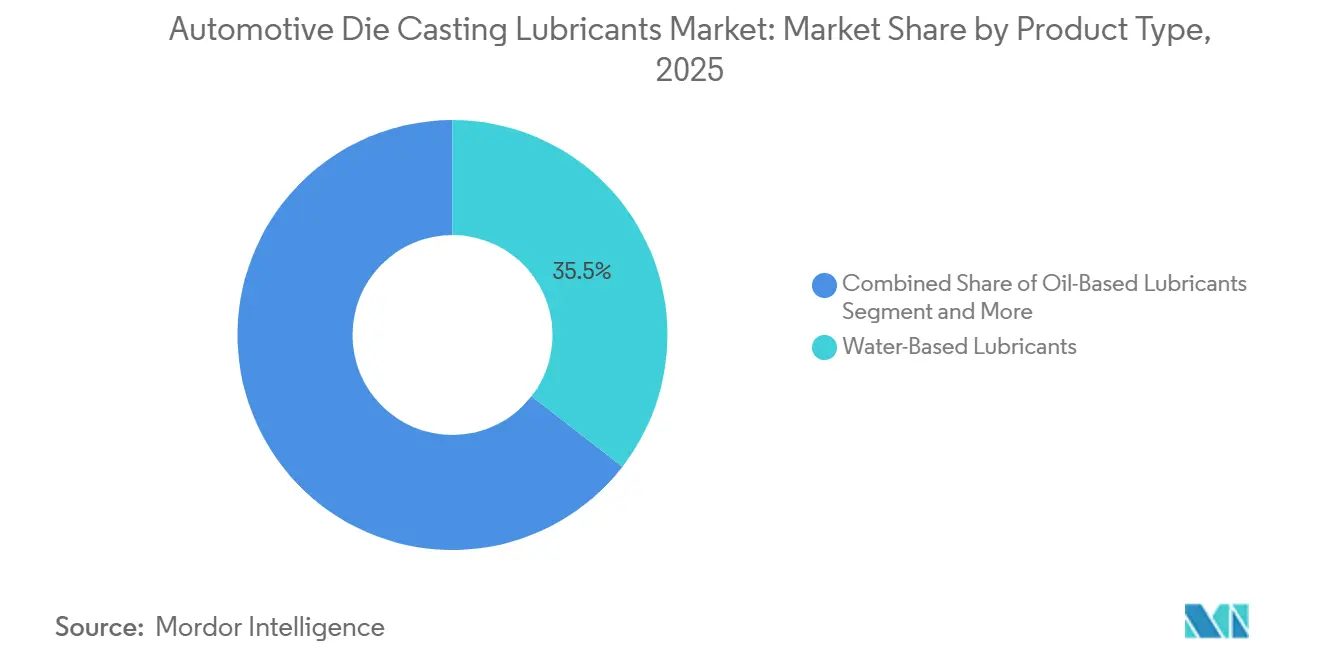
The Automotive Die Casting Lubricants Market size was valued at USD 0.42 billion in 2025, is expected to reach USD 0.44 billion in 2026, and is projected to reach USD 0.58 billion by 2031, at a CAGR of 5.51% during the forecast period (2025-2030). Electric-vehicle platforms are increasingly opting for a few large structural "mega-castings" that are significantly heavier, replacing numerous smaller castings. This transition is enhancing the lubricant value per shot, even as the number of parts decreases. With Gigapress clamp forces reaching extremely high levels, thermal stress on dies has intensified. This development is driving a preference for extreme-pressure oil-based chemistries, although water-based products still lead in medium-tonnage applications, holding 35.47% of total 2025 revenue. Stricter regulations on volatile organic compounds (VOC) in regions such as California, the European Union, and coastal areas of China are accelerating the adoption of advanced electrostatic spray systems. These systems not only provide environmentally friendly, solvent-free films but also significantly reduce overspray, improving efficiency. In the Asia-Pacific region, the market is witnessing substantial growth and capacity expansion, with major investments in facilities aimed at localizing giga-casting for electric vehicles designed for the mass market.
Key Report Takeaways
- By product type, water-based lubricants held 35.47% of the Automotive Die Casting Lubricants market share in 2025, while oil-based grades are poised for the fastest 6.55% CAGR through 2031.
- By application, aluminum die casting captured 56.71% of the Automotive Die Casting Lubricants market size in 2025; magnesium is projected to post a 6.53% CAGR to 2031.
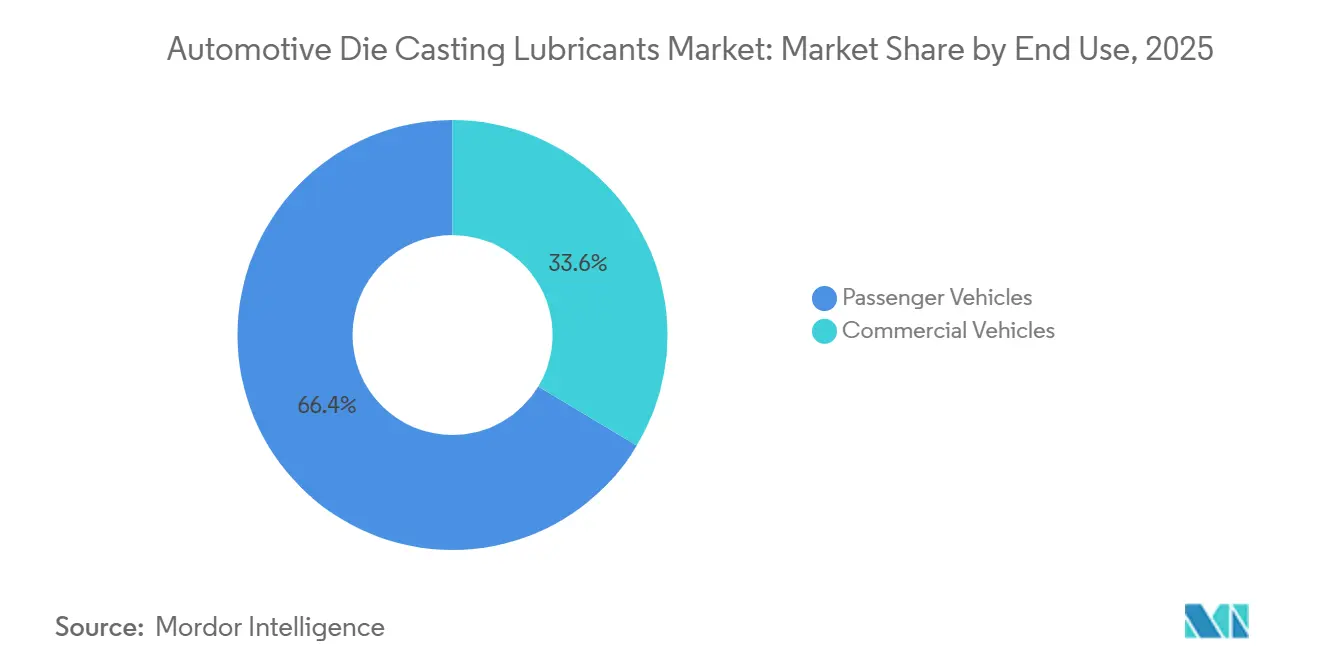
- By end use, passenger vehicles accounted for 66.37% of demand in 2025, whereas commercial vehicles will advance at a 7.61% CAGR, buoyed by electrified last-mile vans.
- By functional use, the die slick led with 28.71% share in 2025, yet the plunger slick is anticipated to rise at a 7.57% CAGR on the back of 60 kg-plus shot weights.
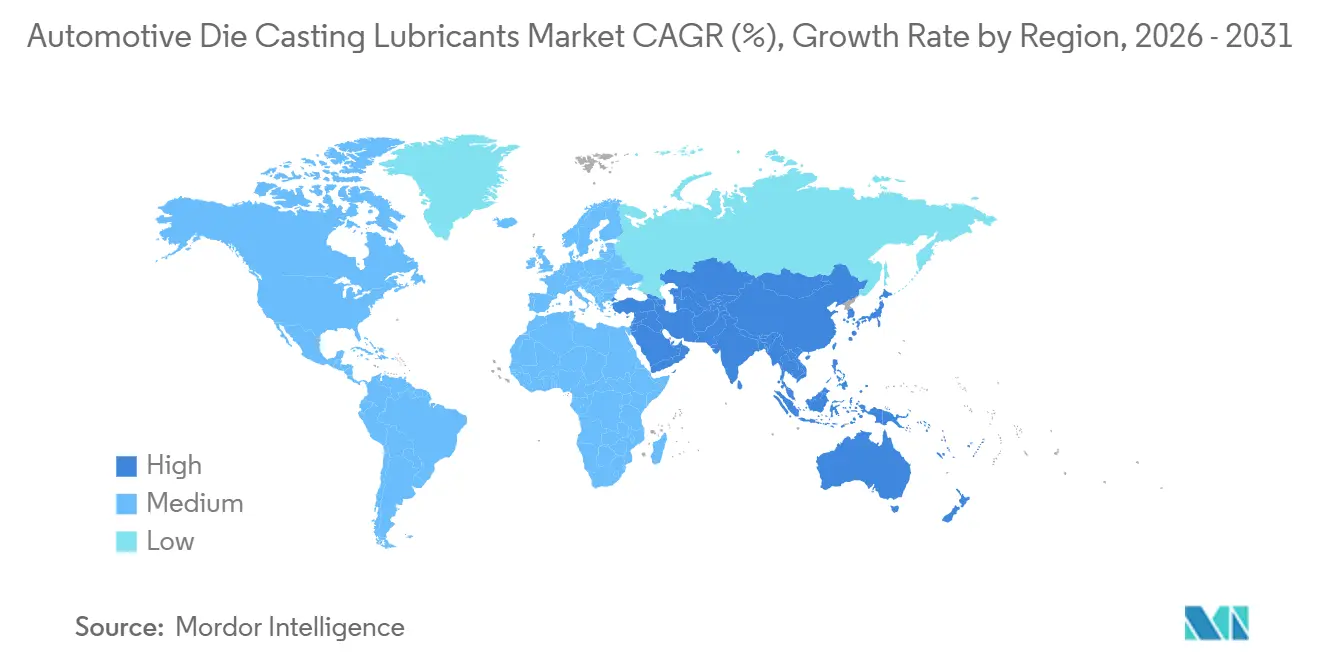
- By geography, Asia-Pacific dominated with a 45.55% revenue share in 2025 and registered the highest 8.59% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Automotive Die Casting Lubricants Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rapid Growth of Asia-Pacific Die-Casting Hubs | +1.4% | China, India, Thailand, Vietnam | Long term (≥ 4 years) |
| High-Pressure and Giga-Casting Adoption | +1.3% | Asia-Pacific core, spill-over to North America and EU | Medium term (2-4 years) |
| EV And Lightweighting Push | +1.2% | Global, with Asia-Pacific and North America leading adoption | Medium term (2-4 years) |
| Stricter VOC And ESG Regulations | +0.9% | EU, California, China Tier-1 cities | Short term (≤ 2 years) |
| Shift to Water-Free Electrostatic Lubricants | +0.8% | North America, Europe, China coastal hubs | Short term (≤ 2 years) |
| Smart-Factory Dispensing and Monitoring | +0.6% | Germany, Japan, South Korea, select U.S. plants | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Rapid Growth of Asia-Pacific Die-Casting Hubs
Wencan has made a significant investment in its Chongqing plant, equipping it with advanced presses specifically designed for Changan Deepal's battery trays. This operation requires a substantial volume of humidity-tolerant, water-based lubricants annually to ensure optimal performance. In India, the government’s Production-Linked Incentive (PLI) scheme is fostering notable capacity growth, with major players like Tata and Mahindra focusing on localizing electric vehicle components. In Thailand, the approval of large-scale die-casting projects aimed at serving Japanese original equipment manufacturers (OEMs) has prompted Quaker Houghton to establish a dedicated technology center in Bangkok.
High-Pressure and Giga-Casting Adoption
Guangdong Hongtu has embarked on a significant venture, deploying multiple high-capacity presses. These presses are set to produce structural components for Xpeng and Li Auto. Once fully operational, the facility will utilize a substantial amount of lubricant annually. In a parallel move, Ryobi made a considerable investment in a high-capacity line dedicated to Toyota's BEV cross-members. This line is further enhanced with Quaker Houghton’s minimum-quantity-lubrication (MQL) package. Meanwhile, graphite-boron-nitride hybrids have secured a notable share in the giga-casting lubricant blend, due to their resilience, enduring extensive usage at high die temperatures. Linamar's large-scale plant in Pune underscores a significant trend: mega-casting is now transitioning to mass-market EVs, priced within an affordable range, expanding beyond just premium models.
EV and Lightweighting Push
Battery-electric architectures are streamlining production by consolidating dozens of stampings into single-shot aluminum castings. These castings can boast a die surface area significantly larger than traditional designs, leading to a notable increase in lubricant demand per cycle compared to legacy sub-frames [1]. At Gigafactory Texas, Tesla's rear underbody cell showcases the power of single casting: it replaces hundreds of individual parts but demands semi-permanent coatings, engineered to endure extensive production runs. Nio's ET9 front mega-casting not only eliminates numerous welds but also reduces body-shop time considerably, amplifying the demand for lubricant per shot. Volvo's shift to advanced alloys for its EX90 giga-castings is driven by the alloy's higher silicon content, which boosts the need for oil-based formulations fortified with robust anti-soldering agents. Adding to this trend is mounting regulatory pressure: the EU's upcoming CO₂ fleet cap imposes significant fines on OEMs for exceeding emission limits, fueling a competitive race for substantial weight reduction [2].
Stricter VOC and ESG Regulations
Under the EU’s Industrial Emissions Directive, foundries with significant daily processing volumes must continuously monitor VOCs. This regulation nudges them towards adopting water-free or semi-permanent lubricants within a few years. Meanwhile, China's Cleaner-Production Plan ties tax rebates to a stringent VOC intensity threshold, hastening the industry's pivot to electrostatic-compatible concentrates. Recently, Fuchs launched Ecocool Global 20, a rapeseed-ester water-dilutable lubricant, which not only met EU Ecolabel standards but also garnered the nod from Volkswagen. Henkel's revamped Bonderite L-CA, stripped of aromatics, secured endorsements from both Tesla and GM for North America's giga-presses. Nowadays, ESG scorecards wield significant influence; suppliers lacking cradle-to-gate Life Cycle Assessments (LCAs) face the threat of delisting.
Restraints Impact Analysis of Automotive Die Casting Lubricants Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Raw-Material Price Volatility | -0.5% | Global, acute in regions dependent on imported esters | Short term (≤ 2 years) |
| EV Power-Unit Simplification | -0.4% | North America, EU, China | Medium term (2-4 years) |
| Thermal-Management Limits | -0.3% | Asia-Pacific high-pressure foundries, North America giga-casting cells | Medium term (2-4 years) |
| Skills Gap in Lubricant Optimization | -0.2% | India, Southeast Asia, Mexico | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Raw-Material Price Volatility
In 2024, prices for synthetic esters and surfactants experienced a significant increase, despite a decline in LME aluminum prices, which put pressure on supplier margins. A sharp rise in palm-derived surfactants occurred when Indonesia restricted exports, leading to a greater reliance on more expensive synthetic alternatives. Smaller formulators in India and Mexico, lacking hedging tools, faced revenue losses to maintain contracts. At the same time, a depreciation of the Yuan increased the landed cost of European lubricants, prompting China to accelerate its transition to domestic blends. These market fluctuations are encouraging a shift towards vertical integration and a preference for lightweight inventory models.
EV Power-Unit Simplification (Fewer Cast Parts)
Tesla's Model Y uses significantly fewer parts compared to traditional gasoline sedans, which helps reduce shot counts despite incorporating larger castings. Meanwhile, GM's Ultium technology consolidates multiple aluminum components into a few mega-castings, resulting in a notable reduction in lubricant usage per vehicle. On the other hand, BYD's Seagull, designed as an affordable option, employs stamped steel to lower costs, significantly reducing its reliance on die-casting compared to conventional internal combustion engine standards. While premium coatings, which are considerably more expensive than standard water-based grades, help offset some volume losses, a substantial structural challenge remains.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Automotive Die Casting Lubricants Market Segment Analysis
By Product Type:
Oil-Based Formulations Gain in Extreme-Pressure CellsOil-based grades are forecast to expand at a 6.55% CAGR, outpacing the overall Automotive Die Foundries operating presses with significant tonnage rely on these chemistries to maintain film integrity at high temperatures, a critical zone where water tends to evaporate prematurely. Toyota's Tahara knuckle line has adopted semi-permanent graphite or boron-nitride coatings, applied periodically, resulting in a substantial extension of die life and a notable reduction in tooling costs. Notably, solvent products enjoy exemptions from the EU 2024/1785 and California Rule 1171 regulations.
Water-based lubricants retain a cost edge at USD 3.80/kg versus USD 6.20 for oil-based lubricants and dominate sub-3,500 ton presses, producing housings and mounts, with a share of 35.47% in 2025. Quaker Houghton’s electrostatic delivery closes some performance gaps, enabling water-based use up to 5,000 tons, yet giga-press dominance ensures oil-based share growth. Bio-feedstock adoption quickens: Henkel’s rapeseed-ester Bonderite line now appears on Tesla and GM-approved lists, turning ESG compliance into a ticket-to-play.

By Application:
Aluminum Dominance Masks Magnesium’s Structural PivotAluminum accounted for 56.71% of the Automotive Die Casting Lubricants market size in 2025. Its recycling compatibility with EU circular economy quotas and weight advantage over steel sustains its leadership. High-silicon Al-Si casting alloys enable Volvo's EX90 rear floor to drop 68 spot welds.
Magnesium’s 6.53% CAGR stems from Chinese EV makers using front-end modules to offset battery mass; BYD’s Han saved 4.2 kg per beam. Fire-risk mitigation requires a significant investment in inert-atmosphere casting lines, which slows Western uptake; however, SF6-free cover gases improve safety compliance. Zinc remains niche for trim where surface finish trumps weight, but its share falls as sub-USD 30,000 EVs strip decorative content.
By End Use:
Commercial Vehicles Outpace Passenger Segment on ElectrificationPassenger vehicles accounted for 66.37% of the 2025 revenue; however, electrified vans and medium-duty trucks are expected to grow lubricant revenues at a faster rate, with a 7.61% CAGR through 2031. Amazon's Rivian vans incorporate multiple large castings, significantly exceeding the footprint of traditional gasoline vans. Meanwhile, Daimler's eActros 600 relies on a heavy battery tray, crafted with semi-permanent lubricants, ensuring durability for extensive production runs.
In the commercial fleet world, every kilogram counts. Even a small weight reduction can translate to substantial additional annual revenue, justifying investments in premium formulations. The approach varies among passenger OEMs: while premium brands showcase advanced mega-casting technology, more budget-conscious brands, exemplified by BYD Seagull, opt for fewer castings, moderating their passenger growth trajectory.
By Functional Use:
Plunger Slick Rises as Shot Weights ClimbDie slick led with 28.71% share, but plunger slick will advance at 7.57% as 60 kg shots push plunger-sleeve friction beyond 400 °C. Chem-Trend’s molybdenum-enhanced MONO-COAT cut Cybertruck plunger scrap.
Plunger slicks, priced at a premium, are less frequently applied but effectively narrow revenue differentials. Henkel's versatile Bonderite L-CA 3600, acting as both a die and plunger slick, streamlines inventory for smaller presses. Demand solidifies as only premium plunger slicks satisfy the vapor-pressure limits set by vacuum-assist casting.
Geography Analysis
APAC Automotive Die Casting Lubricants Market
The Asia-Pacific region held a 45.55% market share of the Automotive Die Casting Lubricants market in 2025 and is expected to post a 8.59% CAGR from 2026 to 2031. China alone poured millions of tons of die-castings, three-fifths of which were for autos, as BYD, Nio, and Xpeng accelerated giga-casting to cut model launch cycles to 18 months [3]. Meanwhile, Japan's Ryobi, with its advanced production line, is directly feeding Toyota's battery electric vehicle (BEV) production. South Korea's E-GMP program is integrating multiple mega-castings per vehicle, sourced domestically. In India, several projects backed by the Production-Linked Incentive (PLI) scheme, which involves substantial investment, are enabling local lubricant blending at a significantly lower cost than imports.
North America Automotive Die Casting Lubricants Market
North America is witnessing a surge in reshoring activities. Notably, Tesla's Texas facility stands out as the region's largest consumer, utilizing a substantial volume of lubricants annually. In a strategic move, Mino, Form Technologies, and Eck Industries have collectively invested significantly to boost their capacity by a considerable amount. Meanwhile, Mexico's Guanajuato hub is playing a pivotal role, servicing major automotive players like GM's Ultium and Ford's F-150 Lightning. On the other hand, Canadian suppliers are channeling a significant investment towards battery housings, showcasing a clear pivot in their focus.
Europe and South America Automotive Die Casting Lubricants Market
Europe grapples with challenges, notably soaring energy prices and the impending solvent phase-out. In a testament to regional collaboration, Germany's Baden-Württemberg cluster is supplying a notable volume annually of water-based products to Volkswagen's Zwickau EV plant. Stellantis has made strategic moves by localizing battery trays in both Lombardy and Piedmont, resulting in a notable growth in output. Spain's Catalonia die casters have invested substantially in press upgrades for the Cupra brand. Meanwhile, the UK is enforcing local-content regulations, mandating that a significant portion of parts be of UK origin in a post-Brexit landscape. South America, though still a niche player, is on an upward trajectory.
Competitive Landscape
In 2025, the leading suppliers—Henkel, Chem-Trend, Quaker Houghton, FUCHS, and MORESCO—accounted for a significant share of revenue in the Automotive Die Casting Lubricants Market, indicating a moderately concentrated market structure. At the regional level, independent suppliers such as Ultraseal India and Hardcastle Petrofer have captured dominant shares in their domestic markets. They strategically co-locate their laboratories near Tier-1 foundries, enabling same-day reformulations.
Technology remains the key differentiator in this market. In recent years, Quaker Houghton launched FLUIDCAST E-STATIC, supported by multiple US patents related to charge-transfer technology. This launch prompted immediate counterfilings from major competitors Henkel and Chem-Trend. FUCHS has also made significant progress with its rapeseed-based ECOCOOL GLOBAL lubricant, capturing a notable share of Europe’s giga-casting segment within a short period due to its substantial die-life extension. Meanwhile, Chinese disruptor Lubgraf Synoils leverages its backward-integrated surfactant lines to undercut global prices by a considerable margin, securing contracts with major players such as BYD and Xpeng.
Companies are pursuing several key strategic approaches. First, they are co-locating technical centers: Quaker Houghton stationed engineers at Linamar Pune recently to accelerate local approvals. Second, they are bundling hardware with chemical offerings: Henkel’s recent acquisition of German IoT firm Monixo enables the company to offer integrated solutions that combine closed-loop spray monitoring with its chemical products. Finally, press-OEM alliances are gaining traction. Chem-Trend’s certification agreement with Idra for high-capacity machines positions the company to secure first-fill contracts as these presses are shipped.
Automotive Die Casting Lubricants Industry Leaders
-
Acme Refining
-
Chem-Trend L.P.
-
CHEMTOOL Incorporated
-
The Hill and Griffith Company
-
Quaker Houghton Inc.
- *Disclaimer: Major Players sorted in no particular order
Automotive Die Casting Lubricants Market Companies Covered in this Report
- Henkel AG & Co. KGaA
- Chem-Trend L.P.
- Quaker Houghton Inc.
- MORESCO Corporation
- FUCHS Lubritech GmbH
- The Hill and Griffith Company
- Geiger + Co. Schmierstoff-Chemie GmbH
- Ultraseal India Pvt. Ltd.
- Acme Refining
- CHEMTOOL Incorporated
- Condat Group
- Hardcastle Petrofer Pvt. Ltd.
- Sunocs LLC
- J&S Chemical Corporation
- Lubgraf Synoils Pvt. Ltd.
- Münch Chemie International
- Falcon Industrial Inc.
- Tower Metalworking Fluids
- Applied Material Solutions
- Daeho Industries Ltd.
- Thermal-Lube Inc.
Read Analysis of Automotive Die Casting Lubricants Companies
Recent Industry Developments in Automotive Die Casting Lubricants Market
- July 2026: Castrol, one of the world’s best-known lubricant brands, came under new ownership after bp received approval to sell the business to investment firm Stonepeak. The Namibia Competition Commission (NaCC) approved the transaction without conditions. Under the deal, Motion JVCo Limited acquired all shares and voting rights in Castrol Group Holdings Limited, marking another milestone in bp’s strategy to reshape its global business portfolio.
- April 2025: Quaker Houghton acquired Japan-based Dipsol Chemicals for approximately USD 155.2 million. Dipsol is a leading provider of surface treatment and plating solutions that primarily serve the automotive sector.
- February 2025: Private-equity firm Architect Equity acquired Gibbs Die Casting Corporation, a major manufacturer of precision die-cast parts for EV, hybrid, and internal-combustion vehicles.
Global Automotive Die Casting Lubricants Market Report Scope
The scope of the report includes Product Type (Water-Based, Oil-Based, and More), Application (Aluminum and More), End Use (Passenger Vehicles and Commercial Vehicles), Functional Use (Die Slick and More), and Geography. The Market Forecasts are Provided in Value (USD).
Segmentation Overview
| Water-Based Lubricants |
| Oil-Based Lubricants |
| Semi-Permanent Lubricants |
| Solvent-Based Lubricants |
| Aluminum Die Casting |
| Magnesium Die Casting |
| Zinc Die Casting |
| Passenger Vehicles |
| Commercial Vehicles |
| Die Slick |
| Plunger Slick |
| Ladle Slick |
| Assembly Slick |
| Others |
| North America | United States |
| Canada | |
| Rest of North America | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Spain | |
| Rest of Europe | |
| Asia-Pacific | China |
| India | |
| Japan | |
| South Korea | |
| Rest of Asia-Pacific | |
| Middle East and Africa | United Arab Emirates |
| Saudi Arabia | |
| South Africa | |
| Turkey | |
| Rest of Middle East and Africa |
| By Product Type | Water-Based Lubricants | |
| Oil-Based Lubricants | ||
| Semi-Permanent Lubricants | ||
| Solvent-Based Lubricants | ||
| By Application | Aluminum Die Casting | |
| Magnesium Die Casting | ||
| Zinc Die Casting | ||
| By End Use | Passenger Vehicles | |
| Commercial Vehicles | ||
| By Functional Use | Die Slick | |
| Plunger Slick | ||
| Ladle Slick | ||
| Assembly Slick | ||
| Others | ||
| By Geography | North America | United States |
| Canada | ||
| Rest of North America | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Spain | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| India | ||
| Japan | ||
| South Korea | ||
| Rest of Asia-Pacific | ||
| Middle East and Africa | United Arab Emirates | |
| Saudi Arabia | ||
| South Africa | ||
| Turkey | ||
| Rest of Middle East and Africa | ||
Key Questions Answered in the Report
What is the projected value of the Automotive Die Casting Lubricants market in 2031?
The sector is forecast to reach USD 0.58 billion by 2031 based on a 5.51% CAGR.
Which product type is expanding fastest?
Oil-based formulations are slated for a 6.55% CAGR as giga-press temperatures exceed 350 °C.
Why is Asia-Pacific the leading region?
China, India, and Southeast Asia are adding mega-casting capacity and localizing EV supply chains, driving a 8.59% regional CAGR.
How are VOC regulations shaping lubricant choice?
Sub-50 g/L VOC caps in the EU, California, and coastal China are catalyzing a shift to water-free electrostatic or semi-permanent chemistries.
What drives rising demand in commercial vehicles?
Electrified delivery vans and medium-duty trucks require larger corrosion-resistant die-cast battery enclosures and the use of lifting lubricant per vehicle.
Which companies dominate the competitive landscape?
Henkel, Chem-Trend, Quaker Houghton, FUCHS, and MORESCO collectively control almost half of global revenue, with regional specialists strong in India and China.