
UAE Industrial Asset Inspection Services Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
| Base Year Market Size (2026) | USD 0.85 Billion |
| Market Size (2027) | USD 0.91 Billion |
| Market Size (2032) | USD 1.45 Billion |
| Growth Rate (2027 - 2032) | 9.80 % |
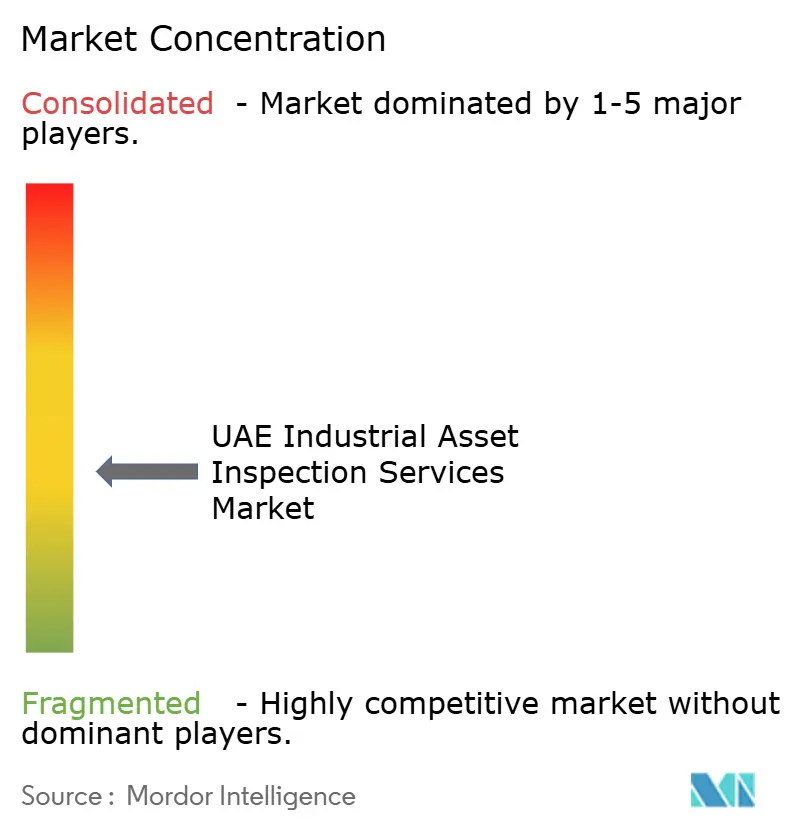
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
UAE Industrial Asset Inspection Services Market Analysis by Mordor Intelligence
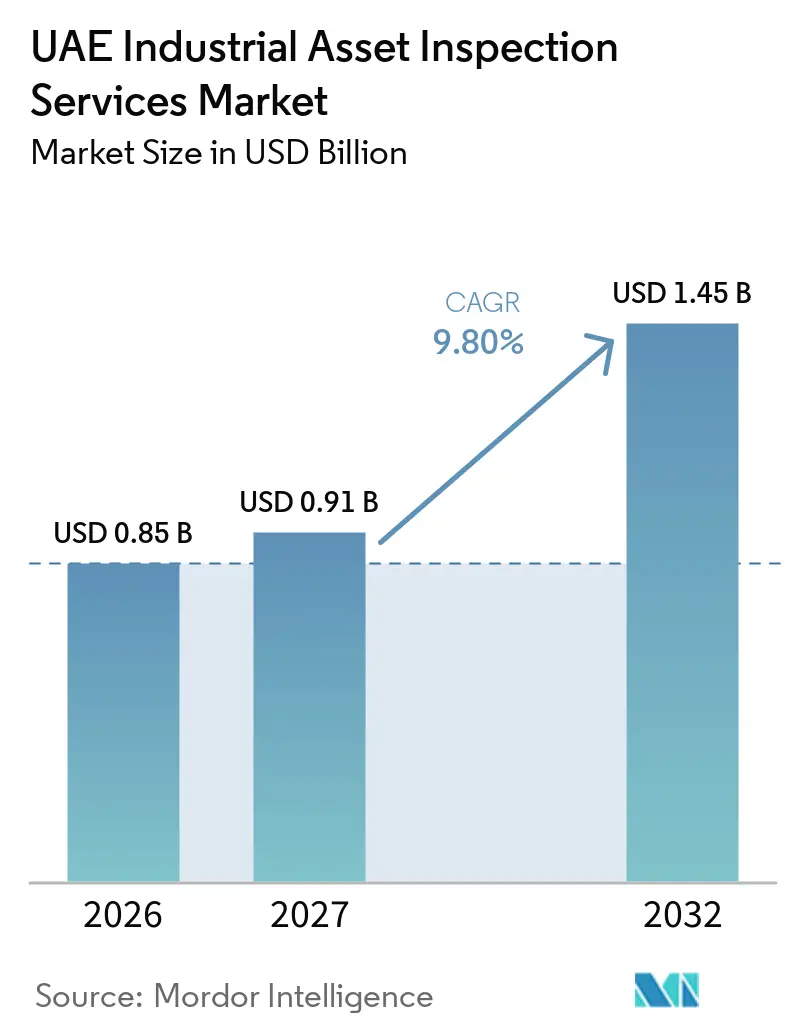
The UAE Industrial Asset Inspection Services Market was valued at USD 0.85 billion in 2026, USD 0.91 billion in 2027, and is expected to reach USD 1.45 billion by 2032, at a CAGR of 9.8% during 2027-2032.
The UAE industrial asset inspection services market is supported by investment in oil and gas, chemicals, gas processing, electricity networks, and renewable generation. ADNOC’s USD 150 billion capital plan for 2026-2030 adds long-life infrastructure that will require inspection throughout construction and operation. Accreditation requirements, recurring equipment checks, and major utility programs provide a steadier base of work than project activity alone. Digital inspection tools can improve data quality and reduce shutdown time, but they also move spending toward analytical capability and away from labor-intensive scopes. Providers that combine hydrocarbon credentials with electrical inspection, robotics, and data-management capability are better placed to serve the changing UAE industrial asset inspection services market.
Key Report Takeaways
- By asset type, pipelines and piping systems held 27.0% of the UAE industrial asset inspection services market share in 2026, while electrical and power equipment is forecast to expand at an 11.0% CAGR through 2032.
- By end-use industry, oil and gas, refining and petrochemicals held 38.0% of the UAE industrial asset inspection services market size in 2026, while power generation, renewable energy and electrical utilities are forecast to expand at an 11.5% CAGR through 2032.
- Growing investments in the UAE’s oil and gas, petrochemical, power generation, and industrial infrastructure sectors are increasing demand for periodic inspections, non-destructive testing, and asset integrity management services to improve operational safety, reliability, and equipment lifespan.
- The adoption of AI-enabled inspection analytics, drones, robotics, and remote inspection technologies is creating opportunities for service providers to improve defect detection, reduce inspection downtime, enhance worker safety, and support data-driven maintenance planning across the UAE’s industrial facilities.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
UAE Industrial Asset Inspection Services Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| ADNOC Asset Integrity and Capacity Expansion Programs | +2.5% | Abu Dhabi, with spillover to offshore UAE | Long term (≥ 4 years) |
| Expansion of Refining, Petrochemical, Gas Processing and Storage Infrastructure | +2.1% | Al Ruwais Industrial City, Abu Dhabi, and Jebel Ali, Dubai | Long term (≥ 4 years) |
| Mandatory Pressure Equipment and Lifting Equipment Inspection Cycles | +1.6% | UAE, concentrated in Abu Dhabi and Dubai | Medium term (2-4 years) |
| Rising Adoption of Advanced and Digital Inspection Technologies | +1.2% | UAE, with early gains in Abu Dhabi and Dubai free zones | Medium term (2-4 years) |
| Condition Monitoring Demand from Aging and High-Criticality Assets | +0.9% | Abu Dhabi and Dubai, with spillover to Sharjah and Fujairah | Long term (≥ 4 years) |
| UAE-Based Deployment of Robotic and Drone Inspection Fleets | +0.6% | UAE, with regulatory concentration in Abu Dhabi and Dubai | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
ADNOC Asset-Integrity and Capacity-Expansion Programs
ADNOC’s asset integrity programs create inspection work across operating assets and new capital projects in the UAE industrial asset inspection services market. ADNOC Gas reported USD 3.6 billion in capital expenditure in 2025, up 98% from the prior year, as projects including Phase 1 of the Rich Gas Development Project progressed. The wider ADNOC plan covers upstream expansion, the Ghasha concession, chemicals production, and gas processing. Ghasha is targeted to produce 1.8 billion standard cubic feet of gas per day and 150,000 barrels per day of oil and condensates. Each completed facility expands the base of equipment subject to in-service integrity work. This favors providers with multi-year framework positions rather than firms dependent only on individual project awards.
Expansion of Refining, Petrochemical, Gas-Processing and Storage Infrastructure
New capacity in Al Ruwais adds inspection work without displacing established refinery workloads in the UAE industrial asset inspection services market. Bureau Veritas received an inspection contract in January 2026 for the TA’ZIZ Chemicals Industrial Zone, covering site work in the UAE and source inspection in Vietnam, China, Germany, South Korea, and the United States.[1] TA’ZIZ targets 4.7 million tons per year of chemicals output across methanol, ammonia, PVC, and caustic soda plants. These facilities require inspection of high-pressure reactors, piping, vessels, tanks, and containment equipment under relevant API, ASME, and other project requirements. Their operating lives create recurring demand after construction is complete. The mix of local and international source inspections also increases the value of providers with cross-border quality systems and project data tools.
Mandatory Pressure-Equipment and Lifting-Equipment Inspection Cycles
Required checks of pressure and lifting equipment form the baseline of non-discretionary work in the UAE industrial asset inspection services market. Accredited inspection bodies must meet national accreditation requirements, maintain equipment traceability, and issue valid inspection documentation under the UAE conformity assessment system.[2] Dubai requirements apply across relevant free-zone and special development areas, while energy assets also face emirate-level oversight. Asset owners therefore need qualified providers for recurring pressure, lifting, and integrity checks even when new capital projects slow. Aging and high-criticality equipment adds demand for condition monitoring, vibration analysis, corrosion assessment, and in-service testing. The result is a renewable revenue base that is less dependent on any one year of construction activity.
Rising Adoption of Advanced and Digital Inspection Technologies
Phased-array ultrasonics, time-of-flight diffraction, defect recognition tools, and robotic platforms are changing service delivery in the UAE industrial asset inspection services market. ADNOC Gas entered a multi-year agreement with AIQ and Gecko Robotics in November 2025 to use AI-powered inspection robotics at gas-processing facilities. The program is expected to generate more than USD 300 million in maintenance and inspection savings over five years through predictive maintenance, shorter shutdowns, and longer asset life. Digital records can also support risk-based inspection programs and connect inspection results with maintenance planning. Commercial drone work requires operators to meet the UAE civil aviation rules for unmanned aircraft activities.[3] These technologies can reduce hours per inspection scope, so providers need data management and maintenance advisory skills to protect the value of their work.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Shortage of Experienced Level III, API, and Advanced-NDT Personnel | -1.5% | UAE, acute in Abu Dhabi petrochemical corridors and Dubai project sites | Long term (≥ 4 years) |
| High Capital and Accreditation Costs for Specialized Inspection Systems | -1.1% | UAE, with a heightened effect on local SME inspection firms | Medium term (2-4 years) |
| Limited Local Calibration Capacity for Specialized Equipment | -0.7% | UAE, with early mitigation gains in Abu Dhabi and Jebel Ali | Long term (≥ 4 years) |
| Cybersecurity and Data Ownership Concerns in Cloud-Based Inspection Programs | -0.4% | UAE, with elevated sensitivity among ADNOC affiliates and critical infrastructure clients | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Shortage of Experienced Level III, API, and Advanced-NDT Personnel
The supply of qualified Level III, API, and advanced NDT personnel remains a capacity constraint for the UAE industrial asset inspection services market. Demand is rising as ADNOC and utility projects require more inspectors, while ASNT Level III, ISO 9712, API 510, API 570, API 653, and CSWIP pathways require documented experience before qualification. The certification process cannot expand at the same speed as project demand. Drone inspection also requires compliant commercial operators under the UAE’s CAR-UAC framework. Limited local calibration capacity for specialized equipment can add turnaround time and logistical complexity for technical service teams. Firms with internal training pipelines, established certification links, and reliable calibration arrangements have a meaningful operational advantage.
High Capital and Accreditation Costs for Specialized Inspection Systems
Advanced ultrasonic, computed radiography, and robotic systems require capital investment that smaller inspection firms may find difficult to carry. National accreditation requires a compliant management system, equipment calibration and traceability records, and financial liability insurance of at least AED 3 million (USD 0.82 million) for notified conformity assessment bodies. Annual accreditation, surveillance audits, technical documentation, and system upkeep add to the cost of serving advanced NDT scopes. These requirements can strengthen the position of established providers with broad accreditation portfolios. Cloud-based inspection programs also raise questions about cybersecurity, data ownership, and access controls, especially for critical infrastructure and ADNOC-affiliated clients. A provider that cannot meet technical and data-governance requirements may be unable to compete for higher-value digital contracts.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Asset Type: Pipeline Networks Lead While Electrical Infrastructure Drives Growth
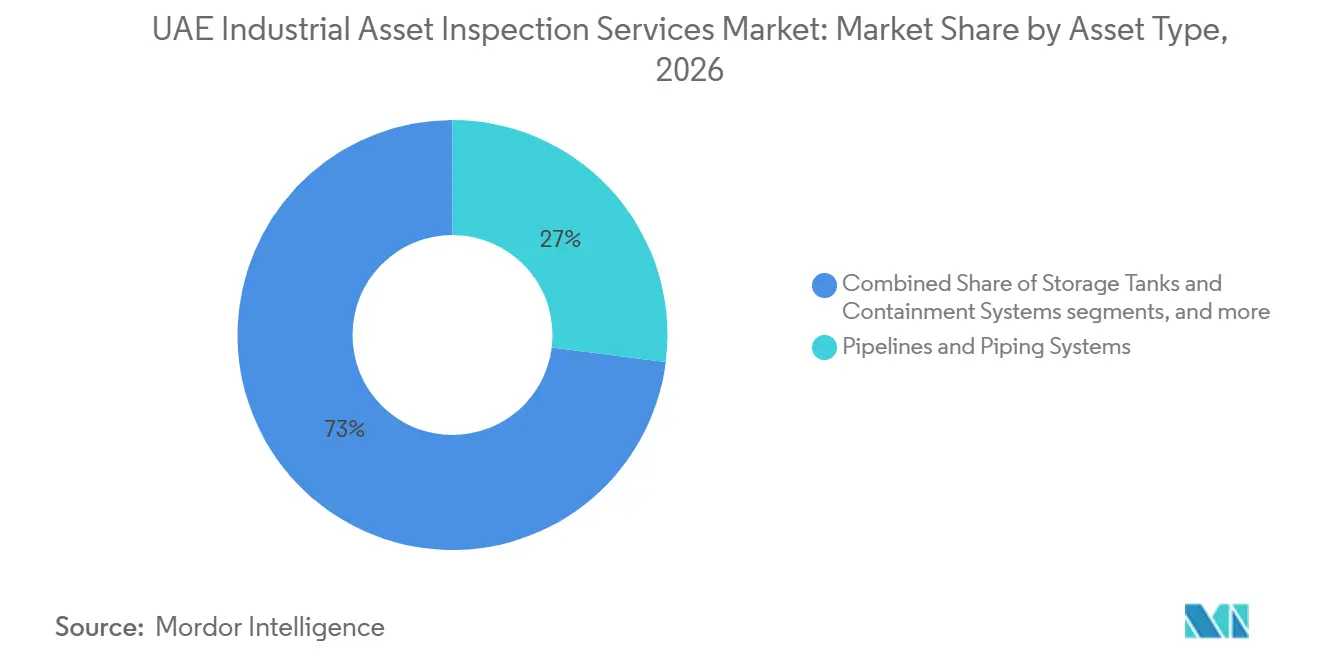
Pipelines and piping systems accounted for 27.0% of the UAE industrial asset inspection services market size in 2026. The category includes oil, gas, industrial transmission, process piping, and offshore pipelines across the country’s hydrocarbon network. Inspection demand is frequent because operators need in-line inspection, corrosion surveys, cathodic protection assessments, and integrity work during both operations and turnarounds. Applus+ renewed and expanded an offshore pipeline integrity contract in 2025, adding in-line inspection for piggable and unpiggable pipelines, nitrogen supply, mechanical cleaning, and gauging services. The expanded scope shows how established frameworks can deepen as client asset needs change.
Pressure vessels, boilers, heat exchangers, storage tanks, and containment systems provide separate recurring scopes within the UAE industrial asset inspection services market. Rotating equipment, including pumps, compressors, turbines, and conveyors, adds condition monitoring and vibration analysis work at gas-processing and industrial sites. Industrial structures, offshore platforms, furnaces, and instrumentation installations also require periodic integrity checks. Electrical and power equipment is forecast to expand at an 11.0% CAGR through 2032, the fastest rate among asset types. Abu Dhabi’s clean-energy target includes 18 GW of installed solar capacity and a 60% clean-energy share in electricity production by 2035. Transformers, switchgear, generators, transmission assets, and power distribution equipment will require IEC-aligned inspection capability as these projects move into operation.

By End-Use Industry: Oil and Gas Leads While Power Utilities Expand Faster
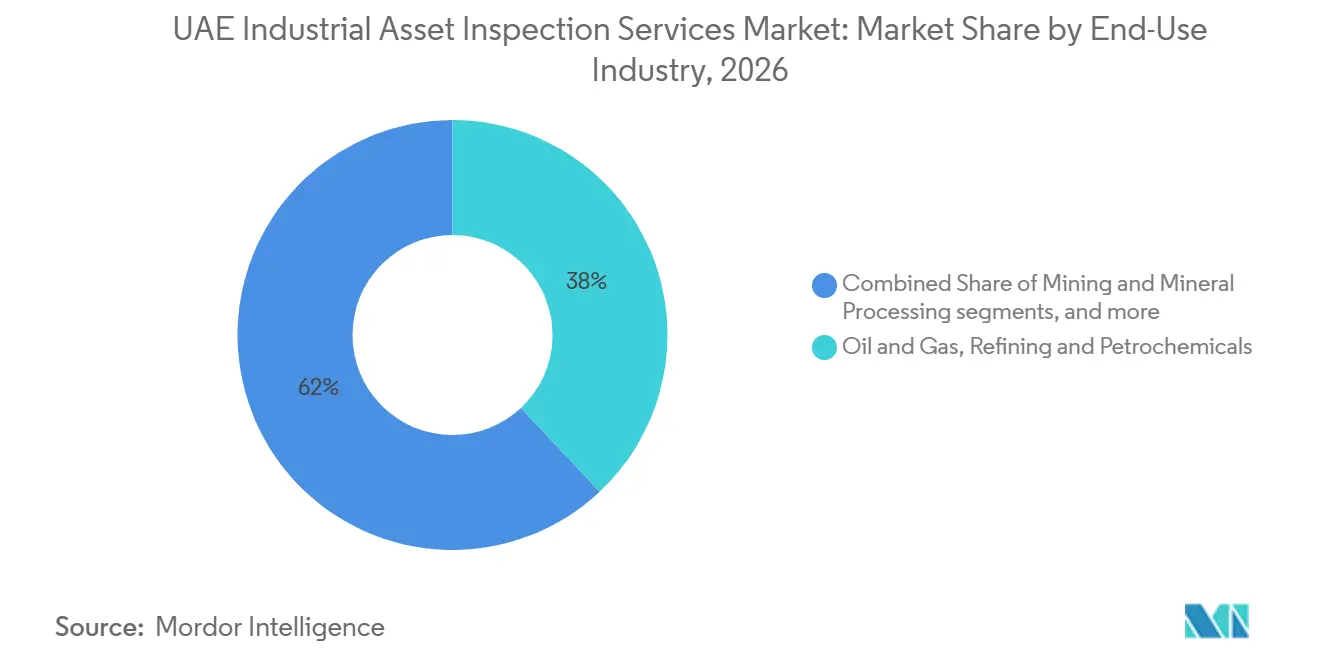
Oil and gas, refining, and petrochemicals held 38.0% of the UAE industrial asset inspection services market share in 2026. ADNOC’s upstream fields, gas-processing hubs, offshore facilities, and the Ruwais refining and chemicals complex drive demand across the full asset lifecycle. The work ranges from fabrication inspection and commissioning verification to statutory integrity programs and turnaround support. Bureau Veritas’ TA’ZIZ contract illustrates the combination of conventional inspection and digital data management that major buyers increasingly seek. Supplier registration and prequalification requirements make relevant accreditation, code knowledge, and comparable delivery experience important for contract eligibility.
Chemical manufacturing, metals, mining, water and wastewater utilities, food and beverage processing, pharmaceuticals, and port operations provide additional work across equipment categories. These industries help providers reduce reliance on the hydrocarbon base, although their inspection volumes are more measured. Power generation, renewable energy, and electrical utilities are projected to expand at an 11.5% CAGR through 2032. DEWA reported that the sixth phase of the Mohammed bin Rashid Al Maktoum Solar Park was 69% complete in September 2025, with 1,000 MW operating from a total of 1,800 MW in the phase. EWEC also received three proposals for the 2.5 GW Taweelah C project, which is targeted for commercial operations in Q4 2028. As solar, storage, gas generation, and grid assets enter operation, more work will shift from construction quality control to recurring testing, monitoring, and maintenance support.
Geography Analysis
Abu Dhabi holds the dominant demand position in the UAE industrial asset inspection services market because it contains much of ADNOC’s operated and affiliated asset base. Ruwais Industrial City, the TA’ZIZ complex, Ghasha offshore development, and clean-energy projects create concurrent inspection requirements. ADNOC’s engineering specifications, inspection test plans, and supplier prequalification system raise the threshold for companies seeking major contracts. Applus+ signed a five-year condition-monitoring and predictive-maintenance contract with ADNOC Gas in September 2025 for facilities at Ruwais, Habshan-5, Habshan, Bab, and Das. Bureau Veritas’ January 2026 TA’ZIZ award confirms the need for broad site and source inspection support in the emirate.
Dubai is the second-largest demand center in the UAE industrial asset inspection services market, with activity concentrated in JAFZA, Dubai Industrial City, and DEWA’s generation and transmission portfolio. Inspection providers must address free-zone and special development area requirements alongside federal accreditation obligations. DEWA’s 17,979 MW generation portfolio includes heat recovery steam generators, gas turbines, auxiliary boilers, and steam turbines that need continuing inspection of pressure, rotating, and structural assets. The sixth solar park phase adds electrical equipment that will need in-service monitoring after commissioning. DEWA issued proposals for the seventh phase in November 2025, supporting a planned total solar park capacity of 7,260 MW by 2030.
Sharjah, Fujairah, Ras Al Khaimah, and Umm Al Quwain have a smaller but expanding role in the UAE industrial asset inspection services market. Manufacturing, ports, storage terminals, and water infrastructure provide the core demand sources in these emirates. Intertek Caleb Brett opened a laboratory in Hamriyah Free Zone in June 2026, extending its analytical and testing capacity into Sharjah.
Competitive Landscape
The UAE industrial asset inspection services market exhibits a medium level of market concentration. Bureau Veritas UAE, Intertek, TÜV Rheinland Middle East, and DNV UAE have established positions with major ADNOC and utility frameworks. Broad accreditation, source-inspection networks, and long local delivery records support their scale. Applus+ Velosi, NDT Corrosion Control Services, AIMMS Group, MISTRAS Group Middle East, and LIN SCAN compete through specialized pipeline, corrosion, rope-access, structural-survey, and tank-inspection capabilities. The UAE industrial asset inspection services industry therefore rewards both broad quality systems and niche technical depth.
Bureau Veritas’ January 2026 TA’ZIZ contract included a project-specific inspection and data-management platform. The move shows that integrated data delivery is becoming more important in large framework awards. Applus+ expanded its offshore pipeline integrity scope in 2025 to cover more in-line inspection and cleaning activities. ADNOC Gas also signed its robotics agreement with AIQ and Gecko Robotics in November 2025, linking inspection data with predictive maintenance tools. These actions raise the standard for firms that depend only on conventional field inspection.
Technology suppliers and inspection contractors are increasingly competing around analytics, reporting, and maintenance recommendations in the UAE industrial asset inspection services market. LIN SCAN provides specialized in-line pipeline inspection services, while Waygate Technologies has a contracted inspection-services arm alongside its technology portfolio. Olympus Middle East FZE, Zetec Middle East, and Eddyfi Technologies are primarily equipment or software suppliers rather than contracted inspection-service providers. Commercial drone services must also meet registration, pilot, and airspace rules under CAR-UAC, creating an additional requirement for aerial inspection contracts. A provider that consolidates records from Abu Dhabi, Dubai, and the northern emirates in one risk-based framework could address a clear operational need while meeting client and regulator requirements.
UAE Industrial Asset Inspection Services Industry Leaders
-
SGS Gulf Limited
-
Applus+ Velosi
-
Bureau Veritas UAE
-
Intertek International Ltd - UAE
-
TÜV Rheinland Middle East LLC
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- September 2026: TÜV Rheinland UAE launched a structured Storage Tank Inspection program providing independent assessment, survey, inspection, and testing services for storage and containment assets across the UAE, targeting one of the highest-frequency statutory inspection categories in the petrochemical and utility sectors.
- June 2026: Intertek Caleb Brett commissioned its new laboratory at Hamriyah Free Zone in Sharjah, extending the company's analytical and testing capacity into the UAE's northern emirates and strengthening access to cargo quality inspection and commodity testing services for energy and commodities clients across the region.
- January 2026: Bureau Veritas was awarded a comprehensive inspection services contract by ADNOC for the TA'ZIZ Chemicals Industrial Zone at Al Ruwais Industrial City, covering on-site inspection and source inspection through international facilities in Vietnam, China, Germany, South Korea, and the United States. A purpose-built inspection and data management tool was specifically developed and deployed for the project.
- November 2025: ADNOC Gas executed a multi-year agreement with AIQ and Gecko Robotics to deploy AI-powered inspection robotics, including the first UAE-manufactured industrial inspection robot, across gas processing facilities. The Cantilever platform, combined with AIQ's AI defect recognition models, is projected to deliver more than USD 300 million in maintenance and inspection cost savings over 5 years.
UAE Industrial Asset Inspection Services Market Report Scope
The UAE Industrial Asset Inspection Services Market Report is Segmented by Asset Type (Pipelines and Piping Systems, Pressure Vessels, Boilers and Heat Exchangers, and More), and by End-Use Industry (Oil and Gas, Refining and Petrochemicals, Mining and Mineral Processing, Water and Wastewater Utilities, Food and Beverage Processing, and More). The Market Forecasts are Provided in Terms of Value (USD).
| Pipelines and Piping Systems | Oil, Gas and Industrial Transmission Pipelines |
| Process Piping and Industrial Utility Piping | |
| Offshore Pipelines, Risers and Flowlines | |
| Pressure Vessels, Boilers and Heat Exchangers | Pressure Vessels and Process Reactors |
| Industrial Boilers and Steam Systems | |
| Heat Exchangers and Pressurized Thermal Equipment | |
| Storage Tanks and Containment Systems | Aboveground and Underground Industrial Storage Tanks |
| Industrial Containment and Bulk Storage Systems | |
| Rotating and Mechanical Equipment | Pumps, Compressors and Industrial Turbines |
| Conveyors, Drives and Fixed Production Machinery | |
| Other Installed Mechanical Equipment | |
| Electrical and Power Equipment | Transformers, Switchgear and Power Distribution Equipment |
| Generators and Electrical Installations | |
| Power Transmission and Electrical Utility Assets | |
| Industrial Structures and Fixed Installations | Industrial Structural Steel and Equipment Supports |
| Offshore Platforms and Fixed Energy Installations | |
| Industrial Towers, Stacks and Supporting Structures | |
| Other Fixed Industrial Assets | Process Furnaces and Refractory Systems |
| Industrial Instrumentation and Control Installations | |
| Other Specialized Installed Industrial Assets |
| Oil and Gas, Refining and Petrochemicals |
| Power Generation, Renewable Energy and Electrical Utilities |
| Chemical Manufacturing (Excluding Petrochemicals) |
| Metals and Other Industrial Manufacturing |
| Mining and Mineral Processing |
| Water and Wastewater Utilities |
| Food and Beverage Processing |
| Pharmaceuticals and Bioprocessing |
| Transportation, Logistics and Port Operations |
| Other Industrial End Users |
| By Asset Type | Pipelines and Piping Systems | Oil, Gas and Industrial Transmission Pipelines |
| Process Piping and Industrial Utility Piping | ||
| Offshore Pipelines, Risers and Flowlines | ||
| Pressure Vessels, Boilers and Heat Exchangers | Pressure Vessels and Process Reactors | |
| Industrial Boilers and Steam Systems | ||
| Heat Exchangers and Pressurized Thermal Equipment | ||
| Storage Tanks and Containment Systems | Aboveground and Underground Industrial Storage Tanks | |
| Industrial Containment and Bulk Storage Systems | ||
| Rotating and Mechanical Equipment | Pumps, Compressors and Industrial Turbines | |
| Conveyors, Drives and Fixed Production Machinery | ||
| Other Installed Mechanical Equipment | ||
| Electrical and Power Equipment | Transformers, Switchgear and Power Distribution Equipment | |
| Generators and Electrical Installations | ||
| Power Transmission and Electrical Utility Assets | ||
| Industrial Structures and Fixed Installations | Industrial Structural Steel and Equipment Supports | |
| Offshore Platforms and Fixed Energy Installations | ||
| Industrial Towers, Stacks and Supporting Structures | ||
| Other Fixed Industrial Assets | Process Furnaces and Refractory Systems | |
| Industrial Instrumentation and Control Installations | ||
| Other Specialized Installed Industrial Assets | ||
| By End-Use Industry | Oil and Gas, Refining and Petrochemicals | |
| Power Generation, Renewable Energy and Electrical Utilities | ||
| Chemical Manufacturing (Excluding Petrochemicals) | ||
| Metals and Other Industrial Manufacturing | ||
| Mining and Mineral Processing | ||
| Water and Wastewater Utilities | ||
| Food and Beverage Processing | ||
| Pharmaceuticals and Bioprocessing | ||
| Transportation, Logistics and Port Operations | ||
| Other Industrial End Users | ||
Key Questions Answered in the Report
What is the projected value of industrial asset inspection services in the UAE?
The UAE industrial asset inspection services market is projected to reach USD 1.45 billion by 2032, from USD 0.85 billion in 2026, at a 9.8% CAGR. The forecast reflects growing asset inspection needs across oil and gas, chemicals, generation, renewables, and industrial infrastructure.
Which asset type has the largest inspection demand in the UAE?
Pipelines and piping systems led asset-type demand with a 27.0% share in 2026, supported by recurring integrity and corrosion inspection needs. This work includes in-line inspection, external surveys, cathodic protection assessments, and related services across onshore and offshore networks.
Which end-use sector is growing fastest for inspection services?
Power generation, renewable energy and electrical utilities is expected to grow at an 11.5% CAGR through 2032 as new generation and grid assets move into operation. Inspection activity will increasingly include transformer testing, electrical equipment monitoring, and predictive maintenance support.
Why is Abu Dhabi important for inspection service providers?
Abu Dhabi hosts major ADNOC assets, Ruwais and TA’ZIZ facilities, offshore development, and clean-energy projects that require site, source, and in-service inspection. Its supplier requirements also make accreditation, technical capability, and delivery history important factors in contract selection.
What qualifications matter for UAE inspection contracts?
National accreditation, traceable equipment calibration, relevant technical certifications, and experience with client requirements are important for high-criticality work. Providers also need the relevant personnel, documentation, and quality systems for the asset type and inspection scope.
How are digital tools changing industrial asset inspection?
Robotics, AI-supported defect recognition, digital records, and risk-based inspection programs can reduce shutdown time and expand demand for data and maintenance support. The change places greater value on turning inspection findings into maintenance decisions and usable client records.