
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 0.82 Billion |
| Market Size (2026) | USD 0.91 Billion |
| Market Size (2031) | USD 1.51 Billion |
| Growth Rate (2026 - 2031) | 10.66 % |
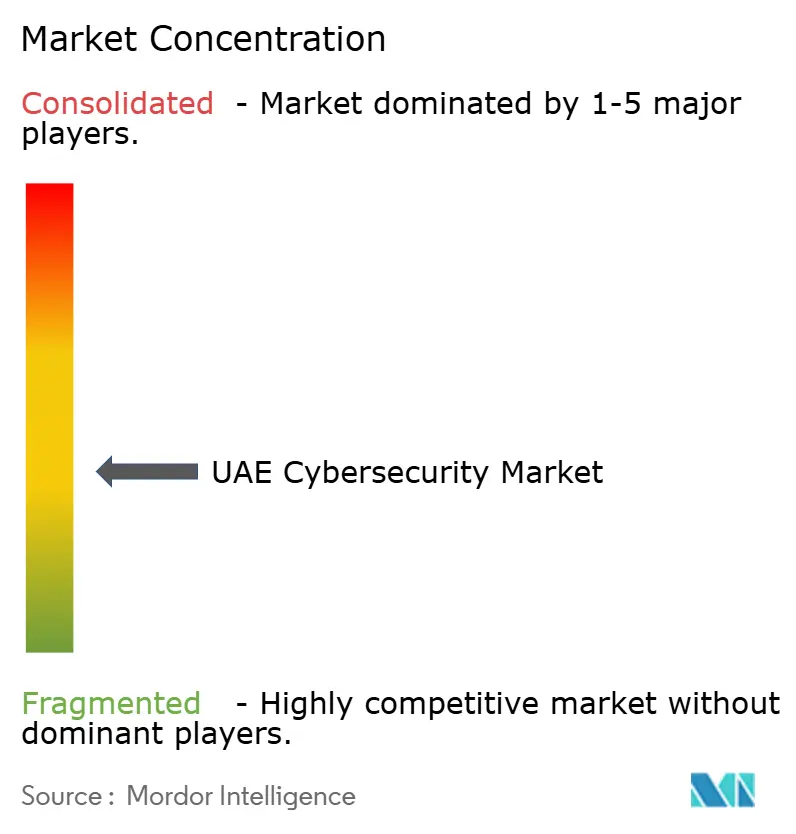
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
UAE Cybersecurity Market Analysis by Mordor Intelligence
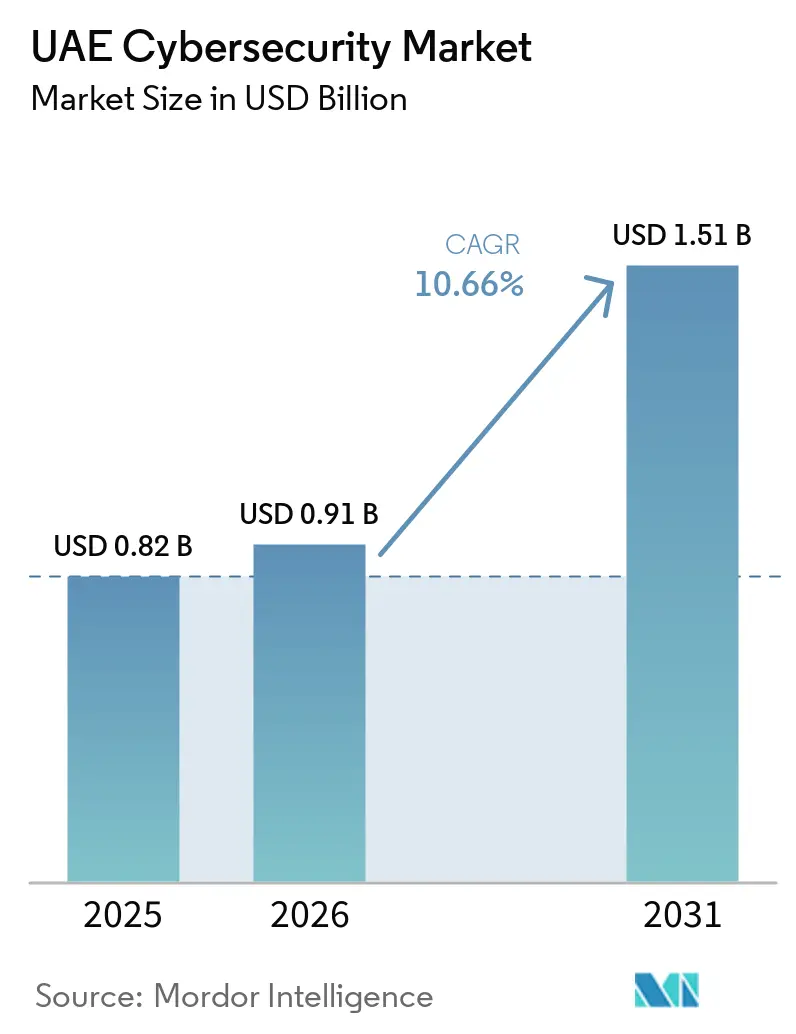
The UAE Cybersecurity Market size was valued at USD 0.82 billion in 2025 and is estimated to grow from USD 0.91 billion in 2026 to reach USD 1.51 billion by 2031, at a CAGR of 10.66% during the forecast period (2026-2031). Heightened sovereign-data mandates, the rollout of 5G networks, and a USD 2 billion government outlay under the National Cybersecurity Strategy are accelerating procurement cycles. Domestic security operations centers are proliferating as regulators require data residency, while cloud-native architectures remain central to digital-transformation roadmaps. Vendors that can certify compliance with Version 2 of the UAE Information Assurance Standards and integrate seamlessly with hyperscale clouds are gaining ground. Competitive dynamics favor modular platforms that orchestrate endpoint, identity, and cloud-access controls on a single pane of glass, easing the skills gap that continues to strain in-house teams.
Key Report Takeaways
- By offering, solutions captured 68.38% of the UAE cybersecurity market revenue in 2025, whereas services are forecast to post an 11.23% CAGR through 2031, the fastest pace among offerings.
- By deployment mode, cloud accounted for 63.12% of the UAE cybersecurity market share in 2025 and is advancing at an 11.16% CAGR to 2031.
- By end-user industry, banking, financial services, and insurance (BFSI) led spending, accounting for 19.56% of the UAE cybersecurity market in 2025, while the healthcare and life sciences industry is projected to grow at a 12.01% CAGR through 2031.
- By organization size, large enterprises held 67.29% of the UAE cybersecurity market in 2025, while small and medium enterprises (SMEs) are forecast to grow at an 11.78% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
UAE Cybersecurity Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Government Cybersecurity Spending Under UAE Vision 2031 | +2.8% | National, with concentration in Abu Dhabi and Dubai | Medium term (2-4 years) |
| Proliferation of 5G and IoT Driving Threat Surface Expansion | +2.3% | National, accelerated in smart-city zones (Dubai, Abu Dhabi, Sharjah) | Short term (≤ 2 years) |
| Mandatory Compliance With UAE Information Assurance Standards | +1.9% | National, stricter enforcement in federal entities and critical infrastructure | Medium term (2-4 years) |
| Surge in Cloud Migration Among SMEs | +1.7% | National, with higher adoption in free zones and tech hubs | Short term (≤ 2 years) |
| Growing Adoption of Cyber Insurance Among Enterprises | +0.9% | National, led by BFSI and multinational subsidiaries | Long term (≥ 4 years) |
| Initiatives to Localize Security Data Centers and SOCs | +1.1% | National, with emphasis on Abu Dhabi and Dubai sovereign zones | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Rising Government Cybersecurity Spending Under UAE Vision 2031
Federal and emirate-level agencies budgeted more than USD 2 billion in 2025, financing sovereign security operations centers, workforce-development programs, and incident-response infrastructure. Mandatory migration of public workloads to IA-compliant hosting by end-2026 is compressing procurement timelines, steering contracts toward vendors with pre-certified solutions. Funds earmarked for quantum-resistant encryption, zero-trust pilots, and AI-driven anomaly detection create first-mover advantages for suppliers that co-develop reference architectures with government buyers. Regulatory linkage between ISO 27001, UAE IA conformity, and eligibility for public tenders is reinforcing security investments across non-oil sectors.
Proliferation of 5G and IoT Driving Threat Surface Expansion
Operators had deployed roughly 7,000 5G base stations by late 2025, reaching 19.4% mobile-subscriber penetration, which in turn enabled network slicing for industrial and smart-city use cases. A surge in connected sensors, drones, and wearables widened the attack surface faster than asset inventories could keep pace. Check Point counted more than 223,800 exposed UAE assets in 2024, spanning unpatched routers and industrial controllers. Vendors offering unified endpoint and IoT management, complete with behavioral analytics, are gaining traction among enterprises seeking visibility across IT and OT domains.
Mandatory Compliance With UAE Information Assurance Standards
Version 2 of the IA Standards, released in 2025, strengthened requirements for encryption key management, incident reporting timelines, and third-party risk assessments.[1]National Electronic Security Authority, “Information Assurance Standards Version 2,” nesa.gov.ae Critical sectors now undergo annual penetration testing by NESA-accredited providers and must localize disaster-recovery workloads within national borders, supporting hyperscale data-center build-outs by Khazna and its peers. The requirements have also accelerated investments in vulnerability management, threat detection and response, data protection, identity and access management, and governance, risk, and compliance platforms. Supply chain clauses require enterprises to audit software vendors, driving demand for solutions that generate software bills of materials and maintain immutable audit trails. As organizations work to meet these regulatory obligations, compliance with the UAE Information Assurance Standards continues to drive growth in cybersecurity solutions in the country.
Surge in Cloud Migration Among SMEs
Government cloud-first mandates moved 80% of federal services to the cloud by 2025, creating implementation benchmarks and compliance practices that supported broader private-sector adoption in the UAE.[2]UAE Government Digital Office, “Cloud-First Policy,” u.ae The launch of AWS and Microsoft Azure sovereign regions in 2024-2025 reduced latency to under 5 milliseconds and helped organizations meet data-residency requirements, making cloud adoption more viable for SMEs handling sensitive customer, financial, and operational data. As SMEs migrated workloads, applications, and databases to cloud environments, they faced higher exposure to misconfigurations, identity-related risks, ransomware, and data breaches. This shift increased demand for cybersecurity solutions, particularly managed security services that bundle cloud security posture management, threat detection, identity and access management, vulnerability management, and 24/7 monitoring. SMEs without in-house expertise increasingly adopted these services because providers offered scalable pricing designed for organizations with fewer than 250 employees, enabling them to strengthen security while managing costs and regulatory obligations.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Shortage of Emirati Cybersecurity Talent Pool | -1.4% | National, acute in specialized domains (threat intelligence, cloud security architecture) | Medium term (2-4 years) |
| High Total Cost of Ownership for Advanced Security Solutions | -1.1% | National, disproportionately affecting SMEs and micro enterprises | Short term (≤ 2 years) |
| Fragmented Regulation Across Free Zones | -0.7% | Dubai International Financial Centre, Abu Dhabi Global Market, and sector-specific free zones | Long term (≥ 4 years) |
| Limited Awareness Among Micro Enterprises | -0.5% | National, concentrated in retail, hospitality, and personal services | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Shortage of Emirati Cybersecurity Talent Pool
Roughly 5,000 Emirati nationals entered private-sector cybersecurity roles during 2024-2025. However, demand for senior threat analysts continued to outpace supply, creating a significant talent gap in the UAE cybersecurity market.[3]Ministry of Human Resources and Emiratisation, “Cybersecurity Talent Initiatives 2025,” mohre.gov.ae Salary inflation and two-year attrition cycles eroded institutional knowledge and increased the cost of building and retaining in-house security teams. This shortage challenged the growth of cybersecurity solutions in the UAE by slowing deployment timelines, limiting organizations’ ability to manage complex threat environments, and increasing reliance on external expertise. As a result, organizations increasingly adopted co-managed SOC models, in which external providers supplied tier-2 and tier-3 analysts to support advanced threat detection, incident response, and continuous monitoring requirements.
High Total Cost of Ownership for Advanced Security Solutions
A full security stack can represent a substantial share of an SME’s IT budget, creating a significant financial barrier for many businesses in the United Arab Emirates. Licensing models that scale by user, device, or gigabyte, along with hardware appliances, integration costs, maintenance fees, and analyst salaries, increase the total cost of ownership and discourage the adoption of next-generation firewalls and XDR solutions. This challenge is particularly relevant to cost-sensitive SMEs operating on limited IT budgets and often prioritizing core business investments over advanced cybersecurity deployments. As a result, many organizations delay upgrades, adopt only basic security tools, or rely on fragmented solutions that may not provide comprehensive protection against evolving cyber threats. Although unified platforms with consumption-based pricing are driving adoption, many cost-sensitive businesses in the United Arab Emirates still view cybersecurity primarily as a compliance requirement rather than a strategic investment, thereby constraining the growth of cybersecurity solutions in the country.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Offering: Services Scale as Skills Gap Widens
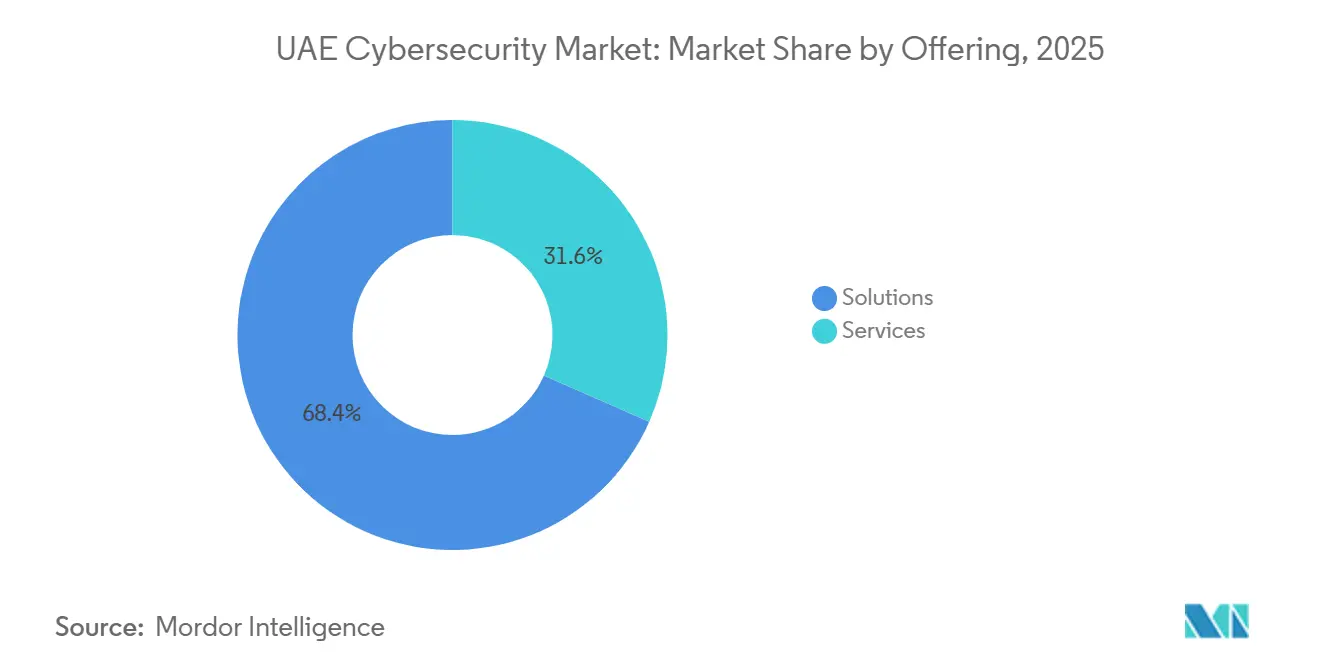
In the UAE cybersecurity market, solutions dominated the offering segment, accounting for 68.38% of total market revenue in 2025. Strong demand for network security, cloud security, endpoint protection, identity and access management, and threat intelligence platforms across sectors such as government, BFSI, energy, telecommunications, and healthcare drove this position. The UAE’s focus on smart city development, digital government initiatives, and critical infrastructure protection continued to drive investments in advanced cybersecurity solutions, helping organizations strengthen resilience against increasingly sophisticated cyber threats.
Meanwhile, the services segment is expected to register the fastest growth, expanding at a CAGR of 11.23% through 2031. Organizations increasingly rely on managed security services, consulting, threat monitoring, incident response, and compliance support to address evolving threat landscapes and cybersecurity talent shortages. The growing adoption of cloud computing, AI-driven security operations, and regulatory compliance requirements is fueling demand for outsourced expertise, making cybersecurity services an essential component of enterprise security strategies across the UAE.


By Deployment Mode: Cloud Retains Primacy Under Data-Residency Rules
The cloud deployment segment dominated the UAE cybersecurity market in 2025, accounting for 63.12% of the total market share. This significant market position reflected the rapid shift of UAE enterprises toward cloud-based security solutions as organizations increasingly migrated critical infrastructure and workloads to cloud environments. Cloud deployment led the market due to the scalability, flexibility, and cost-effectiveness that cloud-based cybersecurity solutions offered compared to traditional on-premises deployments. These benefits particularly appealed to the UAE’s diverse enterprise landscape, including BFSI, government, healthcare, and telecommunications.
Looking ahead, the cloud segment is projected to maintain its growth momentum, registering a compound annual growth rate (CAGR) of 11.16% through 2031. Several factors support this strong growth trajectory, including the UAE government's aggressive digital transformation initiatives, the increasing adoption of hybrid and multi-cloud architectures, and the growing sophistication of cloud-native security threats that require advanced protection capabilities. As organizations continue to adopt cloud-first strategies and reduce capital expenditure on physical infrastructure, demand for cloud-based security services, including Security-as-a-Service (SECaaS), cloud access security brokers (CASB), and cloud workload protection platforms, is expected to drive the sustained expansion of this dominant deployment segment throughout the forecast period.
By End-Use Industry: Healthcare Accelerates, BFSI Consolidates
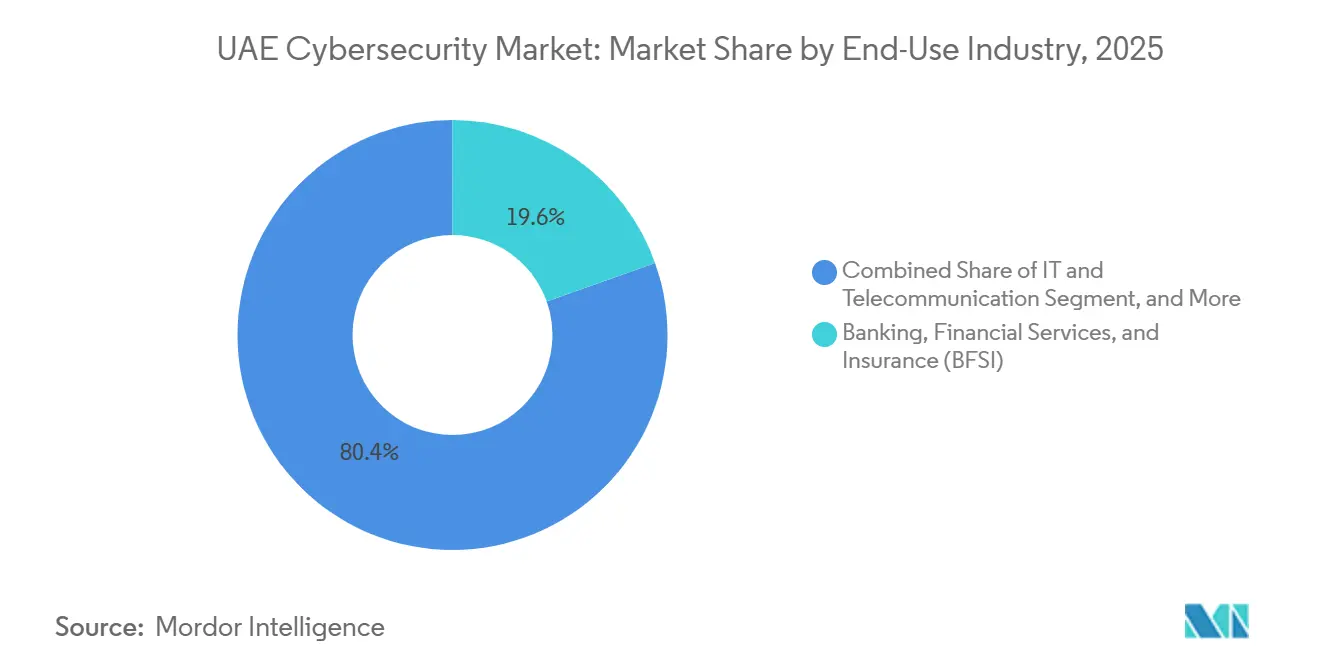
The banking, financial services, and insurance (BFSI) sector led cybersecurity spending in the UAE, accounting for 19.56% of the total market in 2025. This leading position reflected the critical role of cybersecurity in the financial sector, where organizations had to meet stringent regulatory requirements from authorities such as the UAE Central Bank and protect sensitive customer data, financial transactions, and digital banking platforms from increasingly sophisticated cyber threats. The BFSI sector’s significant cybersecurity investments covered a wide range of solutions, including fraud detection systems, encryption technologies, identity and access management, and security operations centers. The need to maintain customer trust and comply with evolving frameworks, such as DESC ISR and PDPL, drove this spending.
While BFSI held the largest share, the healthcare and life sciences industry is emerging as the fastest-growing end-user segment, with a projected compound annual growth rate (CAGR) of 12.01% through 2031. Rapid digitization of healthcare services across the UAE is driving this growth, including the adoption of electronic health records, telemedicine platforms, and connected medical devices, all of which create new attack surfaces that require robust security measures.[4]Ministry of Health and Prevention, “Data Protection Healthcare 2025,” mohap.gov.ae The sector is also increasing cybersecurity investments due to the sensitive nature of patient health information, regulatory mandates for data protection, and the rising threat of ransomware attacks targeting healthcare institutions. These factors position healthcare and life sciences as a key growth driver for the UAE cybersecurity market over the coming years.

By Organization Size: Small and Medium Enterprises (SMEs) Close the Gap
Large enterprises held a dominant 67.29% share of the UAE cybersecurity market in 2025, reflecting their substantial investments in comprehensive security infrastructure and managed services. This significant market share was attributed to the complex IT environments, extensive digital footprints, and greater exposure to sophisticated cyber threats among large organizations across sectors such as BFSI, government, energy, and telecommunications. Large enterprises typically deploy multi-layered security architectures, including advanced threat detection systems, security operations centers, endpoint protection across thousands of devices, and enterprise-grade identity and access management solutions. Dedicated cybersecurity teams and partnerships with leading MSSPs often supported these deployments, ensuring continuous monitoring and rapid incident response.
Small and medium enterprises (SMEs) are forecast to register a compound annual growth rate (CAGR) of 11.78% through 2031, making them the fastest-growing segment by organization size. Increasing awareness of cyber risks among SMEs, regulatory pressures that extend compliance requirements to smaller organizations, and the rising availability of cost-effective, scalable cybersecurity solutions tailored to SME budgets and operational needs are driving this accelerated growth. As SMEs in the UAE increasingly adopt cloud-based services, digital payment systems, and remote work technologies, their vulnerability to cyberattacks has increased, prompting higher investments in essential security measures such as endpoint protection, email security, and managed security services. The growth of this segment also reflects government initiatives and industry programs aimed at strengthening the cybersecurity posture across the entire business ecosystem, not just large corporations.
Geography Analysis
Abu Dhabi and Dubai generate most of the revenue in the UAE cybersecurity market, supported by the country’s critical energy infrastructure and major financial hubs. Abu Dhabi continues to prioritize operational technology (OT) security across the oil, gas, and utilities sectors, given the strategic importance of these assets to the national economy. Dubai, in contrast, places stronger emphasis on cloud security to support banking, logistics, tourism, and other digitally enabled service workloads. Sharjah, Ajman, Ras Al Khaimah, Umm Al Quwain, and Fujairah are also recording steady adoption as SMEs accelerate digitization and increase spending on basic and advanced cybersecurity solutions. Fortinet’s April 2025 MOU with the Sharjah Cyber Security Center underscored the rising regional demand for cybersecurity training, threat intelligence, and institutional capability building.
Free-zone fragmentation continues to complicate compliance for enterprises operating across multiple jurisdictions. The Dubai International Financial Center (DIFC) applies GDPR-style data protection laws, while the Abu Dhabi Global Market (ADGM) enforces separate financial services standards. As a result, multizone enterprises increasingly favor vendors that provide jurisdiction-specific policy templates, compliance mapping, and configurable controls to reduce regulatory complexity and improve governance.
Regional threat vectors remain acute. IBM’s X-Force index placed the UAE fourth globally for cyberattacks in 2024, accounting for 10% of global events. The country also plays a central role in Gulf Cooperation Council threat-sharing pacts and maintains bilateral cybersecurity agreements with the United States, the United Kingdom, and Israel. These partnerships strengthen intelligence exchange and position the UAE as a proving ground for zero-trust architectures, quantum-safe pilots, and other advanced cybersecurity initiatives.
Competitive Landscape
The UAE cybersecurity market is moderately fragmented. Local champions such as Help AG, Injazat, and Etisalat Digital compete alongside global vendors including Cisco, Palo Alto Networks, Microsoft, CrowdStrike, and Fortinet. Local players leverage proximity to government decision‐makers, fluency in Arabic, and expertise in UAE compliance frameworks to win public-sector and critical-infrastructure projects, while international vendors contribute scale, R and D depth, and global threat-intelligence networks. Partnership models are common, Help AG’s May 2025 agreement with Etisalat Digital fuses managed-security operations with carrier infrastructure to deliver integrated monitoring and incident response. Fortinet’s October 2025 deal with Dubai Electricity and Water Authority embeds next-generation firewalls and secure SD-WAN across utility OT networks, illustrating convergence of IT and OT protection.
White-space opportunities persist in hospitality, construction, and personal services, where digital adoption is rising but security budgets trail other sectors. Disruptors are targeting these segments with cloud-delivered platforms that minimize on-premises hardware and use consumption-based pricing. Artificial-intelligence automation of threat detection and incident response is gaining favor, yet Cisco’s 2025 readiness index showed only 4% of UAE organizations fully mature across identity, network, and application domains, suggesting most enterprises still build foundational controls. Vendors that prove cuts in mean time to detect and respond through audited case studies are moving up shortlists.
Localization of data centers has become a decisive bidding factor, because IA Standards bar cross-border telemetry for government and critical-infrastructure workloads. Sophos activated a UAE telemetry hub on AWS infrastructure in 2025, and Cisco placed Duo MFA servers onshore in 2024, giving both vendors latency and compliance advantages over rivals that still backhaul data to Europe or the United States,. Mergers and minority stakes are also reshaping the field, Microsoft’s USD 1.5 billion investment in G42 in 2024 deepened collaboration on sovereign-cloud infrastructure and security research. Competitive positioning now hinges on bundling governance tooling, threat intelligence, and managed detection into SME-friendly subscriptions without sacrificing the advanced analytics demanded by large banks and energy majors. Vendors balancing global scale with local nuance are poised to capture incremental UAE cybersecurity market share.
UAE Cybersecurity Industry Leaders
DarkMatter LLC
Injazat Data Systems LLC
Etisalat Digital
Emirates Integrated Telecommunications Company PJSC (du)
IBM Corporation
- *Disclaimer: Major Players sorted in no particular order

Recent Industry Developments
- June 2026: Emirates Integrated Telecommunications Company PJSC (du) signed a memorandum of understanding (MoU) with Open Innovation AI, in collaboration with the UAE Cyber Security Council, to accelerate the adoption of sovereign Agentic AI by integrating du Tech’s CSC-certified National Hypercloud with Open Innovation AI’s GPU orchestration platform.
- June 2026: Emirates Integrated Telecommunications Company PJSC (du) joined the Dubai Department of Economy and Tourism’s “SME in a Box” initiative as a telecom partner, providing tailored connectivity and digital solutions to support startups and SMEs.
- April 2026: IBM announced new cybersecurity measures to help organizations counter a new generation of cyber threats as attackers begin weaponizing frontier AI models. Attackers are already using these models to accelerate every phase of the attack lifecycle. Frontier AI models represent a step change in offensive capability, significantly reducing the time, cost, and expertise required to carry out sophisticated attacks and increasing the risk of continuous business disruption.
- March 2026: Broadcom Inc., a global technology leader that designs, develops, and supplies semiconductor and infrastructure software solutions, announced Symantec CBX (Carbon Black XDR), a cloud-based platform that combines Symantec and Carbon Black technologies in one intuitive solution. CBX addresses the needs of one of the industry’s largest and historically underserved markets: organizations that lack the resources and training to implement complex security solutions but face the same formidable attackers and threats.


UAE Cybersecurity Market Report Scope
The UAE cybersecurity market comprises technologies, solutions, and services that protect digital infrastructure, networks, applications, and data across sectors such as government, BFSI, energy, healthcare, telecommunications, and retail. The UAE’s strong digital transformation agenda, smart city initiatives, cloud adoption, and national cybersecurity strategies drive the market, as these efforts aim to safeguard critical infrastructure and sensitive information. Rising cyber threats, increasing reliance on digital services, and regulatory requirements are accelerating demand for solutions such as network security, cloud security, identity and access management, endpoint protection, and managed security services, positioning the UAE as one of the most advanced cybersecurity markets in the Middle East.
UAE Cybersecurity Market Report is Segmented by Offerings (Solutions [Application Security, Cloud Security, Data Security, Identity Access Management, Infrastructure Protection, Integrated Risk Management, Network Security, and End-point Security], and Services [Professional Services, and Managed Services]), Deployment (On-premise, and Cloud), End-user Industry (Banking, Financial Services, and Insurance (BFSI), Healthcare and Life Sciences, IT and Telecommunication, Government and Public Administration, Industrial Manufacturing, Retail and E-Commerce, Energy and Utilities, Transportation and Logistics, and Other End-User Industries), and Organization Size (Small and Medium Enterprises (SMEs), and Large Enterprises). The Market Forecasts are Provided in Terms of Value (USD).
By Offering
| Solutions | Application Security |
| Cloud Security | |
| Data Security | |
| Identity and Access Management | |
| Infrastructure Protection | |
| Integrated Risk Management | |
| Network Security | |
| End-point Security | |
| Services | Professional Services |
| Managed Services |
By Deployment Mode
| On-Premises |
| Cloud |
By End-use Industry
| Banking, Financial Services, and Insurance (BFSI) |
| Healthcare and Life Sciences |
| IT and Telecommunication |
| Government and Public Administration |
| Industrial Manufacturing |
| Retail and E-Commerce |
| Energy and Utilities |
| Transportation and Logistics |
| Other End-User Industries |
By Organization Size
| Large Enterprises |
| Small and Medium Enterprises (SMEs) |
| By Offering | Solutions | Application Security |
| Cloud Security | ||
| Data Security | ||
| Identity and Access Management | ||
| Infrastructure Protection | ||
| Integrated Risk Management | ||
| Network Security | ||
| End-point Security | ||
| Services | Professional Services | |
| Managed Services | ||
| By Deployment Mode | On-Premises | |
| Cloud | ||
| By End-use Industry | Banking, Financial Services, and Insurance (BFSI) | |
| Healthcare and Life Sciences | ||
| IT and Telecommunication | ||
| Government and Public Administration | ||
| Industrial Manufacturing | ||
| Retail and E-Commerce | ||
| Energy and Utilities | ||
| Transportation and Logistics | ||
| Other End-User Industries | ||
| By Organization Size | Large Enterprises | |
| Small and Medium Enterprises (SMEs) | ||


Key Questions Answered in the Report
What is the current size of the UAE cybersecurity market?
The UAE Cybersecurity Market size was valued at USD 0.82 billion in 2025 and is estimated to grow from USD 0.91 billion in 2026 to reach USD 1.51 billion by 2031, at a CAGR of 10.66% during the forecast period (2026-2031).
Which vertical allocates the most budget?
Banking, financial services, and insurance (BFSI) contributed 19.56% of 2025 outlays, the largest share among end-use sectors.
Why are managed-security services gaining popularity?
A shortage of senior Emirati cybersecurity talent and the complexity of IA-standards compliance are prompting enterprises to outsource 24/7 monitoring and incident response.
What drives cloud-security demand in the Emirates?
Government cloud-first mandates, AWS and Azure sovereign regions, and data-residency clauses in the IA Standards are accelerating cloud-security adoption.
Which emirates see the highest cybersecurity investment?
Abu Dhabi emphasizes operational-technology protection for energy infrastructure, while Dubai leads spending on cloud security for finance, logistics, and tourism.
How does regulation influence vendor selection?
Compliance with Version 2 of the UAE Information Assurance Standards and on-shore data processing are now baseline requirements for winning government and critical-infrastructure contracts.
Page last updated on:


 Your data is secure and never sold or shared.



