
Real Estate Transaction Advisory Services Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Market Size (2027) | USD 15.68 Billion |
| Market Size (2032) | USD 22.44 Billion |
| Growth Rate (2027 - 2032) | 7.43 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Real Estate Transaction Advisory Services Market Analysis by Mordor Intelligence
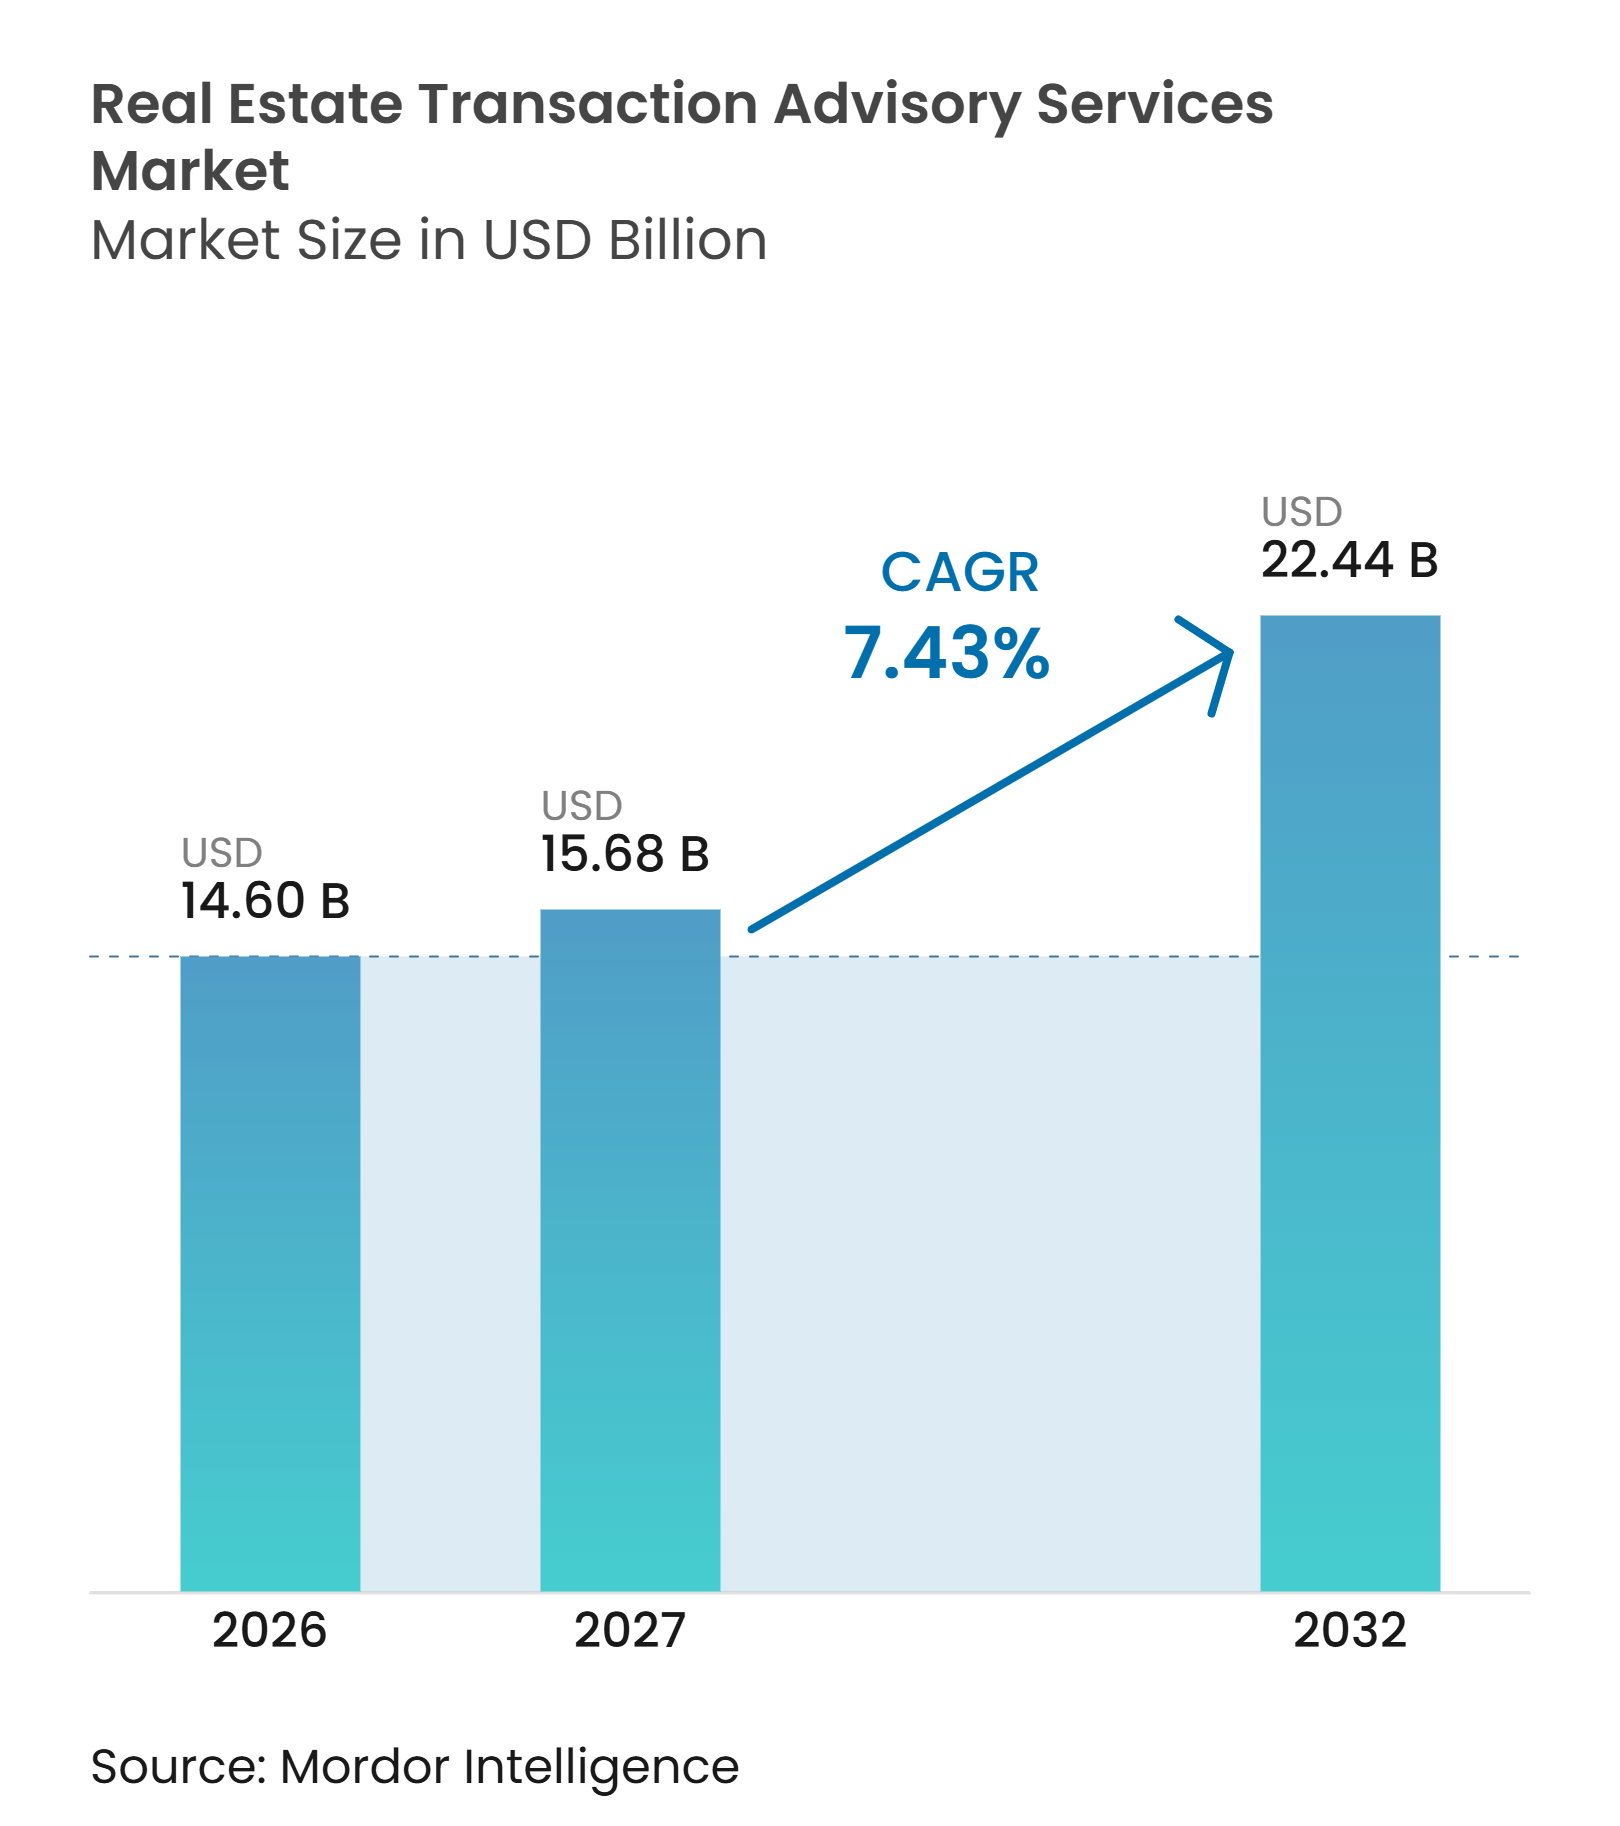
The Real Estate Transaction Advisory Services Market size was valued at USD 14.60 billion in 2026 and is estimated to grow from USD 15.68 billion in 2027 to reach USD 22.44 billion by 2032, at a CAGR of 7.43% during the forecast period (2027-2032).
Growth reflects the greater complexity of institutional real estate transactions, including recapitalizations, joint ventures, continuation vehicles, and sale-leaseback arrangements. These structures require advisers to coordinate valuation, financing, legal, tax, and investor considerations, which raises the value of each mandate. The Real Estate Transaction Advisory Services Market is also gaining support from private capital, distressed asset work, and investment in data centers, logistics properties, and professionally managed residential assets. Interest-rate movements and lengthy closing periods can delay transactions, but they also make lender selection and capital-structure advice more important. Large platforms are broadening their specialist capabilities, while independent firms continue to compete where local knowledge, independence, or sector expertise matters. The Real Estate Transaction Advisory Services Market therefore depends on capabilities that address complex transactions as well as transaction volume.
Key Report Takeaways
- By service type, Property Acquisition and Disposal Advisory held 36.0% of the Real Estate Transaction Advisory Services Market share in 2026, while Capital Markets and Financing Advisory is projected to grow at an 8.30% CAGR through 2032.
- By transaction type, Sales held 63.0% of the Real Estate Transaction Advisory Services Market share in 2026, while Rental Advisory is projected to grow at a 7.93% CAGR through 2032.
- By property type, Commercial Office and Retail held 43.0% of the Real Estate Transaction Advisory Services Market share in 2026, while Industrial and Logistics is projected to grow at a 9.27% CAGR through 2032.
- By geography, North America held 38.0% of the Real Estate Transaction Advisory Services Market share in 2026, while Asia-Pacific is projected to grow at a 9.18% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Real Estate Transaction Advisory Services Market*
| Drivers | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Institutional Transaction Complexity | +2.1% | Global | Short term (≤ 2 years) |
| Private Capital Deployment into Real Estate | +1.8% | Global, with concentration in North America and Europe | Short term (≤ 2 years) |
| Data Center, Logistics, and Living-Sector Transactions | +1.4% | North America, Asia-Pacific core, and Western Europe | Medium term (2-4 years) |
| Distressed and Special-Situations Activity | +1.2% | North America, with spillover to Europe | Short term (≤ 2 years) |
| Portfolio Optimization and Capital Recycling | +0.9% | Asia-Pacific core, with spillover to the Middle East and Africa and Europe | Medium term (2-4 years) |
| Public-Private Partnership and Infrastructure Investment | +0.5% | National markets, with early gains in the Gulf Cooperation Council and Southeast Asia | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Institutional Transaction Complexity Deepens Advisory Mandates
Institutional transaction complexity is expanding the scope of advisory assignments in the Real Estate Transaction Advisory Services Market. General partners increasingly use continuation vehicles and recapitalizations, which call for independent opinions, investor communication, and capital-structure advice. Entity-level transactions also require real estate specialists to work alongside legal and tax advisers. CBRE reported USD 528.3 billion in United States commercial real estate investment volume through the third quarter of 2026, showing the scale of transactions that can require multi-disciplinary support. This shift favors firms that can manage several workstreams without reducing the quality of execution.
Private Capital Deployment Sustains Advisory Demand Through the Cycle
Private capital deployment creates a steady source of transaction assignments because many investors use external advisers for sourcing, due diligence, financing, and closing. The Real Estate Transaction Advisory Services Market benefits when investors need help evaluating assets or building local execution teams. Investors that acquire operating businesses together with property can also require corporate and real estate advice within the same mandate. Capital providers are placing more weight on underwriting discipline as financing choices become more varied. That need supports advisers with strong debt, equity, and cross-border capabilities.
Data Center, Logistics, and Living-Sector Transactions Generate New Advisory Revenue Streams
Data centers, logistics facilities, and living-sector properties are creating mandates that require specialized operating and financial knowledge. A data center transaction may require advice on power supply, tenant credit quality, technical due diligence, and the design of the financing structure. Jones Lang LaSalle Incorporated advised on the sale of a 40.5-megawatt data center in Greater Osaka in May 2026, a transaction described by the company as Japan's largest single-asset data center sale. Residential platforms also need advice on portfolio underwriting, real estate investment trust structures, and cross-border capital flows. These needs give the Real Estate Transaction Advisory Services Market opportunities outside conventional office and retail brokerage.
Distressed and Special-Situations Activity Drives Specialist Advisory Growth
Distressed assets are supporting a separate stream of advisory work even where traditional acquisition activity slows. Berkadia established a Special Situations platform in January 2026 to advise lenders, banks, debt funds, and special servicers on divestment and capital recovery[1]. These assignments can involve asset diagnosis, debt restructuring, disposal planning, and coordination among creditors. Bracewell LLP also launched a dedicated real estate special situations practice in March 2026[2]. This creates demand that does not depend only on stable property valuations.
Restraints Impact Analysis of Real Estate Transaction Advisory Services Market*
| Restraints | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Interest-Rate and Financing Volatility | -1.2% | Global | Short term (≤ 2 years) |
| Long Transaction Cycles | -0.7% | Global | Short term (≤ 2 years) |
| Regulatory and Tax Complexity | -0.4% | Global | Long term (≥ 4 years) |
| Conflicts and Independence Constraints | -0.3% | North America and Europe | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Interest-Rate and Financing Volatility Compresses Near-Term Advisory Volumes
Interest-rate uncertainty can reduce the number of transactions that reach closing in the near term. Cushman & Wakefield reported that United States commercial real estate sales volume declined 14% in April 2026 as buyers reconsidered their underwriting. The Commercial Real Estate Finance Council reported that 92% of respondents viewed mortgage and capitalization rates as a negative influence on their businesses in the third quarter of 2026[3]. When lenders revise terms or pause underwriting, clients may delay a sale or acquisition. This reduces short-term fee conversion even though it can increase the need for financing advice.
Long Transaction Cycles Strain Advisory Revenue Recognition
Long transaction cycles make revenue timing less predictable for advisory firms. Large portfolio sales, entity acquisitions, and cross-border mandates may require extensive due diligence, financing approvals, and regulatory review. Advisory firms often do substantial work before a closing triggers the principal success fee. Complex transactions can use staff capacity for an extended period without a matching increase in recognized revenue. The Real Estate Transaction Advisory Services Market needs firms to manage the trade-off between client service and the cost of long-running assignments.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Real Estate Transaction Advisory Services Market Segment Analysis
By Service Type:
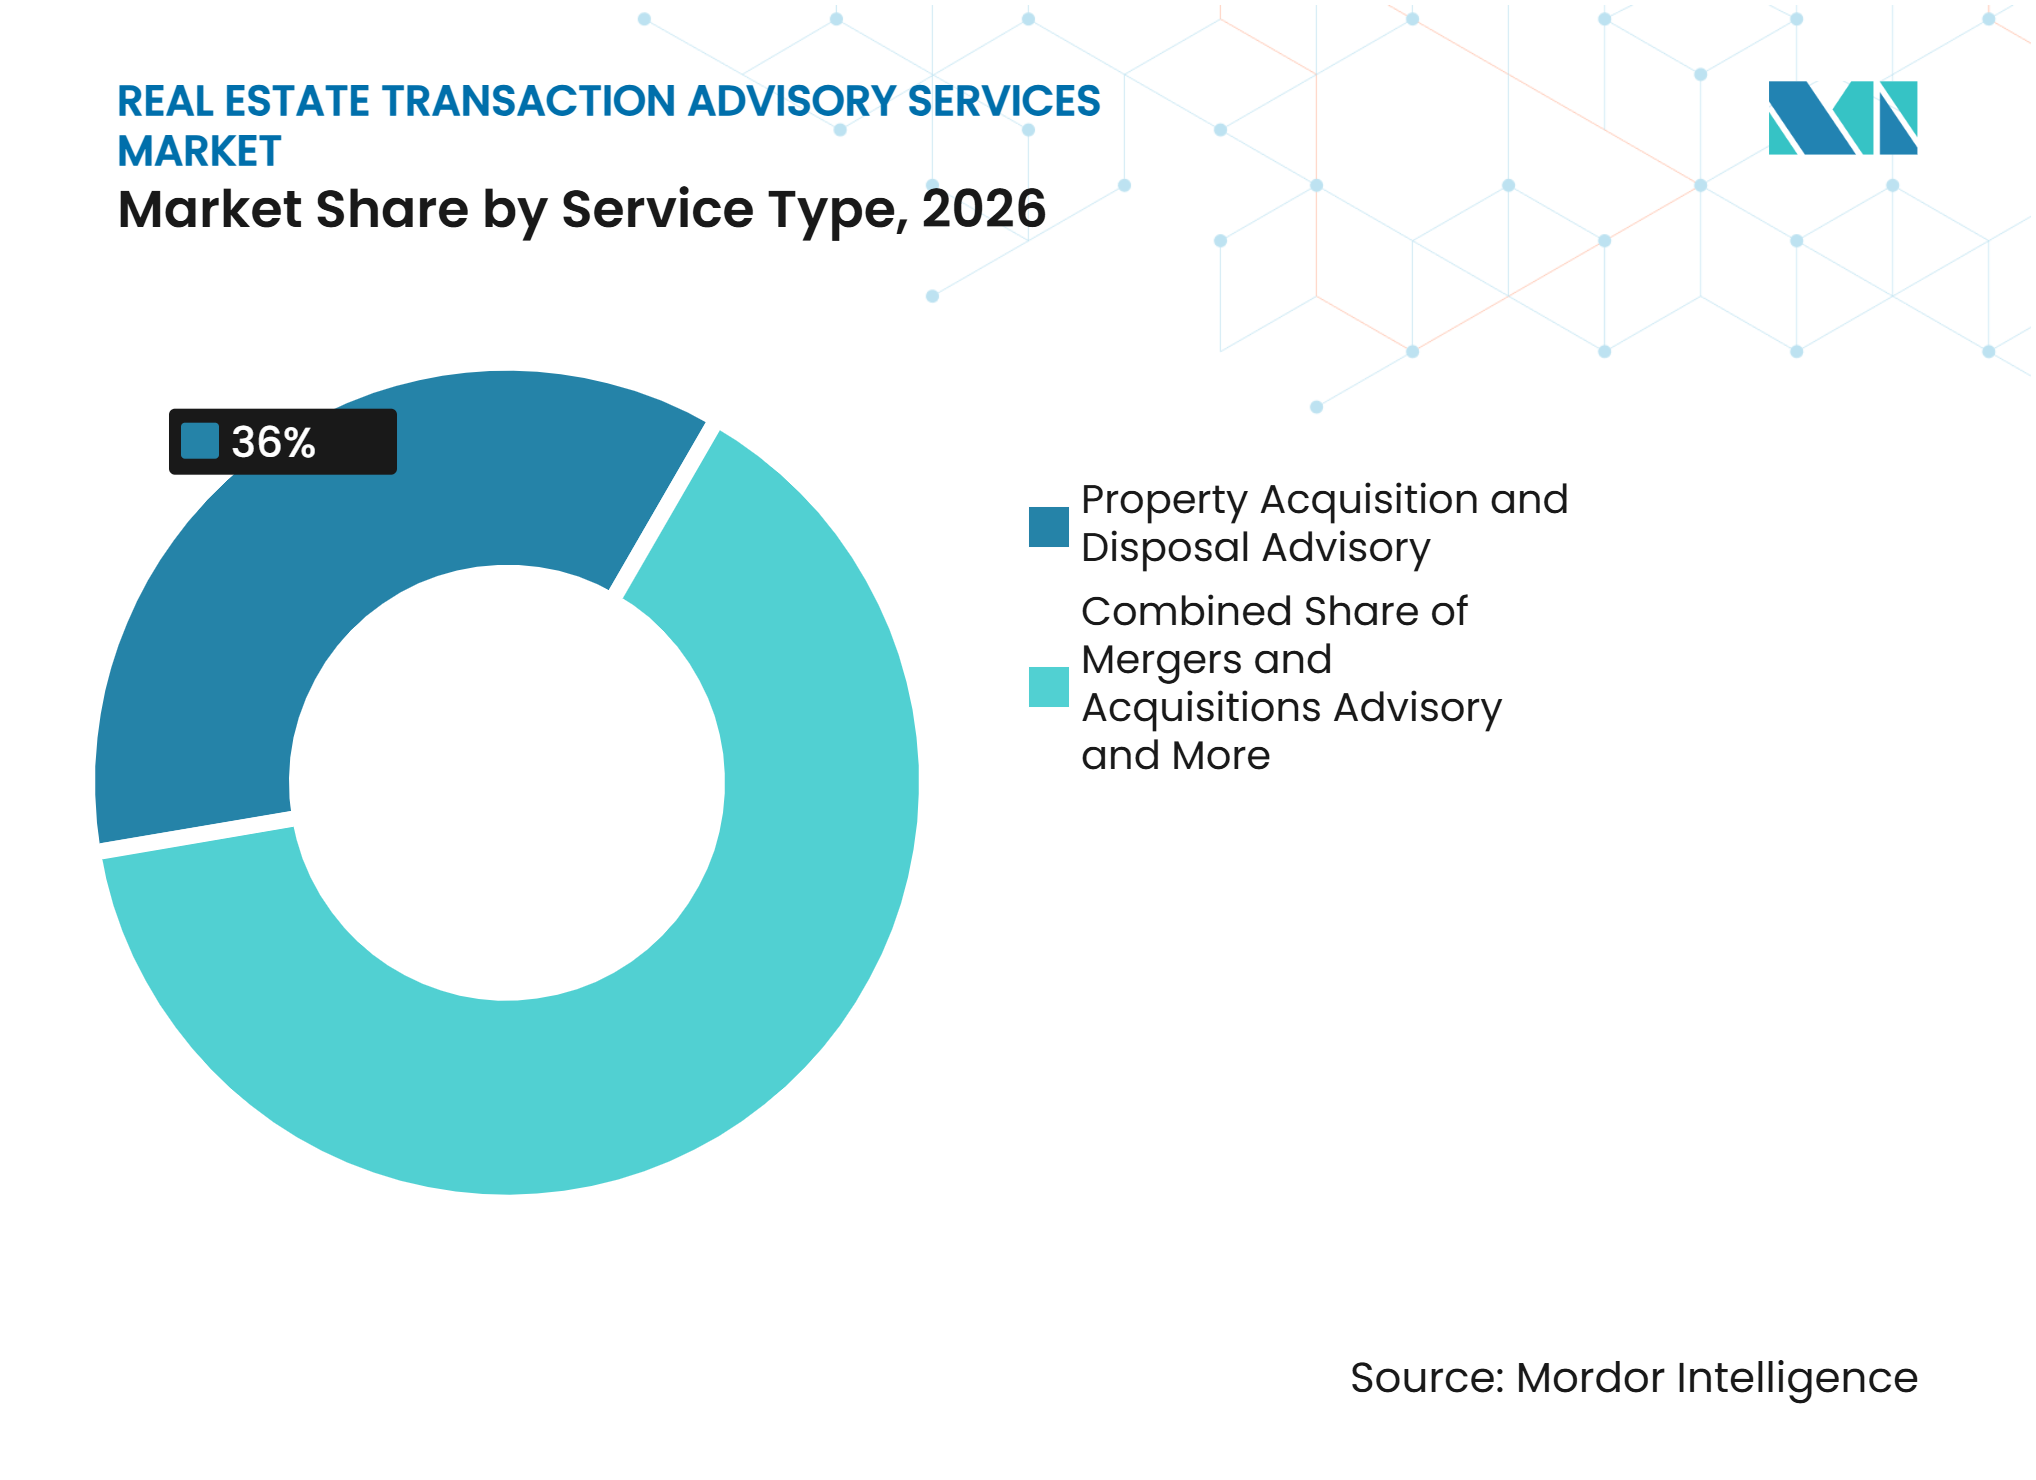
Property Acquisition and Disposal Advisory Remains the Largest Service LineProperty Acquisition and Disposal Advisory held 36.0% of the Real Estate Transaction Advisory Services Market share in 2026. The service remains central because institutional owners and investors need support to identify buyers or sellers, prepare transaction materials, and negotiate terms. Off-market sourcing can be particularly valuable where assets are scarce or where sellers want a controlled process. The segment also benefits from the importance of local buyer relationships and property-level market knowledge. Advisers with broad coverage can connect domestic and cross-border capital with opportunities that may not be marketed publicly.
The service line continues to work alongside other specialties rather than operating as a standalone brokerage offering. A sale mandate may require valuation, financing advice, tax input, and a structured communications process for several investors. JLL arranged the sale and financing of a 36-property, 7.3-million-square-foot logistics portfolio in March 2026, illustrating the scale of assignments that blend sale execution with capital placement. Capital Markets and Financing Advisory is the fastest-growing service line at an 8.30% CAGR through 2032. The growth reflects the increasing number of capital providers and the need to compare debt and equity terms before a transaction moves forward.



By Transaction Type:
Sales Retains Scale While Rental Advisory ExpandsSales held 63.0% of the Real Estate Transaction Advisory Services Market share in 2026. Acquisitions and dispositions remain the largest source of revenue because asset transfers commonly involve high transaction values and several decision-makers. Sales assignments also require advisers to assess buyer interest, recommend pricing strategies, and manage a formal closing process. Large portfolio transactions remain important because they create fees across property advice, financing, and execution. The segment will remain supported by institutional capital seeking exposure to logistics, living, and digital infrastructure assets.
JLL advised Urban Partners on a Nordic logistics portfolio sale in February 2026, demonstrating ongoing demand for large disposal mandates. Rental Advisory is expected to record the fastest growth, at a 7.93% CAGR through 2032. The segment is expanding as tenants in data centers, logistics, life sciences, and specialized office space negotiate more detailed lease terms. These clients may need financial modeling, technical review, workplace strategy, and legal coordination in the same engagement. This makes rental advisory a more complex and higher-value service than a conventional leasing assignment.
By Property Type:
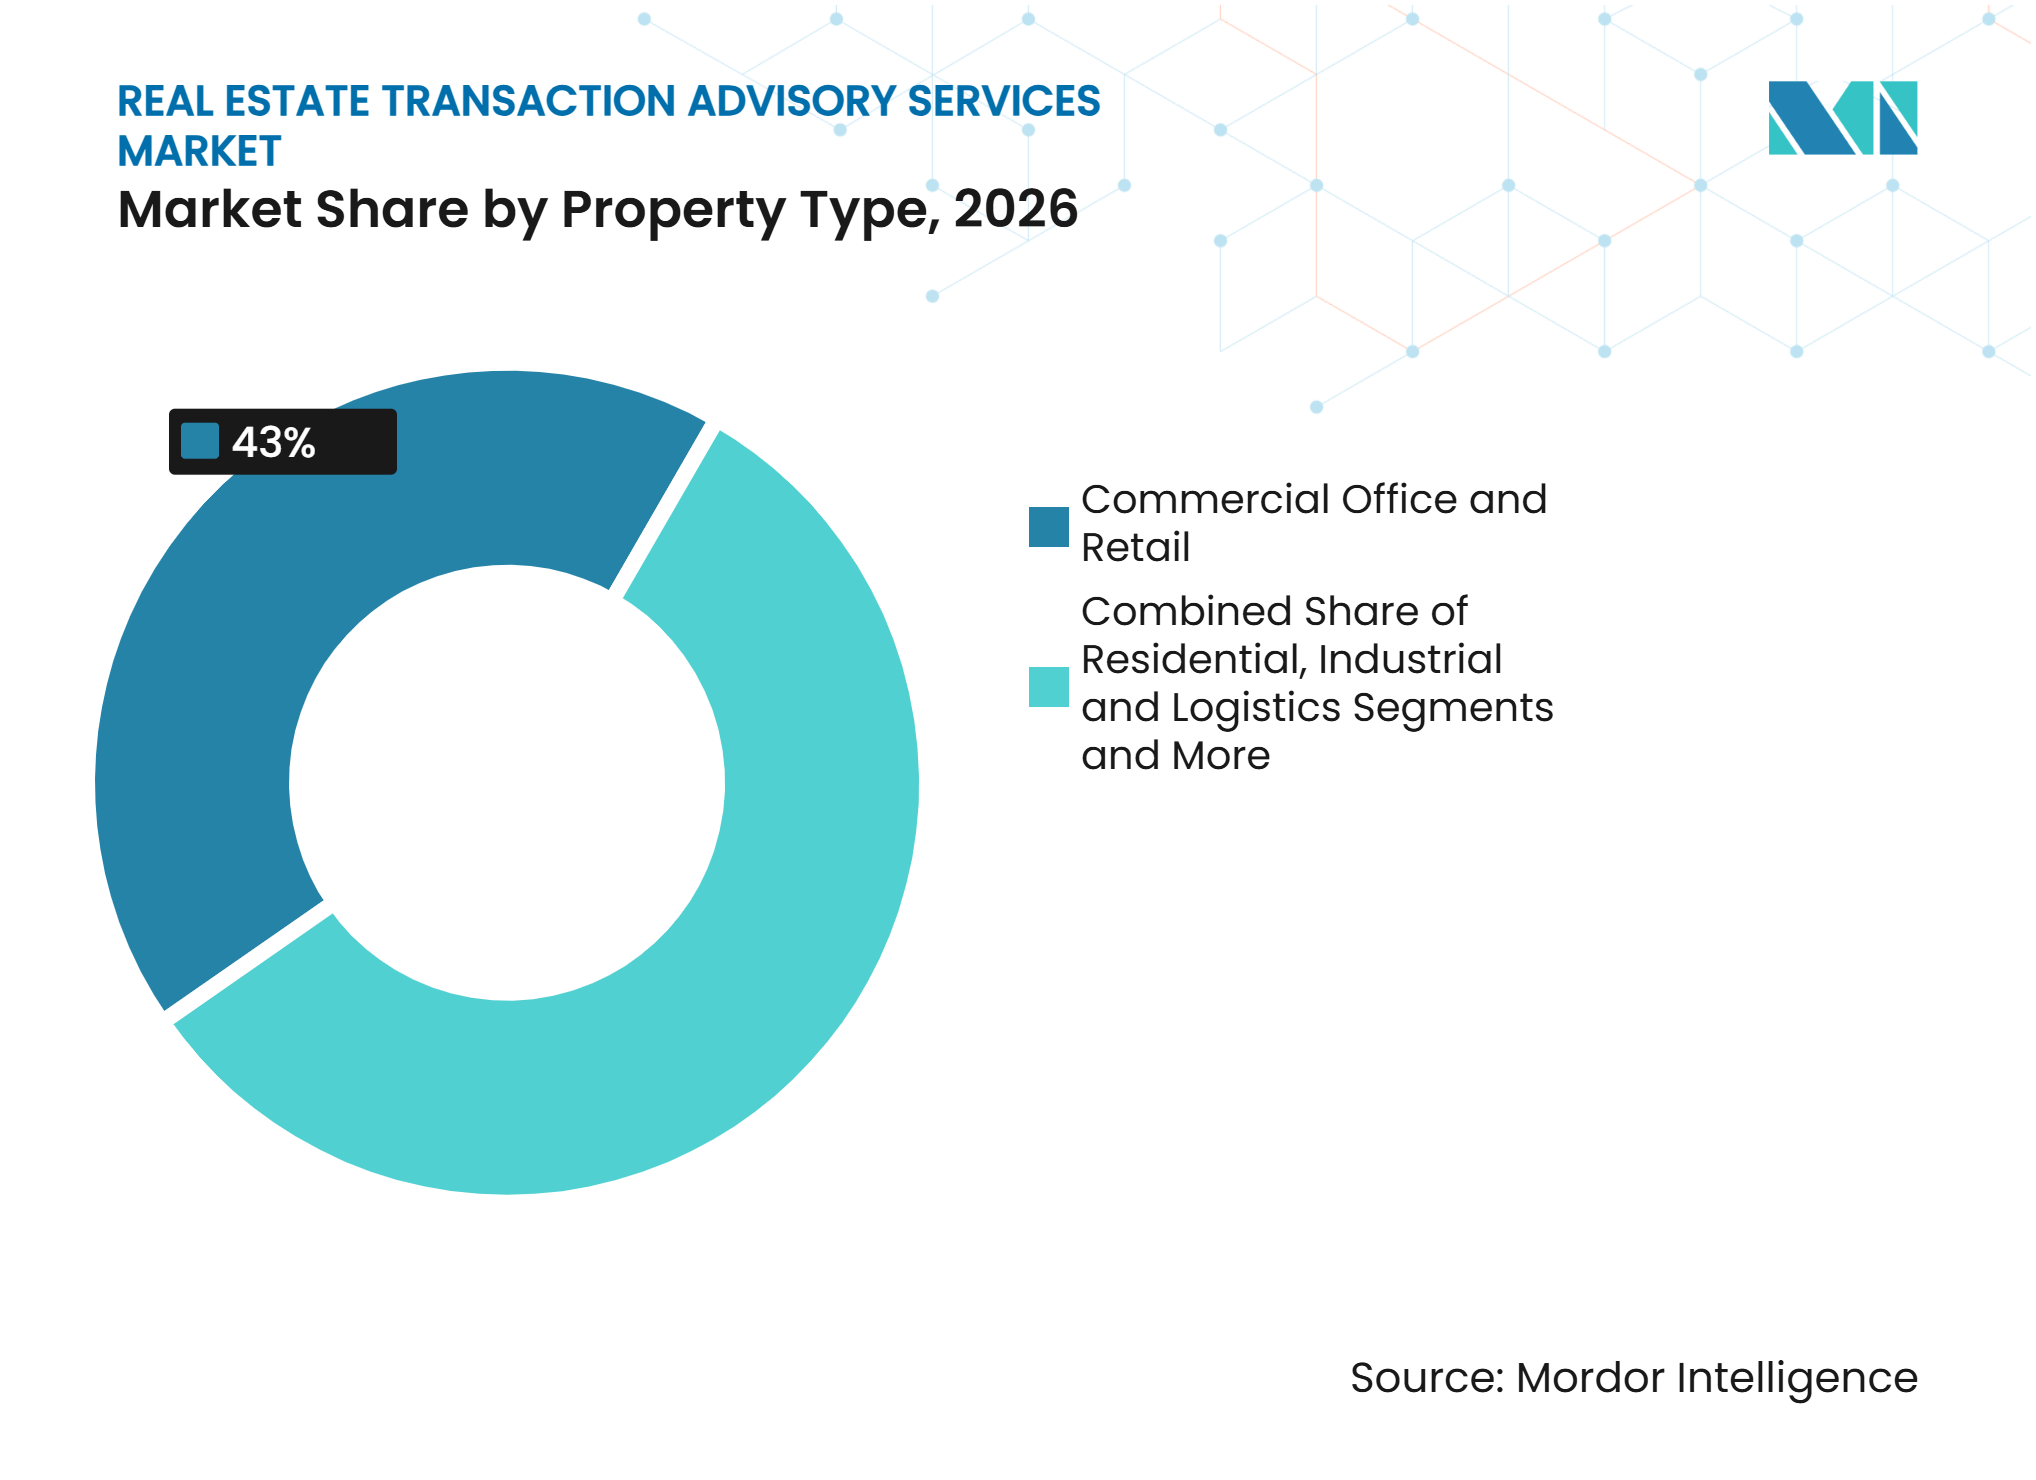
Commercial Office and Retail Leads, While Industrial and Logistics Grows FastestCommercial Office and Retail held 43.0% of the Real Estate Transaction Advisory Services Market share in 2026. The segment has a broad installed base, established investor participation, and continuing demand for both acquisition and restructuring support. Better-quality office assets can attract capital when they meet tenant, location, and energy performance expectations. At the same time, weaker office properties can require restructuring, refinancing, or repositioning advice. This creates transaction work across different parts of the same property category.
Energy efficiency and green lease considerations are becoming more prominent in office mandates. Industrial and Logistics is the fastest-growing property type, at a 9.27% CAGR through 2032. Demand for data-center-adjacent sites, manufacturing capacity, and last-mile distribution facilities is increasing the need for specialist advice. Newmark launched an Industrial and Logistics Advisory division in Germany in August 2026, showing how advisers are adding dedicated coverage for this property type. The segment requires local site knowledge, supply-chain awareness, and the ability to assess power, transport, and tenant requirements.

Geography Analysis
North America
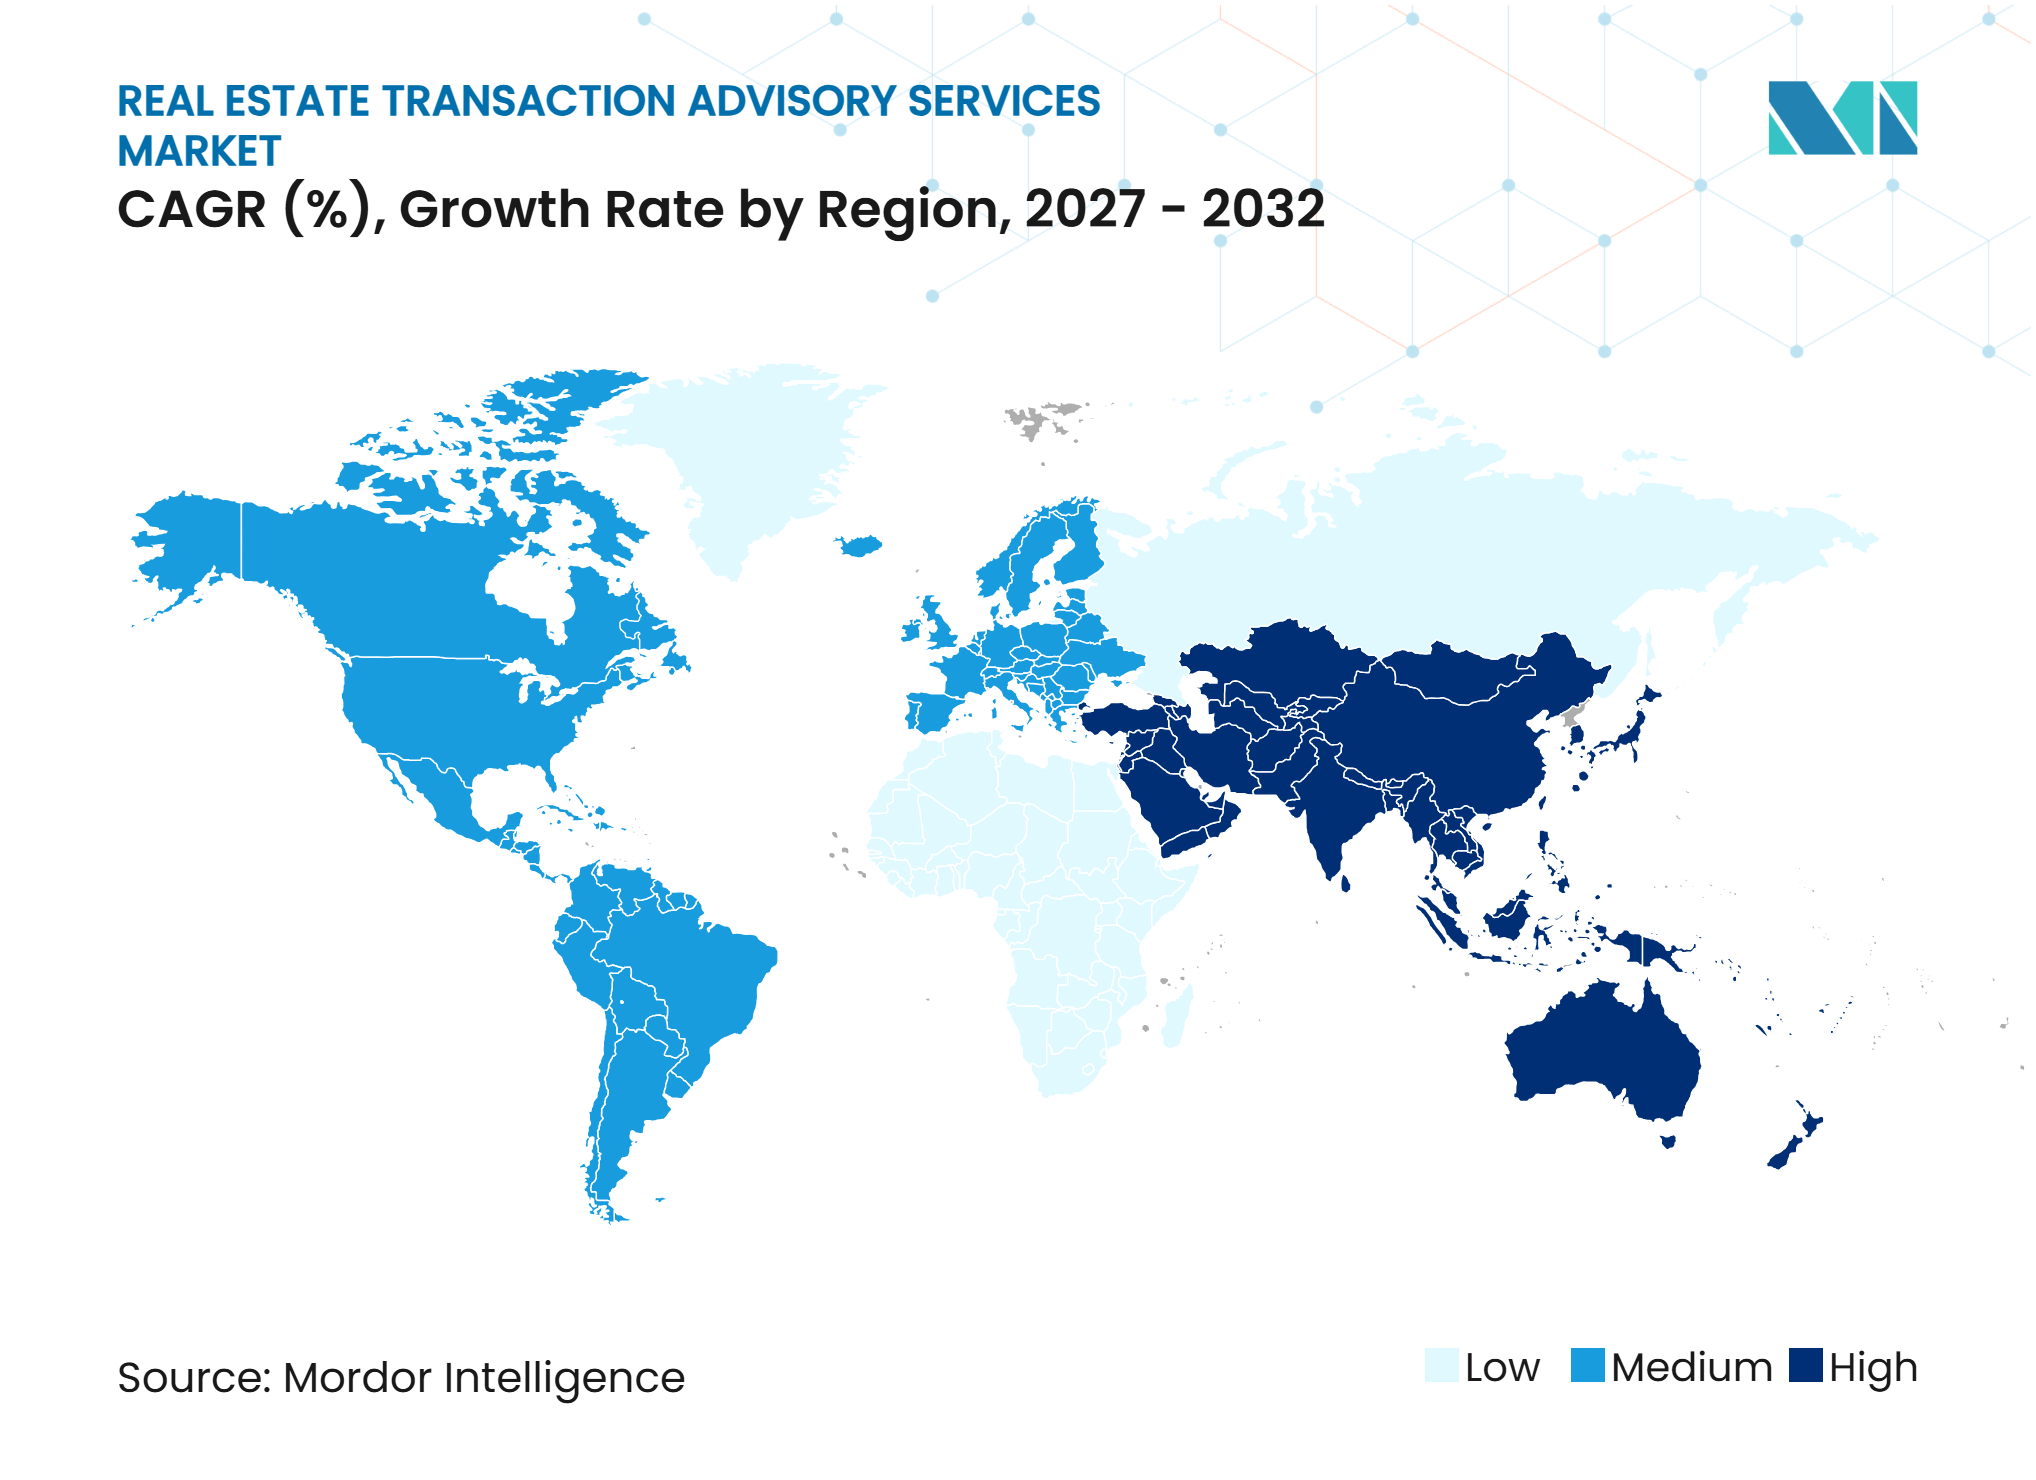
North America held 38.0% of the Real Estate Transaction Advisory Services Market share in 2026. Its position rests on a deep institutional investor base, mature advisory networks, and diverse commercial property activity. CBRE recorded USD 528.3 billion in United States commercial real estate investment volume through the third quarter of 2026, with multifamily, industrial, and data centers all supporting assignment volume. Alternative lenders represented 48% of non-agency commercial real estate loan closings, making lender selection and term negotiation a larger part of advisory work. The region also has an active special-situations pipeline, and Berkadia's new platform shows how firms are building targeted capability for lenders and asset owners.
Asia-Pacific
Asia-Pacific is projected to grow at a 9.18% CAGR through 2032. JLL reported USD 47 billion in Asia-Pacific real estate investment volume in the first quarter of 2026, with strong activity in Singapore and India. JLL's Osaka data center assignment shows the importance of specialized digital infrastructure knowledge in this region. Capital recycling by regional owners can support recurring sales and reinvestment mandates.
Europe, South America, and the Middle East and Africa
Europe continues to offer advisory opportunities in prime logistics and office assets, even as elevated borrowing costs slow some transactions. JLL France reported that foreign investors represented 61% of French real estate investment volume in the first three quarters of 2026, supporting the need for cross-border advice. In the Middle East and Africa, Saudi Arabia's updated ownership framework has increased the importance of legal and regulatory advice for foreign investors. The Abu Dhabi Real Estate Centre reported a 76.1% year-over-year increase in transaction value in the first nine months of 2026, indicating a more active regional transaction environment. Across these mixed markets, advisers need market-specific compliance knowledge, sound local partnerships, and the ability to manage cross-border investor requirements.
Competitive Landscape
Market Concentration
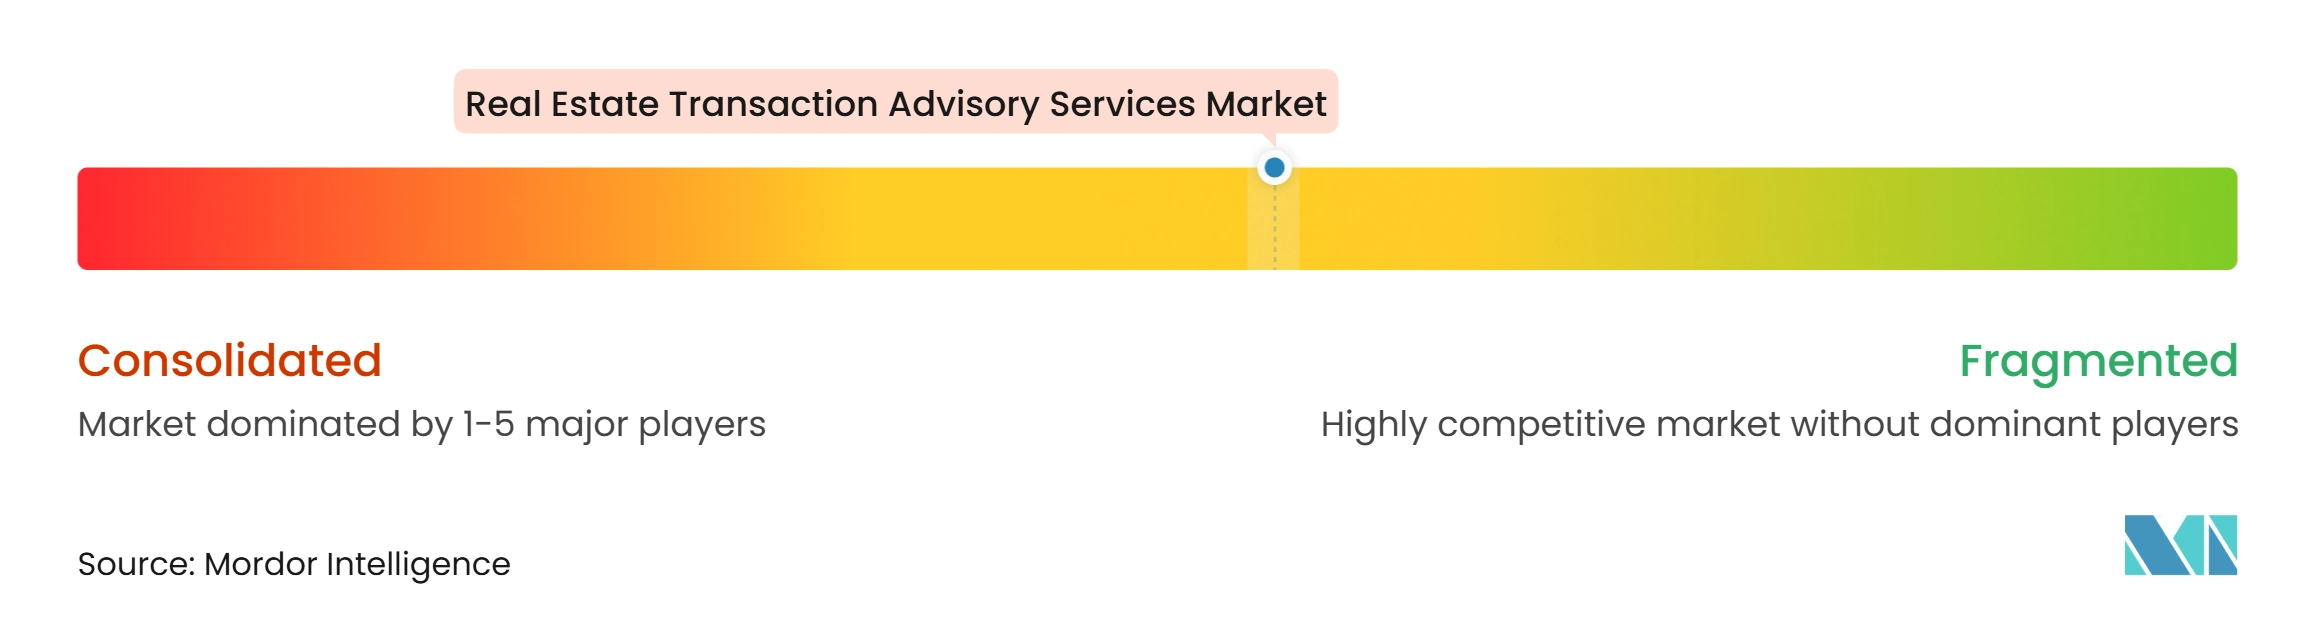
The Real Estate Transaction Advisory Services Market has a moderately concentrated structure. CBRE Group, Inc., Jones Lang LaSalle Incorporated, Cushman & Wakefield plc, Colliers International Group Inc., and Newmark Group Inc. compete for large institutional mandates. Their scale gives them access to broad client relationships, global research, and teams that cover leasing, capital markets, valuation, and property operations. At the same time, boutique firms can compete where clients need independence, a specialized asset focus, or local regulatory knowledge. Competition therefore occurs between integrated global platforms and focused advisers rather than within a single uniform model.
Companies are investing in technical and digital capabilities to reduce their reliance on transaction fees. JLL acquired VIPA Digital Limited in November 2026, adding data center consultancy capabilities that cover site selection, technical due diligence, power assessment, and disposal advice. This action shows that advisers are seeking expertise that helps clients make decisions before a formal transaction begins. Information security also matters as firms manage sensitive client material, particularly where the International Organization for Standardization ISO 27001 standard and the European Union General Data Protection Regulation apply. These requirements can add to the value of established compliance processes.
Specialization is another important competitive strategy in the Real Estate Transaction Advisory Services Market. Savills acquired a majority interest in Hotelivate in August 2026 to strengthen its hospitality advisory capabilities across Asia-Pacific. Transwestern added a national debt and equity placement team in June 2026, which expanded its structured finance coverage across several property types. Firms that can combine a sector specialty with strong financing or cross-border execution are better placed to win complex mandates.
Real Estate Transaction Advisory Services Industry Leaders
-
CBRE Group, Inc.
-
Jones Lang LaSalle Incorporated
-
Cushman & Wakefield plc
-
Colliers International Group Inc.
-
Newmark Group, Inc.
- *Disclaimer: Major Players sorted in no particular order
Real Estate Transaction Advisory Services Market Companies Covered in this Report
- CBRE Group, Inc.
- Jones Lang LaSalle Incorporated
- Cushman & Wakefield plc
- Colliers International Group Inc.
- Newmark Group, Inc.
- Savills plc
- Knight Frank LLP
- BNP Paribas Real Estate S.A.
- Avison Young (Canada) Inc.
- Transwestern Commercial Services LLC
- Eastdil Secured, L.L.C.
- Marcus & Millichap Inc.
- NAI Global
- Lee & Associates Licensing & Administration Co. LP
- Brookfield Asset Management Ltd.
- CapitaLand Investment Limited
- Tishman Speyer Properties, L.P.
- Deloitte Touche Tohmatsu Limited
- PricewaterhouseCoopers International Limited
- KPMG International Limited
Recent Industry Developments in Real Estate Transaction Advisory Services Market
- November 2026: JLL completed the acquisition of VIPA Digital Limited, a London-headquartered independent data center consultancy, adding full-lifecycle advisory capabilities across the data center sector. The move positions JLL to capture advisory fees across site selection, technical due diligence, power assessment, and disposition in one of the fastest-growing real estate advisory categories globally.
- November 2026: JLL advised Nuveen Real Estate on the USD 445.5 million acquisition of a 13-property Western US retail portfolio, also arranging USD 239 million in acquisition financing through US Bank for 11 of the 13 properties.
- October 2026: BNP Paribas Real Estate Netherlands advised an institutional investor on the sale of De Bary, a six-monumental-canal-house office complex in Amsterdam's Gouden Bocht, to Highbrook Investors.
Global Real Estate Transaction Advisory Services Market Report Scope
Segmentation Overview
| Property Acquisition and Disposal Advisory |
| Leasing Advisory Services |
| Mergers and Acquisitions Advisory |
| Capital Markets and Financing Advisory |
| Other Transaction Advisory Services |
| Sales |
| Rental |
| Residential |
| Commercial Office and Retail |
| Industrial and Logistics |
| Others |
| North America | United States |
| Canada | |
| Mexico | |
| South America | Brazil |
| Argentina | |
| Chile | |
| Rest of South America | |
| Europe | United Kingdom |
| Germany | |
| France | |
| Italy | |
| Spain | |
| Russia | |
| Rest of Europe | |
| Asia - Pacific | China |
| India | |
| Japan | |
| South Korea | |
| Australia | |
| Rest of Asia - Pacific | |
| Middle East and Africa | United Arab Emirates |
| Saudi Arabia | |
| South Africa | |
| Nigeria | |
| Rest of Middle East & Africa |
| By Service Type | Property Acquisition and Disposal Advisory | |
| Leasing Advisory Services | ||
| Mergers and Acquisitions Advisory | ||
| Capital Markets and Financing Advisory | ||
| Other Transaction Advisory Services | ||
| By Transaction Type | Sales | |
| Rental | ||
| By Property Type | Residential | |
| Commercial Office and Retail | ||
| Industrial and Logistics | ||
| Others | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| South America | Brazil | |
| Argentina | ||
| Chile | ||
| Rest of South America | ||
| Europe | United Kingdom | |
| Germany | ||
| France | ||
| Italy | ||
| Spain | ||
| Russia | ||
| Rest of Europe | ||
| Asia - Pacific | China | |
| India | ||
| Japan | ||
| South Korea | ||
| Australia | ||
| Rest of Asia - Pacific | ||
| Middle East and Africa | United Arab Emirates | |
| Saudi Arabia | ||
| South Africa | ||
| Nigeria | ||
| Rest of Middle East & Africa | ||
Key Questions Answered in the Report
What is the forecast growth rate for real estate transaction advisory services?
The sector is projected to grow at a 7.43% CAGR from 2027 to 2032, reaching USD 22.44 billion by 2032.
Which service type has the largest share of real estate transaction advisory services?
Property Acquisition and Disposal Advisory leads with 36.0% of revenue in 2026.
Which transaction advisory service is growing the fastest?
Capital Markets and Financing Advisory is projected to grow at an 8.30% CAGR through 2032 as clients seek help with complex funding structures.
Which property category is expanding fastest for transaction advisers?
Industrial and Logistics is forecast to grow at a 9.27% CAGR through 2032, supported by logistics, manufacturing, and data-center-related investment.
Which region leads real estate transaction advisory services?
North America leads with 38.0% of revenue in 2026, supported by a large institutional investor base and diverse commercial property activity.
Why are data centers important for transaction advisers?
Data center deals require advice on power, technical due diligence, tenant assessment, and financing, which makes them specialized assignments.