
North America Data Center Water Treatment and Recycling Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
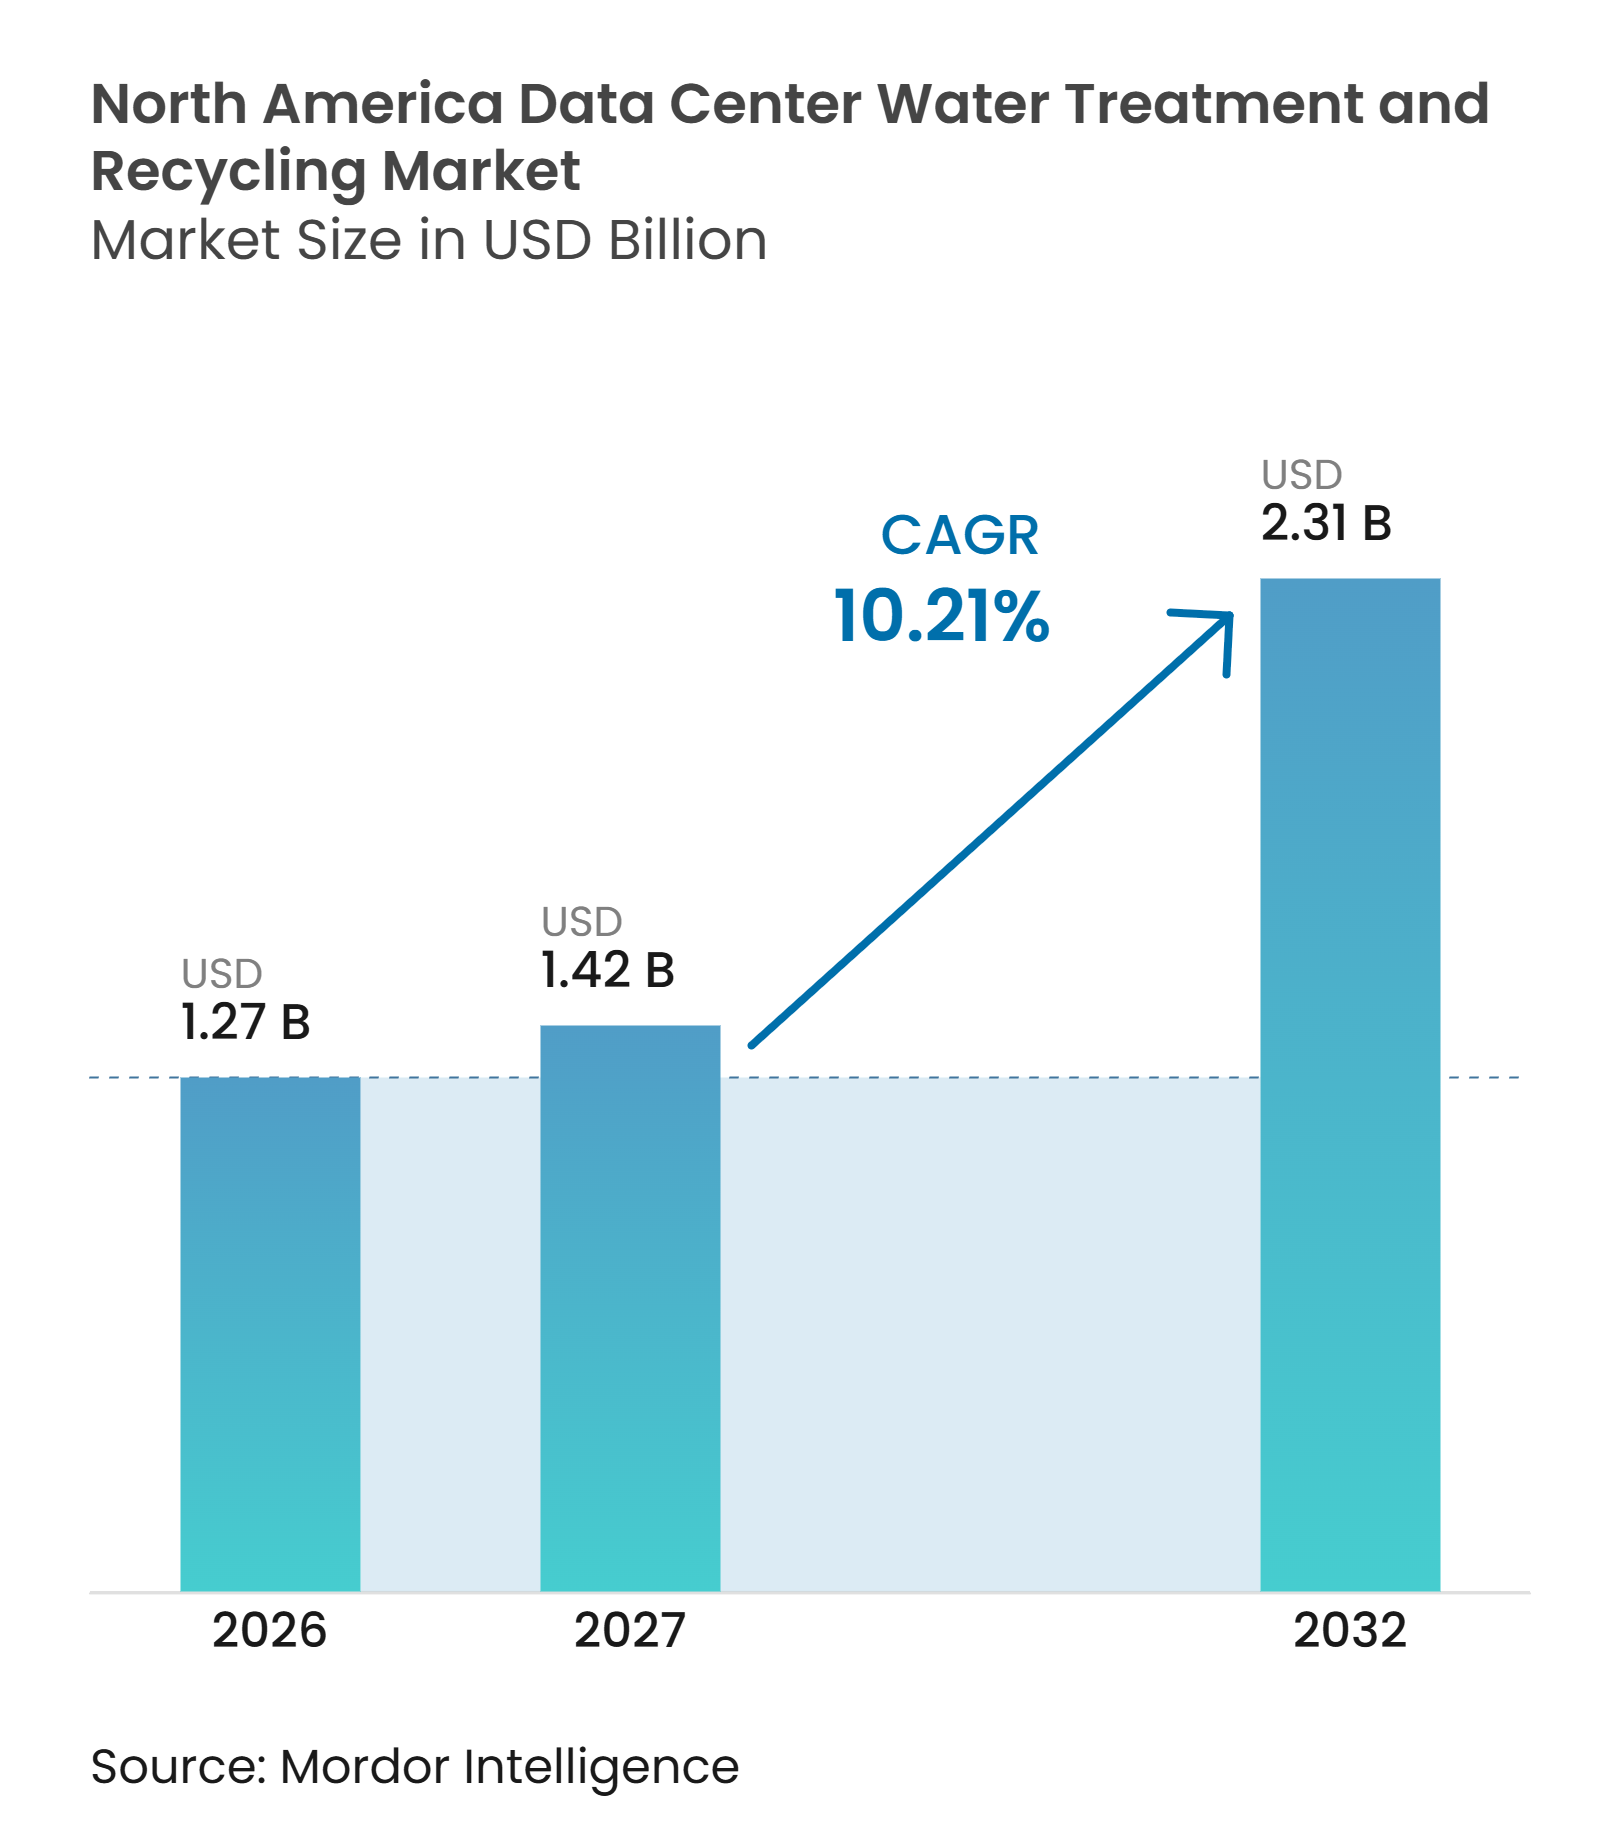
| Base Year Market Size (2026) | USD 1.27 Billion |
| Market Size (2027) | USD 1.42 Billion |
| Market Size (2032) | USD 2.31 Billion |
| Growth Rate (2027 - 2032) | 10.21 % |
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
North America Data Center Water Treatment and Recycling Market Analysis by Mordor Intelligence
The North America data center water treatment and recycling market size is valued at USD 1.27 billion in 2026 and is forecast to reach USD 2.31 billion by 2032, advancing at a CAGR of 10.21% over 2027-2032. The North America data center water treatment and recycling market is being shaped by AI computing projects that require more reliable cooling water and more complex treatment systems. Water availability now affects site selection, capital planning, and operating costs for large campuses. State rules, municipal capacity limits, and disclosure requirements are encouraging operators to use recycled water and on-site treatment. Integrated systems that combine treatment equipment, water chemistry, monitoring, and liquid cooling support are becoming more important in supplier selection. The North America data center water treatment and recycling market also faces delays where drought conditions, tariff changes, uncertain permits, and difficult retrofits affect project economics.
Key Report Takeaways
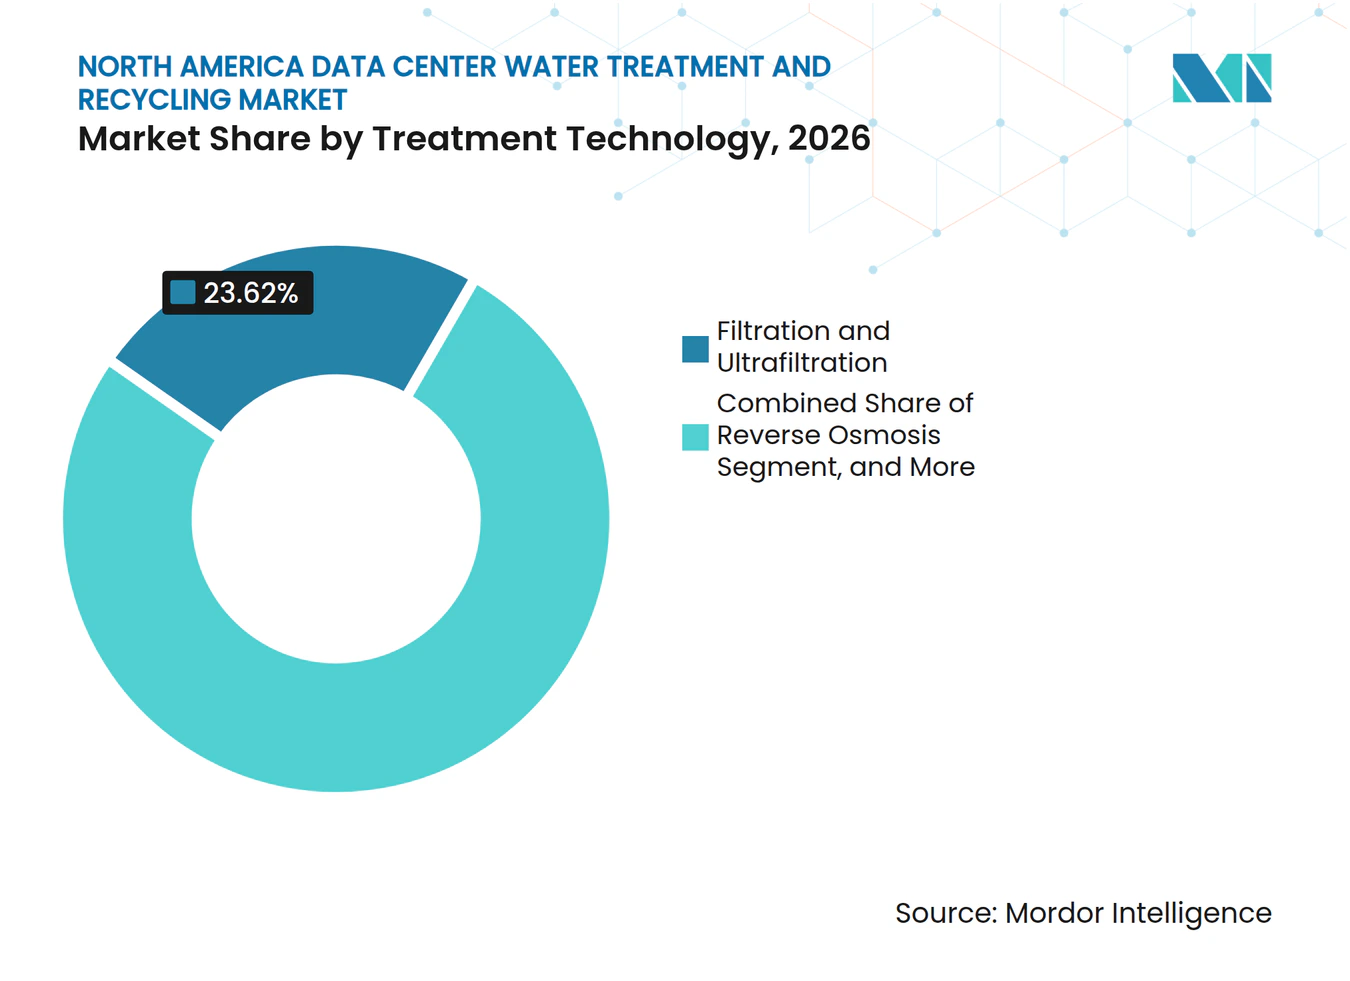
- By treatment technology, filtration and ultrafiltration held 23.62% revenue share in 2026, while other water treatment technologies are projected to expand at a CAGR of 10.48% through 2032.
- By water source, municipal water held 33.86% revenue share in 2026, while other alternative water sources are projected to expand at a CAGR of 10.86% through 2032.
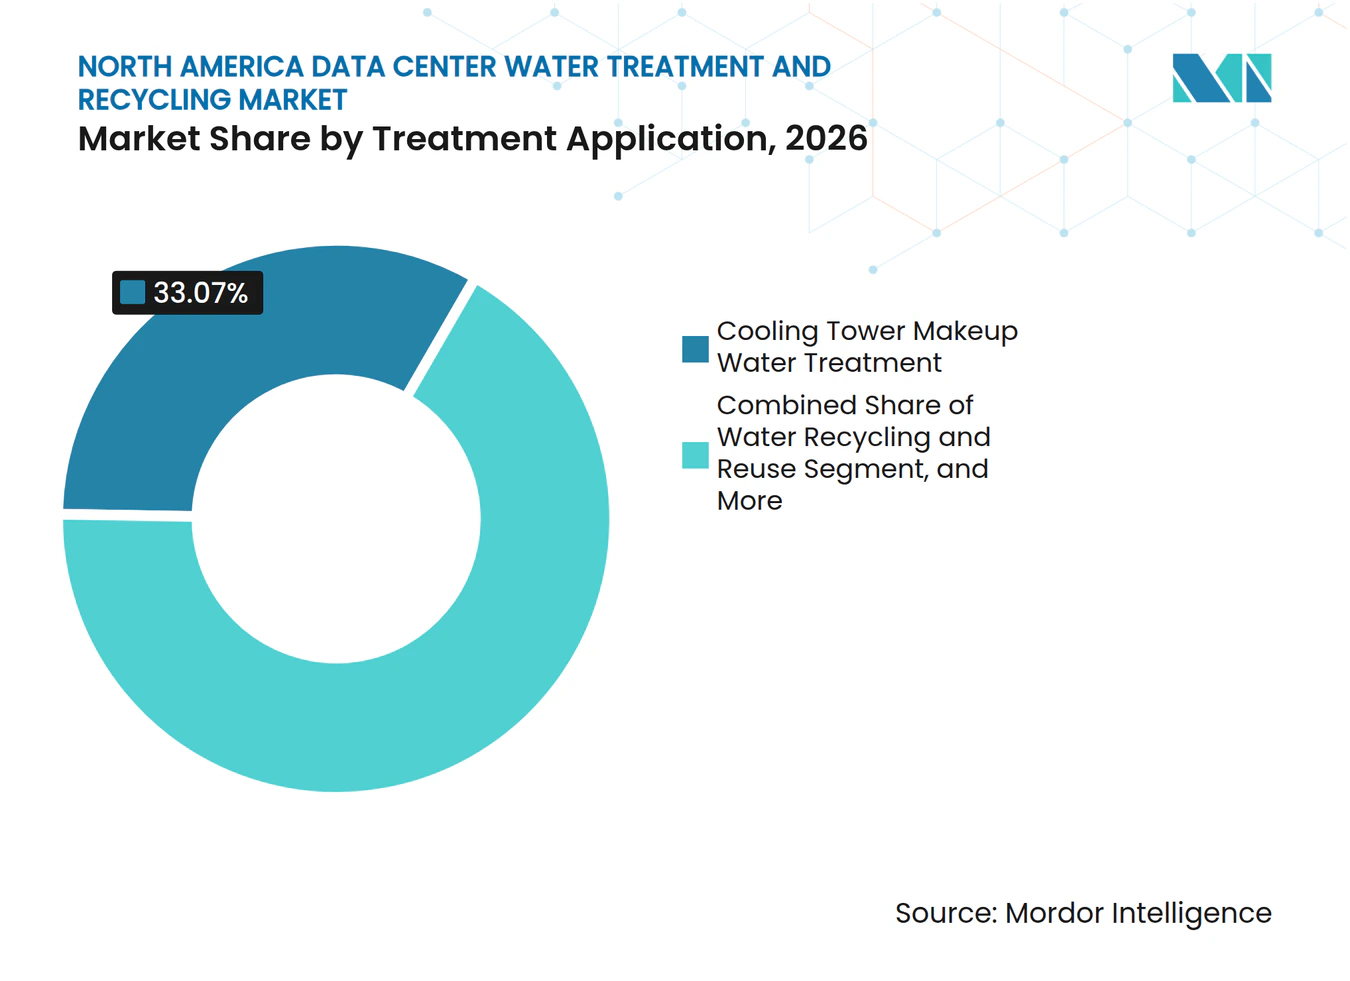
- By treatment application, cooling tower makeup water treatment held 33.07% revenue share in 2026, while ZLD and concentrate management are projected to expand at a CAGR of 10.77% through 2032.
- By solution type, water treatment equipment held 40.94% revenue share in 2026, while water quality monitoring and control systems are projected to expand at a CAGR of 10.58% through 2032.
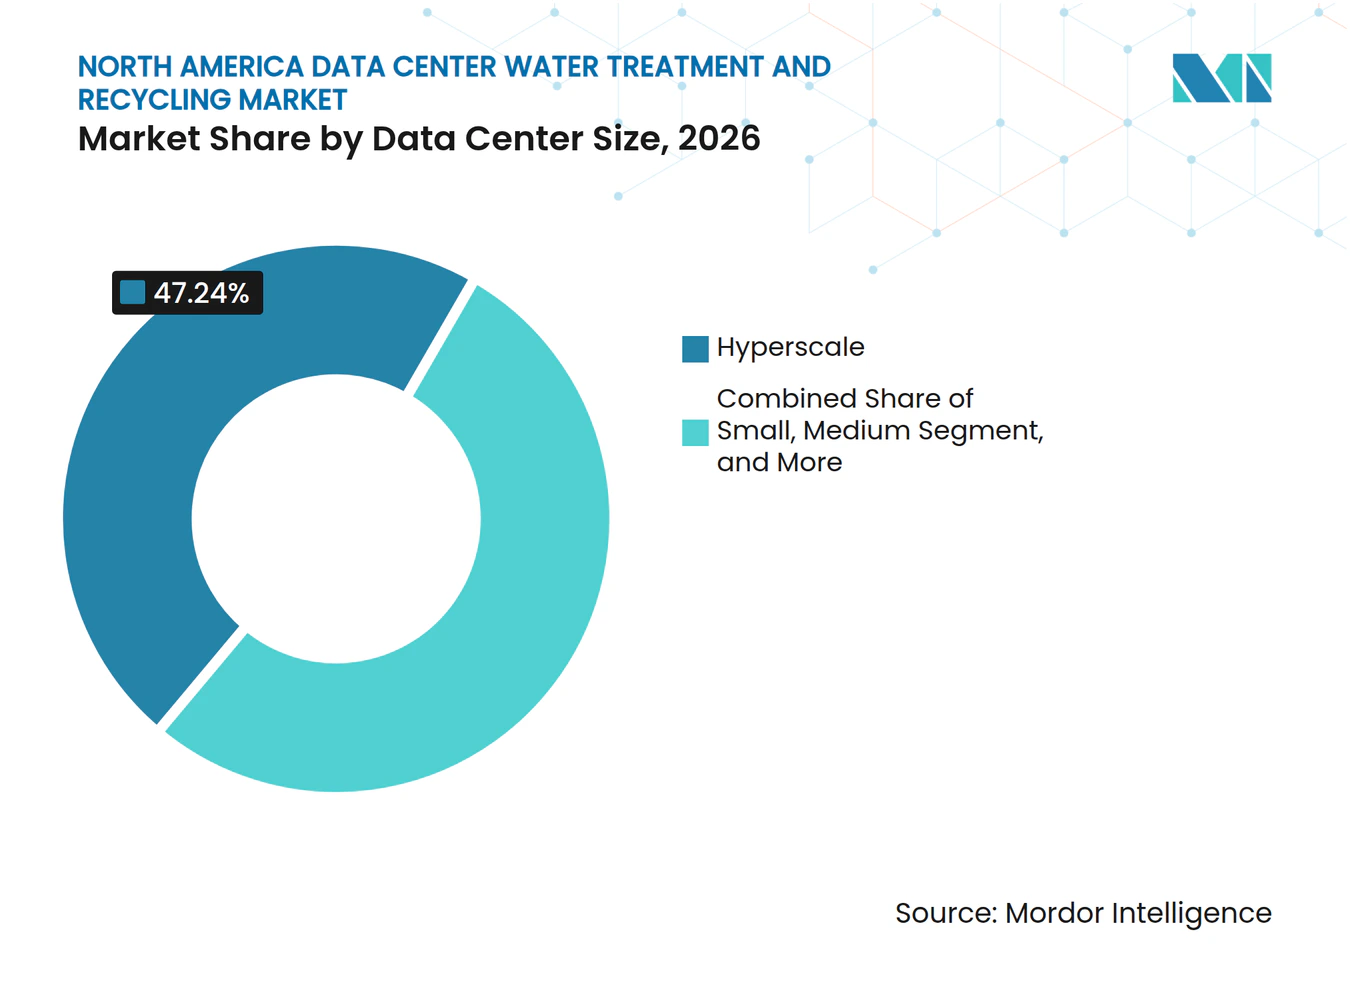
- By data center size, hyperscale facilities held 47.24% revenue share in 2026 and are projected to expand at a CAGR of 10.84% through 2032.
- By data center type, cloud service providers held 50.39% revenue share in 2026 and are projected to expand at a CAGR of 10.96% through 2032.
- By geography, the United States held 87.01% of the North America data center water treatment and recycling market in 2026, while Canada is projected to expand at a CAGR of 11.14% through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of North America Data Center Water Treatment and Recycling Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| AI and Hyperscale Data Center Expansion | +3.2% | Global, concentrated in United States | Short term (≤ 2 years) |
| Water Scarcity Driven Adoption of Recycling and Reuse | +2.1% | United States, Southwest and Southeast, Mexico | Medium term (2-4 years) |
| Direct to Chip and High Density Liquid Cooling Deployment | +1.8% | North America and EU, spillover to Asia-Pacific | Short term (≤ 2 years) |
| WUE Disclosure and Permit Linked Efficiency Requirements | +1.4% | United States, state level, Canada, provincial | Medium term (2-4 years) |
| Cooling Tower Blowdown and HVAC Condensate Recovery | +0.9% | National, with early gains in Texas, Virginia, and Arizona | Long term (≥ 4 years) |
| Modular Reclaimed Water Treatment for Greenfield Campuses | +0.7% | North America, Midwest and Southeast greenfield regions | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
AI and Hyperscale Data Center Expansion Drives Industrial Scale Water Treatment
AI workloads are increasing water demand at facilities that need industrial treatment systems rather than a municipal supply alone. US data centers consume 449 million gallons of water each day, and AI expansion could require an additional 697 million to 1,451 million gallons each day by 2030.[1] A 100 MW data center can use as much water each day as 6,500 households, which makes water infrastructure a major operating consideration for campus owners. Higher thermal density raises cooling water temperatures and increases the need for chemical treatment and membrane replacement. These conditions favor suppliers that can provide higher-specification equipment and ongoing operating support. The North America data center water treatment and recycling market, therefore, benefits when new AI campuses include treatment requirements during design rather than after construction.
Water Scarcity Drives Recycling and Reuse Across More Sites
Water stress in Arizona, Texas, northern Virginia, and Querétaro is making water recycling a practical condition for expansion rather than a voluntary sustainability measure. Amazon Web Services has expanded recycled water use to more than 120 data centers and invested more than USD 1 billion in water infrastructure. The company expects to save 530 million gallons of fresh water each year through these efforts. Its Mississippi campus is developing containerized treatment infrastructure to convert municipal effluent into cooling-grade water by 2027.[2] In Mexico, limits on industrial water concessions make on-site reuse more relevant for campuses in water-stressed states. The North America data center water treatment and recycling market gains opportunities where treatment assets can also support surrounding community water systems.
Direct to Chip Liquid Cooling Changes Water Chemistry Needs
The move from air cooling to liquid cooling changes water chemistry requirements and broadens the role of treatment providers. Closed-loop direct-to-chip systems need ultrapure fluid management, including electrodeionization and precise ion exchange. Hybrid designs also produce concentrated cooling tower blowdown that must be treated before discharge or reuse. Ecolab introduced its Cooling as a Service program in November 2025, combining 3D TRASAR technology for direct-to-chip cooling with a smart coolant distribution unit. Microsoft reported that its closed-loop direct-to-chip AI design operates with zero water evaporation during normal operations. The North America data center water treatment and recycling market is consequently extending from facility cooling towers to the coolant loops close to server racks.
WUE Disclosure and Permit Requirements Support Treatment Investment
Water use effectiveness, or WUE, is moving from a voluntary metric to a requirement in permits, utility agreements, and public policy. Minnesota requires developers to engage the state Department of Natural Resources before construction to confirm water availability and closed-loop recycling capability. Illinois authorized treated municipal wastewater for data center cooling in August 2025, which expands the use case for reclaimed-water treatment systems. The US Environmental Protection Agency identifies data centers as a priority sector in its Water Reuse Action Plan 2.0. Compliance expectations connected with Alliance for Water Stewardship certification are also appearing in operator sustainability programs. These requirements give vendors a clearer basis for offering systems with measurable water performance.
Restraints Impact Analysis of North America Data Center Water Treatment and Recycling Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Regional Drought, Water Tariffs, and Allocation Constraints | -1.3% | United States, Southwest, Mexico, Querétaro, Canada, Alberta | Medium term (2-4 years) |
| Retrofit Disruption and Integration Complexity | -0.9% | National, concentrated in Northern Virginia and Silicon Valley | Long term (≥ 4 years) |
| Unclear Permitting Pathways for Recycled Cooling Water | -0.6% | United States, state by state variation, Mexico, federal gap | Medium term (2-4 years) |
| Intermittent Slug Loads on Publicly Owned Treatment Works | -0.3% | United States, municipal systems adjacent to large campuses | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Regional Drought, Water Tariffs, and Allocation Constraints Affect Siting Economics
Drought and water allocation rules redirect investment, but they can add cost and delay to new projects. Alberta has a moratorium on new water licenses from the Bow River Basin, so developers may need existing rights or constrained municipal supplies. High and changing tariffs in stressed basins can weaken the financial case for conventional treatment programs that assumed stable water prices. These conditions create a stronger case for reuse, but smaller operators may have difficulty funding the required capital work. In Querétaro, industrial water concessions limit extraction volumes and increase the importance of reuse for future expansion. The North America data center water treatment and recycling market must therefore address both water availability and the cost of accessing permitted supply.
Retrofit Disruption and Integration Complexity Slow Upgrades
Many existing facilities in northern Virginia and Silicon Valley were not designed for advanced recycling systems. Adding reverse osmosis or ZLD equipment can require cooling tower blowdown connections, civil work, and planned operational downtime. Colocation operators may find these interruptions difficult to schedule without affecting service commitments to tenants. KMX Technologies introduced a vacuum membrane distillation system in December 2025 that was designed as a modular retrofit for cooling tower blowdown reuse.[3] State discharge permit requirements can add testing, insurance, and reporting costs. These barriers can lengthen payback periods and make brownfield adoption slower than deployment at new campuses.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
North America Data Center Water Treatment and Recycling Market Segment Analysis
By Treatment Technology:
Filtration Provides the Broadest Starting PointFiltration and ultrafiltration held 23.62% of the North America data center water treatment and recycling market share in 2026. These systems are used as a pre-treatment step across many source-water conditions. Their position reflects lower unit costs, simpler integration with existing assets, and applicability across a broad set of feedwater types. Reverse osmosis is a major technology in reclaimed-water treatment trains where operators use municipal effluent for cooling. Ion exchange and water softening help prevent scale in cooling tower makeup circuits. Electrodeionization is becoming more relevant in liquid-cooled server environments where fluid purity requirements are higher than in evaporative cooling.
Other water treatment technologies are projected to expand at a CAGR of 10.48% through 2032. This category includes vacuum membrane distillation, electrochemical treatment, and AI-enabled monitoring platforms. Research has found that ultra-tight ultrafiltration before reverse osmosis can recover biotech and municipal wastewater for cooling with lower lifecycle greenhouse gas emissions than seawater desalination. As source-water quality becomes more variable, operators will need treatment trains that can manage contaminants and maintain stable cooling performance. This supports broader use of specialized membranes and automated controls and can help operators use lower-quality water without compromising cooling conditions.



By Water Source:
Municipal Supply Remains Important While Alternatives ExpandMunicipal water held 33.86% of the North America data center water treatment and recycling market share in 2026. It remains the most consistently quality-assured source in cities where reclaimed-water networks are not yet widely available. Groundwater and surface water support many rural and exurban campuses, but these sources may require more extensive pre-treatment. Aquifer depletion can increase total dissolved solids, while surface-water rules can tighten the quality requirements for intake and discharge. Reclaimed municipal wastewater and industrial recycled water are becoming more important where cities have suitable distribution infrastructure.
Other alternative water sources are projected to expand at a CAGR of 10.86% through 2032. This group includes brackish groundwater, HVAC condensate, and stormwater. Loudoun Water delivered 736 million gallons of recycled water to northern Virginia data center operators in 2024 at less than half the cost of drinking water. Illinois law now permits treated municipal wastewater for data center cooling. Research on municipal wastewater treatment confirms that suitable pre-treatment combinations before reverse osmosis can produce cooling-grade water. Suppliers with experience in variable-quality water sources are better aligned with the changing mix of available supply.
By Treatment Application:
Cooling Tower Makeup Water Is the Largest UseCooling tower makeup water treatment held 33.07% of the North America data center water treatment and recycling market size in 2026. Cooling towers remain common at most facilities, including campuses that use direct-to-chip liquid cooling for AI servers. Chilled-water and closed-loop treatment is another significant use because server-side coolant loops need different quality controls from open cooling circuits. Boiler and heat-rejection system treatment holds a steadier role in cold-climate locations that use steam or hot-water systems as redundant heat-rejection paths. These applications require treatment programs that protect equipment from scale, corrosion, and biological growth.
ZLD and concentrate management are projected to expand at a CAGR of 10.77% through 2032. This activity supports closed-cycle water designs by managing brine and other concentrated waste streams. Research published in 2025 identified reverse osmosis as the most cost-effective first stage in ZLD trains and found that higher recovery lowers the downstream crystallization load. This makes high-recovery reverse osmosis more relevant for campuses seeking zero discharge to surface water. The North America data center water treatment and recycling market is responding to this demand with treatment designs that reduce fresh-water withdrawals and discharge volumes. Such systems are especially relevant where permits require stronger control of wastewater release.

By Solution Type:
Equipment Leads While Monitoring Becomes More ImportantWater treatment equipment held 40.94% revenue share in 2026. This category includes filtration skids, reverse osmosis trains, electrodeionization units, chemical dosing systems, and ZLD crystallizers. These assets form the physical base for on-site water management. Water treatment chemicals provide recurring demand, including formulations for biofouling control and corrosion inhibition in closed-loop liquid cooling circuits. Operation and maintenance services and treatment-plant design are also becoming more important as hyperscale operators outsource complex water activities.
Water quality monitoring and control systems are projected to expand at a CAGR of 10.58% through 2032. Real-time sensor networks, AI-based anomaly detection, and digital reporting needs are supporting this growth. Ecolab’s 3D TRASAR platform is part of its Cooling as a Service offering for direct-to-chip liquid cooling. The platform helps identify scaling, biofouling, and chemical imbalance faster than periodic manual sampling. Centralized monitoring can also help multi-site operators compare water performance across their portfolio. This capability has value when corporate sustainability teams require auditable performance information.
By Data Center Size:
Hyperscale Facilities Lead Demand and ExpansionHyperscale data centers held 47.24% revenue share in 2026. Large campuses typically operate at 100 MW to 1 GW or more of IT load, making on-site water treatment operationally necessary and financially practical. Their high water volumes can support the fixed cost of dedicated treatment assets. Large data centers often deploy partial recycling systems that recover cooling tower blowdown without making the full investment required for ZLD. Small and medium facilities more often use chemical dosing programs and periodic service contracts.
Hyperscale facilities are projected to expand at a CAGR of 10.84% through 2032. Microsoft reported a low average WUE, while Amazon Web Services reported a global WUE significantly below the industry average. This comparison strengthens procurement interest in systems that produce verifiable improvements. Vendors that provide measurable treatment performance and monitoring data can support WUE reporting more directly. Smaller operators still create broad service opportunities, although their requirements are less extensive.
By Data Center Type:
Cloud Providers Account for the Largest DemandCloud service providers held 50.39% revenue share in 2026. Their large AI buildout requires new hyperscale campuses to be developed quickly and with comprehensive water infrastructure. Colocation operators are the second segment by value, but they face a different commercial structure. Cooling demand is often controlled by tenants, so water treatment investments may need to be reflected in lease agreements. Enterprise and edge facilities generally have simpler treatment needs, including chemical dosing, softening, and periodic maintenance.
Cloud service providers are projected to expand at a CAGR of 10.96% through 2032. At its initial Mississippi campus, Amazon Web Services is working with Veolia to convert municipal effluent into cooling water in the coming years. Microsoft reported that most of its owned fleet used low- to zero-water cooling systems. It also reported a substantial improvement in water-use intensity from its earlier baseline. These examples show why cloud buyers favor systems designed around stated WUE objectives instead of standard equipment packages. The same requirements are gradually influencing colocation lease terms and operator responsibilities.
Geography Analysis
North America
North America held 32.84% of regional revenue in 2026. The United States supports this position through hyperscale construction in Northern Virginia, Texas, Arizona, and Georgia, where water-stressed locations are increasing attention on reclaimed water, cooling efficiency, and reliable discharge management. Essential Utilities announced a USD 26 million investment for an 18-million-gallon-per-day plant intended to serve a data center and its on-site power facility, showing how large campuses can act as anchor customers for purpose-built treatment capacity. State-level water rights, industrial discharge permits, and reclaimed-water approvals vary across the United States, which favors providers with broad local execution capability. In Canada, the Quebec and Ontario corridor has a different profile because water-system reliability can be more important than absolute scarcity.
Asia-Pacific
Asia-Pacific is projected to expand at a 10.94% CAGR through 2032. China is a key driver because national and local water-efficiency rules are increasing the value of monitoring, water-use effectiveness measurement, and reuse systems. The GB/T 32910.6-2025 standard establishes water-use effectiveness measurement for data centers, while an Alibaba Cloud facility in Beijing continued to meet its targets after 3 years using ultrafiltration and double-stage reverse osmosis. Malaysia, Singapore, India, and South Korea add demand through data center construction and growing scrutiny of resource efficiency. Regional demand is also supported by projects that use treated effluent to reduce dependence on potable supply.
Europe
Europe is a major regional bloc where disclosure and permitting requirements shape treatment decisions, including water reporting under the EU Corporate Sustainability Reporting Directive and EU Taxonomy from 2025. Germany's Wasserhaushaltsgesetz adds site-specific obligations for cooling-water extraction and thermal discharge, while the Netherlands and Ireland have faced greater scrutiny around water and land use at large campuses.
South America and Middle East and Africa
In South America, water availability and distance from large wastewater plants can limit reclaimed-water use, while severe constraints in Saudi Arabia, the United Arab Emirates, and Qatar make reuse, desalination, and zero liquid discharge more relevant. These mixed regions require technical choices that reflect local hydrology, regulation, and available infrastructure.
Competitive Landscape
Market Concentration
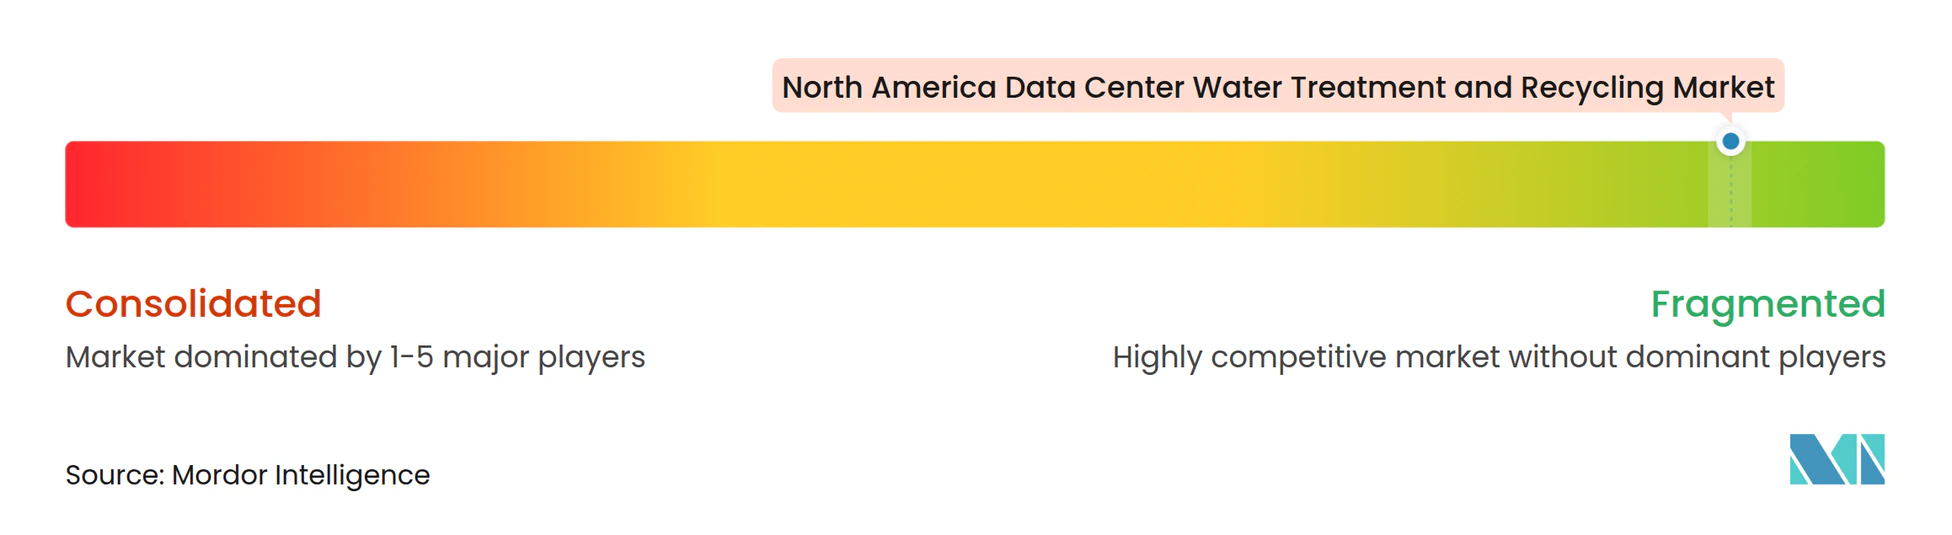
The data center water treatment and recycling market is fragmented, and no supplier holds a dominant overall share. Ecolab, Veolia, and Xylem compete through portfolios that combine equipment, chemicals, monitoring, and long-term managed services, while Gradiant, Kurita, DuPont, Toray, Saltworks Technologies, and IDE Technologies compete through depth in zero-liquid-discharge, membrane bioreactors, high-recovery reverse osmosis, and reclaimed-water treatment. The market concentration score is 1 out of 10 because no top player holds 5% or more of the fragmented global market, while competition remains dispersed across integrated providers and specialists. New technical approaches are also entering the field, including a 2026 US patent covering intelligent trickling-filter water recycling for evaporative cooling in data centers. This structure means the data center water treatment and recycling market rewards product performance, service capability, and regional delivery capacity.
Ecolab closed its acquisition of Ovivo's Electronics ultrapure water business in December 2025 for USD 1.6 billion in cash, expanding its high-tech water capabilities for electronics and data center customers. DuPont announced the acquisition of Sinochem Ningbo RO Memtech in September 2025 to add reverse osmosis membrane manufacturing capacity in China. These moves show that suppliers are using acquisitions to add technology depth and regional production capacity. The data center water treatment and recycling market also places greater value on digital operating tools that can manage water recovery, membrane life, and chemical use. Gradiant's SmartOps, Ecolab's 3D TRASAR, and Xylem Vue illustrate this move toward connected water operations.
The data center water treatment and recycling market leaves opportunities in managed water services for mid-scale colocation sites and packaged systems for edge deployments. Veolia's planned autonomous, containerized treatment systems with Amazon in Mississippi demonstrate how modular formats can serve large operators and provide a model for wider adoption. Suppliers must demonstrate that their systems can manage variable reclaimed-water quality without compromising uptime, making field service, process design, and control software as important as membranes and chemicals. Competitive positions will continue to depend on technical performance, regional presence, and the ability to support long-term water-management programs.
North America Data Center Water Treatment and Recycling Industry Leaders
-
Veolia Environnement S.A.
-
Ecolab Inc.
-
Xylem Inc.
-
SUEZ SA
-
Aquatech International LLC
- *Disclaimer: Major Players sorted in no particular order
North America Data Center Water Treatment and Recycling Market Companies Covered in this Report
- Veolia Environnement S.A.
- Ecolab Inc.
- Xylem Inc.
- SUEZ SA
- Aquatech International LLC
- Solenis LLC
- Kurita Water Industries Ltd.
- DuPont de Nemours, Inc.
- Gradiant Corporation
- Ovivo Inc.
- Pentair plc
- BWT Holding GmbH
- Toray Industries, Inc.
- Alfa Laval AB
- KMX Technologies Inc.
- Hydroleap Pte. Ltd.
- Industrie De Nora S.p.A.
- Tekleen, Inc.
- Vertiv Holdings Co.
- Trane Technologies plc
Recent Industry Developments in North America Data Center Water Treatment and Recycling Market
- September 2026: Gradiant signed an agreement with an undisclosed hyperscale operator to deliver its HyperSolved water and wastewater treatment platform for an AI data-center campus in West Texas. The solution combines alternative water sourcing, high-recovery treatment, wastewater management and AI-based monitoring, with a zero-discharge objective for surface waters
- August 2026: Gradiant announced a new Global Innovation Center in Houston, new offices in Phoenix, Syracuse and Philadelphia, and the appointment of a Managing Director for the Americas. The investment strengthens its North American capabilities in advanced water treatment and operations, including solutions for data centers and AI infrastructure.
- June 2026: Vertiv launched PurgeRite NearZero, a fluid-management service for data-center cooling-system commissioning. It combines mechanical flushing, filtration, reverse osmosis, water treatment, recycling and continuous water-quality monitoring. In selected deployments, Vertiv reported up to 78% lower total water consumption and 91% lower water haul-off volumes compared with conventional commissioning methods.
- May 2026: Gradiant reported deploying its HyperSolved closed-loop water-management system across several large hyperscale data centers. The platform manages water sourcing, treatment, cooling-water quality and discharge, with the aim of increasing reuse and reducing freshwater demand. Customer names and facility locations were not disclosed in the cited announcement.
North America Data Center Water Treatment and Recycling Market Report Scope
The North America Data Center Water Treatment and Recycling Market refers to the regional market for technologies, equipment, chemicals, and services used to treat, condition, and recycle water within data centers across the United States, Canada, and Mexico primarily for cooling systems, liquid-cooling loops, and wastewater management.
The North America Data Center Water Treatment and Recycling Market Report is Segmented by Treatment Technology (Filtration and Ultrafiltration, Reverse Osmosis, Ion Exchange and Water Softening, Electrodeionization, Chemical Treatment and Disinfection, Membrane Bioreactors, and Other Water Treatment Technologies), Water Source (Municipal Water, Groundwater, Surface Water, Reclaimed Municipal Wastewater, Industrial Recycled Water, and Other Alternative Water Sources), Treatment Application (Cooling Tower Makeup Water Treatment, Chilled Water and Closed-Loop Water Treatment, Boiler and Heat Rejection System Water Treatment, Wastewater Treatment, Water Recycling and Reuse, and Zero Liquid Discharge and Concentrate Management), Solution Type (Water Treatment Equipment, Water Treatment Chemicals, Water Quality Monitoring and Control Systems, Treatment Plant Design and Engineering, and Operation and Maintenance Services), Data Center Size (Small, Medium, Large, and Hyperscale), Data Center Type (Colocation, Cloud Service Providers, and Enterprise and Edge), and North America (United States, Canada, and Mexico). The Market Forecasts Are Provided in Terms of Value (USD).
Segmentation Overview
| Filtration and Ultrafiltration |
| Reverse Osmosis |
| Ion Exchange and Water Softening |
| Electrodeionization |
| Chemical Treatment and Disinfection |
| Membrane Bioreactors |
| Other Water Treatment Technologies |
| Municipal Water |
| Groundwater |
| Surface Water |
| Reclaimed Municipal Wastewater |
| Industrial Recycled Water |
| Other Alternative Water Sources |
| Cooling Tower Makeup Water Treatment |
| Chilled Water and Closed-Loop Water Treatment |
| Boiler and Heat Rejection System Water Treatment |
| Wastewater Treatment |
| Water Recycling and Reuse |
| Zero Liquid Discharge and Concentrate Management |
| Water Treatment Equipment |
| Water Treatment Chemicals |
| Water Quality Monitoring and Control Systems |
| Treatment Plant Design and Engineering |
| Operation and Maintenance Services |
| Small |
| Medium |
| Large |
| Hyperscale |
| Colocation |
| Cloud Service Providers |
| Enterprise and Edge |
| United States |
| Canada |
| Mexico |
| By Treatment Technology | Filtration and Ultrafiltration |
| Reverse Osmosis | |
| Ion Exchange and Water Softening | |
| Electrodeionization | |
| Chemical Treatment and Disinfection | |
| Membrane Bioreactors | |
| Other Water Treatment Technologies | |
| By Water Source | Municipal Water |
| Groundwater | |
| Surface Water | |
| Reclaimed Municipal Wastewater | |
| Industrial Recycled Water | |
| Other Alternative Water Sources | |
| By Treatment Application | Cooling Tower Makeup Water Treatment |
| Chilled Water and Closed-Loop Water Treatment | |
| Boiler and Heat Rejection System Water Treatment | |
| Wastewater Treatment | |
| Water Recycling and Reuse | |
| Zero Liquid Discharge and Concentrate Management | |
| By Solution Type | Water Treatment Equipment |
| Water Treatment Chemicals | |
| Water Quality Monitoring and Control Systems | |
| Treatment Plant Design and Engineering | |
| Operation and Maintenance Services | |
| By Data Center Size | Small |
| Medium | |
| Large | |
| Hyperscale | |
| By Data Center Type | Colocation |
| Cloud Service Providers | |
| Enterprise and Edge | |
| By North America | United States |
| Canada | |
| Mexico |
Key Questions Answered in the Report
What is the North America data center water treatment and recycling market size?
The North America data center water treatment and recycling market is valued at USD 1.27 billion in 2026 and is forecast to reach USD 2.31 billion by 2032, at a CAGR of 10.21% over 2027-2032. Water availability, recycled-water access, and more intensive AI cooling requirements support this outlook.
Why are data centers investing in recycled water systems?
Water constraints, permit conditions, and water-use reporting are making recycling important for site selection and expansion. Recycled supply can also reduce the demand for drinking water in locations with suitable municipal infrastructure.
Which data center customer group has the strongest outlook?
Cloud service providers lead with a 50.39% share in 2026 and are projected to expand at a CAGR of 10.96% through 2032. Their campuses commonly require treatment systems designed against formal WUE and water-reuse objectives.
What application is expanding fastest?
ZLD and concentrate management is projected to expand at a CAGR of 10.77% through 2032. The application supports closed-cycle water designs and helps campuses control concentrated waste streams before discharge or reuse.
Which country is expanding fastest in the region?
Canada is projected to expand at a CAGR of 11.14% through 2032. Cold-climate cooling conditions, hyperscale investment, hydropower availability, and the need to reuse licensed water volumes shape its outlook.