
CoaXPress Machine Vision Components Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 0.88 Billion |
| Market Size (2031) | USD 1.37 Billion |
| Growth Rate (2026 - 2031) | 9.26 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | Asia-Pacific |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
CoaXPress Machine Vision Components Market Analysis by Mordor Intelligence
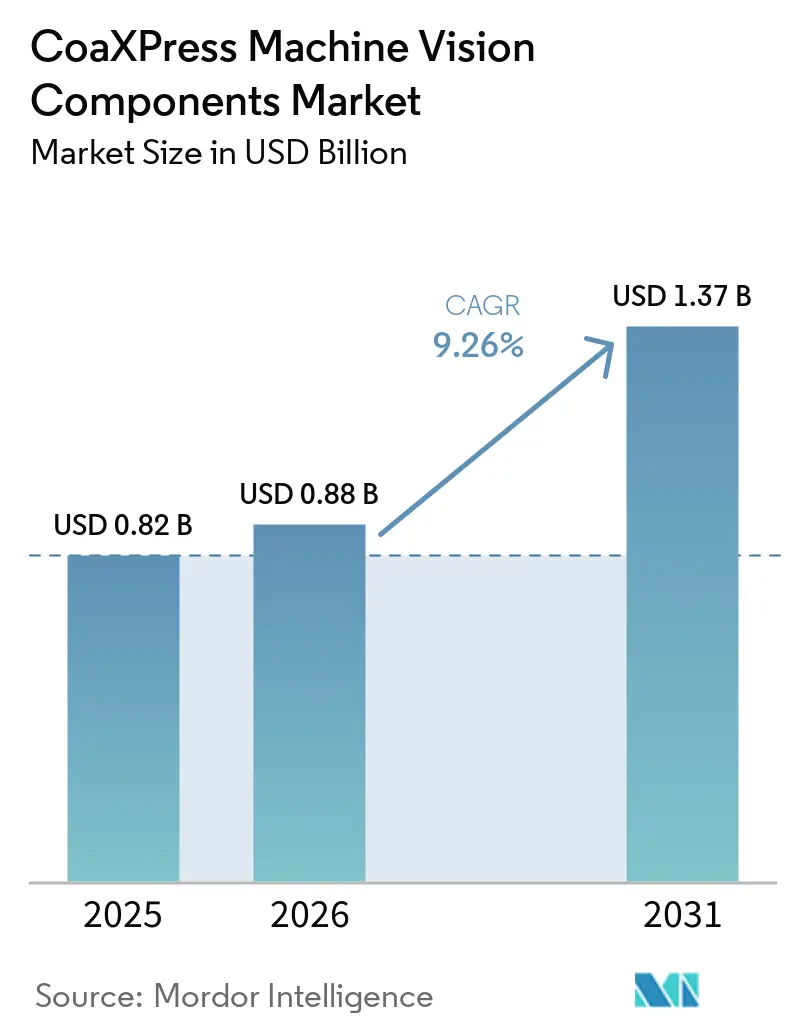
The CoaXPress machine vision components market size is projected to be USD 0.82 billion in 2025, USD 0.88 billion in 2026, and reach USD 1.37 billion by 2031, expanding at a CAGR of 9.26% from 2026 to 2031. Demand centers on inspection tasks that require high bandwidth, stable timing, and reliable image capture. Semiconductor, display, and battery production lines are moving toward continuous inspection rather than selective checks. CoaXPress 2.0 supports 12.5 Gbps per link, power over coax, and low trigger latency, which supports complex camera installations. The CoaXPress machine vision components market also faces pressure from Ethernet interfaces in applications that prioritize shared network access over deterministic timing. The planned CoaXPress v3.0 roadmap points to higher per-link capacity and fiber integration, which may keep the technology relevant in demanding inspection systems.
Key Report Takeaways
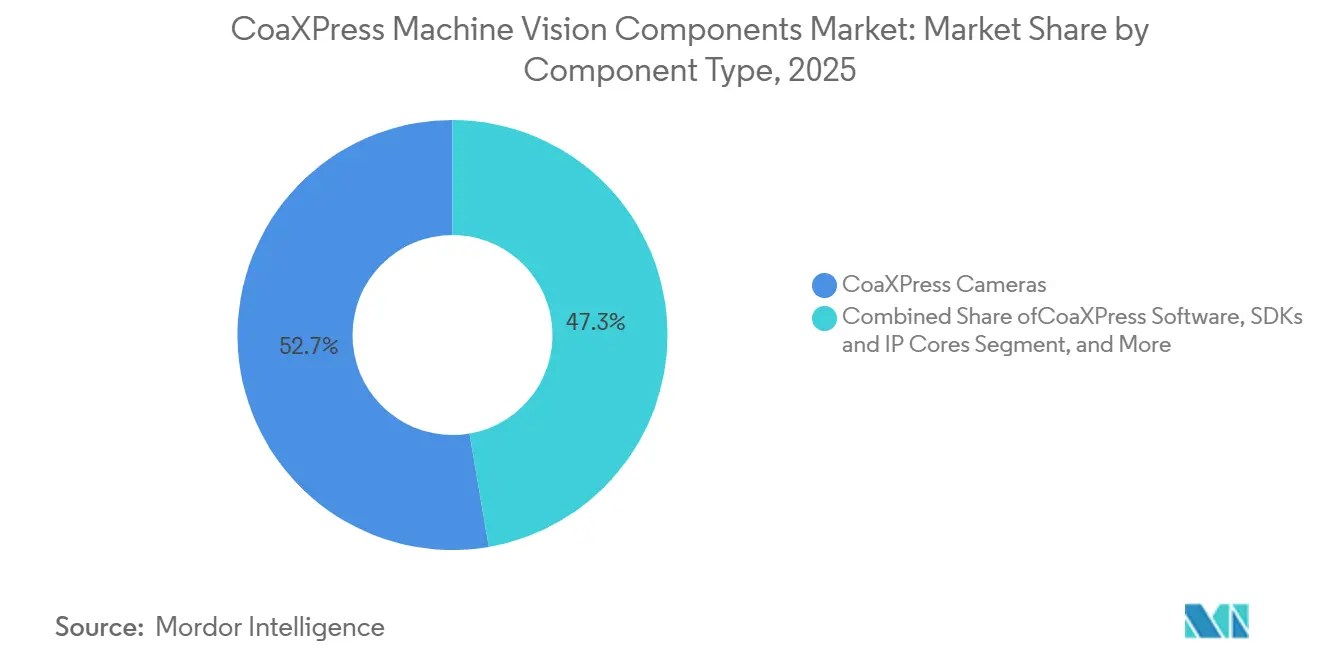
- By component type, cameras held 52.70% of the CoaXPress machine vision components market in 2025, while software, SDKs, and IP cores are projected to expand at an 11.26% CAGR through 2031.
- By camera architecture, area-scan cameras accounted for 61.40% of revenue in 2025, while TDI cameras are projected to grow at an 11.34% CAGR through 2031.
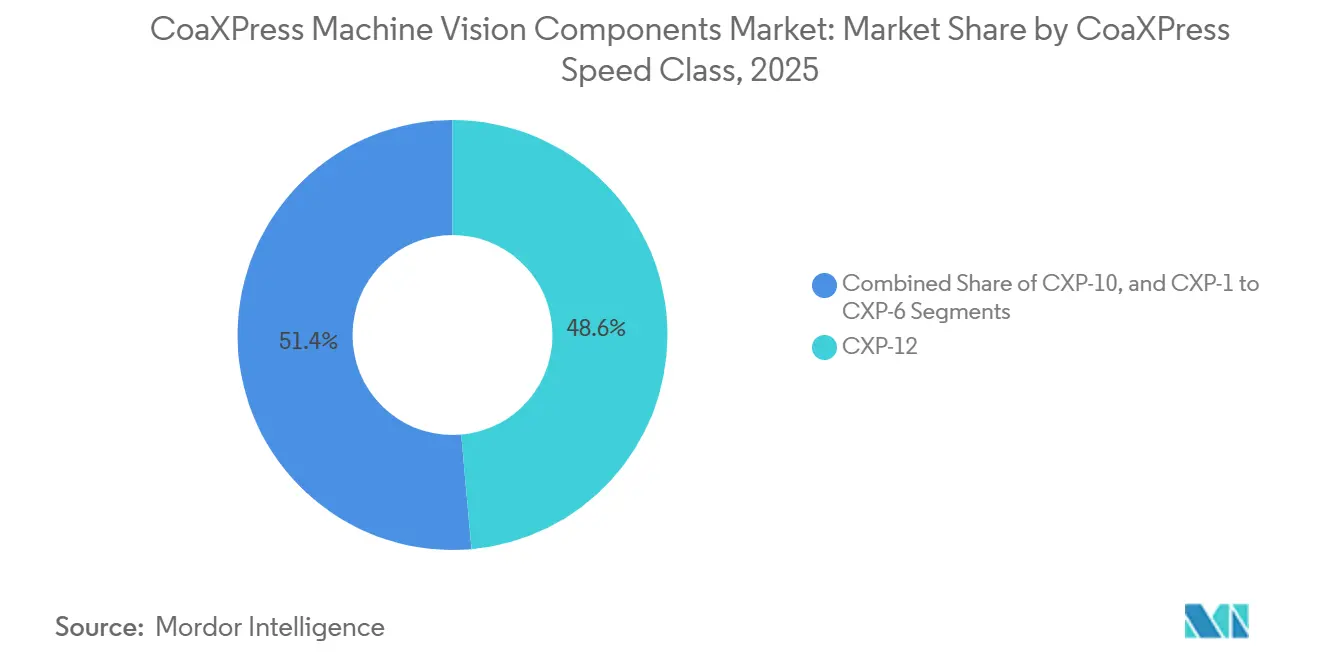
- By CoaXPress speed class, CXP-12 accounted for 48.60% of revenue in 2025 and is projected to grow at a 12.21% CAGR through 2031.
- By end-user industry, electronics and semiconductor manufacturing held 31.80% of revenue in 2025, while automotive and EV manufacturing is projected to expand at a 12.48% CAGR through 2031.
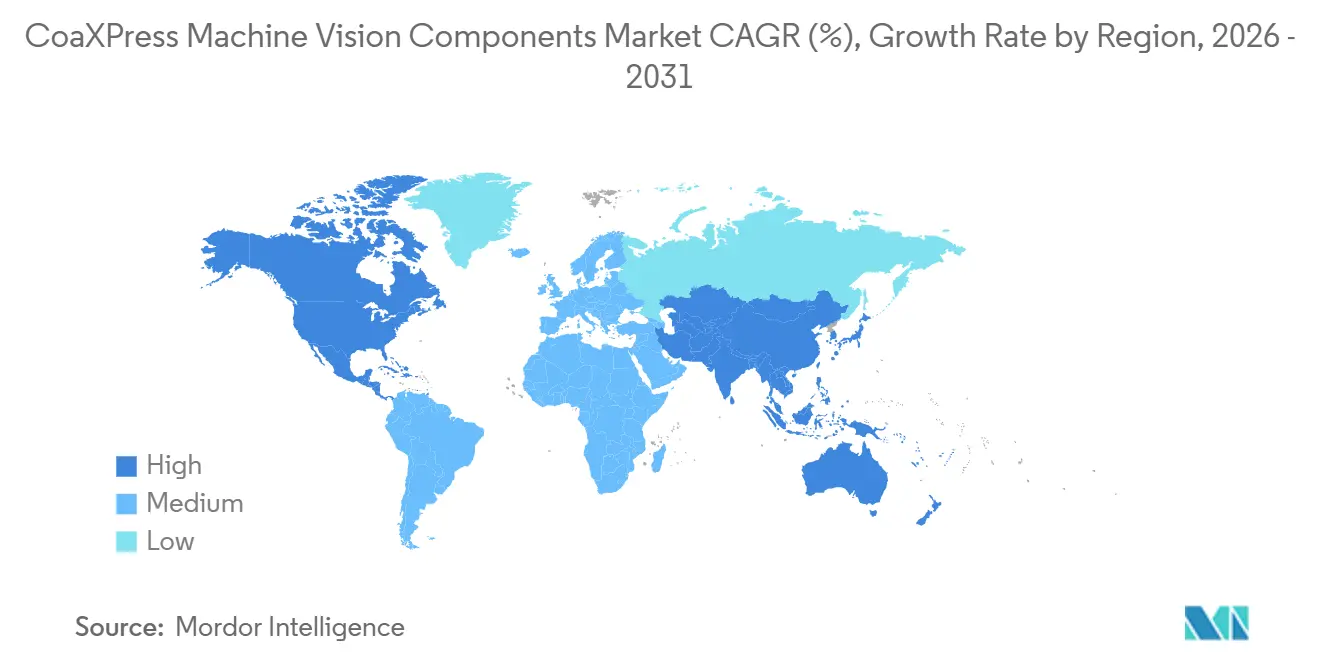
- By geography, Asia-Pacific held 43.70% of the CoaXPress machine vision components market in 2025 and is projected to expand at a 12.02% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of CoaXPress Machine Vision Components Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High-Throughput Semiconductor and Display Inspection | +3.2% | Asia-Pacific core, including Taiwan, South Korea, China, and Japan, with spillover to North America | Long term (≥ 4 years) |
| Factory Automation and Inline Quality Inspection | +2.5% | Global, concentrated in Asia-Pacific and Europe | Medium term (2-4 years) |
| CoaXPress 2.0 and PCIe Bandwidth Expansion | +1.9% | Global, with strongest uptake in North America and Europe | Short term (≤ 2 years) |
| High-Speed Sensor Resolution Escalation | +1.4% | Global, most acute in Asia-Pacific semiconductor and display clusters | Medium term (2-4 years) |
| FPGA and GPU-Direct Data Reduction at the Edge | +0.9% | North America and Europe, emerging in Asia-Pacific | Medium term (2-4 years) |
| CoaXPress-over-Fiber Adoption in EMI-Constrained Installations | +0.6% | Global, including heavy industrial and defense corridors | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
High-Throughput Semiconductor and Display Inspection Underpins Protocol Demand
Semiconductor inspection remains the primary driver of demand in the CoaXPress machine vision components market. High-bandwidth memory, chiplets, and co-packaged optics require full-wafer scans with heavy image data loads. Basler described wafer inspection systems that support 16K resolution and 500 kHz line rates for real-time defect inspection.[1]Basler AG, “Stable Real-Time Wafer Defect Inspection Using High Speed TDI Imaging,” Basler AG These conditions favor multi-link CXP-12 systems, in which compression can compromise inspection quality. TDI cameras and CXP-12-over-Fiber systems also suit the scan speed requirements of advanced foundry lines. Display inspection creates a similar need, as OLED and mini-LED production lines require consistent, high-speed imaging.
Factory Automation and Inline Quality Inspection Widen the End-Market Base
Manufacturers are replacing batch sampling with inspection at each assembly stage, increasing the number of cameras used on a line. BMW used continuous checks for battery weld seams and foaming processes at its Woodruff battery facility. General Motors developed BVSeal to use gas imaging and AI-enabled cobots to identify battery tray leaks. These applications need tightly coordinated image capture before fixtures or robotic tools move. CoaXPress provides a 41.6 Mbps uplink channel that can support trigger rates above 500 kHz. That capability can reduce separate uplink cabling in multi-camera systems and simplify station installation.
CoaXPress 2.0 and PCIe Bandwidth Expansion Raise the Throughput Floor
CXP-12 provides 12.5 Gbps per link, and four links can deliver 50 Gbps to a frame grabber. Active Silicon stated that its PCIe Gen4 products support the transfer requirements of high-speed automated optical inspection.[2]Active Silicon, “CoaXPress Frame Grabbers for High-Speed AOI,” Active Silicon This pairing allows high-resolution sensors to transfer images to host memory with fewer frame losses. Euresys introduced its Coaxlink QSFP28 frame grabber with 100 Gbps throughput over a single QSFP28 port and PCIe 4.0 x8 support. The CoaXPress machine vision components market benefits, as frame grabbers offer more capacity from a single slot. It also raises the performance threshold that Ethernet alternatives must meet in deterministic inspection environments.[3]Euresys SA, “New CoaXPress-over-Fiber Frame Grabber, Coaxlink QSFP28,” Euresys SA
High-Speed Sensor Resolution Escalation Accelerates Bandwidth Demand
High-resolution sensors are increasing the volume of data that must move from the camera to the processing system. KAYA Vision noted that a 105 MP sensor operating at 100 frames per second generates 10.5 GB/s of raw Bayer data.[4] KAYA Vision, “Megapixel Vision Bottlenecks Solved,” KAYA Vision Allied Vision introduced FXO CXP-12 cameras with Sony Pregius S sensors, 24.6 MP resolution, and a 50 x 50 mm form factor in May 2026. Smaller pixels can support dense camera heads in space-constrained cleanrooms. Better low-light performance can also reduce lighting demand at inspection stations. These technical changes support wider use of CoaXPress machine vision components in 3D measurement and high-speed production control.
Restraints Impact Analysis of CoaXPress Machine Vision Components Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Upfront Cost of CoaXPress Frame Grabber Systems | -1.8% | Global, most pronounced in South America, Africa, and Southeast Asia | Long term (≥ 4 years) |
| Competition From 10GigE and Emerging Ethernet-Based Interfaces | -0.8% | Global, stronger in North America and Europe for mid-throughput applications | Medium term (2-4 years) |
| Shortage of CoaXPress Integration and FPGA Engineering Skills | -0.5% | Global, acute in South Asia, Southeast Asia, and South America | Long term (≥ 4 years) |
| Power Delivery and Thermal Constraints in Dense Multi-Link Systems | -0.3% | Global, most relevant in Asia-Pacific high-density semiconductor fabs | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
High Upfront Cost of CoaXPress Frame Grabber Systems Limits Adoption
Four-link CXP-12 frame grabbers with PCIe Gen4 support cost more than USD 3,000 per card. KAYA Vision reported that this is 3 times the cost of comparable GigE Vision frame grabbers. The initial cost can lead integrators in South and Southeast Asia to select GigE Vision systems despite lower performance. Savings from fewer missed frames and fewer reinspection cycles may sit outside the hardware purchasing budget. Basler introduced its imaFlex 2 Dual 100 system in April 2026, featuring FPGA preprocessing that can reduce downstream GPU, CPU, and frame-grabber requirements by 20-50%. However, the approach still requires investment in VisualApplets programming capability.
Competition From 10GigE and Ethernet-Based Interfaces Pressures Mid-Range Tiers
10GigE Vision platforms compete on lower hardware costs and the use of familiar Ethernet infrastructure. They can be useful when several analytical systems need access to the same camera stream. Emergent Vision Technologies outlined the use of RDMA and GPU-direct technology across 10GigE, 25GigE, and 100GigE vision platforms. CoaXPress retains an advantage when systems require deterministic trigger timing and high reliability across multiple cameras. Ethernet systems can also require costly hardware offload to limit CPU load and dropped frames at higher data rates. The CoaXPress machine vision components market, therefore, remains most exposed in mid-throughput applications where timing requirements are less strict.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
CoaXPress Machine Vision Components Market Segment Analysis
By Component Type:
Software and IP Cores Lead Revenue Growth Beyond HardwareCameras held 52.70% of the CoaXPress machine vision components market share in 2025. The replacement of aging Camera Link designs and the adoption of backside-illuminated global-shutter sensors supported this position. Frame grabbers and interface cards constitute the second-largest component category, with PCIe Gen4 boards increasingly incorporating FPGA preprocessing and GPU-direct DMA. Cables, connectors, and cable assemblies remain necessary with every camera installation. The JIIA CXP-001-2021 standard covers compliant CoaXPress equipment, including cable-related requirements.
Software, SDKs, and IP cores are projected to expand at an 11.26% CAGR through 2031. This CoaXPress machine vision components market segment benefits when equipment builders use FPGA IP rather than developing protocol functions in-house. Silicon Software VisualApplets and Microchip PolarFire IP support this process, while repeaters and signal-conditioning products gain relevance as fiber bridge modules extend installed CXP-12 camera fleets. KAYA Instruments offers a dual-signal converter that supports transmission over single-mode fiber beyond 80 km. Software revenue can scale across systems built on the same design, unlike camera revenue, which depends on unit shipments.


By Camera Architecture:
TDI Technology Redefines High-Speed Inspection StandardsArea-scan cameras held 61.40% of 2025 revenue by camera architecture. They support electronics assembly verification, metrology, automotive body inspection, and healthcare imaging. New 24 MP to 127 MP sensors are accelerating the move from CXP-6 to CXP-12 connections. Line-scan cameras remain important where material moves continuously through an inspection station, including web inspection and printed circuit board manufacturing. CXP-12 provides added bandwidth and longer cable reach for these applications.
TDI cameras are projected to expand at an 11.34% CAGR through 2031. This segment of the CoaXPress machine vision components market supports wafer and advanced-packaging inspection, where sensitivity is critical. Tucsen launched the Gemini 8KTDI in March 2025 with a 100G CoaXPress-over-Fiber interface, 94.2% peak quantum efficiency, and a 1 MHz line rate. Teledyne DALSA released the Linea HS2 8k TDI camera in June 2026 with a configurable TDI stage count that balances line rate, dynamic range, and full-well capacity. Vieworks also showed its VT-16K Hybrid TDI camera with a CoaXPress 8-channel interface at Automation World 2026.
By CoaXPress Speed Class:
CXP-12 Dominates Bandwidth-Intensive ApplicationsCXP-12 held 48.60% of revenue in 2025 and is projected to expand at a 12.21% CAGR through 2031. Its installed base and its forecast rate both reflect migration from slower connections. CXP-1 through CXP-6 retain roles in dimensional gauging, barcode reading, and low-resolution inspection. CXP-10 offers a middle option for cameras that exceed CXP-6 capacity but do not need a full CXP-12 deployment. This allows some users to manage infrastructure costs while increasing data capacity.
The widening CXP-12 installed base encourages more board and IP suppliers to support the platform. BitFlow brought its Claxon CXP-12 lineup into full production in June 2026, with configurations from single-link to quad-link and a fiber option. The products were validated with NVIDIA Jetson AGX Orin and TensorRT inference pipelines, making AI processing a more routine part of the acquisition workflow. Chinese supply chains are also broadening access to CXP-12 frame grabbers for semiconductor and electronics inspection. CXP-12's revenue position reflects the platform's ability to serve these bandwidth-intensive workloads.
By End-User Industry:
Automotive and EV Manufacturing Accelerates Market ExpansionElectronics and semiconductor manufacturing held 31.80% of end-user revenue in 2025. The sector remains the main reference application for CXP-12 cameras, TDI architectures, and fiber connections. Aerospace and defense sectors demand long-range imaging for surveillance and tracking in electromagnetically challenging environments. Healthcare and life sciences use high-resolution TDI cameras for genomic sequencing and for scanning pathology slides. General manufacturing uses the technology for automotive stamping, metal surfaces, and packaging verification, while research institutions apply it to particle image velocimetry, fluid dynamics, and materials characterization.
Automotive and EV manufacturing is projected to expand at a 12.48% CAGR through 2031. The CoaXPress machine vision components market gains from battery plants that need continuous checks of cells, welds, joints, and seals. Atlas Copco described VisionTools applications that verify joining, sealing, and assembly at battery production stations. Hanul Semiconductor reported an AI-enabled MLCC inspection system that handled 13,000 units per minute with 98% accuracy in September 2026. Such operating speeds extend high-speed imaging beyond wafer inspection and reinforce the value of synchronized image capture in high-volume production.
Geography Analysis
APAC CoaXPress Machine Vision Components Market
Asia-Pacific held 43.70% of the CoaXPress machine vision components market share in 2025 and is projected to expand at a 12.02% CAGR through 2031. Semiconductor foundries, display plants, and EV battery factories are concentrated across the region. Taiwan and South Korea support advanced logic production, while China is expanding domestic foundry capacity and its local CoaXPress supplier base. BOPIXEL launched a 100 Gbps CoaXPress-over-Fiber camera series in July 2026 for semiconductor and packaging inspection. Tucsen also presented the Libra 27105 in Wuxi in August 2026, demonstrating the depth of its regional product development.
APAC and North America CoaXPress Machine Vision Components Market
Japan retains a central role through JIIA standards work and compliance tooling, while South Korea is building capability in higher-end TDI systems, as shown by Vieworks at Automation World 2026. India is an emerging source of demand as investments in semiconductor and EV manufacturing increase. Basler acquired a 76% stake in Alpha TechSys Automation India in October 2025, adding local systems integration and after-sales support. North America is the second-largest regional market, supported by aerospace, defense, semiconductor construction, and machine vision software development, while major fabs remain in installation phases and deployment is expected to strengthen in 2027 and 2028.
EMEA and South America CoaXPress Machine Vision Components Market
Europe benefits from automotive production, EV battery inspection, and machine vision software expertise, with Germany, Belgium, and the United Kingdom remaining important locations for system developers and suppliers. Allied Vision's FXO CXP-12 cameras were positioned for cleanroom semiconductor and electronics work in Germany. South America, the Middle East, and Africa have smaller revenue bases and are served mainly through distributors. Brazil and Argentina are active in automotive and domestic electronics production, while the United Arab Emirates, Saudi Arabia, and South Africa offer selective demand in industrial automation, defense imaging, and automotive supply chains. Higher upfront costs limit the CoaXPress machine vision components market to applications where its performance benefit is commercially justified.

Competitive Landscape
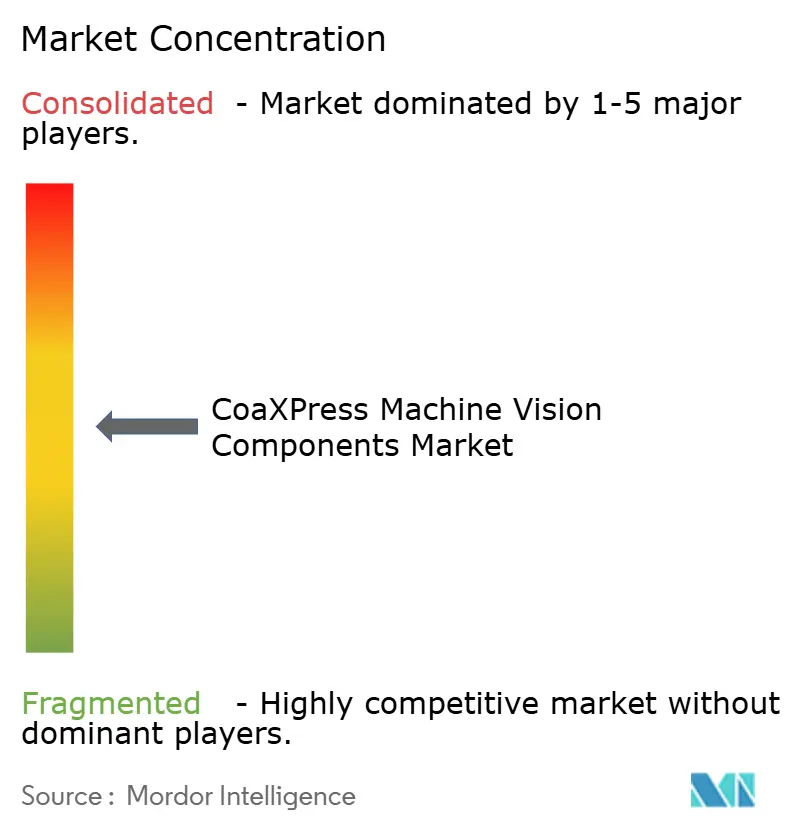
The CoaXPress machine vision components market is moderately fragmented. Competition centers on FPGA firmware, link count, GPU-direct DMA, and dependable synchronization across several cameras. Large suppliers are building broader portfolios that combine cameras, frame grabbers, software, and system support. Allied Vision brought SVS-Vistek, Chromasens, Mikrotron, and NET under its brand in January 2026, while Euresys remained part of the TKH Vision Group. This gave the group a broader combined machine vision offering and made it easier for customers to source additional system elements from a single supplier.
Basler has added capabilities in FPGA software, 3D vision, and Indian systems integration. Its April 2026 CoaXPress-over-Fiber TDI system combined a Racer 2 XL camera, imaFlex 2 Dual 100 frame grabber, VisualApplets software, and QSFP28 modules. On-card preprocessing reduces downstream GPU, CPU, and frame-grabber hardware requirements by 20-50%. Teledyne DALSA strengthened its position through the 2024 acquisition of Adimec and its current camera and frame-grabber portfolio. The Linea HS2 TDI camera and Xtium3 frame grabber represent a high-throughput product pairing, showing that suppliers are trying to control more of the acquisition chain. The CoaXPress machine vision components market is becoming harder for smaller camera-only suppliers to address without partners.
Gidel and KAYA Instruments compete through specialized FPGA and connectivity products. Gidel's Proc1C10N-CXP12 octo frame grabber provides 143 INT8 TOPS of inference capacity from an Altera Stratix 10 NX FPGA. Euresys uses its Coaxlink QSFP28 product to provide 100 Gbps connectivity through QSFP28 and PCIe 4.0, while BitFlow has added validated NVIDIA Jetson integration to its CXP-12 products. JIIA conformance certification also raises qualification requirements for suppliers serving Japanese and Korean equipment customers. This gives established vendors an advantage in contracts that require proven interoperability.
CoaXPress Machine Vision Components Industry Leaders
Euresys SA
Teledyne DALSA, Inc.
Basler AG
Allied Vision Technologies GmbH
JAI A/S
- *Disclaimer: Major Players sorted in no particular order
CoaXPress Machine Vision Components Market Companies Covered in this Report
- Adimec Advanced Image Systems B.V.
- Active Silicon Ltd
- Allied Vision Technologies GmbH
- Basler AG
- BitFlow, Inc.
- Euresys SA
- Gidel Ltd
- Imperx, Inc.
- JAI A/S
- KAYA Instruments Ltd
- Matrox Electronic Systems Ltd.
- Optronis GmbH
- Pleora Technologies Inc.
- Raptor Photonics Limited
- Silicon Software GmbH
- SVS-Vistek GmbH
- Teledyne DALSA, Inc.
- Emergent Vision Technologies Inc.
- Photron Limited
- IDS Imaging Development Systems GmbH

Recent Industry Developments in CoaXPress Machine Vision Components Market
- August 2026: Tucsen Photonics (鑫图光电) officially launched the Libra 27105, a 100G high-throughput area scan camera, at the CSEAC 2026 semiconductor equipment exhibition in Wuxi, China. The product is designed for advanced semiconductor packaging inspection, including front-end wafer screening and back-end 3D metrology, expanding Tucsen's CoaXPress-over-Fiber imaging portfolio.
- July 2026: BOPIXEL launched a full 100 Gbps CoaXPress-over-Fiber camera series covering 12 MP to 105 MP resolutions on a unified 100G QSFP28 fiber platform, targeting advanced semiconductor manufacturing and packaging inspection. This release positions BOPIXEL as one of the first Chinese manufacturers to offer a production-ready CoF camera matrix at scale.
- June 2026: BitFlow, a division of Advantech, announced full production availability of its Claxon CXP-12 frame grabber lineup, spanning single-link to quad-link configurations plus a CoaXPress-over-Fiber variant, validated on NVIDIA Jetson AGX Orin with TensorRT inference, enabling real-time AI inspection with minimal CPU overhead.
- June 2026: Teledyne DALSA released the Linea HS2 8k backside-illuminated TDI camera, achieving a 1 MHz maximum line rate at 8k resolution for semiconductor wafer and genomics flow-cell inspection. The camera joins existing 16k models in the Linea HS2 family and uses Camera Link HS CX4 Active Optical Cable connectors for complete EMI immunity.


Global CoaXPress Machine Vision Components Market Report Scope
CoaXPress Machine Vision Components refer to the specialized hardware and software ecosystem built around the CoaXPress interface standard, enabling high-speed, low-latency transmission of video data and power over coaxial cables for demanding industrial imaging applications that require high resolution and high frame rates.
The CoaXPress Machine Vision Components Market Report is Segmented by Component Type (CoaXPress Cameras, CoaXPress Frame Grabbers and Interface Cards, CoaXPress Cables, Connectors and Cable Assemblies, CoaXPress Repeaters, Signal-Conditioning and Connectivity Components, and CoaXPress Software, SDKs and IP Cores), Camera Architecture (Area-Scan Cameras, Line-Scan Cameras, and TDI Cameras), CoaXPress Speed Class (CXP-1 to CXP-6, CXP-10, and CXP-12), End-User Industry (Electronics and Semiconductor Manufacturing, Automotive and EV Manufacturing, Aerospace and Defense, Healthcare and Life Sciences, General Manufacturing and Machine Builders, Research Institutes and Universities, and Consumer Electronics OEMs), and Geography (North America, South America, Europe, Asia-Pacific, Middle East, Africa). The Market Forecasts are Provided in Terms of Value (USD).
| CoaXPress Cameras |
| CoaXPress Frame Grabbers and Interface Cards |
| CoaXPress Cables, Connectors and Cable Assemblies |
| CoaXPress Repeaters, Signal-Conditioning and Connectivity Components |
| CoaXPress Software, SDKs and IP Cores |
| Area-Scan Cameras |
| Line-Scan Cameras |
| TDI Cameras |
| CXP-1 to CXP-6 |
| CXP-10 |
| CXP-12 |
| Electronics and Semiconductor Manufacturing |
| Automotive and EV Manufacturing |
| Aerospace and Defense |
| Healthcare and Life Sciences |
| General Manufacturing and Machine Builders |
| Research Institutes and Universities |
| Consumer Electronics OEMs |
| North America | United States |
| Canada | |
| Mexico | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Spain | |
| Rest of Europe | |
| Asia-Pacific | China |
| Japan | |
| India | |
| South Korea | |
| Australia | |
| Rest of Asia-Pacific | |
| Middle East | United Arab Emirates |
| Saudi Arabia | |
| Rest of Middle East | |
| Africa | South Africa |
| Rest of Africa |
| By Component Type | CoaXPress Cameras | |
| CoaXPress Frame Grabbers and Interface Cards | ||
| CoaXPress Cables, Connectors and Cable Assemblies | ||
| CoaXPress Repeaters, Signal-Conditioning and Connectivity Components | ||
| CoaXPress Software, SDKs and IP Cores | ||
| By Camera Architecture | Area-Scan Cameras | |
| Line-Scan Cameras | ||
| TDI Cameras | ||
| By CoaXPress Speed Class | CXP-1 to CXP-6 | |
| CXP-10 | ||
| CXP-12 | ||
| By End-User Industry | Electronics and Semiconductor Manufacturing | |
| Automotive and EV Manufacturing | ||
| Aerospace and Defense | ||
| Healthcare and Life Sciences | ||
| General Manufacturing and Machine Builders | ||
| Research Institutes and Universities | ||
| Consumer Electronics OEMs | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Spain | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| Japan | ||
| India | ||
| South Korea | ||
| Australia | ||
| Rest of Asia-Pacific | ||
| Middle East | United Arab Emirates | |
| Saudi Arabia | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Rest of Africa | ||


Key Questions Answered in the Report
What is the Structured Light Projector Market size?
The Structured Light Projector Market size was USD 0.96 billion in 2026 and is forecast to reach USD 1.53 billion by 2031 at a 9.77% CAGR.
What is driving demand for structured light projectors?
Factory automation, robotic bin picking, face authentication, EV battery inspection, and semiconductor metrology are supporting demand.
Which projector architecture leads revenue?
Embedded projector modules held 40.27% revenue share in 2025 and are projected to expand at an 11.73% CAGR through 2031.
Which region leads Structured Light Projector Adoption?
Asia-Pacific held 39.27% revenue share in 2025 and is projected to expand at an 11.47% CAGR through 2031.
Why are VCSEL-based projectors gaining traction?
VCSEL systems are projected to expand at a 12.27% CAGR because array designs can provide higher optical power with controlled thermal performance.
What limits deployment in industrial settings?
Thermal calibration drift, difficult reflective or transparent surfaces, laser-safety compliance, and limited integration talent can slow deployment.
Page last updated on:





