
Alpha Olefin Sulfonate (AOS) Market Size and Share
Market Overview
| Study Period | 2022 - 2032 |
|---|---|
| Market Size (2027) | USD 0.79 Billion |
| Market Size (2032) | USD 1.04 Billion |
| Growth Rate (2027 - 2032) | 5.44 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | Asia-Pacific |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Alpha Olefin Sulfonate (AOS) Market Analysis by Mordor Intelligence
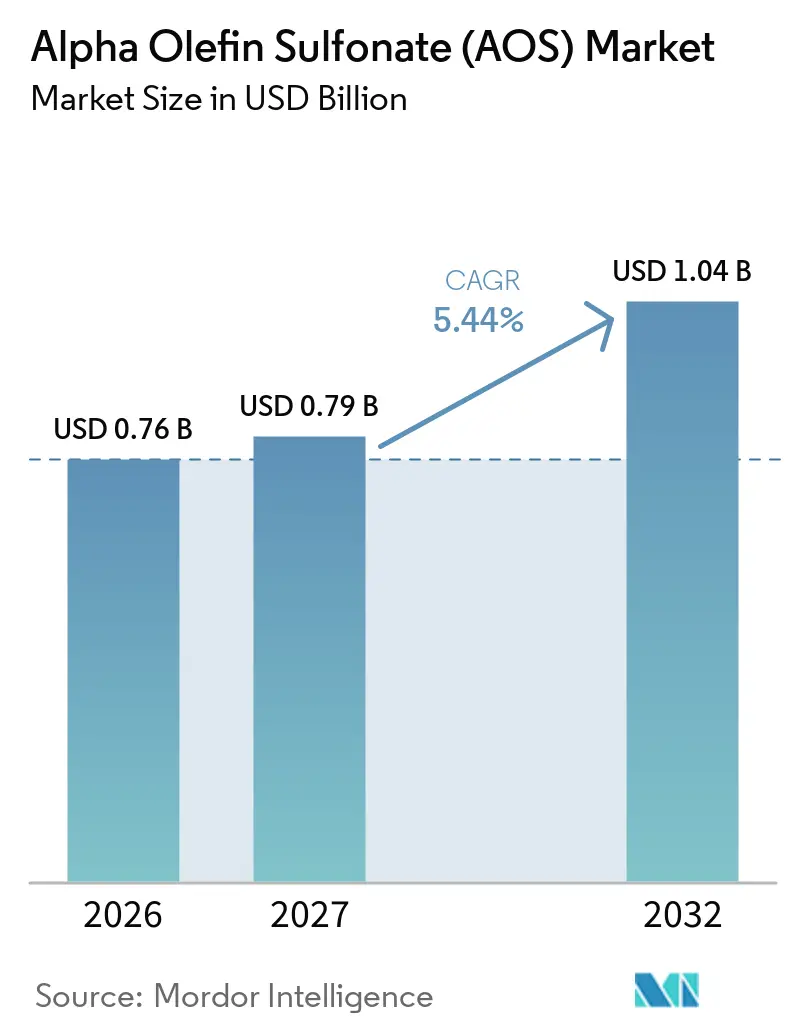
The Alpha Olefin Sulfonate (AOS) market size was valued at USD 0.76 billion in 2026 and is estimated to grow from USD 0.79 billion in 2027 to USD 1.04 billion by 2032, at a CAGR of 5.44% during the forecast period (2027-2032). AOS combines high foaming efficiency, skin compatibility, and aerobic biodegradability, a combination that competing anionic surfactants rarely replicate at equivalent cost. Consumer and retailer pressure to eliminate 1,4-dioxane contamination, a byproduct associated with ethoxylated sulfates, has accelerated formulators' transition to AOS, particularly across North America and Europe. Innospec's 2025 launch of NANSA LSS 70, a 70%-active AOS solution designed as a direct high-concentration alternative to sodium laureth sulfate (SLES), illustrates how producers addressed the performance gap that had delayed broader substitution in premium laundry and personal care systems.
Key Report Takeaways
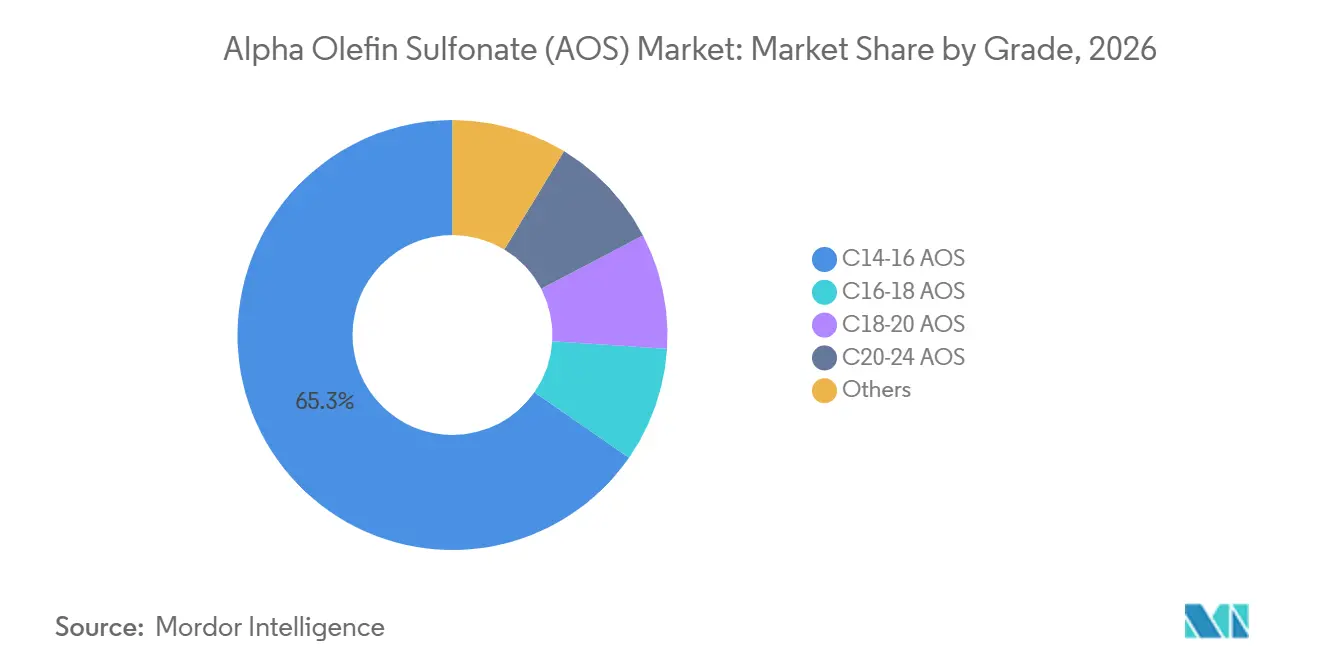
- By grade, C14-16 AOS held 65.32% market share in 2026 and is projected to expand at a 6.12% CAGR through 2032.
- By form, liquid AOS accounted for 39.18% of market share in 2026 and is forecast to grow at a 5.93% CAGR through 2032.
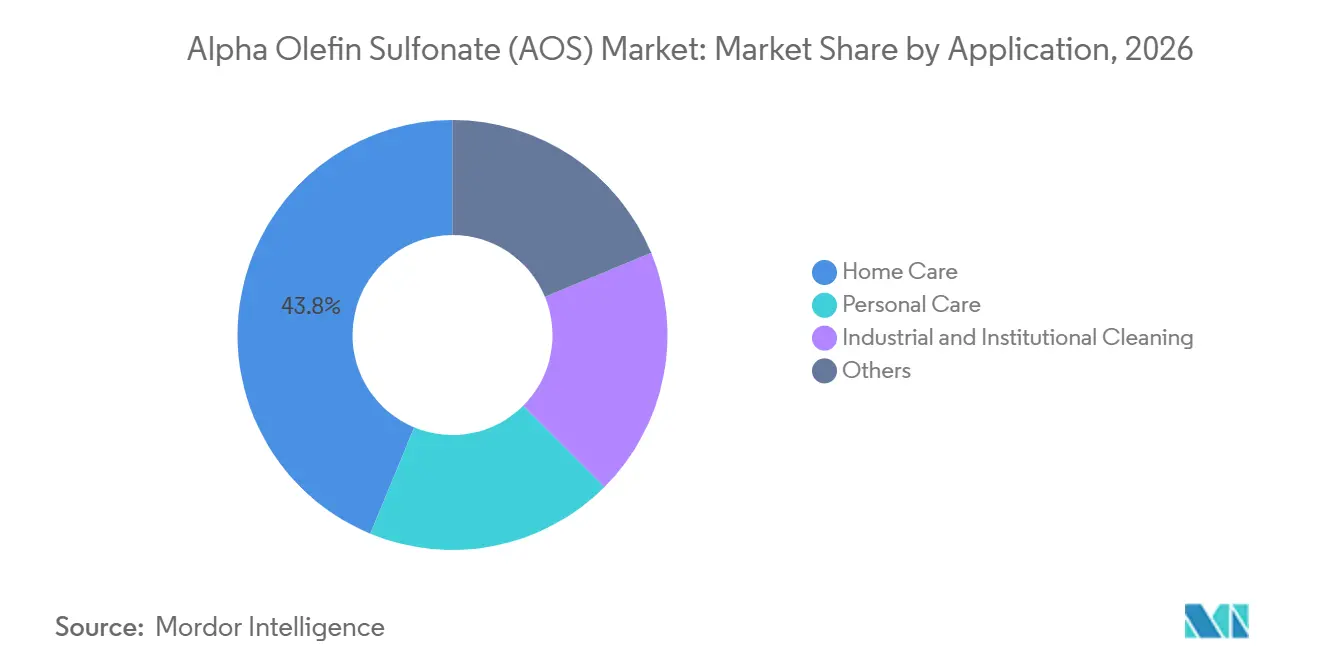
- By application, home care held 43.75% of the market share in 2026, while personal care is forecast to grow at a 6.67% CAGR through 2032.
- By geography, Asia-Pacific accounted for 41.51% of market share in 2026 and is forecast to grow at a 6.28% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Alpha Olefin Sulfonate (AOS) Market*
| Drivers | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Growth in Sulfate-Free and Mild Cleansing Formulations | +1.8% | Global, acute in North America, Europe, and South Korea | Short term (≤ 2 years) |
| Expansion of Household and Institutional Hygiene Products | +1.5% | APAC core, spillover to MEA and South America | Medium term (2-4 years) |
| Biodegradability-Led Ingredient Qualification | +1.0% | Europe, North America, and APAC | Medium term (2-4 years) |
| Growth of Concentrated and Waterless Product Formats | +0.8% | North America and Europe, with early adoption gains in APAC | Short term (≤ 2 years) |
| Bio-Based Alpha-Olefin Feedstock Commercialization | +0.6% | North America, scaling to Europe and APAC | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Growth in Sulfate-Free and Mild Cleansing Formulations
The shift toward sulfate-free cleansing products supports the use of AOS in personal care and household formulations. Product developers require surfactants that deliver cleaning and foaming performance without relying on conventional ethoxylated sulfate systems. AOS is used where hard-water tolerance and cold-water performance are important, particularly in rinse-off applications. AOS is a suitable option for concentrated formulations because it can meet these requirements at high active concentrations. Innospec introduced NANSA LSS 70 as a 70%-active AOS solution for super-concentrated detergent systems. This product development illustrates how suppliers are adapting AOS offerings to the requirements of sulfate-free and concentrated product lines.
Expansion of Household and Institutional Hygiene Products
Household, industrial, and institutional cleaning applications create recurring demand for AOS-containing products. Hospitals, food processing facilities, and commercial kitchens require frequent cleaning, which supports the use of performance surfactants in industrial and institutional formulations. Demand from these channels is considered less tied to consumer sentiment than household retail demand. Demand from Southeast Asia and the Gulf is also linked to regional private-label producers that require reliable technical-grade inputs. The Alpha Olefin Sulfonate (AOS) market benefits when regional manufacturers supply consistent grades and meet delivery requirements. This creates an opportunity for suppliers capable of serving local formulations without compromising quality or supply continuity.
Biodegradability-Led Ingredient Qualification
Biodegradability documentation is becoming more important in surfactant selection, especially for suppliers serving regulated product categories. C14-16 AOS has a recognized aerobic biodegradability profile and has been used across detergent and personal care formulations. This existing record can support qualification processes when customers request ingredient, safety, and supply chain documentation. Larger suppliers may have an advantage because they can provide customers with established product dossiers and technical records. The Alpha Olefin Sulfonate (AOS) market can therefore compete on documentation quality, cost, and physical performance. These requirements may raise barriers for smaller exporters with limited regulatory resources.
Growth of Concentrated and Waterless Product Formats
Concentrated and waterless cleaning formats are increasing the need for surfactants that remain workable at high active concentrations. Laundry sheets, dissolving pods, refill sachets, and powder-to-liquid formats require rapid dissolution and effective cleaning at lower dosage levels. AOS is relevant to these products because liquid grades can be formulated at 35%-70% active concentration. Innospec reports that NANSA LSS 70 remains flowable above 55°C and was designed for highly concentrated formulations. Such grades can reduce water content and transportation weight while preserving pumpability. The shift toward these formats favors producers that can offer high-active grades rather than only standard-strength material.
Restraints Impact Analysis of Alpha Olefin Sulfonate (AOS) Market*
| Restraints | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Linear Alpha-Olefin Feedstock Price Volatility | -0.8% | Global, acute in naphtha-dependent regions, including Europe and Northeast Asia | Short term (≤ 2 years) |
| Competition from Alternative Anionic and Mild Surfactants | -0.6% | Global, most acute in premium personal care in North America, Europe, and South Korea | Medium term (2-4 years) |
| Impurity, Biodegradability, and Regional Compliance Costs | -0.4% | Europe, North America, and increasingly APAC | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Linear Alpha-Olefin Feedstock Price Volatility
AOS production depends on linear alpha-olefin (LAO) feedstocks, linking its cost base to ethylene availability and crude oil conditions. LAO pricing varied in 2025 due to differences in naphtha cracker operations and logistics across Northeast Asia. This variability makes cost management difficult for producers without an integrated feedstock supply or long-term purchasing arrangements. The impact is most significant when feedstock costs change faster than AOS contracts can be revised. In such cases, producers may absorb higher input costs before passing them on to formulators. The Alpha Olefin Sulfonate (AOS) market remains exposed to this margin pressure in naphtha-dependent regions.
Competition from Alternative Anionic and Mild Surfactants
Amino acid-derived surfactants and fermentation-based biosurfactants compete with AOS in the premium personal care market. Sodium cocoyl glycinate, sodium lauroyl sarcosinate, and sophorolipids gained attention in hair care and facial cleansing products in 2025. These alternatives appeal to brands seeking mildness and environmental positioning. In 2025, Godrej Chemicals introduced its SLNOVA biosurfactant platform for personal care, home care, and industrial cleaning applications. Improvements in fermentation scale can narrow the cost gap for premium natural formulations. This competitive pressure is most pronounced in markets where consumer interest in ingredient transparency supports higher formulation costs.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Alpha Olefin Sulfonate (AOS) Market Segment Analysis
By Grade:
C14-16 AOS Leads Across Major Performance RequirementsC14-16 AOS held 65.32% of the global AOS market share in 2026 and is the fastest-growing grade, at a 6.12% CAGR through 2032. Its position reflects its use in both dilute liquid products and highly active concentrated formats. The grade has an established dermatological record that supports its use in infant care, sensitive-skin products, and rinse-off personal care. Its suitability across household and personal care applications gives formulators a flexible surfactant option. The C14-16 AOS market size is further supported by its ability to deliver foam and cleaning performance across varying water conditions.
Capacity expansion plans have focused on the chain lengths most commonly requested by formulators. Stepan announced a 25% annual expansion in AOS capacity across its sites in Illinois, California, and Georgia in 2025. Pilot Chemical also announced plans to significantly expand anionic surfactant capacity at its Middletown, Ohio, facility[1]. C16-18 AOS remains relevant for formulations that benefit from thickening and skin-conditioning properties. C18-20 AOS serves narrower oilfield and high-temperature industrial cleaning applications, while longer-chain grades remain limited by feedstock availability and are more specialized.

By Form:
Liquid AOS Benefits from High-Active Product DevelopmentLiquid AOS accounted for 39.18% of the global AOS market share in 2026 and is forecast to grow at a 5.93% CAGR through 2032. Aqueous liquid grades integrate readily into continuous detergent and personal care production lines. Standard liquid material with an active concentration of 38% to 40% is widely used where dosing precision and product homogeneity are important. Liquid AOS is also used in household and institutional cleaning products that require reliable handling during production. Higher-activity grades are extending this form for applications requiring lower water content. Paste form remains relevant in solid-bar applications such as soap bars and syndet bases, and in markets where cold-chain costs make liquid transport economically infeasible. This positions past-grade AOS as a structurally stable segment in South Asia and Sub-Saharan Africa, rather than a growth category.
Powder and needle grades serve specific markets in powder detergent production and bulk chemical trading, particularly in South and Southeast Asia, but face pressure from displacement as liquid concentrate formats gain retail and institutional share globally. Innospec's development of NANSA LSS 70, a 70%-active liquid AOS solution that remains flowable at temperatures above 55°C, represents a notable advance in product engineering. It enables formulators to reduce transportation quantities and lower water content in finished products without compromising pumpability in ambient-temperature climates, a combination previously achievable only with paste-form AOS (HPC Today, 2025).
By Application:
Personal Care Has the Highest Growth OutlookHome care captured 43.75% of the global AOS market share in 2026, while personal care is projected to grow at a 6.67% CAGR through 2032. Home care demand is centered on liquid dishwashing products, laundry detergents, and multipurpose cleaners, which represent the largest consumption base for AOS. Personal care growth is linked to higher demand for differentiated hair care, skin care, baby care, and sensitive-skin products. The AOS market serves applications where formulators require foam performance alongside a milder product profile.
South Korea and Japan are important personal care markets for C14-16 AOS, which is used in formulations that emphasize sensitivity-skin suitability and performance in hard water. Industrial and institutional cleaning is another growth channel, as hygiene requirements drive demand for technical-grade surfactants. Premium pricing is more acceptable in these applications when specific product requirements must be met. BASF supplied biomass-balanced dimethylaminopropylamine (DMAPA) to Galaxy Surfactants in Asia-Pacific in September 2025, highlighting the growing relevance of sustainability documentation in surfactant supply relationships. AOS suppliers with comparable supply chain and documentation standards are better positioned to participate in this market.
Geography Analysis
APAC Alpha Olefin Sulfonate (AOS) Market
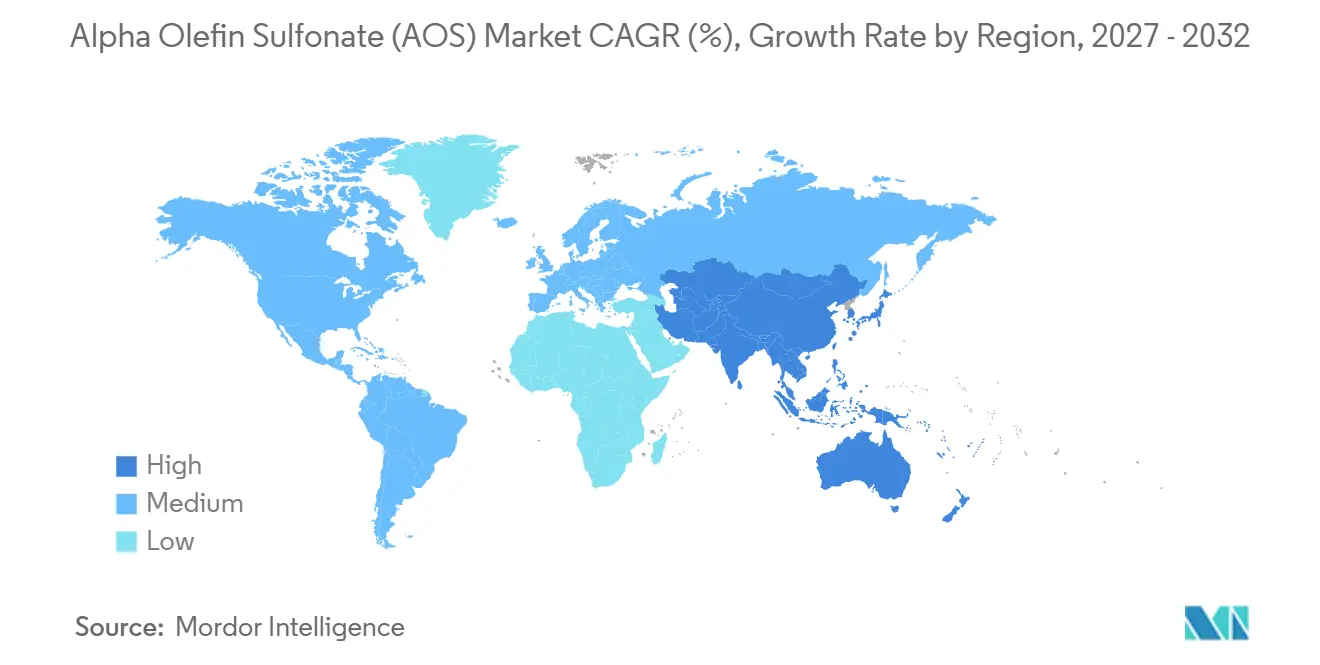
Asia-Pacific accounted for 41.51% of the global AOS market share in 2026 and is projected to register the fastest regional growth at a CAGR of 6.28% through 2032. China benefits from established surfactant manufacturing infrastructure and the presence of regional producers. India is contributing to demand growth through expanding consumer goods production and rising consumption of household cleaning products.
Japan, South Korea and ASEAN Alpha Olefin Sulfonate (AOS) Market
Japan represents a higher-value channel through premium personal care, where AOS is valued for its hard-water foam performance and lower-irritation profile compared to conventional sulfates. South Korea is relevant for infant hygiene and sensitive-skin personal care exports. Southeast Asia contributes additional production capacity and regional demand for liquid detergents. One company acquired a former Evonik surfactant facility in Bekasi, Indonesia, supporting a multi-country Southeast Asian production network.
The Americas and EMEA Alpha Olefin Sulfonate (AOS) Market
North America is a mature but active part of the Alpha Olefin Sulfonate (AOS) market, supported by demand for sulfate-free formulations and industrial cleaning applications. Stepan's 2025 capacity expansion reflects supplier confidence in demand for high-foaming AOS grades. Pilot Chemical's biobased AOS partnership with Novvi made commercial quantities available from the second half of 2025. Europe remains driven by technical and documentation requirements, while concentrated and refillable cleaning products support demand for high-active grades. South America, the Middle East, and Africa offer additional demand driven by urbanization, modern retail expansion, household cleaning penetration, and consumer goods manufacturing investment. Syensqo received International Sustainability and Carbon Certification (ISCC) PLUS mass-balance certification for its bio-circular surfactants produced at its Moerdijk plant in 2025, reflecting the role of certified feedstocks in European supply chains[2].
Competitive Landscape
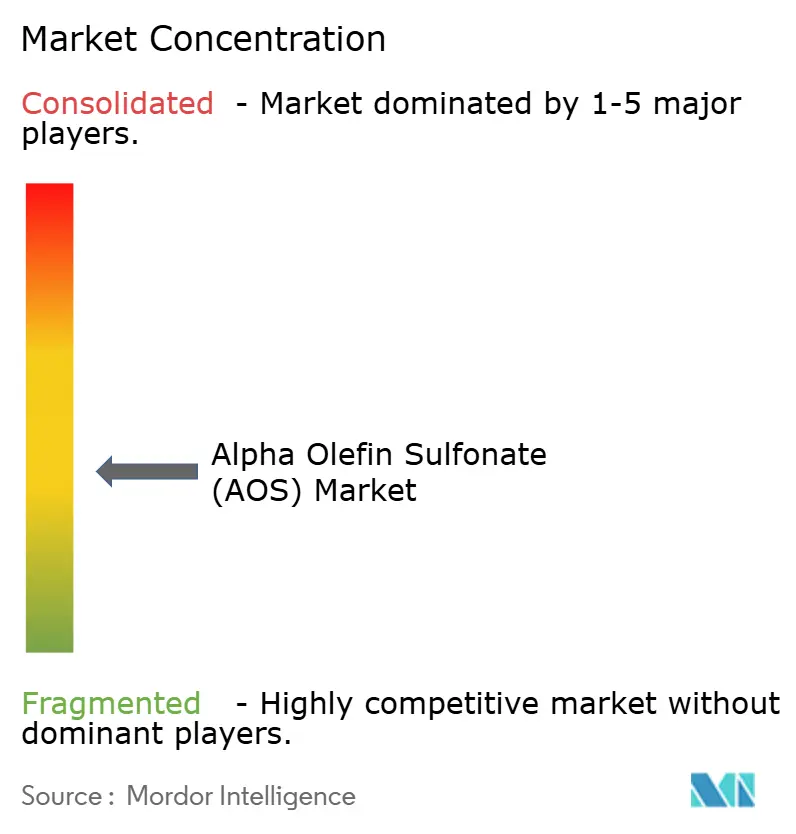
The Alpha Olefin Sulfonate (AOS) market is moderately fragmented. Stepan Company, Pilot Chemical, Clariant, Nouryon, Innospec, and Kao Corporation are key global producers. These companies compete on sulfonation process expertise, grade diversification, product performance, and sustainability credentials. Asian suppliers, including Zanyu Technology Group, Aekyung Chemical, and Aarti Surfactants, compete on scale and proximity to feedstocks, with their cost position being particularly relevant in C14-16 commodity grades. The competitive focus is shifting from price to supply reliability, technical support, and traceable feedstock options.
Stepan increased annual AOS production capacity by 25% in 2025 to meet rising demand for sulfate-free and high-foaming surfactants. Pilot Chemical partnered with Novvi to introduce biobased AOS technology in North America, offering a renewable feedstock option for customers with sustainable chemistry requirements. Aekyung Chemical expanded its manufacturing presence in Vietnam and acquired operations in Indonesia to strengthen its regional reach. These developments reflect how capacity, geographic presence, and differentiated inputs are being used to secure formulation business.
High-activity AOS grades and bio-based certification represent opportunities, as they address both concentrated product design and renewable sourcing requirements. AOS-enzyme hybrid systems offer a possible route to higher-value fabric care products. Oleochemical suppliers are broadening into surfactant production, which could extend competition beyond established AOS specialists. In May 2025, Musim Mas agreed to acquire Stepan's Batangas manufacturing facility in the Philippines through Masurf Inc. In October 2025, Future Origins demonstrated multi-ton production of Nalo, a zero-deforestation fatty alcohol substitute, in partnership with Kao Corporation, Unilever, and L'Oréal. These developments may compete for the same customer spending that would otherwise be directed toward lower-impact surfactant feedstocks.
Alpha Olefin Sulfonate (AOS) Industry Leaders
-
Stepan Company
-
Pilot Chemical Company
-
CLARIANT
-
Kao Corporation
-
Nouryon
- *Disclaimer: Major Players sorted in no particular order
Alpha Olefin Sulfonate (AOS) Market Companies Covered in this Report
- Aarti Surfactants
- Aekyung Chemical Co., Ltd.
- CLARIANT
- Enaspol a.s.
- Galaxy Surfactants
- Godrej Chemicals
- Huntsman International LLC
- Innospec
- Kao Corporation
- LION SPECIALTY CHEMICALS CO., LTD.
- Nouryon
- Pilot Chemical Company
- Sasol
- Stepan Company
- Syensqo
- Zanyu Technology Group Co., Ltd.
Recent Industry Developments in Alpha Olefin Sulfonate (AOS) Market
- October 2025: Nouryon announced expansion investments at its Jiaxing, China, facility, including a completed capacity increase for metal alkyls production and plans to open an organic peroxides innovation center in Tianjin in 2026. These developments expand its specialty chemicals manufacturing presence in China, where demand from the personal care and industrial segments supports long-term growth in AOS raw material demand.
- June 2025: Stepan Company announced a 25% increase in AOS production capacity across its Millsdale, Illinois, Anaheim, California, and Winder, Georgia, facilities, achieved through capital investments and process improvements. The expansion, the largest single-year capacity addition by Stepan in North America for AOS, was driven by rising demand from formulators for sulfate-free, high-foaming surfactants across personal care and industrial and institutional applications.
Global Alpha Olefin Sulfonate (AOS) Market Report Scope
Alpha Olefin Sulfonate (AOS) is a high-foaming anionic surfactant, commonly known by its INCI name, Sodium C14-16 Olefin Sulfonate. AOS is produced through the sulfonation of alpha olefins, typically derived from ethylene oligomerization, and consists of a mixture of alkene sulfonates and hydroxy alkane sulfonates.
The alpha olefin sulfonate (AOS) market is segmented by grade, form, application, and geography. By grade, the market is segmented into C14-16 AOS, C16-18 AOS, C18-20 AOS, C20-24 AOS, and others. By form, the market is segmented into liquid, paste, and powder. By application, the market is segmented into home care, personal care, industrial and institutional cleaning, and others. The report also covers market sizes and forecasts for the alpha olefin sulfonate (AOS) across 15 countries in major regions. The market sizes and forecasts are provided in terms of value (USD).
Segmentation Overview
| C14-16 AOS |
| C16-18 AOS |
| C18-20 AOS |
| C20-24 AOS |
| Others |
| Liquid |
| Paste |
| Powder |
| Home Care |
| Personal Care |
| Industrial and Institutional Cleaning |
| Others |
| Asia-Pacific | China |
| India | |
| Japan | |
| South Korea | |
| ASEAN Countries | |
| Rest of Asia-Pacific | |
| North America | United States |
| Canada | |
| Mexico | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| NORDIC Countries | |
| Rest of Europe | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Middle East and Africa | Saudi Arabia |
| South Africa | |
| Rest of Middle East and Africa |
| By Grade | C14-16 AOS | |
| C16-18 AOS | ||
| C18-20 AOS | ||
| C20-24 AOS | ||
| Others | ||
| By Form | Liquid | |
| Paste | ||
| Powder | ||
| By Application | Home Care | |
| Personal Care | ||
| Industrial and Institutional Cleaning | ||
| Others | ||
| By Geography | Asia-Pacific | China |
| India | ||
| Japan | ||
| South Korea | ||
| ASEAN Countries | ||
| Rest of Asia-Pacific | ||
| North America | United States | |
| Canada | ||
| Mexico | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| NORDIC Countries | ||
| Rest of Europe | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Middle East and Africa | Saudi Arabia | |
| South Africa | ||
| Rest of Middle East and Africa | ||
Key Questions Answered in the Report
What is current market size of Alpha Olefin Sulfonate (AOS) Market?
The Alpha Olefin Sulfonate (AOS) market size was valued at USD 0.76 billion in 2026 and is estimated to grow from USD 0.79 billion in 2027 to USD 1.04 billion by 2032, at a CAGR of 5.44% during the forecast period (2027-2032).
Why is liquid Alpha Olefin Sulfonate (AOS) important to formulators?
Liquid AOS holds a 39.18% share in 2026 and supports continuous production, precise dosing, and highly active concentrated formulations.
Which application is growing fastest for AOS?
Personal care is projected to expand at a 6.67% CAGR through 2032, while home care held a 43.75% share in 2026.
Which region has the strongest growth outlook for AOS?
Asia-Pacific held a 41.51% share in 2026 and is projected to grow at a 6.28% CAGR through 2032.