
United States Industrial Gearbox Service Market Size and Share
Market Overview
| Study Period | 2022 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
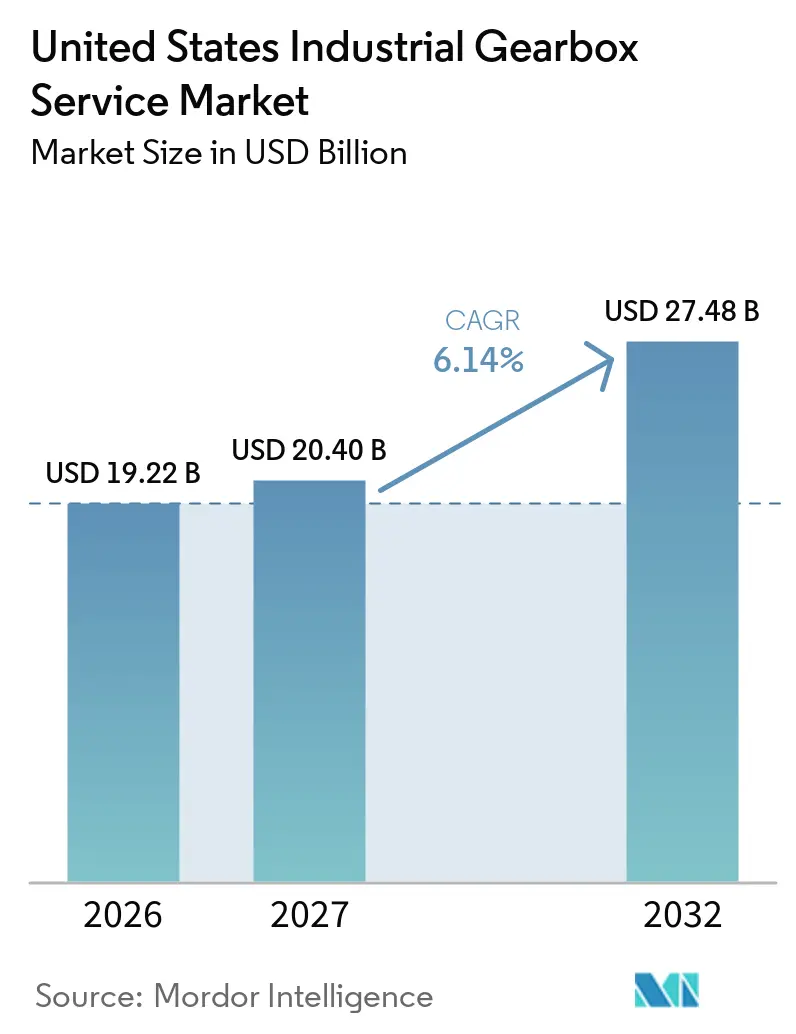
| Base Year Market Size (2026) | USD 19.22 Billion |
| Market Size (2027) | USD 20.40 Billion |
| Market Size (2032) | USD 27.48 Billion |
| Growth Rate (2027 - 2032) | 6.14 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
United States Industrial Gearbox Service Market Analysis by Mordor Intelligence
The United States Industrial Gearbox Service Market size was valued at USD 19.22 billion in 2026 and is estimated to grow from USD 20.40 billion in 2027 to reach USD 27.48 billion by 2032, at a CAGR of 6.14% during the forecast period (2027-2032). The United States industrial gearbox service market is moving toward contracts that connect service fees to equipment availability, rather than isolated parts replacement. Higher replacement costs continue to support repair and rebuild decisions at plants with gearbox-intensive assets. Domestic production expansion also creates a wider installed base that needs support from commissioning through operation. Wind repowering, factory automation, and continuous material movement raise the need for diagnostic, rebuild, and field-service capabilities. Providers that combine mechanical repair skills with connected diagnostics are better placed to retain long-term customer relationships.
Key Report Takeaways
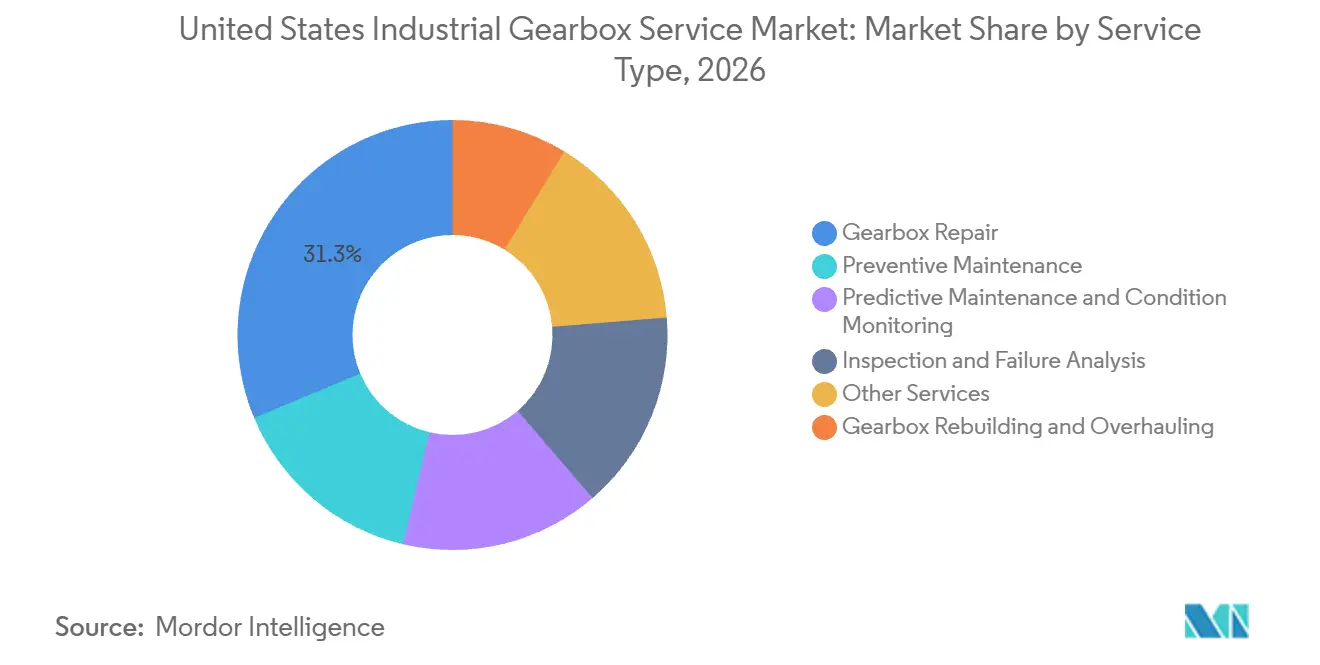
- By service type, Gearbox Repair led with 31.3% revenue share in 2026, while Predictive Maintenance and Condition Monitoring is forecast to expand at an 8.1% CAGR through 2032.
- By gearbox type, Helical Gearboxes held 38.5% revenue share in 2026, while Planetary Gearboxes recorded the highest projected CAGR at a 6.8% through 2032.
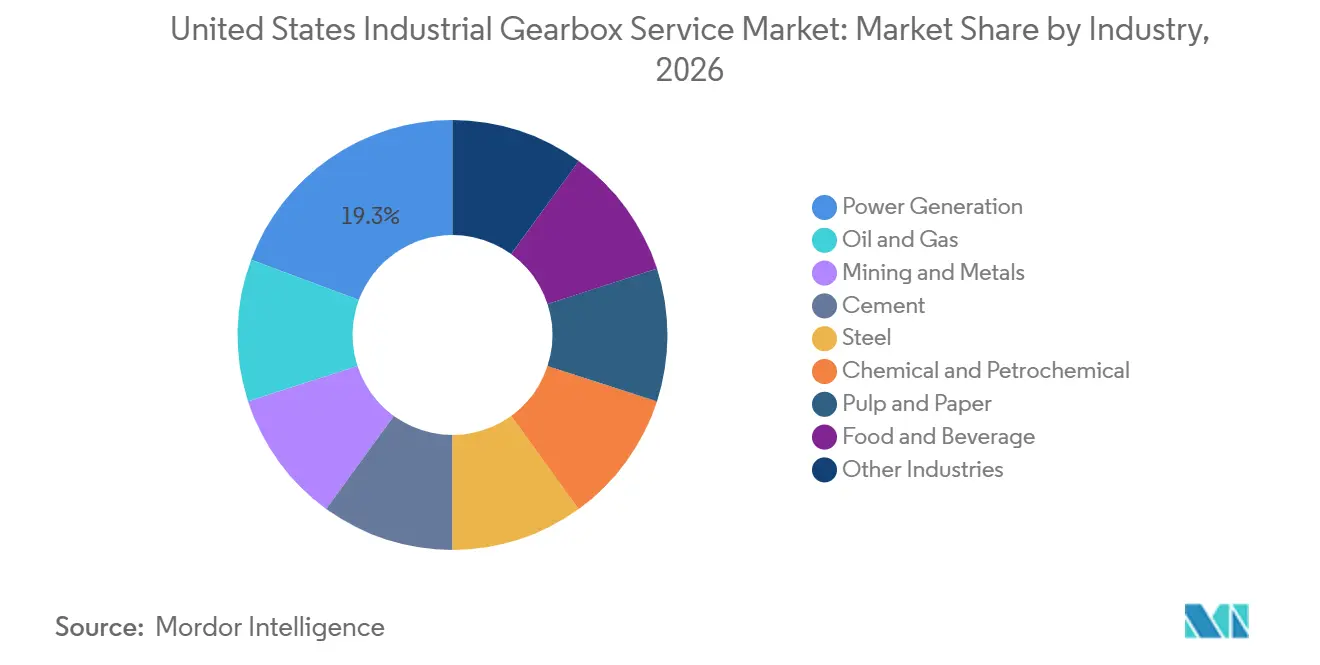
- By industry, Power Generation accounted for 19.3% of the United States industrial gearbox service market share in 2026 and is forecasted to grow at a 6.4% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of United States Industrial Gearbox Service Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Industrial Automation and Smart-Manufacturing Retrofits | +1.2% | National, with early gains in Great Lakes, Gulf Coast, and Southeast manufacturing corridors | Medium term (2-4 years) |
| Aging Installed Base and Deferred Replacement Demand | +1.5% | National, most acute in Rust Belt heavy-industrial clusters and Texas Gulf Coast refining hubs | Short term (≤ 2 years) |
| Wind-Turbine Gearbox Life Extension and Repowering | +1.1% | Great Plains, Pacific Northwest, and Appalachian ridgeline sites | Medium term (2-4 years) |
| Warehouse Automation and High-Duty Material Handling | +0.8% | National, concentrated in inland logistics corridors | Short term (≤ 2 years) |
| Reshoring, Grid Modernization, and Industrial Infrastructure Investment | +1.0% | National, with early capacity additions in Southeast and Southwest semiconductor and data-center corridors | Long term (≥ 4 years) |
| Digital Condition Monitoring and Uptime-Based Service Contracts | +0.9% | National, with faster adoption in continuous-run process industries | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Industrial Automation and Smart-Manufacturing Retrofits
Factory retrofits change the way existing gearbox fleets are managed in the United States industrial gearbox service market. Plants that add sensors to legacy equipment can identify bearing, lubrication, vibration, and thermal concerns before a major mechanical failure occurs. This increases the value of inspection, analysis, and planned repair work around assets that might otherwise have remained unmonitored. A 2025 peer-reviewed study found that OPC UA frameworks can support cost-effective digital retrofits across legacy industrial machinery, which helps make these upgrades accessible beyond the largest factories. The shift does not remove the need for mechanical work, because condition data must still lead to practical repair, overhaul, or replacement decisions. Service companies that can interpret equipment data and complete the physical repair can provide a more complete response to customers.
The United States industrial gearbox service market benefits when a retrofit identifies equipment degradation early enough for work to be planned around production schedules. Planned interventions can reduce the pressure to use emergency labor and expedited parts. This can also make service contracts more useful to customers that operate equipment continuously. Connected diagnostics create an ongoing relationship between the provider and the customer instead of a relationship limited to a breakdown event. The commercial value therefore shifts toward recurring monitoring, inspection, and scheduled maintenance activity. This model requires providers to build credible diagnostic processes while retaining strong gearbox repair capability.
Aging Installed Base and Deferred Replacement Demand
A large share of the industrial gearbox installed base has operated for many years in heavy manufacturing, mining, cement, and process applications. These systems often remain serviceable when gears, bearings, seals, shafts, and housings can be repaired or rebuilt. The United States industrial gearbox service market, therefore, gains from customers choosing a lifecycle extension path instead of purchasing new equipment. Replacement decisions become more difficult when the operating cost of a shutdown is high, and a compatible unit may not be immediately available. Repair providers can respond with teardown, inspection, machining, and recommissioning services that keep a familiar drivetrain in operation. This supports demand for both regional field service and specialized workshop capacity.
Domestic steel costs and tariff conditions active in 2026 reinforced the economic case for repair rather than replacement in capital-intensive operations. The effect is strongest where a new gearbox purchase also requires engineering changes, installation work, and a prolonged production interruption. Deferred replacement does not mean that customers ignore mechanical risk. It often means that operators require more detailed inspections and planned overhauls to maintain reliability. The United States industrial gearbox service market can capture this work when providers show that a rebuild will meet the customer’s operating requirements. This favors firms with machining capacity, technical documentation, and experience with older equipment designs.
Wind-Turbine Gearbox Life Extension and Repowering
Wind repowering creates a specialized source of work for the United States industrial gearbox service market. GE Vernova received orders during 2024 to repower more than 1 gigawatt of U.S. wind turbines, with commercial operation targets running from 2024 through 2027.[1] Repowering work can involve drivetrain evaluation, gearbox replacement, bearing work, and related service activity. It therefore creates opportunities for providers with the needed engineering, lifting, logistics, and quality capabilities. The work is technically distinct from general industrial repair because wind assets face site-specific access limits and demanding operating conditions. Companies with wind drivetrain expertise can use these projects to establish longer service relationships with asset owners.
The potential service base extends beyond the projects already ordered. GE Vernova states that an estimated 10,500 legacy U.S. turbines may be eligible for its Repower program. The U.S. Department of Energy notes that targeted end-of-service actions can extend turbine life by up to 15 years without a full drivetrain replacement.[2] That creates demand at several levels, from complete gearbox work to bearing, seal, and other component interventions. The United States industrial gearbox service market can therefore serve both major repowering programs and smaller life-extension projects. This combination broadens the range of service work available across the existing wind fleet.
Warehouse Automation and High-Duty Material Handling
Automated fulfillment centers require conveyor systems, automated guided vehicles, and robot-related drivetrain components to operate through demanding duty cycles. These operations have limited tolerance for unplanned stops because throughput depends on equipment availability. The United States industrial gearbox service market is supported by the need to inspect and maintain gearboxes that operate in these high-use environments. Planetary designs are relevant in automated guided vehicles and collaborative robot arms because compact units can provide high torque density. This helps explain why planetary gearbox service is expected to grow faster than several established gearbox categories. Providers must respond with quick diagnosis, parts availability, and repair practices that fit short operating windows.
Warehouse operators also create a case for condition monitoring contracts where equipment data can guide maintenance timing. A service arrangement can combine sensor review with inspection and corrective work when operating data indicates deterioration. This approach is more useful when the provider can support both the digital service and the physical repair. It can create more stable revenue than a relationship based only on emergency repairs. The United States industrial gearbox service market also gains from the broader spread of automated material handling across distribution networks. Service firms that understand conveyor, mobile automation, and robotic drivetrain requirements can address this demand without relying on a single end-use sector.
Restraints Impact Analysis of United States Industrial Gearbox Service Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timelin |
|---|---|---|---|
| Skilled Gear-Repair Technician Shortage | -0.7% | National, most acute in rural industrial clusters with limited vocational pipeline | Long term (≥ 4 years) |
| Long Shutdown Windows and Customer Deferral of Overhauls | -0.4% | National, most visible in chemicals, pulp and paper, and cement | Medium term (2-4 years) |
| Component Traceability and Cybersecurity Gating for Connected Service | -0.3% | National, concentrated in energy, chemicals, and critical manufacturing | Medium term (2-4 years) |
| Substitution by Integrated Actuators and Direct-Drive Systems | -0.5% | National, initially limited to low-torque precision applications | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Skilled Gear-Repair Technician Shortage
Skilled labor availability can limit how quickly service providers complete complex gearbox rebuilds. The work requires familiarity with gear geometry, bearing fits, shaft alignment, lubrication systems, and precise reassembly. These skills are difficult to replace quickly because they depend on practical experience as well as formal training. When capacity is limited, providers may face longer repair queues and higher labor costs. The United States industrial gearbox service market can therefore grow more slowly when repair shops cannot scale their technical teams in line with demand. Rural industrial areas can be particularly difficult locations for staffing specialized repair roles.
Training programs can help service companies develop their workforce, but the process takes time. Apprenticeship and hands-on rebuild instruction are important because gearbox work involves judgment that is learned during disassembly and reassembly. Digital workflow tools can support technicians with standardized procedures and equipment records. They do not fully replace the mechanical skills required for complex failure analysis or precision assembly. The United States industrial gearbox service market will remain dependent on providers that can retain experienced technicians and transfer their knowledge to newer staff. This makes workforce development a practical operating requirement rather than a temporary hiring issue.
Component Traceability and Cybersecurity Gating for Connected Service
Connected gearbox service can face longer approval processes in energy, chemical, and critical manufacturing facilities. Customers may require suppliers to show how remote access, sensor data, and equipment records will be protected. In 2026, CISA, NSA, FBI, DOE, and EPA warned of an active threat affecting Siemens S7 Series PLCs and identified critical manufacturing among the targeted sectors. This makes cybersecurity an operational requirement for providers that offer remote monitoring or connected diagnostics. It can be especially challenging for smaller firms that lack dedicated security resources. Qualification requirements can delay the adoption of digital service contracts even when the maintenance case is strong.
Standards and federal guidance make the expected controls clearer, but they also add implementation work. IEC PAS 62443-1-6:2025 addresses security for industrial automation and control systems. NIST Special Publication 800-82 Revision 4 describes operational technology security practices, including separation between information technology and operational technology environments. Providers must account for these expectations when designing sensor connectivity and remote support. The United States industrial gearbox service market may see slower connected-service adoption where approval and integration work is extensive. Firms that meet customer security expectations can turn that requirement into a qualification advantage.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
United States Industrial Gearbox Service Market Segment Analysis
By Service Type:
Predictive Contracts Outpace Corrective RepairGearbox Repair accounted for 31.3% of United States industrial gearbox service market share in 2026. The category remains important because many facilities still require corrective work after a gearbox failure or serious inspection finding. Repair can include bearing replacement, gear work, shaft repair, sealing work, alignment, and testing before a unit returns to service. Rebuilding, overhauling, and preventive maintenance provide a middle path for customers seeking to extend asset life without a full replacement. Predictive Maintenance and Condition Monitoring is expected to grow at an 8.1% CAGR through 2032, using vibration, temperature, lubrication, and other data to identify developing concerns.
Flender reported that its AIQ intelligent sensor system can reduce unplanned downtime by up to 70% and maintenance costs by up to 40% in relevant applications. Inspection and Failure Analysis helps customers decide whether a unit should be repaired, rebuilt, or replaced, while lubricant analysis, uprating, and training can support lifecycle relationships. The United States industrial gearbox service market is shifting toward work initiated by asset-condition evidence, while corrective repair remains necessary for aging equipment and unexpected failures. This can move more activity into planned maintenance windows and give providers time to prepare parts and labor. David Brown Santasalo states that DBS Transform can capture drivetrain data needed for reverse engineering within an on-site window of under 10 hours, supporting decisions during narrow shutdown schedules.

By Gearbox Type:
Helical Dominance Meets Planetary MomentumHelical Gearboxes held 38.5% of United States industrial gearbox service market share in 2026. Their installed base spans food and beverage processing, pulp and paper, chemical plants, and general manufacturing. Long asset lives support demand for inspection, repair, and replacement components. Worm and spur gearboxes continue to serve material handling and packaging applications, while bevel gearboxes remain important in mining conveyors and steel rolling mill drives. Flender expanded its Elgin, Illinois, service center, with operations beginning in February 2026, to add warehouse capacity, in-house gear regrinding, and consolidated storage for industrial and wind customers.
Planetary Gearboxes are forecast to grow at a 6.8% CAGR from 2027 to 2032, supported by warehouse automation, collaborative robotics, and wind turbine drivetrains. Their sun, planet, and ring gear interactions require precise assembly, bearing preload, and shimming during service. That complexity increases labor and engineering requirements and can support higher-value repair work. SEW-EURODRIVE began U.S.-based assembly of P2.e planetary gear units in Wellford, South Carolina, with cataloged-ratio lead times of 6 weeks. Sumitomo Drive Technologies acquired Riverside Spline & Gear in Michigan in June 2026, adding domestic precision gear manufacturing capability that can reduce delays for critical service components.
By Industry:
Power Generation Anchors the Market, Wind Redefines Its ScopePower Generation captured 19.3% of the United States industrial gearbox service market size in 2026 and is forecasted to grow at a 6.4% CAGR through 2032. The segment includes conventional generation assets and a growing range of wind drivetrain service requirements. Philadelphia Gear supports coal, gas, nuclear, hydro, and wind customers through its U.S. service network. Wind assets add lifecycle requirements for inspection, repair, component replacement, and repowering. The United States industrial gearbox service market can serve complete gearbox work and targeted life-extension activity across several power technologies.
Oil and Gas remains significant because compression-train gearboxes operate across the Gulf Coast, and Baker Hughes states that Lufkin Gears and Allen Gears service equipment from more than 30 other OEM brands through U.S. Centers of Excellence. Mining, metals, steel, cement, chemical and petrochemical, and pulp and paper operations all require periodic service based on operating and safety needs. Food and beverage processing can require more frequent work because washdown environments can accelerate gearbox wear. General manufacturing also creates a broad field base for repair and preventive work. Providers must adapt their methods and documentation to the process conditions that influence component life in each application.
Geography Analysis
The United States industrial gearbox service market is organized around industrial clusters rather than state boundaries. The Gulf Coast corridor from Houston through Louisiana to the Alabama coast is important for oil and gas, chemical, and petrochemical gearbox service. Dense process industries create a concentration of compression, pumping, and production assets that need reliable drivetrain support. Philadelphia Gear maintains facilities in the Houston area, while Baker Hughes serves gear customers through U.S. Centers of Excellence. Horsburgh & Scott acquired Houston-based Franklin Machine & Gear in April 2026, extending its Gulf Coast footprint and adding precision CNC machining capability.
The Great Lakes and Rust Belt, including Ohio, Pennsylvania, Michigan, and Illinois, contain a large installed base in steel, paper, and general manufacturing. That installed base supports repair work on equipment that has operated for many years. Flender’s Elgin expansion strengthens access to gear regrinding and parts storage for Midwest industrial and wind customers. The area also supports networks serving power generation, manufacturing, and process industries. Older equipment and new manufacturing investment keep the region central to the United States industrial gearbox service market.
The Great Plains and Mountain West are evolving as wind repowering and grid investment shape service demand. In September 2026, the U.S. Department of Energy announced USD 1.9 billion for 31 grid-improvement projects across 26 states, targeting more than 23 gigawatts of additional grid capacity. Greater grid capacity can support repowered wind assets, which need lifecycle support as projects operate. Hitachi Energy also announced a USD 528 million transformer manufacturing facility in Gallman, Mississippi, within a USD 1.5 billion U.S. expansion program, signaling industrial infrastructure activity that can expand the installed equipment base
Competitive Landscape
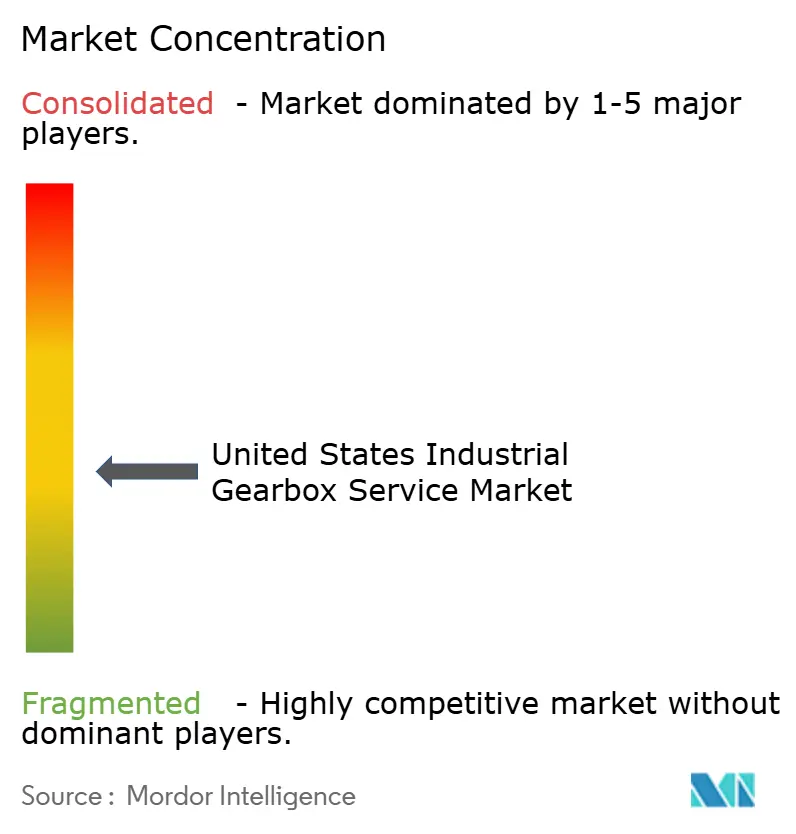
The United States industrial gearbox service market is moderately fragmented. OEM service networks compete with multi-brand independent providers and regional specialists. OEM networks can combine original equipment knowledge, parts access, and established service procedures. Independent providers compete through multi-brand repair capability, local response, and machining expertise. Regional firms retain customers where proximity and turnaround time are decisive.
The Timken Company operates Philadelphia Gear and Standard Machine within Timken Power Systems, combining gear drive repair with motor, generator, and bearing maintenance. Flender uses its Winergy Service360 approach to provide warranty and diagnostic services, including services for third-party gearboxes. Its AIQ sensor offering supports a connected-service model for customers that want condition data alongside mechanical expertise. David Brown Santasalo’s DBS Transform uses structured-light scanning to speed documentation and reverse engineering for gearbox systems. These approaches show how established manufacturers and larger independents compete through wider lifecycle support and faster diagnosis.
Consolidation is visible among multi-brand service providers. Horsburgh & Scott’s April 2026 acquisition of Franklin Machine & Gear added Gulf Coast reach and precision CNC machining capability, while Sumitomo Drive Technologies added Riverside Spline & Gear in June 2026 to bring domestic precision gear manufacturing into its service ecosystem. Connected uptime-based service remains less established because it requires sensor infrastructure, data interpretation, secure connectivity, and the ability to assume some reliability responsibility. The competitive balance will continue to depend on repair execution, local capacity, and the ability to support a wider lifecycle relationship.
United States Industrial Gearbox Service Industry Leaders
-
The Timken Company
-
Baker Hughes
-
Xtek, Inc.
-
US Gearbox
-
Atlanta Gear Works, Inc.
- *Disclaimer: Major Players sorted in no particular order
United States Industrial Gearbox Service Market Companies Covered in this Report
- Atlanta Gear Works, Inc.
- B & D Industrial, Inc.
- Baker Hughes Company
- C-B Gear & Machine, Inc.
- Churon Company
- Cleveland Gear Company, Inc.
- David Brown Santasalo USA Inc.
- Flender Corporation
- Houston Dynamic Service, Inc.
- Koffler Electrical Mechanical Apparatus Repair, Inc.
- Maintenance Plus, Inc.
- Motor & Gear Engineering, Inc.
- Precision Pump & Gear Works, Inc.
- SEW-EURODRIVE, Inc.
- Sumitomo Heavy Industries (S.H.I.) America, Inc.
- The Horsburgh & Scott Co.
- The Timken Company
- United Gear Works LLC
- US Gearbox, Inc.
- Xtek, Inc.
Recent Industry Developments in United States Industrial Gearbox Service Market
- September 2026: The US Department of Energy announced intention to fund 31 grid-improvement projects across 26 states under the SPARK initiative, committing USD 1.9 billion federal against a USD 5.25 billion total investment. Projects will reconductor or rebuild over 1,500 miles of transmission line, adding more than 23 gigawatts of capacity, directly expanding power generation gearbox service demand across multiple states.
- September 2026: Hitachi Energy announced plans for a USD 528 million transformer manufacturing facility in Gallman, Mississippi, the cornerstone of a USD 1.5 billion US manufacturing expansion. The investment creates over 700 jobs and signals sustained industrial infrastructure buildout in the Southern US, generating downstream gearbox service demand.
United States Industrial Gearbox Service Market Report Scope
Industrial gearbox service encompasses the professional inspection, maintenance, repair, and overhaul of mechanical power transmission units used in factories and heavy machinery.
The United States industrial gearbox service market is segmented by service type, gearbox type, and industry. By service type, the market is segmented into gearbox repair, gearbox rebuilding and overhauling, preventive maintenance, predictive maintenance and condition monitoring, inspection and failure analysis, and other services. By gearbox type, the market is segmented into helical gearboxes, bevel gearboxes, planetary gearboxes, worm gearboxes, spur gearboxes, and other gearbox types. By industry, the market is segmented into power generation, oil and gas, mining and metals, cement, steel, chemical and petrochemical, pulp and paper, food and beverage, and other industries. For each segment, market sizing and forecasts are provided in terms of value (USD).
Segmentation Overview
| Gearbox Repair |
| Gearbox Rebuilding and Overhauling |
| Preventive Maintenance |
| Predictive Maintenance and Condition Monitoring |
| Inspection and Failure Analysis |
| Other Services |
| Helical Gearboxes |
| Bevel Gearboxes |
| Planetary Gearboxes |
| Worm Gearboxes |
| Spur Gearboxes |
| Other Gearbox Types |
| Power Generation |
| Oil and Gas |
| Mining and Metals |
| Cement |
| Steel |
| Chemical and Petrochemical |
| Pulp and Paper |
| Food and Beverage |
| Other Industries |
| By Service Type | Gearbox Repair |
| Gearbox Rebuilding and Overhauling | |
| Preventive Maintenance | |
| Predictive Maintenance and Condition Monitoring | |
| Inspection and Failure Analysis | |
| Other Services | |
| By Gearbox Type | Helical Gearboxes |
| Bevel Gearboxes | |
| Planetary Gearboxes | |
| Worm Gearboxes | |
| Spur Gearboxes | |
| Other Gearbox Types | |
| By Industry | Power Generation |
| Oil and Gas | |
| Mining and Metals | |
| Cement | |
| Steel | |
| Chemical and Petrochemical | |
| Pulp and Paper | |
| Food and Beverage | |
| Other Industries |
Key Questions Answered in the Report
What is the projected growth rate for United States industrial gearbox service?
The United States Industrial Gearbox Service Market size was valued at USD 19.22 billion in 2026 and is estimated to grow from USD 20.40 billion in 2027 to reach USD 27.48 billion by 2032, at a CAGR of 6.14% during the forecast period (2027-2032).
Which service category is growing fastest?
Predictive Maintenance and Condition Monitoring is forecast to grow at an 8.1% CAGR through 2032.
Which gearbox type leads service revenue?
Helical Gearboxes led service revenue with a 38.5% share in 2026.
Why are wind turbines relevant to gearbox servicing?
Repowering and life-extension activity require drivetrain evaluation, gearbox work, and component service across the U.S. wind fleet.
What is the main workforce challenge for service providers?
Specialized gearbox rebuild work depends on technicians with practical mechanical, machining, inspection, and assembly skills.
How are providers differentiating their service offerings?
Providers are adding condition monitoring, digital inspection, reverse engineering, machining, and multi-brand repair capabilities.