
Southeast Asia Cross-border E-commerce Market Size and Share
Southeast Asia Cross-border E-commerce Market Analysis by Mordor Intelligence
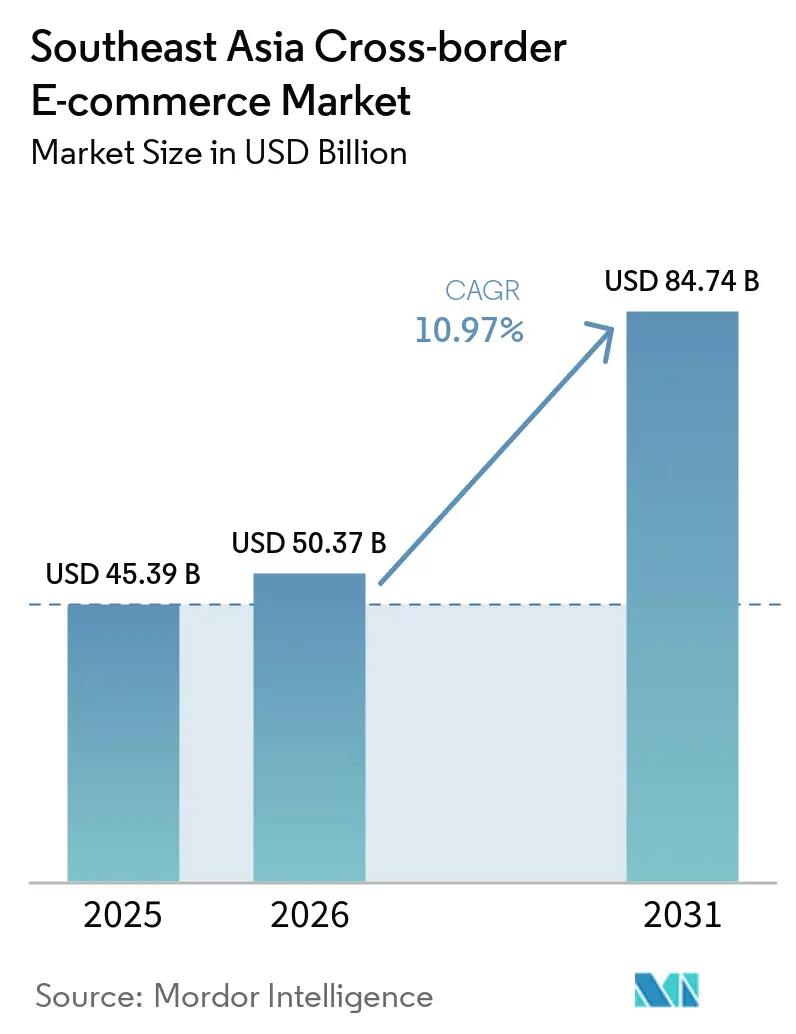
The Southeast Asia cross-border e-commerce market size was valued at USD 50.37 billion in 2026 and estimated to grow from USD 55.9 billion in 2027 to reach USD 92.43 billion by 2032, at a CAGR of 10.58% during the forecast period (2027-2032).
Growth depends on turning video-led product discovery and foreign-seller access into completed international goods orders. In Vietnam, merchandise demand on online marketplaces gives overseas retailers a channel to established buyers. Platform responses combine overseas listing access with payment and distribution services. Tariff preferences can improve eligible goods' economics, but destination-specific taxes and reverse-shipping risk can absorb some available margin. Choosing destination and delivery mode together gives sellers a way to retain tariff headroom as margin after allowing for potential return charges.
Key Report Takeaways
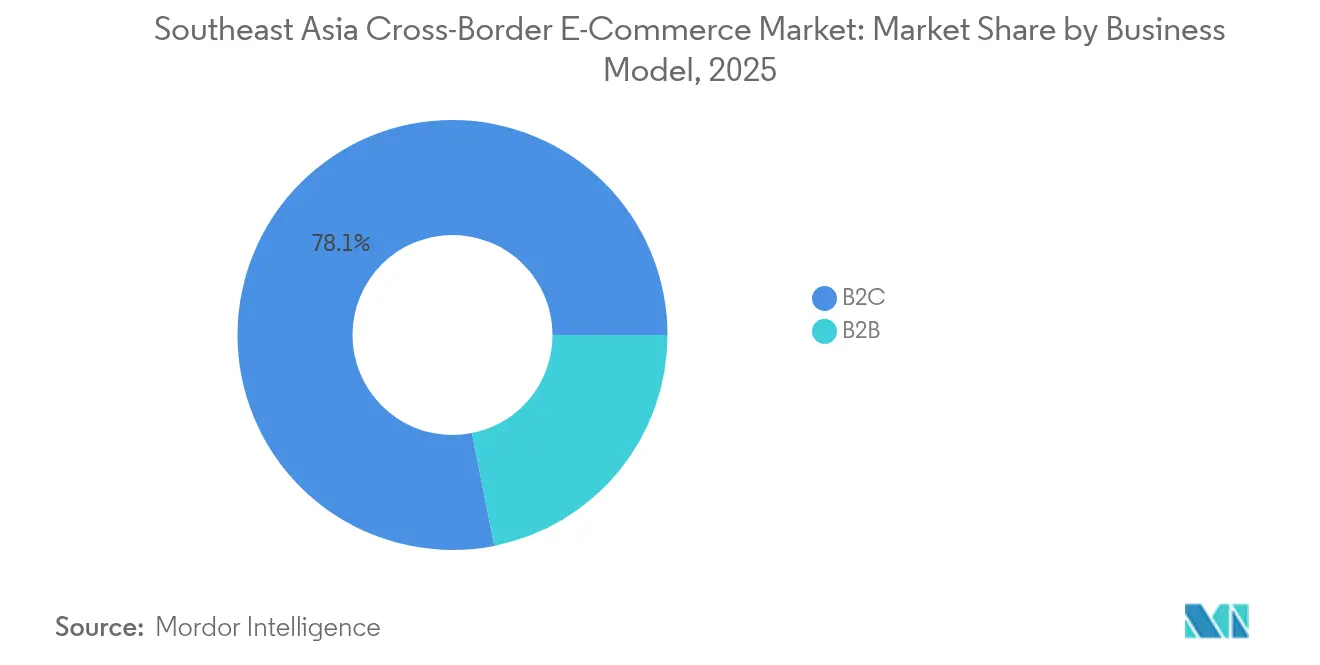
- Across business models, B2C led with a 78.5% Southeast Asia cross-border e-commerce market share in 2026 and is projected to post the fastest CAGR, 11.12%, during 2027-2032.
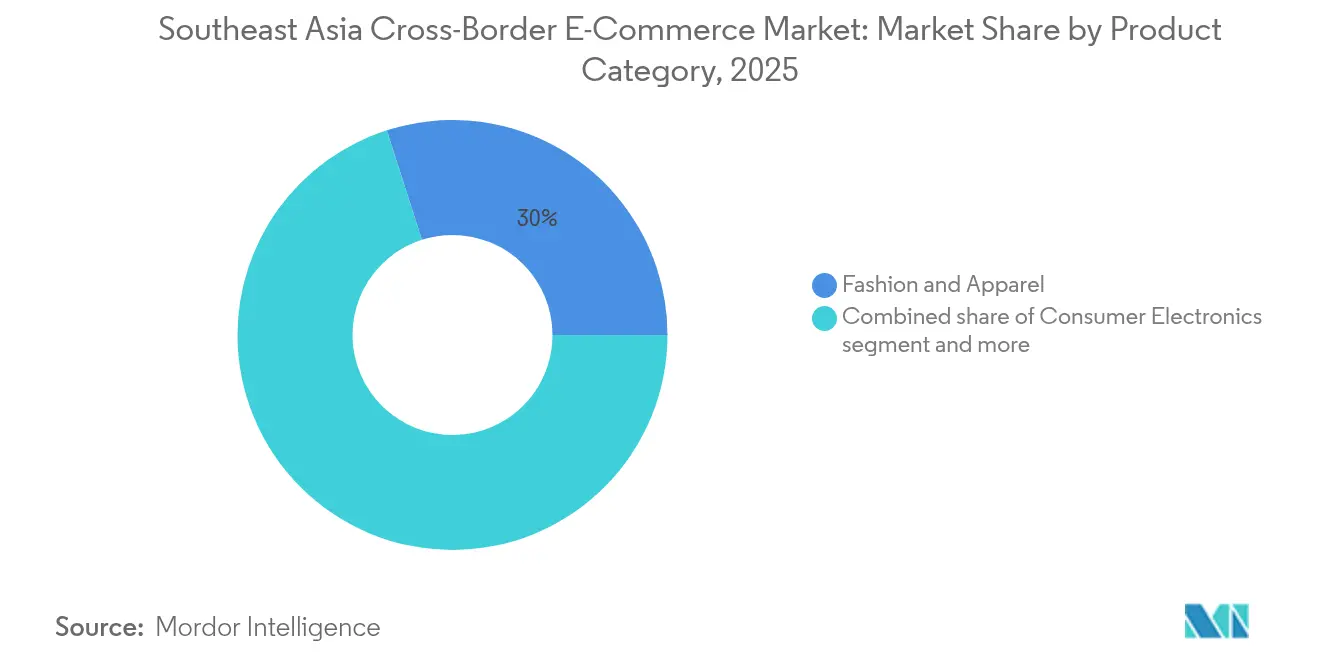
- Among product categories, fashion and apparel led with a 29.89% share of the Southeast Asia cross-border e-commerce market size in 2026, while beauty and personal care is projected to grow fastest at a CAGR of 10.64% during 2027-2032.
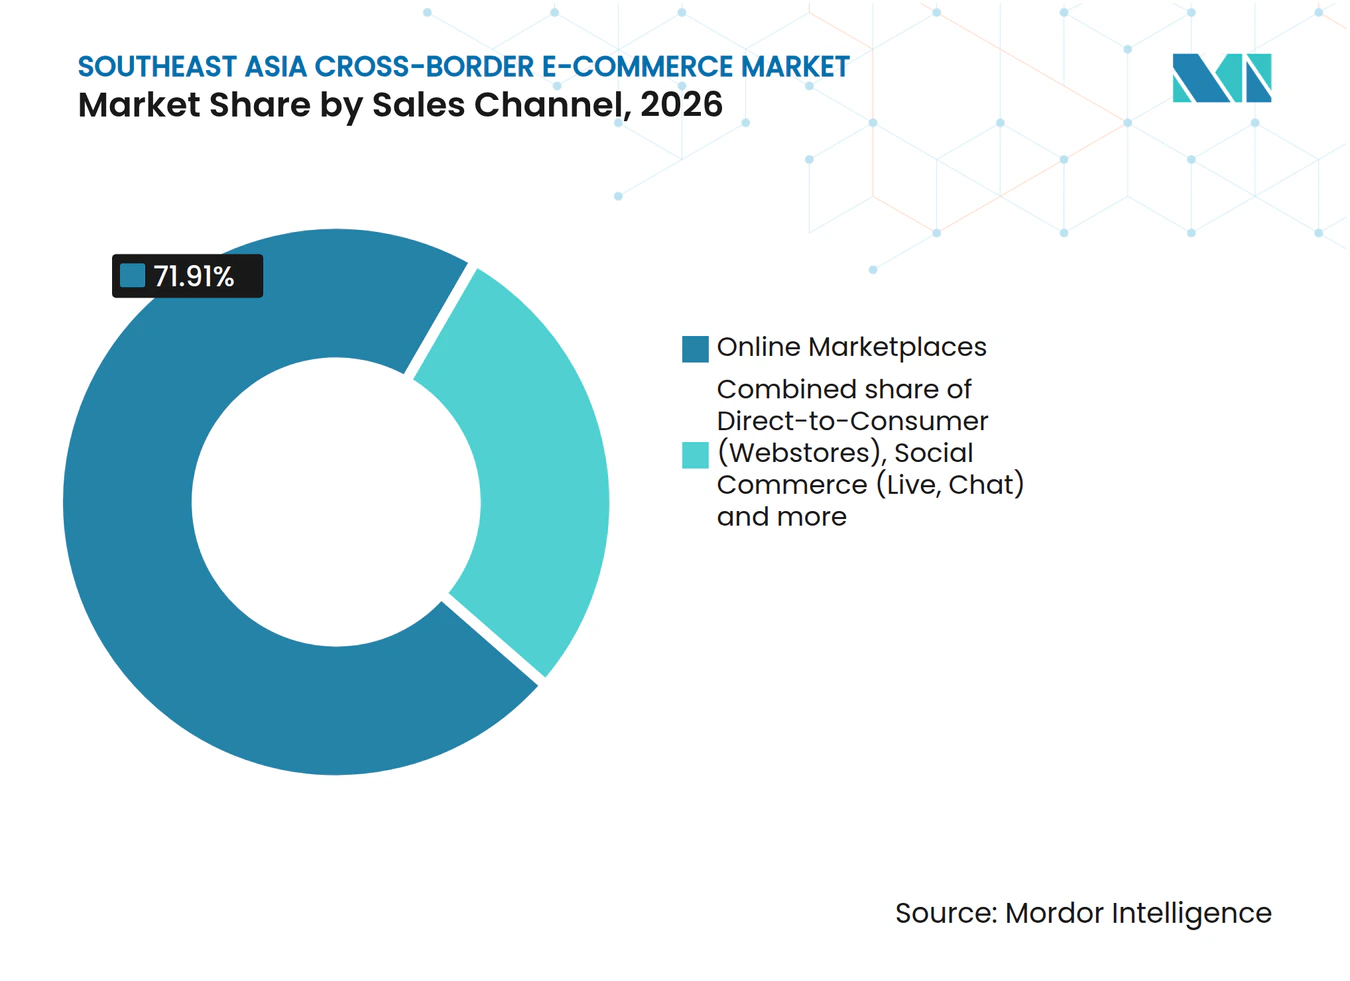
- By sales channel, online marketplaces led with a 71.91% share in 2026, while social commerce (live, chat) is projected to grow fastest at a CAGR of 19.2% during 2027-2032.
- Geographically, Indonesia led with a 34.12% share in 2026, while Vietnam is projected to grow fastest at a CAGR of 10.9% during 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Southeast Asia Cross-border E-commerce Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rapid adoption of domestic e-wallet super-apps across ASEAN (GrabPay, GCash, MoMo) fueling cross-border checkout | +3.8% | Vietnam's national territory | Short term (≤ 2 years) |
| RCEP tariff phase-downs lowering landed costs for Chinese and Korean origin goods | +2.8% | Vietnam's national customs territory | Long term (≥ 4 years) |
| Rise of video-commerce and live-streaming converting social media engagement to cross-border sales | +4.2% | Thailand, Singapore, Vietnam, Philippines and Malaysia | Short term (≤ 2 years) |
| B2B2C bonded-warehouse model (e.g., Lazada’s use of Malaysia’s DFTZ bonded warehouse) cutting delivery lead times | +3% | KLIA Aeropolis, Malaysia | Medium term (2-4 years) |
| Proliferation of BNPL providers (Kredivo, Atome) expanding ticket sizes among Gen-Z shoppers | +1.2% | Malaysia's national territory | Short term (≤ 2 years) |
| ASEAN Customs Transit System (ACTS) enabling duty-suspended truck moves across CLMV corridor | +0.8% | Cambodia, Lao PDR, Myanmar and Vietnam | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Rapid adoption of domestic e-wallet super-apps across ASEAN (GrabPay, GCash, MoMo) fueling cross-border checkout
Domestic super-app adoption creates a payment-integration opportunity for retailers considering Vietnamese expansion. In October 2026, MoMo's platform served more than 30 million users in Vietnam. Its domestic ecosystem connected over 500,000 businesses and merchants. MoMo also partnered with more than 70 banks, financial institutions and insurance companies. For an overseas retailer, the decisive condition is whether its checkout accepts the wallet, since platform scale alone does not complete an international goods order.
RCEP tariff phase-downs lowering landed costs for Chinese and Korean origin goods
Lower preferential duties create pricing headroom for cross-border sellers whose goods satisfy RCEP origin and import requirements. Vietnam's RCEP schedule lowered the duty on qualifying China-origin radio-telephony or radio-telegraphy equipment from a 10% base rate to 7.5% in 2026.[1] For qualifying Korea-origin equipment in the same tariff category, the scheduled duty fell from a 10% base rate to 6.7% in 2026. The differing rates make origin commercially relevant even within one narrowly defined product category. An eligible seller can use the reduced tariff component to support a lower offer or preserve margin. Only merchandise with demonstrable preferential eligibility gains that headroom, and other imported orders do not.
Rise of video-commerce and live-streaming converting social media engagement to cross-border sales
Video commerce can expand demand by combining demonstrated sales activity with a more accessible route for foreign merchants. TikTok Shop Southeast Asia Cross-Border E-commerce reported that short-video-driven GMV rose 257% year over year during Double 12 in 2025.[2] On November 14, 2025, TikTok began onboarding Korean businesses into Thailand, Singapore, Vietnam, the Philippines and Malaysia without requiring local entities or local bank accounts. Sellers needed a Korean business registration certificate, passport, domestic address and virtual account, with local partnerships supporting those without logistics infrastructure. For Korean exporters, that combination makes the format a regional entry opportunity while retaining a defined documentary and fulfillment burden.
B2B2C bonded-warehouse model (e.g., Lazada’s use of Malaysia’s DFTZ bonded warehouse) cutting delivery lead times
Integrated fulfillment can make customs clearance part of a coordinated delivery service for merchants selling across borders. A 2025 WTO-hosted case study described the DFTZ eFulfillment Hub at KLIA Aeropolis as integrating warehousing, sorting, last-mile delivery and cross-border fulfillment. The study cited a MITI fact sheet that put the possible fall in cargo clearance time at around six hours to roughly three hours. For overseas sellers, connecting clearance with the physical activities needed to complete an order gives the hub a role throughout fulfillment. The merchant's delivery promise must still allow time for sorting and last-mile handoff beyond any customs saving.
Restraints Impact Analysis of Southeast Asia Cross-border E-commerce Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Fragmented de-minimis rules creating landed-cost opacity for merchants | -2.2% | Thailand and Malaysia | Short term (≤ 2 years) |
| High reverse-logistics costs and return rates in fashion cross-border flows | -1.6% | Vietnam's national territory | Medium term (2-4 years) |
| Patchy FX controls in Indonesia and Vietnam delaying seller payouts by up to 5 days | -0.8% | Indonesia and Vietnam | Short term (≤ 2 years) |
| Social-commerce fraud incidents eroding trust in Tier-2/3 cities | -0.6% | Singapore's national territory | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Fragmented de-minimis rules creating landed-cost opacity for merchants
Destination and transport choices complicate the tax calculation behind an apparently simple cross-border selling price. Thailand began collecting import duty and VAT on foreign goods sold online from the first unit of value on January 1, 2026, ending its earlier exemption for low-value goods. Malaysia gives qualifying air-courier consignments de minimis treatment based on cost, insurance and freight (CIF) value, while road imports do not qualify for that exemption. These differences mean that merchants cannot assume a low-value parcel receives the same treatment across nearby destinations or shipping modes. A delivery option that changes the applicable exemption can therefore alter the economics of the same goods order. The remaining constraint is the cost of maintaining destination-specific quotations while absorbing any tax treatment omitted from the buyer's price.
High reverse-logistics costs and return rates in fashion cross-border flows
A cross-border merchant's margin depends partly on which approved returns trigger an additional shipping charge. On June 28, 2026, Lazada announced merchant return-shipping fees for its Southeast Asian cross-border sites, with a stated July 2 start. Qualifying orders required confirmed receipt, an initiated return and refund, physical return to Lazada's inspection warehouse or the merchant, and platform approval. That combination would attach a shipping cost to an order already subject to an approved refund. The announcement exempted change-of-mind returns and allowed fee refunds when verification found the merchant was not at fault. For merchants on Lazada's cross-border sites, qualifying returns outside those exceptions would add return shipping to an order already refunded, reducing the margin on the outbound sale.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Southeast Asia Cross-border E-commerce Market Segment Analysis
By Business Model:
Consumer Buying Choices Shape B2C ExpansionB2C accounted for a 78.5% share of the Southeast Asia cross-border e-commerce market size in 2026, making it the largest segment and the fastest-growing segment with a projected CAGR of 11.12% during 2027-2032. A January 2025 Airwallex and Statista survey reported that China-based retailers accounted for 61% of cross-border sales in Malaysia. Its Malaysian sample comprised 1,000 respondents who had bought internationally online in the preceding 12 months. That origin mix illustrates an established consumer-facing trade route for foreign retail supply among shoppers already purchasing internationally. Retailers entering Malaysia need an offer that differs from the established Chinese supply, not only a way to order across borders.
Consumer-facing expansion can also come from filling local assortment gaps, creating a competitive option beyond discounted imports. Citi's report drew on a March 2025 survey of 600 cross-border shoppers in Singapore, Indonesia and Thailand, along with Cube Asia market data and industry interviews. The research identified savings in some instances, products unavailable locally and familiar payment methods as factors affecting overseas purchases. An overseas offer can rest on local assortment gaps and familiar payment options, with price competition reserved for products where a genuine saving exists.



By Product Category:
Fashion Scale and Beauty DemonstrationFashion and apparel represented a 29.89% Southeast Asia cross-border e-commerce market share in 2026, making it the largest segment. In the e-Conomy SEA 2025 report, fashion and accessories accounted for 27% of video-commerce GMV in Indonesia, Malaysia, the Philippines, Singapore, Thailand and Vietnam. That category-level spending means a fashion seller is addressing demonstrated merchandise demand within video commerce, making channel presence a practical complement to cross-border product supply. For foreign brands, the commercial challenge is to turn participation in that buying format into a distinctive imported assortment that earns a transaction among competing fashion offers.
Beauty and personal care is the fastest-growing segment, with a projected CAGR of 10.64% during 2027-2032. In the e-Conomy SEA 2025 report, beauty and personal care accounted for 21% of video-commerce GMV, with product demonstration credited for its larger representation in that format. That fit gives overseas beauty brands a way to explain an unfamiliar product before asking a shopper to place an international order. Selecting imported products suited to live, interactive presentation makes assortment design part of the distribution strategy for overseas beauty brands.

By Sales Channel:
Marketplace Access and Recurring Live SellingOnline marketplaces formed the largest segment, with a 71.91% share in 2026. By March 2, 2025, Shopee Vietnam reported more than 350,000 cumulative International Platform seller sign-ups for destinations including Thailand, Malaysia, Singapore, the Philippines and Taiwan. Sign-ups at that scale show Vietnamese sellers choosing a single marketplace program for access to 5 named destination markets. For a merchant, access to multiple destinations through that route can reduce the need to establish separate selling relationships in each destination. Retaining platform access becomes commercially more consequential as the seller uses the same relationship to serve additional destination markets.
Social commerce (live, chat) is the fastest-growing segment, with a projected CAGR of 19.2% during 2027-2032. Indonesia's trade minister reported live-shopping interest among 80% of consumers during Harbolnas 2025. The e-Conomy SEA report's 2025 estimate, annualized from the first half of 2025, put median monthly live-video output at 30+ for the top 1,000 creators in Indonesia, Malaysia, the Philippines, Singapore, Thailand and Vietnam. For sellers competing through prominent creators, that production rhythm turns live selling into a recurring content commitment. A continuing selling presence built on repeated product presentations suits cross-border merchants better than reliance on a single live event.
Geography Analysis
Indonesia Southeast Asia Cross-border E-commerce Market
Indonesia held a 34.12% Southeast Asia cross-border e-commerce market share in 2026, making it the largest geography. Harbolnas, held December 10 to 16, 2025, recorded Indonesian online-shopping transaction value up to 17% above the 2024 event. The Indonesian E-Commerce Association organized this national online-shopping event. The stronger event-period spending makes national shopping campaigns a useful timing benchmark for foreign sellers targeting Indonesia's online buyers.
Vietnam Southeast Asia Cross-border E-commerce Market
Vietnam is the fastest-growing geography, with a projected CAGR of 10.9% during 2027-2032. Product sales volume across 4 online platforms in Vietnam reached 2.19 billion products in the first half of 2026, up 13.7% from the first half of 2025. The figures covered Shopee, TikTok Shop, Lazada and Tiki, using Metric.vn and YouNet ECI data reported by VnEconomy. That expanding physical-goods sales base gives sellers an operating route to buyers already purchasing merchandise through established platforms. An overseas brand needs channel access and parcel-handling capacity together if growing platform activity is to become a deliverable cross-border sale.
Thailand requires covered foreign platform operators serving Thai users to notify the Electronic Transactions Development Agency before operation, while Philippine law covers foreign B2B and B2C merchants serving its market with minimum contacts. Malaysia's ePAM instead addresses shipment handling, letting licensed or registered couriers file simplified declarations for multiple importers before air shipments arrive. In a January 2025 Airwallex and Statista survey of 1,000 Singapore-based shoppers who had bought internationally online in the preceding 12 months, 69% bought cross-border at least monthly. Within Rest of Southeast Asia, Cambodia's customs authority and DHL Express Cambodia signed a memorandum on express-parcel information on March 27, 2025. Platform entry and parcel clearance remain separate commercial decisions when choosing routes across these destinations, even where buyers already purchase internationally.
Regulatory Framework and Outlook
The comparison covers selected jurisdictions from the perspective of foreign intermediary platforms selling physical goods across borders. Indonesia's framework, effective June 8, 2026, requires foreign operators' business licensing and, when ministry-team assessment finds any annual consumer, package or internet-traffic threshold met, a representative office holding SIUP3A. Vietnam's e-commerce law imposes structural and registration requirements on covered foreign ordering platforms, subject to coverage tests and treaty commitments. Indonesia's platform duties also include complaint and dispute mechanisms and product-and-fee transparency, extending compliance work beyond initial entry.
Regulatory Table of Southeast Asia Cross-border E-commerce Market
| Decision factor | Indonesia | Vietnam |
|---|---|---|
| Primary authority | Ministry of Trade | Ministry of Industry and Trade |
| Key instruments or direction | Permendag No. 19/2026 and PP 28/2025 | Law on E-Commerce and Decree No. 248/2026/ND-CP |
| Commercial effect | Foreign-platform licensing and conditional representative-office requirements | Covered foreign ordering platforms establish local entities and register, with treaty-specific alternatives |
| Current policy attractiveness | Medium | Low |
| Future direction of policy attractiveness | No change | Hardening |
| Source: Mordor Intelligence | ||
Indonesia's Medium rating reflects licensing, conditional representation and complaint and transparency duties, while the operative June framework and September 22, 2026 team formation for foreign platforms support No change in operating conditions. Vietnam's Low rating reflects the entity requirement for covered foreign ordering platforms before Vietnamese-language display or .vn domain use, or after reaching the transaction threshold. If an applicable treaty bars the entity requirement, platforms must appoint an authorized legal entity in Vietnam, deposit escrow at a commercial bank or foreign bank branch there, and meet platform management conditions. Vietnam's Hardening direction reflects the June 30, 2027 end of profile continuation for websites and applications whose notifications or registrations were confirmed before July 1, 2026.
Value Chain Stages
The comparison separates order intermediation, logistics integration and final delivery by the service each supplier sells. Under Shopee's Philippines terms, applicable transaction and commission fees are deducted from purchase proceeds, with cross-border fees charged to sellers located outside the Philippines. Lazada connects overseas sellers with Southeast Asian customers through a marketplace supported by payment and distribution services. Janio offers cross-border fulfillment, customs and last-mile services in Singapore, Malaysia, Indonesia, Thailand, Vietnam and the Philippines, giving it a service to sell beyond marketplace access.
Value Chain Analysis Table of Southeast Asia Cross-border E-commerce Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Marketplace order intermediation | Marketplace operators such as Shopee and Lazada | Philippines marketplace transaction and applicable commission fees | Separate platform and delivery charges | Establish the combined fee and shipping basis before listing |
| Logistics integration and fulfillment | Fulfillment providers such as Janio and Ninja Van | Fulfillment, customs-handling and logistics service fees | Risk of shipment-data gaps across transport legs | Maintain a shared order and shipment record |
| Final delivery | Last-mile providers such as Janio and Ninja Van | Delivery-service fees | Exposure to unsuccessful recipient handoffs | Confirm delivery details before final dispatch |
| Source: Mordor Intelligence | ||||
For deliveries within the Philippines, Shopee's terms place delivery with the selected logistics provider, while Shopee acts as an intermediary and buyers and sellers bear shipping costs. Ninja Van offers cross-border e-commerce shipping from Malaysia, along with fulfillment and warehousing services. Janio bundles fulfillment, per-country customs, cash on delivery and last-mile services for marketplace sellers under a single service-level agreement. The integrator's value lies in selling a defined obligation across customs and final delivery, giving merchants one party to hold accountable for that combined service.
Competitive Landscape
Market Concentration
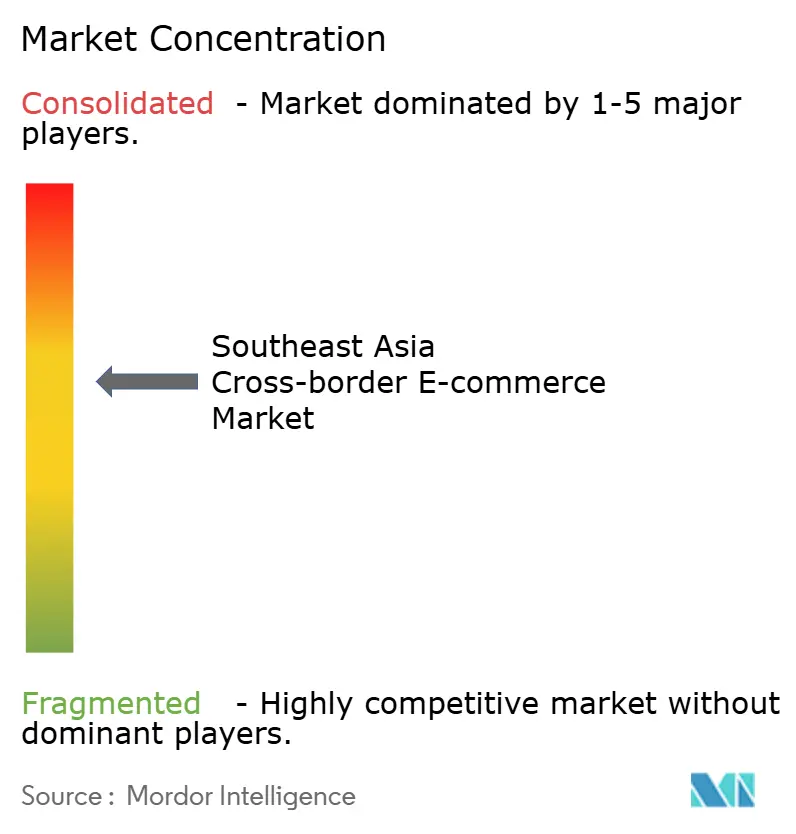
Competition centers on established marketplace ecosystems, including Shopee (Sea Ltd) and Lazada Group (Alibaba). Shopee reported global gross merchandise value of USD 127.4 billion in 2025, up 26.8% year over year.[3] Lazada's cross-border business brings brands and sellers from origins including China, Hong Kong SAR, Korea, Japan, the United States and Europe to Southeast Asian customers. Tokopedia (TikTok) was identified as an established Indonesian marketplace in TikTok's June 2025 description of an integrated seller center for Tokopedia and TikTok Shop. The field combines Shopee's marketplace ecosystem, Lazada's multi-origin cross-border business and Tokopedia's Indonesian base, making geographic coverage a concrete distinction among sellers' platform choices.
The practical strategic question is how a domestic seller can enter another destination through the platform relationship it already uses. On October 13, 2025, Shopee Malaysia announced its Rai Lokal growth package for micro, small and medium-sized enterprises. The announcement described its International Platform and Direct Programme as complementary initiatives enabling those sellers to reach Singapore, Thailand and the Philippines through Shopee's logistics and payments. A challenger must offer a credible route from merchant enrollment to overseas listing to win exporters already using a regional platform.
Bukalapak announced that it would phase out physical-goods marketplace sales from January through February 2025 and focus on virtual products and services. The Singapore High Court ordered Qoo10 Pte Ltd wound up and appointed liquidators on November 11, 2024, and a January 2025 liquidator notice identified it as in liquidation. Indonesia's framework, effective June 8, 2026, sets annual foreign-platform representation thresholds of 1,000 consumers, 1,000 packages or 1% of domestic internet users. Platforms assessed by a ministry-formed team as meeting any threshold must appoint a representative office holding the SIUP3A trade license. Bukalapak's announced physical-goods exit and Qoo10 Pte Ltd's January 2025 liquidation status make service continuity a channel-selection issue for Indonesian sellers, alongside qualifying foreign operators' duty to appoint a representative office holding SIUP3A.
Southeast Asia Cross-border E-commerce Industry Leaders
-
Shopee (Sea Ltd)
-
Lazada Group (Alibaba)
-
Tokopedia (TikTok)
-
Bukalapak
-
Qoo10 Pte Ltd
- *Disclaimer: Major Players sorted in no particular order
Southeast Asia Cross-border E-commerce Market Companies Covered in this Report
- Shopee (Sea Ltd)
- Lazada Group (Alibaba)
- Tokopedia (TikTok)
- Bukalapak
- Qoo10 Pte Ltd
- JD.com Inc (JD.ID)
- eBay Inc
- AliExpress
- Shopify Inc
- Blibli (PT Global Digital Niaga)
- Tiki Corp
- Zalora (Global Fashion Group)
- Carousell Pte Ltd
- Sendo Joint Stock Co
- SHEIN
- Temu (PDD Holdings)
- ezbuy (LightInTheBox)
- Wish (Qoo10 Pte Ltd)
- Global-e Online Ltd
Read Analysis of Southeast Asia Cross-border E-commerce Companies
Key Opportunities for Market Participants
The opportunities compare 3 merchandising plays for foreign sellers serving Vietnamese buyers under the new platform-governance framework. The law, effective July 1, 2026, requires intermediary platform owners to verify seller identities before sales, using legal documents for foreign sellers. Platforms must also screen seller-generated listings before display to prevent illegal sales, counterfeits, intellectual property infringement, smuggled goods and goods of unknown origin. The proposed plays target Vietnamese beauty, apparel and electronics shoppers seeking identifiable sellers and traceable imported goods, giving foreign merchants a reason to prioritize assortments they can document for platform review.
Market Opportunities Table of Southeast Asia Cross-border E-commerce Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Documented beauty-brand entry | Foreign-seller verification before first sale | Vietnamese beauty and personal care shoppers | Prepare legal-identity records for platform onboarding | Verification must precede selling | Foreign beauty brands able to document legal identity |
| Authentic branded apparel assortments | Pre-display counterfeit and rights screening | Imported fashion and apparel shoppers in Vietnam | Support branded offers with traceable rights | Counterfeit or intellectual-property risk during listing review | Rights-holding apparel brands and authorized distributors |
| Origin-documented electronics offers | Screening of smuggled or unknown-origin goods | Vietnamese consumer electronics buyers | Build imported assortments with documented origin | Origin ambiguity at listing review | Electronics exporters with traceable supply |
| Source: Mordor Intelligence | |||||
The central opening is to offer those shoppers a documented imported range that can enter seller admission and listing review under the July 2026 framework. The platform owns the statutory checks, while merchants can improve the quality of the identity, rights and origin information behind their goods. Where an exporter must choose between product breadth and traceability, a documented initial assortment offers a practical way to address admission and listing checks before expanding the range.
Recent Industry Developments in Southeast Asia Cross-border E-commerce Market
- Jul 2026: Vietnam's Law on E-Commerce and implementing Decree No. 248/2026/ND-CP took effect on July 1, covering e-commerce activities including cross-border commerce.
- Jun 2026: Lazada announced return-shipping fees for its Southeast Asian cross-border sites with a stated July 2 start. Qualifying orders required confirmed receipt, an initiated return and refund, physical return to Lazada's inspection warehouse or the merchant, and platform approval. Change-of-mind returns were exempt, with fee refunds available if verification found the merchant was not at fault.
- Jun 2026: Indonesia's Ministry of Trade promulgated Permendag No. 19/2026 on June 8, replacing the 2023 regulation on trade through electronic systems.
Southeast Asia Cross-border E-commerce Market Report Scope and Research Methodology
Market Definition and Coverage
The Southeast Asia cross-border e-commerce market measures annual value of physical goods bought online by businesses or consumers from sellers based outside the buyer's Southeast Asian country, with orders crossing a customs border before delivery. It covers purchases through online marketplaces, seller webstores and social commerce.
Scope exclusions: Digital-only services and downloads, domestic e-commerce orders, bulk wholesale freight movements not routed as e-commerce parcels, and separately sold logistics, payment or fulfillment services are excluded.
Segments Covered in This Report
- By Business Model
- B2C
- B2B
- By Product Category
- Fashion and Apparel
- Consumer Electronics
- Home Appliances
- Furniture
- Beauty and Personal Care
- Toys, Food and Others
- Others
- By Sales Channel
- Online Marketplaces
- Direct-to-Consumer (Webstores)
- Social Commerce (Live, Chat)
- By Geography
- Indonesia
- Thailand
- Vietnam
- Philippines
- Malaysia
- Singapore
- Rest of Southeast Asia
Data Sources, Market Sizing, and Validation
Desk Research
The analyst uses sources such as the U.S. International Trade Administration's Southeast Asia Region Forecast for country market context and channel behavior, the e-Conomy SEA research summarized by Google for regional digital-commerce indicators, Citi's cross-border shopper study for purchase barriers and payment preferences, and DBS's regional e-commerce report for sector sales and country conditions. These sources supply country context, channel behavior, purchase barriers and payment preferences that inform the segment and country allocation.
Company filings, annual reports, investor presentations and reputable regional business press can clarify platform activity, market entry, order channels and fulfillment arrangements, with cross-checks against public trade and regulatory information. The named sources are illustrative and not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Structured interviews and surveys may include Southeast Asian online sellers, marketplaces, logistics providers, payment firms and trade specialists, including commercial, operations, customs and research leaders. Questions test secondary evidence on transaction boundaries, buyer and seller locations, channels, product mix, delivery routes and destination-country differences. Where evidence is incomplete or conflicting, analysts document the gap, compare independent source types and use respondent explanations to assess whether the available signals fit the market definition.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 34% | CXOs: 20% | |
| Mid tier: 41% | Functional/Unit leaders: 35% | |
| Smaller Players: 25% | Managers: 45% |
Market-Sizing & Forecasting
A top-down estimate sets the annual value of qualifying online cross-border physical-goods purchases delivered across Southeast Asian customs borders, then allocates that total across business model, product category, sales channel and destination country using evidence on each view. Relevant indicators include regional e-commerce sales and GMV as context, cross-border shopper incidence and spending from surveys, platform cross-border order or seller activity, customs and tariff conditions, and country-level online purchasing and logistics signals. These indicators test market scale, growth direction and distribution across countries and segments. Analysts can apply multivariate regression where comparable historical indicators support relationships with market growth, then use scenario analysis to reflect country-specific policy, payment and fulfillment changes. Missing observations are bridged with the closest supported regional or country series and checked against the defined transaction boundary. Selective bottom-up checks can compare sampled seller or platform order activity and representative transaction values with the top-down view, while gaps in coverage are recorded and bounded using independent public evidence. Primary experts can review whether the chosen indicators, country shares and forecast directions reflect current selling and delivery conditions, with unresolved differences returned for clarification before estimates are finalized.
Data Validation & Update Cycle
Analysts triangulate market totals and segment shares across independent public research, company disclosures, trade indicators and primary evidence, while checking that every input measures the same goods order, geography and year. Variances, outliers, double counts and abrupt share movements are investigated against source definitions and country developments, documented, and reviewed by another analyst before sign-off. Re-contact is triggered when an interview conflicts with a material source or leaves a market-boundary question unresolved. The evidence and forecast are refreshed annually, reviewed between cycles after material regulatory or commercial events, and checked in a fresh pre-delivery pass.
Mordor Intelligence's Southeast Asia Cross Border E Commerce Market Size Compared With Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The Southeast Asia cross-border e-commerce market measures annual value of physical goods bought online by businesses or consumers from sellers based outside the buyer's Southeast Asian country, with orders crossing a customs border before delivery.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Relevant indicators include regional e-commerce sales and GMV as context, cross-border shopper incidence and spending from surveys, platform cross-border order or seller activity, customs and tariff conditions, and country-level online purchasing and logistics signals.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 55.9 B (2027) | |
| Global Consultancy A | USD 45.39 B (2025) | At its 2025 base, this estimate is 18.8% below this report's 2027 value of USD 55.9 B, 2 years later. Its 2025 estimate is below the report's 2027 figure, consistent with the earlier measurement year. The page describes online cross-border retail of consumer goods, while this report specifically counts physical goods crossing a customs border. |
| Global Consultancy B | USD 49.7 B (2022) | At its 2022 base, this estimate is 11.1% below this report's 2027 value of USD 55.9 B, 5 years later. The older 2022 transaction-value observation can be lower as regional cross-border online goods sales expand over time. The cited overview does not further detail product or channel coverage. |
Mordor Intelligence's analysts triangulate market totals and segment shares across independent public research, company disclosures, trade indicators and primary evidence, while checking that every input measures the same goods order, geography and year.
Key Questions Answered in the Report
What is the Southeast Asia cross-border e-commerce market size and growth outlook?
The size was USD 50.37 billion in 2026 and is estimated at USD 55.9 billion in 2027, reaching USD 92.43 billion by 2032. The forecast CAGR is 10.58% during 2027-2032.
What supports Southeast Asian demand for goods sold online from abroad?
Video-led selling and eligible tariff preferences support the outlook. TikTok Shop Southeast Asia Cross-Border E-commerce reported short-video-driven GMV up 257% year over year during Double 12 in 2025.
Which business model leads Southeast Asia's cross-border online goods sales?
B2C led with a 78.5% share in 2026 and is projected to grow at a CAGR of 11.12% during 2027-2032.
Which companies are central to Southeast Asia's cross-border retail competition?
Shopee (Sea Ltd) and Lazada Group (Alibaba) provide established platform routes. Tokopedia (TikTok) was identified as an established Indonesian marketplace in TikTok's June 2025 seller-center description.
What challenges affect overseas goods sellers serving Southeast Asian shoppers?
Tax differences and return-shipping exposure can constrain margins. In Malaysia, the qualifying air-courier exemption depends on cost, insurance and freight value, while road imports do not qualify.
Which country leads cross-border goods e-commerce in Southeast Asia?
Indonesia led with a 34.12% share in 2026. Vietnam is the fastest-growing geography, with a projected CAGR of 10.9% during 2027-2032.