
Saudi Arabia Pet Insurance Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
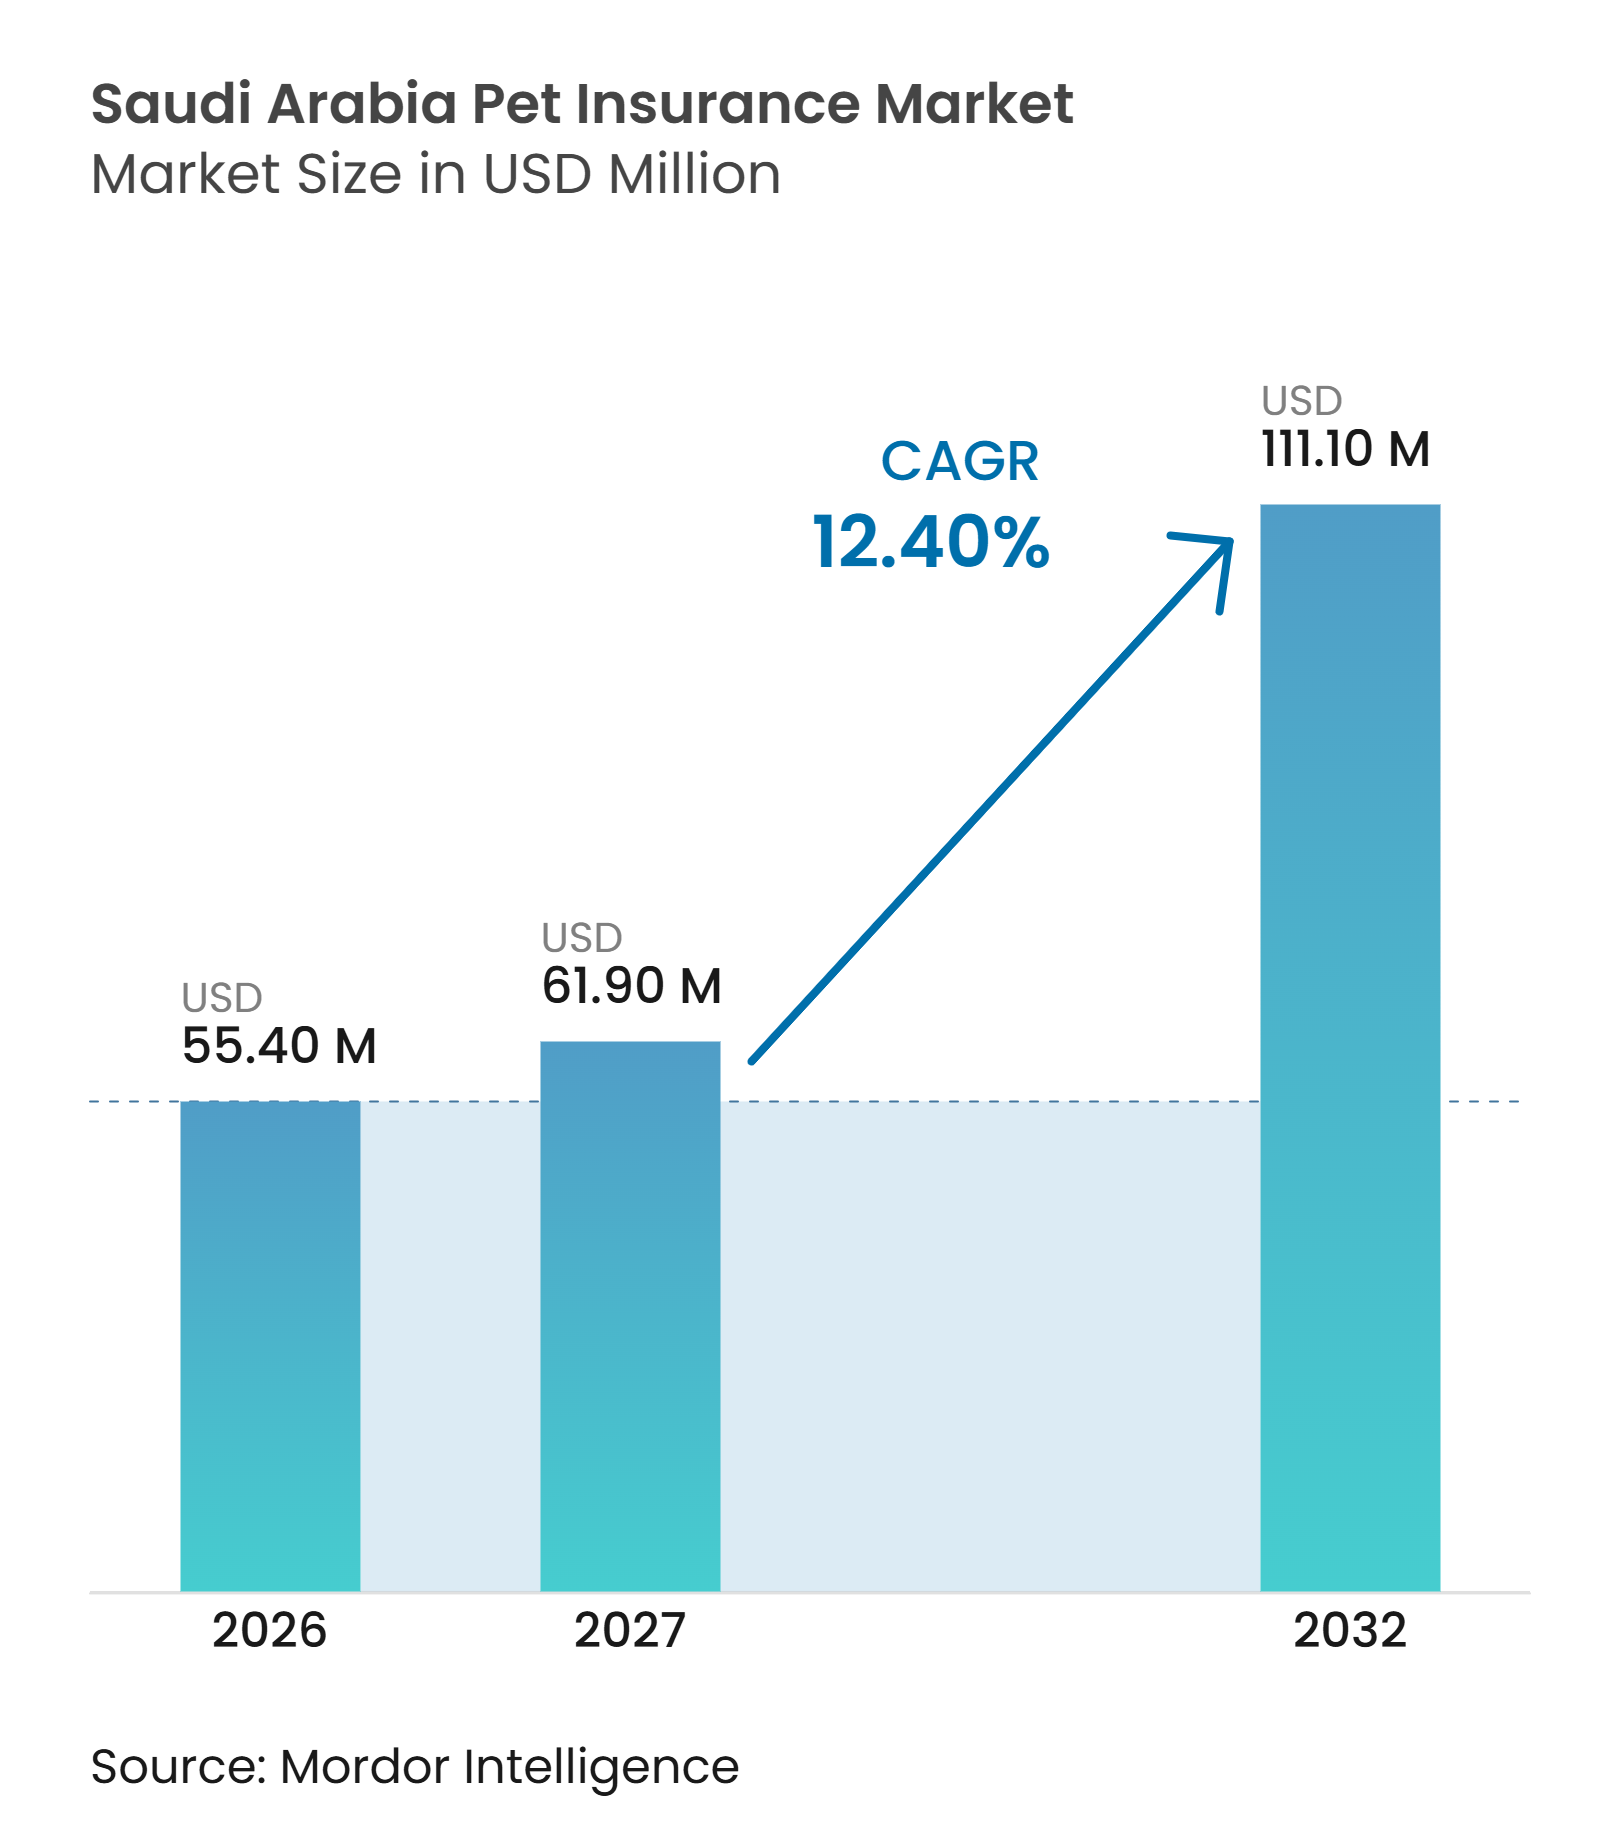
| Base Year Market Size (2026) | USD 55.40 Million |
| Market Size (2027) | USD 61.90 Million |
| Market Size (2032) | USD 111.10 Million |
| Growth Rate (2027 - 2032) | 12.40 % |
| Market Concentration | High |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Saudi Arabia Pet Insurance Market Analysis by Mordor Intelligence
The Saudi Arabia Pet Insurance Market size is projected to be USD 55.40 million in 2026, USD 61.90 million in 2027, and reach USD 111.10 million by 2032, growing at a CAGR of 12.40% from 2027 to 2032.
The category remains new, following Tree Digital Insurance Agency's 2024 launch of the Kingdom's first licensed pet insurance product. The Insurance Authority's preliminary approval for Melon Digital Insurance in January 2026 indicates that the field is beginning to draw another digital-focused participant. The Saudi Arabia pet insurance market is shaped by the simultaneous expansion of pet ownership, veterinary services, and online insurance access. These conditions give insurers room to build awareness while improving their pricing models as claims experience develops. Early competition is likely to focus on product access, veterinary documentation, and trust in claims handling rather than on broad price competition alone.
Key Report Takeaways
- By policy type, the accident & illness segment captured 65.4% of the Saudi Arabia pet insurance market share in 2026, while accident and illness plans are projected to grow at a 16.5% CAGR through 2032.
- By coverage architecture, basic and entry tiers accounted for 58.1% of the Saudi Arabia pet insurance market size in 2026, while comprehensive caps are forecast to expand at a 17.2% CAGR through 2032.
- By animal type, cats held a 73.2% share of the Saudi Arabia pet insurance market in 2026 and are projected to grow at a 12.8% CAGR through 2032.
- By distribution channel, direct digital channels held 84.8% of the Saudi Arabia pet insurance market share in 2026, while broker, MGA, and carrier channels are forecast to grow at a 14.8% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Saudi Arabia Pet Insurance Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Pet Ownership and Pet Humanization | +2.3% | National, concentrated in Riyadh, Jeddah, and Dammam | Medium term (2-4 years) |
| Demand for Advanced Veterinary Care | +2.1% | Riyadh and Jeddah core markets | Medium term (2-4 years) |
| Rising Veterinary Treatment Expenses | +1.8% | National | Short term (≤ 2 years) |
| Digital Insurance Distribution and Administration | +2.4% | National, with early gains in Riyadh | Short term (≤ 2 years) |
| Wider Availability of Accident and Illness Coverage | +1.5% | National | Medium term (2-4 years) |
| Expansion of Veterinary Clinics and Specialized Services | +1.2% | Riyadh, Jeddah, and Eastern Province | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Rising Pet Ownership and Pet Humanization
Saudi Arabia's pet population increased from approximately 800,000 in 2020 to 2.4 million in 2023, reflecting growing companion-animal ownership and changing attitudes toward dogs alongside the established cat-owning population. This expanding customer base creates opportunities for pet insurance, particularly in major urban centres such as Riyadh, Jeddah, and Dammam. The Ministry of Environment, Water and Agriculture sponsored the third Saudi Pet & Vet Expo in November 2025, which featured more than 120 exhibitors from 16 countries[1]. Greater pet ownership and awareness of animal welfare are expanding the potential demand for accident, illness, and veterinary-care coverage.
Increasing Demand for Advanced Veterinary Care and Treatment
Saudi Arabia's veterinary infrastructure is expanding, with 734 private veterinary clinics, 1,709 veterinary pharmacies, 181 government veterinary clinics and branches, and 2,912 licensed private veterinarians reported in the 2025 veterinary infrastructure assessment[1]. In 2025, Saudi Teriaq Veterinary established One Health Teriaq Vet Lab, an integrated diagnostic laboratory in Jeddah, strengthening access to veterinary diagnostics in the western region. Increasing access to laboratory testing and specialized veterinary services can raise treatment complexity and potential claims costs, supporting demand for broader accident and illness coverage.
Rising Veterinary Treatment Expenses Driving Demand for Financial Protection
The growing availability of veterinary diagnostics, specialist consultations, and surgical procedures increases the potential financial burden on pet owners, particularly when unexpected treatment is required. The expansion of veterinary services creates an opportunity for insurers to offer tiered coverage, including accident protection, illness treatment, diagnostics, and surgical expenses. Competitive pricing, transparent exclusions, and appropriate claims limits will be important for encouraging first-time policyholders while managing rising treatment costs.
Digitalization of Pet Insurance Distribution and Policy Administration
Saudi Arabia approved its InsurTech Rules in July 2023, establishing a regulatory framework for technology-enabled insurance activities. The Insurance Authority launched its TAMEEN digital services portal in February 2025 and introduced 15 additional services in December 2025, including electronic sales, product registration, and electronic integration[2]. Separately, Tree Digital Insurance Agency partnered with Aseel Pet App to expand digital access to pet insurance and veterinary-care services. These developments support digital policy distribution, customer acquisition, and integration with pet-care platforms.
Restraints Impact Analysis of Saudi Arabia Pet Insurance Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Limited Consumer Awareness and Low Adoption | -1.5% | National | Short term (≤ 2 years) |
| Premium Affordability and Price Sensitivity | -1.3% | National, with higher sensitivity outside key urban centers | Medium term (2-4 years) |
| Pre-Existing Condition Exclusions and Veterinary Eligibility | -0.8% | National | Medium term (2-4 years) |
| Limited Insurer and Product Availability | -0.7% | National, outside Riyadh | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Limited Consumer Awareness and Low Pet Insurance Adoption
Pet insurance remains an emerging product category in Saudi Arabia, with Tree Digital Insurance Agency launching the Kingdom's first licensed pet insurance product in September 2024, covering veterinary treatment, surgeries, and medications for cats and dogs. As a relatively new offering, limited familiarity with policy benefits, exclusions, waiting periods, and claims procedures may constrain adoption, particularly among first-time buyers. The Insurance Authority's consumer-protection mandate and complaint-handling mechanisms provide a regulatory foundation for building customer confidence. Wider education through veterinary clinics, pet-care platforms, and digital channels will be essential to expand awareness and encourage adoption.
Premium Affordability and High Price Sensitivity Among Pet Owners
Pet insurance adoption may be constrained by the additional cost of premiums alongside recurring expenses for pet food, grooming, vaccinations, and veterinary treatment. Saudi Arabia's cooperative insurance framework requires insurers to operate under regulated risk-pooling and financial requirements. Flexible coverage tiers, deductibles, co-payments, and instalment options could improve affordability and broaden customer reach. The Insurance Authority's draft Insurance Law, published for consultation in June 2025 with comments closing on 22 July 2025, proposed reforms covering licensing, policyholder protection, digital insurance, and regulatory supervision.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Saudi Arabia Pet Insurance Market Segment Analysis
By Policy Type:
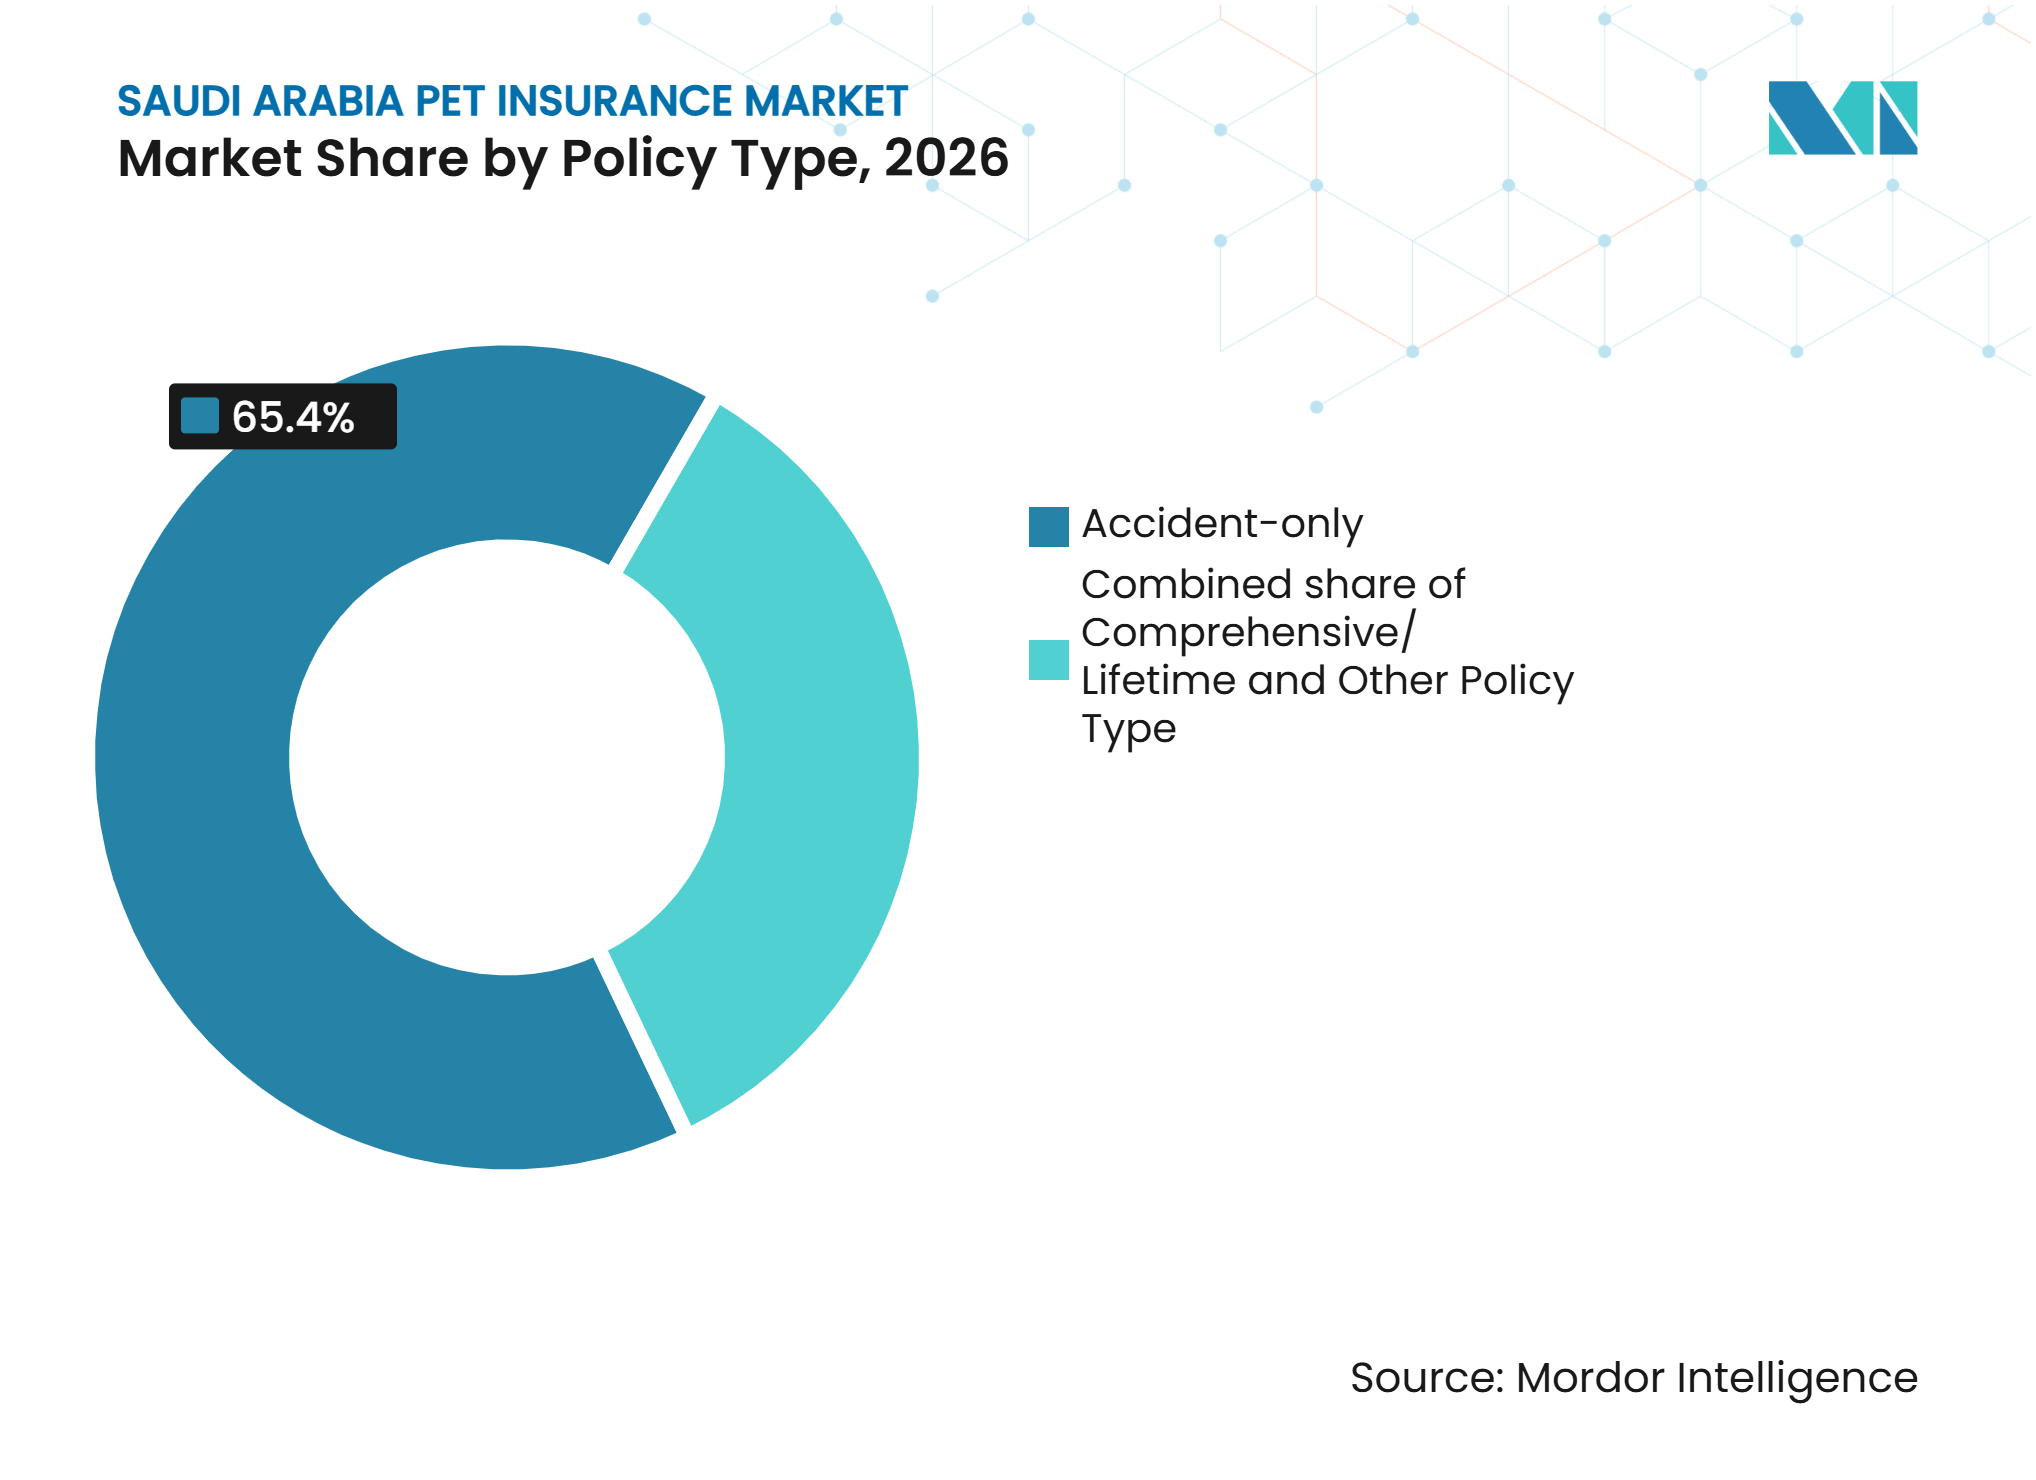
Digital-First Policyholders Begin with Accident CoverThe accident & illness segment accounted for an estimated 65.4% share in 2026, making them the leading policy category in Saudi Arabia's emerging pet insurance market. These policies appeal to first-time buyers seeking protection against unexpected injuries at relatively accessible coverage levels. Tree's FurBasic plan provides an example of this entry-level approach, covering accident-related veterinary expenses with a veterinary-fee limit of SAR 5,000 (USD 1,333). Accident and illness plans are projected to record the fastest growth, at a 16.5% CAGR from 2027 to 2032, as owners increasingly consider protection against infections, chronic conditions, and other medical expenses. Tree's FurDeluxe plan already combines accident and illness coverage, demonstrating the availability of broader protection in the market.
Comprehensive and lifetime products remain less established, with higher coverage limits and potential premiums creating affordability challenges for customers. Tree's FurRoyal plan offers comprehensive accident and illness protection with veterinary expenses covered up to SAR 20,000 (USD 5,333). However, lifetime coverage should not be treated as an established standalone product category without supporting policy documentation. Preventive services, including vaccinations, routine check-ups, and microchipping, are not covered under Tree's published policy. Saudi Arabia's animal identification requirements and veterinary licensing framework can improve animal records and claims verification, creating opportunities for more specialized products over time.


By Coverage Architecture:
Entry Tiers Lead While Comprehensive Caps ExpandBasic and entry-tier plans accounted for an estimated 58.1% share in 2026, reflecting demand for affordable protection focused on emergency treatment and accident-related veterinary expenses. These plans provide an accessible starting point for first-time policyholders, while mid-tier products introduce broader illness coverage and higher benefit limits. Comprehensive coverage is projected to grow at a 17.2% CAGR through 2032, supported by increasing access to advanced veterinary diagnostics and treatment. Tree's three-tier structure, comprising FurBasic, FurDeluxe, and FurRoyal, illustrates how insurers can differentiate products through veterinary-fee limits of SAR 5,000 (USD 1,333.33), SAR 10,000 (USD 2,666.67), and SAR 20,000 (USD 5,333.33), respectively.
Higher coverage tiers can generate greater premium value. The Ministry of Municipalities and Housing updated veterinary-care facility requirements in September 2025, covering licensing approvals, operational standards, electronic payment facilities, and QR-code identification. These requirements can strengthen documentation and operational consistency across veterinary providers, supporting claims administration and the development of higher-limit insurance products.
By Animal Type:
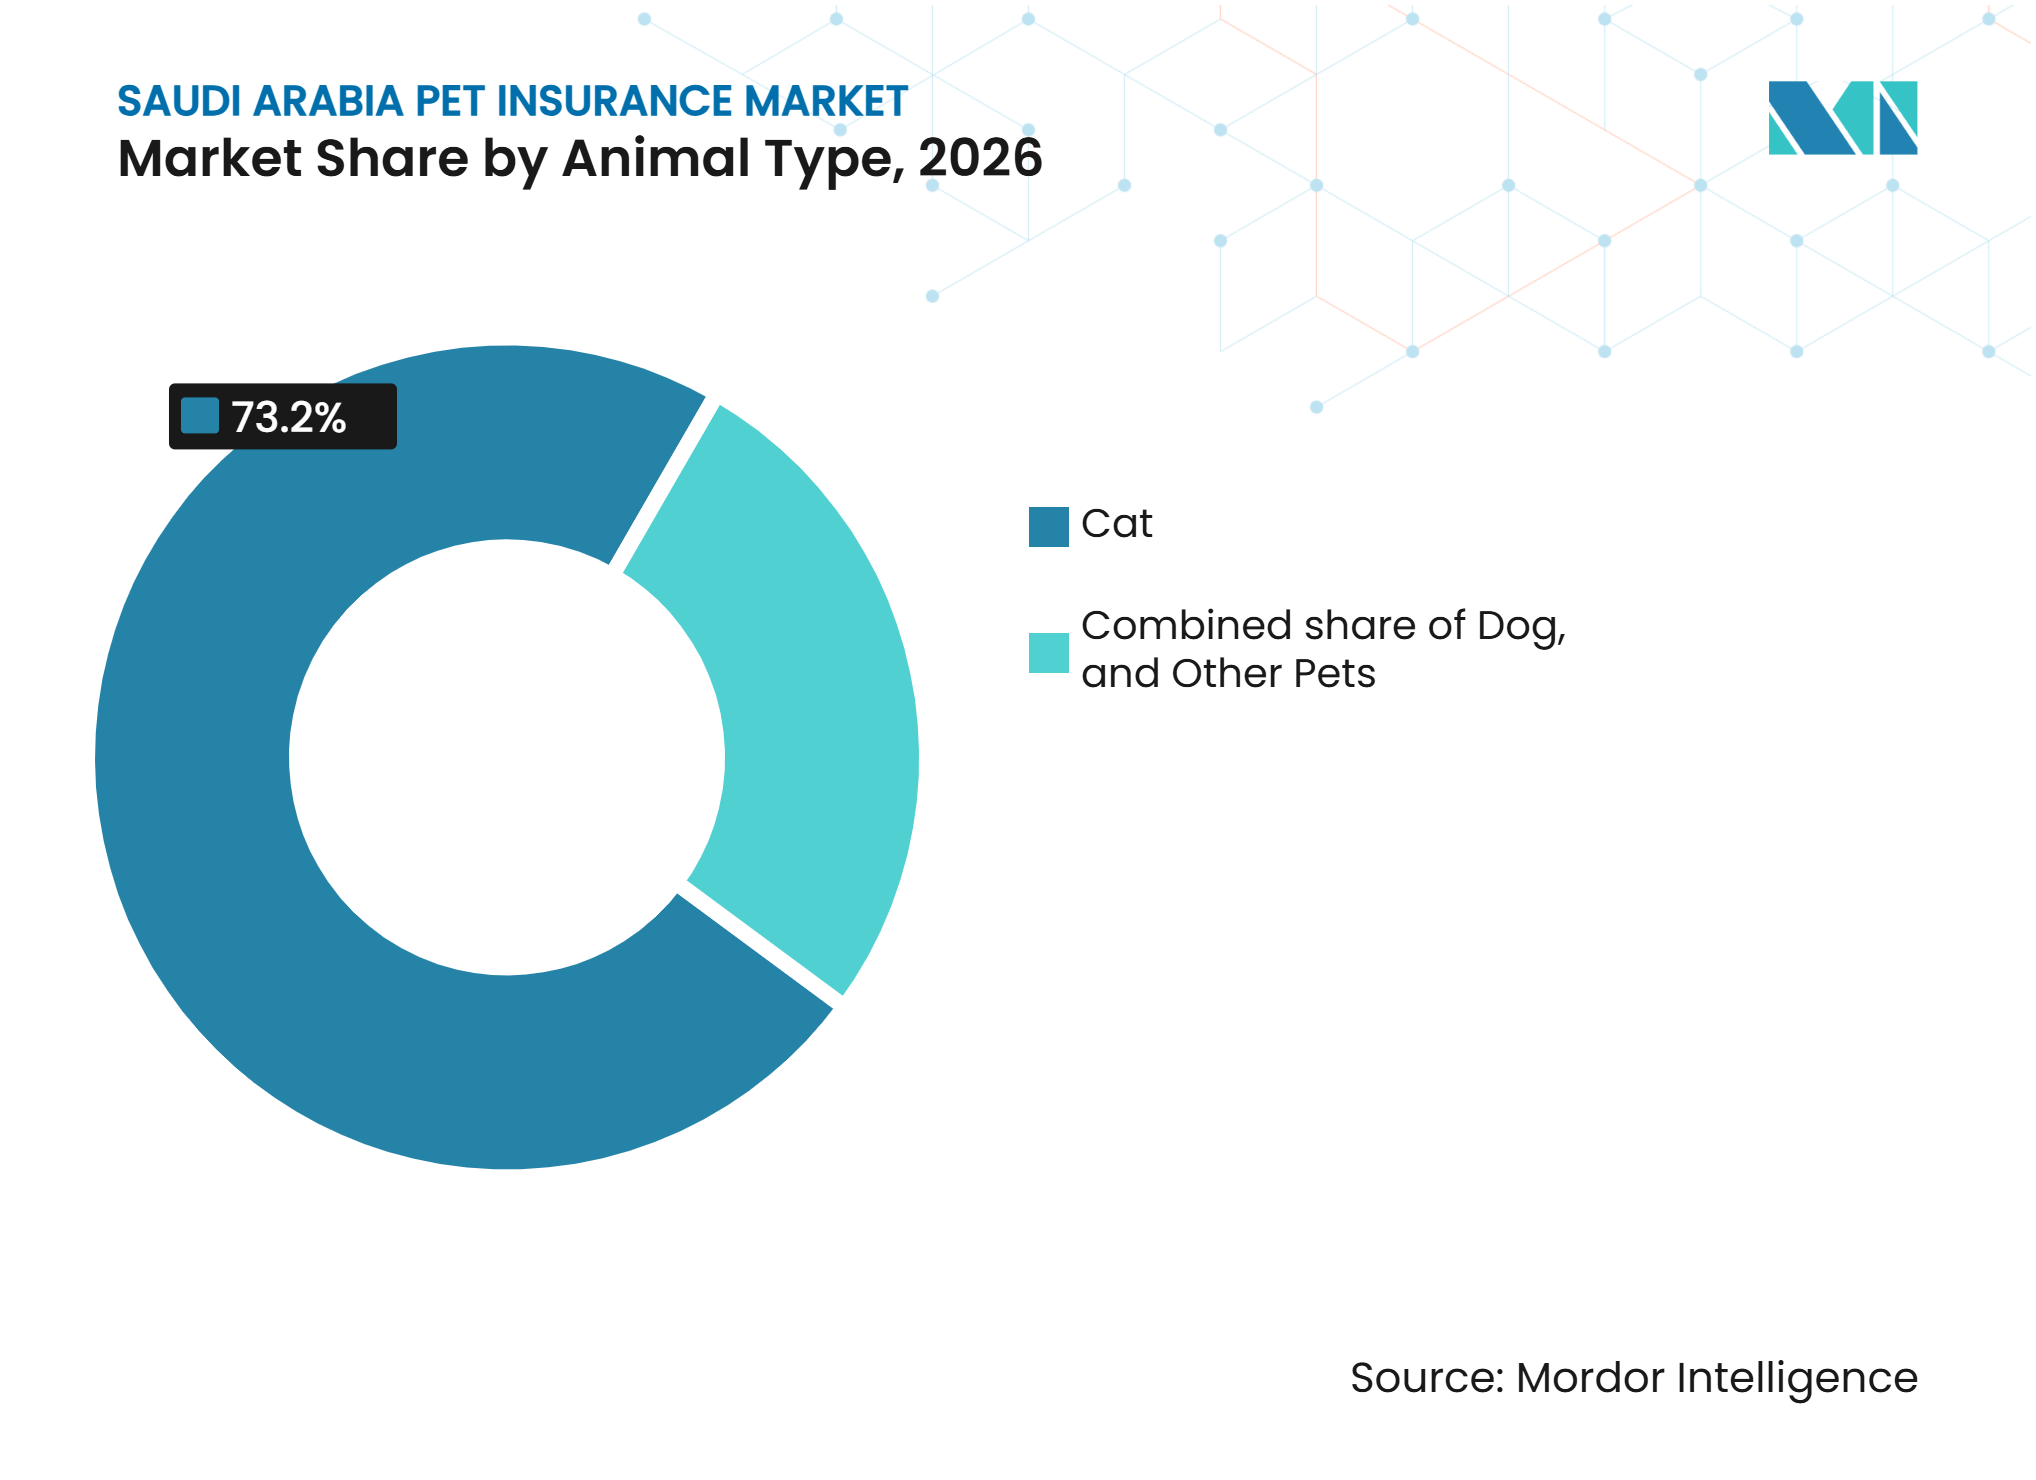
Cats Anchor Current Premium DemandCats accounted for an estimated 73.2% share in 2026 and are projected to grow at a 12.8% CAGR through 2032, reflecting their established presence in Saudi households and the early focus of local pet insurance offerings. Tree's published insurance products cover cats and dogs, providing veterinary treatment protection across accident-only and broader illness plans. Persian cats, Siamese cats, and Arabian Maus represent potential customer niches for tailored coverage.
Dog insurance represents an additional opportunity as pet-friendly infrastructure and public acceptance develop. Saudi Arabia's public-transport regulations permit small pets to travel in appropriate carriers, subject to safety requirements and transport-operator policies. Import and export procedures also require veterinary health documentation and animal identification through electronic microchips or other approved identification methods. Birds, exotic animals, and equines remain potential specialist segments.

By Distribution Channel:
Direct Digital Retains a Clear LeadDirect digital channels accounted for an estimated 84.8% share in 2026, reflecting the importance of mobile-based quotations, electronic policy issuance, and digital customer servicing in this emerging market. Tree's online platform allows customers to obtain personalized quotations based on pet age, breed, and coverage selection. The Insurance Authority's TAMEEN portal, launched in February 2025, subsequently added 15 digital services in December 2025, including electronic sales and electronic integration. These initiatives strengthen the regulatory and technological infrastructure supporting digital insurance distribution.
Broker, MGA, and carrier channels are projected to grow at a 14.8% CAGR through 2032, providing opportunities for insurers to expand through partnerships and specialized distribution networks. Melon received preliminary approval from the Insurance Authority in January 2026 to establish a digital insurance agency. Its November 2024 partnership with AIFT was intended to support the development of digital pet insurance solutions in Saudi Arabia. Veterinary clinics, pet-care applications, bancassurance, and employer-linked distribution also offer potential customer-acquisition channels as the market develops.
Geography Analysis
Riyadh
Riyadh is the primary commercial and product-development centre for Saudi Arabia's emerging pet insurance market. The city recorded 451 registered pet-care businesses by the end of H1 2024, the highest among Saudi regions, compared with 309 in the Makkah Region and 125 in the Eastern Province. Tree Digital Insurance Agency is headquartered in Riyadh and launched Saudi Arabia's first licensed pet insurance product in September 2024, establishing the city as an early centre for product distribution and customer acquisition. The concentration of veterinary businesses and digital insurance infrastructure supports initial product development, premium benchmarking, and claims-data collection.
Jeddah and the Western Region
Jeddah is an important secondary market, supported by its large urban population and expanding veterinary infrastructure. Saudi Teriaq Veterinary established One Health Teriaq Vet Lab in Jeddah in 2025, identifying it as the first integrated veterinary diagnostic laboratory in the Western Region. The facility strengthens access to veterinary diagnostic services and supports more comprehensive clinical assessment. The wider Makkah Region recorded 309 registered pet-care businesses in H1 2024, ranking second nationally. These developments create opportunities for insurers to expand veterinary partnerships, distribute illness and accident coverage, and reach customers beyond Riyadh.
Eastern Province and Secondary Cities
The Eastern Province offers additional growth opportunities through expanding animal-welfare initiatives and veterinary services. Saudi Aramco launched Olfa Animal Welfare in August 2024, with mobile veterinary clinics planned for the Eastern Region and its first animal shelter planned for Dammam in 2025. During its first operational year in 2025, Olfa treated more than 11,000 animals, demonstrating increased investment in animal welfare and veterinary access. The Eastern Province recorded 125 registered pet-care businesses in H1 2024. Makkah, Madinah, Asir, and Tabuk also offer potential for future insurance distribution as veterinary infrastructure and consumer awareness expand. National veterinary facility requirements updated in September 2025 apply across these locations, supporting more consistent operating and documentation standards.
Competitive Landscape
Market Concentration
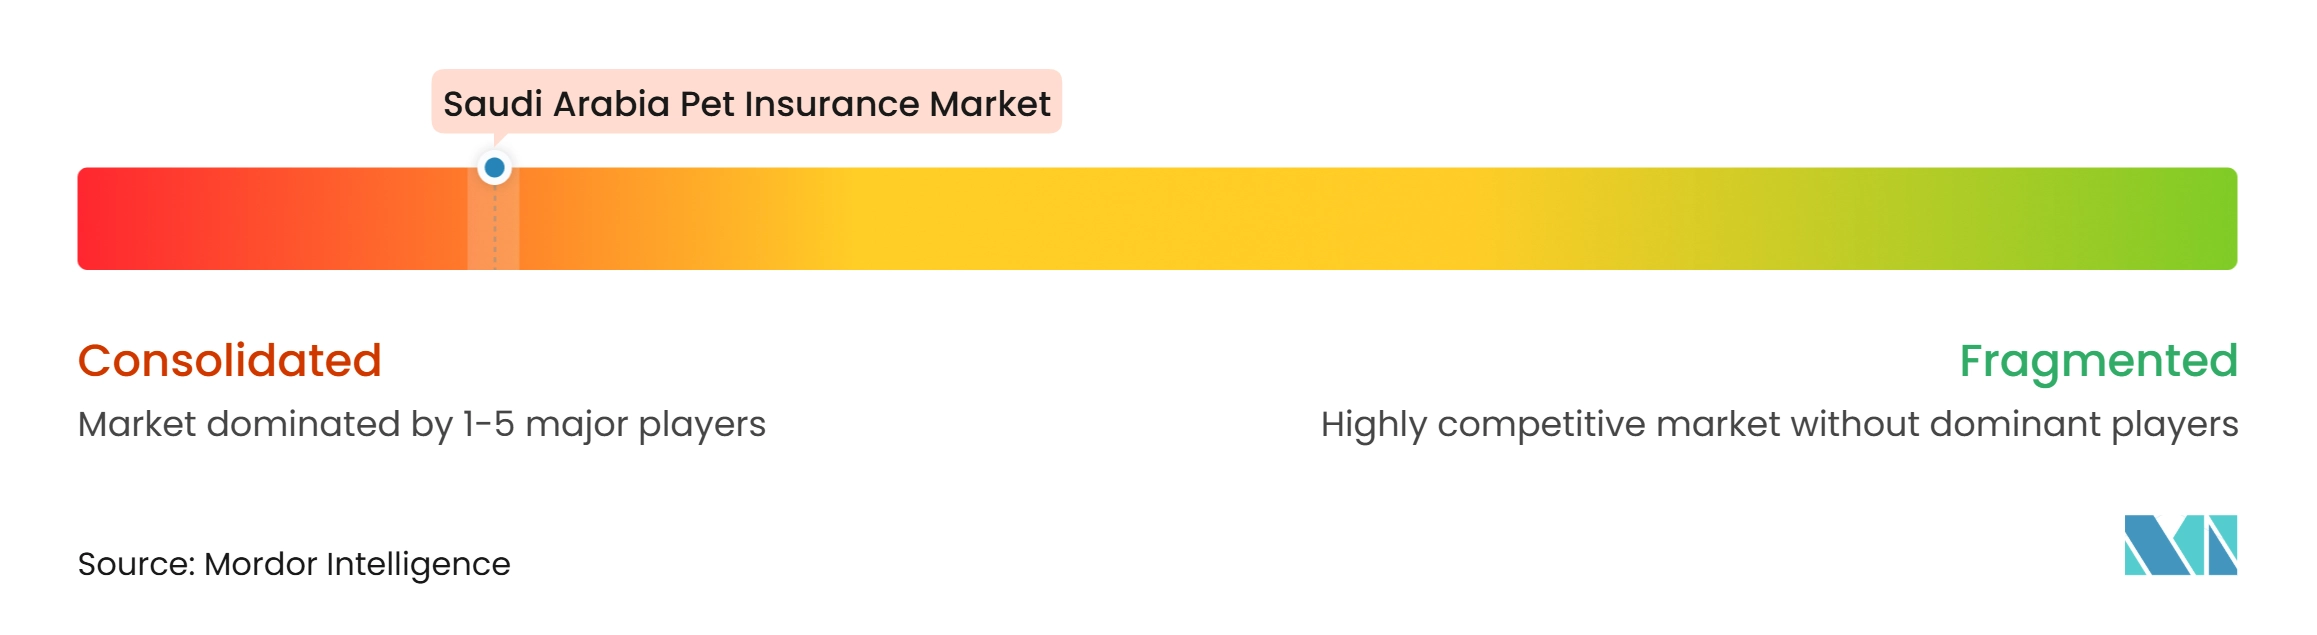
Tree Digital Insurance Agency holds the leading first-mover position because it launched the Kingdom's first licensed pet insurance product in 2024. It is a wholly owned Tawuniya subsidiary and operates within a market that had only 1 active licensed pet insurance provider during its initial period. Tree's position benefits from its early digital operating model and its ability to develop product awareness before competitors launch. The Insurance Authority's licensing framework and cooperative insurance rules have created a formal barrier to entry that limits casual participation. The approval pathway for Melon and the authorization of digital brokerage activity show that this controlled structure is beginning to admit more technology-led participants. The Saudi Arabia pet insurance market is therefore concentrated today, but its competitive structure is likely to change as licensed agencies complete their launch requirements.
Tree has pursued platform integration through its partnership with the Aseel pet app, linking insurance with veterinary clinics, pet food suppliers, and care services used by pet owners. This model can lower customer acquisition costs and keep the insurance offer close to the point where care decisions occur. Melon has paired its market entry plans with AIFT's IXT platform, which brings specialized technology and established-market experience to local product development. Insurance House Company and Lonsdale and Associates can provide intermediary routes to commercial clients and high-net-worth individuals. These routes differ from Tree's direct digital focus and may be more relevant for tailored or higher-value cover. The areas with the clearest room for product development are customizable cat-focused plans, preventive wellness add-ons, and claims services integrated with veterinary records.
Regulatory changes will influence which insurers can compete effectively as the category expands. The Insurance Authority revoked 28 brokerage and agency licenses in 2025, indicating closer attention to the quality and compliance of market participants. It also introduced digital services through TAMEEN, making electronic integration a more practical requirement for agencies and carriers. Salama Cooperative Insurance and Saudi Enaya received permission to merge in June 2025, creating a larger entity with the potential to consider emerging lines once its merger process is complete. Tree's recognition at the Global Brand Awards in December 2025 also shows that brand standing is becoming relevant before the market has broadened materially. Competitive success will depend on credible pricing, connected service networks, and the ability to explain coverage clearly as more choices become available.
Saudi Arabia Pet Insurance Industry Leaders
-
Tree Digital Insurance Agency
-
Melon
-
The Company for Cooperative Insurance (Tawuniya)
-
Bupa Arabia for Cooperative Insurance Company
-
Gulf Insurance Group Saudi Arabia
- *Disclaimer: Major Players sorted in no particular order
Saudi Arabia Pet Insurance Market Companies Covered in this Report
- Tree Digital Insurance Agency
- The Company for Cooperative Insurance (Tawuniya)
- Melon Digital Insurance
- Bupa Arabia for Cooperative Insurance Company
- Gulf Insurance Group (GIG Saudi Arabia)
- Al Rajhi Takaful
- Allianz Saudi Fransi Cooperative Insurance
- MEDGULF
- Walaa Cooperative Insurance
- Arabian Shield Cooperative Insurance
Recent Industry Developments in Saudi Arabia Pet Insurance Market
- January 2026: Melon Digital Insurance received preliminary IA approval to establish a digital-first insurance agency in Saudi Arabia, with pet insurance as its initial product focus. The company, backed by AIFT's InsurTech platform IXT, is completing final licensing requirements ahead of commercial launch.
- November 2025: The IA licensed Riyadh Re, a wholly owned subsidiary of Tawuniya, to operate as a reinsurance company. With capital of SAR 550 million (USD 146.6 million), Riyadh Re strengthens domestic reinsurance capacity alongside Saudi Re.
- November 2025: The IA announced the transition to a risk-based capital (RBC) framework, with parallel implementation in 2026 and full implementation from 1 January 2027. The framework aligns insurers' capital requirements more closely with their risk exposures.
- November 2025: The IA proposed amendments to Article 44 of the Implementing Regulations, introducing a five-day claims-processing period after receipt of complete documentation and up to two additional days for settlement.
Saudi Arabia Pet Insurance Market Report Scope
Segmentation Overview
| Accident & Illness |
| Comprehensive / Lifetime |
| Other Policy Type |
| Basic / entry tiers |
| Mid tiers |
| Comprehensive caps |
| Dog |
| Cat |
| Other Pets (Birds, Exotics, Equine, etc.) |
| Direct digital |
| Broker / MGA-carrier |
| Bancassurance / composite cross-sell |
| Other channels |
| By Policy Type | Accident & Illness |
| Comprehensive / Lifetime | |
| Other Policy Type | |
| By Coverage Architecture | Basic / entry tiers |
| Mid tiers | |
| Comprehensive caps | |
| By Animal Type | Dog |
| Cat | |
| Other Pets (Birds, Exotics, Equine, etc.) | |
| By Distribution Channel | Direct digital |
| Broker / MGA-carrier | |
| Bancassurance / composite cross-sell | |
| Other channels |
Key Questions Answered in the Report
What is the Saudi Arabia pet insurance market forecast through 2032?
The Saudi Arabia pet insurance market is projected to grow from USD 61.9 million in 2027 to USD 111.1 million by 2032 at a 12.4% CAGR.
Which policy type leads pet insurance adoption in Saudi Arabia?
Accident & illness plans lead with 65.4% share in 2026, while accident and illness plans have the highest policy-type growth forecast at 16.5% CAGR through 2032.
Why are digital channels important for pet insurance in Saudi Arabia?
Direct digital channels hold 84.8% share in 2026, supported by online issuance, claims functions, and Insurance Authority digital services through TAMEEN.
Which animal type has the largest insured base in Saudi Arabia?
Cats account for 73.2% share in 2026 and are forecast to grow at a 12.8% CAGR through 2032.
What factors are limiting adoption among Saudi pet owners?
Limited awareness, annual premium affordability, pre-existing condition exclusions, and limited product availability outside Riyadh remain the main constraints.
Which Saudi cities offer the strongest expansion potential for insurers?
Riyadh leads product development and early adoption, while Jeddah and the Eastern Province offer growth through veterinary access, intermediary distribution, and expatriate demand.