
Heparin Market Analysis by Mordor Intelligence
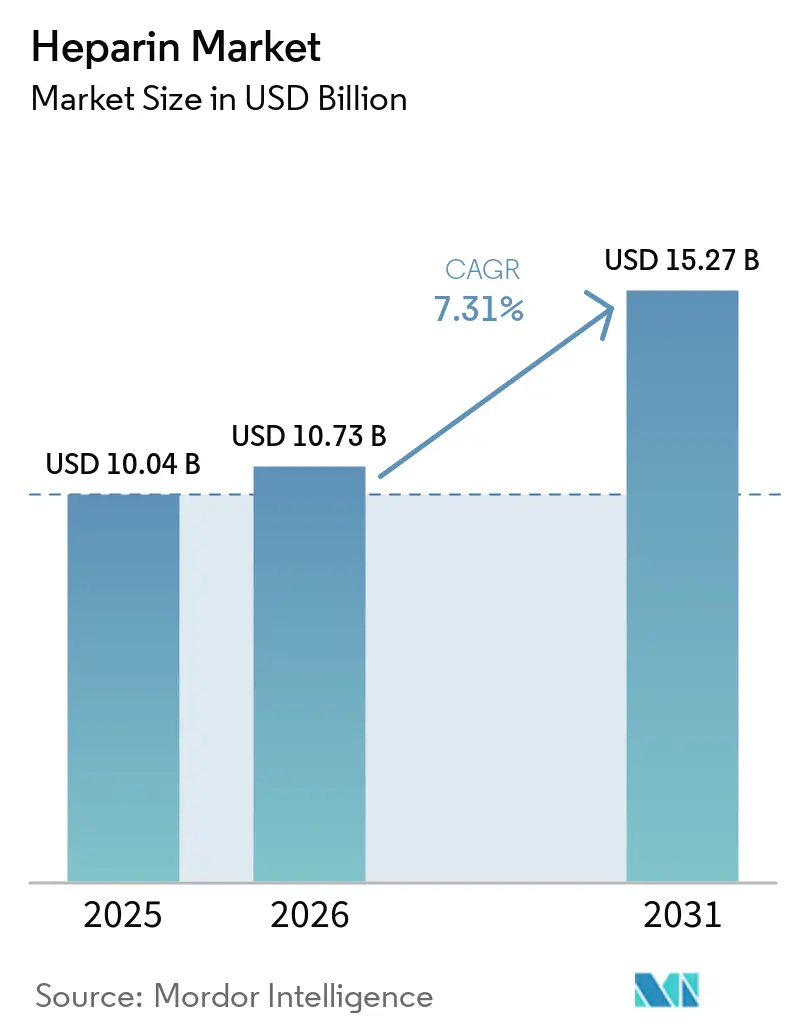
The heparin market size is expected to increase from USD 10.73 billion in 2026 to USD 11.51 billion in 2027 and reach USD 16.16 billion by 2032, growing at a CAGR of 7.02% over 2027-2032.
An expanding older population and recurring dialysis care broaden potential injectable demand, while treatment choices and bleeding restrictions keep growth tied to eligible patients. China’s institutional purchasing makes access important to injectable commercialization, alongside capacity investment in pre-filled syringes. Animal-origin inputs and quality obligations extend the investment decision upstream to sourcing and manufacturing controls. Suppliers therefore compete on commercial reach and local clinical access as well as on the molecule, because distribution, manufacturing quality, and treatment implementation each stand between patient need and revenue.
Key Report Takeaways
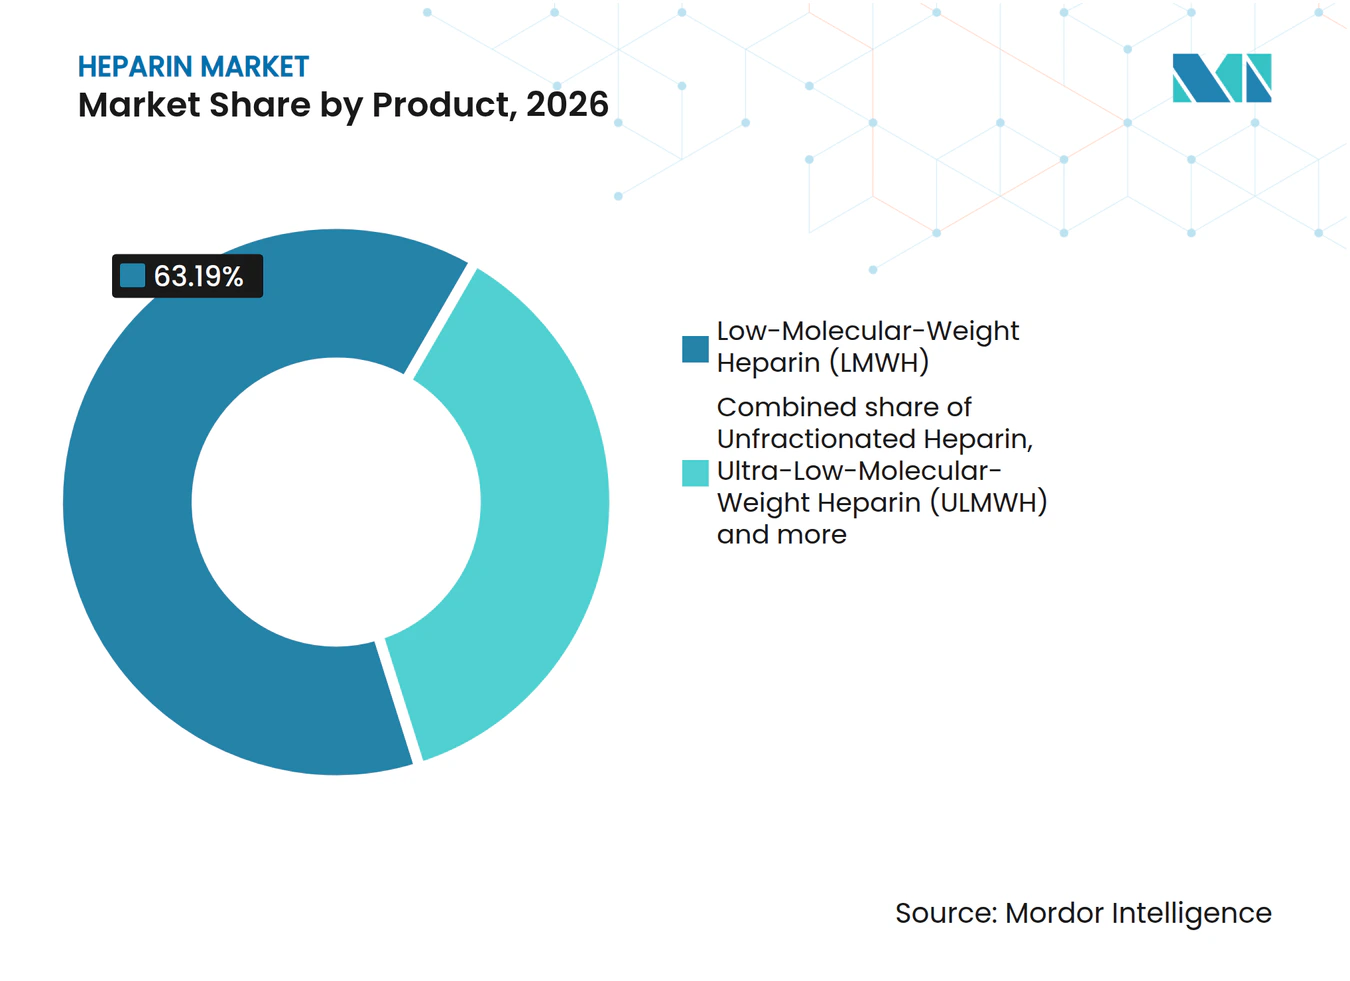
- By product, low-molecular-weight heparin (LMWH) held a 63.19% heparin market share in 2026, while synthetic / biosynthetic heparin is forecast to grow fastest at a CAGR of 8.15% over 2027-2032.
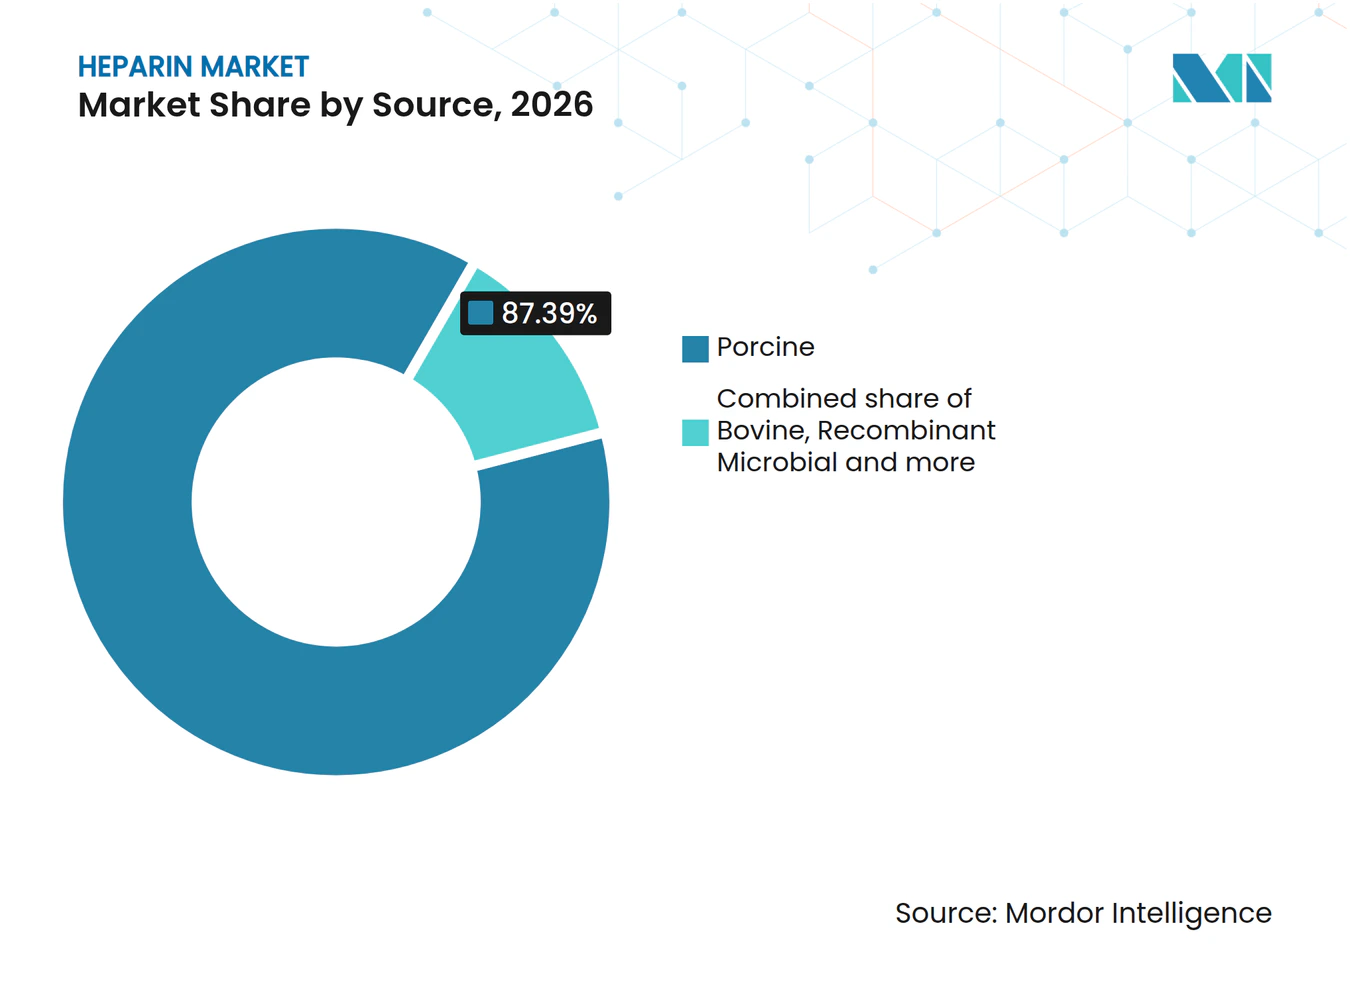
- Across sources, porcine heparin led with an 87.39% share of the heparin market size in 2026, and recombinant microbial heparin is forecast to post the fastest CAGR of 8.85% over 2027-2032.
- Dosage forms were led by injectable solution at 68.41% of revenue in 2026, with pre-filled syringes forecast to be the fastest-growing segment at a CAGR of 7.2% over 2027-2032.
- By route of administration, sub-cutaneous administration held the largest share at 54.68% of revenue in 2026 and is forecast to grow fastest at a CAGR of 7.15% over 2027-2032.
- Applications were led by deep vein thrombosis (DVT), with 46.16% of revenue in 2026, while hemodialysis is forecast to grow fastest at a CAGR of 7.55% over 2027-2032.
- Among end users, hospitals accounted for 72.15% of revenue in 2026, and home-care settings are forecast to be the fastest-growing segment at a CAGR of 8.3% over 2027-2032.
- Across geographies, Asia-Pacific led with 32.41% of revenue in 2026 and is forecast to record the fastest CAGR, at 7.95% over 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Heparin Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Escalating Surgical Procedure Volumes and Dialysis Procedures | +3% | North America, Europe, Asia-Pacific, and South America | Short term (≤ 2 years) |
| Rapid Adoption of Low-Molecular-Weight Heparin Coupled with Expansion of Biosynthetic Heparin Programs | +2.5% | North America, Europe, and Asia-Pacific | Short term (≤ 2 years) |
| High Burden of Targeted Diseases and Aging Population | +2% | Asia-Pacific, Europe, and North America | Long term (≥ 4 years) |
| Expanding Application in Medical Devices | +0.9% | ECMO treatment centers in Japan | Medium term (2-4 years) |
| Increasing Application in Oncology Care | +0.5% | Oncology care centers in the United States | Medium term (2-4 years) |
| Escalating Use of Heparin in Extracorporeal Membrane Oxygenation (ECMO) and Cardiopulmonary Bypass Circuits | +0.4% | North America, Europe, and Asia | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Escalating Surgical Procedure Volumes and Dialysis Procedures
Recurring dialysis care supports repeat anticoagulant demand as the treated population expands. Fresenius Medical Care estimated that about 4.5 million people worldwide received regular dialysis in 2025, compared with about 4.3 million in 2024. NHS Highland guidance provides routine heparin dosing to reduce extracorporeal-circuit clotting during adult hemodialysis and hemodiafiltration for patients at low bleeding risk. Specified higher-risk patients require renal-unit medical assessment before heparin anticoagulation. These clinical boundaries tie the supply opportunity to eligible treatment activity. For dialysis providers, clot prevention makes access to suitable anticoagulation part of delivering the treatment itself.
Rapid Adoption of Low-Molecular-Weight Heparin Coupled with Expansion of Biosynthetic Heparin Programs
A guideline preference for LMWH in a defined population with acute pulmonary embolism (PE) gives suppliers a clinical basis for expanding initial injectable treatment. In its 2026 acute pulmonary embolism guideline, the American Heart Association and American College of Cardiology recommended LMWH over unfractionated heparin for adults in the guideline’s C1-E1 clinical categories who require initial parenteral anticoagulation. The guideline states that this preference aims to reduce recurrent venous thromboembolism (VTE) and major bleeding. For treating teams, these objectives connect anticoagulant selection to both recurrent clotting risk and treatment-related harm, increasing the importance of the initial product choice. A 2026 review reported multi-gram-scale bioengineered heparin production, while noting that reaching industrial volumes remained challenging. The guideline preference can shape initial treatment now, whereas the review describes research-scale bioengineered heparin, so the nearer-term demand mechanism is LMWH selection.
High Burden of Targeted Diseases and Aging Population
An expanding older population widens the potential treatment base across thrombosis, cardiac care, and dialysis applications. The World Health Organization projects that the global population aged 60 years and older will grow from 1 billion in 2020 to 1.4 billion by 2030. That projection adds about 400 million people aged 60 and older by 2030, a 40% increase on the 2020 level. Demographic expansion can support demand without requiring greater medicine consumption per treated patient, while clinical selection determines how much of the broader cohort enters care.
Expanding Application in Medical Devices
Japanese reimbursement gives a heparin-coated circuit application a commercial route beyond obtaining device approval. Nipro Corporation’s Biosaver ECMO system received Japanese marketing approval on September 3, 2025, and insurance coverage began November 1, 2025.[1] Jointly developed with the National Cerebral and Cardiovascular Center, the system incorporates a heparin-coated circuit set designed for up to 14 days of continuous use. This defined duration connects the coating application to equipment intended for sustained extracorporeal support. Any incremental demand for heparin coating material depends on uptake of this reimbursed circuit set in Japanese clinical care.
Restraints Impact Analysis of Heparin Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Supply-Chain Vulnerability due to Dependence on Animal Derived Raw Material | -1% | China and United States | Short term (≤ 2 years) |
| Risk and Adverse Bleeding Events | -0.6% | United States and United Kingdom | Short term (≤ 2 years) |
| Stringent Regulatory Requirements | -0.4% | United States import market | Long term (≥ 4 years) |
| Therapeutic Shift Toward Direct Oral Anticoagulants in Long-term Thromboprophylaxis | -0.3% | Hip-fracture care center in Argentina | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Supply-Chain Vulnerability due to Dependence on Animal Derived Raw Material
Animal-derived sourcing exposes pharmaceutical manufacturers to constraints before purification begins. In its 2026 assessment, the Council on Foreign Relations identified China as the origin of 80% of global heparin supply and 74% of U.S. supply, describing porcine intestinal mucosa as a raw material.[2] Converting that slaughter byproduct into pharmaceutical input requires dedicated collection, segregation, preservation, and processing infrastructure. Separately, the council reported that, as of May 2025, the American Pharmacists Association listed heparin as in shortage and experts advised clinicians to begin rationing. The same assessment found that the United States did not produce porcine mucosa at meaningful pharmaceutical scale. Replacing imports concentrated in China with U.S. raw material would require collection to scale first, delaying that domestic route to additional medicine supply.
Risk and Adverse Bleeding Events
Hospira’s August 2026 heparin sodium injection label contraindicates use during uncontrolled active bleeding, except when due to disseminated intravascular coagulation, and advises avoiding use during major bleeding unless benefits outweigh risks.[3] These restrictions limit the patients for whom additional injectable supply can translate into treatment. The same labeling reports fatal hemorrhage and calls for caution in conditions with increased hemorrhage risk. Argyll & Bute’s major-hemorrhage protocol directs clinicians managing patients on heparin to stop the infusion, consider protamine, and seek senior clinical or hematology advice on protamine dosage and administration. Reversal planning leaves the label’s bleeding restrictions in place, limiting suppliers’ volume opportunity to patients whose clinical risk-benefit assessment permits heparin sodium injection.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Heparin Market Segment Analysis
By Product:
LMWH Scale Supports Formulation ExpansionLow-molecular-weight heparin (LMWH) accounted for a 63.19% share of the heparin market size in 2026. Shenzhen Hepalink Pharmaceutical Group Co. Ltd. (Hepalink) reported double-digit year-over-year growth in enoxaparin sodium formulation sales volume during the 6 months ended June 30, 2026. The company’s in-house sales management system accompanied its reported expansion across the group’s major regional markets. The reported growth rests on channel reach for an established enoxaparin medicine, so access to treatment channels is an expansion lever within the largest segment.
Synthetic / biosynthetic heparin is forecast to be the fastest-growing segment, at a CAGR of 8.15% over 2027-2032. A 2026 review classified heparosan followed by chemoenzymatic modification of bioengineered heparin as semi-industrial and still scaling. Unfractionated heparin’s intravenous infusion role in NHS Ayrshire & Arran’s August 2025 guidance includes weight-based dosing, coagulation monitoring, and protamine reversal after hematology advice. For bioengineered supply to reach finished-dose manufacturers at industrial volumes, the semi-industrial route must move beyond its reported scale.



By Source:
Porcine Scale Shapes Source ChoicesPorcine heparin held 87.39% of revenue in 2026, making it the largest segment. In 2025, Bioiberica S.A.U. reported manufacturing one in every 5 heparin doses administered worldwide. The company sources its heparin entirely from porcine material in Europe, North America, and South America. Its dose-based production scale illustrates an operating manufacturer’s reach, while the sourcing footprint shows that porcine participation can span several continents. Bioiberica sources its heparin from 3 continents but from a single animal species, so diversifying where it sources does not diversify what it sources.
Recombinant microbial heparin is forecast to be the fastest-growing segment, at a CAGR of 8.85% over 2027-2032. Shenzhen Hepalink reported completing pilot-scale amplification of heparin precursor fermentation in a collaborative research project targeting microbial heparin manufacturing. Carrying precursor fermentation through to finished API production is the next commercial requirement for turning this research pathway into medicine supply. Bovine heparin’s quality role was illustrated when Argentina’s medicines regulator ANMAT established an active pharmaceutical ingredient (API) reference substance in February 2026 for proton nuclear magnetic resonance identification and coagulometric identification and biological potency testing. Argentina’s reference material gives local quality testing a source-specific basis for distinguishing bovine API identity and potency within the national framework.

By Dosage Form:
Injectable Requirements and Syringe InvestmentInjectable solution represented a 68.41% heparin market share in 2026. In August 2025, HLL Lifecare invited bids for 50,000 5-mL vials of intravenous heparin injection at 1,000 units/mL for dialysis, for onward supply to a foreign country. The Indian procurement agency’s requirement specified an end use alongside concentration and container volume, so any bidder would need to supply that exact vial presentation for a cross-border dialysis program in the largest segment.
Pre-filled syringes are forecast to be the fastest-growing segment, with a CAGR of 7.2% over 2027-2032. Hepalink completed its Pingshan pre-filled syringe manufacturing facility in Shenzhen on February 4, 2025, with annual capacity of 330 million units, primarily for enoxaparin sodium injections. Its facility announcement also reported European Union good manufacturing practice certification, connecting physical capacity to a manufacturing quality framework. In September 2026, Macter International launched Hepanox, an enoxaparin sodium LMWH anticoagulant, in pre-filled syringe format. Both the Pingshan capacity and the Macter launch concern enoxaparin syringes, which ties pre-filled syringe growth to LMWH finished-dose supply.
By Route of Administration:
Clinical Sequences Span Both RoutesSub-cutaneous administration was the largest segment, with 54.68% of revenue in 2026, and is forecast to be the fastest-growing segment at a 7.15% CAGR over 2027-2032. Inhixa’s product information describes an acute ST-segment elevation myocardial infarction regimen combining an initial intravenous bolus with subcutaneous enoxaparin doses. In this regimen the subcutaneous doses follow an intravenous bolus, so subcutaneous demand in STEMI care arrives bundled with an intravenous step.
Intravenous administration is recommended to reduce ischemic events in patients with non-ST-segment elevation acute coronary syndrome under the 2025 American College of Cardiology/American Heart Association guideline for unfractionated heparin. That recommendation places the route within an acute coronary treatment decision centered on the prevention of ischemic events. The intravenous step serves acute coronary pathways in both NSTE-ACS, through recommended unfractionated heparin, and STEMI, through the enoxaparin regimen’s opening bolus, linking demand to the initial treatment sequence.
By Application:
DVT Care and Center-Based DialysisDeep vein thrombosis (DVT) was the largest segment, accounting for 46.16% of revenue in 2026. The National Institute for Health and Care Excellence (NICE) includes LMWH-containing regimens among options for confirmed proximal DVT or PE with estimated creatinine clearance of 15 to 50 mL/min. For this group, one option uses LMWH for at least 5 days before edoxaban, or dabigatran when creatinine clearance is at least 30 mL/min. Its guidance calls for attention to the product’s dose-adjustment and monitoring requirements and for locally agreed protocols or specialist or multidisciplinary advice. In this renal subgroup, the injectable lead-in gives LMWH suppliers a role at treatment initiation even when the chosen longer course uses an oral anticoagulant.
Hemodialysis is forecast to be the fastest-growing segment, with a CAGR of 7.55% over 2027-2032. Fresenius Medical Care estimated that 89% of dialysis patients worldwide received hemodialysis at dialysis centers in 2025. This treatment mix concentrates the application’s commercial exposure in dialysis centers, where a supplier can address an organized provider base responsible for delivering the treatment. Supplier expansion in this application hinges on reaching dialysis-center operators, where the predominant share of dialysis patients receives treatment.
By End User:
Hospital Supply and Home-Care PathwaysHospitals were the largest segment by end user, accounting for 72.15% of global heparin revenue in 2026. Nearly 4 million pre-filled syringes of LMWH were issued in NHS hospital trusts in England in July 2025. That scale illustrates the institutional distribution behind injectable treatment, with one month’s supply of a single drug class involving millions of ready-to-use presentations. For manufacturers, the hospital channel couples substantial unit demand with a ready-to-use presentation, placing finished-dose capability at the center of this end-user opportunity.
Home-care settings are forecast to be the fastest-growing segment, at a CAGR of 8.3% over 2027-2032. Following individual VTE risk assessment, University College London Hospitals NHS Foundation Trust (UCLH) advises continued enoxaparin at home after gynecological cancer surgery when apixaban is unsuitable. UCLH teaches the patient, family member, or caregiver to give injections and provides the full medicine supply before discharge. Anticoagulant treatment usually continues for 28 days after surgery, but the patient’s doctor chooses the exact duration, which may be longer or shorter. Home administration can extend use beyond the ward while leaving the discharge hospital as the medicine supplier in this pathway.
Geography Analysis
APAC Heparin Market
Asia-Pacific held a 32.41% heparin market share in 2026 and is forecast to grow at a CAGR of 7.95% over 2027-2032, making it the largest and fastest-growing region. In February 2026, Hepalink’s enoxaparin manufacturing subsidiary ranked first in China’s national centralized procurement renewal for Prolongin injection. Renewal of access through national procurement connects a named formulation to an institutional channel that can support distribution beyond individual prescribing decisions. Cambodia’s Ministry of Health approved the 40 mg/0.4 mL strength of Prolongin enoxaparin injection manufactured by Hepalink subsidiary Shenzhen Techdow Pharmaceutical Co., Ltd. in February 2026. Together the 2 events extend one enoxaparin brand’s reach, through institutional procurement in China and ministry registration in Cambodia, with sustained supply needed to turn that access into treatment availability.
North America and Europe Heparin Market
In North America, the 2025 U.S. guideline recommends enoxaparin or fondaparinux as alternatives to unfractionated heparin for non-ST-segment elevation acute coronary syndrome at diagnosis when early invasive management is not anticipated. Europe’s 2025 survey of 114 cardiac surgery centers across 29 countries found 78.1% reported written heparinization protocols and 70.2% had no universal activated-clotting-time target after heparin reversal. Norway’s Directorate of Health weakly recommended protamine sulfate for heparin users with acute intracerebral hemorrhage in its August 2026 update. In each setting a guideline or local protocol sets the anticoagulant choice and its monitoring routine, so product positioning in these regions has to follow protocol content.
MEA and South America Heparin Market
Within Middle East and Africa, South Africa’s adult hospital guidance recommends subcutaneous unfractionated heparin with bleeding monitoring, or enoxaparin, for high-risk medical inpatients when rivaroxaban is contraindicated. Egypt’s 2025 national drug formulary includes enoxaparin prophylaxis for moderate- and high-risk surgical patients and acutely ill medical patients with reduced mobility and increased VTE risk. South America’s purchasing channel is illustrated by Brazil’s Ministry of Health, which contracted Biomm S/A in 2025 to supply enoxaparin 100 mg/mL in pre-filled syringes. A July 2025 enoxaparin sodium order from Chile’s Hospital de Cauquenes to Laboratorio Chile S.A. records accepted receipt. Brazil’s federal contract and Chile’s hospital order point to different purchasing levels, while the Egyptian and South African documents tie enoxaparin and heparin use to defined risk groups.

Regional Editions
Regulatory Framework and Outlook
Selected jurisdictions are compared from the perspective of established heparin API manufacturers maintaining documented quality systems. Good manufacturing practice (GMP) and pharmacopoeial frameworks place quality management, product standards, and regulatory documentation at different points in the supply process. The comparison emphasizes the predictability of quality responsibilities and the administrative steps accompanying supply, which influence where an established producer can participate efficiently.
Regulatory Table of Heparin Market
| Decision factor | United States | France | China | South Africa | Brazil |
|---|---|---|---|---|---|
| Primary authority | FDA | ANSM | NMPA | SAHPRA | ANVISA |
| Key instruments or direction | Import Alert 55-03, nonbinding field guidance; applicable CGMP framework | Part II API GMP covers manufacturing, repackaging, and relabeling | 2025 Pharmacopoeia issued by NMPA and National Health Commission, effective October 1, 2025 | API Q7 guidance, read with the medicines GMP guide taking precedence in discrepancies | Brazilian Pharmacopoeia eighth edition approved May 15, 2026; IN 451/2026 published June 15, 2026 |
| Commercial effect | Possible detention for inadequate CGMP systems; possible refusal when inspections support apparent adulteration | Covered API activities carry GMP responsibilities | Compliance with the operative standard; submissions were conditional on necessary registration-standard changes | Manufacturers should document and implement API quality-management systems | Minimum API quality requirements; published GMP certification (CBPF) administrative and foreign-regulator recognition changes |
| Current policy attractiveness | Medium | High | Medium | High | Medium |
| Future direction of policy attractiveness | No change | No change | No change | No change | No change |
| Source: Mordor Intelligence | |||||
For established manufacturers, U.S. Import Alert 55-03’s conditional refusal framework and China’s Pharmacopoeia, in force since October 1, 2025, preserve the quality-compliance task, supporting Medium ratings and No change. France’s defined API GMP coverage and South Africa’s documented quality-system approach support High ratings for established manufacturers, with No change reflecting continuity in those core quality tasks. Brazil’s May 2026 Pharmacopoeia edition approval covered general minimum-quality requirements for APIs, medicines, and health products, while June’s IN 451/2026 changed foreign-regulator recognition criteria and CBPF certification administration. Both changes concern general quality requirements or certification administration, so an established API manufacturer’s core duty to demonstrate quality continues, supporting Brazil’s Medium rating and No change direction.
Value Chain Stages
The value chain compares raw-material sourcing, API production, and finished-medicine supply as distinct points of supplier earnings. SARIA subsidiary Van Hessen supplies pharmaceutical manufacturers with mucosa for heparin API, much of it from its own offal production. Upstream value capture therefore begins with supplying an animal-derived pharmaceutical input, while subsequent stages earn from the API and the finished injection.
Value Chain Analysis Table of Heparin Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Raw-material sourcing | Pharmaceutical raw-material suppliers such as Van Hessen, a SARIA subsidiary | Mucosa sales | Dependence on animal-origin collection | Qualify additional collection sources |
| API production and supply | API suppliers such as Bioiberica S.A.U.; API manufacturers such as Hepalink | Heparin API sales | Exposure to interruption at an individual processing site | Qualify alternative API production locations |
| Finished-medicine supply | Injectable medicine suppliers such as B. Braun | Finished-injection sales | Country differences in product registration and availability | Match country supply plans to authorized presentations |
| Source: Mordor Intelligence | ||||
Hepalink’s API operations in China and Wisconsin illustrate how geographic distribution at the processing stage addresses a different resilience need from adding raw-material collection sources. B. Braun’s heparin injection availability varies with country registration and approval, linking finished-dose reach to the destination jurisdiction. Country-specific authorization determines where extra API capacity can translate into finished-injection sales.
Competitive Landscape
Market Concentration

Competition spans Opocrin S.p.A. in APIs, Baxter International Inc., the B. Braun Melsungen AG group and Pfizer Inc. in finished injections, and Sanofi S.A. in branded LMWH. Opocrin supplies porcine-derived heparin sodium, while Baxter offers a U.S. premixed heparin injection. The B. Braun group’s U.S. operating company, B. Braun Medical Inc., supplies heparin sodium formulations, and Pfizer participates through injections labeled for intravenous or subcutaneous use in the United States. Sanofi marketed Lovenox/Clexane in more than 100 countries in 2025. Generic enoxaparin in the United States and biosimilars in parts of Europe and in China broadened the competitive field around that footprint, giving buyers alternatives to the branded medicine.
In July 2025, B. Braun Medical Inc. launched 25,000-unit heparin sodium injections in 0.45% sodium chloride at 50 units/mL and 100 units/mL, expanding its U.S. premixed-bag range to 7 products. The announcement specified 2D enhanced barcodes for the 250 mL and 500 mL bags. For hospital users, a choice between concentrations and machine-readable bag identification brings formulation breadth and medication identification into the same supplier proposition. Challengers to the U.S. premix range need a presentation strategy that addresses concentration choice and barcode identification alongside the anticoagulant ingredient.
Brazil approved a new Clexane indication for Sanofi Medley Farmacêutica Ltda. on February 10, 2025. The approval covered extended treatment of deep vein thrombosis and pulmonary embolism and recurrence prevention in patients with active cancer. For a branded LMWH supplier facing generic and biosimilar alternatives, indication-specific authorization offers an additional basis for positioning. Challengers seeking the same clinical opportunity must consider the authorized patient population alongside their ability to supply an appropriate formulation. Local indication access is a separate competitive asset, since a broad international footprint does not itself authorize treatment of a particular patient group in an individual country.
Heparin Industry Leaders
-
Opocrin S.p.A.
-
Baxter International Inc.
-
B. Braun Melsungen AG
-
Pfizer Inc.
-
Sanofi S.A.
- *Disclaimer: Major Players sorted in no particular order
Heparin Market Companies Covered in this Report
- B. Braun
- Baxter
- Dr. Reddy’s Laboratories
- Hebei Changshan Biochemical Pharmaceutical Co. Ltd.
- Leo Pharma
- Opocrin S.p.A.
- Pfizer
- Fresenius
- GLAND PHARMA
- Hikma Pharmaceuticals
- Techdow USA Inc.
- Viatris
- Abbott Laboratories
- Smiths Group
- Sanofi
- Shenzhen Hepalink Pharmaceutical Group Co. Ltd.
- Bioiberica
- Nanjing King-Friend Biochemical Pharmaceutical Co. Ltd.
- Cipla
- Emcure Pharmaceuticals Ltd
Key Opportunities for Market Participants
The opportunity comparison focuses on obstetric, procedural, and renal-care uses of heparin for acute pulmonary embolism (PE). The 2026 American Heart Association/American College of Cardiology guideline addresses each setting, including LMWH and unfractionated heparin (UFH) options for pregnant patients who can receive anticoagulation. The guideline announcement says implementation depends on local resources, so a supplier’s offer has to fit the service that delivers each recommendation.
Market Opportunities Table of Heparin Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Heparin supply for pregnancy-associated acute PE | Guidance recommends LMWH or UFH for pregnant patients who can receive anticoagulation | Obstetric and acute-PE care teams | Supply suitable heparin options through obstetric PE pathways | Local resources for pathway implementation | LMWH and UFH manufacturers serving obstetric care |
| Concurrent anticoagulation for catheter-directed thrombolysis | Therapeutic LMWH or UFH, or subtherapeutic UFH, recommended with catheter-directed thrombolysis for acute PE | Interventional and PE response teams | Supply presentations suited to the chosen procedural regimen | Coordinating concurrent treatment and dose intensity | Heparin suppliers serving procedural centers |
| LMWH supply with dose-management support in severe kidney disease | Anti-Xa monitoring is reasonable for LMWH-treated acute PE with severe chronic kidney disease and creatinine clearance <30 mL/min | Acute-PE teams treating patients with severe chronic kidney disease | Pair LMWH supply with dose-adjustment support where anti-Xa monitoring is chosen | Bleeding risk and capacity for individualized dose management | LMWH suppliers with clinical support capabilities |
| Source: Mordor Intelligence | |||||
The central opening is LMWH supply with dose-management support for acute PE in severe chronic kidney disease. The guideline’s monitoring option addresses LMWH-treated patients, whereas the eligible obstetric and catheter-directed thrombolysis pathways allow both LMWH and UFH. That LMWH-specific recommendation gives suppliers a focused way to differentiate through support for selected anti-Xa monitoring and dose adjustment when serving renal-care teams.
Recent Industry Developments in Heparin Market
- Sep 2026: Macter International launched Hepanox, an enoxaparin sodium LMWH anticoagulant, in pre-filled syringe format.
- Aug 2026: Shenzhen Hepalink reported double-digit year-over-year growth in enoxaparin sodium formulation sales volume for the 6 months ended June 30, 2026.
- Jun 2026: ANVISA published IN 451/2026, changing foreign-regulator recognition criteria and the administrative process for Good Manufacturing Practice certification.
Heparin Market Report Scope and Research Methodology
Market Definition and Coverage
The global heparin market measures annual worldwide manufacturer sales value of heparin active pharmaceutical ingredients and finished heparin medicines for human clinical anticoagulation and related uses. It covers products sold across all countries worldwide.
Scope exclusions: Heparin-coated or heparin-impregnated devices, including catheters, heparin rinsing or flush solutions, veterinary heparin products, and anticoagulants other than heparin, including direct oral anticoagulants, are excluded.
Segments Covered in This Report
-
By Product
- Unfractionated Heparin
- Low-Molecular-Weight Heparin (LMWH)
- Ultra-Low-Molecular-Weight Heparin (ULMWH)
- Synthetic / Biosynthetic Heparin
-
By Source
- Porcine
- Bovine
- Recombinant Microbial
-
By Dosage Form
- Injectable Solution
- Pre-filled Syringe
- Topical Gel / Cream
- Others
-
By Route of Administration
- Intravenous
- Sub-cutaneous
-
By Application
- Deep Vein Thrombosis (DVT)
- Atrial Fibrillation and Heart Attack
- Coronary Artery Disease
- Hemodialysis
- Other Applications
-
By End User
- Hospitals
- Ambulatory Surgical Centers
- Specialty Clinics
- Home-care Settings
-
By Geography
-
North America
- United States
- Canada
- Mexico
-
Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
-
Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
-
Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
-
South America
- Brazil
- Argentina
- Rest of South America
-
North America
Data Sources, Market Sizing, and Validation
Desk Research
Public sources such as the World Health Organization Model List of Essential Medicines, DailyMed prescribing information, the Government Accountability Office review of drug shortages, and House Energy and Commerce hearing submissions provide evidence on medicine presentations, clinical use, quality requirements, treatment settings, and supply disruptions. The analyst uses these sources to map therapeutic demand and manufacturing constraints to the annual value of API and finished-medicine sales.
Company filings and investor materials help identify product portfolios, manufacturing capacity, sales channels, and business developments, while reputable press reports provide dated cross-checks on launches, procurement, and supply events. These sources are not exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
Structured interviews with API manufacturers, finished-medicine suppliers, hospital and dialysis procurement specialists, and clinical pharmacy or anticoagulation leaders would test secondary evidence on product mix, transaction points, prices, supply capacity, and regional access. Respondents would review the assumptions behind regional and segment estimates and identify changes in treatment practice or procurement that public sources may not capture. Where evidence conflicts or remains sparse, analysts would compare independent responses with filings, published clinical guidance, and supplier or channel checks, then document a range or use a comparable segment proxy for unresolved inputs.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 35% | CXOs: 20% | APAC: 40% |
| Mid tier: 45% | Functional/Unit leaders: 35% | EMEA: 32% |
| Smaller Players: 20% | Managers: 45% | Americas: 28% |
Market-Sizing & Forecasting
The model starts with a top-down estimate of global annual manufacturer sales for heparin API and finished medicines, valued at invoice prices in USD, and reconciles that total to regional and therapeutic product views. Core indicators include dialysis and surgical procedure activity and eligible treated populations to estimate use, API and finished-dose capacity and supply availability to constrain deliverable sales, and product, source, dosage, route, and care-setting mix together with manufacturer selling prices to estimate value and shifts in the sales mix. To keep regional and product estimates aligned with the global value, analysts build segment shares from reported sales, procurement and portfolio evidence and adjust for the relative growth of each segment.
A multivariate regression can relate historical market value to procedure activity, treated populations, supply capacity, and price and mix indicators where comparable time series exist. Scenario analysis can test changes in animal-origin supply, clinical adoption, and synthetic or biosynthetic production. Selective bottom-up checks use supplier sales roll-ups, channel checks, and sampled manufacturer selling price times volume for major formulations, with API sales counted only when they are not subsequently captured in a finished-medicine sale. If supplier or regional inputs are missing, analysts use a comparable product or geography as a proxy, bound it with low and high scenarios, and reconcile the residual to the top-down total. Interviews with relevant market specialists would test variable-level assumptions and explain discrepancies before forecasts are set.
Data Validation & Update Cycle
Analysts triangulate manufacturer filings, regulatory and clinical records, procurement signals, and market estimates, then compare independent demand and supply indicators with the modeled sales path. They review outliers in prices, segment shares, regional totals, and year-over-year changes against the source record, resolve variances through a second source or targeted re-contact, and document any remaining adjustment before sign-off. The dataset is refreshed annually, updated between cycles after material regulatory, supply, or product events, and given a fresh source and calculation review before delivery.
Mordor Intelligence's Heparin Market Size Measured Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The global heparin market measures annual worldwide manufacturer sales value of heparin active pharmaceutical ingredients and finished heparin medicines for human clinical anticoagulation and related uses.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Core indicators include dialysis and surgical procedure activity and eligible treated populations to estimate use, API and finished-dose capacity and supply availability to constrain deliverable sales, and product, source, dosage, route, and care-setting mix together with manufacturer selling prices to estimate value and shifts in the sales mix.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 11.51 B (2027) | |
| Global Consultancy A | USD 5.8 B (2025) | At its 2025 base, this estimate is 49.6% below this report's 2027 value of USD 11.51 B, 2 years later. Its lower starting valuation and published 7.2% forecast leave a lower path by the later report year. |
| Global Consultancy B | USD 7.8 B (2025) | At its 2025 base, this estimate is 32.2% below this report's 2027 value of USD 11.51 B, 2 years later. Its published 2.6% forecast advances the earlier valuation more slowly. |
Mordor Intelligence's analysts triangulate manufacturer filings, regulatory and clinical records, procurement signals, and market estimates, then compare independent demand and supply indicators with the modeled sales path.
Key Questions Answered in the Report
What is the heparin market size and growth outlook?
The size is forecast at USD 11.51 billion in 2027 and USD 16.16 billion by 2032, with a CAGR of 7.02% over 2027-2032.
What supports demand for injectable heparin?
Fresenius Medical Care estimated that about 4.5 million people worldwide received regular dialysis in 2025. NHS Highland guidance provides routine heparin dosing for adult hemodialysis patients at low bleeding risk.
Which heparin product category leads revenue?
Low-molecular-weight heparin held 63.19% of revenue in 2026. Synthetic / biosynthetic heparin is forecast to grow fastest at a CAGR of 8.15% over 2027-2032.
Which companies compete in heparin supply?
Opocrin S.p.A., Baxter International Inc., B. Braun Melsungen AG, Pfizer Inc., and Sanofi S.A. are among the industry’s major participants.
What limits expansion in heparin treatment?
Hospira’s August 2026 heparin sodium injection label contraindicates use during uncontrolled active bleeding except when due to disseminated intravascular coagulation. The industry is forecast to grow at a CAGR of 7.02% over 2027-2032.
Which region leads heparin revenue and growth?
Asia-Pacific held 32.41% of revenue in 2026 and is forecast to grow fastest at a CAGR of 7.95% over 2027-2032.