
Graphene Coating Market Size and Share
Market Overview
| Study Period | 2022 - 2032 |
|---|---|
| Market Size (2027) | USD 313.24 Million |
| Market Size (2032) | USD 862.31 Million |
| Growth Rate (2027 - 2032) | 22.45 % |
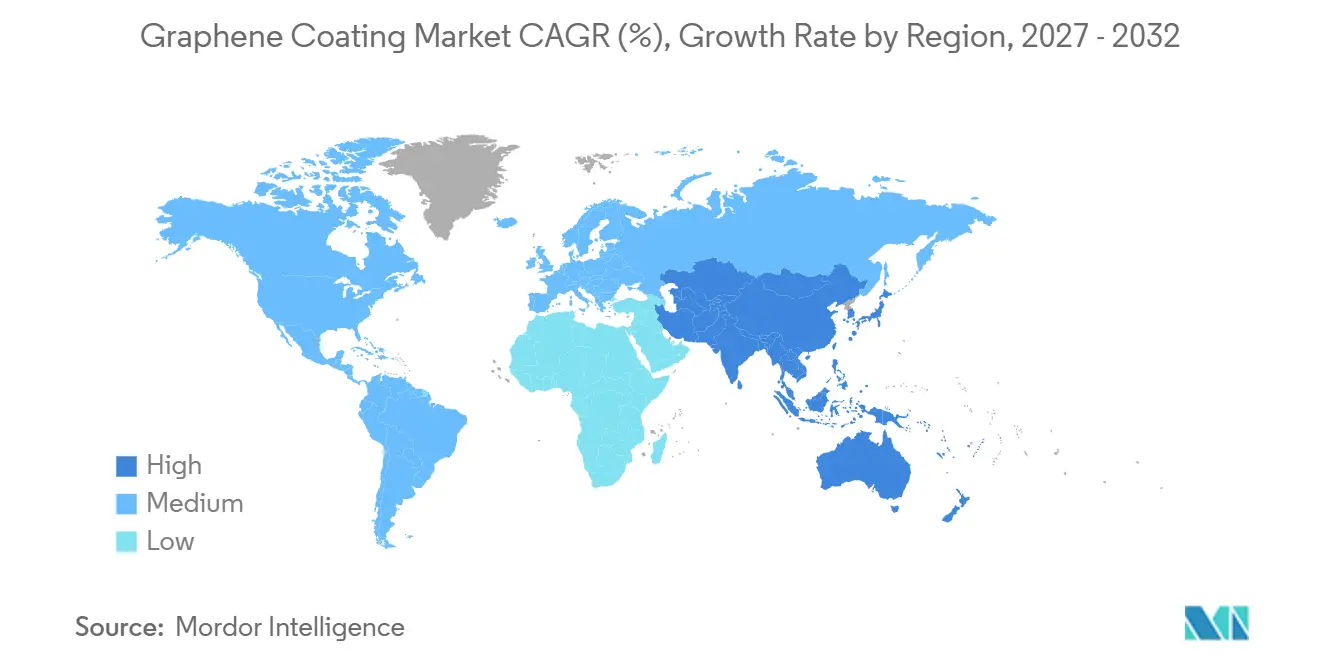
| Fastest Growing Market | Asia-Pacific |
| Largest Market | Asia-Pacific |
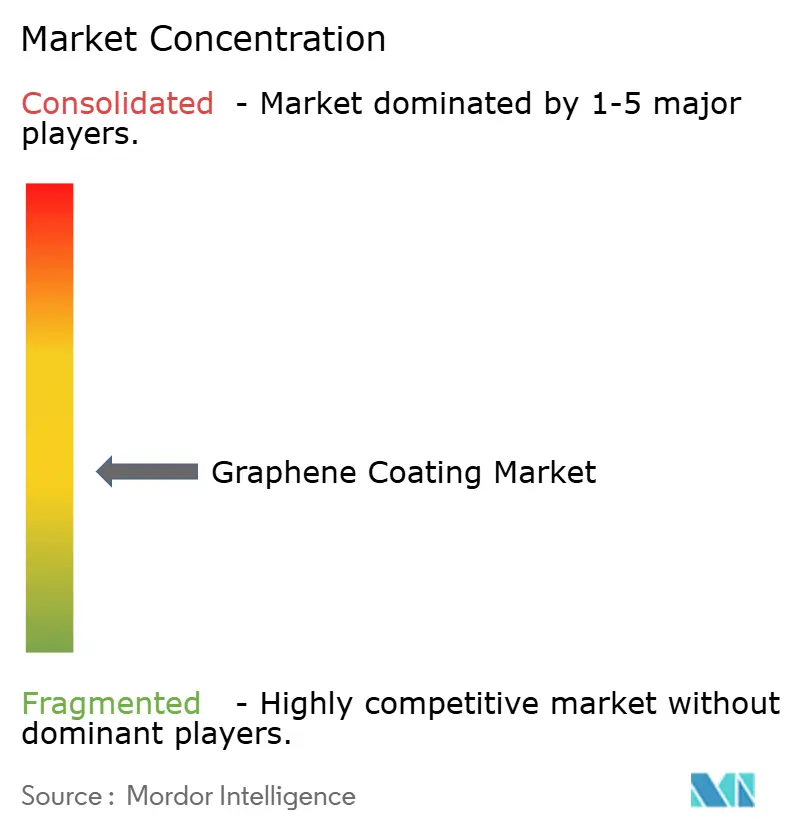
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Graphene Coating Market Analysis by Mordor Intelligence
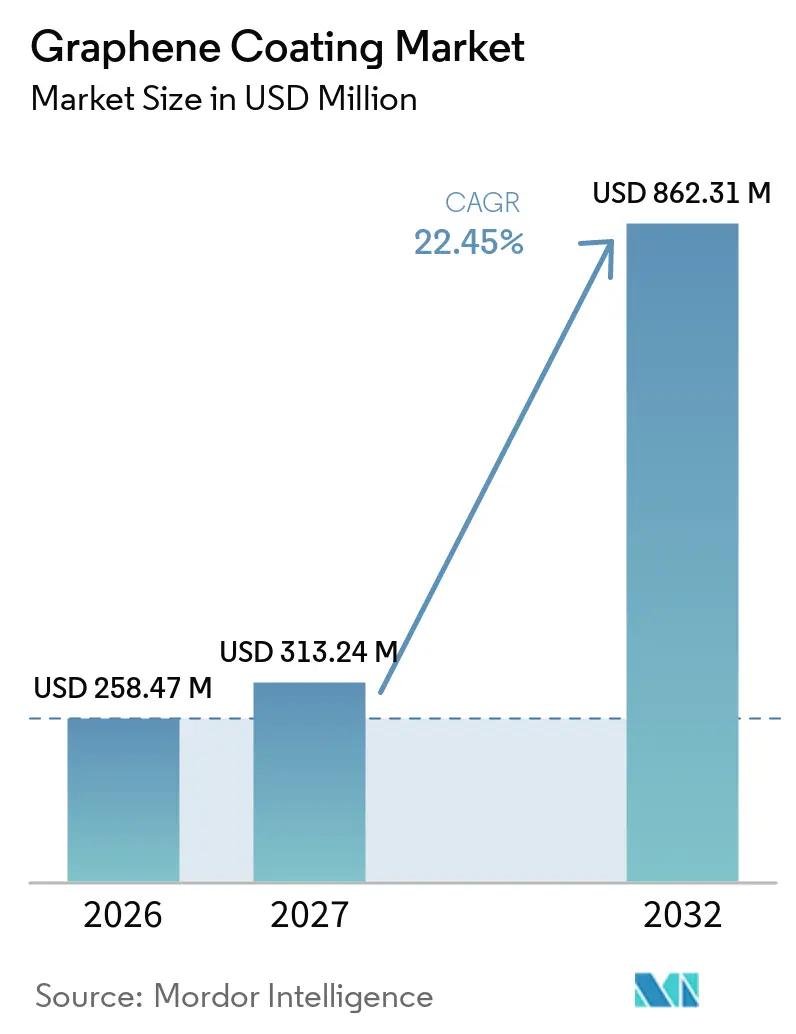
The Graphene coating market size was valued at USD 258.47 million in 2026 and is estimated to grow from USD 313.24 million in 2027 to USD 862.31 million by 2032, at a CAGR of 22.45% during the forecast period (2027-2032). The graphene coating market is supported by demand from offshore energy assets, electric vehicle battery packs, and semiconductor packaging, where coating failure can result in significant operating and replacement costs. Lower graphene powder prices have made commercial formulations more accessible to mainstream coating producers, although coating-grade material remains more expensive than conventional additives. Buyers place greater weight on barrier performance, thermal control, and compliance with emissions regulations when selecting coatings. Partnerships between established coating companies and graphene specialists are becoming a practical route to commercial access. Qualification requirements remain a limiting factor, as differences in graphene characterization can lengthen approval cycles for regulated applications.
Key Report Takeaways
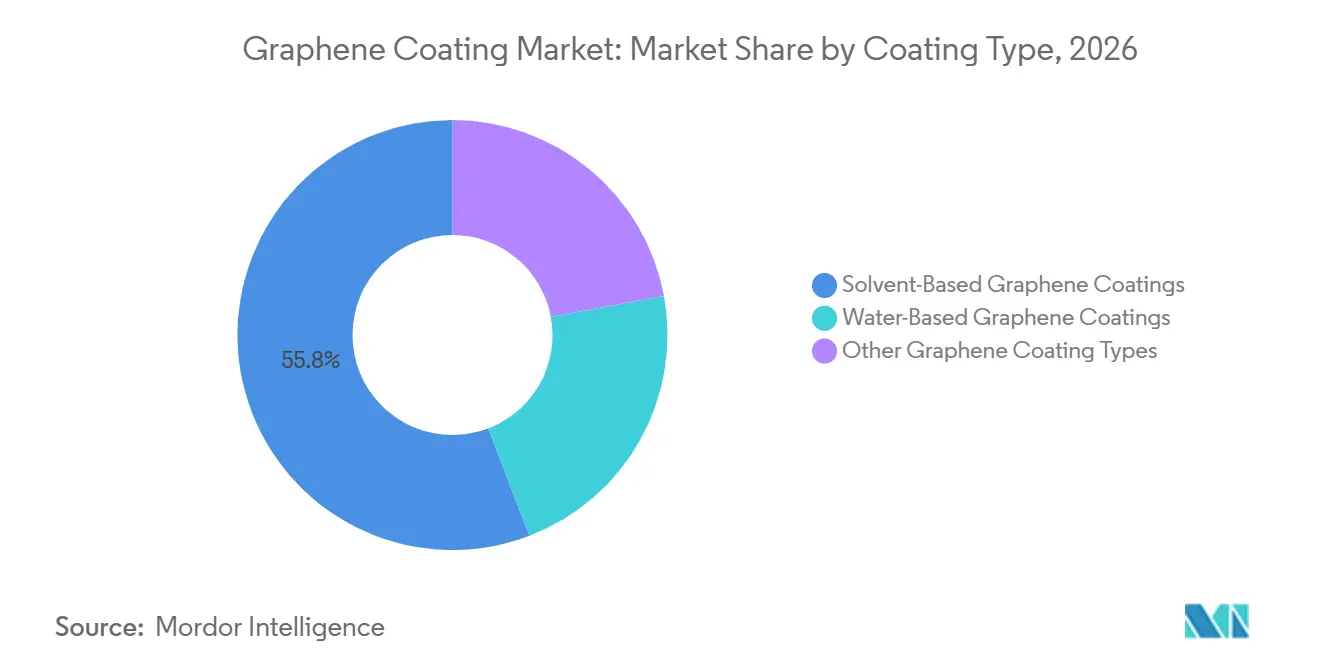
- By coating type, solvent-based coatings held 55.82% of the market share in 2026, while water-based coatings are projected to grow at a CAGR of 23.12% through 2032.
- By application, corrosion protection accounted for 34.17% of the Graphene coating market share in 2026 and is projected to expand at a CAGR of 23.89% through 2032.
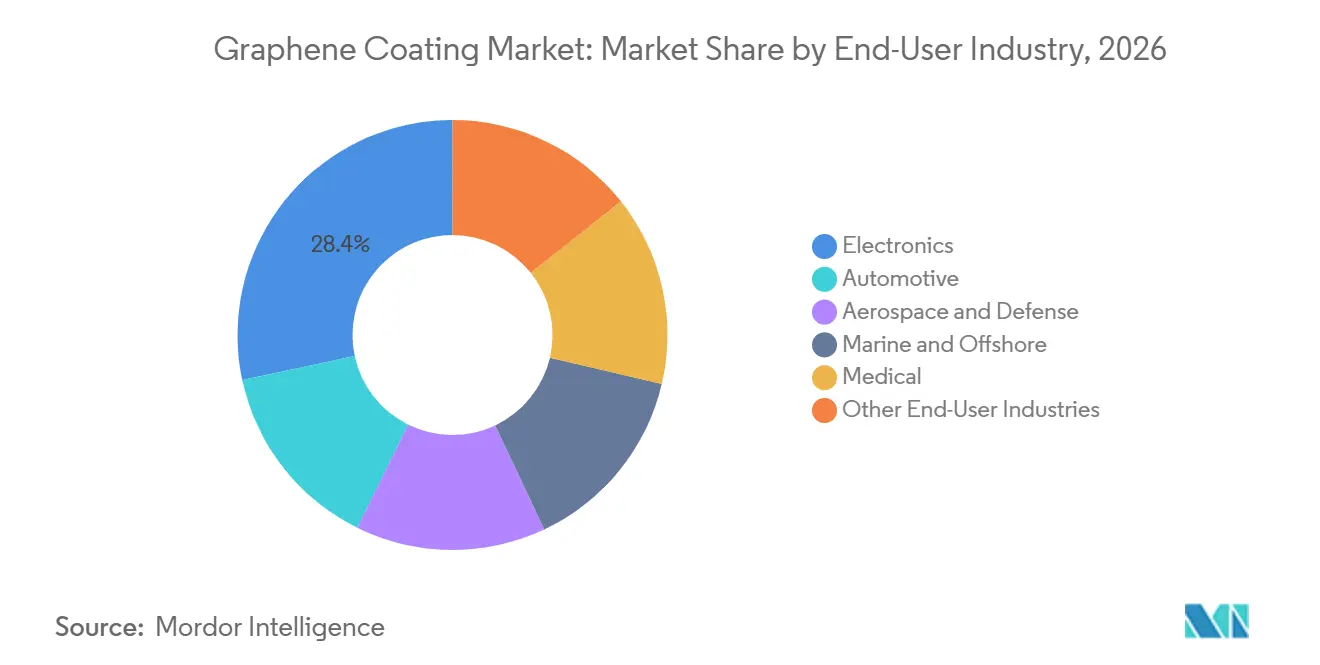
- By end-user industry, electronics held 28.36% market share in 2026, while automotive is forecast to grow at a CAGR of 24.05% through 2032.
- By geography, Asia-Pacific accounted for 34.73% of market share in 2026 and is forecast to grow at a CAGR of 23.74% through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Graphene Coating Market*
| Drivers | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Corrosion Protection Demand for High-Value Assets | +3.5% | Global, strongest in North America, the Middle East, and the Asia-Pacific offshore sectors | Long term (≥ 4 years) |
| Electronics and Thermal-Management Adoption | +3.2% | Asia-Pacific, especially China, South Korea, and Japan, with spillover to North America | Medium term (2-4 years) |
| Automotive Lightweighting and Electric Vehicle (EV) Component Protection | +2.8% | Asia-Pacific, especially China, North America, and Europe | Medium term (2-4 years) |
| Tightening VOC and Solvent-Emission Requirements | +2.1% | Europe and North America, with spillover to East Asia | Short term (≤ 2 years) |
| Ship-Efficiency Requirements and Biocide-Free Foul-Release Coatings | +1.8% | Global, led by European maritime operators and South Korean shipbuilders | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Corrosion-Protection Demand for High-Value Assets
The graphene coating market benefits from the rising cost of corrosion damage to industrial infrastructure. Graphene platelets create a longer diffusion path for oxygen, chloride ions, and moisture through a coating film. A September 2025 study found that (3-Aminopropyl)triethoxysilane (APTES)-functionalized graphene oxide in a waterborne sol-gel coating on aluminum alloy achieved over 99.9% corrosion protection efficiency and reduced corrosion current density by nearly 10,000 times. The same study reported that the hardness increased from 0.25 GPa to 0.61 GPa[1]. Longer replacement cycles strengthen the economic case for premium coatings on offshore platforms and chemical processing equipment. Asset owners in North America and the Middle East, therefore, have reason to evaluate lifecycle cost rather than initial coating price alone.
Electronics and Thermal-Management Adoption
The graphene coating market is gaining support from electronics producers that need to manage heat in dense chip packages and 5G equipment. A December 2025 conference paper reported that a 5 wt% graphene spray coating on aluminum packaging enclosures achieved a thermal conductivity of 209 W/(m·K). The same study showed a 9°C reduction in device operating temperature compared with commercially coated aluminum. A July 2025 paper found that oxygenated graphene ink coatings on copper increased the heat transfer coefficient by 152% over bare copper and reached a critical heat flux of 174 W/cm². These results address a practical heat management constraint in AI hardware and high-power semiconductor packaging, and favor suppliers already working with electronics manufacturers on next-generation thermal specifications.
Automotive Lightweighting and Electric Vehicle (EV) Component Protection
The graphene coating market is supported by demand from electric vehicle components that require corrosion resistance, thermal cycling tolerance, and low added weight. Battery trays and underbody components are exposed to road salt and undergo repeated charge-discharge temperature cycles. A September 2025 review assessed graphene-based nanocomposite coatings for automotive corrosion resistance across several substrates and formulation approaches. The review also discussed the opportunity to replace hexavalent chromium systems being phased out under REACH. Automotive suppliers are increasingly engaging directly with graphene producers rather than relying solely on major paint companies. NanoXplore identified coatings as a growth area in its 2025 annual information form, alongside its transportation business.
Tightening Volatile Organic Compound (VOC) and Solvent-Emission Requirements
The graphene coating market is affected by tighter regulations on solvent emissions and aerosol coatings. The U.S. Environmental Protection Agency finalized amendments to the National Volatile Organic Compound Emission Standards for Aerosol Coatings in January 2025. The compliance deadline was subsequently extended from July 17, 2025, to January 17, 2027. The European Commission also updated EU Ecolabel criteria for paints and related products in December 2025, including anti-corrosion coating requirements. Waterborne graphene formulations offer a route to lower-emission coatings while retaining barrier and thermal properties. Incumbent solvent-based suppliers must absorb the costs of reformulation, testing, and customer reapproval during the transition.
Restraints Impact Analysis of Graphene Coating Market*
| Restraints | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Graphene Cost and Inconsistent Supply Quality | -1.5% | Global, most acute for small and medium-sized formulators in Europe and North America | Long term (≥ 4 years) |
| Dispersion, Agglomeration, and Formulation Complexity | -1.2% | Global, with greater impact in markets lacking local formulation expertise | Medium term (2-4 years) |
| Qualification Delays Caused by Inconsistent Test Protocols | -1.0% | Global, particularly Europe, North America, and Japan | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
High Graphene Cost and Inconsistent Supply Quality
The graphene coating market continues to face a cost barrier, as coating-grade graphene is priced above conventional pigments and additives. This cost premium is most difficult to justify for substrates where coating failure has limited consequences. Material quality can also vary among suppliers in layer count, lateral flake size, defect density, and surface chemistry. This variation can produce inconsistent coating results even when formulators use nominally similar recipes. Suppliers without robust incoming-quality testing may encounter batch-to-batch failures and higher warranty exposure. These issues can reduce buyer confidence and keep demand concentrated in high-value applications where the technical benefit is clear.
Dispersion, Agglomeration, and Formulation Complexity
The graphene coating market is also constrained by graphene agglomeration in liquid media. Strong interlayer interactions can prevent platelets from dispersing and orienting correctly within the coating matrix. Achieving meaningful barrier improvement at 0.5-2 wt% loading can require surface functionalization, specialized dispersants, or additional processing equipment. A June 2025 study reported that corrosion resistance in sulfonated graphene-reinforced waterborne epoxy coatings was highly sensitive to dispersion quality. These requirements increase development costs and can delay product launches, while also providing an advantage to specialist formulators with established dispersion expertise.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Graphene Coating Market Segment Analysis
By Coating Type:
Water-Based Variants Gain Ground on Solvent-Based IncumbentsSolvent-based coatings account for 55.82% of the 2026 graphene coating market, reflecting their established formulation base and substrate compatibility for heavy industrial and marine applications. Epoxy and polyurethane solvent systems have a longer record in anti-corrosion work at offshore facilities, jetties, and petrochemical plants. This history creates specification inertia in applications with long design lives. Water-based coatings hold a smaller share but are forecast to expand at a 23.12% CAGR through 2032: lower-emission requirements and improved technical performance support demand for water-based graphene coatings. A 2025 study found that a functionalized graphene oxide waterborne sol-gel formulation delivered over 99.9% corrosion protection efficiency on aluminum alloy.
These results challenge the assumption that solvent-based products must deliver superior protection in demanding environments. Updated European labeling criteria place additional scrutiny on emissions from anti-corrosion coatings, creating a more favorable regulatory environment for waterborne products from 2027. Powder coatings and hybrid sol-gel systems hold the remaining share of the graphene coating market. These products are relevant where thermal cycling and film integrity are more important than ease of processing. Aerospace and high-temperature industrial applications are likely to remain key outlets for these alternatives. The transition will depend on successful qualification for specific substrates and operating environments.

By Application:
Corrosion Protection Anchors Demand While Anti-Fouling Builds a Long-Term PositionCorrosion protection accounted for 34.17% of the graphene coating market in 2026 and is forecast to grow at a 23.89% CAGR through 2032. This combination of scale and growth indicates that the application is already established while new asset owners continue to add demand. A June 2025 review described how polydopamine-modified graphene can improve barrier and mechanical properties in anticorrosion formulations, pointing to coatings that could combine corrosion protection, abrasion resistance, and self-healing functions. Scratch and abrasion resistance is the second-largest application, used in automotive exterior panels and electronics enclosures where surface durability can reduce warranty costs.
Anti-fouling and foul-release products currently hold a smaller share of the graphene coating market but offer a longer-term opportunity. In April 2025, the International Maritime Organization's Marine Environment Protection Committee agreed to develop a legally binding biofouling management framework. The expected framework may come into force around 2029 and could accelerate the replacement of biocide-based paints. A June 2025 review assessed graphene-derived nanocomposites for eco-friendly maritime antifouling surfaces. Flame retardancy is also relevant for electric vehicle battery pack enclosures, while thermal management applications include data center cooling infrastructure and electronic equipment.
By End-User Industry:
Electronics Leads Market Share, Automotive Drives Forecast GrowthElectronics held 28.36% of the graphene coating market in 2026, with demand centered on semiconductor packaging, printed circuit board (PCB) conformal coatings, and thermal dissipation layers in 5G and data center equipment. IEEE-published testing in December 2025 reported a 9°C reduction in device temperature from graphene spray coatings on aluminum packaging enclosures, along with a surface hardness of 1,039 MPa. Electronics buyers can use these results as measurable inputs for coating specification decisions. Aerospace and defense is the second-largest end-user group, with applications that value low density, corrosion resistance, and electromagnetic interference shielding in structural and avionics systems.
Marine and offshore applications contribute to demand through vessel-efficiency targets and the shift away from biocidal antifouling systems. Medical applications remain in an early stage despite graphene's reported antibacterial properties and emerging biocompatibility data, as regulatory approval pathways for device coatings are lengthy. Automotive is forecast to grow at a 24.05% CAGR through 2032, the fastest rate among end-user industries. Electric vehicle battery tray protection and lightweight body panel coatings are the primary targets in the graphene coating market. NanoXplore's 2025 disclosures identify automotive and industrial coatings as related growth areas. Automotive Tier 1 qualification cycles of 18-36 months mean approvals currently underway could support revenue between 2027 and 2029.
Geography Analysis
Asia-Pacific held 34.73% of the graphene coating market share in 2026 and is forecast to expand at a 23.74% CAGR through 2032. The region brings together graphene producers, electronics manufacturers, electric vehicle developers, and public research programs, supporting faster product development and customer qualification. China is a major regional production base with a strong focus on thermal management and new-energy battery applications. South Korea has relevant shipbuilding and consumer electronics activity. Japan's Cabinet Office made recommendations in May 2025 to accelerate the commercialization of advanced materials across high-performance sectors[2].
Singapore has become an early-adopter market for graphene-based Heating, Ventilation, and Air Conditioning (HVAC) thermal coatings. A March 2025 case study by Graphene Manufacturing Group reported 10-20% energy savings from THERMAL-XR coatings on commercial air-conditioning systems in Singapore's banking sector. The graphene coating market in North America is supported by infrastructure maintenance, aerospace and defense procurement, and HVAC-R demand. The U.S. Environmental Protection Agency recorded graphene-related premanufacture notices in 2025, including one for a paint coating containing graphene platelets. In March 2026, Graphene Manufacturing Group received U.S. approval to import and sell THERMAL-XR ENHANCE and made its first bulk U.S. shipment to Nu-Calgon in June 2026.
Canada adds manufacturing capacity through NanoXplore and GIT Coatings. GIT Coatings opened a 1-million-liter production facility in Dartmouth, Nova Scotia, in October 2025, supported by CAD 5 million (~USD 3.56 million) in Export Development Canada funding. Europe has demand driven by strict environmental regulations, marine coatings, and aerospace manufacturing. Directa Plus reported that its Q1 2025 revenue increased 40% year over year while it expanded operations in Romania. Nordic shipping groups are testing biocide-free foul-release coatings ahead of a potential international biofouling framework, creating a distinct maritime opportunity in the graphene coating market. Brazil incorporated the International Maritime Organization's biofouling guidance into its national maritime rules in June 2025. The Middle East offers high-value petrochemical and offshore assets where long operating lives can support premium corrosion-protection specifications.
Competitive Landscape
The graphene coating market is moderately fragmented. Large coating companies generally source graphene additives for established product lines, while dedicated graphene producers seek to supply finished coating products. Partnerships are the primary commercial model, rather than broad vertical integration. AkzoNobel launched Ecosparc-enhanced Interzone 954 in Australia in May 2026 under a supply agreement with Sparc Technologies. This arrangement combines an established coating supplier's distribution access with a specialist additive developed through field trials.
GIT Coatings takes a different approach, building an integrated marine-coating business around proprietary products. Its biocide-free hard foul-release technology has been applied to more than 500 vessels across over 20 countries and holds Lloyd's Register Enhanced Type Approval. A 2025 capacity expansion brought the company's annual production capacity to 1 million liters. In August 2025, Hempel received U.S. Patent 12384922 for anti-corrosive zinc primer compositions that include graphene as a conductive pigment, indicating that formulation-level intellectual property is becoming a point of differentiation. The graphene coating market is therefore being shaped by both material expertise and the ability to meet application-specific testing requirements.
A commercial gap remains in coatings that can combine corrosion protection, thermal management, and anti-fouling in a single validated product. Laboratory results support the feasibility, but commercial performance at scale has not yet been demonstrated. Medical device coatings represent another open area, as no dedicated graphene coating supplier has completed the relevant FDA or CE marking process for device-level use. Haydale launched JustHeat in April 2025 and achieved CE and Underwriters Laboratories (UL) certification within six months of commercial prototype status, demonstrating that focused regulatory efforts can shorten commercialization timelines. In the graphene coating market, suppliers that deliver certified multifunctional products could capture share currently distributed across corrosion, thermal, and specialty coating categories.
Graphene Coating Industry Leaders
-
NANOXPLORE
-
Graphenea, Inc.
-
Vorbeck Materials
-
Directa Plus S.p.A.
-
HAYDALE PLC
- *Disclaimer: Major Players sorted in no particular order
Graphene Coating Market Companies Covered in this Report
- Akzo Nobel N.V.
- Applied Graphene Materials plc
- Directa Plus S.p.A.
- Global Graphene Group
- Grafoid
- Graphene Manufacturing Group Ltd.
- Graphenea, Inc.
- Graphite Innovation & Technologies Inc (GIT)
- HAYDALE PLC
- Hempel
- NANOXPLORE
- Sparc Technologies
- Universal Matter Inc.
- Vorbeck Materials
- Xiamen Knano Graphene Technology Co., Ltd.
Recent Industry Developments in Graphene Coating Market
- July 2026: Graphene Manufacturing Group commissioned its Generation 2.0 Graphene Manufacturing Plant in Brisbane, targeting 10 tons of graphene per annum upon completion. The project was delivered on schedule and within its AUD 2.3 million (USD 1.61 million) capital budget, strengthening supply capacity for THERMAL-XR graphene coating demand across the Heating, Ventilation, Air Conditioning, and Refrigeration (HVAC-R) and data center sectors.
- May 2026: Graphene Manufacturing Group was contracted to apply THERMAL-XR graphene coating to 300-600 air conditioners across two luxury residential towers at Queensland's Gold Coast, representing its largest single HVAC-R graphene coating project in Australia to date.
Global Graphene Coating Market Report Scope
A graphene coating is a liquid polymer formulation, primarily used for automotive paint protection, that incorporates graphene oxide particles into a silicon dioxide matrix. The coating forms a protective layer on vehicle surfaces, offering resistance to environmental contaminants, UV exposure, and minor surface abrasions. Graphene oxide particles within the matrix enhance the structural integrity of the coating, thereby improving durability and heat dissipation compared to conventional silicon dioxide-based coatings.
The graphene coating market is segmented by coating type, application, end-user industry, and geography. By coating type, the market is segmented into water-based graphene coatings, solvent-based graphene coatings, and other graphene coating types. By application, the market is segmented into corrosion protection, scratch and abrasion resistance, anti-fouling and foul release, flame retardancy, and others. By end-user industry, the market is segmented into automotive, aerospace and defense, marine and offshore, electronics, medical, and other end-user industries. The report also covers market sizes and forecasts for the graphene coating across 15 countries in major regions. The market sizes and forecasts are provided in terms of value (USD).
Segmentation Overview
| Water-Based Graphene Coatings |
| Solvent-Based Graphene Coatings |
| Other Graphene Coating Types |
| Corrosion Protection |
| Scratch and Abrasion Resistance |
| Anti-Fouling and Foul Release |
| Flame Retardancy |
| Others |
| Automotive |
| Aerospace and Defense |
| Marine and Offshore |
| Electronics |
| Medical |
| Other End-User Industries |
| Asia-Pacific | China |
| India | |
| Japan | |
| South Korea | |
| ASEAN Countries | |
| Rest of Asia-Pacific | |
| North America | United States |
| Canada | |
| Mexico | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| NORDIC Countries | |
| Rest of Europe | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Middle East and Africa | Saudi Arabia |
| South Africa | |
| Rest of Middle East and Africa |
| By Coating Type | Water-Based Graphene Coatings | |
| Solvent-Based Graphene Coatings | ||
| Other Graphene Coating Types | ||
| By Application | Corrosion Protection | |
| Scratch and Abrasion Resistance | ||
| Anti-Fouling and Foul Release | ||
| Flame Retardancy | ||
| Others | ||
| By End-User Industry | Automotive | |
| Aerospace and Defense | ||
| Marine and Offshore | ||
| Electronics | ||
| Medical | ||
| Other End-User Industries | ||
| By Geography | Asia-Pacific | China |
| India | ||
| Japan | ||
| South Korea | ||
| ASEAN Countries | ||
| Rest of Asia-Pacific | ||
| North America | United States | |
| Canada | ||
| Mexico | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| NORDIC Countries | ||
| Rest of Europe | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Middle East and Africa | Saudi Arabia | |
| South Africa | ||
| Rest of Middle East and Africa | ||
Key Questions Answered in the Report
What is current market size of Graphene Coating Market?
The Graphene coating market size was valued at USD 258.47 million in 2026 and is estimated to grow from USD 313.24 million in 2027 to USD 862.31 million by 2032, at a CAGR of 22.45% during the forecast period (2027-2032).
Why are graphene coatings used for corrosion protection?
Graphene can create a barrier that slows the movement of oxygen, moisture, and chloride through the coating film. Corrosion protection holds a 34.17% share and is projected to grow at a 23.89% CAGR through 2032.
Which end-user sector is growing fastest for graphene coatings?
The automotive sector is forecast to grow at a 24.05% CAGR through 2032, supported by electric-vehicle battery tray and body panel applications.
Which region leads demand for graphene coatings?
Asia-Pacific leads with a 34.73% revenue share in 2026 and has the fastest projected regional growth at 23.74% CAGR through 2032.