
Ghana Liquid Packaging Cartons Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
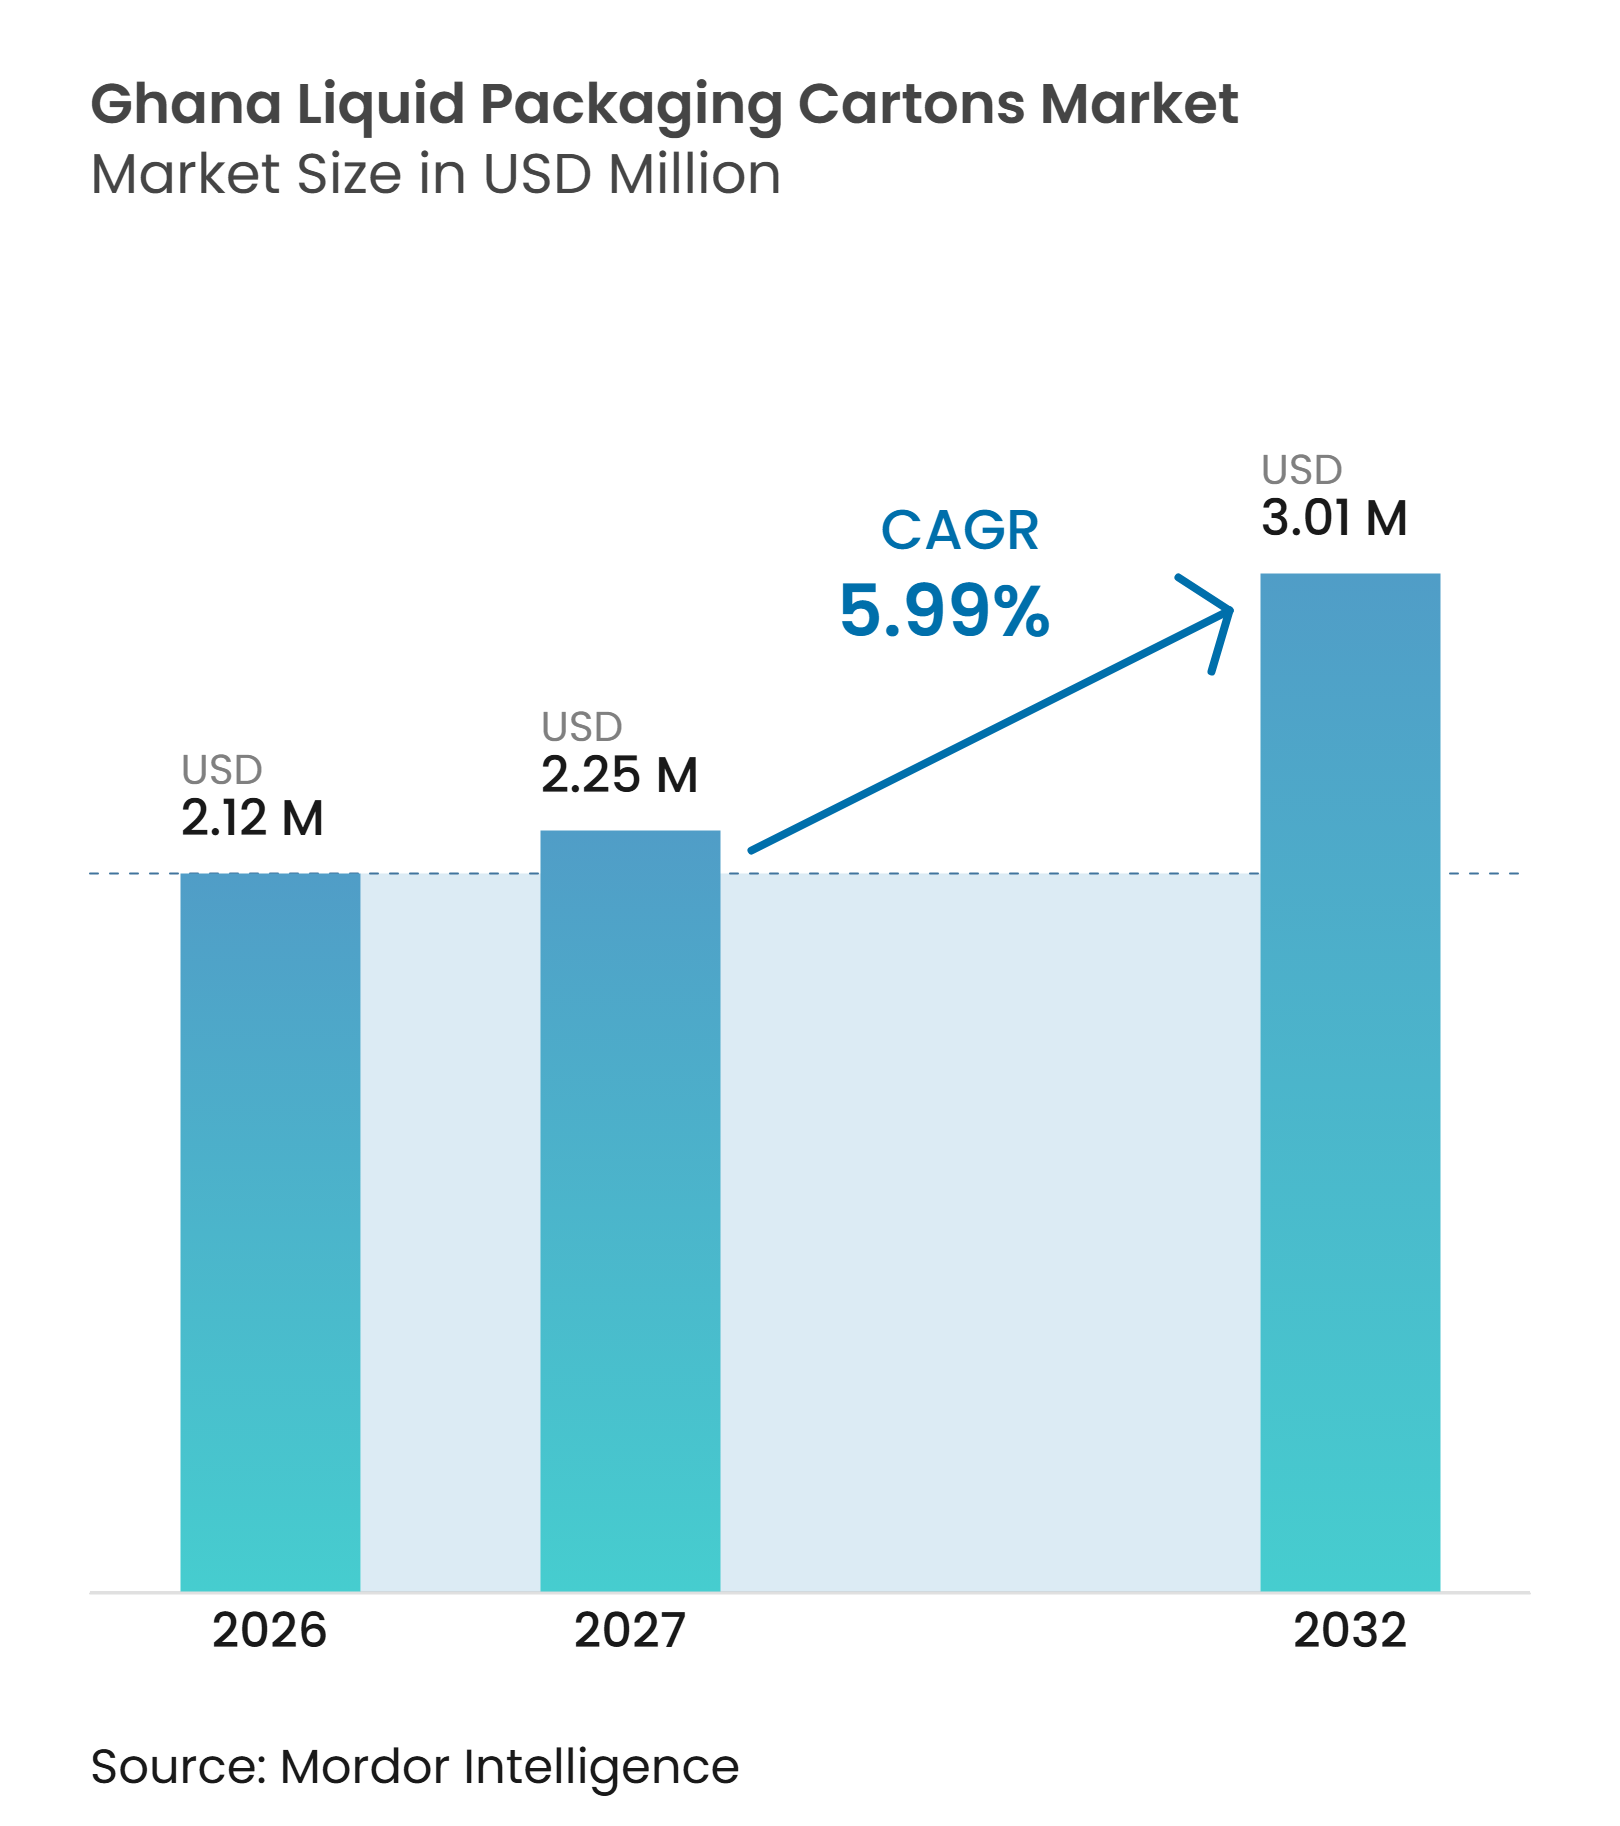
| Base Year Market Size (2026) | USD 2.12 Million |
| Market Size (2027) | USD 2.25 Million |
| Market Size (2032) | USD 3.01 Million |
| Growth Rate (2027 - 2032) | 5.99 % |
| Market Concentration | High |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Ghana Liquid Packaging Cartons Market Analysis by Mordor Intelligence
The Ghana Liquid Packaging Cartons Market size is projected to expand from USD 2.12 million in 2026 and USD 2.25 million in 2027 to USD 3.01 million by 2032, registering a CAGR of 5.99% between 2027 and 2032.
The Ghana liquid packaging cartons market benefits from urban demand for shelf-stable milk, juice, and flavored drinks that can move through distribution networks with limited refrigeration. Aseptic formats remain important because they enable nationwide distribution without refrigeration before opening. Local beverage producers are expanding carton-based offerings through partnerships with established packaging system suppliers. Imported boards and laminates expose processors to currency fluctuations and longer replenishment cycles. Electricity costs also pressure conversion economics, while planned industrial solar capacity could support investment in food processing and packaging operations.
Key Report Takeaways
- By product type, aseptic cartons held 89.31% of the Ghana liquid packaging cartons market share in 2026 and are projected to expand at a 6.17% CAGR through 2032.
- By application, milk accounted for 44.82% of the Ghana liquid packaging cartons market size in 2026, while plant-based beverages are projected to record a 7.04% CAGR through 2032.
- By pack size, formats below 250 ml held 48.63% of the Ghana liquid packaging cartons market share in 2026 and are expected to expand at a 6.57% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Ghana Liquid Packaging Cartons Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Expansion of Locally Produced Shelf-Stable Milk and Flavored Milk | +1.8% | National, concentrated gains in Greater Accra and Ashanti Region | Medium term (2-4 years) |
| Convenience and School-Channel Demand for Small-Format Packs | +1.4% | National, with early gains in Greater Accra, Ashanti, and Central Region | Short term (≤ 2 years) |
| Cold-Chain Gaps Increasing the Value of Ambient Cartons | +1.2% | National, strongest structural pull in Northern and Upper Regions | Long term (≥ 4 years) |
| Sustainability-Led Shift Toward Fiber-Based Packaging | +0.6% | National, early adoption gains in Accra and Kumasi trade zones | Medium term (2-4 years) |
| Local Plant-Based Beverage Diversification | +0.5% | National, concentrated in urban centers and university towns | Medium term (2-4 years) |
| Aseptic Technology Partnerships Expanding Domestic Product Capability | +0.4% | National, centered on Tema and Greater Accra industrial corridor | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Expansion of Locally Produced Shelf-Stable Milk and Flavored Milk
Ghanaian processors are using shelf-stable milk and flavored milk to replace part of the volume previously served by imported products. Fan Milk PLC reported GHS 1 billion (USD 84.86 million) in revenue in fiscal year 2025, and dairy sales contributed GHS 1.04 billion (USD 88.25 million) of gross revenue in its audited results. Niche Cocoa Industry launched Daily Milk in October 2025 in 180 ml aseptic cartons with banana, vanilla, and strawberry variants. Ghana relies on imported milk powder for local processing because domestic raw milk production remains limited at scale. This production model supports aseptic packs because recombined milk must be distributed with stable quality across a broad retail network. Each additional aseptic filling line can create recurring demand for laminate and related packaging materials in the Ghana liquid packaging cartons market.
Convenience and School-Channel Demand for Small-Format Packs
The school channel provides a defined route to market for small, shelf-stable beverage formats. Niche Cocoa Industry and the Ministry of Education signed an agreement to supply enriched ready-to-drink cocoa beverages to 1.8 million basic schoolchildren across 6 cocoa-growing regions. The agreement states an intention to extend supply to 5.6 million children nationally. Institutional buyers require consistent shelf life, hygienic delivery, and ambient storage, which align with aseptic carton formats. Research on urban Ghanaian school food environments found that branded industrial beverages were present at 30.9% of school-adjacent vendor sites. This demand supports the position of sub-250 ml formats in the Ghana liquid packaging cartons market, particularly in school and convenience channels.
Cold-Chain Gaps Increasing the Value of Ambient Cartons
Cold-chain limitations make ambient shelf life a practical requirement for many beverage producers in Ghana. The Global Cold Chain Foundation reported limited temperature-controlled transport from farms to collection centers and few third-party logistics providers in the country. The assessment also identified weaker road and rail infrastructure outside Accra.[1] Products requiring refrigeration, therefore, face greater spoilage and service risks in the Northern, Upper East, Upper West, Volta, and Brong-Ahafo regions. Denmark and Ghana formalized a cold-chain partnership in November 2025 to improve capacity through participation in agribusiness, development finance, and local manufacturing. Until this infrastructure becomes more widely available, ambient cartons remain a practical distribution format for the Ghana liquid packaging cartons market.
Sustainability-Led Shift Toward Fiber-Based Packaging
Packaging decisions are increasingly shaped by Ghanaian plastic waste policy and export compliance requirements. Ghana's Environmental Protection Authority stated in February 2025 that it would engage supermarket owners and trade permit holders on a shift from single-use plastics to paper packaging. The European Union Packaging and Packaging Waste Regulation applies recyclability, traceability, and recycled-content requirements to agri-food exports from July 2026. A 2025 scientific study identified weak enforcement, the high cost of biodegradable materials, and limited recycling infrastructure as barriers to the adoption of eco-design in Ghana. The same study identified extended producer responsibility programs and phased plastic bans as policy tools that can change packaging procurement. These conditions favor fiber-based carton options where brand owners need to address both domestic and export requirements.
Restraints Impact Analysis of Ghana Liquid Packaging Cartons Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Imported Board and Laminate Exposure to Currency and Long Lead Times | -1.5% | National | Medium term (2-4 years) |
| High Electricity and Conversion Costs for Local Packaging Operations | -1.2% | National, with acute pressure in Accra and Kumasi manufacturing zones | Short term (≤ 2 years) |
| Limited Local Testing, Collection, and Recycling Infrastructure | -0.8% | National, widest gap in secondary and peri-urban areas | Long term (≥ 4 years) |
| Price Sensitivity Favoring Lower-Cost Non-Carton Formats | -0.7% | National, most acute in rural and peri-urban markets | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Imported Board and Laminate Exposure to Currency and Long Lead Times
Liquid carton production depends on multilayer paperboard, polyethylene, and aluminum laminates that are imported into Ghana. The cedi depreciated by 10.4% against the US dollar in the year to July 2026, raising local-currency costs for imported packaging inputs and spare parts. Camelot Ghana reported a 43% increase in cost of sales in fiscal year 2025, mainly due to exchange-rate-driven inflation in the cost of imported raw materials. The exposure limits local processors' ability to manage input costs through operating efficiencies alone. It also increases working-capital needs when imported inputs must be ordered well before delivery. These pressures may reduce the price competitiveness of carton products in more price-sensitive channels.
High Electricity and Conversion Costs for Local Packaging Operations
Electricity costs remain a direct constraint on aseptic filling and carton conversion operations. Ghana's Public Utilities Regulatory Commission implemented a 14.75% tariff increase in May 2025, followed by a 9.86% increase effective January 2026, before a 4.81% reduction effective April 2026. The Ghana National Chamber of Commerce and Industry stated that energy can account for 30-40% of operating costs for many Ghanaian businesses. The Association of Ghana Industries found that 19% of surveyed businesses identified electricity cost as their main operating challenge in the second quarter of 2026. Continuous aseptic lines also depend on a stable electricity supply, making interruptions an additional operating risk. Solar projects in industrial zones could reduce this burden for some manufacturers over time.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Ghana Liquid Packaging Cartons Market Segment Analysis
By Product Type:
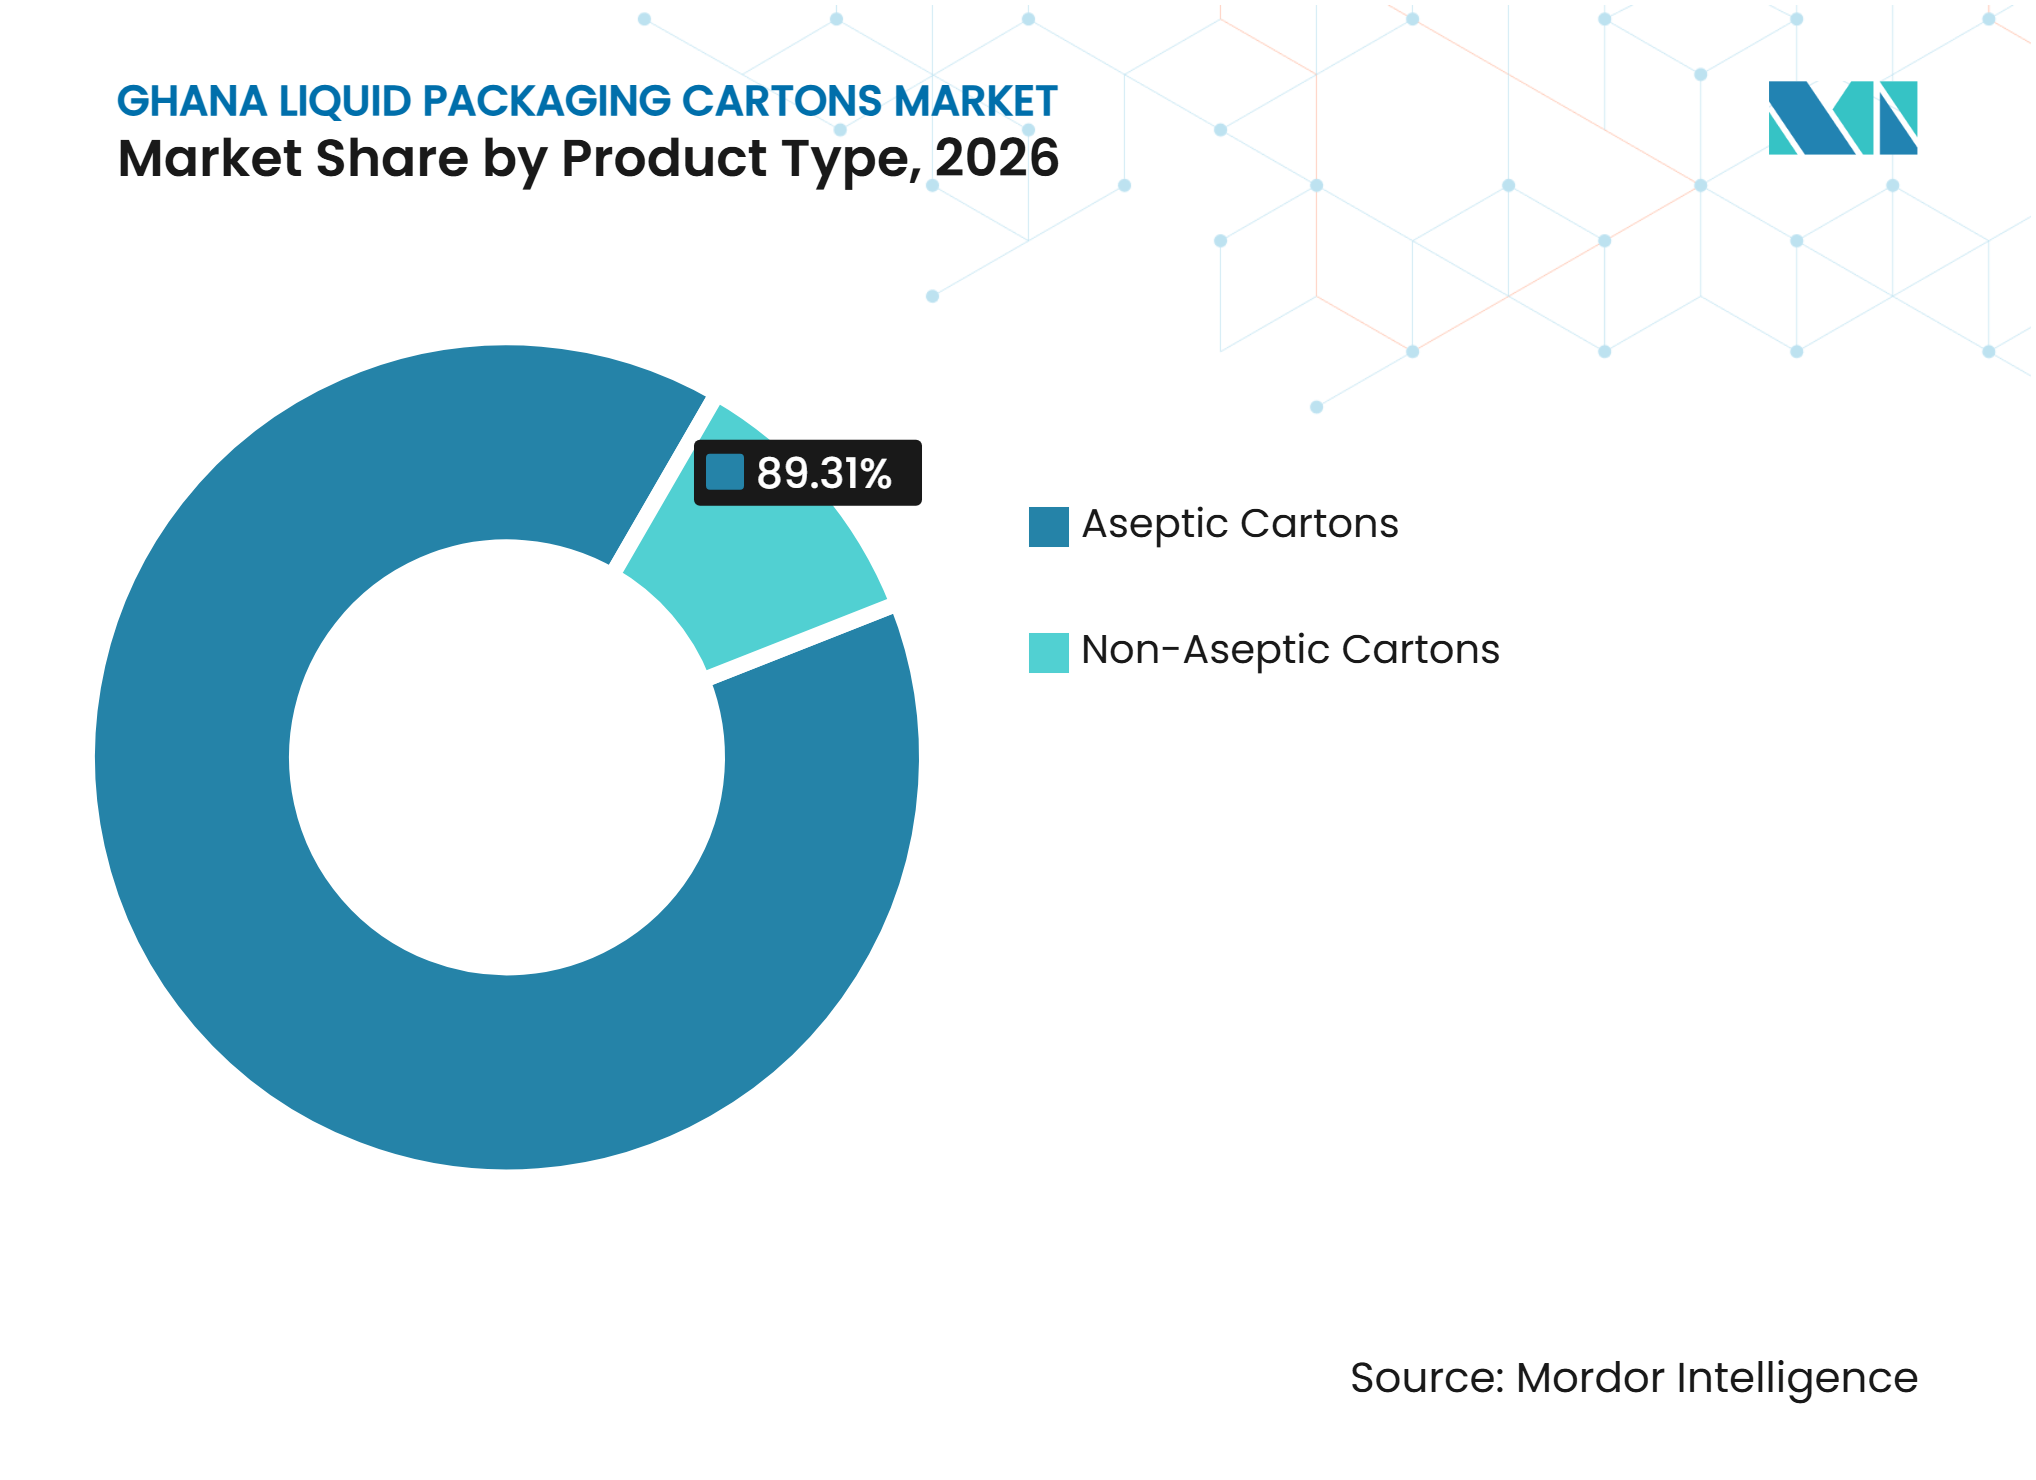
Aseptic Technology Anchors Market DemandAseptic cartons held an 89.31% share in the Ghana liquid packaging cartons market in 2026 and are projected to expand at a 6.17% CAGR through 2032. This position reflects the need for safe storage and distribution where refrigerated transport is limited. The Global Cold Chain Foundation found that temperature-controlled logistics remain minimal outside Accra and that few third-party logistics providers operate in Ghana. Aseptic packs allow beverages to remain stable before opening and enable producers to reach distant regions without continuous cold storage. Tetra Pak and Niche Cocoa Industry introduced Daily Milk in October 2025 using aseptic packaging designed for a 9-month ambient shelf life.
Non-aseptic cartons continue to play a smaller role in chilled dairy and juice products sold through urban retail channels. These formats are more practical where shorter refrigerated transport routes and retail refrigeration are available. SIG announced 17 new filling-line agreements across India, the Middle East, and Africa in August 2026, covering aseptic cartons, spouted pouches, and bag-in-box products. SIG also launched its Neo aseptic platform in April 2026, offering pack-size changes in under 15 minutes without machine-part changes. The Ghana liquid packaging cartons industry therefore remains oriented toward aseptic systems, while chilled-carton options serve a narrower urban requirement.



By Application:
Milk Holds Volume While Plant-Based Beverages AccelerateMilk accounted for 44.82% of the liquid packaging carton market in Ghana in 2026. Ghana imports milk powder for local processing because domestic milk supply is not available at a sufficient scale to meet broad processing needs. Recombined UHT milk is therefore an accessible dairy format for many consumers. Juices are the next major use case because cartons extend product availability in areas with limited retail refrigeration. Fan Milk's fiscal year 2025 results demonstrate the continued value of dairy demand for local beverage processors.
Plant-based beverages are projected to record the fastest application CAGR of 7.04% through 2032. Soy milk has an established local presence through the Vitamilk brand, while products based on cashew, tiger nut, and almond target consumers in Accra. Research from the University of Science and Technology of Education found that price and psychological resistance were the main barriers to the adoption of plant-based milk in Accra. Dairy products other than milk, including drinking yogurt and fermented beverages, remain more associated with chilled retail. Liquid foods, cooking creams, specialty nutrition drinks, and energy drinks currently have a limited role in cartons but offer product-development opportunities for the Ghana liquid packaging cartons market.
By Pack Size:
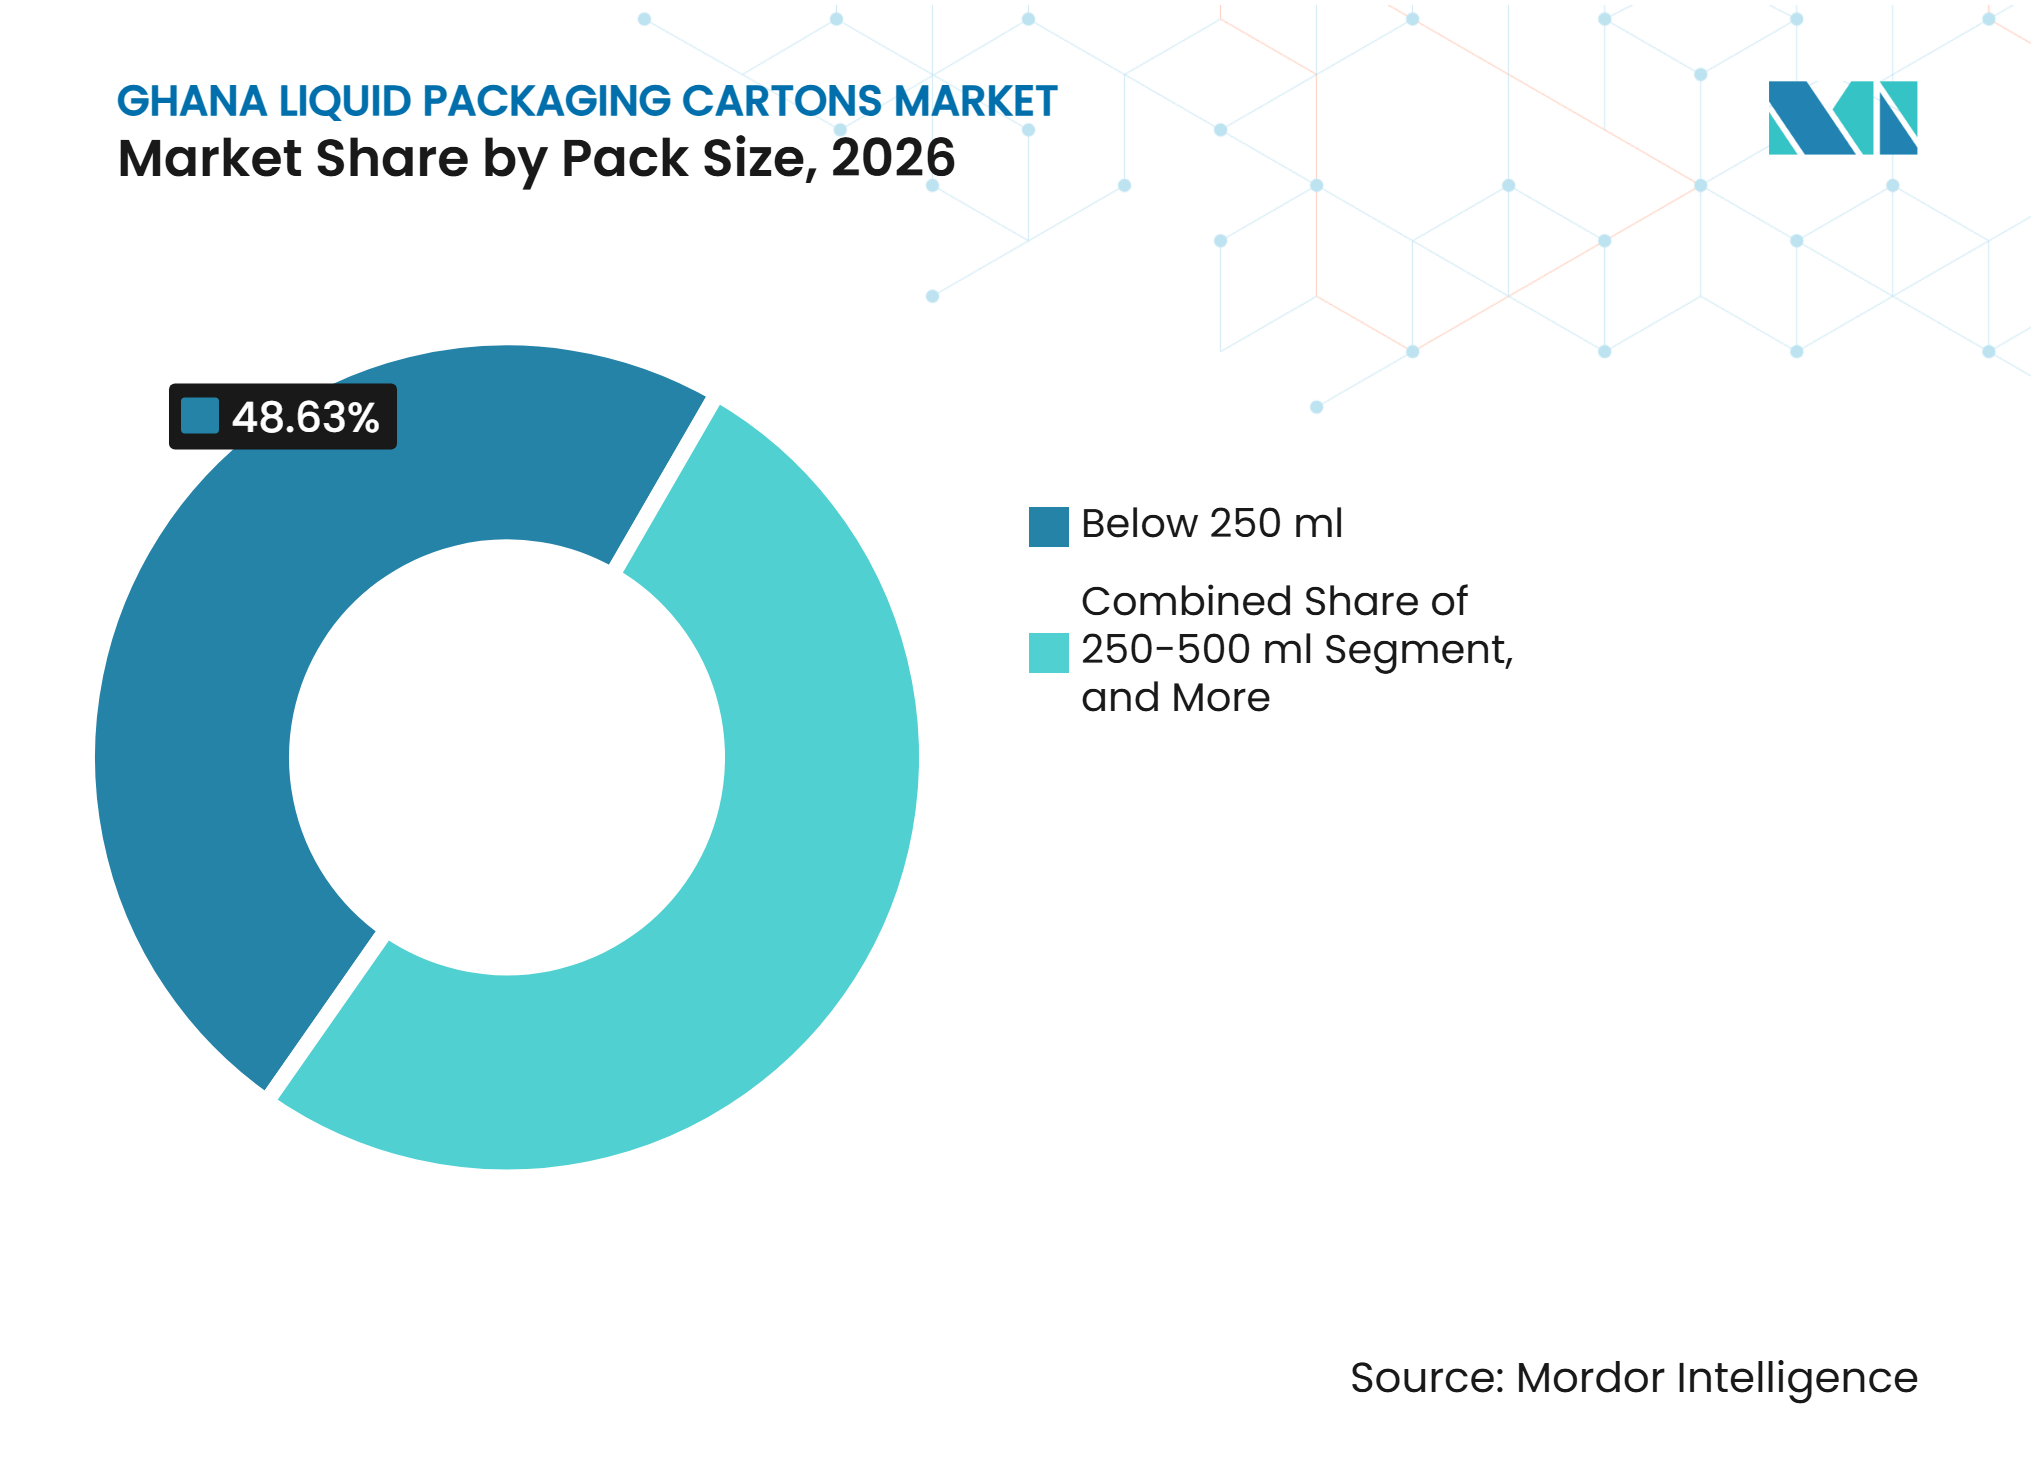
Small Formats Lead on Share and Forecast ExpansionFormats below 250 ml held a 48.63% share in the Ghana liquid packaging cartons market in 2026 and are expected to expand at a 6.57% CAGR through 2032. These pack sizes fit school breaks, urban travel, and single-serve purchasing patterns. Daily Milk was introduced in 180 ml aseptic cartons for school breaks, sports activities, and study sessions. Niche Cocoa Industry also signed an agreement to supply ready-to-drink cocoa beverages to 1.8 million schoolchildren in 6 cocoa-growing regions. The size range benefits from both institutional distribution and everyday convenience purchases.
The 250-500 ml range serves household and food-service use, especially for ambient milk and juice purchases in urban homes. Formats above 500 ml are used more often by institutional buyers, caterers, and food-service operators. These larger packs face stronger competition from chilled bulk formats where refrigeration is available at the point of service. Tetra Pak and Sterilgarda Alimenti launched a 1-liter aseptic carton with a paper-based barrier in April 2026. This material development indicates a route to reduced aluminum dependence and improved end-of-life recyclability across pack sizes in the Ghanaian liquid packaging carton market.

Geography Analysis
Greater Accra: Commercial Hub and Primary Entry Point
Greater Accra concentrates modern retail, food service, institutional buyers, and the port gateway at Tema. This concentration supports demand for shelf-stable milk, ambient juice, and flavored beverages across supermarkets, convenience stores, and school canteens. Fan Milk's Accra-based operations contributed GHS 1.04 billion (USD 88.25 million) in dairy sales in fiscal year 2025. Tema Industrial Zone and Dawa Industrial Zone also place processing, logistics, packaging activities, and equipment services within a single corridor. The planned 100 MW solar project at Dawa Industrial Zone is intended to serve manufacturers and agro-processors. These factors make Greater Accra the main entry point for investment in Ghana's liquid packaging carton market and for national distribution.
Ashanti Region: Manufacturing Strength and Secondary Demand
The Ashanti Region is an important inland area for demand and distribution, centered on Kumasi. Dense trader networks and regional market infrastructure support movement into surrounding towns and rural markets. Kasapreko operated 9 Krones filling lines by 2025, including an 80,000-bottles-per-hour PET line commissioned in Kumasi in 2022.[2] Its manufacturing presence demonstrates the beverage-production scale that supports packaging demand in the region. Kumasi's population, student base, and informal trade networks reinforce demand for convenient beverage formats, while limited refrigeration in secondary retail keeps ambient cartons relevant.
School Programs Drive Peripheral Deman
The Western, Central, Northern, Upper East, Upper West, and Volta regions offer a broader distribution opportunity for ambient cartons. The Ghana School Feeding Program helps expand branded beverage distribution beyond conventional modern retail channels. Northern and Upper regions have pronounced cold-chain gaps identified in the Global Cold Chain Foundation assessment. The Ghana liquid packaging cartons market size is supported by the need for products that move without continuous refrigeration. Denmark and Ghana's 2025 cold-chain partnership seeks to reduce post-harvest losses and improve local capacity. Aseptic cartons remain useful for national coverage across Ghana's 16 administrative regions while refrigeration infrastructure develops.
Competitive Landscape
Market Concentration
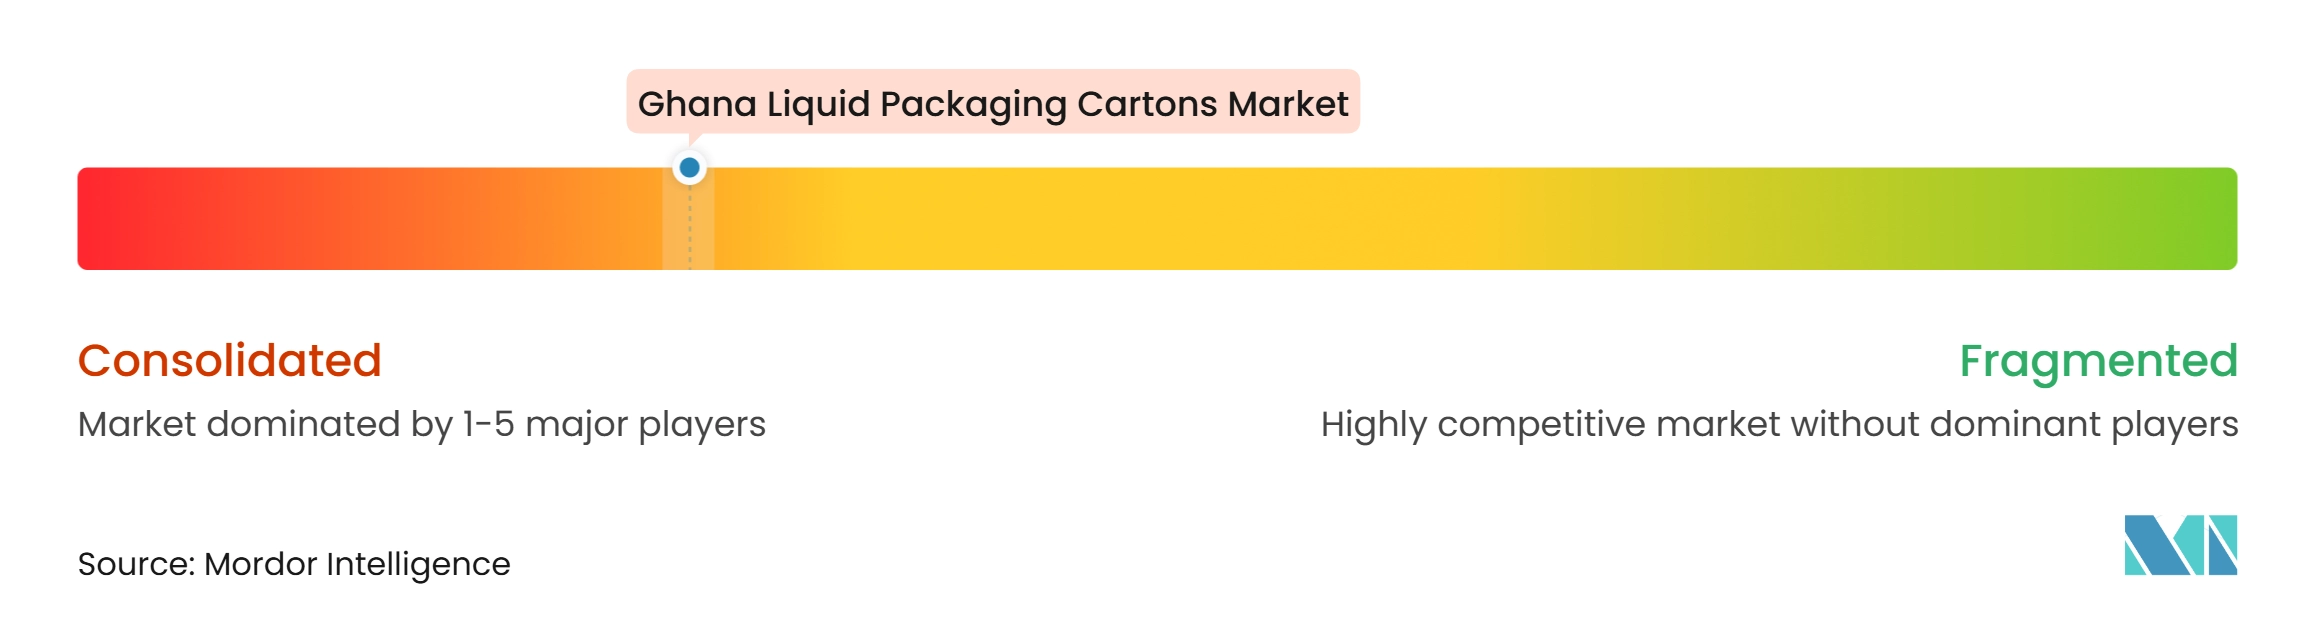
Tetra Pak International SA, SIG Group AG, and Elopak ASA compete at the technology-system level in the Ghana liquid packaging cartons market, which is highly concentrated. Their filling equipment, proprietary laminate systems, consumables, and service arrangements create high switching barriers after a processor selects a platform. A platform change can require capital investment and product requalification by the beverage producer. This structure supports recurring revenue from consumables and maintenance for established suppliers. Local beverage brands compete more directly through distribution, price points, and products suited to Ghanaian consumers.
SIG relocated its Lagos office in February 2026 to serve as its West Africa hub, including Ghana, providing closer technical, sales, customer service, and after-sales support.[3] Tetra Pak and Niche Cocoa Industry jointly launched Daily Milk in Accra in October 2025, adding a locally tailored aseptic flavored-milk range. Kasapreko was listed on the Ghana Stock Exchange in June 2026 after a GHS 700 million (USD 59.40 million) initial public offering. Its prospectus allocated 96% of proceeds to a high-capacity water and carbonated soft-drinks facility at Adeiso. These actions build commercial positions through service coverage, product development, and production capacity.
Paper-based barrier systems, smaller aseptic filling lines, and used-carton collection infrastructure remain areas for further development. Smaller filling lines could make aseptic production more accessible to local plant-based brands with modest initial volumes. Royal Crown Packaging Ghana Limited and FON Packaging Ventures serve smaller converter and trade-label needs that large system suppliers may not address.
Ghana Liquid Packaging Cartons Industry Leaders
-
Tetra Pak International SA
-
SIG Group AG
-
Elopak ASA
-
Greatview Aseptic Packaging Co. Ltd.
-
Novolex Holdings, LLC
- *Disclaimer: Major Players sorted in no particular order
Ghana Liquid Packaging Cartons Market Companies Covered in this Report
- Tetra Pak International SA
- SIG Group AG
- Elopak ASA
- Greatview Aseptic Packaging Co. Ltd.
- Pactiv Evergreen Inc.
- Nippon Paper Industries Co., Ltd.
- UFlex Limited
- IPI S.r.l.
- Mondi Group plc
- Stora Enso Oyj
- Obeikan Investment Group
- Nampak Limited
- Royal Crown Packaging Ghana Limited
- Polytanks (Gh) Ltd - Kraft Division
- FON Packaging Ventures
- Universal Labelling & Packaging Services Ltd (UNIPACK)
- Packaging Matrixx
- Everpack
- Finepack
- Ecopack
- Accra Brewery Limited (AB InBev Ghana)
- Kasapreko Company Limited
- Niche Cocoa Industry Ltd
- Gentle Giants Ltd (Vitamilk)
- Namio Ghana Ltd
- Delsoy Milk Drink Limited
Recent Industry Developments in Ghana Liquid Packaging Cartons Market
- August 2026: SIG Group announced agreements for 17 new filling lines with manufacturers across India, the Middle East and Africa at Gulfood Manufacturing 2026. The agreements covered aseptic cartons, spouted pouches, and bag-in-box products. The agreements included West Africa among the targeted regions and reflected SIG's geographic expansion strategy.
- June 2026: Kasapreko PLC was listed on the Ghana Stock Exchange following a GHS 700 million (USD 59.40 million) initial public offering. The company earmarked 96% of the proceeds for a high-capacity facility for water and carbonated soft drinks at Adeiso in Ghana's Eastern Region. The Adeiso facility targets a combined filling capacity of 250,000 bottles per hour and is expected to strengthen demand for beverage packaging from late 2026.
- April 2026: SIG Group launched the SIG Neo filling machine platform for aseptic cartons. The platform includes Neo Shield sterile airflow technology and supports pack-size changeovers in under 15 minutes without machine-part changes. SIG stated that the Neo Slimline 15 Aseptic variant can reduce total filling costs by up to 15% compared with standard multi-serve aseptic filling machines.
- April 2026: Tetra Pak International SA and Sterilgarda Alimenti launched a 1-liter aseptic carton with a paper-based barrier. The development indicated a material pathway that could reduce aluminum-laminate use while improving recyclability. The launch is relevant to carton producers that are evaluating lower-input-dependency packaging options.
Ghana Liquid Packaging Cartons Market Report Scope
The Ghana liquid packaging cartons market encompasses the production, supply, and consumption of carton-based packaging solutions for storing, protecting, transporting, and distributing liquid and semi-liquid food and beverage products in Ghana.
The Ghana Liquid Packaging Cartons Market Report is Segmented by Product Type (Aseptic Cartons and Non-Aseptic Cartons), Application (Milk, Juices, Plant-Based Beverages, Dairy Products (Excluding Milk), Energy and Functional Drinks, Liquid Food, and Other Applications), and Pack Size (Below 250 ml, 250-500 ml, and Above 500 ml). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Aseptic Cartons |
| Non-Aseptic Cartons |
| Milk |
| Juices |
| Plant Based Beverages |
| Dairy Products (Excluding Milk) |
| Energy and Functional Drinks |
| Liquid Food |
| Other Applications |
| Below 250 ml |
| 250-500 ml |
| Above 500 ml |
| By Product Type | Aseptic Cartons |
| Non-Aseptic Cartons | |
| By Applications | Milk |
| Juices | |
| Plant Based Beverages | |
| Dairy Products (Excluding Milk) | |
| Energy and Functional Drinks | |
| Liquid Food | |
| Other Applications | |
| By Pack Size | Below 250 ml |
| 250-500 ml | |
| Above 500 ml |
Key Questions Answered in the Report
What is the projected size of the Ghana liquid packaging cartons market?
The Ghana liquid packaging cartons market is expected to increase from USD 2.12 million in 2026 to USD 3.01 million by 2032, at a 5.99% CAGR over 2027-2032.
Which product type leads liquid packaging cartons in Ghana?
Aseptic cartons led with 89.31% share in 2026 and are projected to expand at a 6.17% CAGR through 2032.
Why are aseptic cartons important for beverage distribution in Ghana?
They support ambient storage and distribution where cold-chain transport and reliable refrigeration are limited.
Which application is the largest for liquid packaging cartons in Ghana?
Milk held 44.82% of application demand in 2026, supported by locally processed recombined UHT milk.
Which pack size has the strongest outlook in Ghana?
Formats below 250 ml held 48.63% share in 2026 and are expected to expand at a 6.57% CAGR through 2032.
What factors constrain carton packaging operations in Ghana?
Imported material exposure, currency depreciation, electricity costs, and limited recycling infrastructure constrain operations.