
Air-Operated Double Diaphragm (AODD) Pumps Market Size and Share
Market Overview
| Study Period | 2022 - 2032 |
|---|---|
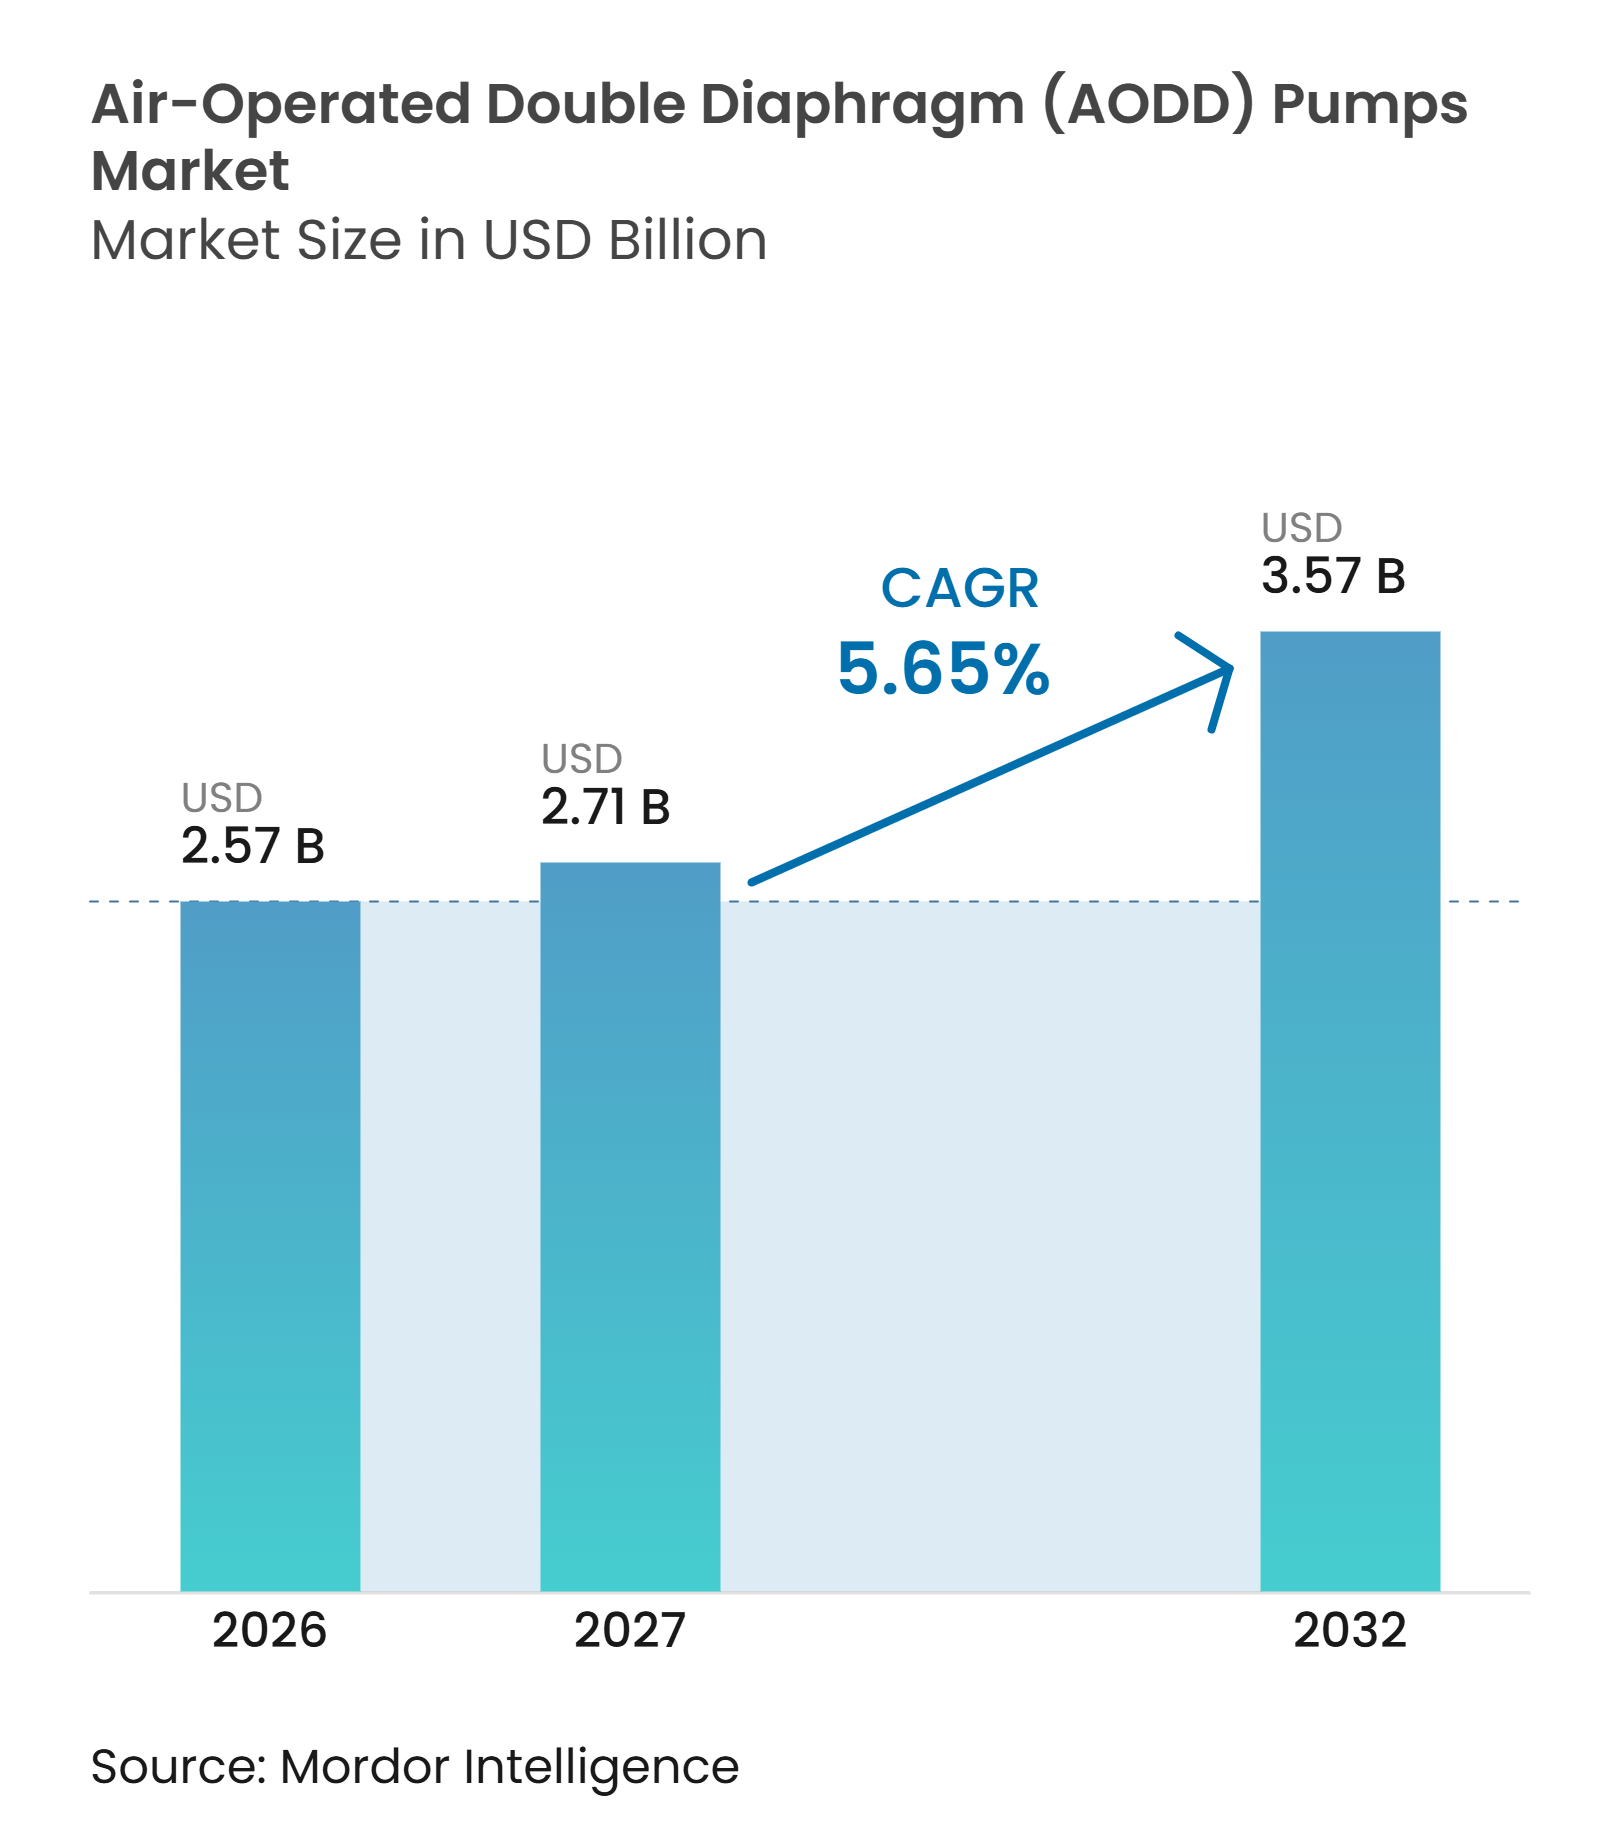
| Market Size (2027) | USD 2.71 Billion |
| Market Size (2032) | USD 3.57 Billion |
| Growth Rate (2027 - 2032) | 5.65 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | Asia-Pacific |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Air-Operated Double Diaphragm (AODD) Pumps Market Analysis by Mordor Intelligence
The Air-Operated Double Diaphragm Pumps Market size is projected to be USD 2.57 billion in 2026, USD 2.71 billion in 2027, and reach USD 3.57 billion by 2032, growing at a CAGR of 5.65% from 2027 to 2032. The air-operated double diaphragm (AODD) pumps market is supported by water and wastewater upgrades, chemical capacity additions, and demand for safer fluid transfer in hazardous and hygienic processes. These pumps can self-prime, handle abrasive fluids, and avoid an electrical component at the fluid-contact point, which supports their use in difficult process settings. Demand is also moving toward high-purity equipment for semiconductor plants, battery production, and pharmaceutical finishing, where corrosion resistance and contamination control matter. Suppliers are responding with sanitary, non-metallic, air-efficient, and electrically operated diaphragm products, which broaden customer choice but also increase competitive pressure. The air-operated double diaphragm (AODD) pumps market therefore benefits from infrastructure investment and specialized applications, while continuous-duty energy use remains a material limitation.
Key Report Takeaways
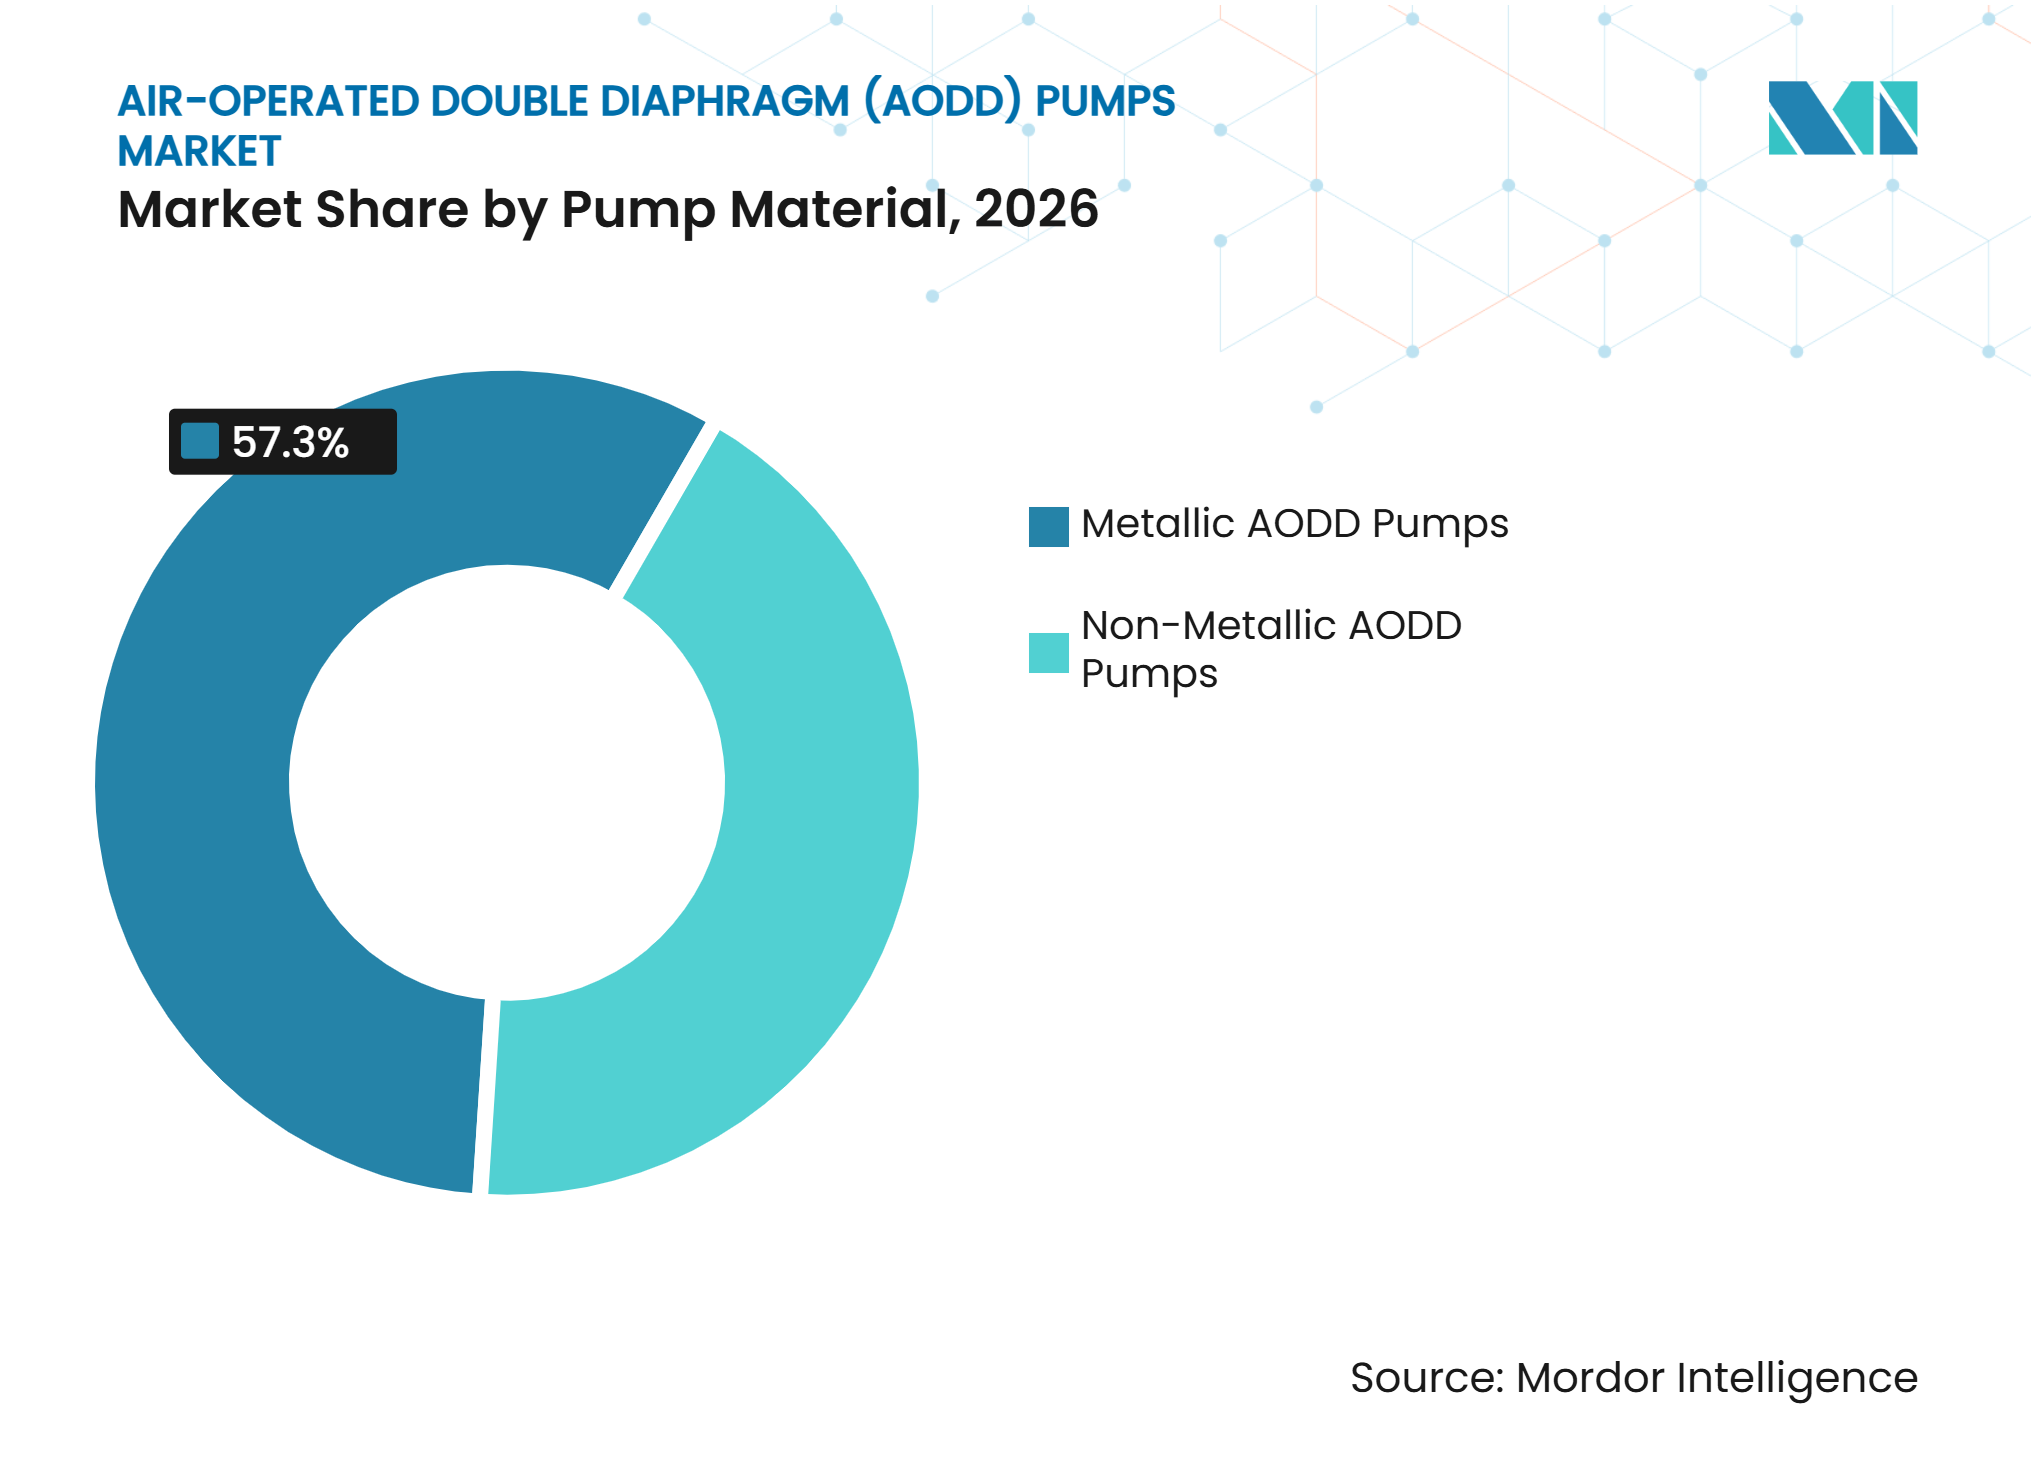
- By pump material, metallic pumps held 57.3% of the market share in 2026, while non-metallic pumps are forecast to expand at a 5.9% CAGR through 2032.
- By pump design, standard designs held 41.7% of the market share in 2026, while sanitary designs are forecast to expand at a 5.7% CAGR through 2032.
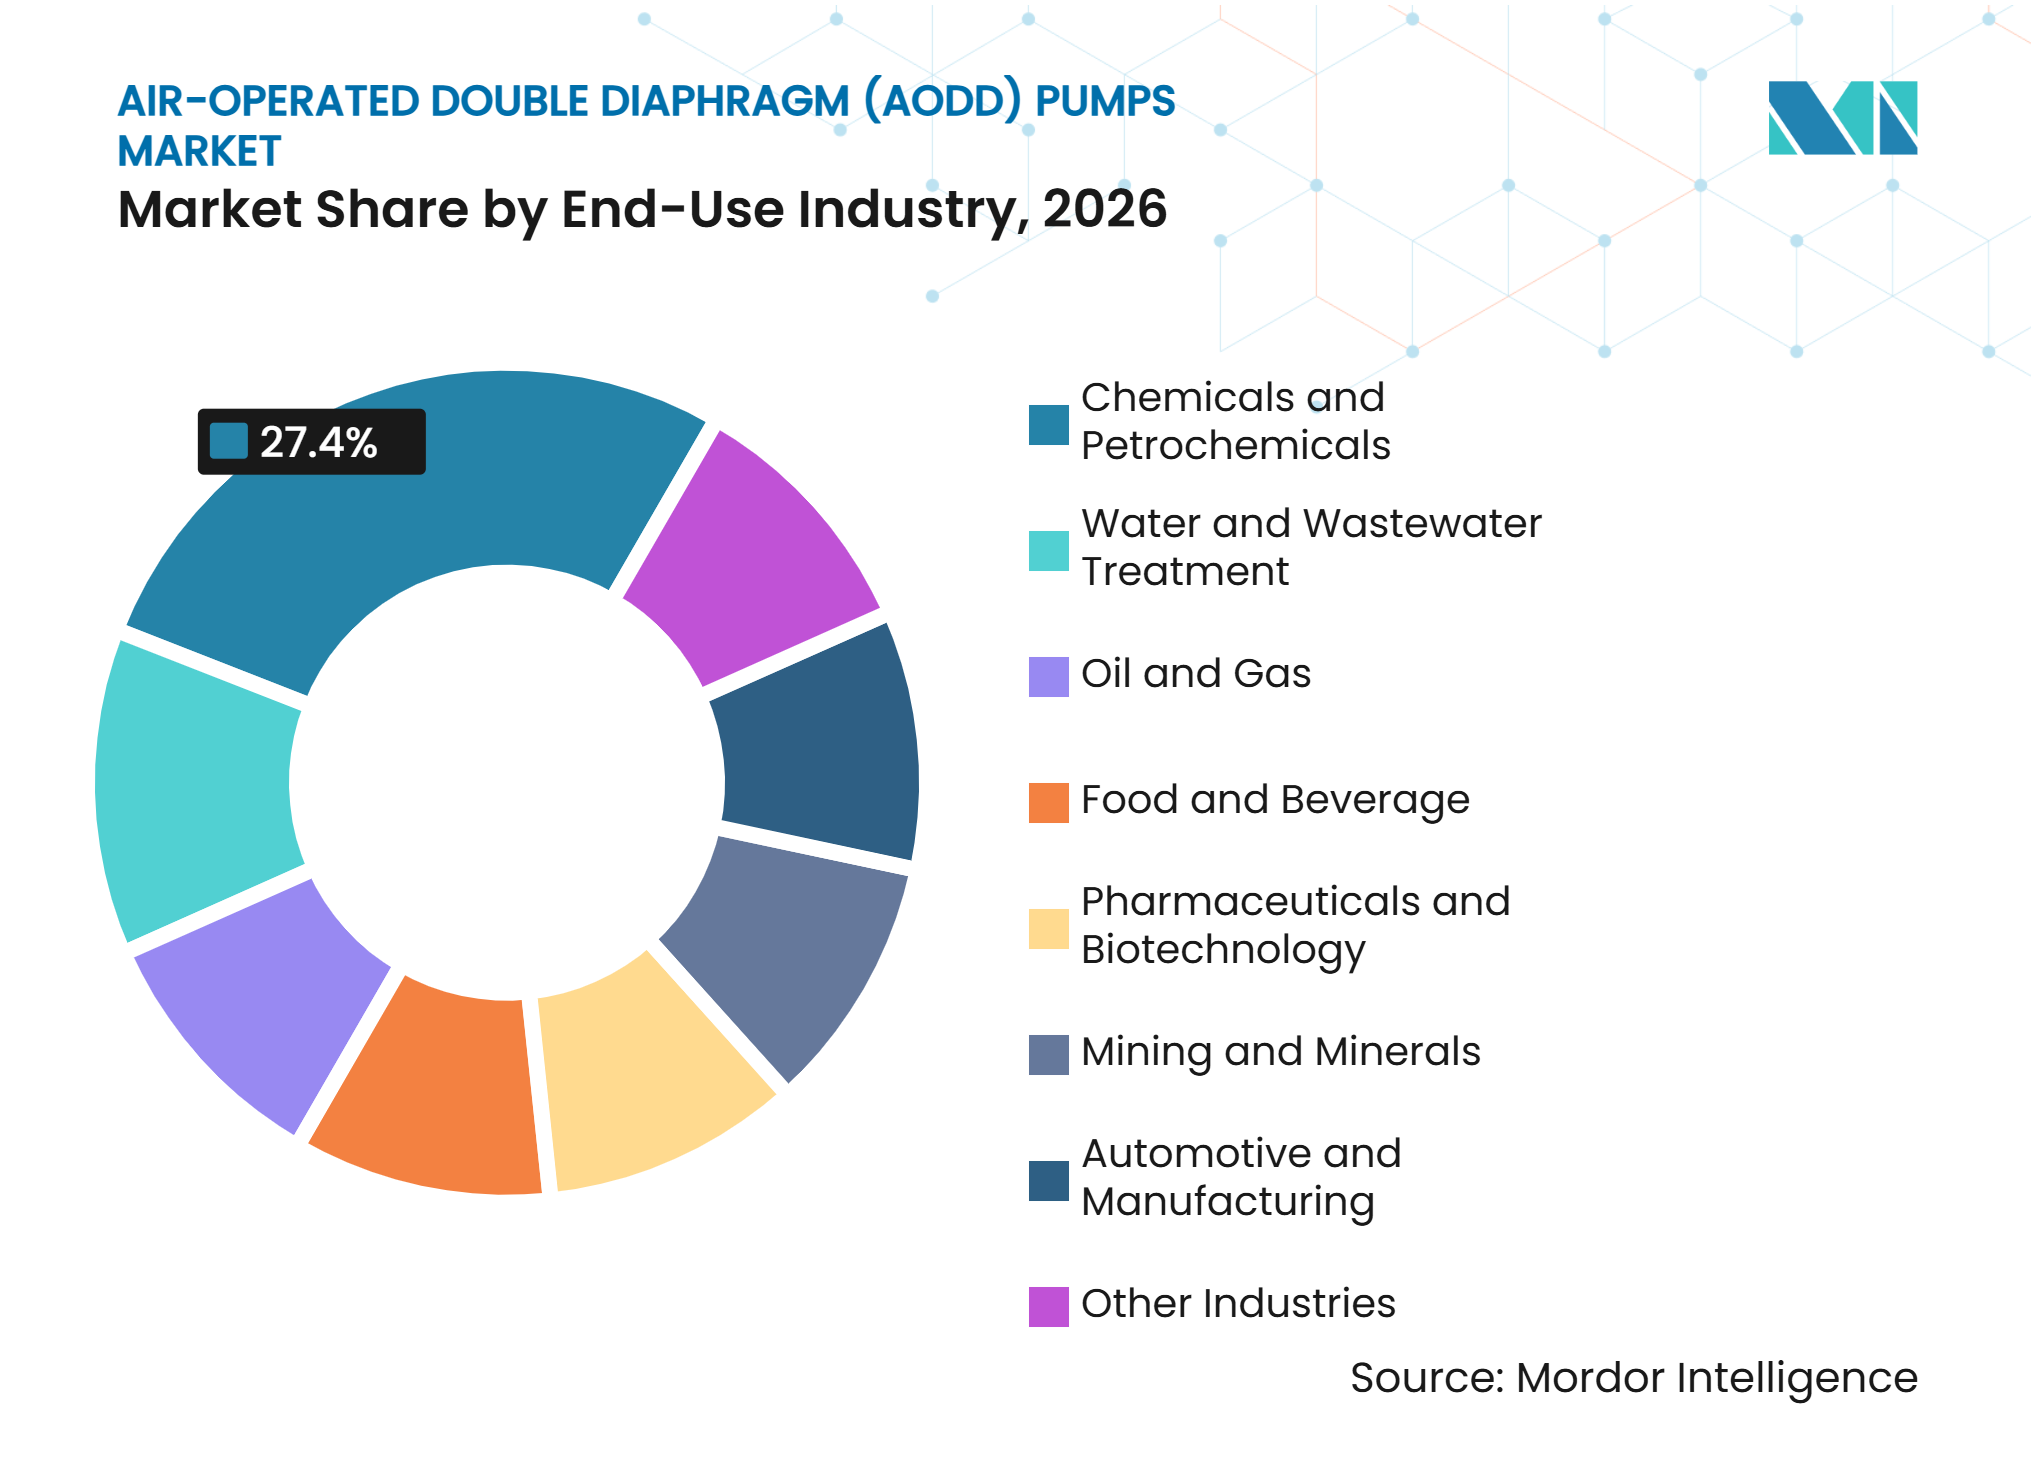
- By end-use industry, chemicals and petrochemicals held 27.4% of revenue in 2026, while pharmaceuticals and biotechnology are forecast to expand at a 6.8% CAGR through 2032.
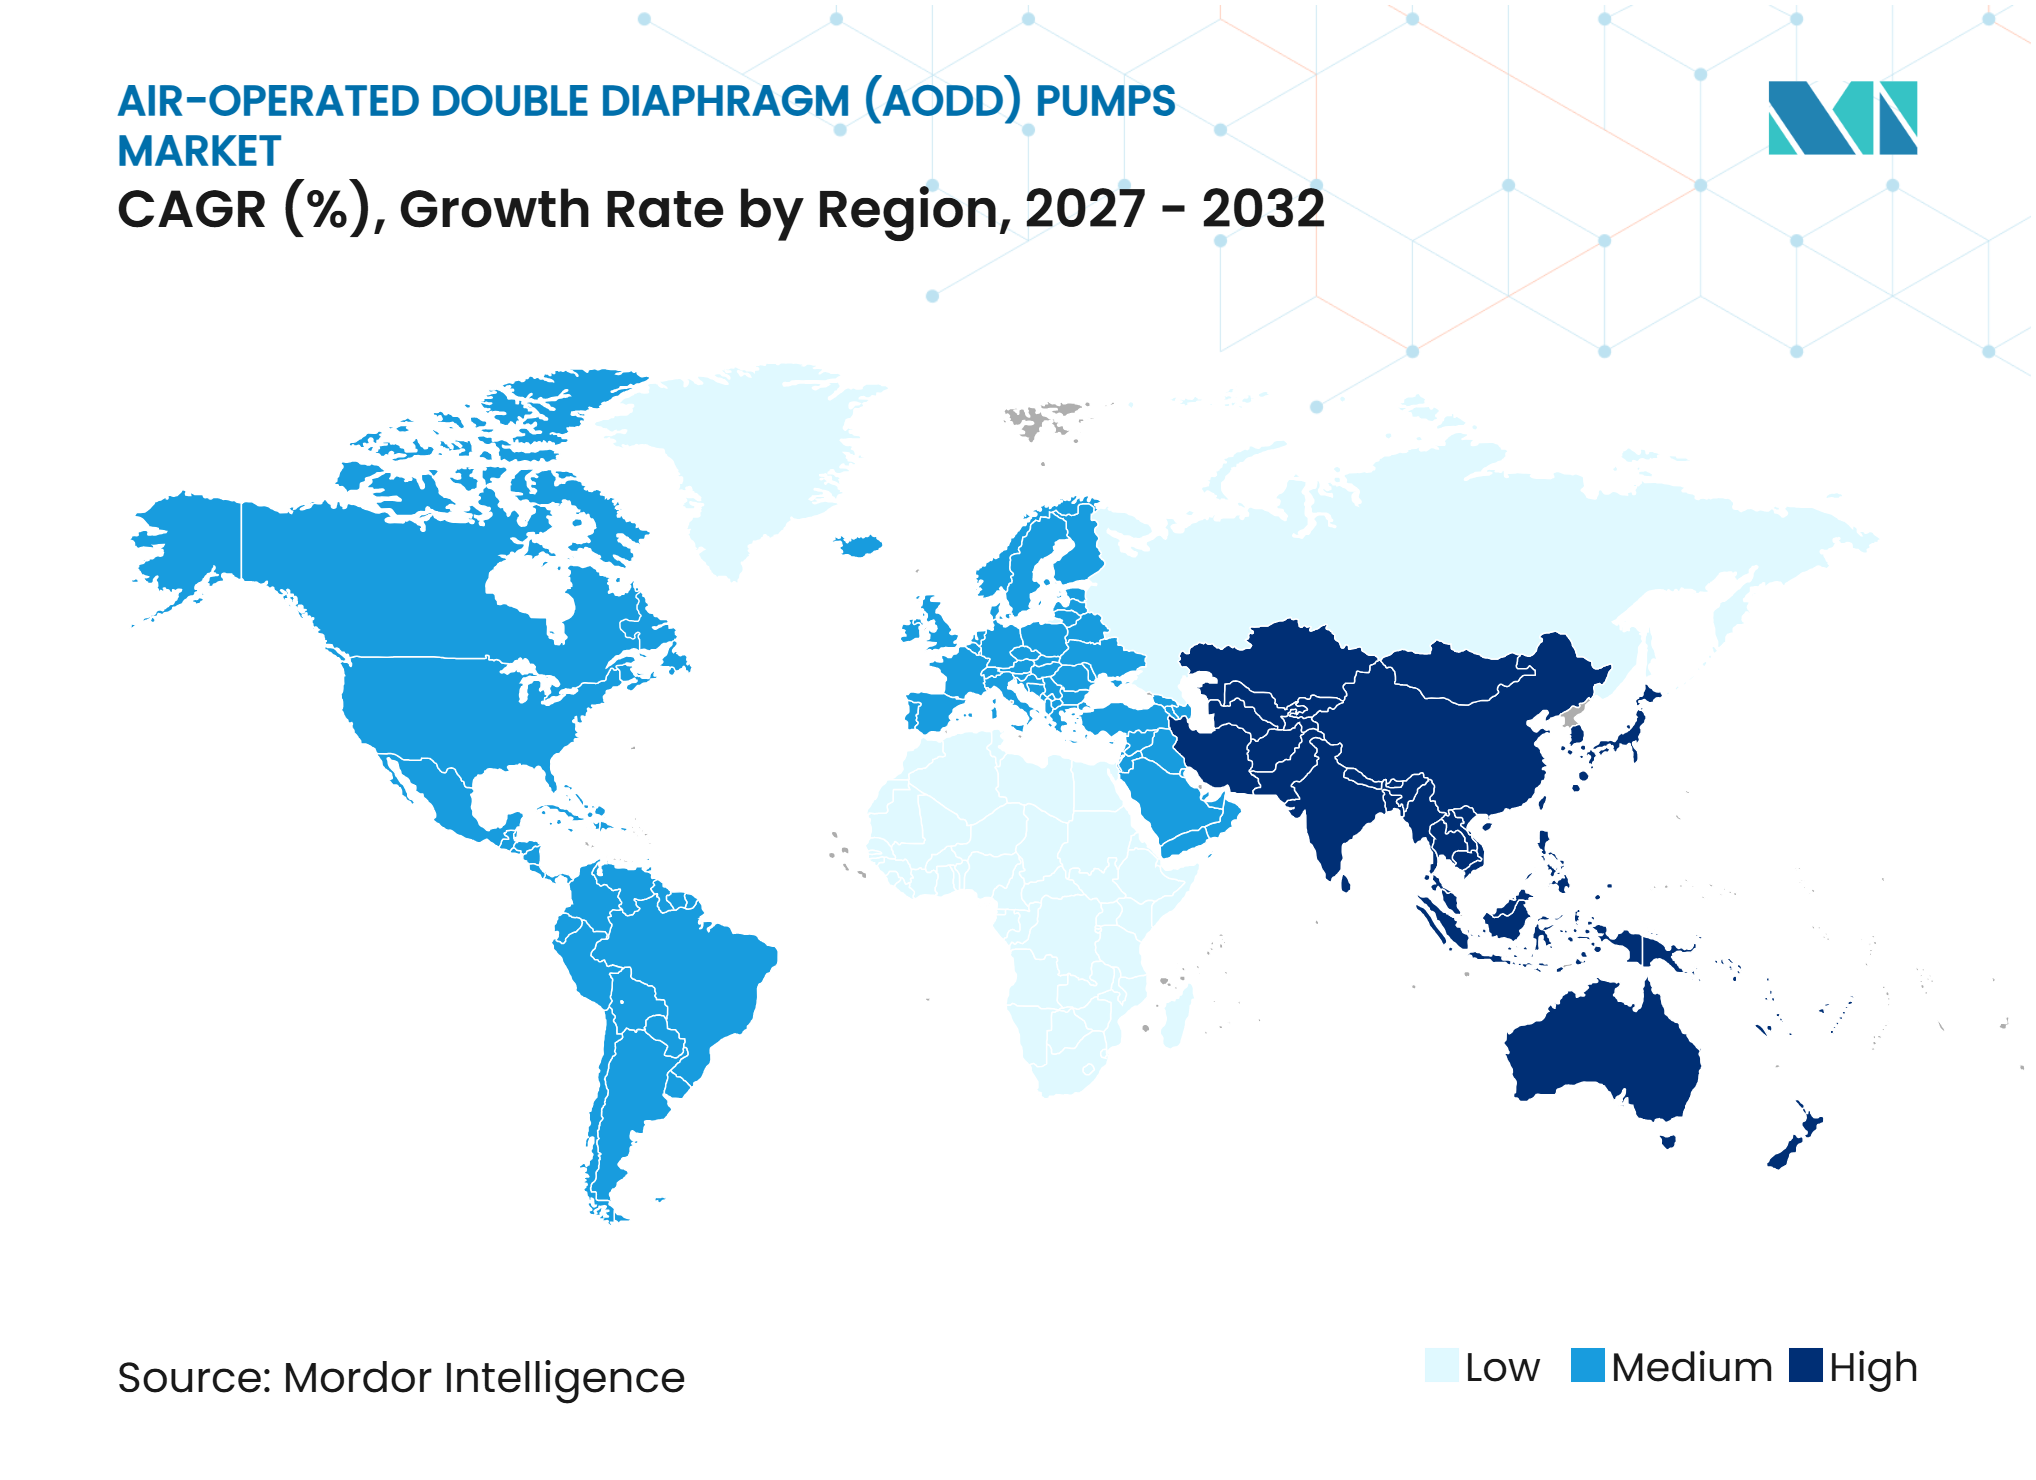
- By geography, Asia-Pacific held 51.8% of the market share in 2026 and is forecast to expand at a 6.1% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Air-Operated Double Diaphragm (AODD) Pumps Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Water And Wastewater Treatment Capacity Expansion | +1.2% | Global, led by North America, Asia-Pacific, and Middle East and Africa | Medium term (2-4 years) |
| Chemical And Petrochemical Capacity Additions | +1.0% | Middle East and Africa, Asia-Pacific, and South America | Long term (≥ 4 years) |
| Hazardous-Area And Leak-Free Fluid Handling Requirements | +0.8% | Global, particularly Europe and Asia-Pacific | Short term (≤ 2 years) |
| Sanitary Transfer Demand In Food, Beverage, And Pharmaceuticals | +0.7% | North America, Europe, and Asia-Pacific | Medium term (2-4 years) |
| Battery Materials And Semiconductor Chemical Handling | +0.5% | Asia-Pacific, with expansion into North America | Medium term (2-4 years) |
| Installed-Base Upgrades For Air-Efficient And Smart AODD Pumps | +0.4% | Global, with early gains in North America and Europe | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Water and Wastewater Treatment Capacity Expansion
Water and wastewater programs provide a durable source of orders for the air-operated double diaphragm (AODD) pumps market. Hillsborough County began its USD 1.2 billion One Water Wastewater Project in May 2026, adding treatment infrastructure that requires pumping and chemical handling equipment.[1] Halton is committing USD 3.68 billion (CAD 5.2 billion) through 2031 to water and wastewater infrastructure, supporting a multi-year equipment procurement cycle.[2] Cape Town is allocating USD 107.62 million (ZAR 1.77 billion) for wastewater treatment works extensions in FY2026, which reinforces demand for reliable sludge handling and chemical dosing systems.[3] These projects favor pumps that can manage solids, dosing chemicals, and variable operating conditions without extensive electrical equipment at the point of use. The air-operated double diaphragm (AODD) pumps market can benefit when public programs turn single equipment purchases into longer-term maintenance and replacement contracts.
Chemical and Petrochemical Capacity Additions
Chemical and petrochemical projects expand the need for corrosive-fluid transfer and dosing equipment in the air-operated double diaphragm (AODD) pumps market. Hengyi Industries confirmed a USD 5 billion expansion of its Brunei refinery complex, with Phase 2 operations expected from 2029. These projects commonly require equipment that can transfer aggressive process fluids and manage variable viscosity without compromising containment. Non-metallic pumps with polypropylene or polyvinylidene fluoride (PVDF) wetted parts are relevant where fluoropolymer streams or chemically aggressive media would limit the use of conventional metallic configurations. The air-operated double diaphragm (AODD) pumps market gains from new construction as well as from replacement demand at operating complexes. Suppliers with broad material options and hazardous-area certifications can address more of these projects as process conditions become more specialized.
Hazardous-Area and Leak-Free Fluid Handling Requirements
Hazardous-area requirements remain a core reason for specifying pneumatic diaphragm pumps. AODD designs have no electrical component near the fluid stream and use pressure-limited pneumatic operation, which supports their use around flammable liquids and explosive atmospheres. Yamada Corporation issued an ATEX 2025 Declaration of Conformity certified by DEKRA for its pump range, illustrating the importance of documented compliance in hazardous-area procurement.[4] Certification requirements can narrow the pool of eligible equipment suppliers and increase the value of established documentation and test records. The air-operated double diaphragm (AODD) pumps market is therefore less exposed to product substitution in classified zones than in general industrial settings. Manufacturers that pair ATEX and IEC System for Certification to Standards Relating to Equipment for Use in Explosive Atmospheres (IECEx)-ready product lines with material compatibility support can serve chemical, mining, and process customers more effectively.
Sanitary Transfer Demand in Food, Beverage, and Pharmaceuticals
Food, beverage, pharmaceutical, and biotechnology facilities require fluid handling equipment that supports cleaning, traceability, and appropriate contact materials. The U.S. Food and Drug Administration’s current good manufacturing practice regulations require suitable equipment design, cleaning, and maintenance for drug manufacturing operations. Tapflo delivered a multi-unit pump skid package to a multinational pharmaceutical manufacturer in Europe during January 2025. Sanitary AODD products with 316L stainless steel bodies and compatible diaphragm materials align with these requirements. The increase in outsourced development and manufacturing spreads production across more individual sites, each with separate equipment qualification and procurement needs. This structure supports recurring demand across the air-operated double diaphragm (AODD) pumps market rather than concentrating purchasing in a smaller number of captive plants.
Restraints Impact Analysis of Air-Operated Double Diaphragm (AODD) Pumps Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Compressed-Air Energy Intensity In Continuous-Duty Applications | -0.6% | Global | Short term (≤ 2 years) |
| Substitution By Electric, Centrifugal, And Peristaltic Pumps | -0.5% | North America and Europe | Medium term (2-4 years) |
| Limited Availability Of Skilled Pneumatic-Pump Service Technicians | -0.3% | Middle East and Africa, South America, and emerging Asia-Pacific | Long term (≥ 4 years) |
| Certification And Material-Compatibility Costs For Specialized Applications | -0.2% | Global | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Compressed-Air Energy Intensity in Continuous-Duty Applications
Compressed air can make AODD pumps costly in sustained, high-volume service. Pneumatic actuator cycles convert only 20% to 25% of compressor input energy into useful hydraulic work in the operating conditions described in the source draft. This penalty is most material when chemical and wastewater sites run pumps for long periods at high duty factors. Tapflo’s Low Energy Air Package addresses this issue by targeting lower air use at partial loads and low inlet pressure. Buyers evaluating total ownership cost can select an electric alternative when the service does not require a pneumatic architecture. This issue limits the air-operated double diaphragm (AODD) pumps market in continuous-duty applications, even as it encourages suppliers to improve air efficiency.
Substitution by Electric, Centrifugal, and Peristaltic Pumps
Electric diaphragm pumps are becoming a stronger option where hazardous-area classification is absent and continuous operation is important. ARO introduced the EVO 210 electric double diaphragm pump in September 2025 and positioned it around industrial applications seeking lower energy use and noise. DEPA introduced the IonTec electric double diaphragm pump in September 2025 and stated that it can use up to 30% less power than pneumatic equivalents. Centrifugal and peristaltic pumps also remain relevant in services where their flow characteristics or operating costs fit the duty better. The substitution risk is greatest in general manufacturing and non-classified food processing, rather than in explosive atmospheres that require certified equipment. The air-operated double diaphragm (AODD) pumps market must therefore compete on safety, fluid compatibility, dry-running tolerance, and operating flexibility.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Air-Operated Double Diaphragm (AODD) Pumps Market Segment Analysis
By Pump Material:
Non-Metallic Gains Ground in Corrosive-Media ApplicationsMetallic pumps held 57.3% of the air-operated double diaphragm (AODD) pumps market share in 2026. Their position reflects use in oil and gas, chemical processing, mining, and other applications that require strength, abrasion resistance, or higher operating temperatures. Cast iron, aluminum, and 316L stainless steel remain established options for industrial, pressure-intensive, and sanitary duties. Metallic bodies also fit existing maintenance practices at large utilities and process facilities. Their installed base supports replacement demand for diaphragms, valve balls, seats, and complete units. The air-operated double diaphragm (AODD) pumps industry continues to rely on these designs where thermoplastic materials cannot satisfy operating conditions.
Non-metallic pumps are forecast to grow at a 5.9% CAGR through 2032. The air-operated double diaphragm (AODD) pumps market size for non-metallic equipment benefits from semiconductor wet processing, lithium-cell electrolyte handling, and pharmaceutical active ingredient transfer. Polypropylene, polyvinylidene fluoride (PVDF), and ultra-high molecular weight polyethylene (UHMW-PE) wetted parts can reduce corrosion exposure and contamination risk in these services. IDEX lists Trebor high-purity diaphragm pumps in its portfolio, indicating the strategic value of dedicated high-purity offerings. Non-metallic units can carry a 15% to 30% premium, according to the source draft, because their value depends on chemical compatibility and purity rather than basic transfer duty. Suppliers offering certified non-metallic product lines are positioned to address a larger share of corrosive and high-purity applications.



By Pump Design:
Sanitary Configurations Outpace Legacy VariantsStandard pump designs held 41.7% of the market share in 2026. These products serve general industrial, chemical, and wastewater applications where hygiene is secondary to dependable transfer performance. Municipal utilities and downstream chemical facilities often choose standard designs because maintenance teams know the equipment and replacement parts are widely available. The large installed base can support recurring orders as diaphragms and valve components reach their service limits. Standard pumps also remain useful where variable flow, dry-running tolerance, and solid handling are more important than surface finish. This gives conventional configurations a stable role across the air-operated double diaphragm (AODD) pumps market.
Sanitary designs are forecast to grow at a 5.7% CAGR through 2032. The air-operated double diaphragm (AODD) pumps market size for sanitary equipment is supported by biologics manufacturing and stricter cleaning expectations. The Process Industry Practices (PIP) RESP73H standard describes requirements for hygienic AODD pumps used in food and pharmaceutical applications. Heavy-duty configurations remain important for high-solids mining duties, while explosion-proof versions serve classified areas. High-pressure products address uses such as filter presses and spray painting. These specialized designs can command higher value because they solve specific process problems that standard products may not address.
By End-Use Industry:
Pharma and Biotech Leads Growth, Chemicals Anchor RevenueChemicals and petrochemicals held 27.4% of revenue in 2026, making them the largest end-use category. This position reflects both routine replacement requirements and new plant construction across the Middle East, Asia-Pacific, and South America. These facilities use AODD pumps for corrosive transfer, chemical dosing, sampling, and variable-duty services. Hengyi’s planned Brunei refinery expansion illustrates the type of chemical investment that can create future procurement opportunities. Water and wastewater are also a major customer group because it uses pumps for metering, sludge handling, and chemical treatment. Food and beverage, mining, automotive manufacturing, oil and gas add demand through specialized transfer and handling tasks.
Pharmaceuticals and biotechnology are forecast to expand at a 6.8% CAGR through 2032. The air-operated double diaphragm (AODD) pumps industry benefits when biologics facilities specify cleanable equipment and suitable elastomers for fluid contact. FDA’s current good manufacturing practice requirements support the need for systems that can be cleaned and maintained for their intended process use. Manufacturers such as Graco, Tapflo, and Yamada offer products suited to sanitary applications, although final selection depends on process validation and site requirements. Contract development and manufacturing organizations spread production across many locations, increasing the number of separate equipment decisions. This operating model supports a broader base of demand for sanitary fluid-handling products.

Geography Analysis
Asia-Pacific: Dominant Revenue Contributor and Fastest-Growing Region
Asia-Pacific held 51.8% of the air-operated double diaphragm (AODD) pumps market share in 2026 and is forecast to grow at a 6.1% CAGR through 2032. The region combines chemical production, battery manufacturing, semiconductor investment, food processing, and water-treatment expansion. These industries require equipment that can manage corrosive fluids, abrasive slurries, and hygienic transfer services. Iwaki confirmed that its Miharu plant began operations in October 2026 and double pneumatic pump capacity from 600,000 to 1.2 million units annually. Vietnam, Indonesia, and Thailand add opportunity as manufacturers diversify supply chains and expand processing capacity. Teryair Equipment received U.S. patent approval in August 2025 for its Non-Stall Valve, showing that Indian suppliers are also developing differentiated AODD technology. The air-operated double diaphragm (AODD) pumps market size in Asia-Pacific is strengthened by local manufacturing investment and a growing need for high-purity chemical handling.
North America: Premium Specifications Anchored by Infrastructure Spending
North America benefits from water infrastructure projects, premium process specifications, and established domestic suppliers. Hillsborough County’s USD 1.2 billion wastewater project demonstrates the scale of public investment that can support demand for treatment equipment. Compliance factors such as NSF/ANSI 61 for potable water, 3-A sanitary requirements for food processing, and Underwriters Laboratories (UL) or Canadian Standards Association (CSA) listings for safety-sensitive installations can favor suppliers with established documentation. Graco reported USD 2.2 billion in FY2025 net sales across its business, while its Husky line remains part of its industrial fluid handling portfolio. Connected monitoring products that track cycle count, air use, and diaphragm condition align with the region’s focus on maintenance planning and uptime. These requirements create a higher bar for product qualification and reinforce the role of suppliers that offer technical support. The air-operated double diaphragm (AODD) pumps market in North America also faces strong competition from electric alternatives in non-classified, continuous-duty uses.
Regional Dynamics Sustain a Diversified Growth Base
Europe retains demand where ATmosphères EXplosibles (ATEX) compliance, chemical processing, food production, and specialist manufacturing favor certified diaphragm pumps. Verder Group acquired a majority stake in Spanish dosing-pump manufacturer ITC in May 2025, extending its presence in Southern Europe and adjacent dosing applications. Middle East and Africa demand is linked to chemical investment and water infrastructure, where hazardous-area capability and corrosion-resistant materials are relevant. In South America, mining operations use heavy-duty designs for high-solids transfer, while chemical projects create demand for compatible dosing and transfer equipment. Braskem approved investment to expand ethylene and polyethylene production at its Rio de Janeiro facility in 2026. The market share remains diversified outside Asia-Pacific because each region has a different combination of infrastructure, regulation, and process industries. This mix reduces reliance on a single end market, but it also requires suppliers to adjust product certification, distribution, and service models by region.
Competitive Landscape
Market Concentration
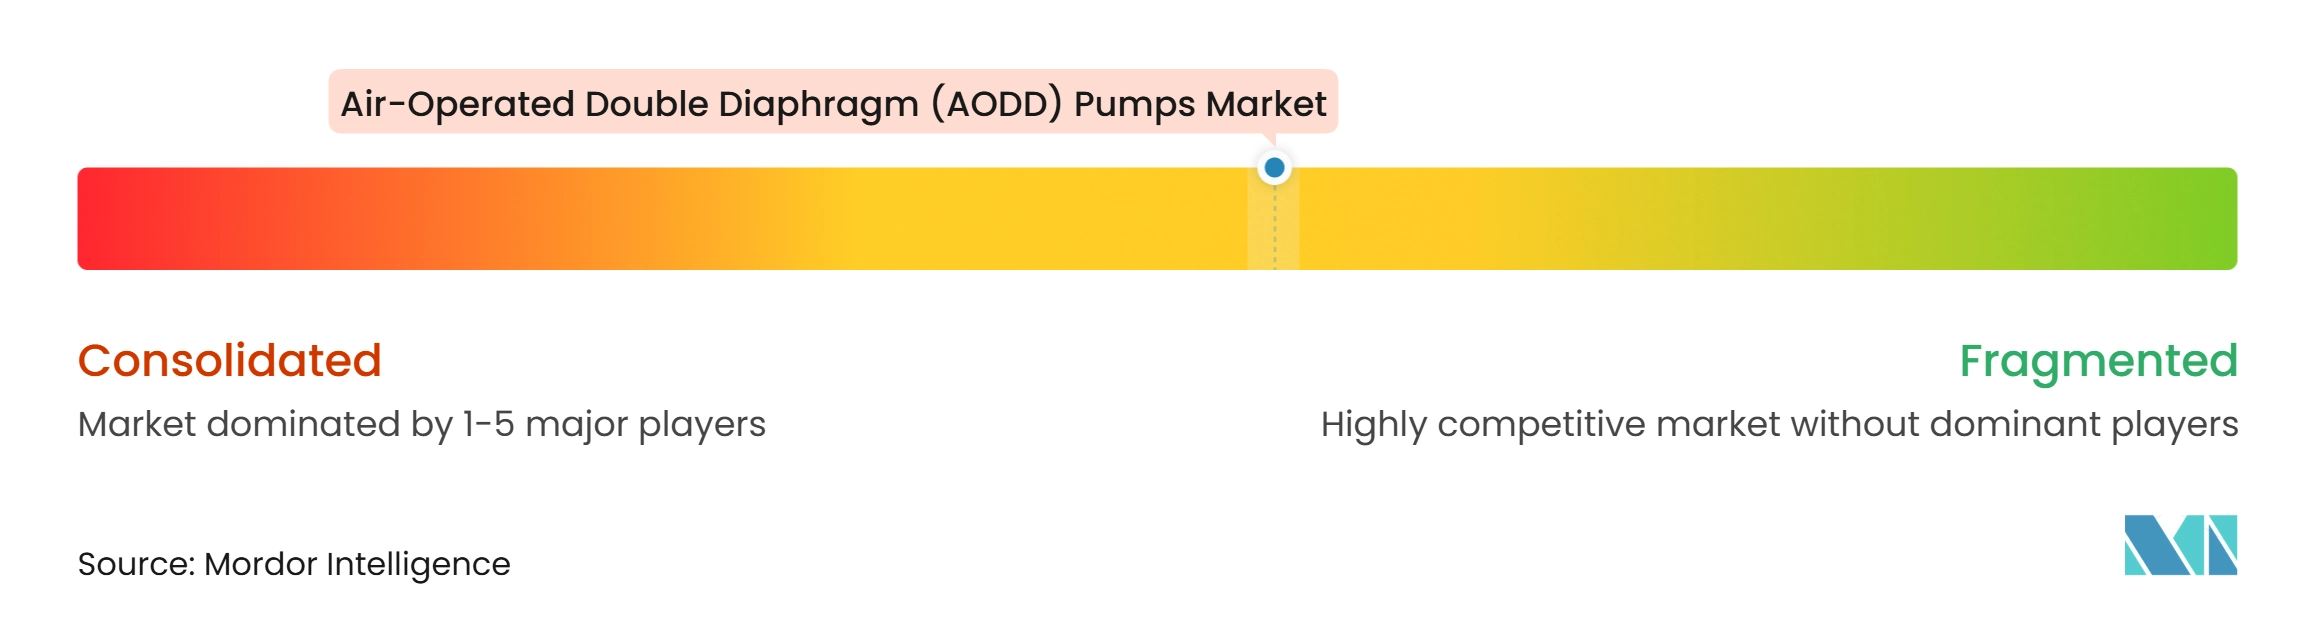
The air-operated double diaphragm (AODD) pumps market is moderately consolidated. IDEX Corporation, Dover Corporation through Wilden, Ingersoll Rand through ARO, Graco through Husky, and Crane Co. through DEPA are prominent groups in high-specification configurations. Their position is reinforced by global distribution, established brands, and certification portfolios. IDEX identifies Warren Rupp, Trebor, and Blagdon among its pumping-related brands and presents Trebor in its high-purity portfolio. European specialists including Tapflo, Lutz Pumpen, Debem, Verder, and Fluimac compete through application knowledge and regional proximity. Asian producers including Yamada, Iwaki, Zhejiang Ligao, Teryair, and DYI SHENG add competition in industrial and cost-sensitive applications.
Product differentiation is moving beyond mechanical performance toward energy use, maintenance, and control. ARO introduced its EVO 210 electric double diaphragm pump in 2025 for industrial customers that seek lower compressed-air consumption and noise. DEPA introduced IonTec in 2025 as an electrical product that it says can use up to 30% less power than comparable pneumatic units. Tapflo expanded its electric operated double diaphragm (EODD) range with TE20, TE25, and TE30 sizes in May 2025. These moves show that suppliers are pursuing electric alternatives while retaining pneumatic products for applications where safety and fluid compatibility remain decisive. The competitive pressure is strongest where buyers compare lifecycle energy costs across multiple pump technologies.
The air-operated double diaphragm (AODD) pumps market also has a clear opportunity for connected systems that combine cycle counting, air-use visibility, diaphragm wear monitoring, and remote operating control. Teryair’s Non-Stall Valve patent illustrates continued product development around low-flow reliability and diaphragm life. Yamada’s ATEX declaration shows that certification remains a central competitive requirement for hazardous locations. Suppliers that connect technical documentation with local service capacity can better compete in high-value chemical, sanitary, and high-purity applications. The large groups have an advantage in distribution and product breadth, but specialists can retain positions through material expertise and tailored engineering.
Air-Operated Double Diaphragm (AODD) Pumps Industry Leaders
-
Dover Corporation
-
Graco Inc.
-
IDEX Corporation
-
Ingersoll Rand Inc.
-
Yamada Corporation
- *Disclaimer: Major Players sorted in no particular order
Air-Operated Double Diaphragm (AODD) Pumps Market Companies Covered in this Report
- Blagdon Pump
- Crane Company
- Debem S.r.l.
- Depa GmbH
- Dover Corporation
- DYI SHENG INDUSTRY CO., LTD.
- Edson International
- Fluimac S.r.l.
- Graco Inc.
- IDEX Corporation
- Ingersoll Rand Inc.
- Iwaki Co., Ltd.
- Ligao Pump Technology Co., Ltd.
- Lutz Pumpen GmbH
- Mody Pumps
- Standard Pump, Inc.
- Tapflo Group
- Teryair Equipment Pvt. Ltd.
- Verder Group
- Yamada Corporation
Recent Industry Developments in Air-Operated Double Diaphragm (AODD) Pumps Market
- October 2026: Iwaki Co., Ltd. confirmed that the new Miharu manufacturing plant began operations, doubling pneumatic pump capacity from 600,000 to 1.2 million units annually to serve growing AODD demand across Asia-Pacific.
- May 2026: Hillsborough County, Florida, broke ground on the USD 1.2 billion One Water Wastewater Project, one of the largest single-county wastewater infrastructure investments in the United States.
- May 2026: Crane's DEPA IonTec electrically operated double diaphragm pump achieved a wider distribution launch through Tomlinson Hall and additional channel partners across Europe, bringing the 30% lower-power unit to general industrial customers.
- March 2026: Hengyi Industries confirmed a USD 5 billion expansion of its Brunei refinery complex, with Phase 2 operations expected from 2029, representing a significant source of chemical-pump procurement in Southeast Asia.
Global Air-Operated Double Diaphragm (AODD) Pumps Market Report Scope
An Air-Operated Double Diaphragm (AODD) pump is a type of positive displacement reciprocating pump that uses compressed air instead of an electric motor to move liquids.
The North America air-operated double diaphragm (AODD) pumps market is segmented into pump material, pump design, end-use industry, and geography. By pump material, the market is segmented into metallic AODD pumps, and non-metallic AODD pumps. By pump design, the market is divided into standard AODD pumps, sanitary AODD pumps, heavy-duty AODD pumps, explosion-proof AODD pumps, and high-pressure AODD pumps. By end-use industry, the market is segmented into chemicals and petrochemicals, water and wastewater treatment, oil and gas, food and beverage, pharmaceuticals and biotechnology, mining and minerals, automotive and manufacturing, and other industries. The report also covers the market size and forecasts for the global air-operated double diaphragm (AODD) pumps market across 26 countries. For each segment, the market sizing and forecasts have been provided on the basis of value (USD).
Segmentation Overview
| Metallic AODD Pumps |
| Non-Metallic AODD Pumps |
| Standard AODD Pumps |
| Sanitary AODD Pumps |
| Heavy-Duty AODD Pumps |
| Explosion-Proof AODD Pumps |
| High-Pressure AODD Pumps |
| Chemicals and Petrochemicals |
| Water and Wastewater Treatment |
| Oil and Gas |
| Food and Beverage |
| Pharmaceuticals and Biotechnology |
| Mining and Minerals |
| Automotive and Manufacturing |
| Other Industries |
| North America | United States |
| Canada | |
| Mexico | |
| Europe | Germany |
| France | |
| Italy | |
| Spain | |
| United Kingdom | |
| Poland | |
| Russia | |
| Rest of Europe | |
| Asia-Pacific | China |
| India | |
| Japan | |
| South Korea | |
| Australia | |
| Indonesia | |
| Vietnam | |
| Thailand | |
| Rest of Asia-Pacific | |
| South America | Brazil |
| Argentina | |
| Chile | |
| Rest of South America | |
| Middle East and Africa | Saudi Arabia |
| United Arab Emirates | |
| Egypt | |
| South Africa | |
| Morocco | |
| Rest of Middle East and Africa |
| By Pump Material | Metallic AODD Pumps | |
| Non-Metallic AODD Pumps | ||
| By Pump Design | Standard AODD Pumps | |
| Sanitary AODD Pumps | ||
| Heavy-Duty AODD Pumps | ||
| Explosion-Proof AODD Pumps | ||
| High-Pressure AODD Pumps | ||
| By End-Use Industry | Chemicals and Petrochemicals | |
| Water and Wastewater Treatment | ||
| Oil and Gas | ||
| Food and Beverage | ||
| Pharmaceuticals and Biotechnology | ||
| Mining and Minerals | ||
| Automotive and Manufacturing | ||
| Other Industries | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| Europe | Germany | |
| France | ||
| Italy | ||
| Spain | ||
| United Kingdom | ||
| Poland | ||
| Russia | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| India | ||
| Japan | ||
| South Korea | ||
| Australia | ||
| Indonesia | ||
| Vietnam | ||
| Thailand | ||
| Rest of Asia-Pacific | ||
| South America | Brazil | |
| Argentina | ||
| Chile | ||
| Rest of South America | ||
| Middle East and Africa | Saudi Arabia | |
| United Arab Emirates | ||
| Egypt | ||
| South Africa | ||
| Morocco | ||
| Rest of Middle East and Africa | ||
Key Questions Answered in the Report
What is the forecast growth rate for air-operated double diaphragm pumps?
The category is forecast to grow at a 5.65% CAGR from 2027 to 2032, reaching USD 3.57 billion by 2032.
Which pump material leads revenue?
Metallic pumps led with 57.3% share in 2026, while non-metallic pumps are forecast to grow at a 5.9% CAGR through 2032.
Which AODD pump design is growing fastest?
Sanitary designs are forecast to grow at a 5.7% CAGR through 2032, supported by pharmaceutical and food processing requirements.
Which end-use sector is expanding fastest?
Pharmaceuticals and biotechnology are projected to expand at a 6.8% CAGR through 2032.
Which region leads AODD pump demand?
Asia-Pacific held 51.8% share in 2026 and is forecast to grow at a 6.1% CAGR through 2032.
Why are electric diaphragm pumps relevant to buyers?
Electric models address air-use and noise concerns in non-classified, continuous-duty services, while pneumatic models retain advantages in hazardous and difficult fluid-transfer settings.