
Vietnam Pet Veterinary Diets Market Size and Share
Market Overview
| Study Period | 2021 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
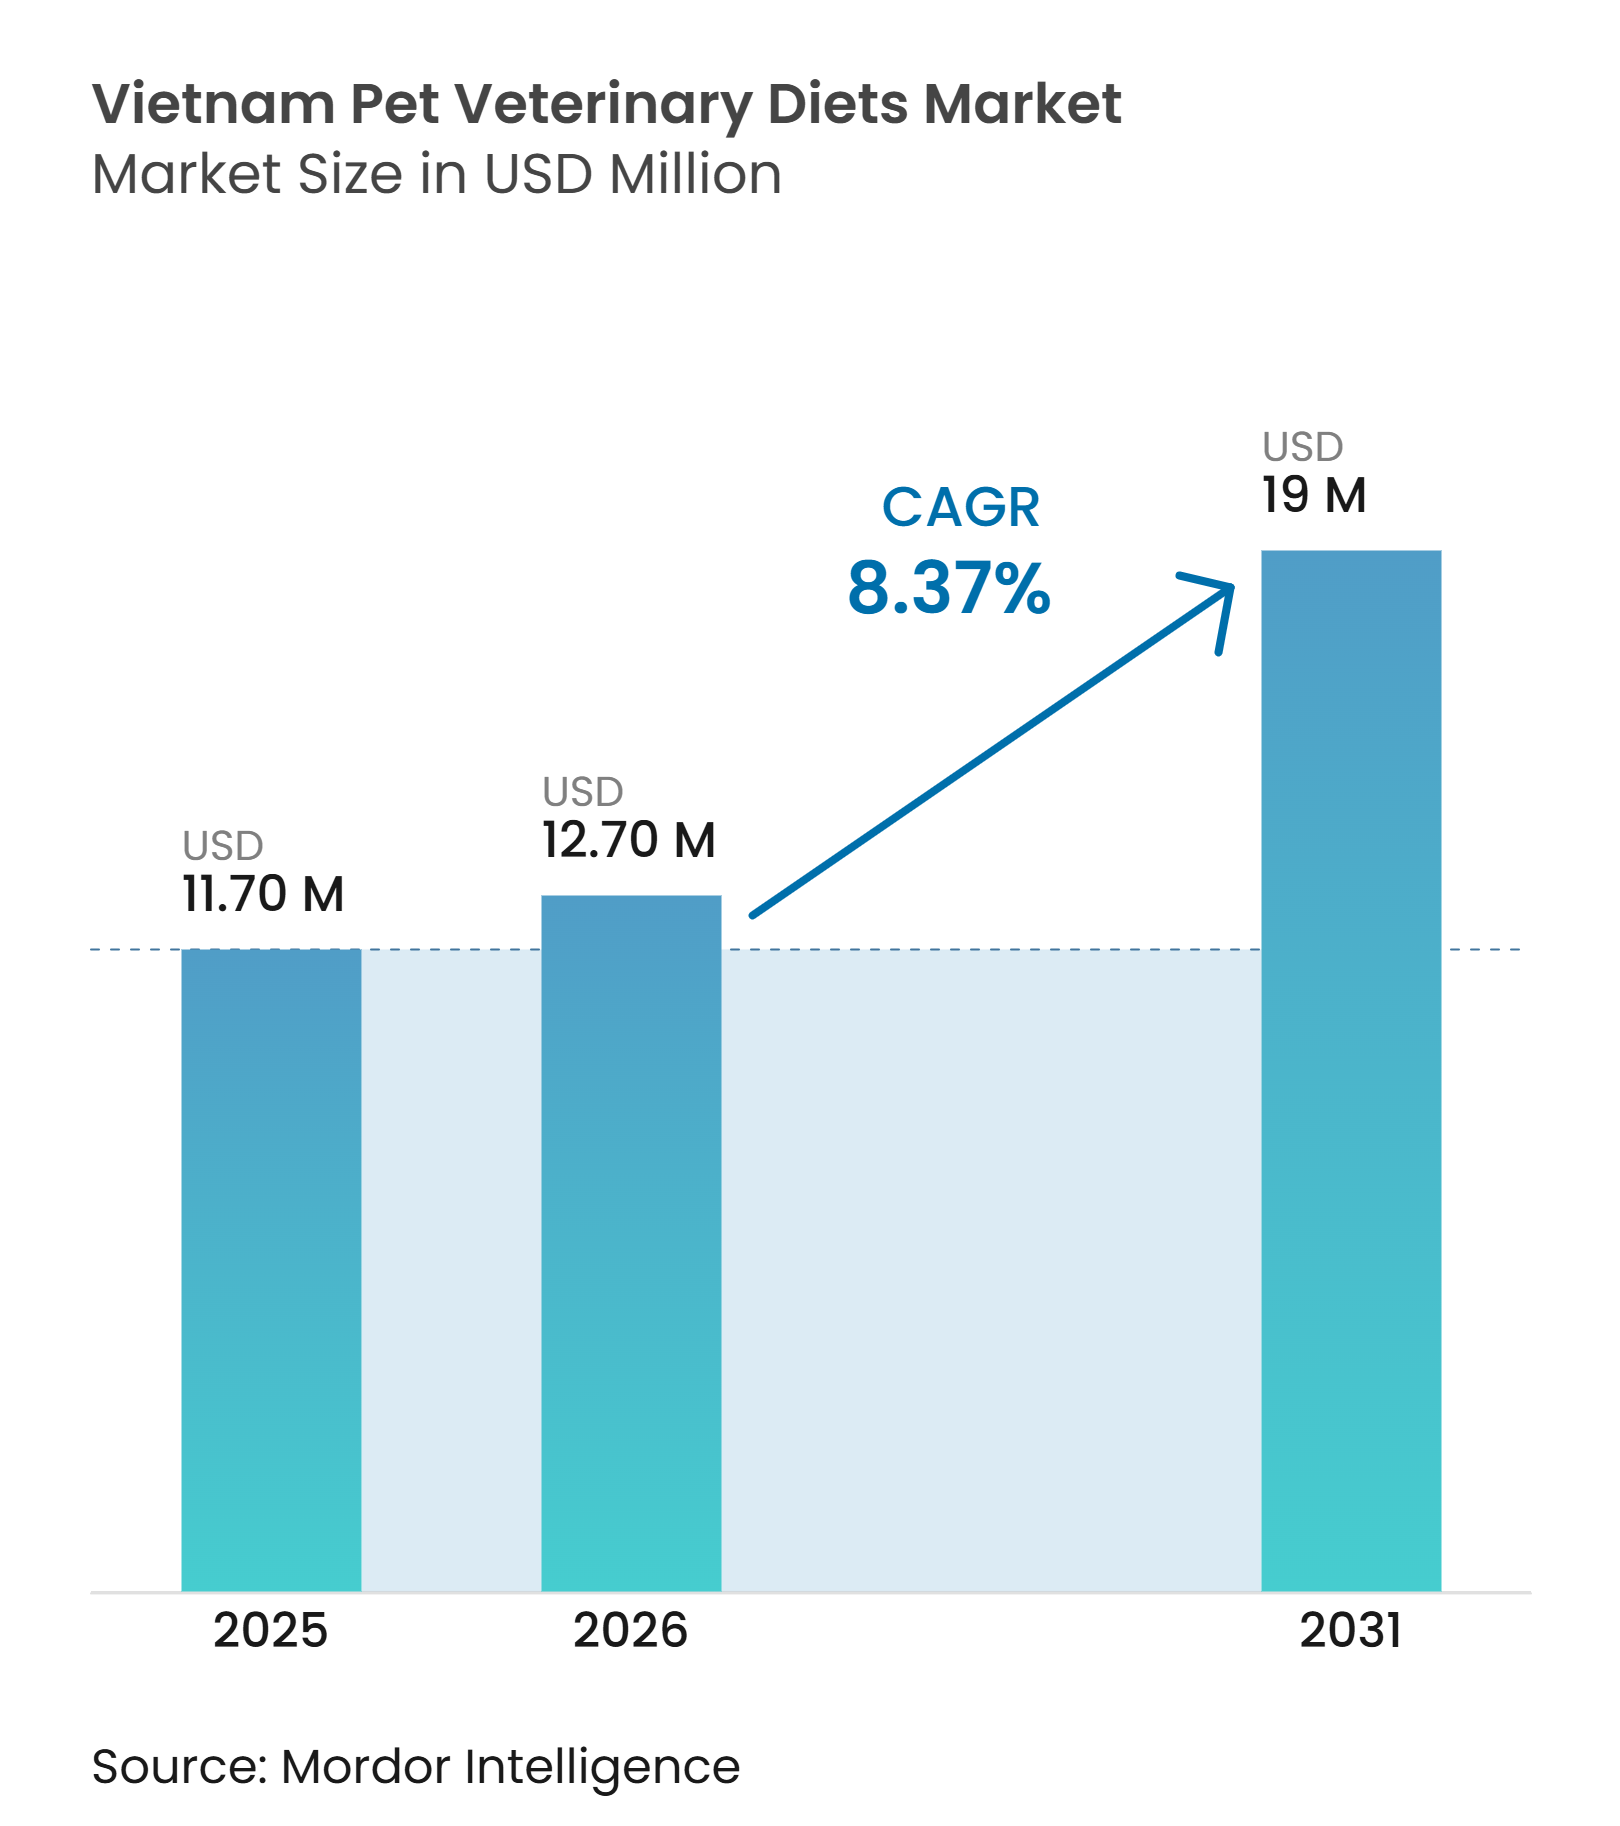
| Base Year Market Size (2025) | USD 11.70 Million |
| Market Size (2026) | USD 12.70 Million |
| Market Size (2031) | USD 19 Million |
| Growth Rate (2026 - 2031) | 8.37 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Vietnam Pet Veterinary Diets Market Analysis by Mordor Intelligence
The Vietnam pet veterinary diets market size was valued at USD 11.7 million in 2025 and is estimated to grow from USD 12.7 million in 2026 to reach USD 19 million by 2031, at a CAGR of 8.37% during the forecast period 2026-2031. Vietnam reported in 2025 that the domestic pet industry has the potential to become a billion-dollar category [1], which supports the move of the Vietnam pet veterinary diets market from a niche clinical category toward a broader premium pet health segment. Urban pet ownership patterns are becoming more health-oriented, and that is increasing demand for condition-specific diets that fit into veterinary treatment plans. Vietnam's pet sector is moving beyond standalone product purchases toward integrated care models that combine retail with recurring services such as grooming, hygiene treatment, vaccination, and boarding, according to the Vietnam News Agency.
Key Report Takeaways
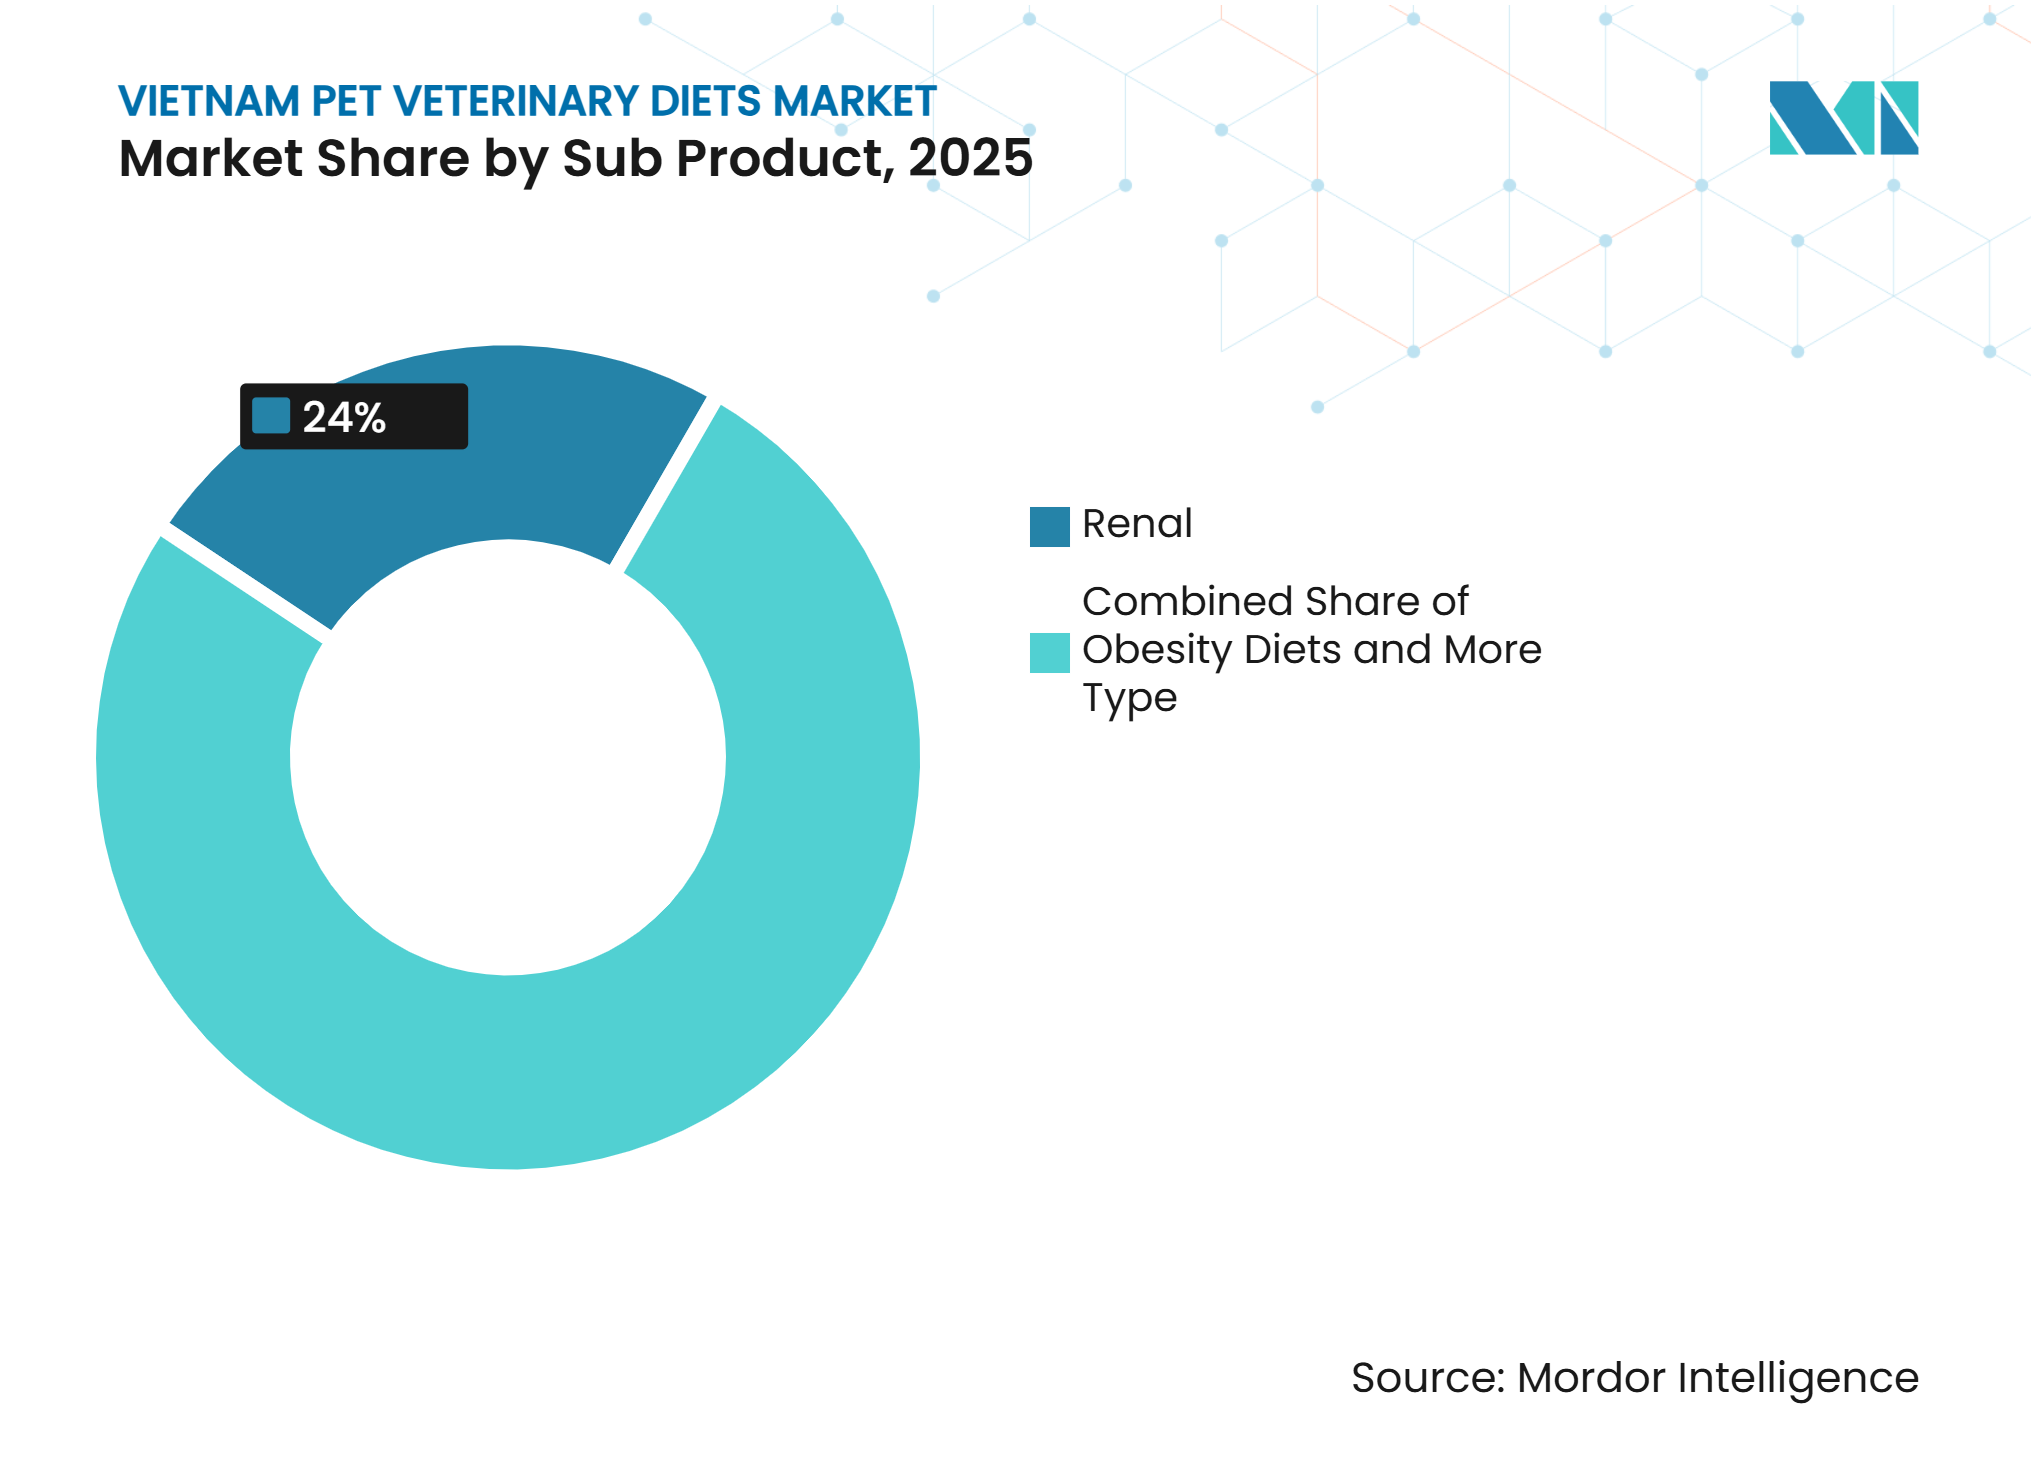
- By sub-product, renal diets held 24.0% of the Vietnam pet veterinary diets market share in 2025, while obesity diets are projected to record the fastest CAGR of 10.8% during 2026-2031.
- By pet type, dogs accounted for 61.1% of the Vietnam pet veterinary diets market share in 2025, while cats are projected to expand at the fastest CAGR of 8.3% during 2026-2031.
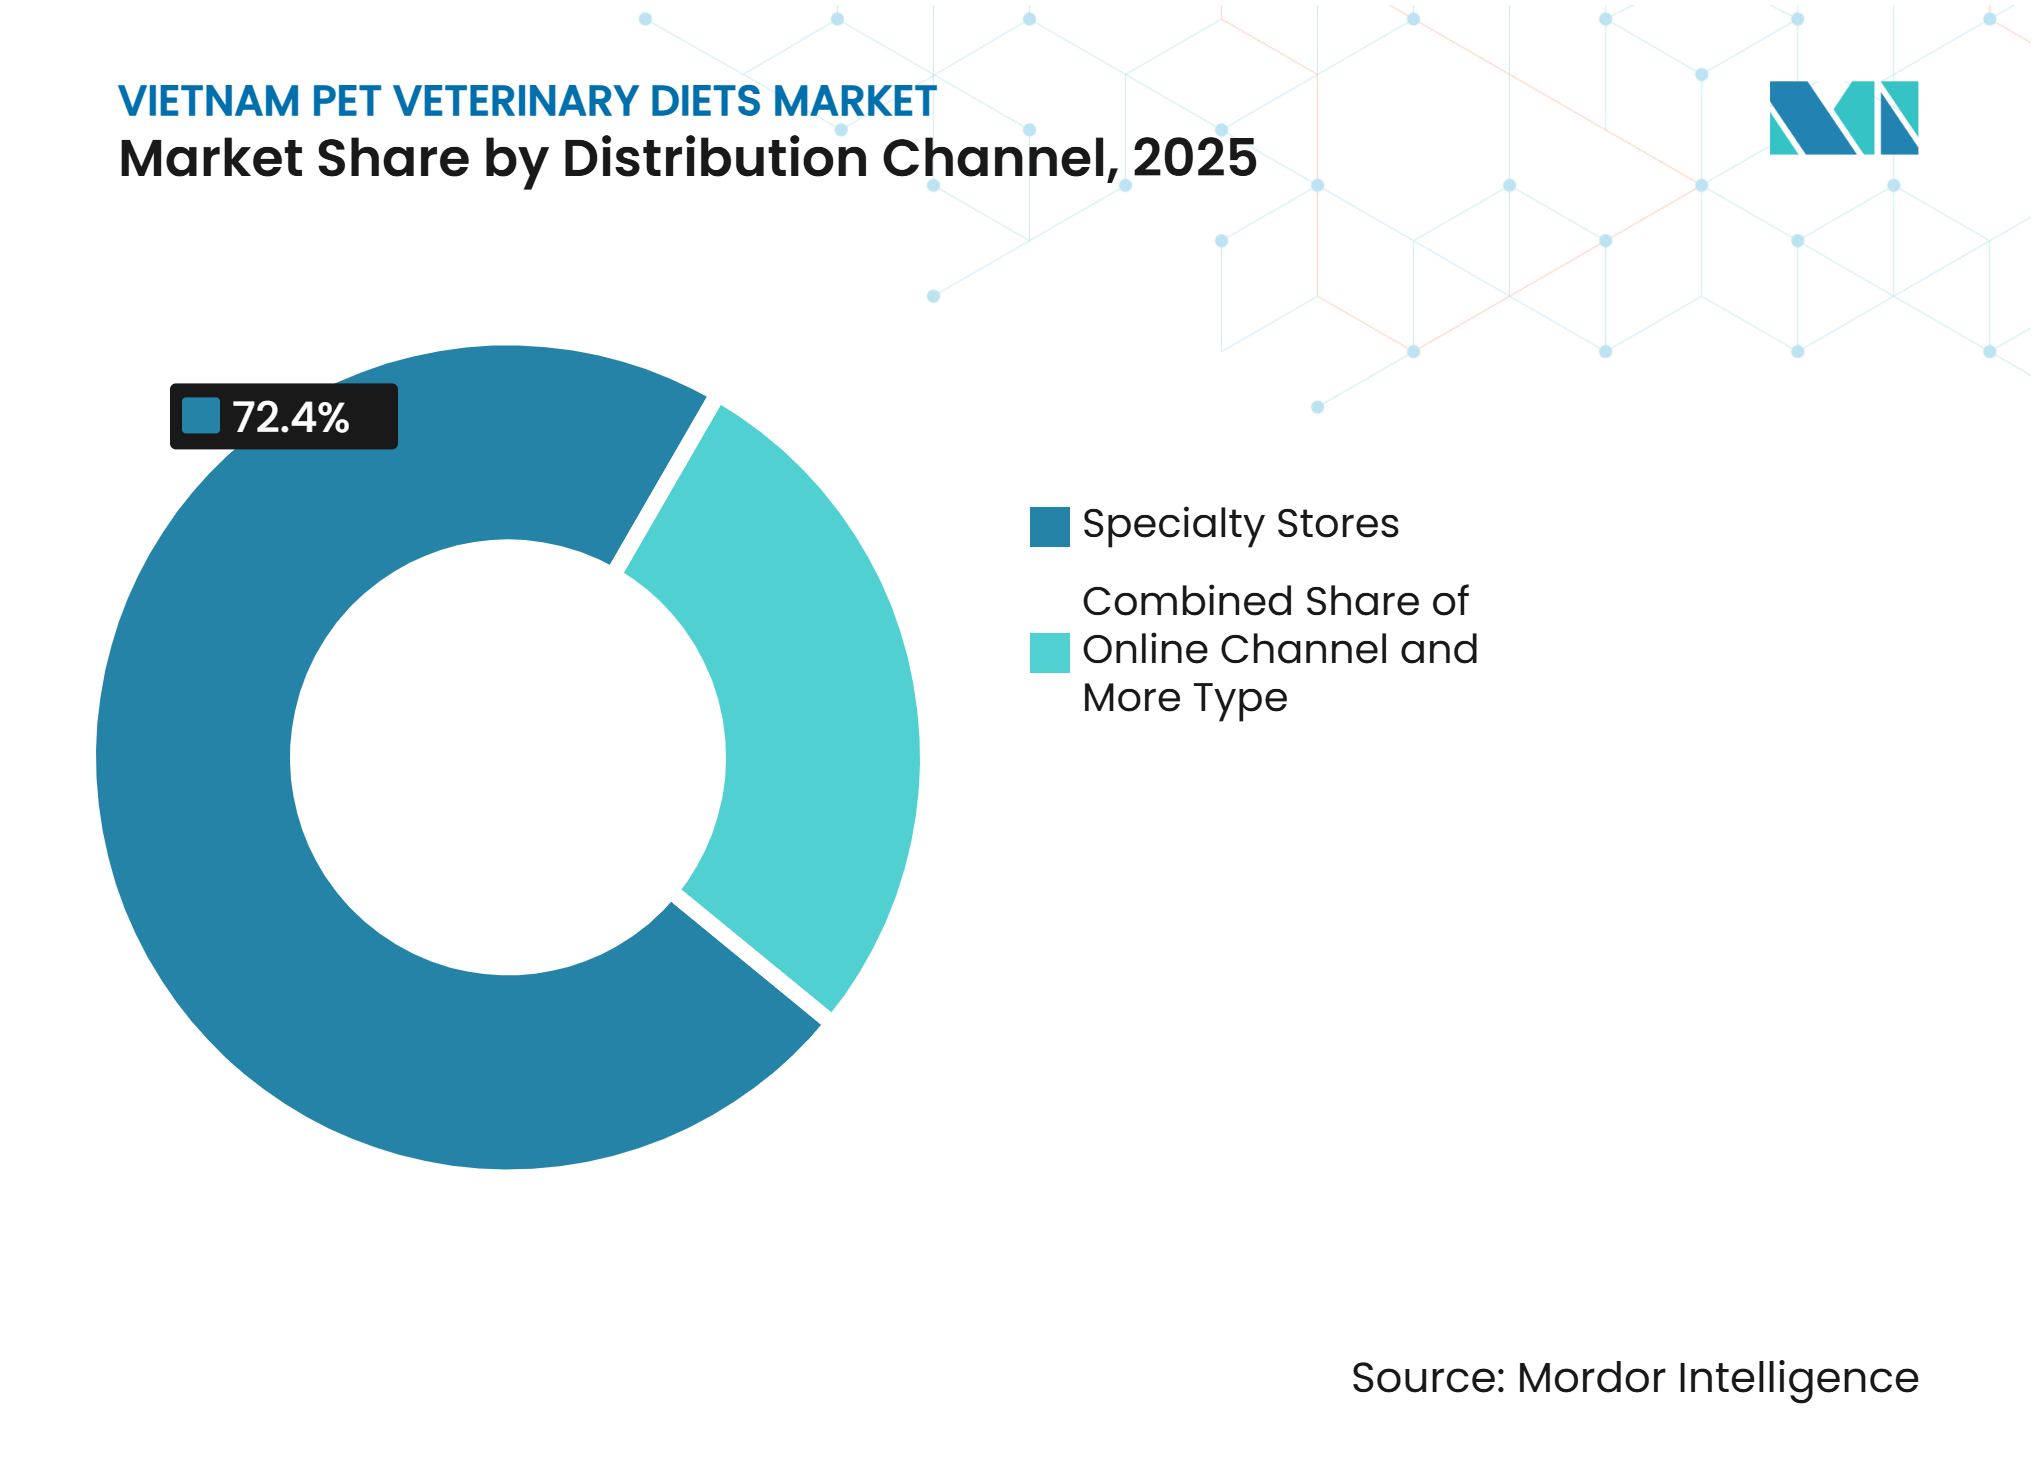
- By distribution channel, specialty stores accounted for 72.4% share of the Vietnam pet veterinary diets market size in 2025, while the online channel is projected to grow at the fastest CAGR of 9.3% during 2026-2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Vietnam Pet Veterinary Diets Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Diagnosis and Treatment of Chronic Pet Conditions | + 2.30% | National, with concentration in Ho Chi Minh City and Hanoi | Medium term (2-4 years) |
| Expanding Pet Humanization and Premium Nutrition Spending | + 1.80% | National, strongest in Ho Chi Minh City and Hanoi urban districts | Long term (≥ 4 years) |
| Growing Veterinary Clinic and Hospital Access in Vietnam | + 1.40% | National, with rapid expansion in Tier-1 and Tier-2 cities | Medium term (2-4 years) |
| Higher Awareness of Therapeutic Diet Benefits Among Urban Pet Owners | + 1.10% | Urban centers, especially Ho Chi Minh City, Hanoi, and Da Nang | Medium term (2-4 years) |
| Better Availability Through E-Commerce and Specialist Pet Retail | + 0.80% | National, with strongest same-day delivery relevance in major cities | Short term (≤ 2 years) |
| Rising Adoption of Breed-Specific and Condition-Specific Diets | + 0.60% | Urban centers, particularly higher-income households | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Rising Diagnosis and Treatment of Chronic Pet Conditions
Vietnamese clinics are handling more chronic pet conditions, and that is strengthening the treatment base for the Vietnam pet veterinary diets market. Vietnamese clinics are handling more chronic pet conditions, strengthening the treatment base for the Vietnam pet veterinary diets market. A 2024 research paper published in Veterinary Integrative Sciences reported that 37.1% of dogs and cats examined in Ho Chi Minh City presented with urolithiasis.[2], indicating significant clinical demand for urinary support nutrition. The International Renal Interest Society stated in 2025 that renal diets remain a first-line nutritional measure for chronic kidney disease management[3], which supports the durable use of kidney care formulations once diagnosis occurs. This is important because therapeutic feeding in kidney and urinary care is not a one-time purchase and typically spans longer treatment cycles. The result is that chronic disease management supports repeat demand in a way that ordinary premium pet food does not.
Expanding Pet Humanization and Premium Nutrition Spending
Pet care spending in Vietnam is increasingly tied to health outcomes and not only to basic feeding. Vietnam News Service reported in 2025 that pet owners in Ho Chi Minh City were willing to spend more than VND 30 million on a single treatment episode, equal to USD 1,200, which shows the willingness of urban households to support clinically guided care. A Vietnamese news reported in 2026 stated that the broader Vietnamese pet food market is projected to reach USD 167.98 million, indicating that premium and health-oriented nutrition is gaining a wider base. Vietnam Plus, a local news publisher, also reported in 2024 that the country’s fertility rate fell to 1.91, a trend that supports a shift in discretionary spending among younger urban households toward pets and pet wellness. This matters to the Vietnam pet veterinary diets market because premium therapeutic feeding tends to scale first where pet attachment, health spending, and urban lifestyle patterns are already aligned.
Growing Veterinary Clinic and Hospital Access in Vietnam
The Vietnam pet veterinary diets market depends heavily on access to formal diagnosis and follow-up care. Nong Nghiep Moi Truong reported in 2025 that nearly 3,000 veterinary clinics and hospitals were operating across Vietnam, even though the sector still faced a shortage of licensed staff. This clinic base matters because most therapeutic feeding decisions are tied to veterinary recommendations rather than the casual owner trial. As clinical capacity expands, more pets with kidney, urinary, digestive, and weight-related conditions can be identified earlier and managed with diet over a longer period. That makes veterinary infrastructure one of the clearest service-side supports for sustained category growth.
Better Availability Through E-Commerce and Specialist Pet Retail
Access through specialist retail and digital platforms is improving the continuity of treatment-led feeding. VnEconomy reported in 2026 that pet product e-commerce revenue reached VND 687.3 billion (USD 26.12 million) in a single week, indicating that online buying has become an important part of Vietnam’s pet economy. Ministry of Culture, Sports and Tourism, Vietnam, also reported in 2026, citing the Deputy Head of the Department of Animal Husbandry and Veterinary Medicine, that pet food import management has shifted toward declaration, post-inspection, and traceability. This is relevant because therapeutic diets need a reliable refill path after the first recommendation, and online availability lowers that friction in urban markets. For the Vietnam pet veterinary diets market, digital access helps preserve treatment continuity while specialty retail continues to anchor trust.
Restraints Impact Analysis of Vietnam Pet Veterinary Diets Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Limited Awareness of Veterinary Diets Outside Major Cities | -0.90% | Rural and semi-urban areas, including the Mekong Delta, Central Highlands, and Northern Uplands | Long term (≥ 4 years) |
| Higher Price Sensitivity Versus Standard Pet Food | -0.80% | National, with strongest drag in Tier-2 and Tier-3 cities | Medium term (2-4 years) |
| Dependence on Veterinarian Recommendation for Repeat Purchases | -0.40% | National, most acute in areas with low clinic density | Medium term (2-4 years) |
| Informal and Grey-Market Product Availability | -0.50% | National, concentrated in informal offline and consumer-to-consumer channels | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Limited Awareness of Veterinary Diets Outside Major Cities
The market remains heavily concentrated in major urban centers, which limits addressable demand outside them. Nong Nghiep Moi Truong reported in 2025 that Vietnam’s veterinary sector still faced a shortage of licensed personnel, which means diagnostic capability remains concentrated in stronger clinic markets. In many secondary or rural areas, pets are more likely to pass through informal care channels that do not systematically identify diet-linked chronic conditions. That reduces both owner awareness and clinician-led conversion into prescription feeding. As a result, the Vietnam pet veterinary diets market can expand nationally only if diagnostic and education capacity spreads beyond the current metro-led base.
Higher Price Sensitivity Versus Standard Pet Food
Affordability remains a meaningful restraint on conversion into prescription nutrition. Ministry of Culture, Sports and Tourism, Vietnam reported in 2025 that only 5% of Vietnam’s estimated 12 million dogs and cats were fed food formulated specifically for pets, indicating that even standard pet food penetration remains low. Ministry of Culture, Sports and Tourism, Vietnam, also reported in 2025 that income concerns and value-focused household behavior were still shaping pet care spending decisions. This means therapeutic nutrition must compete not only with other premium food options, but also with basic feeding habits that have not yet fully shifted into the commercial pet food system. The Vietnam pet veterinary diets market, therefore, expands most easily where owners already accept higher recurring health-related spend.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Vietnam Pet Veterinary Diets Market Segment Analysis
By Sub Product:
Renal Dominance Masks Rapid Metabolic Diet GrowthRenal diets were the largest sub-product, with 24.0% of the Vietnam pet veterinary diets market share in 2025, reflecting the long treatment duration usually associated with kidney disease management. The International Renal Interest Society stated in 2025 that renal nutrition remains central to chronic kidney disease care, supporting stable repeat demand in this subcategory. Urinary tract disease, diabetes, and digestive sensitivity form the next important therapeutic demand layer because they are tied to chronic management rather than short-term feeding changes. Loan and Dao reported in Veterinary Integrative Sciences in 2024 that urolithiasis prevalence reached 37.1% among examined dogs and cats in Ho Chi Minh City, supporting a stronger demand for urinary diets in urban clinical settings. Oral care and derma diets remain smaller because they require a more developed mix of owner awareness, diagnosis, and sustained nutritional compliance.
Obesity diets are the fastest-growing sub-product and are projected to expand at 10.8% CAGR during 2026-2031. Obesity is a major risk factor for diabetes mellitus in cats, and that relationship supports broader long-term demand for weight-management nutrition in the Vietnam pet veterinary diets market. This gives obesity diets a role that goes beyond a single niche because weight control can affect diabetes and joint-related feeding needs over time. The other veterinary diets category includes early-stage cardiac and hepatic formulations, and these remain smaller because their clinical use depends on deeper diagnostic capability. As urban clinic standards improve, these smaller therapeutic niches can widen without taking away the leadership position of renal diets in the near term.



By Pets:
Dog-Led Market With Accelerating Feline Prescription DemandDogs were the largest pet type, with 61.1% of the Vietnam pet veterinary diets market share in 2025, which is consistent with the long-standing role of dogs in Vietnamese households. This base reflects wider dog ownership across urban and non-urban settings, even though therapeutic diet conversion remains stronger in cities. Cats are the fastest growing pet type and are projected to expand at 8.3% CAGR during 2026-2031, which points to a gradual shift in demand mix inside the Vietnam pet veterinary diets market. The faster cat trajectory aligns with apartment living, indoor ownership patterns, and stronger adoption of premium care among urban households. The result is a market where dogs continue to anchor current demand while cats contribute a faster growth profile.
Vietnam News Service reported in 2025 that urban pet care spending was moving toward more advanced treatment practices, which supports higher compliance among owners who treat companion animals as core household members. That trend is especially relevant for cat owners in dense urban settings, where feeding behavior is more controlled and veterinarian recommendations can be followed more consistently. The other pets segment remains small, but it shows that the country’s companion animal base is widening beyond dogs and cats. VnEconomy reported in 2026, citing 2Vet leadership, that reptile ownership and organized husbandry activity were also visible in Lam Dong province. For the Vietnam pet veterinary diets market, this segment does not yet drive scale, but it does point to a broader long-term base for specialized nutrition.
By Distribution Channel:
Specialty Stores Lead, Digital Channels Reshape Repurchase BehaviorSpecialty stores were the largest distribution channel and held 72.4% share of the Vietnam pet veterinary diets market size in 2025. This reflects the prescription-led nature of therapeutic nutrition, where owners still rely on veterinarian advice and specialist retail support before purchase. The channel structure remains favorable to specialty stores because therapeutic diets are linked to disease-specific use rather than routine impulse buying. Vietnam’s 2024 regulatory compliance framework for imported animal feed also supports a more formal path for clinically positioned products. That keeps clinic-linked retail and specialist stores at the center of the current purchase journey.
The online channel is the fastest-growing distribution format and is projected to expand at 9.3% CAGR during 2026-2031. VnEconomy reported in 2026 that pet products were already generating substantial e-commerce revenue, confirming that digital buying behavior has moved into the mainstream of Vietnam’s pet sector. Petfair Vietnam also reported in 2026 that the country’s pet supply chain and retail ecosystem were becoming more organized, which supports the rise of structured refill models and broader SKU access. For the Vietnam pet veterinary diets market, online growth matters most after the initial prescription because it helps maintain refill continuity. Supermarkets and hypermarkets retain a presence, but they are less central because therapeutic nutrition still depends on trust, clinical guidance, and more specialized merchandising.

Geography Analysis
Ho Chi Minh City is the largest demand center within the Vietnam pet veterinary diets market and remains the country’s primary hub for premium pet nutrition and veterinary services. Petfair Vietnam identified the city in 2026 as the leading market for category investment, specialist retail, and advanced pet care activity. This matters because therapeutic diet adoption depends on a dense mix of clinics, specialist channels, and households willing to pay for treatment-linked feeding. Ho Chi Minh City also serves as an early entry point for imported therapeutic products and multinational brand distribution activity. That gives the city a clear first-mover role in shaping current demand patterns across the Vietnam pet veterinary diets market.
Hanoi is the second major demand cluster and is building category depth from a smaller base. Petfair Vietnam reported in December 2024 that its Hanoi roadshow positioned the Northern market as an opportunity zone for premium pet nutrition and veterinary services, which shows active ecosystem development in the region. Ministry of Culture, Sports and Tourism, Vietnam, reported in 2026 that Hanoi is regarded as a high-potential market for premium pet food and multi-pet household products. That combination suggests strengthening adoption conditions for prescription nutrition as specialist care infrastructure becomes more visible. In the Vietnam pet veterinary diets market, Hanoi is therefore the clearest secondary growth center after Ho Chi Minh City.
Secondary cities such as Da Nang, Can Tho, and urban centers in the Mekong Delta remain developmental markets rather than the core national revenue base. These markets can add future demand because urbanization and rising pet ownership norms are extending beyond the two largest metros. Nong Nghiep Moi Truong reported in 2025 that the shortage of licensed veterinary professionals remained a structural bottleneck, and that constraint is more visible outside the strongest city markets. Limited clinic depth means fewer pets move into structured diagnosis and prescription feeding pathways in these cities. The Vietnam pet veterinary diets market can still widen geographically over time, but near-term national growth will continue to be led by urban markets with stronger veterinary infrastructure.
Competitive Landscape
Market Concentration
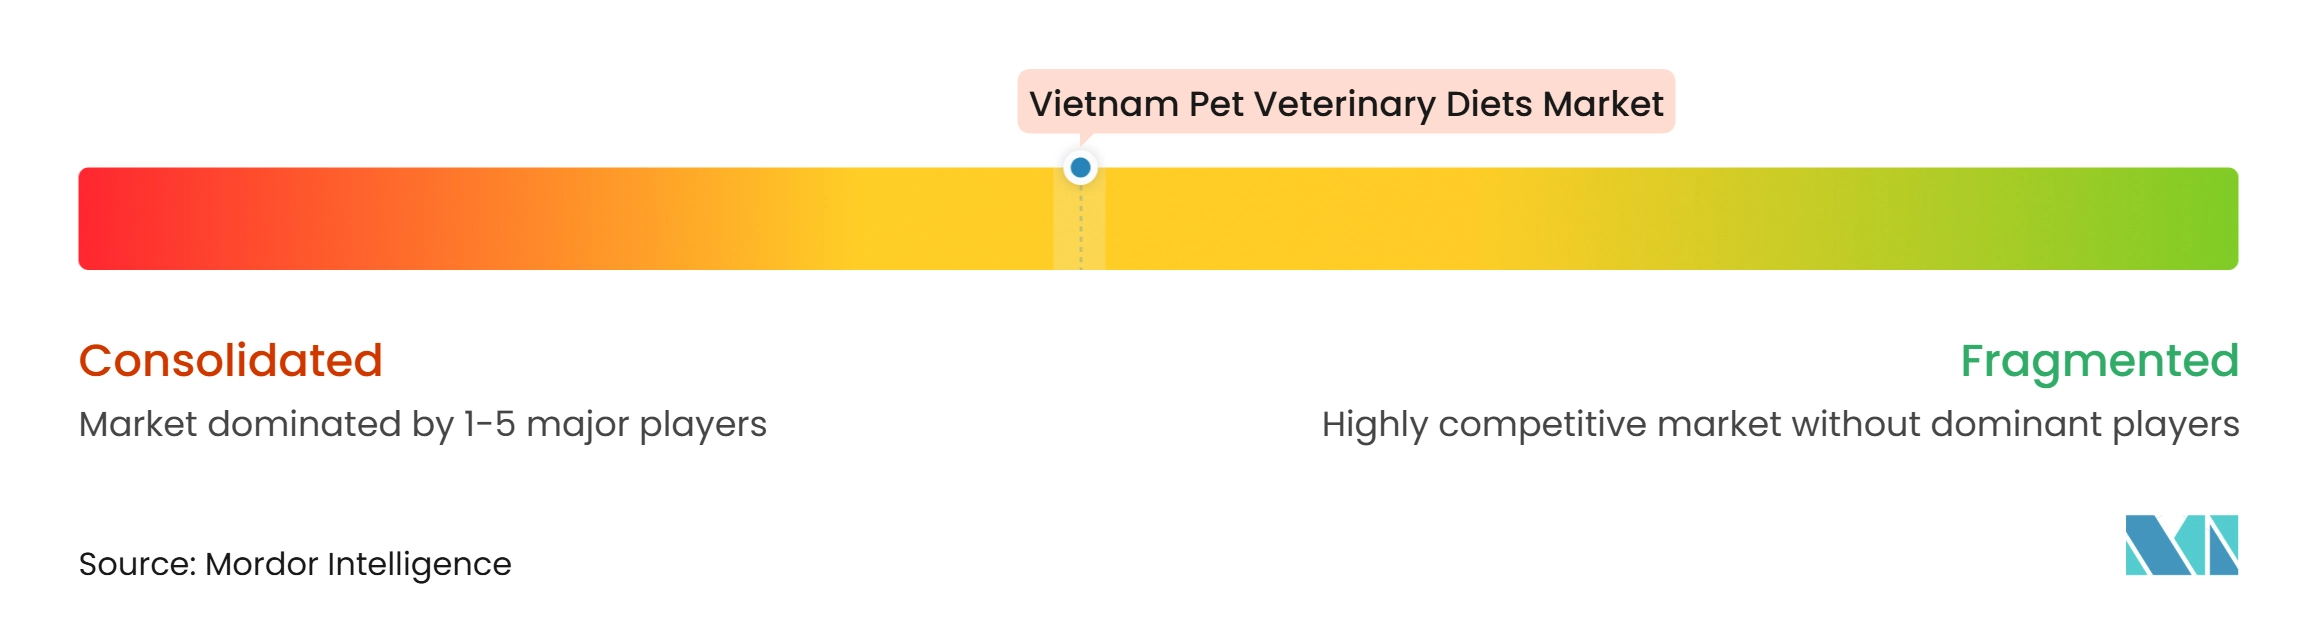
The Vietnam pet veterinary diets market remains moderately concentrated, with global brands holding the strongest clinical visibility in renal, urinary, and gastrointestinal nutrition. Hill’s Pet Nutrition stated on its corporate research page in 2026 that it employs more than 220 veterinarians, PhD nutritionists, and food scientists, which supports its strong prescriber credibility in therapeutic diets. This research scale matters because prescription feeding is shaped by clinical confidence and not only by brand recognition at the shelf. Royal Canin, Hill’s, Nestlé Purina, Virbac, and Farmina all appear in the supplied source set as active investors in therapeutic product development or channel expansion during 2024 to 2026. That shows that the Vietnam pet veterinary diets market is being contested by companies with large international product systems and strong veterinary positioning.
Virbac launched Vikaly in Europe in September 2025, and the product combined benazepril with a renal diet in a single medicated feed for cats. Hill’s launched Prescription Diet k/d + Derm Complete for dogs and k/d + z/d Hydrolyzed for cats in June 2026, showing its push into multi-condition therapeutic feeding. Royal Canin previewed GLYCOADVANCED and Veterinary Fresh Nutrition at VMX 2026, which shows ongoing investment in targeted therapeutic line. These moves matter to the Vietnam pet veterinary diets market because new therapeutic launches typically set the next layer of veterinarian discussion and product availability. They also reinforce the advantage of players that already operate at scale across prescription nutrition.
Nestlé Purina made its full Pro Plan Veterinary Diets portfolio available through the Amazon store in the United States in 2024, which shows a multi-channel distribution model that is relevant to markets with rising digital pet food purchases. Farmina signed a national distribution agreement with MWI Animal Health in July 2025, which supports broader veterinary channel strengthening for its clinical diet range. Charoen Pokphand Foods reported THB 122 billion in Vietnam revenue for FY2024, equal to USD 3.62 billion, which confirms the group’s broad operating presence in the country even though the supplied source set does not position it as a leading prescription diet specialist. MARD’s 2024 import compliance framework continues to favor formal registered suppliers over informal channels, which supports brand holders with stronger regulatory readiness. This keeps the Vietnam pet veterinary diets market tilted toward established players that can combine clinical positioning, regulatory compliance, and broader channel support.
Vietnam Pet Veterinary Diets Industry Leaders
-
Mars, Incorporated
-
Nestlé S.A.
-
Colgate-Palmolive Company
-
Virbac S.A.
-
Farmina Pet Foods S.r.l.
- *Disclaimer: Major Players sorted in no particular order
Vietnam Pet Veterinary Diets Market Companies Covered in this Report
- Mars, Incorporated
- Nestlé S.A.
- Colgate-Palmolive Company (Hills Pet Nutrition)
- Virbac S.A.
- Farmina Pet Foods Holding B.V.
- Affinity Petcare, S.A.
- Dechra Pharmaceuticals Limited
- Monge and C. S.p.A.
- United Petfood Group N.V.
- VAFO Group a.s.
- Pet Like Co., Ltd.
- Perfect Companion Group Co., Ltd.
- DoggyMan H.A. Co., Ltd.
- Archer-Daniels-Midland Company
- Charoen Pokphand Group Company Limited
Recent Industry Developments in Vietnam Pet Veterinary Diets Market
- June 2026: Hill's Pet Nutrition launched Prescription Diet k/d + Derm Complete for dogs and k/d + z/d Hydrolyzed for cats, the brand's first prescription diets formulated to support concurrent chronic kidney disease alongside dermatological or gastrointestinal sensitivities.
- January 2026: Royal Canin previewed GLYCOADVANCED at VMX 2026 in Orlando, a new feline therapeutic diet for overweight diabetic cats, and also announced Veterinary Fresh Nutrition for launch later in 2026.
- September 2025: Virbac S.A. launched Vikaly in Europe, the world’s first medicated feed for cats that integrates the pharmaceutical active ingredient benazepril into a clinical renal diet kibble.
Vietnam Pet Veterinary Diets Market Report Scope
Pet veterinary diets are specialized nutritional products formulated to manage specific animal health conditions. The Vietnam Pet Veterinary Diets Market Report is segmented by sub product (diabetes, digestive sensitivity, oral care diets, renal, urinary tract disease, obesity diets, derma diets, and other veterinary diets), by pets (cats, dogs, and other pets), and by distribution channel (convenience stores, online channel, specialty stores, supermarkets/hypermarkets, and other channels). Forecasts are provided in terms of value (USD) and volume (metric tons).
Segmentation Overview
| Diabetes |
| Digestive Sensitivity |
| Oral Care Diets |
| Renal |
| Urinary Tract Disease |
| Obesity Diets |
| Derma Diets |
| Other Veterinary Diets |
| Cats |
| Dogs |
| Other Pets |
| Convenience Stores |
| Online Channel |
| Specialty Stores |
| Supermarkets/Hypermarkets |
| Other Channels |
| By Sub Product | Diabetes |
| Digestive Sensitivity | |
| Oral Care Diets | |
| Renal | |
| Urinary Tract Disease | |
| Obesity Diets | |
| Derma Diets | |
| Other Veterinary Diets | |
| By Pets | Cats |
| Dogs | |
| Other Pets | |
| By Distribution Channel | Convenience Stores |
| Online Channel | |
| Specialty Stores | |
| Supermarkets/Hypermarkets | |
| Other Channels |
Key Questions Answered in the Report
What is driving demand for veterinary diets in Vietnam?
The strongest demand drivers are rising diagnosis of chronic pet conditions, higher urban spending on pet health, and better access through specialist retail and online refill channels.
Which sub-product leads the Vietnam pet veterinary diets space?
Renal diets were the largest sub-product with 24.0% share in 2025, supported by the long treatment cycle of kidney disease management.
Which sub-product is growing the fastest in Vietnam?
Obesity diets are projected to record the fastest CAGR of 10.8% during 2026-2031, supported by growing attention to weight-related metabolic conditions.
Why do specialty stores still lead distribution?
Specialty stores led with 72.4% share in 2025 because prescription diets still depend on veterinary trust, clinician recommendation, and more specialized product guidance.