
Sterile Barrier Packaging Inspection Systems Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 348.89 Million |
| Market Size (2031) | USD 473.96 Million |
| Growth Rate (2026 - 2031) | 6.32 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Sterile Barrier Packaging Inspection Systems Market Analysis by Mordor Intelligence
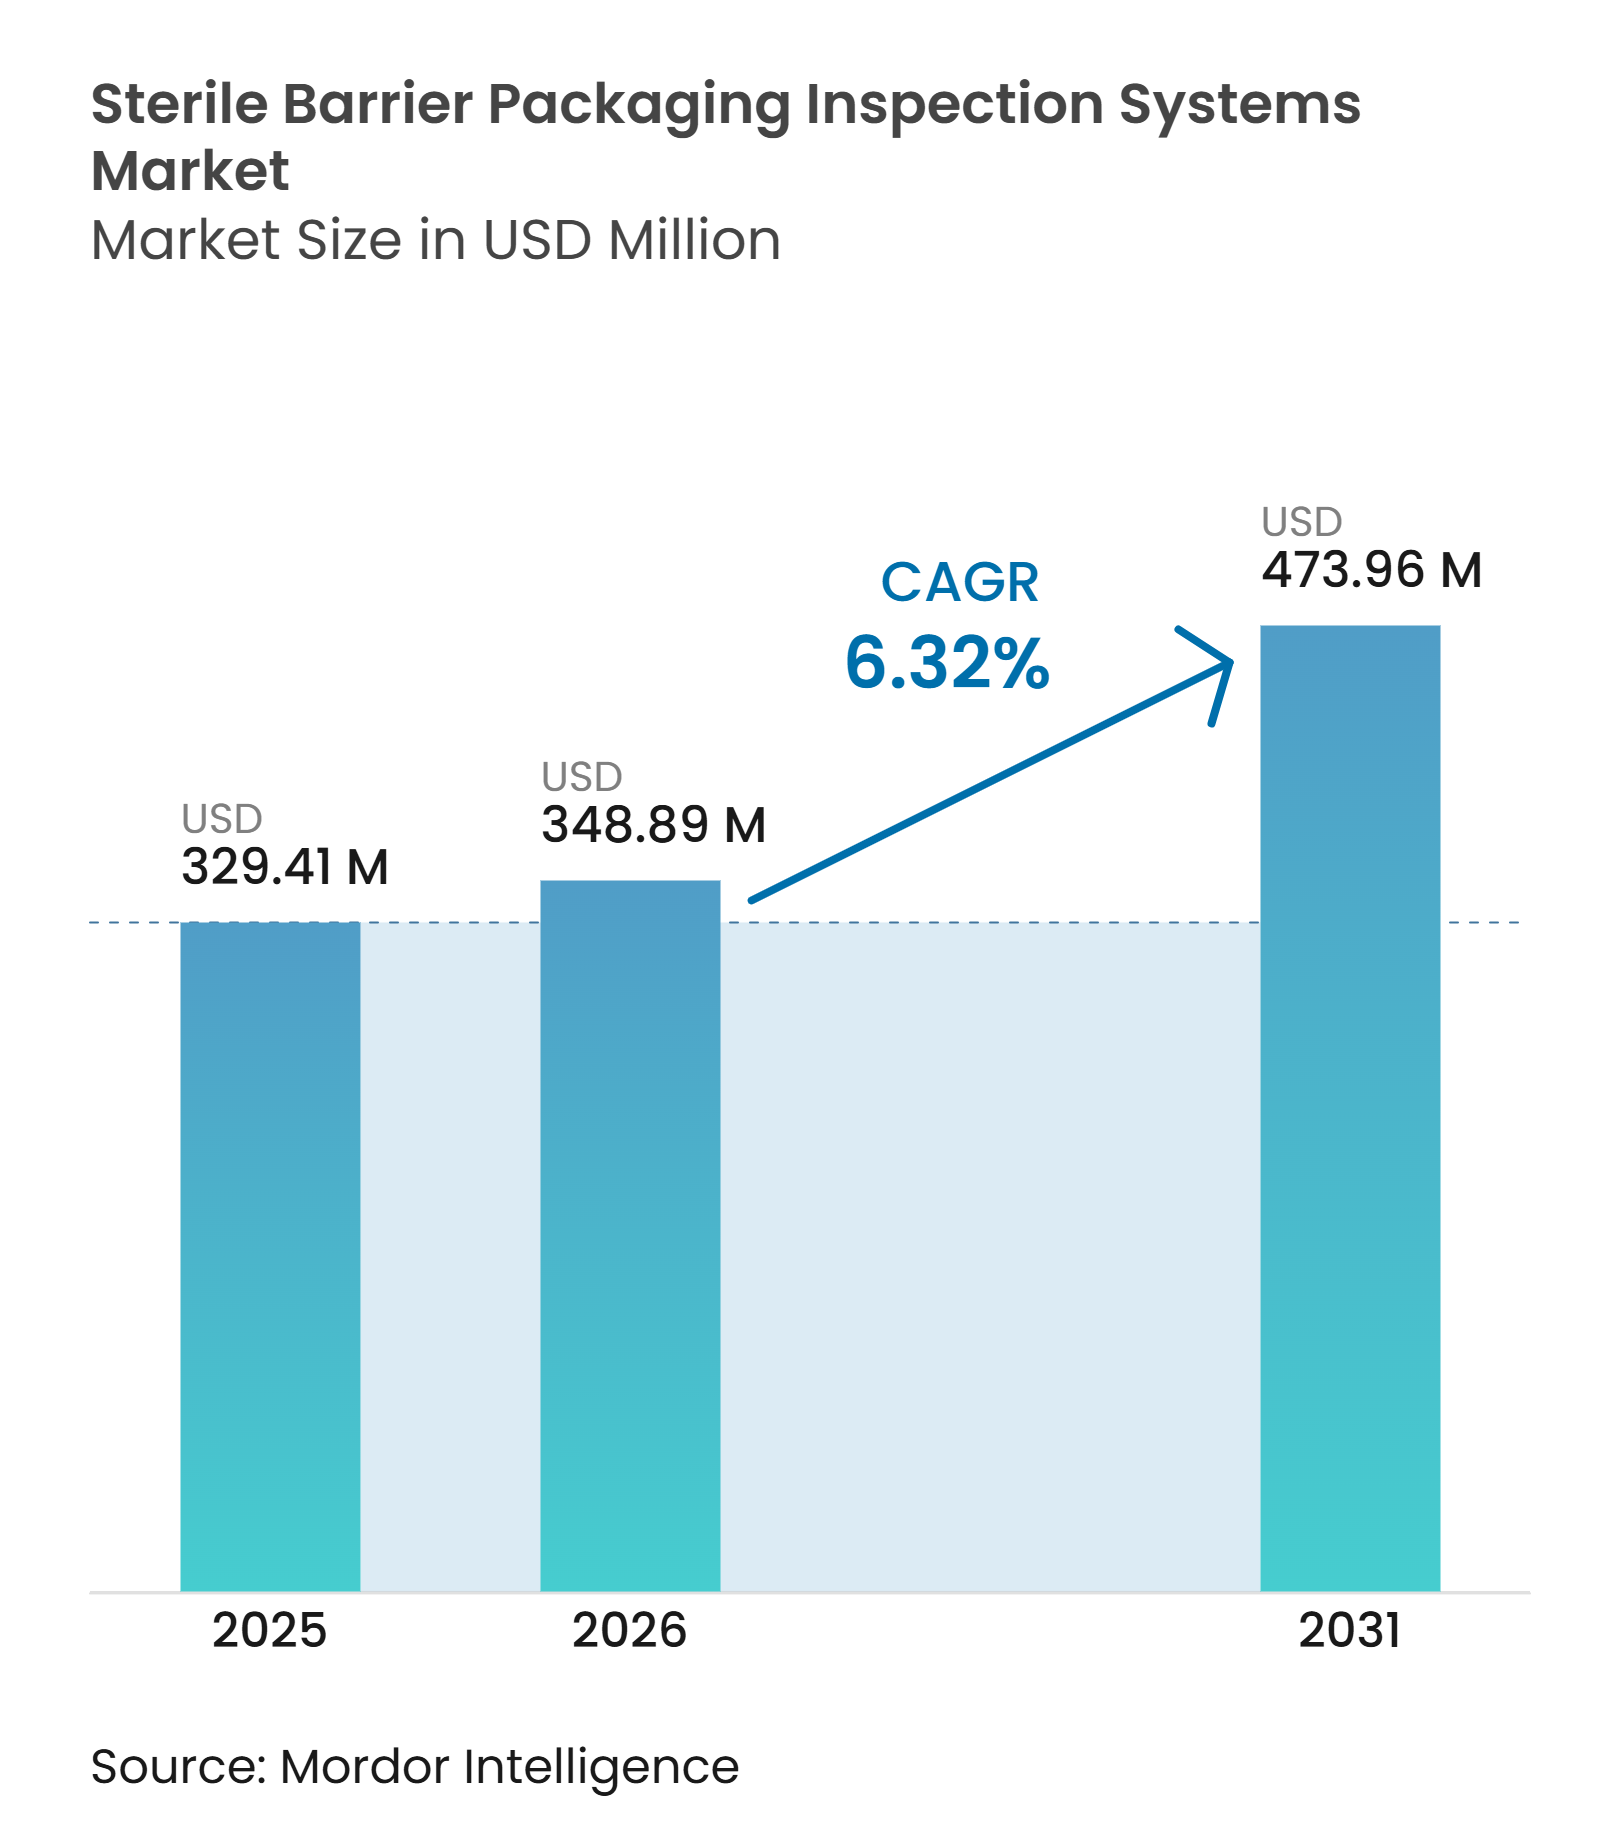
The sterile barrier packaging inspection systems market size was valued at USD 329.41 million in 2025 and estimated to grow from USD 348.89 million in 2026 to reach USD 473.96 million by 2031, at a CAGR of 6.32% during the forecast period (2026-2031). Regulatory changes are driving equipment decisions, particularly where sterile barrier validation must be repeated after a standard revision. The sterile barrier packaging inspection systems market is also moving toward continuous, unit-level checks that can support high-speed sterile production. Inspection suppliers are combining visual inspection, leak detection, data capture, and traceability functions within fewer production-line systems. This shift gives established suppliers an advantage where validation records, engineering support, and integration experience matter to buyers. Demand opportunities are strongest where new sterile capacity, changing packaging formats, and audit-ready electronic records require new inspection capabilities.
Key Report Takeaways
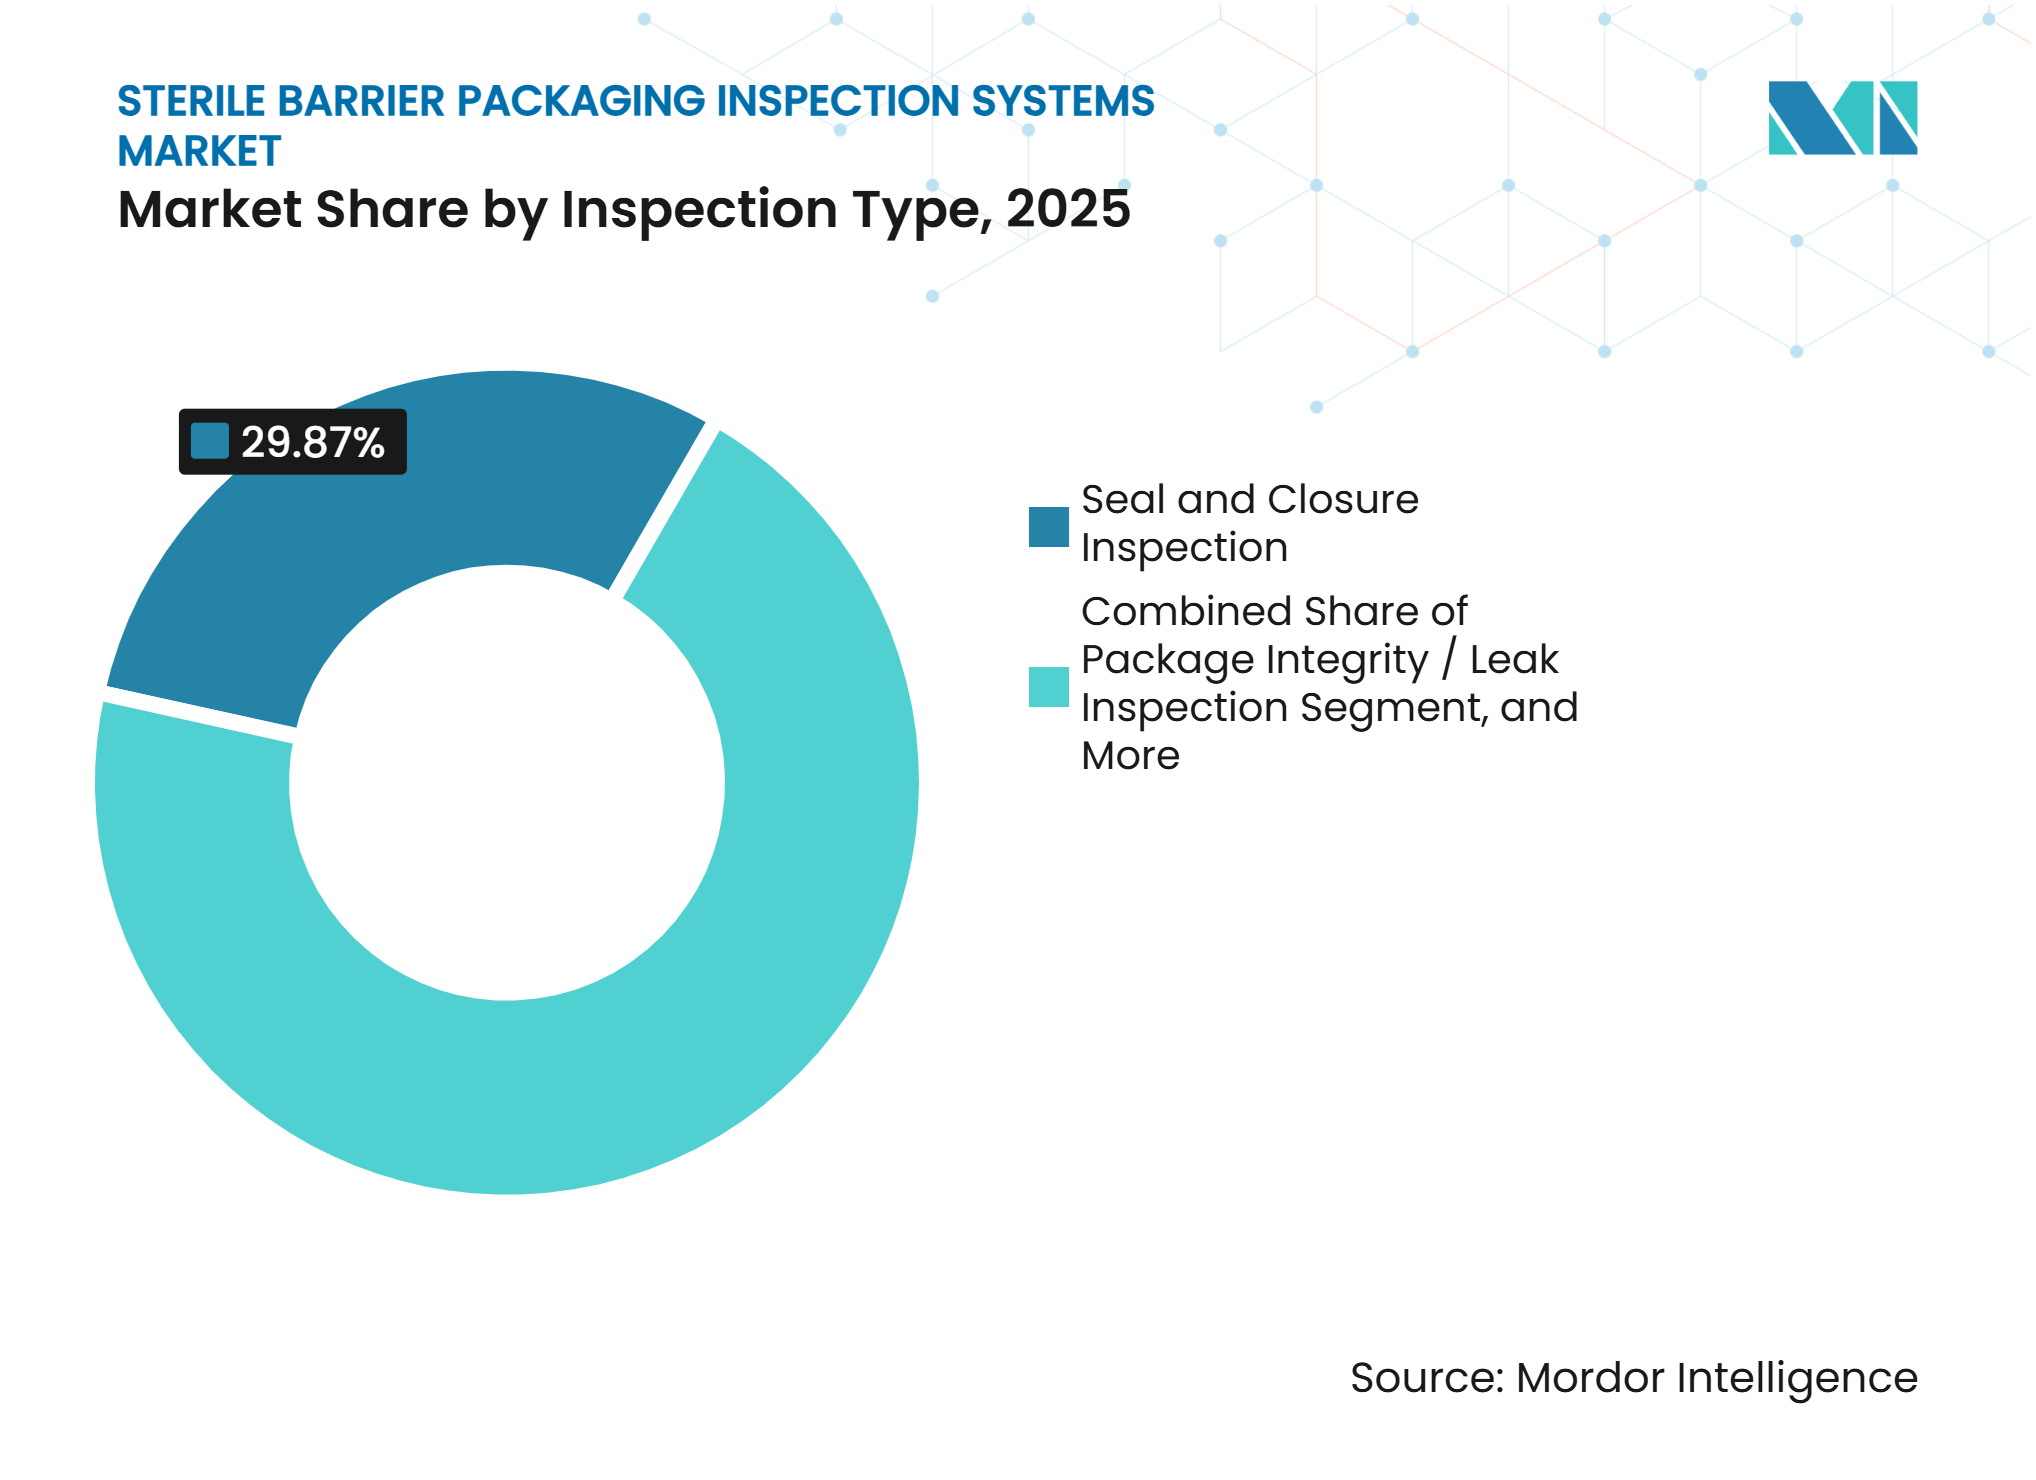
- By inspection type, Seal and Closure Inspection led the sterile barrier packaging inspection systems market, while Package Integrity and Leak Inspection is projected to expand at a 7.59% CAGR through 2031.
- By package format, Pouches and Bags held 35.59% of revenue in 2025, while Rigid Trays and Lidded Trays are expected to expand at a 7.12% CAGR through 2031.
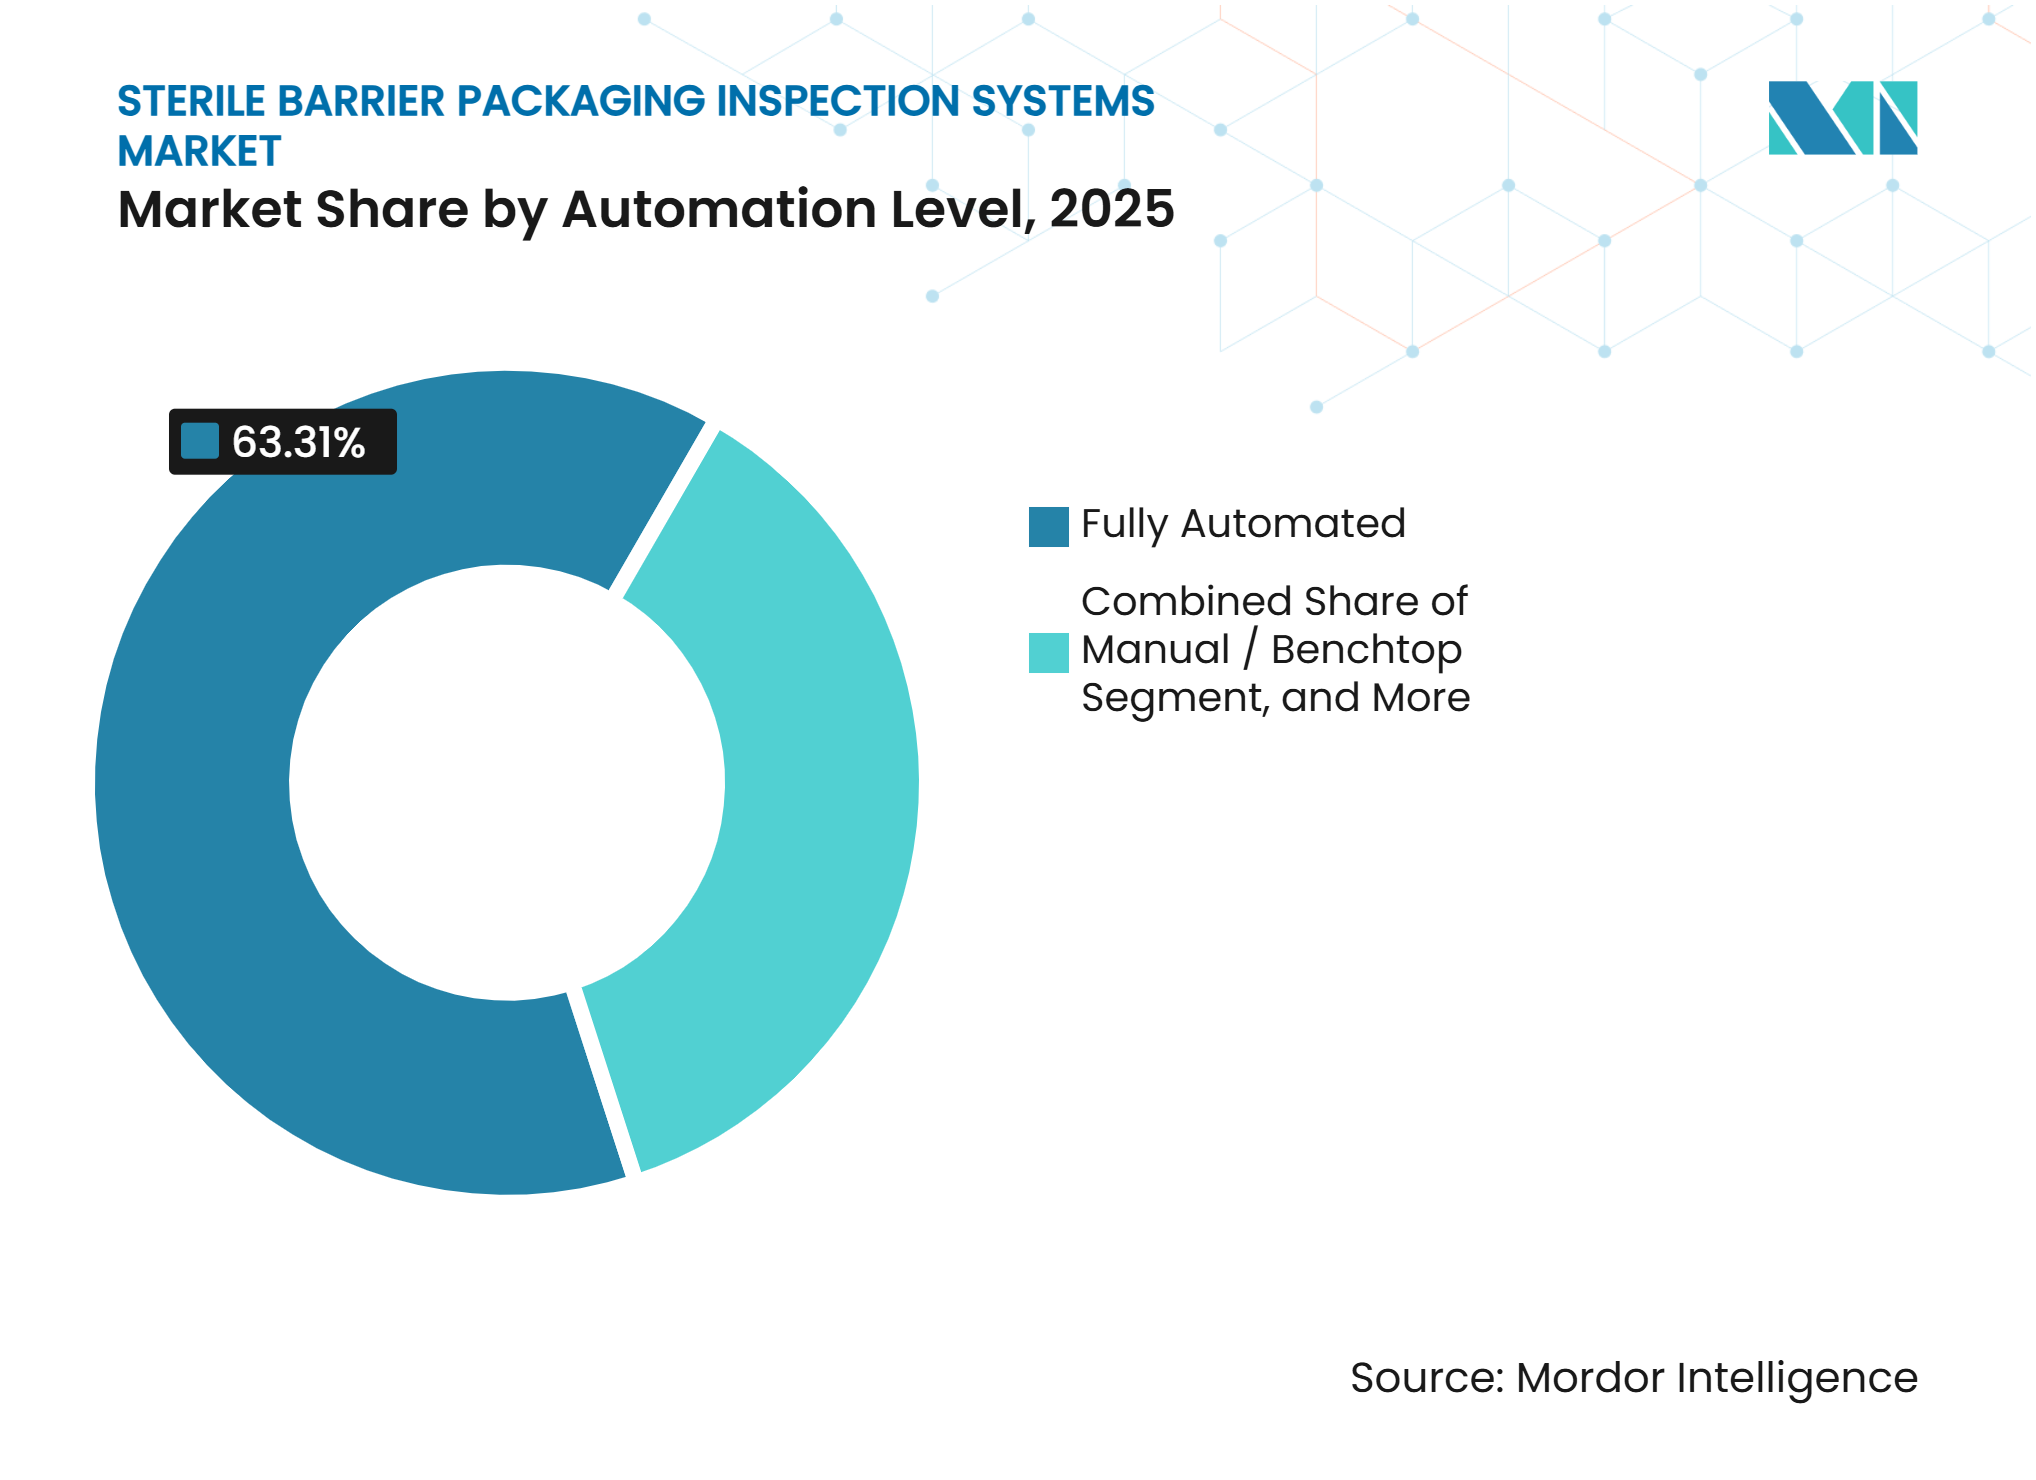
- By automation level, Fully Automated systems accounted for 63.31% of revenue in 2025 and are projected to grow at a 7.25% CAGR through 2031.
- By end-user, Medical Device Manufacturers held 66.43% of revenue in 2025, while Contract Manufacturers and CMO-CDMOs are projected to grow at a 7.34% CAGR through 2031.
- By geography, North America accounted for 34.96% of revenue in 2025, while Asia-Pacific is expected to grow at a 7.41% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Sterile Barrier Packaging Inspection Systems Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| ISO 11607 Validation and Process Control Spending | +1.4% | Global, concentrated in North America and Europe | Short term (≤ 2 years) |
| Shift From Sampling to 100% Inline Inspection | +1.2% | Global, strongest in North America and Europe, growing in Asia-Pacific | Medium term (2-4 years) |
| High-Throughput Sterile Device Manufacturing Growth | +0.9% | Asia-Pacific core, with spillover to North America and Europe | Medium term (2-4 years) |
| Digital Traceability and Electronic Batch-Record Integration | +0.7% | Global, compliance-led in North America and the European Union | Medium term (2-4 years) |
| Infrared and Airborne Ultrasound Adoption in Medical Packaging | +0.5% | North America and Europe, with early adoption in Asia-Pacific | Long term (≥ 4 years) |
| Defect-Library Learning From Sterilization and Distribution Data | +0.3% | North America and Europe | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
ISO 11607-Driven Validation and Process-Control Spending
ISO 11607 revisions are prompting manufacturers to requalify their inspection processes rather than simply replace equipment. EN ISO 11607-2:2026 introduced a Dynamic Moist Microbial Penetration Test for Tyvek sterile lids, with the stated January 2027 compliance deadline increasing demand for seal-integrity testing.[1] ISO/FDIS 11607-3 was in the final draft stage in April 2026 and addresses process development requirements for forming, sealing, and assembly operations. These requirements place more importance on inspection methods that can be documented and repeated across production settings. A new method may require installation, operational, and performance qualification records before it supports batch-release decisions. The sterile barrier packaging inspection systems market, therefore, benefits when manufacturers seek systems with proven validation support and compatible documentation.
Shift From Sampling to 100% Inline Inspection
The shift from batch sampling to unit-level container-closure integrity testing is changing replacement decisions across sterile packaging lines. Deterministic methods, including vacuum decay and airborne ultrasound, provide quantitative results that can reduce reliance on subjective dye penetration or water-bath testing. Airborne ultrasound supports non-destructive testing of porous materials and can be configured for inline use. Continuous inspection also creates more data for defect classification and process monitoring. Systems that maintain inspection sensitivity at production speed can limit the throughput concerns associated with broader coverage. The sterile barrier packaging inspection systems market is gaining from this change because customers increasingly treat inspection data as part of production control.
Growth of High-Throughput Sterile Device Manufacturing
New sterile fill-finish and device production lines require inspection equipment validated for the relevant package formats. PCI Pharma Services announced more than USD 1 billion in investments across the United States and European operations during April 2026. The program includes automated visual inspection supporting more than 70 million prefilled syringes and cartridges and 40 million vials annually. Format compatibility remains important because contract manufacturers may handle multiple customer products and package designs. Inspection suppliers can also retain revenue through calibration, revalidation, and replacement services after installation. The sterile barrier packaging inspection systems market gains as capacity investments bring inspection requirements into early project planning.
Digital Traceability and Electronic Batch-Record Integration
Electronic batch records are becoming more relevant when buyers select inspection platforms for regulated sterile operations. Körber introduced PAS-X Track and Trace in March 2025 as a cloud-native, vendor-neutral site-management platform for packaging lines, manufacturing execution systems, and enterprise resource planning systems. The platform reflects demand for systems that connect line information with plant-level records. Inspection suppliers must increasingly provide compatible communication protocols and controlled data logging. This capability can help manufacturers review production events and preserve an audit trail across packaging operations. The sterile barrier packaging inspection systems market is supported when inspection equipment is purchased as part of a connected production environment.
Restraints Impact Analysis of Sterile Barrier Packaging Inspection Systems Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Validation Burden for New Inspection Modalities | -0.9% | Global, most acute in North America and Europe | Short term (≤ 2 years) |
| High Retrofit Cost and Line-Integration Complexity | -0.7% | Global, most significant in established North American and European facilities | Medium term (2-4 years) |
| False-Reject Risk for Porous and Reflective Materials | -0.4% | Global | Medium term (2-4 years) |
| Shortage of Packaging-Process and Machine-Vision Specialists | -0.3% | Global, particularly acute in North America and Europe | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Validation Burden for New Inspection Modalities
New inspection methods require documented installation, operational, and performance qualification before regulated facilities can rely on them for release decisions. This work can extend the adoption period even where a technology offers clear technical benefits. Validation can be especially demanding for packages with uncommon shapes, materials, or seal structures. Manufacturers need evidence that the system works across the defined production range and remains reliable during normal operation. The requirement increases the value of established methods, published testing approaches, and suppliers with application support. The sterile barrier packaging inspection systems market faces a slower adoption path, with buyers required to undergo lengthy qualification cycles for new technologies.
High Retrofit Cost and Line-Integration Complexity
Existing lines designed around manual sampling may need mechanical, software, and cleanroom changes before deterministic inline inspection can be added. Older facilities may lack the footprint, conveyor arrangement, speed control, or electrical design needed for an integrated system. ATEQ introduced its Series 7 leak and flow testing platform in July 2026 with integration support and on-site calibration across more than 40 countries. The need for this support shows that installation remains a material part of the purchase decision. Downtime, redesign, and revalidation can raise the total cost beyond the equipment price for retrofit projects. The sterile barrier packaging inspection systems market may experience order delays when smaller manufacturers and hospital sterile supply departments cannot justify full automation.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Sterile Barrier Packaging Inspection Systems Market Segment Analysis
By Inspection Type:
Deterministic Leak Testing Gains MomentumPackage Integrity and Leak Inspection is projected to record a 7.59% CAGR from 2026 to 2031, making it the fastest-growing inspection category. The sterile barrier packaging inspection systems market size in this category is driven by demand for deterministic, non-destructive container closure integrity testing. Vacuum decay and airborne ultrasound offer quantitative results for pouches, rigid trays, and parenteral containers. In the sterile barrier packaging inspection systems market, these approaches can yield results less dependent on operator interpretation. Manufacturers can use them to support a more consistent review of seal quality and package integrity. They also align with the broader shift toward electronic records and repeatable process controls.
Seal and Closure Inspection held the largest position within inspection type because it applies to a broad range of sterile packaging formats. It remains a basic control point in sterile packaging operations, from initial package formation through final inspection. Foreign Particle and Contamination Inspection is benefiting from machine-learning tools that use prior defect records to support classification. Package Appearance and Cosmetic Inspection serves both the quality requirements and the presentation needs of finished packs. Label and Print Inspection supports identification and serialization requirements where information accuracy is essential. Product Presence and Position Inspection addresses assembly and pack-completeness checks for drug-device combinations and other complex packs.



By Package Format:
Pouches Lead While Rigid Trays ExpandPouches and Bags accounted for 35.59% of revenue in 2025 and represented the largest package-format position. This segment held the leading share of the sterile barrier packaging inspection systems market because pouches are widely used for implants, procedure kits, and single-use medical instruments. Airborne ultrasound is suited to pouch seals because it can inspect porous materials without destroying the package. PTI describes its Seal-Sensor system as an inline platform for 100% pouch-seal scanning in accordance with ASTM F3004-13. This capability supports continuous monitoring at production speed. It can reduce reliance on end-of-line sampling for relevant pouch applications.
Rigid Trays and Lidded Trays are expected to grow at a 7.12% CAGR through 2031. Demand is linked to robotic-assisted surgery kits and orthopedic implant sets that use thermoformed rigid trays. The sterile barrier packaging inspection systems market requires reliable inspection of seals, lid placement, package geometry, and potential leaks for these formats. Blister and Tub Formats also require specialized methods for pharmaceutical packaging applications. Sepha offers VisionScan 3D for non-destructive blister-leak detection, replacing destructive blue-dye testing for applicable formats.[2] Sterilization Wraps and Reels, Rigid Containers and Cases, and other formats remain relevant in hospital sterile supply and specialty-device settings.
By Automation Level:
Fully Automated Systems Hold the LeadFully Automated systems held 63.31% of revenue in 2025, reflecting demand for continuous inspection at production speed. The sterile barrier packaging inspection systems market share at this automation level is driven by the need for broad inline coverage. Syntegon launched the AIM9 in February 2026, featuring visual inspection and integrated container closure integrity testing, with output up to 600 vials per minute. The platform combines line-scan and area-scan cameras with optional deep-learning functions. In the sterile barrier packaging inspection systems market, integrated designs can reduce the number of systems required in the cleanroom. They may also help users coordinate visual checks and leak-detection activities.
Semi-Automated systems occupy a narrower position between high-throughput automation and basic benchtop testing. They may not meet the speed needs of large contract manufacturing lines. They can also be too costly for low-volume facilities that only need limited release testing. Manual and Benchtop systems continue to support method development, process characterization, and clinical-stage batches. Their lower level of automation can be suitable when full production-line integration is not justified. Semi-automated suppliers may find opportunities where line speeds are moderate and product portfolios are still developing.

By End-User:
Medical Device Manufacturers Lead DemandMedical Device Manufacturers held 66.43% of revenue in 2025 and remained the largest end-user group. Their position reflects direct responsibility for sterile barrier integrity through the product's shelf life. The sterile barrier packaging inspection systems market size in this end-user group is supported by design-control requirements and product-liability exposure. For the sterile barrier packaging inspection systems market, these factors make inspection spending less dependent on short-term changes in capital equipment. Buyers need systems that cover their relevant formats and support documented quality processes. Medical device companies also require equipment that can fit established manufacturing and cleanroom procedures.
Contract Manufacturers and CMO-CDMOs are projected to advance at a 7.34% CAGR through 2031. Their demand is linked to the continued outsourcing of sterile fill-finish and assembly work by pharmaceutical and biotechnology sponsors. These organizations often manage multiple customer stock-keeping units and package configurations. They value format flexibility, rapid changeover, and the ability to apply different inspection methods within the same operation. Pharmaceutical Manufacturers remain another major customer group, with inspection needs shaped by sterile production and container closure expectations. Sterile Packaging Manufacturers invest in inspection systems to provide quality-assured pouches, reels, and trays to downstream customers.
Geography Analysis
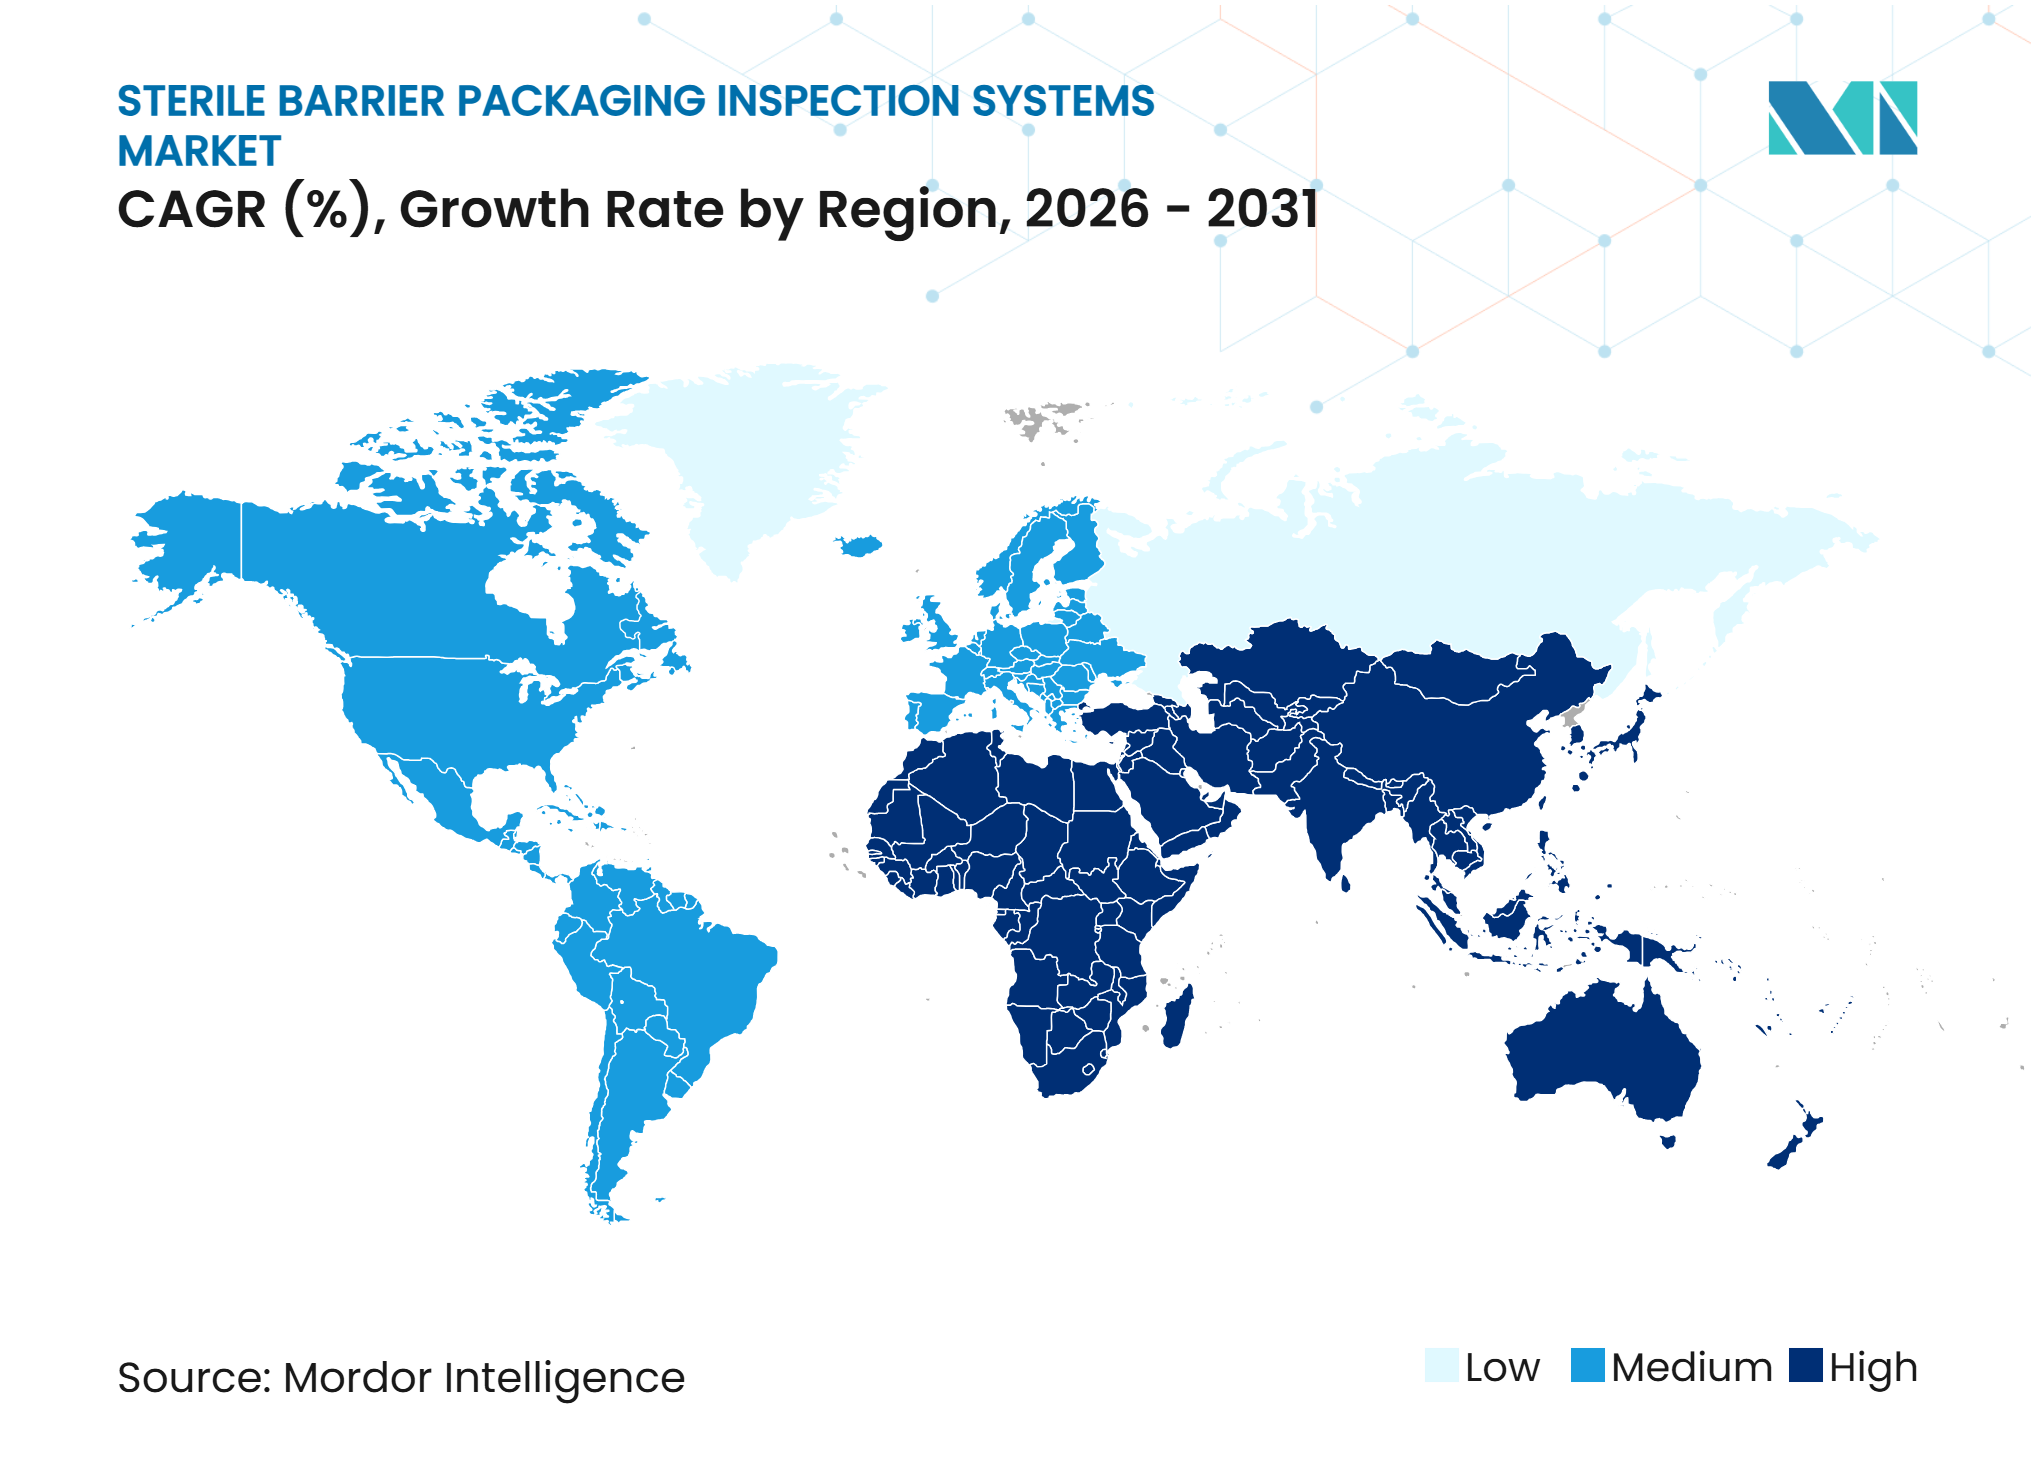
North America held 34.96% of revenue in 2025 and was the largest regional contributor. This regional revenue share reflects a high concentration of regulated sterile manufacturing sites. Facilities in the sterile barrier packaging inspection systems market are seeking integrated systems that provide controlled data outputs and fit electronic-record requirements. The United States drives most regional demand through its large base of medical device and pharmaceutical production. Canada and Mexico add demand as suppliers expand production for North American regulated markets.
Asia-Pacific is projected to grow at a 7.41% CAGR from 2026 to 2031. China’s GB/T 19633.2-2024 standard became effective in December 2025 and aligns domestic packaging validation requirements with ISO 11607. India’s Production-Linked Incentive program supports domestic medical device manufacturing and adds to regional equipment needs. Japan published updated JIS T 0841-1 and JIS T 0841-2 standards in 2026, aligning with ISO 11607.[3] Sepha’s participation at Korea Pack 2026 and Thailand LAB International 2026 shows active commercial engagement across Asia-Pacific.
Europe was the second-largest regional revenue contributor, with Germany, France, the United Kingdom, Italy, and Spain forming the core demand base. Changes to EN ISO 11607-2:2026 are encouraging revalidation activity among device producers and sterile packaging converters. Germany remains both a major customer base and a technology export center for the sterile barrier packaging inspection systems market. South America has growing demand centered on Brazil and Argentina, although infrastructure limitations and currency volatility can slow system adoption. The Middle East and Africa represent a smaller combined opportunity, while healthcare investment in Gulf Cooperation Council countries supports new local sterile manufacturing capacity.
Competitive Landscape
Market Concentration
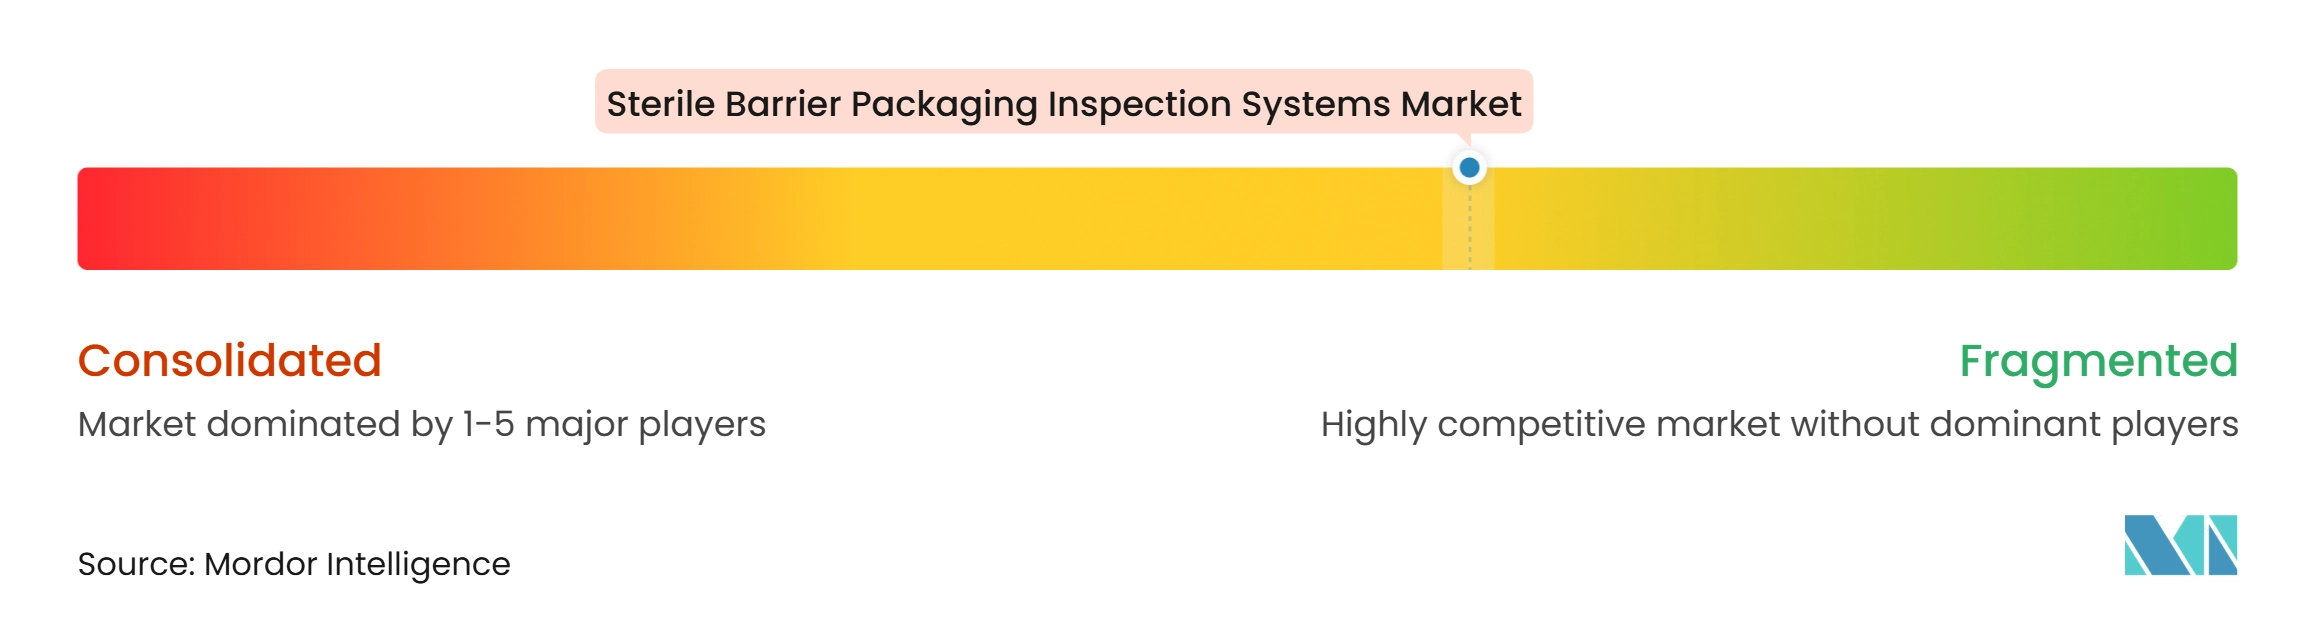
The sterile barrier packaging inspection systems market is moderately fragmented, with specialized container-closure testing providers competing against larger line-automation companies. PTI, Sepha, ATEQ, and Cognex Corporation focus on testing methods, validation experience, and application engineering. Cognex, Mettler-Toledo, Antares Vision Group, and Syntegon offer inspection as part of broader automation portfolios. Larger suppliers can combine inspection with filling, labeling, serialization, and service capabilities. Specialized companies compete where customers require detailed knowledge of methods for difficult package formats.
Technology competition increasingly centers on defect classification, connected analytics, and integrated line functions. Cognex introduced the In-Sight 3900 Vision System in May 2026, with embedded artificial intelligence, up to 25 MP resolution, and faster processing than its previous generation. Syntegon’s AIM9 combines visual inspection and container closure integrity testing on a single platform. Antares Vision Group introduced its CY Series for prefilled-syringe inspection and leak detection at Interphex NYC 2026.[4] WITT Gasetechnik acquired INFICON’s Contura leak-detection product line and associated patents effective July 1, 2026, then rebranded the range as Leak Master Contura.
This move changed ownership in the pressure-differential leak-detection category. Suppliers are seeking stronger software, service, and application-engineering capabilities as hardware features become easier to compare. The sterile barrier packaging inspection systems market offers room for focused suppliers in semi-rigid packs, sterilization wraps, and combination drug-device kits. False rejects on porous or reflective materials remain a practical concern because they can raise line downtime and affect automation economics.
Sterile Barrier Packaging Inspection Systems Industry Leaders
-
Packaging Technologies and Inspection (PTI)
-
Sepha Ltd
-
ATEQ SAS
-
Cognex Corporation
-
Mettler-Toledo International Inc.
- *Disclaimer: Major Players sorted in no particular order
Sterile Barrier Packaging Inspection Systems Market Companies Covered in this Report
- Packaging Technologies and Inspection (PTI)
- Sepha Ltd
- ATEQ SAS
- Cognex Corporation
- Mettler-Toledo International Inc.
- Antares Vision S.p.A.
- Syntegon Technology GmbH
- Ishida Co., Ltd.
- Wipotec-OCS GmbH
- Industrial Vision Systems Ltd
- Vision Engineering Ltd
- Labthink International, Inc.
- Teledyne Technologies Incorporated
- Van der Stahl Scientific
- Optimeasure Ltd
- Nolek A/S
- TriVision A/S
Recent Industry Developments in Sterile Barrier Packaging Inspection Systems Market
- September 2026: Systech, part of Markem-Imaje and Dover, launched Systech TraceIQ, an enterprise pharmaceutical traceability platform that transforms serialization data from passive compliance records into operational intelligence supporting inspection and packaging line coordination. The launch directly addresses the growing need for audit-ready inspection-to-traceability data integration across global sterile supply chains.
- July 2026: ATEQ Leaktesting launched its Series 7 leak and flow testing platform, comprising 3 models, F720, F750, and F770, with high-precision measurement down to 0.001 Pa resolution, cloud connectivity for remote diagnostics, and support across 40-plus countries. The platform is positioned for automated inline integration across medical device and pharmaceutical packaging applications.
- June 2026: ISO and CEN formally issued EN ISO 11607-2:2026, introducing a mandatory Dynamic Moist Microbial Penetration Test for Tyvek sterile lids. The European Commission's EC No. 2026/1387, effective June 29, 2026, invalidated EN ISO 11607-2:2019 certification for EU exports, with a 90-day retesting window for Chinese manufacturers.
- May 2026: Syntegon presented OpaqView, an inspection technology for opaque injectable products, at the PDA Visual Inspection Forum in Dublin. The technology uses cameras, illumination, and software to detect particles in formulations that conventional visual inspection cannot reliably address and is available on Syntegon automated inspection platforms.
Global Sterile Barrier Packaging Inspection Systems Market Report Scope
The sterile barrier packaging inspection systems market comprises technologies and equipment used to assess the integrity, quality, and compliance of sterile barrier packaging. These systems inspect packaging for defects such as leaks, seal failures, contamination, and material inconsistencies to help ensure that medical devices, pharmaceuticals, and other sterile products remain protected throughout their shelf life.
The Sterile Barrier Packaging Inspection Systems Market Report is Segmented by Inspection Type (Seal and Closure Inspection, Package Integrity / Leak Inspection, Foreign Particle and Contamination Inspection, Package Appearance / Cosmetic Inspection, Label, Print, and Code Inspection, Product Presence and Position Inspection, and Other Inspection Types), Package Format (Pouches and Bags, Rigid Trays and Lidded Trays, Blister and Tub Formats, Sterilization Wraps and Reels, Rigid Containers and Cases, and Other Package Formats), Automation Level (Fully Automated, Semi-Automated, and Manual / Benchtop), End-User (Medical Device Manufacturers, Pharmaceutical Manufacturers, Contract Manufacturers / CMO-CDMOs, Sterile Packaging Manufacturers, and Other End-Users), and Geography (North America, South America, Europe, Asia-Pacific, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Seal and Closure Inspection |
| Package Integrity / Leak Inspection |
| Foreign Particle and Contamination Inspection |
| Package Appearance / Cosmetic Inspection |
| Label, Print, and Code Inspection |
| Product Presence and Position Inspection |
| Other Inspection Types |
| Pouches and Bags |
| Rigid Trays and Lidded Trays |
| Blister and Tub Formats |
| Sterilization Wraps and Reels |
| Rigid Containers and Cases |
| Other Package Formats |
| Fully Automated |
| Semi-Automated |
| Manual / Benchtop |
| Medical Device Manufacturers |
| Pharmaceutical Manufacturers |
| Contract Manufacturers / CMO-CDMOs |
| Sterile Packaging Manufacturers |
| Other End-Users |
| North America | United States |
| Canada | |
| Mexico | |
| South America | Brazil |
| Argentina | |
| Chile | |
| Rest of South America | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Spain | |
| Rest of Europe | |
| Asia-Pacific | China |
| Japan | |
| India | |
| South Korea | |
| Australia | |
| Rest of Asia-Pacific | |
| Middle East | United Arab Emirates |
| Saudi Arabia | |
| Turkey | |
| Rest of Middle East | |
| Africa | South Africa |
| Egypt | |
| Rest of Africa |
| By Inspection Type | Seal and Closure Inspection | |
| Package Integrity / Leak Inspection | ||
| Foreign Particle and Contamination Inspection | ||
| Package Appearance / Cosmetic Inspection | ||
| Label, Print, and Code Inspection | ||
| Product Presence and Position Inspection | ||
| Other Inspection Types | ||
| By Package Format | Pouches and Bags | |
| Rigid Trays and Lidded Trays | ||
| Blister and Tub Formats | ||
| Sterilization Wraps and Reels | ||
| Rigid Containers and Cases | ||
| Other Package Formats | ||
| By Automation Level | Fully Automated | |
| Semi-Automated | ||
| Manual / Benchtop | ||
| By End-User | Medical Device Manufacturers | |
| Pharmaceutical Manufacturers | ||
| Contract Manufacturers / CMO-CDMOs | ||
| Sterile Packaging Manufacturers | ||
| Other End-Users | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| South America | Brazil | |
| Argentina | ||
| Chile | ||
| Rest of South America | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Spain | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| Japan | ||
| India | ||
| South Korea | ||
| Australia | ||
| Rest of Asia-Pacific | ||
| Middle East | United Arab Emirates | |
| Saudi Arabia | ||
| Turkey | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Egypt | ||
| Rest of Africa | ||
Key Questions Answered in the Report
What is the sterile barrier packaging inspection systems market size?
The market was valued at USD 329.41 million in 2025, is estimated at USD 348.89 million in 2026, and is forecast to reach USD 473.96 million by 2031.
What is driving demand for sterile barrier packaging inspection systems?
ISO 11607-related validation, wider inline inspection, sterile production capacity, and electronic batch-record integration are supporting demand.
Which inspection type is growing fastest?
Package Integrity and Leak Inspection is projected to grow at a 7.59% CAGR through 2031.
Which package format generated the most revenue?
Pouches and Bags accounted for 35.59% of revenue in 2025, supported by widespread medical device packaging use.
Which region is expected to grow fastest through 2031?
Asia-Pacific is projected to expand at a 7.41% CAGR, supported by standards alignment and growing device manufacturing capacity.