
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
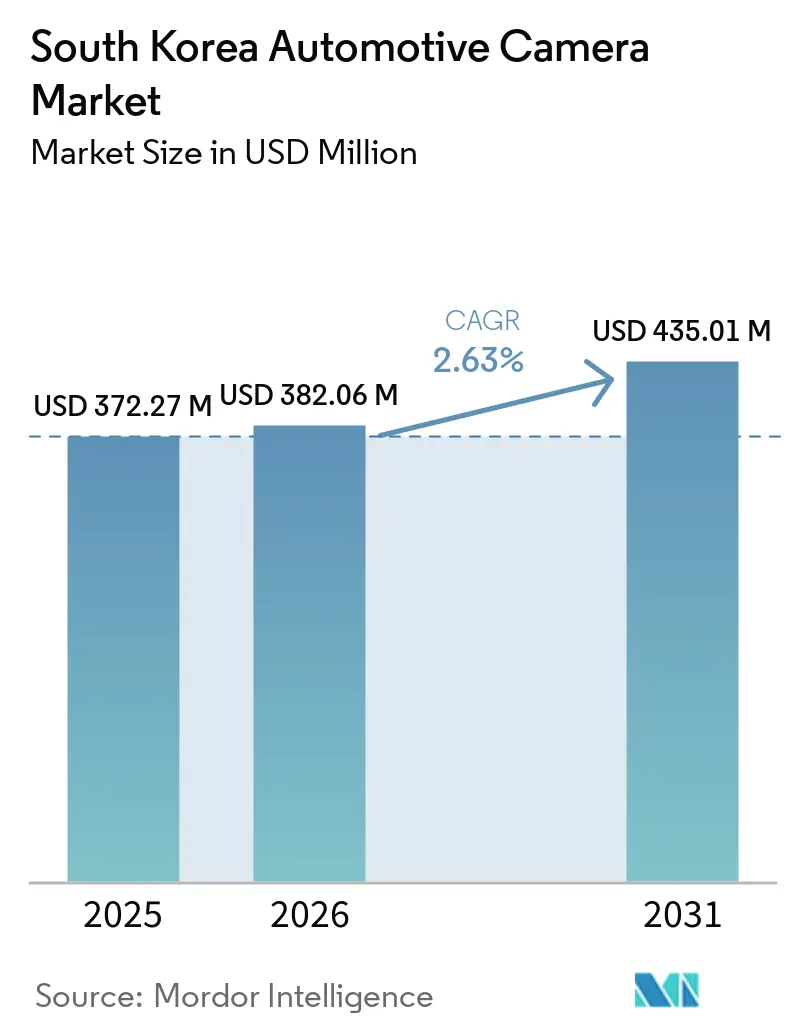
| Base Year Market Size (2025) | USD 372.27 Million |
| Market Size (2026) | USD 382.06 Million |
| Market Size (2031) | USD 435.01 Million |
| Growth Rate (2026 - 2031) | 2.63 % |
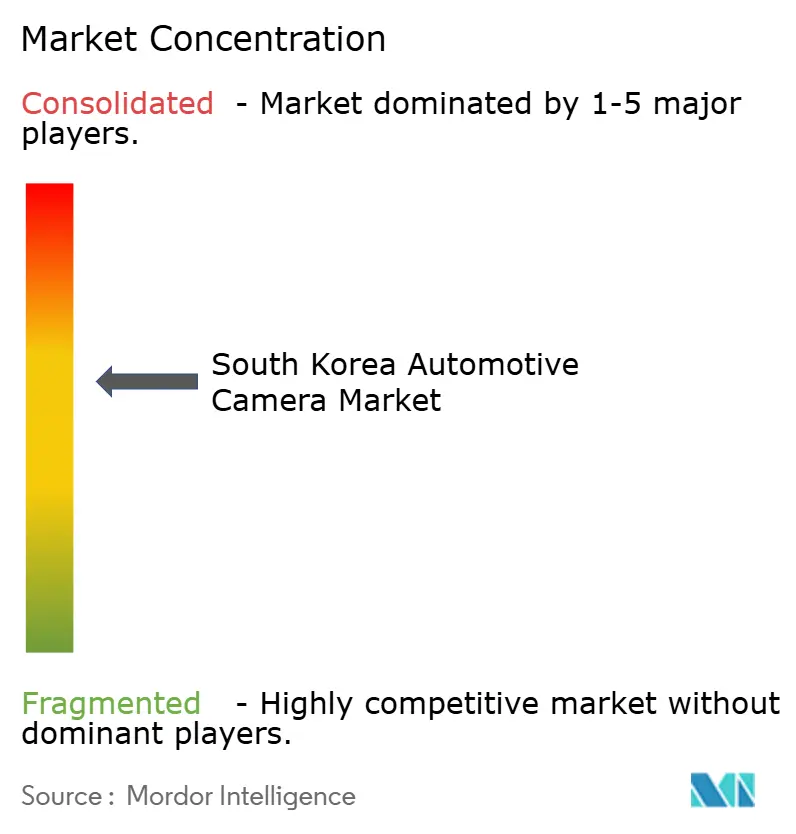
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
South Korea Automotive Camera Market Analysis by Mordor Intelligence
The South Korea automotive camera market size was valued at USD 372.27 million in 2025, is estimated at USD 382.06 million in 2026, and is projected to reach USD 435.01 million by 2031, growing at a CAGR of 2.63% from 2026 to 2031. Softer headline growth conceals an industry shift toward high-resolution sensing modules, edge AI processing, and interior monitoring mandates that favor domestic Tier-1 suppliers. Hyundai Motor Group’s decision to vertically integrate its camera supply chain reshapes the competitive landscape, pushing global vendors to differentiate on embedded AI rather than on unit price. Seoul’s 2027 occupant-monitoring rule and municipal retrofit incentives for legacy trucks are opening sizable aftermarket pools even as passenger-car installation rates plateau. Meanwhile, export contracts for smart-city buses signal that Korean module makers can leverage their home-market scale abroad. The short-term growth ceiling remains chip availability: TSMC’s tight 7 nm and 6 nm capacity is prolonging lead times for automotive-grade image-signal processors, delaying new-model launches, and forcing Hyundai to co-invest in Samsung’s 5 nm line.
Key Report Takeaways
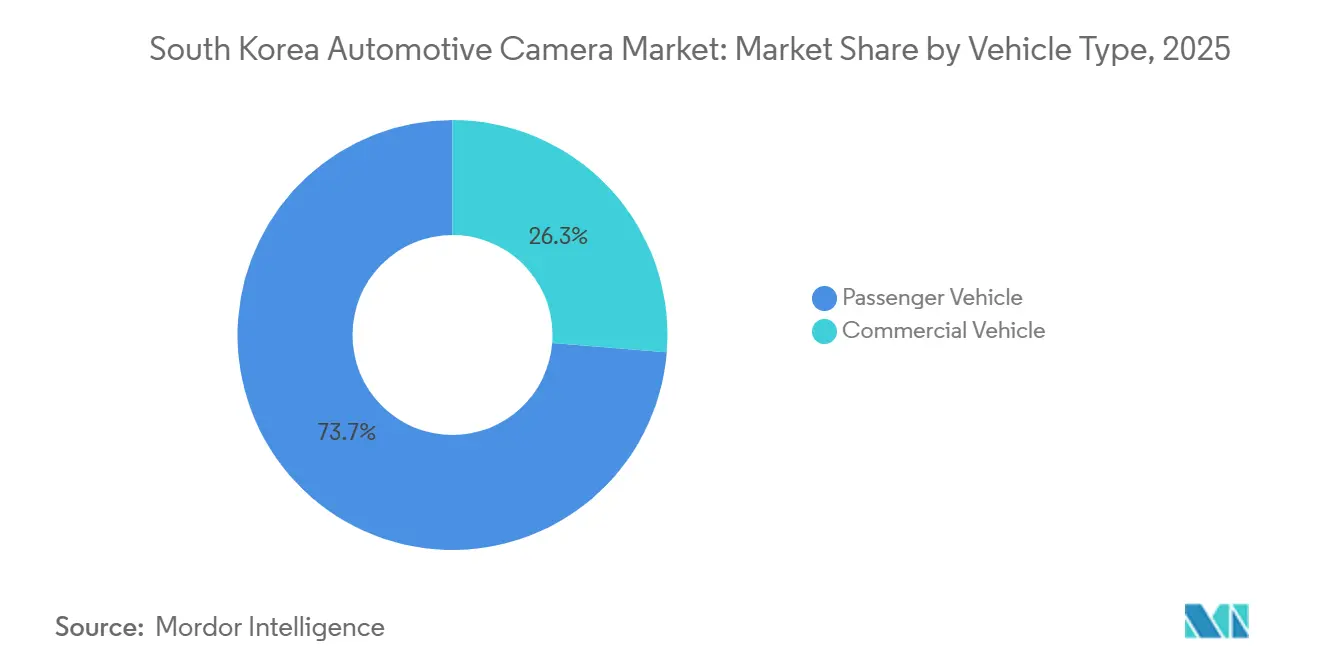
- By vehicle type, passenger cars led the South Korean automotive camera market with 73.73% of the market share in 2025, while commercial vehicles are expected to advance at a 4.37% CAGR through 2031.
- By camera type, viewing units captured 62.27% of the revenue in 2025; sensing cameras are forecast to expand at a 4.52% CAGR through 2031.
- By application, ADAS accounted for a 46.42% share of the South Korean automotive camera market in 2025, and driver monitoring is projected to grow at a 5.02% CAGR through 2031.
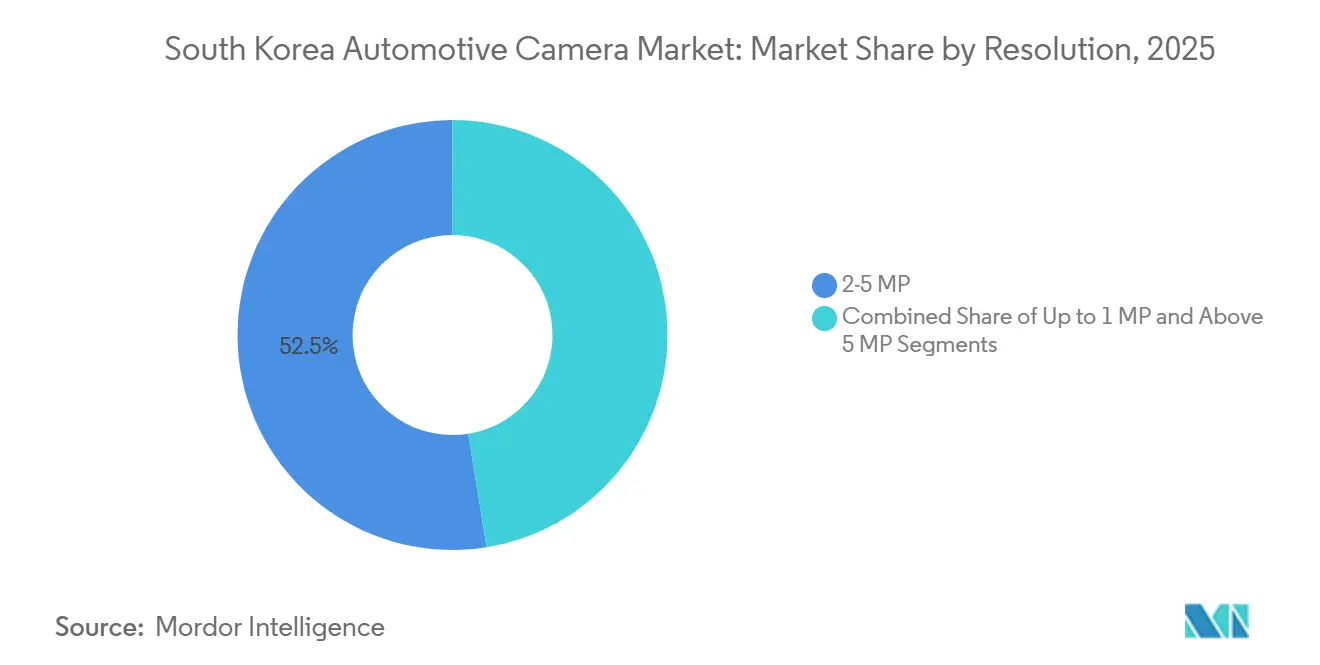
- By resolution, 2–5 MP devices commanded 52.53% share in 2025, whereas above-5 MP cameras are projected to rise at a 4.28% CAGR to 2031.
- By sales channel, OEM-fit systems held an 85.18% share in 2025; the aftermarket is projected to grow at a 4.74% CAGR until 2031.
- By mounting location, front cameras dominated with 34.39% share in 2025, but interior units are the fastest-growing at a 4.84% CAGR.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
South Korea Automotive Camera Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Hyundai/Kia L2+ ADAS Growth | +1.1% | National, with spill-over to ASEAN export markets | Short term (≤2 years) |
| Stricter NCAP/KNCAP Safety Rules | +0.8% | National, with early gains in Seoul, Busan, Incheon metro areas | Medium term (2-4 years) |
| 2027 Edge-AI Occupant Monitoring | +0.6% | National, phased rollout starting with commercial vehicles | Medium term (2-4 years) |
| Seoul Fleet Retrofit Subsidies | +0.4% | Seoul, Gyeonggi, Incheon metropolitan region | Medium term (2-4 years) |
| Falling 3-MP HDR CMOS Prices | +0.3% | Global supply chain, direct impact on Korean OEMs | Short term (≤2 years) |
| Smart City Bus Export Potential | +0.2% | National production, exports to Middle East and Southeast Asia | Long term (≥4 years) |
| Source: Mordor Intelligence | |||
Proliferation of Level 2+ ADAS in Hyundai/Kia Lines
Hyundai Motor Group has shipped a significant number of Level 2+ vehicles globally, equipping each with multiple cameras [1]. This development has notably increased the camera-to-vehicle ratio. Kia’s EV9 GT-Line, equipped with a wide-angle front camera, effectively reduces phantom braking incidents compared to radar-only systems by predicting lane-cut-ins. As Lidar technology remains cost-prohibitive, camera modules have emerged as the primary sensor. Hyundai Mobis’s advanced camera design enables long-range object detection at a fraction of the cost of Lidar. Additionally, Samsung Electro-Mechanics has introduced a four-camera system that delivers real-time stitched surround-view parking feeds for the Genesis GV lineup.
Tightening NCAP and KNCAP Safety Mandates
The Ministry of Land, Infrastructure, and Transport elevated KNCAP to a higher performance standard, requiring forward-collision warnings, lane-departure warnings, and automatic emergency braking (AEB) for a top safety rating. Original Equipment Manufacturers (OEMs) have started standardizing these sensors, with Hyundai and Kia incorporating collision assistance as a standard feature in most of their passenger models. Failures at tunnel exits have been a significant issue during KNCAP testing. To address this, suppliers are now utilizing HDR cameras with higher frame rates to reduce glare saturation. Future protocols will include pedestrian detection as a mandatory feature, driving the transition from lower-resolution to higher-resolution front cameras capable of detecting silhouettes at greater distances. Additionally, certifications such as functional-safety ISO 26262 and cybersecurity ISO/SAE 21434 have become critical requirements, creating substantial barriers for consumer-grade imports.
Edge-AI-Enabled Occupant-Monitoring Mandate (2027)
Government mandates will soon require trucks over a certain weight to install driver-attention cameras, with the requirement extending to passenger cars shortly after. Due to privacy laws prohibiting the cloud upload of interior footage, suppliers are turning to on-device solutions with embedded neural networks. For instance, LG Innotek's direct-heating module efficiently tracks gaze at high frame rates while consuming minimal power. Meanwhile, HL Klemove's camera, powered by Qualcomm Snapdragon Ride, can quickly detect microsleep. As a testament to the growing demand, insurers are already offering discounts to fleets that implement these compliant systems [2].
Declining ASPs for 3 MP HDR CMOS Sensors
Recent price reductions for 3 MP HDR sensors, driven by expansions at Sony and OmniVision's fabs, allowed LG Innotek to lower material costs while maintaining strong gross margins[3]. Hyundai Mobis leveraged the cost curve to launch a competitively priced dual-camera dash-cam kit, significantly undercutting Chinese imports. High-dynamic-range imaging remains critical for highways with tunnels that experience significant luminance variations. The importance of HDR technology is evident, as non-HDR sensors have been linked to multiple recall incidents.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| TSMC N7/N6 Chip Bottlenecks | -0.5% | Global supply chain, acute impact on Korean Tier-1s | Short term (≤2 years) |
| Chinese Tier-2 Camera Price Pressure | -0.4% | Aftermarket and export channels | Short term (≤2 years) |
| Slow Adoption of KNCAP-Style AEB for CV Segment | -0.3% | National, concentrated in M&HCV operators | Medium term (2-4 years) |
| Privacy Barriers in Interior Analytics | -0.2% | National, with stricter enforcement in Seoul | Long term (≥4 years) |
| Source: Mordor Intelligence | |||
Automotive-Grade Chip Supply Bottlenecks
TSMC allocated a small portion of its wafers using advanced technology to automotive clients, which significantly extended lead times for image-signal processors. As a result, Hyundai postponed the launch of its Genesis GV90's surround-view feature by several months. To secure a local supply, Hyundai collaborated with Samsung Foundry to fund the construction of a new production line. Meanwhile, LG Innotek, while diversifying to STMicro's silicon, experienced a reduction in throughput. This limitation required them to lower the resolution of some trims from high to standard levels.
Competitive Price Pressure From Chinese Tier-2 Makers
Sunny Optical, Ofilm, and Luxvisions captured a significant portion of the aftermarket volume by offering products at prices notably lower than those of their Korean counterparts. Although Korean brands reduced retail dash-cam prices, they continued to experience margin erosion. OEM supplies remain supported by Hyundai's rigorous durability test and the IATF 16949 standard. However, the enforcement of these standards in retrofits is inconsistent. Anti-dumping duties were introduced, but customs audits have not yet aligned with import volumes.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Vehicle Type: Commercial-Fleet Upgrades Outpace Saturated Passenger Demand
Passenger cars retained 73.73% of South Korea's automotive camera market revenue in 2025, while commercial vehicles are projected to post a 4.37% CAGR through 2031, nearly double the passenger pace. Seoul's initiative under the Zero Traffic Fatality plan saw delivery vans retrofitted with blind-spot and rear cameras, boosting the South Korean automotive camera market.
As fleet electrification advances, the demand for automotive cameras is expected to continue rising. Light trucks, such as the Hyundai Porter EV, now include rear and surround-view cameras as standard features. Additionally, hydrogen-powered tractors are equipped with advanced camera systems. However, small owner-driver fleets remain hesitant due to the high cost of retrofitting advanced camera systems, which limits their adoption in medium- to heavy-duty trucks. On a positive note, municipal subsidies and insurer discounts are helping to make these systems more affordable. While passenger sedans generally feature fewer cameras, SUVs are equipped with more, reflecting differences in trim levels. This shift from focusing on volume to emphasizing value suggests that commercial fleets will play a pivotal role in driving revenue growth in the years to come.
By Camera Type: Sensing Units Close the Gap
Viewing cameras generated 62.27% of revenue in 2025, serving parking and rear-view functions. Sensing cameras, which embed ISPs and run object-detection algorithms, are forecasted to grow at a 4.52% CAGR, driven by KNCAP penalties for vehicles lacking forward-collision and lane-keeping support. As HDR sensors became commoditized, the cost gap between formats narrowed, enabling mid-tier trims to adopt advanced sensing.
In South Korea's automotive camera market, long-range front cameras are featured in select premium and electric vehicle models. In-cabin sensing cameras have been integrated into premium van segments, reflecting growing mainstream adoption of driver monitoring systems. Aftermarket dashcams continue to rely on viewing cameras, with price points kept below a certain threshold. ISO certification is required for sensing units but remains optional for basic viewing cameras, indicating a two-tier supply chain structure.
By Application: Driver Monitoring Takes the Growth Crown
ADAS remained the largest slice at 46.42% in 2025, but driver-monitoring cameras are the fastest-growing at 5.02% CAGR through 2031. Parking systems, now featured in most new passenger cars, face limited expansion potential. Following a pilot program that significantly reduced bus accidents in Seoul, insurers are offering discounts, spurring a surge in demand for interior cameras.
Remote Smart Parking Assist integrates multiple camera feeds into a comprehensive 3D view for select Hyundai and Kia models. Meanwhile, Kia's machine-learning cruise control, equipped with a wide-angle camera, predicts sudden lane changes, leading to a notable decrease in phantom braking. The South Korean automotive camera market, particularly in driver monitoring, is expected to grow substantially, driven by increasing adoption in commercial fleets. However, growth is anticipated to slow as the market matures.
By Resolution: Above-5 MP Moves Mainstream
2-5 MP cameras generated 52.53% of the revenue in 2025, balancing image clarity against data load. Above-5 MP devices, crucial for 360-degree surround-view and highway ADAS, are growing at a 4.28% CAGR, driven by Hyundai Mobis’s 8 MP module that detects obstacles at a distance of 150 m. Below-resolution threshold cameras are still found in budget models, but are expected to be phased out once pedestrian test requirements take effect.
Higher resolutions significantly increase ISP throughput demands, and as certification costs rise, premium trims are absorbing the higher bill of materials. At the same time, declining sensor prices are compressing margins for lower-resolution sensors, prompting suppliers to shift focus toward the upscale market. Mandatory resolution testing standards are extending validation cycles while reinforcing the quality advantage held by domestic Tier-1 suppliers.

By Sales Channel: Subsidies Propel the Aftermarket
OEM installations accounted for 85.18% of volume in 2025 due to Hyundai’s vertically integrated sourcing. The aftermarket is expected to grow at 4.74% annually as Seoul invests up to KRW 1.5 million per truck in blind-spot and surround-view upgrades. Hyundai Mobis's MCS-400 four-camera kit recorded strong sales, achieving significant installations and a dominant position in the aftermarket.
Chinese Tier-2 manufacturers gained a notable share of retrofit volume by offering lower prices than local brands. However, import duties and certification requirements limit their progress in the OEM segment. Following Seoul's initiative, Gyeonggi and Incheon plan to expand their retrofit programs, aiming to achieve substantial vehicle coverage in the coming years. While OEM fitment is approaching saturation, the aftermarket has become the primary channel for additional sales, despite lower unit average selling prices (ASPs).
By Mounting Location: Interior Cameras Race Ahead
Front-facing modules accounted for 34.39% of the market in 2025, underpinning collision avoidance and lane-keeping. Interior cameras are forecast to rise 4.84% annually, the South Korean automotive camera market’s fastest pace, as edge-AI chips from Qualcomm and NXP enable real-time attention tracking without cloud latency. Rear and side units remain standard, but privacy laws require suppliers to anonymize stored biometric data within a specified timeframe, increasing development costs while supporting user acceptance.
Stereo front cameras are set to debut on a luxury SUV to improve depth perception when exiting tunnels, while side-mirror cameras are being upgraded for better low-light accuracy. Rear-view devices face price erosion, as a low-resolution sensor from a major supplier effectively commoditizes entry-level units.
Geography Analysis
The Seoul–Gyeonggi–Incheon corridor dominated demand, supported by major automotive manufacturing plants in the region. Municipal retrofit grants have driven a temporary increase in activity in the area, but this momentum is expected to decline as older fleets complete their upgrades. Busan and Daegu have been slower in adopting ADAS; however, adoption is expected to accelerate with the introduction of self-driving trucks on highways nationwide.
Exports are significantly altering the revenue structure, with domestic manufacturers securing substantial bus orders in international markets and equipping each vehicle with multiple domestically sourced cameras. Industry bodies anticipate substantial growth in automotive camera exports, supported by strong opportunities for Korean suppliers in public transport tenders in emerging markets. As metropolitan Seoul shifts its focus from volume to value, advanced sensors and occupant monitoring systems are contributing significantly to revenue despite accounting for a smaller share of units sold. Additionally, logistics hubs in Gyeonggi, which host a large portion of the nation's truck fleet, are preparing for the impact of the driver-attention mandate.
Competitive Landscape
A few established players, such as Hyundai Mobis, LG Innotek, Samsung Electro-Mechanics, HL Mando Corp, and Continental AG, dominate OEM supply, giving South Korea's automotive camera market a moderately concentrated profile. Their global automotive revenue has grown only modestly, primarily due to pricing pressure from Chinese Tier-2 vendors, which has tightened aftermarket margins. In response, established players are embedding AI directly onto silicon.
Major electronics manufacturers, drawing on their expertise in smartphone optics, secured a leading automaker's surround-view camera pack. This development highlights the growing threat of cross-over competition from the electronics domain. However, stringent supplier-quality requirements—mandating high durability and compliance with established cybersecurity and functional safety standards—effectively restrict price-driven imports from entering OEM channels. The retrofit kits market remains highly competitive.
South Korea Automotive Camera Industry Leaders
-
Continental AG
-
Hyundai Mobis
-
LG Innotek
-
HL Mando Corp
-
Autoliv
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- August 2026: South Korean electronic components manufacturer LG Innotek announced that it will supply automotive camera modules to Zoox, Amazon’s autonomous driving subsidiary, for the mass production of its purpose-built robotaxi fleet. The companies have collaborated since the early stages of the robotaxi’s development. Over the next several years, Zoox will equip its vehicles with LG Innotek’s camera modules, which are already being installed on the robotaxis.
- February 2026: MCNEX and Valens Semiconductor announced the joint development of a new family of high-resolution front and rear automotive cameras. The cameras deliver QHD (2560×1440) video over unshielded twisted pair (UTP) or low-cost coax channels, powered by Valens' VA7000 A-PHY chipsets. The cameras enable OEMs to reduce the cost and complexity of their wiring harness while maintaining high image quality for ADAS and autonomous applications.
South Korea Automotive Camera Market Report Scope
The South Korea automotive camera market report is segmented by vehicle type (passenger vehicle and commercial vehicle), camera type (viewing and sensing), application (ADAS, and more), resolution (up to 1 MP, 2-5 MP, and above 5 MP), sales channel (OEM-fit and aftermarket), mounting location (front, rear, side, and interior/in-cabin). The market forecasts are provided in terms of value (USD).
By Vehicle Type
| Passenger Vehicle | Hatchback |
| Sedan | |
| Sports Utility Vehicle (SUV) | |
| Multi-Purpose Vehicle (MPV) | |
| Commercial Vehicle | Light Commercial Vehicle (LCV) |
| Medium and Heavy Commercial Vehicle (M&HCV) |
By Camera Type
| Viewing Camera |
| Sensing Camera |
By Application
| ADAS |
| Parking and Surround View |
| Driver Monitoring |
By Resolution
| Up to 1 MP |
| 2-5 MP |
| Above 5 MP |
By Sales Channel
| OEM-Fit |
| Aftermarket |
By Mounting Location
| Front |
| Rear |
| Side |
| Interior / In-Cabin |
| By Vehicle Type | Passenger Vehicle | Hatchback |
| Sedan | ||
| Sports Utility Vehicle (SUV) | ||
| Multi-Purpose Vehicle (MPV) | ||
| Commercial Vehicle | Light Commercial Vehicle (LCV) | |
| Medium and Heavy Commercial Vehicle (M&HCV) | ||
| By Camera Type | Viewing Camera | |
| Sensing Camera | ||
| By Application | ADAS | |
| Parking and Surround View | ||
| Driver Monitoring | ||
| By Resolution | Up to 1 MP | |
| 2-5 MP | ||
| Above 5 MP | ||
| By Sales Channel | OEM-Fit | |
| Aftermarket | ||
| By Mounting Location | Front | |
| Rear | ||
| Side | ||
| Interior / In-Cabin | ||
Key Questions Answered in the Report
What is the forecast value of the South Korea automotive camera market in 2031?
The market is expected to reach USD 435.01 million by 2031, rising at a 2.63% CAGR.
Which segment is expanding fastest?
Driver-monitoring cameras are slated for the highest growth at a 5.02% CAGR through 2031 as occupant-attention rules go live.
How will chip shortages affect supply?
Limited wafer capacity at major foundries is extending ISP lead times, and ongoing co-investment agreements in advanced process nodes are expected to ease this pressure in the coming years.
Are privacy regulations slowing adoption of interior cameras?
New rules require on-device processing and 72-hour video deletion, adding cost but also fostering domestic AI innovation that supports continued growth in driver-monitoring cameras.