
South America Manufacturing Inspection Services Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
| Base Year Market Size (2026) | USD 0.55 Billion |
| Market Size (2027) | USD 0.59 Billion |
| Market Size (2032) | USD 0.77 Billion |
| Growth Rate (2027 - 2032) | 5.47 % |
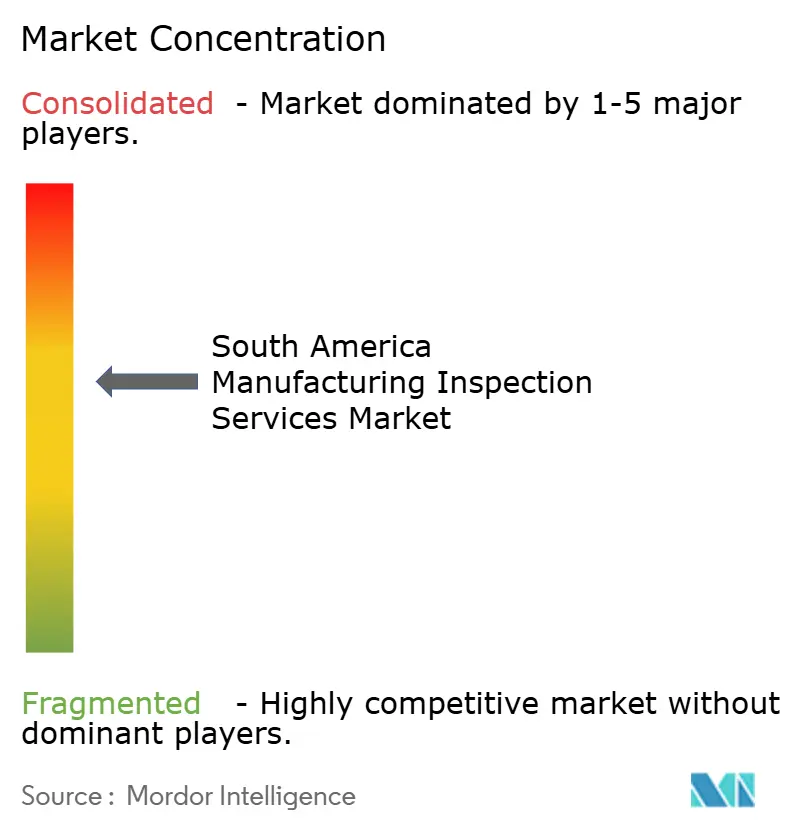
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
South America Manufacturing Inspection Services Market Analysis by Mordor Intelligence
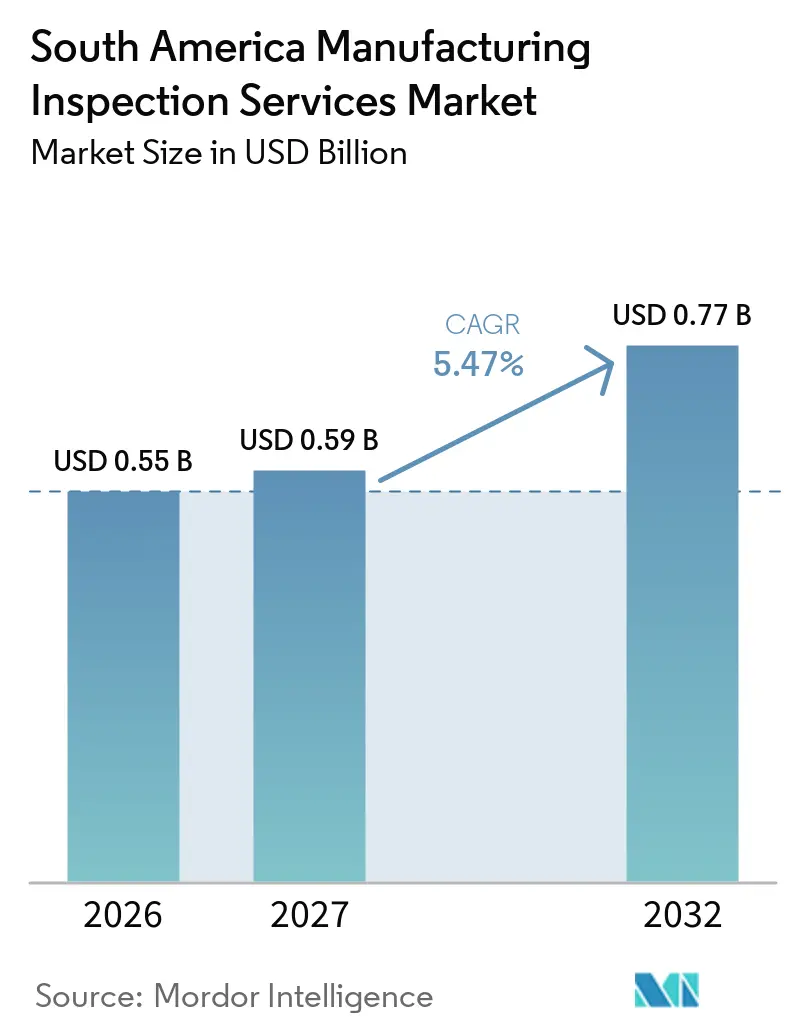
The South America Manufacturing Inspection Services Market size is expected to increase from USD 0.55 billion in 2026 to USD 0.59 billion in 2027 and reach USD 0.77 billion by 2032, growing at a CAGR of 5.47% over 2027-2032.
Mandatory conformity programs in Brazil support recurring inspection work for pressure equipment, calibration laboratories, and production lines. Stronger export activity also increases the need for documented quality checks across supplier networks, particularly for manufacturers supplying automotive, aerospace, energy, and industrial equipment markets. Automotive production, energy equipment maintenance, and semiconductor investment are broadening the range of assets that need inspection. The growing use of automated production systems and advanced manufacturing technologies is also increasing demand for dimensional verification, equipment calibration, non-destructive testing, and process quality audits. Manufacturers are placing greater emphasis on traceable inspection records, consistent testing procedures, and digital documentation to demonstrate compliance with customer specifications and applicable technical standards. The South America manufacturing inspection services market is therefore supported by compliance obligations as well as industrial investment, even when manufacturing output is uneven. Opportunities are also emerging for inspection providers that combine on-site assessments with remote monitoring, digital reporting, and predictive maintenance support, helping industrial customers identify defects earlier and reduce unplanned downtime.
Key Report Takeaways
- By inspection service type, final product and pre-dispatch inspection held 25% of the South America manufacturing inspection services market share in 2026, while quality containment and reinspection services are forecast to grow at a 6.8% CAGR through 2032.
- By manufacturing industry, automotive and automotive components accounted for 20% of the South America manufacturing inspection services market size in 2026, while electronics, electrical equipment, and semiconductors are projected to advance at a 7.2% CAGR through 2032.
- By geography, Brazil held 50% of the South America manufacturing inspection services market share in 2026, while the Rest of South America is forecast to expand at a 7.5% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of South America Manufacturing Inspection Services Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Stricter Safety and Conformity Requirements for Critical Manufacturing Assets | +1.5% | National, Brazil-led, with Argentina and Colombia | Short term (≤ 2 years) |
| Outsourcing of Inspection Capacity by Manufacturers | +1.2% | Brazil core, with spillover to Chile and Colombia | Medium term (2-4 years) |
| Expansion of Automotive, Aerospace, Energy-Equipment and Heavy-Engineering Production | +1% | Brazil, particularly São Paulo and Paraná, and Argentina | Medium term (2-4 years) |
| Export Traceability and Buyer-Mandated Quality Documentation | +0.8% | Brazil, Chile, and Colombia | Short term (≤ 2 years) |
| Digital Inspection, Remote Expertise and AI-Assisted Defect Detection | +0.6% | Brazil, particularly São Paulo and Manaus, and Argentina | Long term (≥ 4 years) |
| Inspection Demand from Aging Plants and Higher Asset-Utilization Targets | +0.4% | Brazil, Argentina, and Colombia | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Stricter Safety and Conformity Requirements for Critical Manufacturing Assets
Brazil strengthened the enforcement framework for compulsory product certification through INMETRO Portaria No. 57/2025. The measure authorizes the RBMLQ-I network to inspect manufacturers and importers that operate under certified product programs. This extends compliance oversight into the supply chains that support manufacturing plants. NR-13 requires periodic inspections of boilers, pressure vessels, industrial piping, and large metal storage tanks, while new tank classification obligations take effect in July 2026. ISO/IEC 17020 remains the accreditation framework for inspection bodies, and Uruguay’s accreditation body joined the ILAC Mutual Recognition Arrangement for this scope in September 2025. These requirements make the South America manufacturing inspection services market less dependent on discretionary capital spending because mandatory inspection cycles continue during slower investment periods.[1]
Outsourcing Inspection Capacity by Manufacturers
Brazilian manufacturing output declined 0.2% in 2025, yet total industrial production rose 0.6% during the year. This combination can encourage manufacturers to convert fixed quality costs into purchased inspection services. Accredited internal teams require calibrated equipment, documented procedures, certified Level III personnel, and audit records, which are difficult for smaller plants to maintain. The South America manufacturing inspection services market can therefore benefit when small and mid-sized manufacturers seek external capacity instead of building complete in-house inspection functions. These conditions also support recurring demand for the South America manufacturing inspection services market across plants with limited internal quality resources.[2]
Expansion of Automotive, Aerospace, Energy-Equipment and Heavy-Engineering Production
Brazil produced 2.644 million vehicles in 2025, and exports rose 32.1% to 528,800 units. Export shipments create additional inspection points for components, subassemblies, and finished products because destination markets apply their own quality requirements. ANFAVEA expects output to reach 2.741 million units in 2026, including production of hybrid and electric vehicles at several domestic factories. Those vehicles require different checks for battery packs, power electronics, and electric motors. Petrobras began a planned shutdown at the Henrique Lage Refinery in September 2025, supported by more than BRL 1 billion (USD 0.18 billion) in investment for regulatory inspections, maintenance, and projects. CNEN also disclosed BRL 750 million (USD 135.5 million) in modernization and maintenance investment for Angra 1 in 2025, linking inspection demand to asset integrity and safety obligations.[3]
Export Traceability and Buyer-Mandated Quality Documentation
The WTO recorded more than 5,200 Technical Barriers to Trade notifications in 2025, the highest annual total to date. Quality requirements were the most frequently stated objective, appearing in 1,598 notifications. Brazil was among the 3 most active notification submitters, showing its greater engagement with product rules in export markets. Export quality certificates for agricultural and food products create a need for documented inspection evidence at departure. Automotive buyer agreements can also require conformance with IATF 16949 and VDA-related processes, which extends audit demands through Tier-2 and Tier-3 suppliers. Each export contract can produce recurring verification work because documents must accompany shipments and be updated following process changes, which supports the South America manufacturing inspection services market.
Restraints Impact Analysis of South America Manufacturing Inspection Services Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Shortage of Certified Level III and Advanced Metrology Personnel | -1% | Regional, Brazil, Argentina, Colombia, and Chile | Long term (≥ 4 years) |
| High Capital Cost of Digital Radiography, CT and Automated Inspection Systems | -0.8% | National, all of South America | Medium term (2-4 years) |
| Fragmented Accreditation, Standards and Procurement Requirements Across Countries | -0.6% | Cross-border, Mercosur region | Medium term (2-4 years) |
| Exchange-Rate Volatility and Uneven Manufacturing Investment Cycles | -0.5% | Argentina, Brazil, and Colombia | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Shortage of Certified Level III and Advanced Metrology Personnel
ISO 9712 certification requires non-destructive testing personnel to demonstrate training, industrial experience, and examination performance. Level III is the highest certification tier and includes responsibility for developing procedures and approving results. Building the regional pipeline remains difficult because younger professionals have limited awareness of non-destructive testing careers. Qualification requirements also limit the pool of personnel available for demanding contracts. Recognition differences between national practices can reduce the movement of qualified personnel across borders. Smaller operators face the greatest constraint because they cannot easily fund dedicated training programs, leaving complex work more accessible to large accredited providers.
High Capital Cost of Digital Radiography, CT and Automated Inspection Systems
Digital radiography, phased-array ultrasonic testing, full matrix capture, and industrial computed tomography can expand the capability of inspection providers. Their purchase, calibration, and recertification costs remain difficult for many regional firms to absorb. NR-13 inspection of pressure vessels and piping can require thickness measurement, visual testing, non-destructive testing, and, in higher-risk cases, hydrostatic and tightness tests. ISO/IEC 17020 accreditation requires documented equipment traceability, calibration records, and method-specific competence. These requirements frequently depend on access to instruments validated under ISO/IEC 17025 laboratory standards. The South America manufacturing inspection services market may therefore remain divided between providers that offer advanced methods and smaller firms that continue to focus on conventional visual or manual services.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
South America Manufacturing Inspection Services Market Segment Analysis
By Inspection Service Type:
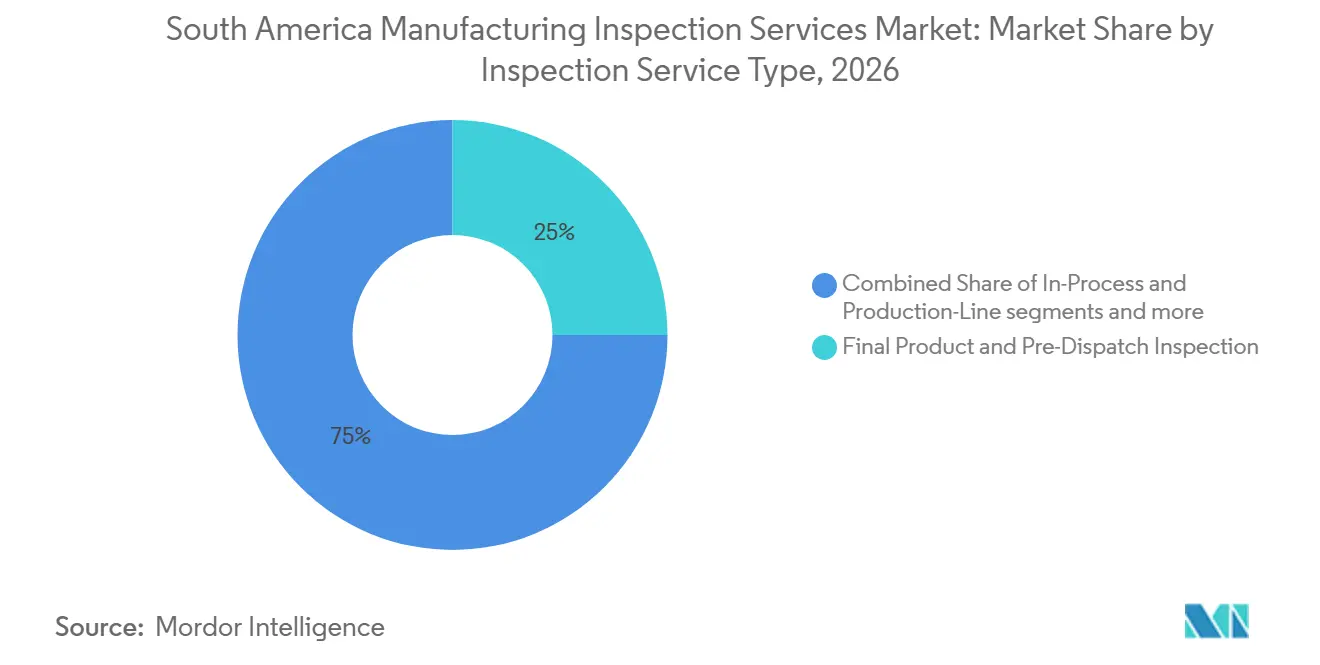
Documentation Requirements Support Pre-Dispatch DemandFinal Product and Pre-Dispatch Inspection held 25% of the South America manufacturing inspection services market share in 2026, making it the largest service type. Purchase orders and export letters of credit can require a certificate from an accredited body before payment is released. This requirement gives the service a clear role at the point of shipment. Pre-Production Material and Component Inspection is used at the start of the inspection cycle. Manufacturers working under ISO 9001 or IATF 16949 requirements are shifting some controls to incoming materials so that they can reduce rework later in the process.
Quality Containment and Reinspection Services is the fastest-growing service type, with the South America manufacturing inspection services market size for this service projected to rise at a 6.8% CAGR from 2027 to 2032. A product failure at a customer site can cause production stoppages, recalls, and contract penalties that exceed a supplier’s annual inspection budget. Automotive suppliers can be required to provide corrective-action and reinspection evidence before they resume deliveries. This creates a defined service event following a quality escape. The service often gains importance during supply-chain disruption, when mixed-origin components and expedited production can raise first-pass defect rates. Its growth is supported by the same supply-chain complexity that can place pressure on conventional inspection services.

By Manufacturing Industry:
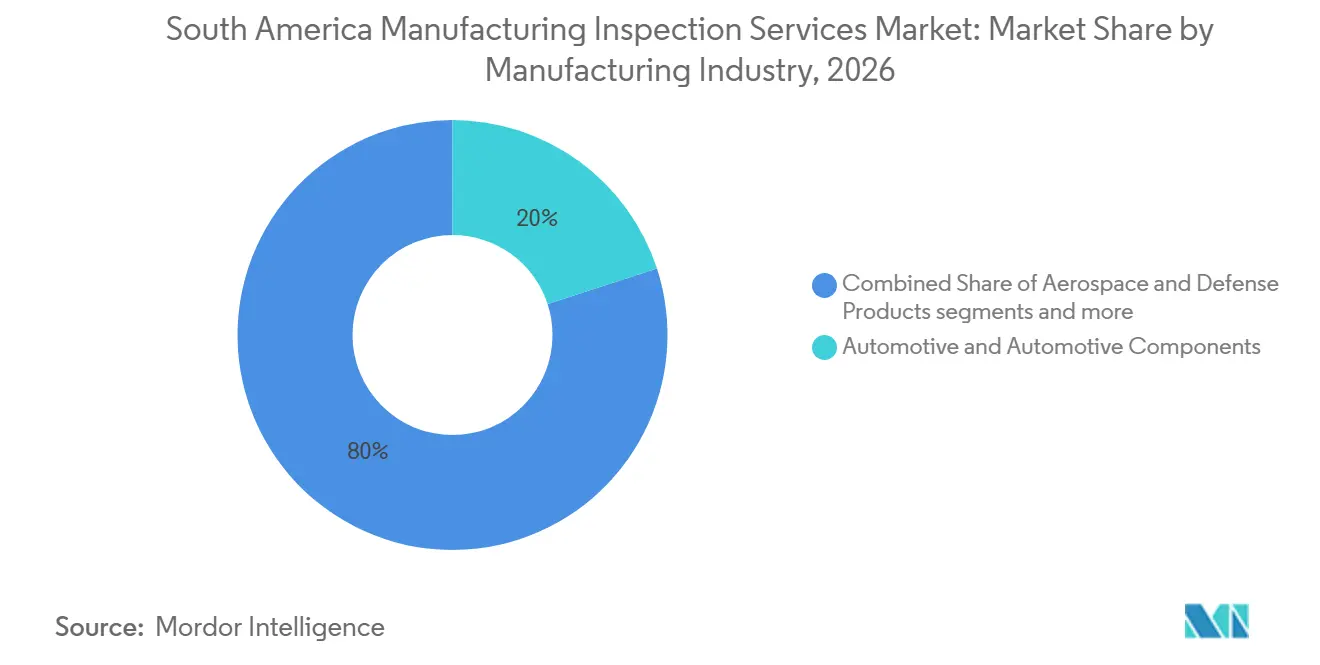
Automotive Scale and Electronics Investment Drive DemandAutomotive and Automotive Components accounted for 20% of the South America manufacturing inspection services market share in 2026, the largest industry vertical. Brazil’s 2.644 million vehicle output and 528,800 exported units in 2025 generate work in component qualification, weld integrity, dimensional metrology, and final vehicle checks. These activities extend across Tier-1 and Tier-2 supplier plants in the São Paulo and Paraná industrial belts. Industrial Machinery, Equipment, and Fabricated Metals is another large user of services because heavy plants operate periodic maintenance and turnaround programs. Pharmaceuticals, Medical Devices, and Life Sciences Products require inspection during production and finished-product release under Good Manufacturing Practice requirements.
Food and Beverage Products, Chemicals and Plastics, Textiles, Consumer Products, Building Materials, and Packaging use inspection services that reflect applicable technical standards. In Brazil, these requirements may be linked to ABNT or INMETRO, while Argentina, Chile, and Colombia use their own national frameworks. Electronics, Electrical Equipment and Semiconductors is forecast to grow at a 7.2% CAGR through 2032. Brazil’s semiconductor revenue was estimated at USD 1.2 billion in 2025. Brasil Semicon provides BRL 24.8 billion (USD 4.48 billion) for semiconductor research, production capacity, and factory development through 2035. New facilities need first-article, in-process, and automated optical inspection as they begin production. High component density, solder-joint integrity, and printed circuit board trace quality make this vertical more dependent on specialized methods than many conventional manufacturing activities.
Geography Analysis
Brazil Manufacturing Inspection Services Market
Brazil held 50% of the South America manufacturing inspection services market share in 2026. Its position reflects the concentration of automotive, chemical, food, pharmaceutical, and energy-equipment production in the São Paulo, Minas Gerais, and Paraná industrial corridor. Seven Brazilian states increased industrial production faster than the national 0.6% average in 2025. Espírito Santo rose 11.6%, Rio de Janeiro increased 5.1%, and Santa Catarina grew 3.2%, which broadens demand beyond the traditional São Paulo hub. Its accredited infrastructure and compulsory regulatory framework support formal service delivery.
Brazil and Chile Manufacturing Inspection Services Market
INMETRO recognition and ISO/IEC 17020 scope create an important entry condition for bodies serving compulsory product categories in Brazil. ANFAVEA’s projected 2.741 million vehicle output for 2026 and the introduction of hybrid and electric vehicle production can increase the need for battery and power-electronics qualification. Chile is shaped by mining-related manufacturing, including fabricated steel structures, process vessels, and conveyor systems supporting copper and lithium activity.
South America Manufacturing Inspection Services Market
Colombia has demand from a wider manufacturing base, food, pharmaceuticals, and energy-sector operations that require advanced inspection. The rest of South America is the fastest-growing geographic group, with the South America manufacturing inspection services market size expected to grow at a 7.5% CAGR from 2027 to 2032. Mining and energy investment in Peru, Bolivia, Ecuador, and Paraguay is increasing production of processing equipment and renewable-energy components closer to extraction sites. Uruguay’s inclusion in the ILAC Mutual Recognition Arrangement strengthens international recognition for inspection accreditation in the region. Mobile teams, remote expert support, digital reporting, and portable equipment are important for reaching isolated Tier-2 manufacturing facilities without constructing fixed laboratories.
Competitive Landscape
The South America manufacturing inspection services market exhibits a medium level of market concentration. These firms compete through broad accreditation coverage, deep technical scope, and the ability to manage multi-country contracts. Their customers often want one accountable provider across Brazil, Argentina, Chile, and Colombia. ISO/IEC 17020 and ISO/IEC 17025 requirements under INMETRO reinforce this advantage because establishing accredited scope requires time, equipment, and formal competence. Regional specialists remain important for price-sensitive clients and for remote locations where global field coverage is less extensive.
Intertek acquired TESIS in Brazil in 2025, adding building-products testing and assurance services in the country. In 2026, Intertek ETL completed its acquisition of QTEST in Colombia to extend its electrical product testing and certification capability in the Andean region. Bureau Veritas acquired Lab System in Brazil, a consumer-products testing laboratory focused on toys and hardlines. It also acquired GeoAssay in Chile, bringing mineral analysis laboratories and a 264-person workforce into its network. These transactions extend regional service coverage and reduce the pool of independent mid-tier acquisition targets.
More than 20 Brazilian and regional specialists provide non-destructive testing, calibration, and process-audit services, particularly for small and mid-sized manufacturers. Their local relationships and knowledge of regional operations can be valuable outside the main industrial corridors. Mobile digital inspection, AI-enabled defect detection for smaller electronics assemblers, and cross-border accreditation support are practical areas for service development. The end of merger discussions between SGS and Bureau Veritas in January 2025 preserved separate competition between the 2 global providers.
South America Manufacturing Inspection Services Industry Leaders
-
SGS S.A.
-
Bureau Veritas S.A.
-
Intertek Group plc
-
TÜV Rheinland AG
-
Applus+ Services S.A.
- *Disclaimer: Major Players sorted in no particular order
South America Manufacturing Inspection Services Market Companies Covered in this Report
- SGS S.A.
- Bureau Veritas S.A.
- Intertek Group plc
- TÜV Rheinland AG
- Applus+ Services S.A.
- TÜV SÜD AG
- DNV AS
- UL LLC
- ALS Limited
- Eurofins Scientific SE
- DEKRA SE
- LRQA Limited
- ABS Group of Companies, Inc.
- RINA S.p.A.
- Kiwa N.V.
- Cotecna Inspection SA
- Control Union Certifications B.V.
- Mérieux NutriSciences Corporation
- OCA Global SA
- Tecnitest Engenharia de Ensaios Não Destrutivos LTDA
- Contronics Engenharia de Inspeções LTDA
- NDT do Brasil Serviços de Inspeção LTDA
- FB Ensaios Não Destrutivos LTDA
- L9 Inspeções e Ensaios LTDA
- Inspectra Serviços de Inspeção Industrial LTDA
- Qualilab Inspeções Industriais LTDA
- Oceânica Engenharia e Consultoria Submarina S.A.
- Sudamerica Inspection Services
- Waygate Technologies
- Evident Scientific
Recent Industry Developments in South America Manufacturing Inspection Services Market
- October 2026: Intertek ETL completed the acquisition of QTEST, a Colombian market-leading electrical product testing and certification business, expanding the group's Latin American testing footprint into Colombia's electrical sector and accelerating its position across the Andean sub-region. The acquisition is aligned with Intertek's deepening presence in Latin America's high-growth ATIC (Assurance, Testing, Inspection and Certification) markets, following prior investments in Brazil.
- November 2025: Applus+ launched a continuous wind tower quality inspection and structural integrity program at the Polo Industrial de Camaçari, Bahia, Brazil, deploying phased-array UT, magnetic particle testing, and liquid penetrant testing across the full production schedule. The project ensures conformance with technical specifications and regulatory requirements of Brazil's renewable energy sector on an ongoing basis.
- September 2025: Petrobras's Henrique Lage Refinery (REVAP) in São José dos Campos commenced a planned maintenance shutdown, mobilising more than 5,000 workers with an investment exceeding BRL 1 billion (USD 0.18 billion), encompassing NR-13 regulatory inspections, preventive and corrective maintenance, and strategic upgrade projects for diesel S10 production capacity and energy efficiency improvement.
- September 2025: Applus+ signed a 24-month nationwide contract covering 124 operational and storage units of a leading Brazilian agro-industrial group, performing conventional and advanced NDT, NR-13 compliance inspections, integrity engineering services, and strategic asset database development. Services include phased array, MFL (Magnetic Flux Leakage), digital radiography, and videoscopy.
South America Manufacturing Inspection Services Market Report Scope
The South America Manufacturing Inspection Services Market Report is Segmented by Inspection Service Type (Pre-Production Material and Component Inspection, First-Article and Initial Production Inspection, and More), by Manufacturing Industry (Automotive and Automotive Components, Aerospace and Defense Products, and More), and by Geography (Brazil, Argentina, and More). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Pre-Production Material and Component Inspection |
| First-Article and Initial Production Inspection |
| In-Process and Production-Line Inspection |
| Final Product and Pre-Dispatch Inspection |
| Manufacturing Process and Production Surveillance Inspection |
| Quality Containment and Reinspection Services |
| Automotive and Automotive Components |
| Aerospace and Defense Products |
| Electronics, Electrical Equipment and Semiconductors |
| Industrial Machinery, Equipment, and Fabricated Metals |
| Chemicals, Plastics and Industrial Materials |
| Food and Beverage Products |
| Pharmaceuticals, Medical Devices and Life Sciences Products |
| Textiles, Apparel, Footwear and Accessories |
| Furniture, Homeware, Toys and Other Consumer Products |
| Building Materials and Construction Products |
| Packaging, Paper and Printed Products |
| Other Manufactured Products |
| Brazil |
| Argentina |
| Chile |
| Colombia |
| Rest of South America |
| By Inspection Service Type | Pre-Production Material and Component Inspection |
| First-Article and Initial Production Inspection | |
| In-Process and Production-Line Inspection | |
| Final Product and Pre-Dispatch Inspection | |
| Manufacturing Process and Production Surveillance Inspection | |
| Quality Containment and Reinspection Services | |
| By Manufacturing Industry | Automotive and Automotive Components |
| Aerospace and Defense Products | |
| Electronics, Electrical Equipment and Semiconductors | |
| Industrial Machinery, Equipment, and Fabricated Metals | |
| Chemicals, Plastics and Industrial Materials | |
| Food and Beverage Products | |
| Pharmaceuticals, Medical Devices and Life Sciences Products | |
| Textiles, Apparel, Footwear and Accessories | |
| Furniture, Homeware, Toys and Other Consumer Products | |
| Building Materials and Construction Products | |
| Packaging, Paper and Printed Products | |
| Other Manufactured Products | |
| By Geography | Brazil |
| Argentina | |
| Chile | |
| Colombia | |
| Rest of South America |
Key Questions Answered in the Report
What is the forecast growth rate for manufacturing inspection services in South America?
The South America manufacturing inspection services market is forecast to grow at a 5.47% CAGR from 2027 to 2032, increasing from USD 0.55 billion in 2026 to USD 0.77 billion by 2032.
Which inspection service has the largest share in South America?
Final Product and Pre-Dispatch Inspection leads with a 25% share in 2026 because buyers and lenders often require an accredited certificate before shipment or payment.
Which manufacturing sector will grow fastest for inspection providers?
Electronics, Electrical Equipment and Semiconductors is projected to grow at a 7.2% CAGR through 2032 as new facilities need automated and in-process controls.
Why does Brazil lead regional demand for manufacturing inspections?
Brazil held a 50% share in 2026 due to its industrial scale, compulsory conformity rules, accredited infrastructure, and concentration of automotive and energy-equipment assets.
What limits the expansion of inspection providers in South America?
Limited Level III personnel and the high cost of advanced radiography, automated testing, and calibrated equipment restrict the capacity of smaller firms.
Which countries outside Brazil offer the strongest growth potential?
The rest of South America is expected to grow at a 7.5% CAGR through 2032, supported by mining, energy, and renewable-equipment activity in Peru, Bolivia, Ecuador, and Paraguay.