
Propylene Glycol Alginate Market Size and Share
Market Overview
| Study Period | 2021 - 2031 |
|---|---|
| Market Size (2026) | USD 383.17 Billion |
| Market Size (2031) | USD 508.19 Billion |
| Growth Rate (2026 - 2031) | 5.81 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | Asia-Pacific |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Propylene Glycol Alginate Market Analysis by Mordor Intelligence
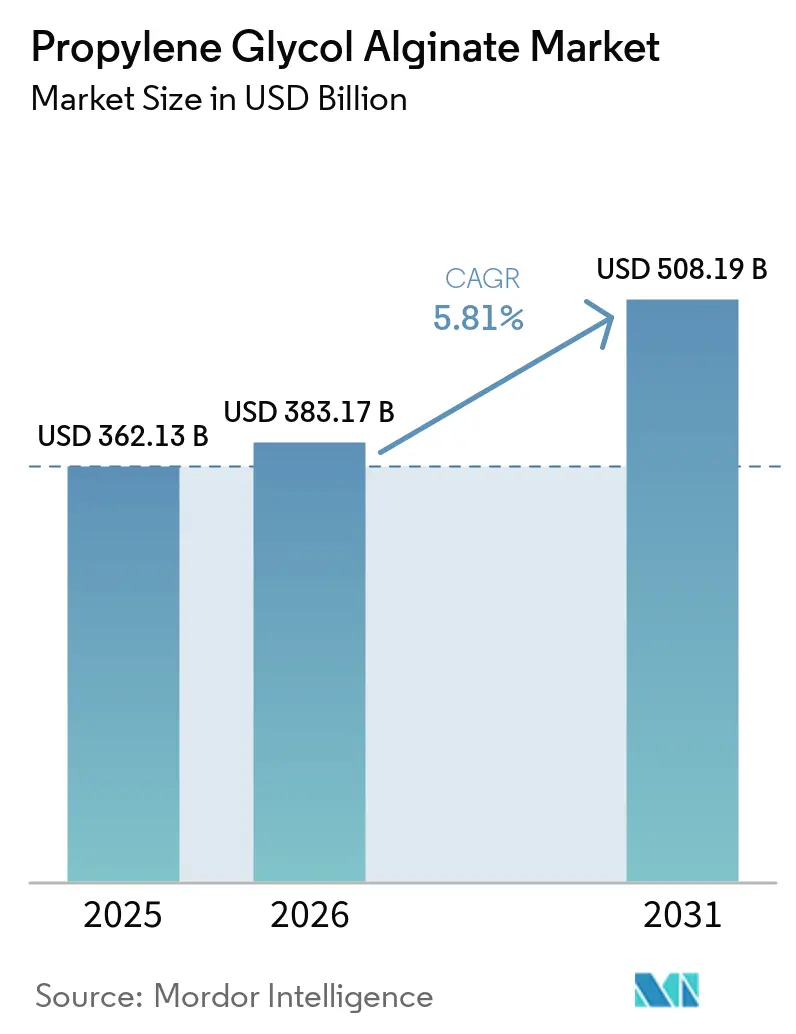
The Propylene Glycol Alginate Market size was valued at USD 362.13 billion in 2025 and is estimated to grow from USD 383.17 billion in 2026 to reach USD 508.19 billion by 2031, at a CAGR of 5.81% during the forecast period (2026-2031). The propylene glycol alginate market is supported by the material’s ability to retain viscosity and stabilize emulsions in acidic systems with a pH of 3–5, where sodium alginate and many other polysaccharide thickeners can precipitate. This capability supports its use in acidified dairy beverages, fruit juice emulsions, beer foam, and low-pH dressings. Its recognition as International Numbering System (INS) 405 under the Codex General Standard for Food Additives gives food formulators a defined international reference point for permitted use. The propylene glycol alginate market also benefits from the U.S. authorization of the ingredient as a stabilizer, emulsifier, and thickener in specified food uses. Suppliers are responding through formulation support, higher-purity grades, and wider hydrocolloid portfolios, while restricted brown-seaweed feedstock and differing national requirements continue to shape investment decisions.
Key Report Takeaways
- By grade, food grade held 58.32% of the propylene glycol alginate market share in 2025, while pharmaceutical grade is projected to advance at a 6.16% CAGR through 2031.
- By form, powder held 72.74% of the propylene glycol alginate market share in 2025 and is projected to advance at a 6.34% CAGR through 2031.
- By application, stabilizers held 28.51% of the propylene glycol alginate market share in 2025, while thickeners are projected to advance at a 6.42% CAGR through 2031.
- By end-use, food and beverage held 52.17% of the propylene glycol alginate market share in 2025, while pharmaceuticals are projected to advance at a 6.77% CAGR through 2031.
- By geography, Asia-Pacific held 37.23% of the propylene glycol alginate market share in 2025 and is projected to advance at a 6.26% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Propylene Glycol Alginate Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Clean-Label and Natural Ingredient Reformulation | +1.5% | Global | Short term (≤ 2 years) |
| Expansion of Plant-Based and Functional Beverages | +1.2% | APAC core, North America & EU | Short term (≤ 2 years) |
| Growth in Pharmaceutical Grade Excipient Applications | +1.0% | North America & EU | Medium term (2-4 years) |
| Rising Use in Dairy Alternatives and Acidic Beverage Systems | +0.8% | APAC core, spillover to North America | Short term (≤ 2 years) |
| Seaweed-Aquaculture Integration for Supply Security | +0.4% | APAC core, spillover to South America | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Clean-Label and Natural Ingredient Reformulation
The propylene glycol alginate market is gaining support as food producers review formulations that rely on synthetic emulsifiers such as propylene glycol esters of fatty acids and polysorbate 80. Propylene glycol alginate is derived from seaweed, although it remains a chemically modified polysaccharide classified as INS 405 and E405. Its thickening, emulsifying, and stabilizing functions can allow a manufacturer to use fewer ingredients in one formulation. This matters when companies seek shorter ingredient lists without losing texture or stability in finished products. The propylene glycol alginate market is also supported by the established food-additive framework for INS 405 in Codex standards[1]. European food producers continue to work within the requirements of Regulation (EC) No 1333/2008 when they assess the use of permitted additives.
Expansion of Plant-Based and Functional Beverages
Propylene glycol alginate can stabilize plant proteins in acidified plant milks and fermented oat beverages, where pea and soy proteins can separate at low pH. This behavior gives the propylene glycol alginate market a defined role in beverages that require both suspension and acidity tolerance. It can also stabilize oil-based flavors and nutrients used in fortified juices, sports drinks, and energy beverages. These uses extend the material beyond conventional beverage thickening and support demand for qualified beverage grades. KIMICA identifies acid stability and emulsification among the functional properties of its propylene glycol alginate products. Fermented and adaptogenic beverages in Asia-Pacific provide an additional outlet because many of these products operate at lower pH levels.
Growth in Pharmaceutical Grade Excipient Applications
The propylene glycol alginate market is moving beyond a limited stabilizer role in pharmaceutical formulations. Drug producers are using propylene glycol alginate in controlled-release tablets, buccal films, suspension formulations, enteric coatings, and topical gels. Pharmaceutical production requires controlled endotoxin levels, heavy-metal limits, and consistent viscosity grades. These requirements favor suppliers that have appropriate quality systems and can complete lengthy customer qualification processes. Shandong Jiejing Group Corporation states that it holds ISO 9001, ISO 14001, and national pharmaceutical Good Manufacturing Practice certification. The U.S. food regulation also defines authorized uses for propylene glycol alginate as a stabilizer, emulsifier, and thickener, reinforcing the material’s established safety and functional position[2].
Rising Use in Dairy Alternatives and Acidic Beverage Systems
Plant proteins can aggregate in the acidic conditions used for fermented and acidified dairy-style products. Propylene glycol alginate remains functional in these systems and can stabilize protein particles in almond milks, drinking yogurts, and fermented soy beverages. This technical requirement narrows the set of suitable substitutes and supports a premium position for propylene glycol alginate in selected applications. A 2025 review describes the compatibility of propylene glycol alginate with proteins, including pea, soy, and casein, and identifies protein-propylene glycol alginate composite systems as a major application area. The propylene glycol alginate market, therefore, has a direct link to the development of plant-based dairy and acidic beverage formulations. Chinese, Japanese, and South Korean producers of fermented plant beverages add to regional demand for acid-stable ingredients.
Restraints Impact Analysis of Propylene Glycol Alginate Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Seaweed Availability and Climate-Linked Raw-Material Volatility | -1.2% | Global, epicenter in APAC & South America | Medium term (2-4 years) |
| Competition from Xanthan Gum, Carrageenan, Guar Gum and Modified Starch | -0.9% | Global | Medium term (2-4 years) |
| Divergent International Safety and Labeling Requirements | -0.4% | North America & EU | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Seaweed Availability and Climate-Linked Raw-Material Volatility
Propylene glycol alginate production depends on brown seaweed, including Laminaria hyperborea, Macrocystis pyrifera, and Ascophyllum nodosum. Commercial sourcing is concentrated in Chile, China, Norway, and Japan, which limits the number of meaningful feedstock regions. Changes in ocean conditions can reduce biomass yields in Chilean Laminaria beds and Norwegian Ascophyllum populations. Seasonal harvesting windows also limit production scheduling for higher-quality raw material. The propylene glycol alginate market can face supply disruption when one important harvesting region has an adverse season. China’s role in seaweed-to-alginate processing can add supply risk for producers that purchase Chinese alginic acid before undertaking their own esterification.
Competition from Xanthan Gum, Carrageenan, Guar Gum and Modified Starch
Xanthan gum can provide thickening and suspension performance at lower prices in neutral-pH uses such as soups, sauces, and dairy dressings. Guar gum and modified starch also compete in cost-sensitive applications that do not require strong acid stability. A 2025 study found that physically treated starch blends can function as xanthan gum substitutes in specific thickener applications. The propylene glycol alginate market is consequently more dependent on acidic applications in which its performance is clearly differentiated. This dependence can concentrate revenue in a narrower set of beverage, dairy-alternative, and dressing applications. Suppliers need application-specific support to retain customers that may otherwise select a lower-cost texturizer for neutral-pH products.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Propylene Glycol Alginate Market Segment Analysis
By Grade:
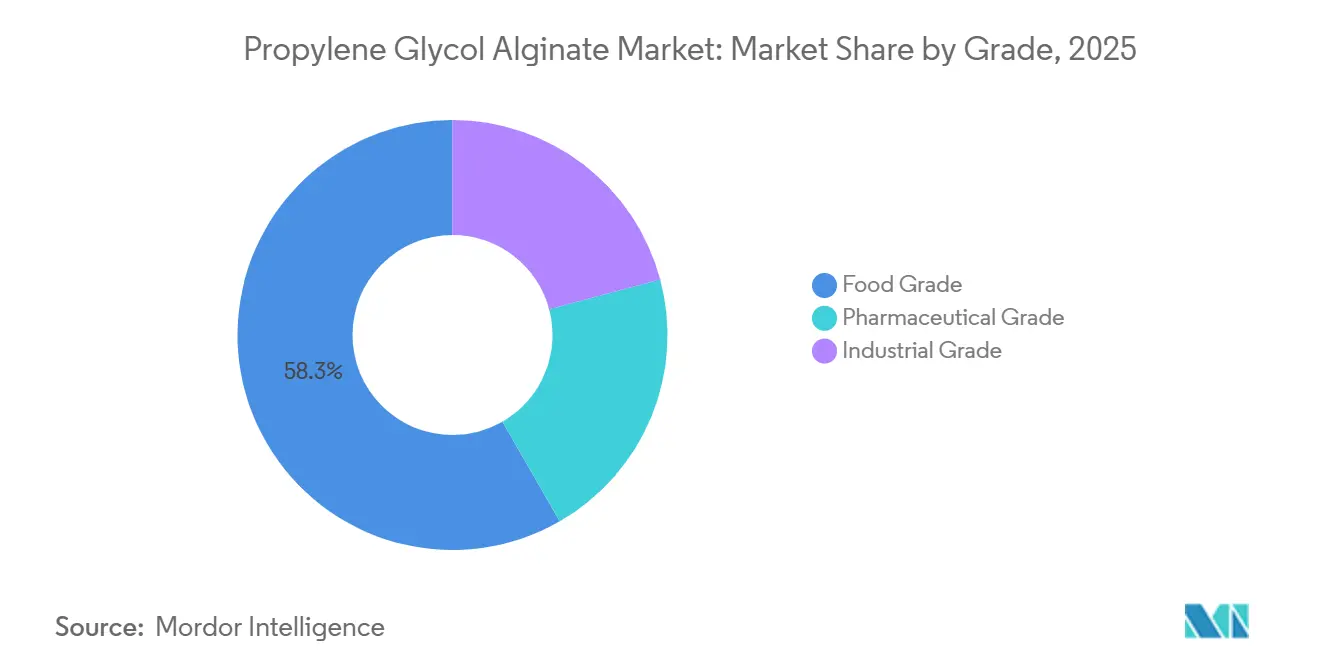
Food Grade Leads Demand, While Pharmaceutical Grade AcceleratesFood grade held 58.32% of the propylene glycol alginate market size in 2025 because it is used across beverages, dairy products, bakery products, and condiments. The grade has a long-established role in Asia-Pacific and Europe. Codex lists INS 405 in the General Standard for Food Additives, supporting its use across authorized food categories. Industrial grade serves textile printing and dyeing applications, particularly in China. Shandong Jiejing Group Corporation maintains food, pharmaceutical, and industrial alginate capabilities. As Chinese producers upgrade facilities for pharmaceutical production, the supply available solely for food grade products may become more limited.
Pharmaceutical grade is projected to advance at a 6.16% CAGR through 2031. Drug manufacturers use this material in controlled-release oral dosage forms, enteric coatings, liquid-medication suspension stabilizers, and topical gel formulations. This grade requires tighter control of endotoxins, heavy metals, and viscosity than conventional food applications. It also requires dedicated manufacturing equipment and third-party audits aligned with Good Manufacturing Practice requirements. KIMICA introduced a dedicated pharmaceutical grade propylene glycol alginate line in Q1 2025 for controlled-release drug formulation and international pharmaceutical applications. Shandong Jiejing Group Corporation has national pharmaceutical Good Manufacturing Practice certification, which supports its position in this segment.

By Form:
Powder Leads Both Market Share and GrowthPowder held 72.74% of the propylene glycol alginate market share in 2025 and is projected to advance at a 6.34% CAGR through 2031. Food and pharmaceutical manufacturers use powder because it supports precise metering in continuous production. It also fits dry-blended premixes and can be stored at ambient conditions. These features reduce handling and logistics requirements compared with liquid products. The 2025 review of propylene glycol alginate composites identifies compatibility with protein matrices through co-precipitation and dry blending as an important processing advantage. Powder also suits oral dosage forms because it is compatible with granulation and tableting operations.
Liquid propylene glycol alginate serves beverage and sauce applications that value rapid dissolution and ready-to-use handling. Craft food producers and food-service operators can use it without dedicated hydration equipment. This convenience can justify a higher cost in smaller batches or time-sensitive production processes. Contract development and manufacturing organizations are evaluating liquid grades for parenteral and topical work because pre-solubilized inputs can simplify processing. The 2025 review also describes propylene glycol alginate nanoparticle systems made through antisolvent co-precipitation, a method suited to liquid-phase processing. These uses give liquid products a specialized role, even though powder remains the standard form for larger production volumes.
By Application:
Thickeners Outpace Stabilizers in Growth RateStabilizers held 28.51% of the propylene glycol alginate market size in 2025. Propylene glycol alginate stabilizes oil-in-water beverage emulsions and helps suspend proteins in dairy drinks. Established commercial formulations can create continuity in demand because manufacturers know how propylene glycol alginate performs at the production scale. Emulsifiers use their esterified structure to stabilize oil-water interfaces in dressings, mayonnaise-style products, and nutritional emulsions. Gelling and foaming agents serve alcoholic-beverage foam systems and dairy-style desserts. Protein-propylene glycol alginate composites also support active-ingredient encapsulation, Pickering emulsion stabilization, and controlled-release delivery across several application areas.
Thickeners are projected to advance at a 6.42% CAGR through 2031. Plant-based dairy and functional beverage producers need viscosity control that remains stable at low pH. This requirement differs from general-purpose thickening because it is tied to a narrow operating environment. KIMICA states that low usage levels of 0.002%–0.005% can support persistent beer foam. This use demonstrates the material’s role in applications that require precise functional performance rather than bulk viscosity.
By End-Use:
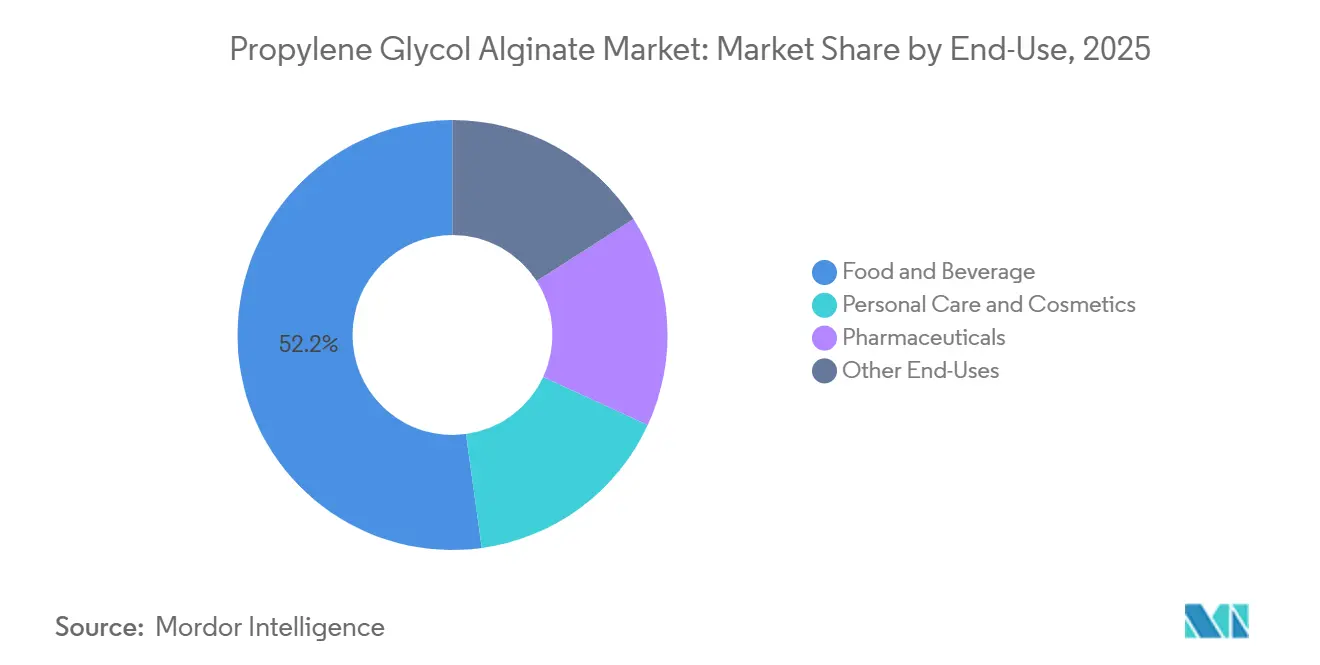
Food and Beverage Anchors Revenue, While Pharmaceuticals Command GrowthFood and beverage held 52.17% of the propylene glycol alginate market share in 2025. It includes acidified beverages, dairy products, bakery items, and condiments that are difficult to reformulate without changing functional performance. U.S. rules authorize the propylene glycol alginate in specified uses that include baked goods, fats and oils, gelatins and puddings, condiments, and sweet sauces. Personal care and cosmetics use propylene glycol alginate for film formation and emulsification in low-pH serums and lotions. This category could draw more attention when suppliers invest in cosmetic grade qualification.
Pharmaceuticals are projected to advance at a 6.77% CAGR through 2031. Producers are seeking this category because pharmaceutical grade propylene glycol alginate has a higher pricing than food grade material. It is used as a suspension stabilizer in oral liquids and a film former in enteric coatings. Wound-care hydrogels and buccal drug delivery offer additional uses outside traditional oral solid dosage forms. Qualification requirements from the United States Pharmacopeia and European Pharmacopoeia set demanding quality expectations for excipient suppliers. The propylene glycol alginate industry is therefore placing greater value on certification, repeatability, and validated supply.
Geography Analysis
APAC Propylene Glycol Alginate Market
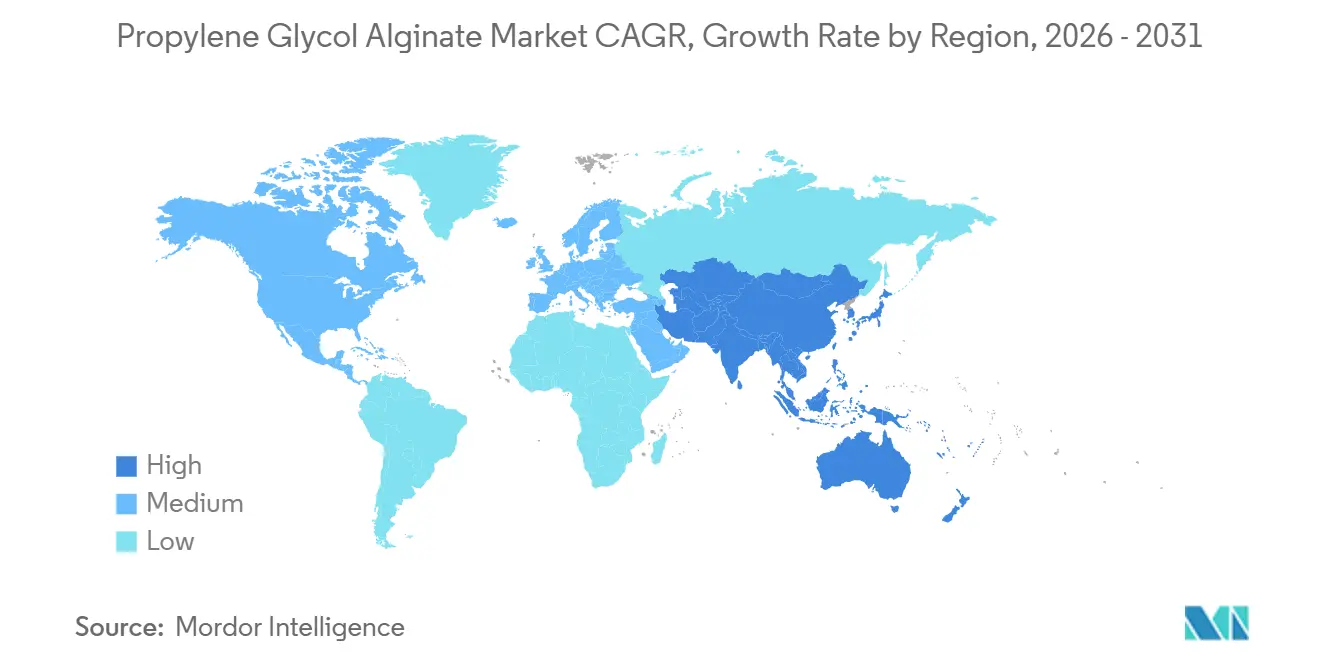
Asia-Pacific held 37.23% of the propylene glycol alginate market share in 2025 and is projected to advance at a 6.26% CAGR through 2031. China leads the production of seaweed through integrated seaweed cultivation, alginate extraction, and esterification. Qingdao Bright Moon Seaweed Group Co., Ltd. describes its operations as covering seaweed-based products and related processing capabilities. Integrated production supports the cost-effective supply of food grade and industrial grade products. China’s food authorization framework and pharmaceutical Good Manufacturing Practice requirements allow qualified producers to address separate food and pharmaceutical demand. Japan contributes through KIMICA’s propylene glycol alginate capabilities, while India’s generics sector is creating demand for pharmaceutical grade excipients.
North America and Europe Propylene Glycol Alginate Market
North America has demand from large food-processing operations and the broad U.S. authorization for propylene glycol alginate in food categories. Beverage and dairy producers are reviewing emulsifier systems as they introduce products with shorter ingredient lists. Functional beverage development also supports the use of acid-stable stabilizers. Canada and Mexico add demand through supply chains linked to the wider North American food sector. Europe includes major food-processing demand in Germany, the United Kingdom, and France. The region applies the food-additive requirements for E405 under its regulatory system, while formulators rely on established use in beverage and dairy products.
MEA and South America Propylene Glycol Alginate Market
South America is important both as a raw material source and as a consumption region for the propylene glycol alginate market. Chile supplies Laminaria and Macrocystis that are used as alginate feedstock for global processors. Brazil’s food processing and dairy-alternative activities create a domestic outlet for stabilizers. Argentina and other South American countries add demand through food and beverage manufacturing. The Middle East and Africa remain smaller by revenue, but packaged-food production and pharmaceutical manufacturing support long-term opportunity. Saudi Arabia and South Africa are important demand centers, while the region relies on imported propylene glycol alginate because commercial seaweed cultivation infrastructure is limited.
Competitive Landscape
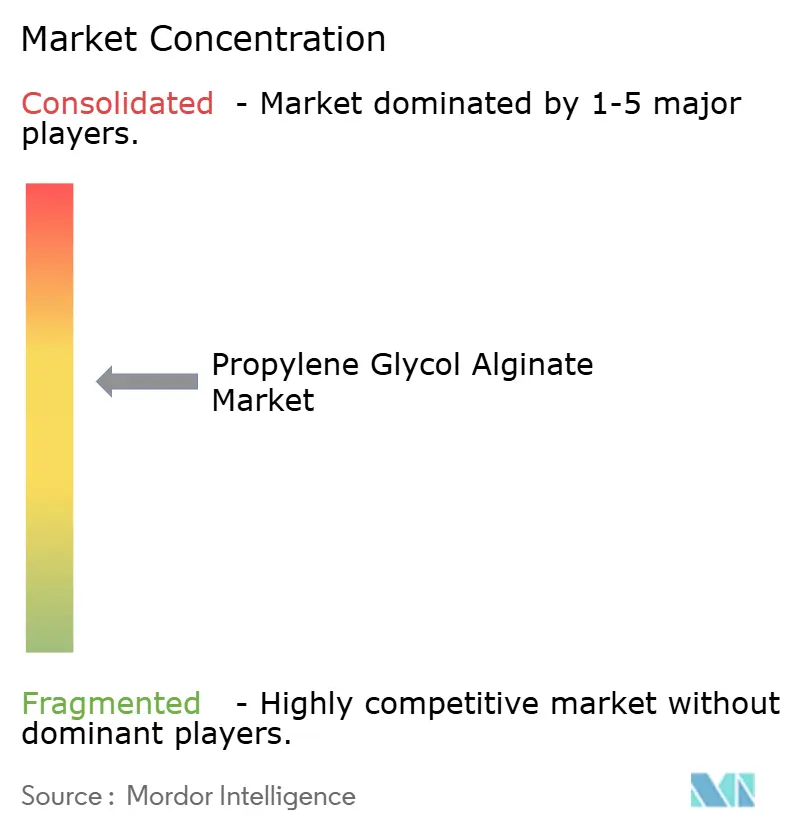
The propylene glycol alginate market is moderately concentrated, with the top five players including KIMICA, Shandong Jiejing Group Corporation, Cargill, Incorporated, CP Kelco U.S., Inc., and FMC Corporation. Qingdao Bright Moon Seaweed Group Co., Ltd., Shandong Jiejing Group Corporation, and IRO Alginate Industry Co., Ltd. benefit from Chinese seaweed supply chains and integrated processing. These companies can supply food grade and industrial grade propylene glycol alginate at scale. Cargill, Incorporated, CP Kelco U.S., Inc., Kerry Group, and Ashland use formulation support, distribution reach, and application expertise to compete with cost-focused suppliers. Qingdao Bright Moon Seaweed Group Co., Ltd. reports a broad seaweed-derived ingredient portfolio. The competitive structure gives buyers a choice between integrated feedstock access and broader technical support.
Tate & Lyle’s combination with CP Kelco U.S., Inc. expanded its hydrocolloid portfolio across propylene glycol alginate, pectin, xanthan gum, gellan gum, and specialty gums. This move strengthened its ability to supply multi-ingredient stabilization systems to multinational food producers. Tate & Lyle also expanded its collaboration with BioHarvest Sciences in May 2026 to include multiple plant-based molecules. In February 2026, Tate & Lyle and Manus Bio launched Yume M Stevia Sweetener, reflecting the company’s broader biotechnology partnership activity. These actions show how portfolio breadth and technical development can supplement a supplier’s base ingredient position.
Kerry Group spent EUR 314 million (approximately USD 330 million) on research and development in 2025, with spending directed toward next-generation ingredient technologies. Tate & Lyle invested USD 10 million in digital and artificial intelligence-powered formulation tools in fiscal year 2026. Qualified pharmaceutical grade supply outside East Asia remains limited, creating a potential opening for suppliers with the required certifications. Sustainability-certified propylene glycol alginate with full seaweed supply-chain traceability is also relevant for European clean-label buyers. Patent activity in protein-propylene glycol alginate composite systems points toward competition based on encapsulation and drug-delivery applications. The propylene glycol alginate industry will continue to compete through application knowledge as well as production capacity.
Propylene Glycol Alginate Industry Leaders
-
KIMICA
-
Shandong Jiejing Group Corporation
-
Cargill, Incorporated
-
CP Kelco U.S., Inc.
-
FMC Corporation
- *Disclaimer: Major Players sorted in no particular order
Propylene Glycol Alginate Market Companies Covered in this Report
- ALGAIA
- Ashland
- Cargill, Incorporated
- CP Kelco U.S., Inc.
- FMC Corporation
- Hawkins Watts Limited
- Ingredion
- IRO Alginate Industry Co., Ltd.
- Kerry Group
- KIMICA
- Marine Biopolymers Ltd.
- Qingdao Bright Moon Seaweed Group Co., Ltd.
- Shandong Jiejing Group Corporation
- Tate & Lyle
Recent Industry Developments in Propylene Glycol Alginate Market
- June 2026: Shandong Jiejing Group Corporation presented its propylene glycol alginate portfolio and marine bioactive compounds at the Convention on Pharmaceutical Ingredients (CPhI) China 2026 in Shanghai. The showcase supports the pharmaceutical and nutraceutical use of propylene glycol alginate as a functional excipient and stabilizer.
- May 2026: Tate & Lyle expanded its collaboration with BioHarvest Sciences to develop multiple plant-based sweetener molecules. The initiative supports demand for plant-based formulation ingredients and complements the use of propylene glycol alginate as a stabilizer and texture modifier in food and beverage formulations.
Global Propylene Glycol Alginate Market Report Scope
Propylene glycol alginate is a modified alginate derivative produced by esterifying alginic acid with propylene glycol. It functions as a versatile hydrocolloid that provides controlled viscosity, stabilization, emulsification, and texture in formulated products.
The Propylene Glycol Alginate Market is segmented by grade, form, application, end-use, and geography. By grade, the market is segmented into food grade, pharmaceutical grade, and industrial grade. By form, the market is segmented into powder and liquid. By application, the market is segmented into stabilizers, emulsifiers, thickeners, gelling and foaming agents, and other applications. By end-use, the market is segmented into food and beverage, pharmaceuticals, personal care and cosmetics, and other end-uses. The report also covers the market size and forecasts for propylene glycol alginate in 15 countries across major regions. For each segment, the market sizing and forecasts have been done on the basis of value (USD).
Segmentation Overview
| Food Grade |
| Pharmaceutical Grade |
| Industrial Grade |
| Powder |
| Liquid |
| Stabilizers |
| Emulsifiers |
| Thickeners |
| Gelling and Foaming Agents |
| Other Applications |
| Food and Beverage |
| Pharmaceuticals |
| Personal Care and Cosmetics |
| Other End-Uses |
| Asia-Pacific | China |
| India | |
| Japan | |
| South Korea | |
| ASEAN Countries | |
| Rest of Asia-Pacific | |
| North America | United States |
| Canada | |
| Mexico | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| NORDIC Countries | |
| Rest of Europe | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Middle East and Africa | Saudi Arabia |
| South Africa | |
| Rest of Middle East and Africa |
| By Grade | Food Grade | |
| Pharmaceutical Grade | ||
| Industrial Grade | ||
| By Form | Powder | |
| Liquid | ||
| By Application | Stabilizers | |
| Emulsifiers | ||
| Thickeners | ||
| Gelling and Foaming Agents | ||
| Other Applications | ||
| By End-Use | Food and Beverage | |
| Pharmaceuticals | ||
| Personal Care and Cosmetics | ||
| Other End-Uses | ||
| By Geography | Asia-Pacific | China |
| India | ||
| Japan | ||
| South Korea | ||
| ASEAN Countries | ||
| Rest of Asia-Pacific | ||
| North America | United States | |
| Canada | ||
| Mexico | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| NORDIC Countries | ||
| Rest of Europe | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Middle East and Africa | Saudi Arabia | |
| South Africa | ||
| Rest of Middle East and Africa | ||
Key Questions Answered in the Report
What is the size of the propylene glycol alginate market?
The propylene glycol alginate market stands at USD 383.17 billion in 2026 and is projected to reach USD 508.19 billion by 2031.
What is driving demand for propylene glycol alginate?
Demand is supported by acid-stable thickening, emulsification, and protein suspension in beverages, dairy alternatives, and food products.
Which grade is projected to advance fastest through 2031?
Pharmaceutical grade is projected to advance at a 6.16% CAGR through 2031 as drug producers require qualified excipients.
Which form held the largest market share in 2025?
Powder held 72.74% of the market share in 2025 because it supports precise metering, dry blending, ambient storage, and tableting.