
Pet Grooming Services Market Size and Share
Market Overview
| Study Period | 2022 - 2032 |
|---|---|
| Market Size (2027) | USD 21.85 Billion |
| Market Size (2032) | USD 30.05 Billion |
| Growth Rate (2027 - 2032) | 6.58 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Pet Grooming Services Market Analysis by Mordor Intelligence
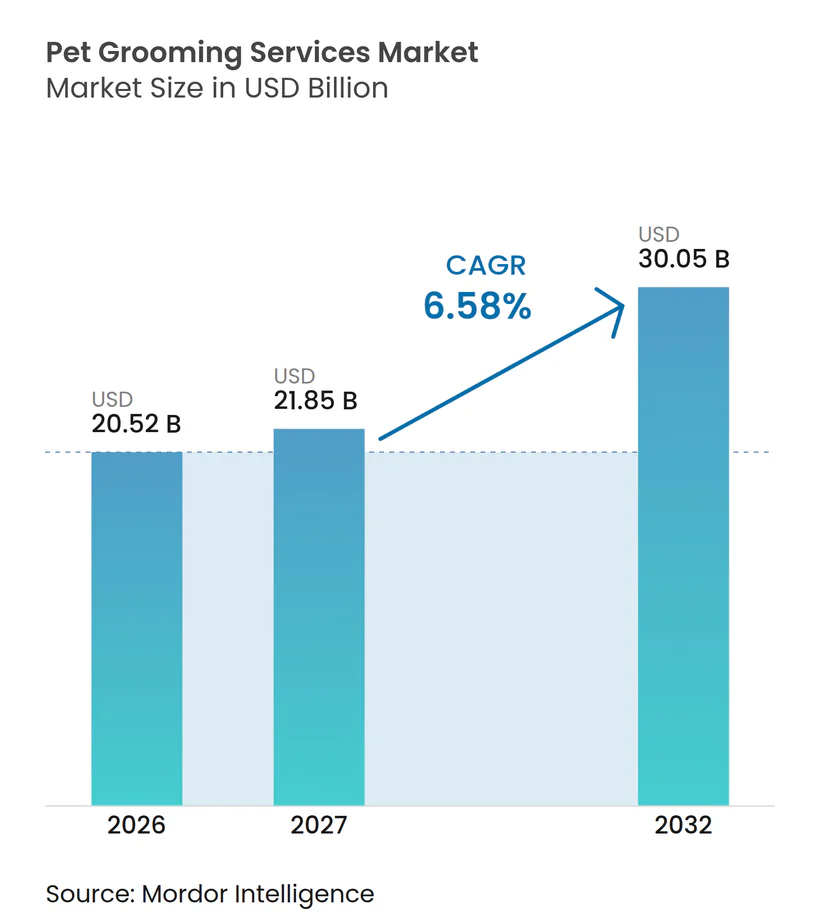
The global pet grooming services market size was valued at USD 20.52 billion in 2026 and is estimated to grow from USD 21.85 billion in 2027 to reach USD 30.05 billion by 2032, at a CAGR of 6.58% during the forecast period (2027-2032). The global pet grooming services market is supported by pet owners viewing grooming as essential for hygiene, skin care, parasite control, and coat maintenance rather than as an occasional appearance-related service. The United States pet industry spending reached USD 158 billion in 2025[1]. Spending in the other services category, which includes grooming, boarding, and training, reached USD 14.3 billion in 2025 and is projected to reach USD 14.9 billion in 2026. Recurring appointments and membership plans help providers improve demand predictability, while online booking and reminder systems reduce missed appointments. In Asia-Pacific, rising urban pet ownership and the emergence of mobile grooming services and specialist salons indicate growing adoption of professional grooming services in metropolitan centers. The market offers organized providers opportunities to strengthen customer retention through consistent service quality, safe animal handling, and convenient appointment access.
Key Report Takeaways
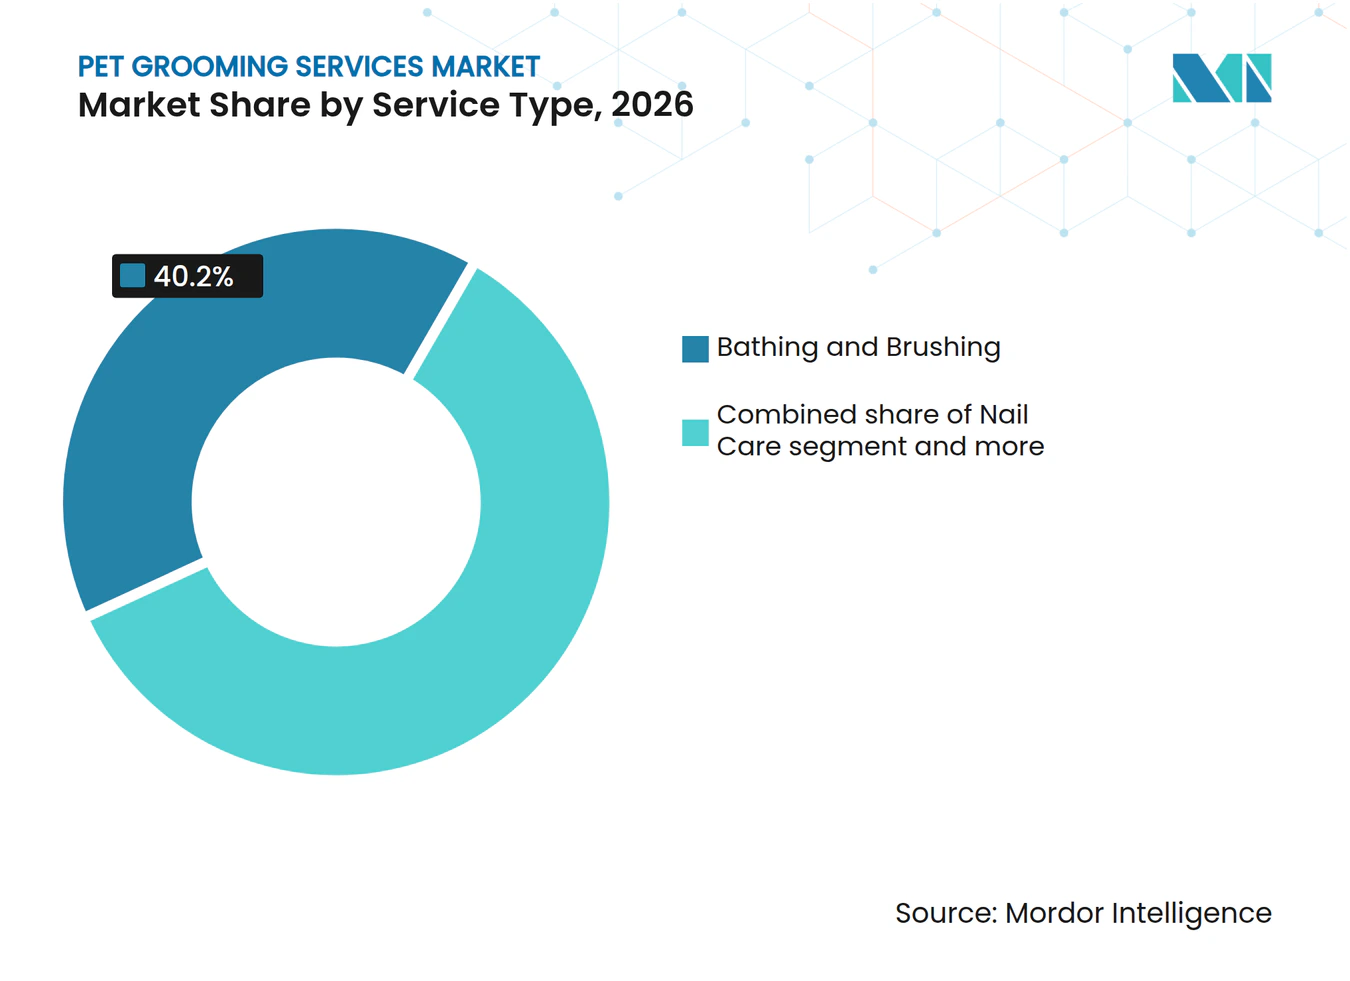
- By service type, bathing and brushing accounted for 40.20% of the global pet grooming services market share in 2026, while specialized skin, coat, and spa treatments are projected to grow at a 6.80% CAGR through 2032.
- By pet type, dogs accounted for 86.20% of the global pet grooming services market share in 2026, while cats are projected to grow at an 8.40% CAGR through 2032.
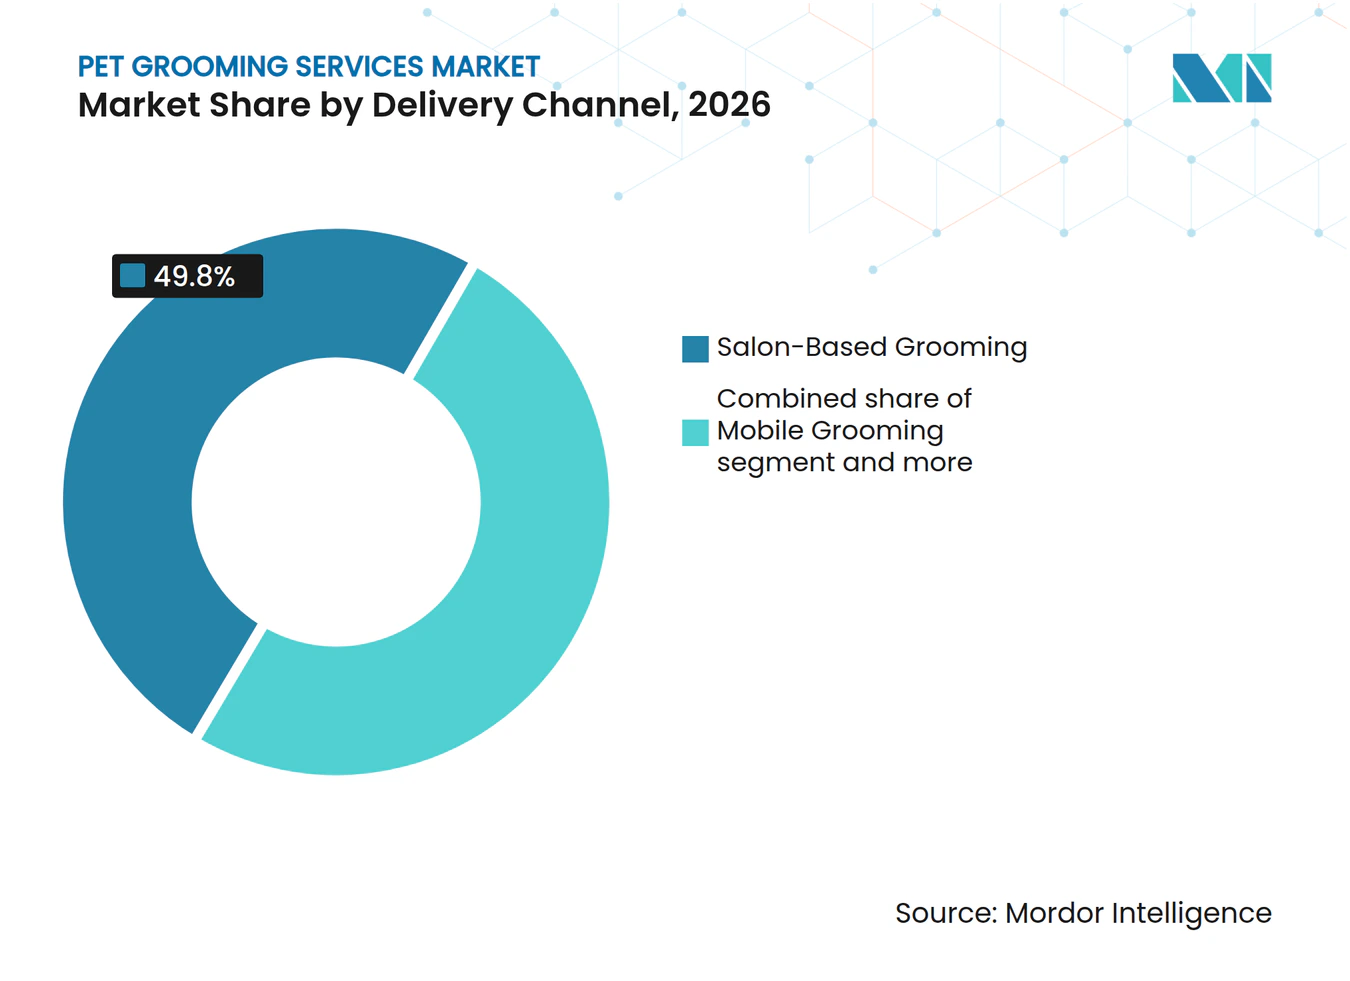
- By delivery channel, salon-based grooming accounted for 49.80% of the global pet grooming services market share in 2026, while at-home grooming is projected to grow at a 6.93% CAGR through 2032.
- By geography, North America accounted for 44.20% of the global pet grooming services market share in 2026, while Asia-Pacific is projected to grow at an 8.20% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Pet Grooming Services Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Pet Humanization and Premium Wellness Spending | +2.1% | Global, with highest intensity in North America and Western Europe | Long term (≥ 4 years) |
| Expanding Companion-Animal Ownership and Grooming Frequency | +1.5% | Global, with Asia-Pacific and South America accelerating fastest | Medium term (2-4 years) |
| Rising Awareness of Pet Hygiene and Preventive Grooming | +0.5% | Global, with early gains in urban Southeast Asia and India | Medium term (2-4 years) |
| Expansion of Multi-Service Pet-Care Facilities and Franchise Networks | +0.7% | North America primarily, with growth in Europe and Asia-Pacific | Medium term (2-4 years) |
| Growth of Mobile and At-Home Grooming Driven by Convenience | +1.0% | North America, Australia, and urban Asia-Pacific | Short term (≤ 2 years) |
| Digital Booking, Memberships, and Recurring-Service Models | +0.6% | Global, with rapid adoption in North America and East Asia | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Pet Humanization and Premium Wellness Spending
Pet humanization is increasing owners’ willingness to pay for grooming services that support coat condition, hygiene, and preventive care. This trend is expanding the global pet grooming services market beyond basic wash-and-trim offerings to include medicated baths, allergen-focused shampoos, dental hygiene, and breed-specific care. Petco reported USD 1.025 billion in services and other revenue for the 52 weeks ended January 31, 2026, compared with USD 999.6 million in the prior year, despite a decline in company-wide net sales. This result demonstrates the value of integrated service offerings amid softer retail demand. In metro cities, this preference supports specialized salons that offer clear service standards, pet safety measures, and quality products.
Expanding Companion-Animal Ownership and Grooming Frequency
A larger companion-animal base increases the number of households that use professional grooming services. The American Pet Products Association (APPA) reported 71 million dog-owning households and 53 million cat-owning households in the United States in 2025. Animal Medicines Australia reported that 73% of Australian households owned at least one pet in 2025[2]. Demand for professional grooming increases when owners schedule routine visits rather than seek services only when their pets need haircuts. In the global pet grooming services market, membership plans increase visit frequency and provide service providers with a more stable appointment base.
Rising Awareness of Pet Hygiene and Preventive Grooming
Preventive grooming is gaining importance as pet owners increasingly link nail care, ear cleaning, dental hygiene, and coat maintenance with animal comfort and routine care. Basic grooming also helps owners identify matting, skin irritation, and hygiene needs before these issues become more difficult to manage. This need is particularly relevant in densely populated cities, where owners have limited time for regular at-home care and seek convenient services for companion animals. The global pet grooming services market benefits when providers communicate the practical value of these routines rather than positioning them as luxury purchases. Groomers who provide clear care records and trained handling can build trust among first-time users of professional grooming services.
Expansion of Multi-Service Pet-Care Facilities and Franchise Networks
Multi-service facilities combine grooming, retail, boarding, training, and veterinary services within a single customer relationship. PetSmart operated approximately 1,700 stores across North America and completed 13.6 million grooming appointments in 2025[3]. Petco identifies its services business, including grooming, veterinary, and training, as a differentiated component of its operating model. These formats improve convenience for pet owners and create cross-selling opportunities across services and products. Similarly, the pet grooming services market can benefit from organized formats that provide reliable appointment systems, product access, and pet-care advice.
Restraints Impact Analysis of Pet Grooming Services Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Service Prices and Household Budget Sensitivity | -0.8% | Global, acute in North America and Western Europe | Short term (≤ 2 years) |
| Shortage of Skilled Groomers and Constrained Appointment Capacity | -0.6% | Global, most acute in Australia, North America, and Germany | Medium term (2-4 years) |
| Inconsistent Licensing and Quality Standards Across Jurisdictions | -0.3% | Global, with highest impact in fragmented markets including the United States and Southeast Asia | Long term (≥ 4 years) |
| Vehicle, Water, Waste, and Safety Compliance Costs for Mobile Operators | -0.2% | North America, Australia, and Western Europe | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
High Service Prices and Household Budget Sensitivity
Household budget pressures can shift routine bathing and brushing from salons to home care. The American Pet Products Association (APPA) reported that 51% of United States dog owners groomed their dogs at home in 2025, while spending on salon and mobile grooming declined. Professional grooming remains more relevant for full cuts, breed-specific styling, de-shedding, and complex hygiene needs. The People's Dispensary for Sick Animals (PDSA) reported that more than two-fifths of United Kingdom pet owners considered pet ownership more expensive than expected in 2025. The global pet grooming services market requires clear service differentiation, as basic services face the highest substitution risk during periods of household cost pressure.
Shortage of Skilled Groomers and Constrained Appointment Capacity
A shortage of trained groomers limits appointment availability and affects service quality consistency. In 2025, the Pet Industry Association of Australia reported that 79% of grooming businesses found it extremely difficult to recruit skilled groomers[4]. The survey also found that 76% of respondents supported mandatory animal-care qualifications for new entrants. To address a shortage of skilled groomers, Germany supported a one-year dog-grooming certificate program through the Zentralverband Zoologischer Fachbetriebe Deutschlands e. V. (ZZF) and the Potsdam Chamber of Industry and Commerce. In Asia-Pacific, structured training programs and welfare-focused handling practices are important as organized pet grooming services expand.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Consumer Preferences & Spending Patterns
Pet owners increasingly balance professional grooming services with at-home maintenance. APPA’s 2026 Dog Report found that 51% of United States dog owners groomed their dogs at home in 2025, while dog-wipe ownership increased by 108% year over year. This trend indicates that owners manage routine cleaning between salon visits, making convenience and specialized coat care key reasons to seek professional services. A 2025 pet-owner analysis also found that 80% of surveyed United States pet owners considered pets vital to family members, supporting demand for personalized care and animal comfort.
Affordability influences grooming service purchases. APPA reported that 22% of pet owners reduced pet spending in 2025, while approximately half maintained spending levels, according to its 2026 industry findings. United States cat ownership reached 53 million households in 2025, a 5% year-over-year increase, according to APPA. These trends create opportunities for affordable maintenance packages and cat-specific services, although pet ownership growth alone does not confirm demand for professional grooming services.
Service Market Performance Intelligence
Pricing in the global pet grooming services market varies by pet size, coat condition, service complexity, and convenience. Petco’s grooming menu lists add-ons from USD 20 for VIP treatment to USD 35 for Calm & Refresh, while self-wash starts at USD 20 at selected locations. Add-ons can increase average transaction value without raising base grooming prices. Higher-priced packages must provide clear benefits. Mobile grooming meets convenience-driven demand, but vehicle and labor costs make route utilization critical to profitability. Tiered menus, coat-care treatments, and recurring packages can balance affordability with predictable revenue.
Customer acquisition depends on converting occasional grooming visits into repeat business while controlling promotional spending. PetSmart’s 2025 CSR Report stated that Treats Rewards members accounted for 95% of sales, although this reflected total sales rather than grooming-specific retention. Petco reported fiscal 2025 net sales of USD 6.0 billion, down 2.5%, while services revenue, including grooming and veterinary care, rose from USD 1.0 billion to approximately USD 1.025 billion. Automated reminders, online rebooking, and loyalty-linked offers can increase repeat visits. Grooming-specific acquisition costs and conversion rates remain insufficiently disclosed for industry-wide comparisons.
Pet Grooming Services Market Segment Analysis
By Service Type:
Bathing Anchors the Base, Spa Treatments Grow FasterBathing and brushing accounted for 40.20% of the global pet grooming services market size in 2026. These services are a common entry point for professional grooming and help providers build recurring relationships with pet owners. Groomers can also recommend nail care, de-shedding, dental hygiene, and coat treatments based on pet needs. However, routine bathing and brushing face competition from at-home care. Providers can remain relevant through safe handling, appropriate products, and consistent results.
Specialized skin, coat, and spa treatments are forecast to grow at a CAGR of 6.80% through 2032. Medicated baths, hydrotherapy, de-shedding, and coat conditioning can generate higher value by supporting pet comfort and hygiene. Hair cutting and styling retain a professional advantage for breeds requiring regular trimming, as improper home cuts can create visible issues. Nail care is also a recurring service, as delayed trimming can affect comfort and mobility. These offerings can reduce the industry's reliance on basic services.



By Pet Type:
Dogs Lead, While Cats Gain Ground in Premium ServicesDogs accounted for 86.20% of the global pet grooming services market in 2026. This share reflects the large dog population in mature grooming markets and diverse coat-care needs across breeds. Many breeds require regular professional trimming, bathing, and de-shedding, supporting recurring demand. Recognition of professional grooming skills can strengthen customer confidence in specialized grooming services. Dogs remain central to salon capacity planning, staff training, and service offerings.
Cats are projected to expand at a CAGR of 8.40% through 2032. The American Pet Products Association (APPA) reported a 5% year-over-year increase in United States cat ownership, reaching 53 million households in 2025. Long-haired and medium-haired cats need grooming to prevent matting and manage shedding. Many salons primarily serve dogs, creating opportunities for cat-specific facilities, calmer handling, and feline-trained staff. Birds, small mammals, and other animals represent a smaller share of demand and are typically served by specialty operators or veterinary-linked providers.
By Delivery Channel:
Salons Retain Scale, While At-Home Grooming ExpandsSalon-based grooming accounted for 49.80% of the global pet grooming services market in 2026. Fixed salons benefit from established customer relationships, dedicated equipment, and higher appointment throughput than a single mobile operator can typically achieve. PetSmart completed more than 13 million grooming appointments through its store network in 2025. Integrated facilities can combine grooming with boarding, training, retail, and veterinary services, offering convenience to owners seeking multiple pet services in one visit.
At-home grooming is projected to grow at a CAGR of 6.93% through 2032. Unlike do-it-yourself grooming, this format involves a trained professional visiting the owner’s home. It suits anxious, elderly, or transport-sensitive pets and owners who value convenience. Mobile grooming remains important because its door-to-door, cage-free model addresses similar needs. Local regulations on vehicle idling, wastewater disposal, and home-occupation licensing remain key compliance considerations for these formats.

Geography Analysis
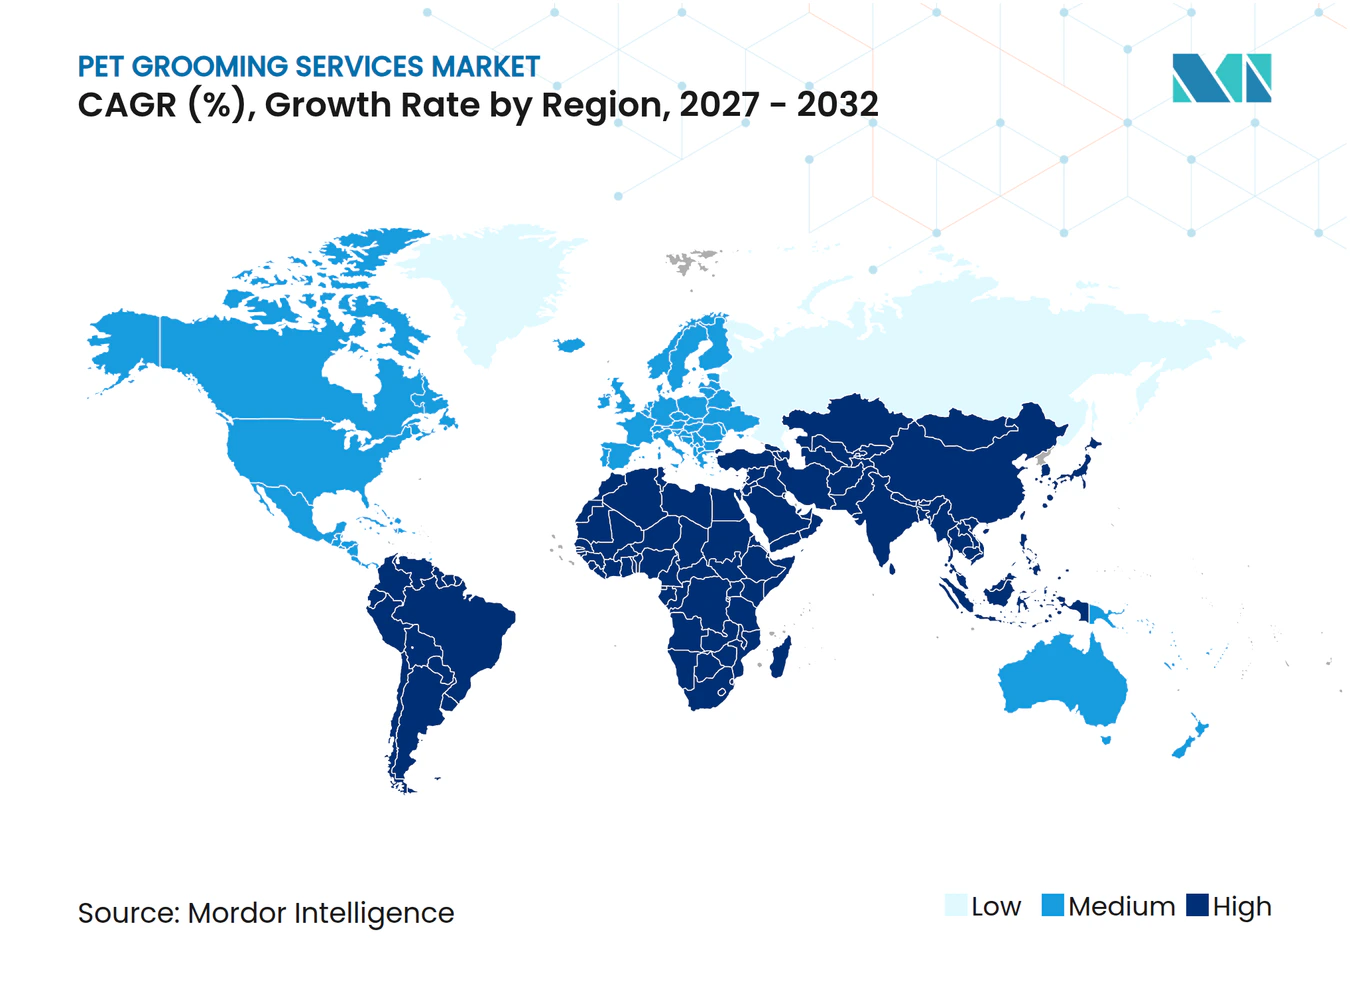
North America accounted for 44.20% of revenue in 2026. APPA reported 95 million United States pet-owning households in 2025. PetSmart recorded more than 13 million grooming appointments across approximately 1,700 stores, while Woof Gang Bakery & Grooming reached 300 locations in January 2026 and reported USD 150 million in 2025 systemwide sales. Providers emphasize membership, digital booking, and personalized services.
Asia-Pacific is projected to grow at an 8.20% CAGR through 2032. In 2025, 29.2% of South Korean households owned companion animals, while Australia’s pet ownership rate reached 73%. India’s pet-care spending totaled USD 3.6 billion in 2024, with growing interest in mobile grooming and specialist salons. Across other regions, Brazil and Peru present opportunities supported by substantial pet ownership, with Peru’s 2024 ENAPRES survey reporting that 51.7% of households owned at least one dog. In Europe, Germany has formal grooming training pathways, while the United Kingdom had 343 Pets at Home grooming salons. In the Middle East and Africa, demand is concentrated in the UAE and Saudi Arabia, where mobile grooming can address access constraints and consumer convenience needs.
Service Provider Network & Expansion Intelligence
The global pet grooming network includes independent salons, mobile groomers, and retail-integrated chains. PetSmart’s 2025 Corporate Social Responsibility (CSR) Report recorded 13.6 million grooming appointments across nearly 1,700 stores, demonstrating the service capacity and customer retention benefits of established networks. In the United Kingdom, Pets at Home operated 343 grooming salons across 459 pet care centers, integrating grooming with retail and veterinary services. These models show how customer traffic and complementary services can support repeat bookings, while independent operators can differentiate through personalized care and local convenience.
Franchising has supported network expansion; however, awarded territories do not necessarily become operating salons. Sparkle Grooming Co. reported 507 licenses awarded across 27 states, although only six salons were open at the time of its published update. Woof Gang Bakery & Grooming reported USD 150 million in systemwide sales in 2025, up 25% year over year, and opened its 300th location in January 2026. These developments highlight franchise growth potential and the need to convert signed territories into operating locations while maintaining consistent grooming quality.
Competitive Landscape
Market Concentration
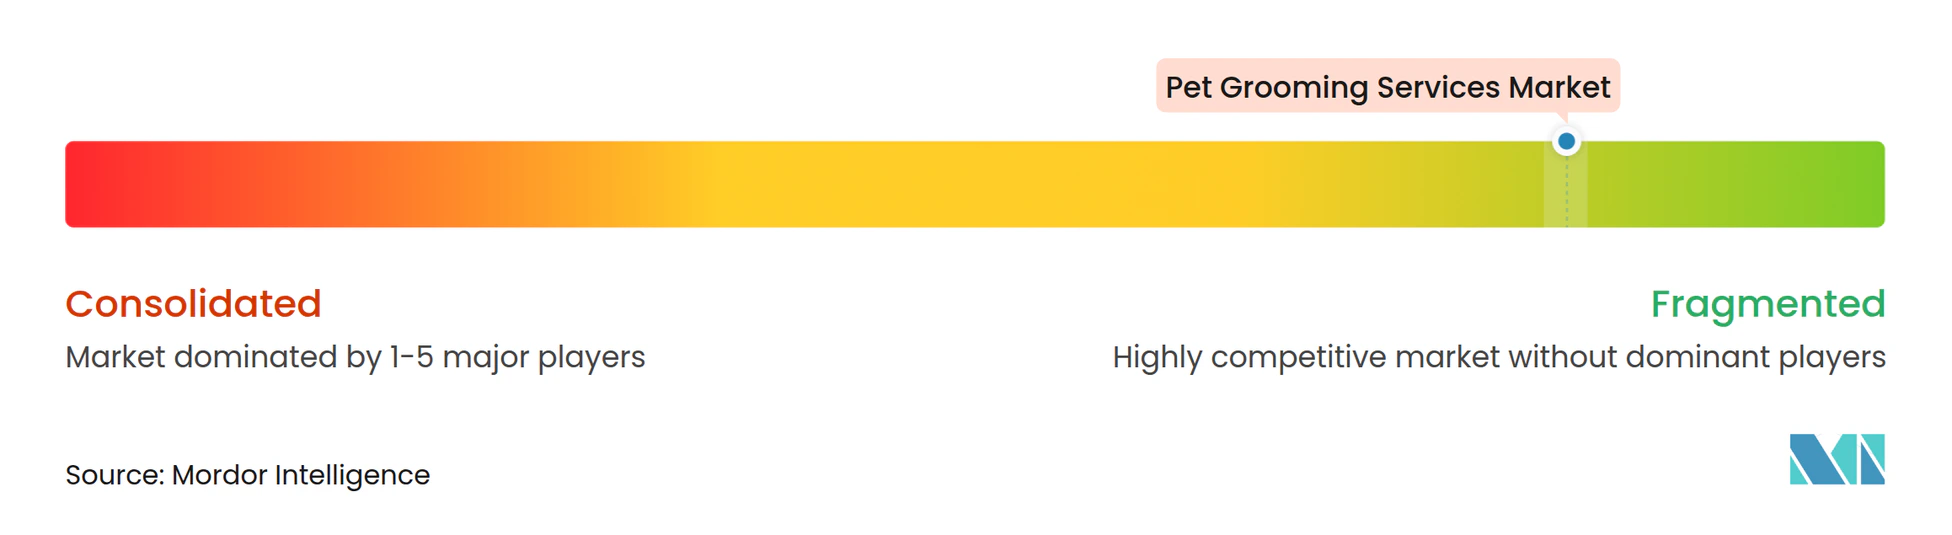
The global pet grooming services market is highly fragmented, and no single operator accounts for more than 5% of global revenue, reflecting a competitive landscape dominated by independent groomers, regional chains, and local service providers. PetSmart, Petco, and Pets at Home provide retail-linked services, while Woof Gang Bakery & Grooming, Aussie Pet Mobile, Sparkle Grooming Co., and Scenthound use franchise models. Independent salons, veterinary-linked providers, mobile operators, and boarding-grooming hybrids account for substantial service availability, supporting local competition but limiting standardization. Technology supports scheduling, service histories, reminders, and memberships. Petco stated that its app and e-commerce platform enabled omnichannel service interactions. Sparkle Grooming Co. reported a 73% membership conversion rate and more than 500 awarded licenses by April 2026. Digital booking and care records can build consumer confidence by improving service transparency, appointment convenience, and continuity of pet care. Woof Gang Bakery & Grooming entered Arkansas, Oklahoma, and Utah in June 2026, targeting around 450 North American locations by 2027. Top Dog Holdings acquired Dogfather Grooming in November 2025 and Doggie Styles in December 2025. Home Franchise Concepts opened 177 new territories across its portfolio in 2025, with Aussie Pet Mobile leading portfolio growth.
Pet Grooming Services Industry Leaders
-
PetSmart LLC
-
Petco Health and Wellness Company, Inc.
-
Pets at Home Group Plc
-
Woof Gang Bakery & Grooming
-
Bark & Mane
- *Disclaimer: Major Players sorted in no particular order
Pet Grooming Services Market Companies Covered in this Report
- Petco Health and Wellness Company, Inc.
- PetSmart LLC
- Pets at Home Group Plc
- Woof Gang Bakery & Grooming
- Bark & Mane
- Groomit for Pets LLC
- Barkbus
- Best Friends Pet Care, Inc.
- EarthWise Pet
- Healthy Spot
- Pet Evolution
- Pet Supplies Plus
- The Dog Stop
- Wag N' Wash Natural Pet Food & Grooming
- Woofie's
- Zoomin Groomin
- Dogtopia Enterprises
- Camp Bow Wow
- Pooch Dog SPA
- The Pooch Mobile
Recent Industry Developments in Pet Grooming Services Market
- October 2026: Top Dog Holdings acquired K9 Studio Dog Groomers in Greenwich, Connecticut. The 21-year-old salon joined Dogfather Grooming, supporting Top Dog’s strategy to acquire established independent salons across the Northeast for its hybrid mobile and salon network.
- June 2026: Woof Gang Bakery & Grooming operates in 36 United States’ states and Canada following expansion into Arkansas, Oklahoma, and Utah. The company targets approximately 450 North American locations by 2027.
- April 2026: Sparkle Grooming Co. surpassed 500 franchise licenses across 27 states within 24 months of franchising, including Texas, Florida, Ohio, and the Mid-Atlantic. Its Quick-Service Pet Care model achieved a 73% membership conversion rate.
- February 2026: Sparkle Grooming Co. signed a 67-unit Mid-Atlantic development agreement covering Maryland, Washington, D.C., Northern Virginia, and North Carolina. The initial salons were scheduled to open in 2026.
Global Pet Grooming Services Market Report Scope
The global pet grooming services market report analyzes professional grooming services for companion animals across salon-based, mobile, at-home, and integrated pet-care settings. The market is segmented by service type, pet type, delivery channel, and geography. The study examines key growth drivers, including pet humanization, rising companion-animal ownership, increasing awareness of pet hygiene, franchise expansion, and digital booking adoption, alongside restraints such as high service prices, skilled-groomer shortages, inconsistent quality standards, and mobile-service compliance costs. It evaluates service-provider networks, geographic expansion, service pricing, customer acquisition trends, consumer preferences, and spending patterns. The report provides market size and growth forecasts, competitive landscape analysis, market concentration and share assessments, strategic developments, and profiles of leading service providers. It also identifies opportunities in cat-specific low-stress grooming, integrated wellness services, and subscription-based platforms. Market estimates and forecasts are presented in value (USD) across all covered segments and regions.
Segmentation Overview
Key Questions Answered in the Report
What is the 2027 value of pet grooming services?
The global pet grooming services market is estimated at USD 21.87 billion in 2027 and is forecast to reach USD 30.05 billion by 2032, supported by repeat care needs across service formats and by increasing use of professional grooming for hygiene and coat maintenance.
Which pet grooming service has the largest share?
Bathing and brushing held 40.20% of revenue in 2026, making it the largest service category because it remains a routine need for professionally groomed pets.
Which pet category is growing fastest in professional grooming?
Cats are forecast to grow at an 8.40% CAGR through 2032, supported by rising cat ownership, mat prevention needs, and demand for specialized handling.
Why is at-home pet grooming growing?
At-home grooming is projected to grow at a 6.93% CAGR through 2032 because it offers professional care with greater convenience for owners and a lower-stress setting for pets.
How concentrated is the pet grooming services sector?
The sector has a low concentration level, as no single provider accounted for more than 5% of global revenue, while numerous independent operators and widely dispersed service locations sustain a highly fragmented competitive landscape.