
France Kitchen Sink Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 172.52 Million |
| Market Size (2026) | USD 180.20 Million |
| Market Size (2031) | USD 224.02 Million |
| Growth Rate (2026 - 2031) | 4.45 % |
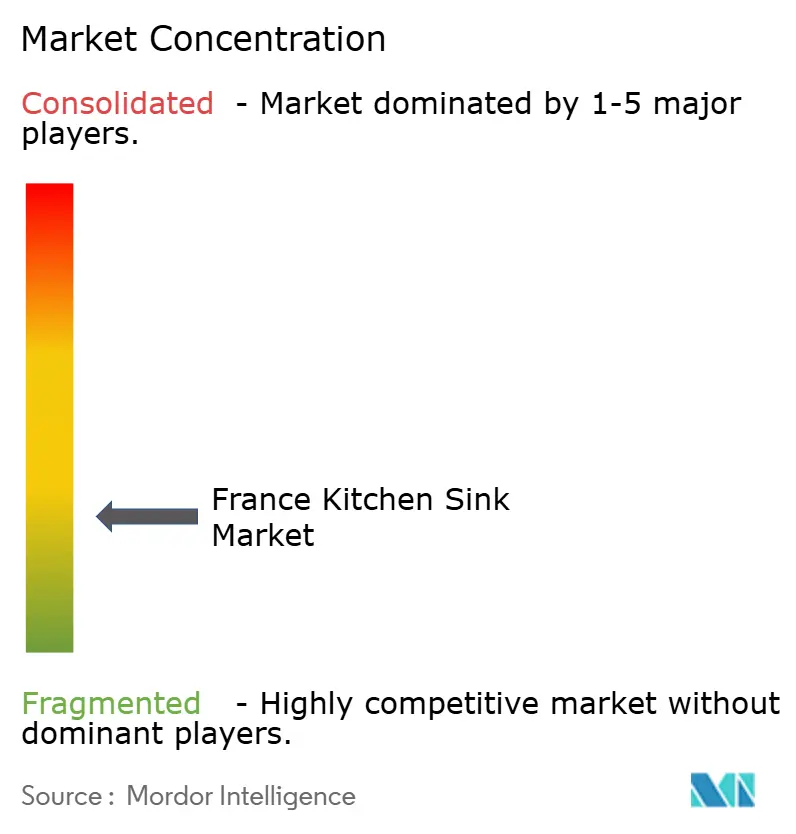
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
France Kitchen Sink Market Analysis by Mordor Intelligence
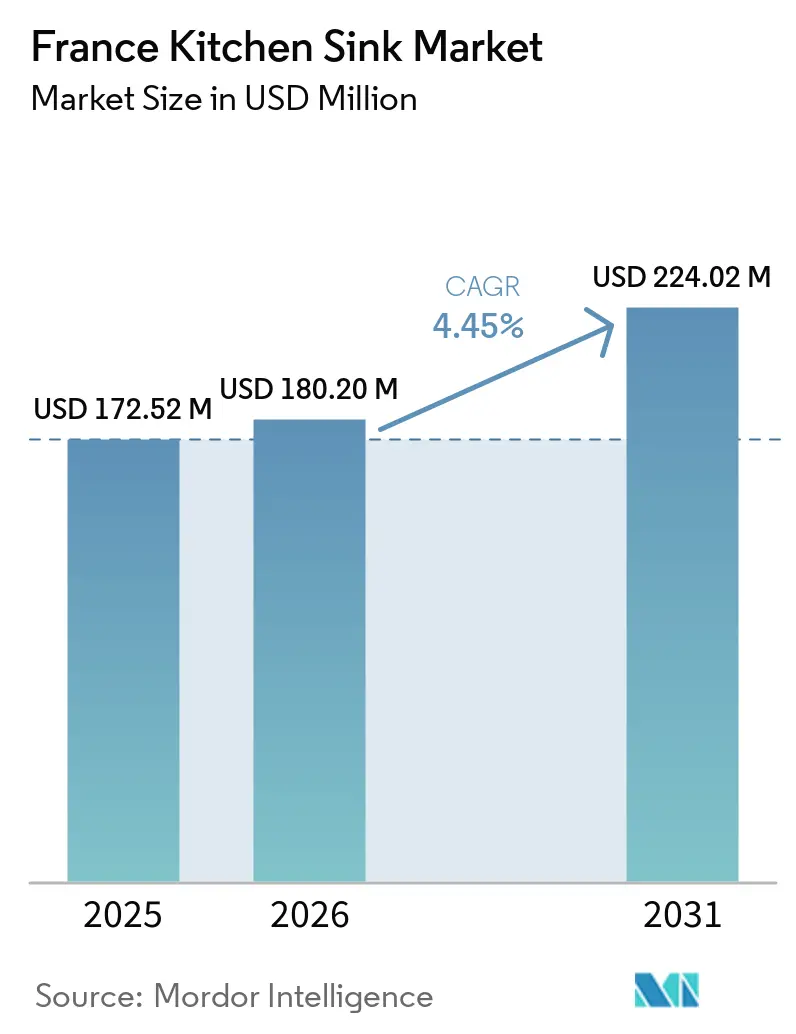
The France kitchen sink market size was valued at USD 172.52 million in 2025 and is estimated at USD 180.20 million in 2026, and is forecast to reach USD 224.02 million by 2031, growing at a 4.45% CAGR during 2026–2031. The France kitchen sink market benefits from renovation demand that remains relevant even when new construction is weak, because kitchen upgrades often accompany property transactions and planned home improvements. French construction investment is expected to recover in 2026, while housebuilding is also set to expand, which should support fixture demand across residential projects[1]. Product development is moving toward coordinated sink, faucet, waste, and accessory systems, giving suppliers a way to compete on design and installation convenience rather than price alone. Composite materials, workstation designs, and online purchasing are widening the premium and digital routes to market for the France kitchen sink market. Material costs, replacement-cycle delays, and price competition from imports remain important constraints for producers and distributors.
Key Report Takeaways
- By material, stainless steel held 42.3% of the France kitchen sink market share in 2025, while quartz composite is forecast to grow at a 6.20% CAGR through 2031.
- By installation type, undermount sinks accounted for 54.2% of the France kitchen sink market size in 2025, while farmhouse and apron-front sinks are projected to grow at a 6.00% CAGR through 2031.
- By bowl configuration, single-bowl sinks held 56.0% of the France kitchen sink market share in 2025, while dual-bowl sinks are forecast to expand at a 5.10% CAGR through 2031.
- By end user, residential applications accounted for the largest value share of the France kitchen sink market, at 54.8% in 2025, while commercial applications are projected to grow at the fastest CAGR of 5.40% during 2026–2031.
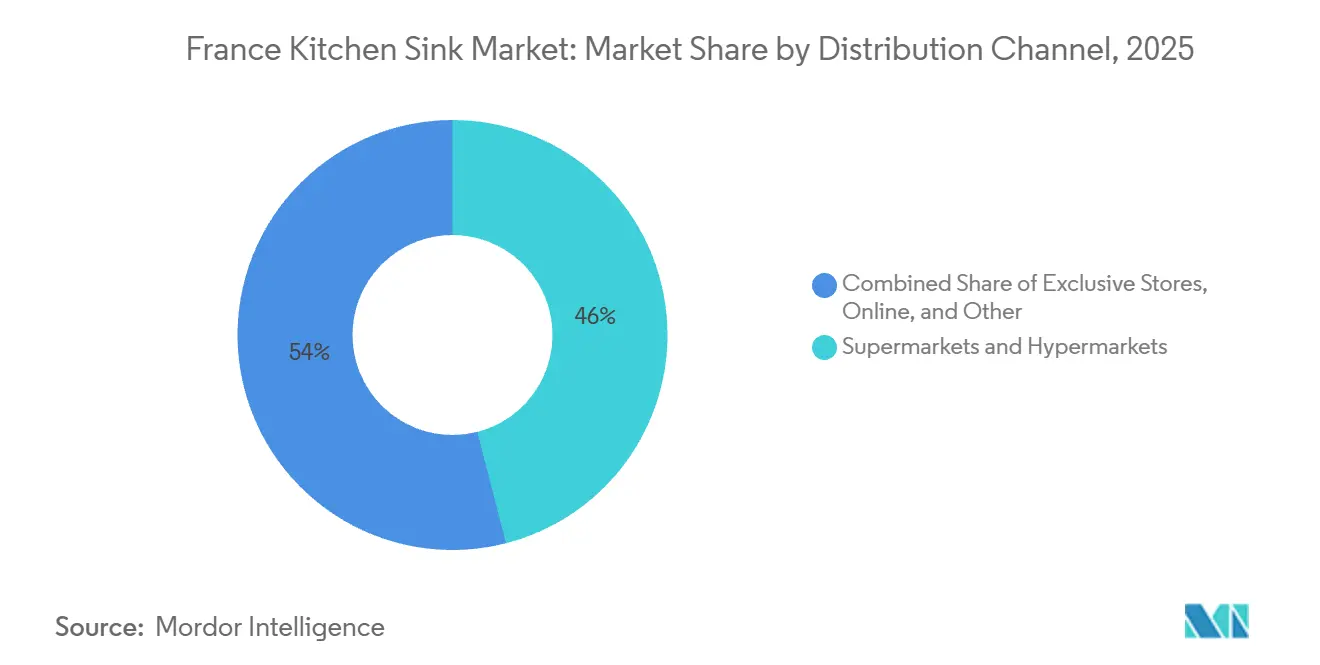
- By distribution channel, supermarkets and hypermarkets held 46.0% of the kitchen sink market in France in 2025, while online channels are forecast to grow at an 8.00% CAGR through 2031.
- By geography, Île-de-France accounted for 28.0% of kitchen sink demand in France in 2025, while the rest of France is projected to grow at a 5.70% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
France Kitchen Sink Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Kitchen Renovation and Replacement Demand | +1.2% | National, strongest in Île-de-France and Provence-Alpes-Côte d'Azur | Medium term (2-4 years) |
| Premium Composite and Design-Led Sink Adoption | +0.9% | National, concentrated in urban centers and affluent suburban areas | Long term (≥ 4 years) |
| Growth of Multifunctional Workstation Sinks | +0.7% | Île-de-France and major metropolitan regions | Medium term (2-4 years) |
| Expansion of E-Commerce and Omnichannel Kitchen Purchasing | +0.5% | National | Short term (≤ 2 years) |
| Sink-Tap-Waste-System Integration | +0.4% | National, with early gains in premium urban areas | Long term (≥ 4 years) |
| Import-Led Access to Broad Product Assortments | +0.2% | National | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Rising Kitchen Renovation and Replacement Demand
France’s building maintenance and renovation sector generated EUR 117.7 billion in output in 2024, while residential renovation remained comparatively stable during the contraction in new construction[2]. This pattern supports the French kitchen sink market because replacement demand is linked to kitchen refits as well as newly completed homes. A sink purchase can therefore remain part of household improvement spending when a construction slowdown limits demand from new projects. The Fédération Française du Bâtiment expects housing starts of slightly under 300,000 units in 2026, still about 60,000 below the 40-year average[3]. Suppliers that offer standard dimensions and dependable installer support are better placed to serve renovation projects with varied cabinet and countertop conditions. This demand profile gives the France kitchen sink market a more stable base than categories dependent only on new-home construction.
Premium Composite and Design-Led Sink Adoption
Quartz composite, granite composite, and related proprietary materials are broadening the premium offer in the French kitchen sink market. These materials support coordinated kitchen surfaces because they can be selected to complement countertops, cabinet finishes, and faucets. SCHOCK’s CRISTADUR GREEN Line uses more than 99% natural, renewable, or recycled raw materials, linking material development with durability and circularity considerations[4]. The EU Ecodesign for Sustainable Products Regulation entered into force in July 2024 and provides the framework for product requirements that address circularity and sustainability. BLANCO frames the category as the kitchen water place, selling integrated BLANCO UNIT solutions that combine workstations, faucets, filtration, and under-sink organization. Composite products can command a higher selling price than standard stainless steel, which helps value growth when unit demand is moderate. The French kitchen sink market therefore offers suppliers an opportunity to use material choice, finish options, and environmental credentials to differentiate their ranges.
Growth of Multifunctional Workstation Sinks
Workstation sinks combine the basin with accessories such as cutting boards, colanders, drying racks, and sliding ledges. They address demand for usable preparation space, especially in compact urban kitchens where a larger countertop is not always available. BLANCO introduced its INTEOS workstation system in 2025 with shared cutout dimensions across stainless steel and SILGRANIT versions, which can simplify specification and installation choices. Suppliers are positioning workstation sinks around a ‘sink-to-table’ experience. Kohler markets its Synthos Luxe sink with multi-level ledges and accessories that cover food prep, serving and storage. These launches show that large suppliers are using accessories and system compatibility to strengthen their premium position. For the France kitchen sink market, the format supports demand for visible, functional fixtures in open-plan residential spaces and food preparation environments.
Expansion of E-Commerce and Omnichannel Kitchen Purchasing
EUR 196.4 billion (USD 221.93 billion) online in 2025, of which online product sales accounted for EUR 76.1 billion (USD 86.00 billion). Furniture and home décor online sales increased 3% during the year, indicating that home-related buying remains active through digital channels. The France kitchen sink market can benefit as buyers use online channels to compare materials, finishes, dimensions, and accessory packages before purchase. Digital storefronts are particularly relevant for brands that do not operate broad physical retail networks in France. Retailers still need reliable delivery, clear specifications, and accessible returns because sinks are large, heavy, and sensitive to installation requirements. Omnichannel sales can also connect online product research with showroom advice and local collection options.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Stainless-Steel, Nickel, Energy and Logistics Cost Exposure | -0.8% | Global, with direct effects across French distribution tiers | Short term (≤ 2 years) |
| Mature Housing Stock and Replacement-Cycle Volatility | -0.6% | National, with greater exposure in Île-de-France and Hauts-de-France | Long term (≥ 4 years) |
| Installation Complexity Across Diverse French Kitchen Layouts | -0.4% | Urban areas, particularly Paris and Lyon | Medium term (2-4 years) |
| Low-Cost Import Competition and Price Transparency | -0.5% | National | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
High Stainless-Steel, Nickel, Energy and Logistics Cost Exposure
Stainless steel remains central to the France kitchen sink market, so changes in nickel, energy, and logistics costs affect a large part of the supply chain. Lower nickel costs can improve consumer affordability, but they can also pressure manufacturers that acquired material under earlier and higher-priced contracts. The resulting mismatch can reduce margins for producers, distributors, and retailers. FIEC expects material costs to rise in 2026 because of factors including the Carbon Border Adjustment Mechanism and supply disruptions. Cost exposure is most difficult for standard stainless steel products because they face intense price comparison. Manufacturers are responding by expanding higher-value composite, colored, and accessory-led offers that compete on more than base product price.
Mature Housing Stock and Replacement-Cycle Volatility
France has a large and aging housing stock, and many existing kitchens do not conform to current modular layout standards. This creates long-term renovation potential, but it also makes replacement work harder when cabinets, plumbing, or countertop openings need adaptation. Housing starts fell to 261,000 units in 2024 and recovered to 283,000 in 2025, remaining below the long-run annual average cited by the Fédération Française du Bâtiment. Slower property transactions and postponed home projects can delay sink replacement purchases. Maintenance renovation volume in Île-de-France declined 2.2% in 2025, which illustrates the pressure that can affect even the country’s largest regional demand center. The France kitchen sink market must therefore balance long-term replacement demand with short-term decisions to defer renovation spending.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Material: Composite Innovation Challenges Stainless Steel Dominance
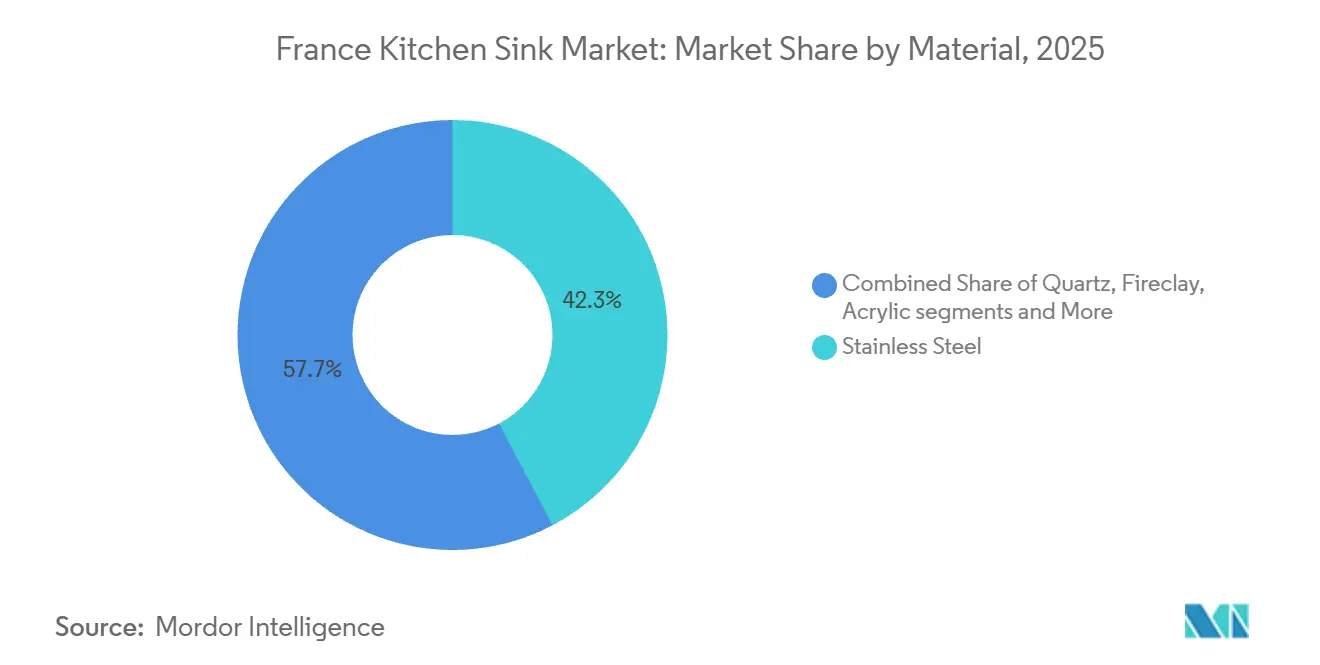
Stainless steel held 42.3% of the France kitchen sink market in 2025. Its position reflects durability, ease of cleaning, and availability across economy, mid-range, and premium price points. The material also remains suited to commercial kitchens, where hygienic surfaces and practical maintenance are important. Standard stainless steel products serve large retail chains as well as specialist kitchen retailers. Quartz composite is forecast to grow at a 6.2% CAGR through 2031, supported by demand for heat-resistant surfaces and coordinated colors. This makes it the fastest-growing material category in the France kitchen sink market.
Composite products help suppliers move beyond a standard fixture sale toward a coordinated kitchen-surface offer. SCHOCK’s CRISTADUR GREEN Line shows how recycled and renewable content can become part of the product proposition. The ESPR creates a policy setting in which durability and circularity are increasingly relevant to product development. Fireclay retains a place in farmhouse and apron-front designs, particularly where a traditional appearance is part of the kitchen plan. Granite and marble products serve design-led mid-premium projects, while acrylic options remain relevant to lower-cost replacements. Material choice is increasingly linked to countertop coordination, installation method, and expected kitchen use rather than appearance alone.

By Installation Type: Undermount Leads, Farmhouse Gathers Momentum
Undermount sinks accounted for 54.2% of the France kitchen sink market in 2025. The format produces a flush transition between the countertop and sink, which supports the clean-lined look sought in design-led renovations. Stone and quartz counters are particularly compatible with this installation approach. Precise templating and professional installation are important for these projects. Farmhouse and apron-front designs are forecast to grow at a 6% CAGR through 2031. Their growth is supported by renovation projects that combine heritage details with contemporary materials and finishes.
Farmhouse designs are now available in narrower profiles, composite materials, stainless steel, and matte finishes. This broader range lets the format move beyond rural-style projects into modern kitchen schemes. Top-mount and drop-in sinks remain important for replacements where changing the countertop opening is not practical. They offer a more accessible option for older homes and value-focused upgrades. Flush-mount products are suitable for integrated countertop projects, while dual-mount designs give installers greater flexibility. The installation mix in the France kitchen sink market reflects both premium surface trends and the practical constraints of the existing housing stock.
By Bowl Configuration: Single Bowl Dominates, Dual Bowl Rises on Workflow Logic
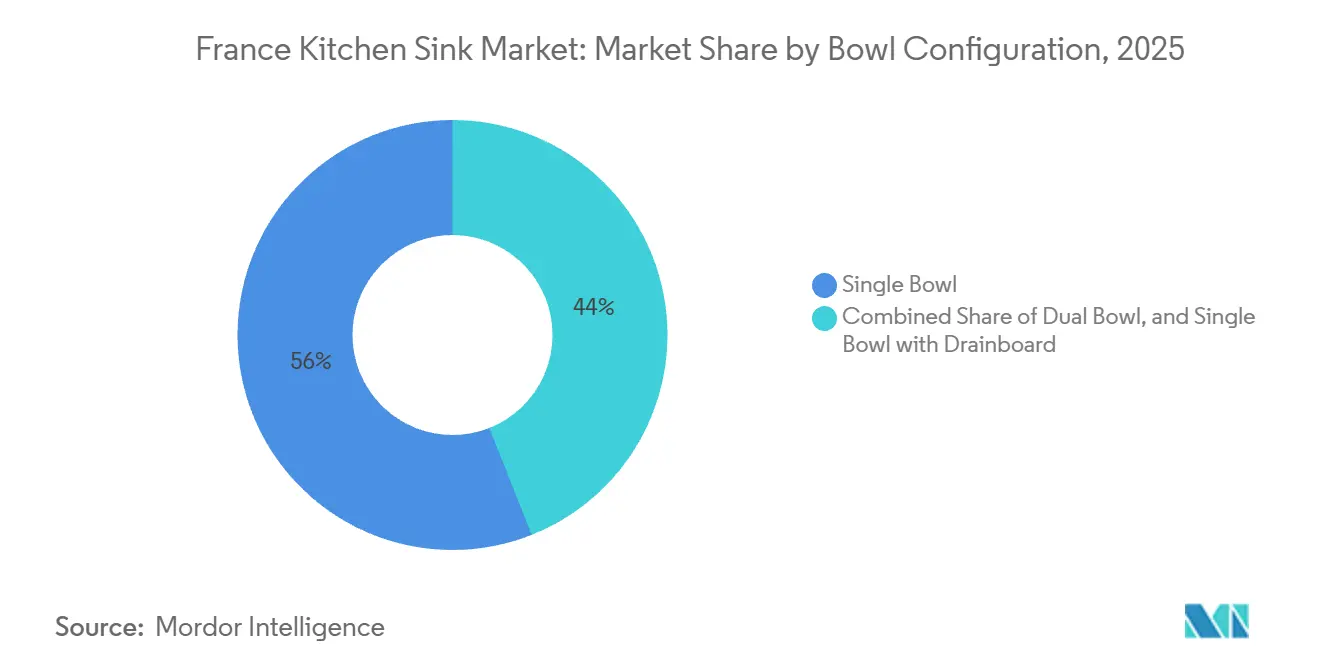
Single-bowl products held 56% of the France kitchen sink market in 2025. Their popularity is linked to deep basins, undermount installations, and accessory systems that provide preparation functions without dividing the bowl. A larger unobstructed basin can accommodate oversized cookware and support meal preparation. BLANCO’s INTEOS system and Kohler’s Synthos collection both use workstation concepts that fit this approach. The configuration is also appropriate for kitchens where counter space is limited. These advantages keep single-bowl formats central to the France kitchen sink market.
Dual-bowl sinks are expected to grow at a 5.1% CAGR through 2031. They are useful when washing and rinsing need to occur at the same time, especially in larger homes and commercial kitchens. Foodservice operators may prefer physical separation for their cleaning workflows. Single-bowl sinks with drainboards continue to meet demand from households that value space efficiency and familiar rinsing patterns. The choice between one and two bowls increasingly depends on accessories, meal preparation, and cleaning routines. Suppliers can address this variation by providing basin sizes and accessory packages that work across several cabinet widths.
By End-User: Commercial Growth Signals Specification-Tier Shift
Home renovations and upgrades following property transactions remain the principal sources of residential demand. The segment covers entry-level stainless steel products as well as premium composite and coordinated system products. Households can select different materials and installation types according to budget, countertop condition, and desired style. Commercial applications are forecast to expand at a 5.4% CAGR through 2031. This pace is faster than the overall France kitchen sink market growth rate.
Residential applications accounted for 54.8% of the France kitchen sink market in 2025. Commercial demand is associated with hospitality, foodservice, and kitchen operations that need durable and easy-to-maintain sinks. Deep-drawn stainless steel, larger basins, and dual-bowl configurations are relevant to these applications. Urban food preparation businesses also require equipment that supports cleaning and operational workflows. Suppliers serving commercial buyers need clear technical information and reliable product availability. Their product ranges often differ from residential offers because sanitation, capacity, and installation needs are more demanding. The commercial opportunity raises the value of products designed for professional use without removing the importance of the residential replacement cycle.
By Distribution Channel: Hypermarkets Anchor Volume, Online Redefines Access
Supermarkets and hypermarkets held 46% of the France kitchen sink market in 2025. These outlets provide broad access to standard stainless steel and entry-level composite products. Their scale supports high-volume purchases and helps consumers compare products across accessible price tiers. They also remain suitable for straightforward replacement purchases. Online channels are projected to grow at an 8% CAGR through 2031. This is the fastest distribution-channel growth rate in the France kitchen sink market.
E-commerce allows buyers to compare product dimensions, finishes, installation methods, and accessories before selecting a sink. It also helps specialist brands serve customers outside the areas covered by their showrooms. France’s e-commerce turnover reached EUR 196.4 billion in 2025, showing the wider scale of digital purchasing. Exclusive stores and design studios retain an important role for premium composite products and integrated sink-faucet systems. Online buying behaviour is shifting. One in three French online buyers used generative AI in their purchase journey in 2025, according to an Odoxa study for Fevad, and marketplaces held 32% of online product sales. Contractor procurement and project purchasing also remain relevant for new residential developments and commercial kitchen installations. The channel mix favors suppliers that can provide clear product information and consistent service across physical and online touchpoints.
Geography Analysis
Île-de-France held 28% of the France kitchen sink market in 2025. The region has a high concentration of premium renovation activity, kitchen studios, specialist material distributors, and projects that favor undermount, composite, and integrated systems. Its scale makes it a leading specification center for products with higher design and installation requirements. However, maintenance renovation volume in the region decreased 2.2% in 2025, compared with a national decline of 1.1%. This result shows that the region’s demand is sensitive to property conditions and household confidence.
Provence-Alpes-Côte d’Azur combines higher-income renovation activity with demand from secondary homes and hospitality properties, while Auvergne-Rhône-Alpes benefits from residential renovation and foodservice activity centered on Lyon. The construction renovation price index increased 1.2% year over year in the second quarter of 2025. Plumbing and HVAC installation prices increased 1.3% during the same period, affecting the cost base for sink-related work. Nouvelle-Aquitaine has demand for farmhouse and fireclay styles through rural renovation projects. Hauts-de-France also benefits from its location near northern European supply and design networks.
Rest of France is forecast to grow at a 5.7% CAGR through 2031. Demand is supported by renovation in peri-urban and rural areas, where secondary homes and relocations expand the improvement base, and by growing showroom and online fulfillment activity in Toulouse, Nantes, Bordeaux, and Rennes. National housing starts are expected to increase by 9.5% in 2026, which should gradually expand the future replacement base outside the dense Île-de-France area. Overseas regions add demand through hospitality infrastructure and commercial kitchen upgrades, making local product availability and installation support important across the France kitchen sink market.
Competitive Landscape
The France kitchen sink market is fragmented. European specialists hold a strong position in premium composite and design-led products through material platforms and coordinated system offers. Franke, BLANCO, and SCHOCK compete through differentiated designs, accessories, finishes, and support for specification channels. BLANCO introduced INTEOS in February 2025 as a workstation system available in stainless steel and SILGRANIT, with common cutout dimensions that give designers and installers greater flexibility. This approach shifts competition toward the total sink area rather than the basin alone.
Italian suppliers such as Elleci, Foster, and Plados Telma compete in the mid-premium range through design choice and manufacturing quality. Integrated sink and faucet offers are particularly relevant where consumers want a coordinated finish. Chambord remains associated with the heritage fireclay and farmhouse category, which serves specialized renovation projects. Smaller suppliers can use online distribution, color options, and competitive composite pricing to build visibility in the France kitchen sink market. Alveus introduced Monarch Originals with PVD coatings in gold, bronze, copper, and anthracite in June 2025, providing an alternative to price-based competition in standard stainless steel.
Franke expanded its Centro Fragranite range in August 2025 with a single-bowl model designed for a 500 mm cabinet, while Kohler launched the Audrine fireclay collection in January 2026 with Studio McGee. These moves show that leading suppliers are using compact formats, system design, and finish differentiation to reach distinct renovation needs. Imports remain a price pressure in standardized products, but European suppliers can respond through material innovation, faster specification support, and integrated product ranges. The France kitchen sink market remains competitive because no single supplier controls the range of material, installation, and channel preferences across the country.
France Kitchen Sink Industry Leaders
-
Franke Group
-
BLANCO GmbH + Co KG
-
SCHOCK GmbH
-
Kohler Co.
-
Villeroy & Boch AG
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- January 2026: Kohler Co. launched the Audrine kitchen sink collection in partnership with Studio McGee designer Shea McGee. Crafted from smooth, nonporous fireclay in White and Dune finishes, Audrine represents Kohler's first kitchen sink design collaboration with the firm and targets the premium apron-front segment, gaining momentum in both new-build and renovation specifications across Europe. The collection pairs with the existing Edalyn kitchen faucet to offer a fully coordinated system specification.
- November 2025: Kohler introduced the Synthos Workstation sink collection, winning both the iF Design Award and the Red Dot Award for product design innovation. The collection was developed for hosting and seamless kitchen workflow, competing directly with BLANCO's INTEOS in the premium workstation segment. Available configurations serve multiple kitchen size formats.
- June 2025: Alveus d.o.o. launched Monarch Originals kitchen sinks with PVD coating technology in Gold, Bronze, Copper, and Anthracite finishes, citing the company's position as the first brand to introduce PVD technology to the kitchen sink category more than 15 years ago. The range targets design-conscious consumers seeking non-standard colorway coordination across kitchen surfaces.
- February 2025: BLANCO GmbH + Co KG unveiled INTEOS, its workstation sink system, at KBIS 2025 in Las Vegas, simultaneously announcing a full brand refresh to mark its 100th anniversary. INTEOS is available in stainless steel and SILGRANIT composite across 30-, 33-, 39-, and 45-inch configurations and shares a single cutout dimension across all materials, simplifying design specification and contractor installation.
France Kitchen Sink Market Report Scope
| Stainless Steel |
| Quartz |
| Fireclay |
| Granite/Marble |
| Acrylic |
| Others |
| Top-Mount / Drop-In |
| Undermount |
| Farmhouse / Apron-Front |
| Flush Mount |
| Dual Mount |
| Others |
| Single Bowl |
| Dual Bowl |
| Single Bowl with Drainboard |
| Residential |
| Commercial |
| Supermarkets/Hypermarkets |
| Exclusive Stores |
| Online |
| Others |
| lle-de-France |
| Provence-Alpes-Cote d'Azur |
| Auvergne-Rhone-Alpes |
| Nouvelle-Aquitaine |
| Hauts-de-France |
| Rest of France (all other metropolitan & overseas regions) |
| By Material | Stainless Steel |
| Quartz | |
| Fireclay | |
| Granite/Marble | |
| Acrylic | |
| Others | |
| By Installation Type | Top-Mount / Drop-In |
| Undermount | |
| Farmhouse / Apron-Front | |
| Flush Mount | |
| Dual Mount | |
| Others | |
| By Bowl Configuration | Single Bowl |
| Dual Bowl | |
| Single Bowl with Drainboard | |
| By End-User | Residential |
| Commercial | |
| By Distribution Channel | Supermarkets/Hypermarkets |
| Exclusive Stores | |
| Online | |
| Others | |
| By Geography | lle-de-France |
| Provence-Alpes-Cote d'Azur | |
| Auvergne-Rhone-Alpes | |
| Nouvelle-Aquitaine | |
| Hauts-de-France | |
| Rest of France (all other metropolitan & overseas regions) |
Key Questions Answered in the Report
What is the forecast growth rate for kitchen sinks in France?
The France kitchen sink market is forecast to grow at a 4.4% CAGR from 2026 to 2031 and is expected to reach USD 224 million by 2031. Renovation activity and a recovery in housing starts support this outlook.
Which material leads kitchen sink sales in France?
Stainless steel led with a 42.3% share in 2025. It remains widely used because it is durable, easy to clean, and offered across value, mid-range, and premium kitchen projects.
Which kitchen sink material is growing fastest in France?
Quartz composite is forecast to grow at a 6.2% CAGR through 2031. Its growth reflects demand for coordinated colors, heat-resistant surfaces, and differentiated finishes in design-led renovations.
What type of installation is most common for French kitchen sinks?
Undermount sinks held a 54.2% share in 2025. The format suits quartz and stone countertops and supports a flush transition between the work surface and basin.
Why are online sink sales growing in France?
Online channels are forecast to grow at an 8% CAGR through 2031. Digital shopping helps buyers compare dimensions, finishes, installation methods, and compatible accessories before making a purchase.