
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Market Size (2026) | USD 24.79 Billion |
| Market Size (2031) | USD 34.83 Billion |
| Growth Rate (2026 - 2031) | 4.02 % |
| Fastest Growing Market | Middle East and Africa |
| Largest Market | Asia-Pacific |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Automotive Steering Sensor Market Analysis by Mordor Intelligence
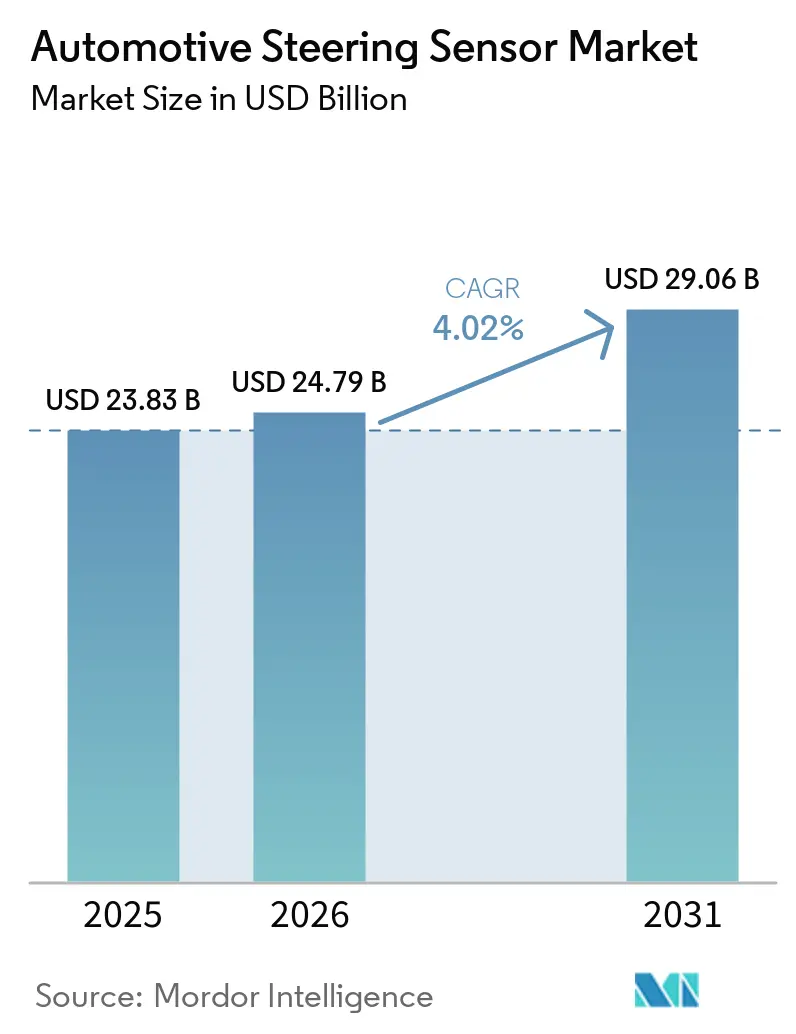
The automotive steering sensor market was valued at USD 23.83 billion in 2025, is estimated at USD 24.79 billion in 2026, and is projected to reach USD 34.83 billion by 2031, registering a 4.02% CAGR during 2026–2031. Continued migration from mechanical steering columns toward electronically controlled systems supports this growth, as automakers increasingly integrate steering sensors into electric power steering (EPS), advanced driver-assistance systems (ADAS), and emerging automated driving platforms. Rising vehicle electrification is further increasing the need for accurate measurements of steering position, torque, and angle to support responsive and efficient control systems.
Key Report Takeaways
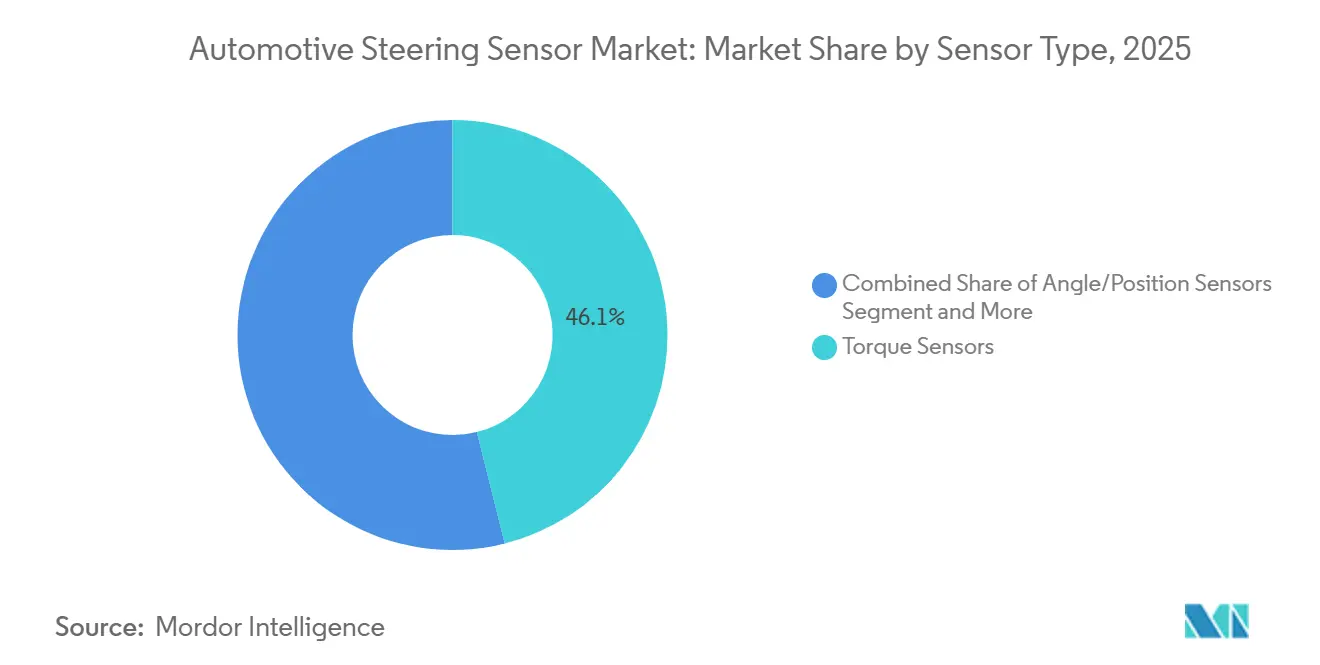
- By sensor type, torque sensors captured 46.10% of the automotive steering sensor market in 2025, whereas capacitive sensing solutions are forecast to grow at a 12.95% CAGR between 2026 and 2031.
- By vehicle type, passenger cars led with 46.85% market share of the automotive steering sensor market in 2025; off-highway vehicles are expected to grow at a 9.75% CAGR through 2031.
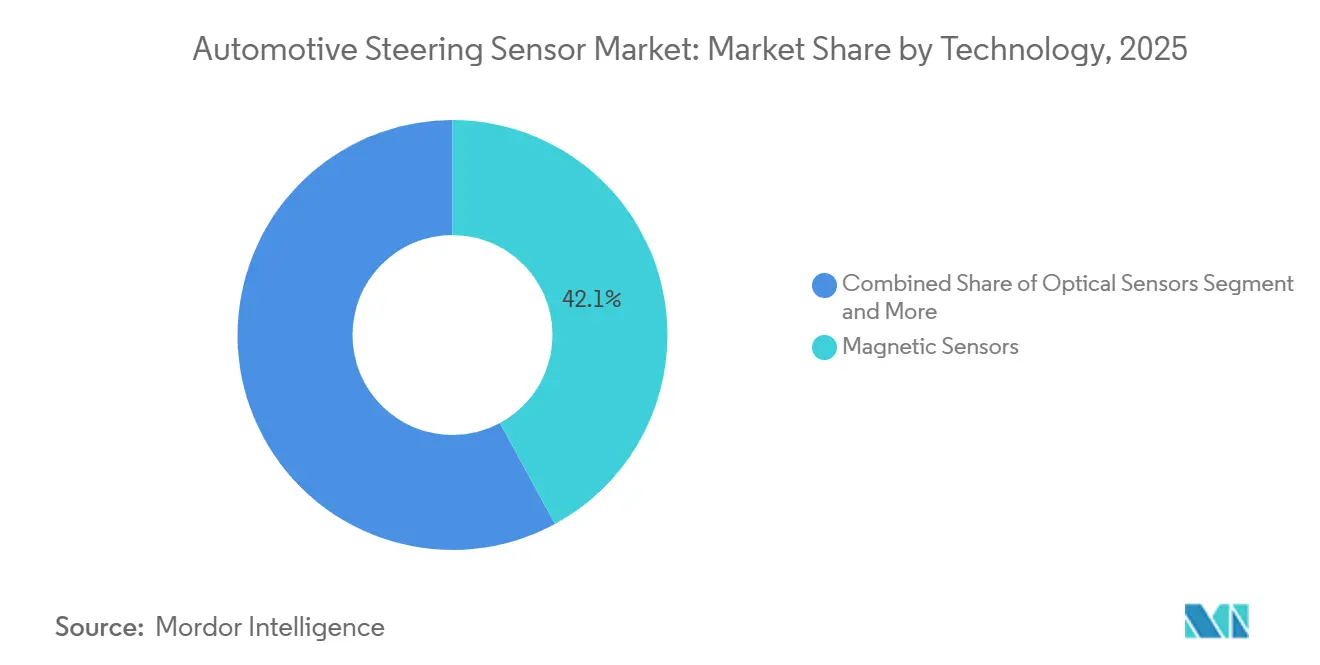
- By technology, magnetic sensors dominated the automotive steering sensor market in 2025 with a 42.15% share, while ultrasonic sensors are estimated to grow at a 13.65% CAGR through 2031.
- By application, steering angle detection accounted for 38.10% of the automotive steering sensor market in 2025, while lane-keeping assistance applications are accelerating at a 14.45% CAGR through 2031.
- By geography, Asia-Pacific accounted for 54.25% of the automotive steering sensor market share in 2025, while the Middle East and Africa are set to expand at an 11.05% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Automotive Steering Sensor Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| EPS Penetration Across Vehicle Classes | +1.2% | Global, with Asia-Pacific leading adoption | Medium term (2–4 years) |
| Mandatory Safety and Fuel-Efficiency Norms | +0.8% | North America and EU regulatory focus | Short term (≤ 2 years) |
| ADAS and Autonomy Sensor Demand | +0.6% | Global, concentrated in premium segments | Long term (≥ 4 years) |
| Modular Steer-by-Wire Retrofits | +0.4% | Europe and North America early adoption | Medium term (2–4 years) |
| Edge-AI Predictive Maintenance Sensors | +0.3% | Asia-Pacific manufacturing hubs, EU fleet operators | Long term (≥ 4 years) |
| Standardized Digital TMR Sensor Interfaces | +0.2% | Global semiconductor ecosystem | Medium term (2–4 years) |
| Source: Mordor Intelligence | |||
EPS Penetration Across Vehicle Classes
Electric power steering adoption accelerates across all vehicle segments. This widespread implementation creates demand for sophisticated torque and angle sensors that enable precise calibration of steering assistance. The technology's expansion into off-highway vehicles represents a paradigm shift, as construction and agricultural equipment manufacturers integrate EPS systems to reduce operator fatigue and improve fuel efficiency. In July 2026, ZF announced the production of its 100 millionth electric power steering (EPS) system, highlighting continued scaling of EPS across passenger cars, SUVs, and light commercial vehicles and indicating strong momentum in this traditionally hydraulically dominated segment.
Mandatory Safety and Fuel-Efficiency Norms
Regulatory frameworks increasingly mandate the integration of advanced steering sensors to meet safety and environmental standards. The European Union's General Safety Regulation requires lane-keeping assistance systems in all new vehicles from 2024[1], directly driving demand for high-precision angle sensors capable of detecting steering wheel movements within 0.1-degree accuracy. Similarly, the United States' Corporate Average Fuel Economy standards incentivize EPS adoption through fuel-efficiency credits, as electric steering systems consume 90% less energy than hydraulic alternatives under typical driving conditions. China's New Energy Vehicle[2] mandate extends these requirements to commercial vehicles, with steering sensor specifications becoming integral to vehicle certification processes. ISO 26262 compliance factors add development complexity but ensure sensor reliability meets automotive safety integrity levels, particularly for ASIL-C and ASIL-D applications in autonomous driving systems[3].
ADAS and Autonomy Sensor Demand
Advanced driver assistance systems create unprecedented demand for multi-axis steering sensors that provide real-time feedback for automated steering interventions. Level 2+ autonomous driving features require sensor fusion architectures where steering sensors complement camera and radar systems to execute precise lane-centering and emergency steering maneuvers. The integration complexity extends beyond hardware to software algorithms that interpret sensor signals for path planning and vehicle dynamics control. Mercedes-Benz reported deploying triple-redundant steering-sensor arrays in its Drive Pilot system, underscoring the reliability requirements for highway automation applications. This redundancy approach becomes standard practice as automakers progress toward Level 3 and Level 4 autonomy, where sensor failures could compromise passenger safety and regulatory compliance.
Modular Steer-by-Wire Retrofits
Steer-by-wire technology eliminates mechanical linkages between the steering wheel and road wheels, enabling flexible vehicle architectures and enhanced safety features. The modular approach enables aftermarket installation on existing vehicle platforms, expanding market opportunities beyond new-vehicle production. This technology requires sophisticated sensor arrays to simultaneously monitor driver intent, vehicle dynamics, and road conditions, creating demand for integrated sensor modules that combine torque, angle, and velocity measurements. The absence of mechanical backup systems places critical importance on sensor reliability and fail-safe operation, driving adoption of tunnel magnetoresistance sensors that offer superior accuracy and durability compared to traditional potentiometric designs. Early adopters in premium vehicle segments demonstrate a 15% improvement in steering precision and a 25% reduction in driver fatigue during extended highway driving.
Restraints Impact Analysis of Automotive Steering Sensor Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Reliability and Qualification Cost | −0.5% | Global, particularly affecting smaller suppliers | Short term (≤ 2 years) |
| EMI/Thermal Issues in 800-V EV Platforms | −0.4% | Europe and China EV manufacturing hubs | Medium term (2–4 years) |
| Tariff-Driven MR Sensor Supply Risk | −0.3% | US–China trade corridor, EU dependencies | Short term (≤ 2 years) |
| Cyber-Security Redesign Cost for CAN FD | −0.3% | Global, concentrated in connected vehicle segments | Medium term (2–4 years) |
| Source: Mordor Intelligence | |||
High Reliability and Qualification Cost
Automotive steering sensor qualification requires extensive testing protocols that can take 18-24 months and cost USD 2-5 million per sensor variant, creating barriers for smaller suppliers and limiting the speed of innovation. The qualification process encompasses temperature cycling from -40°C to 150°C, vibration testing across multiple axes, and electromagnetic compatibility validation under various interference conditions. These requirements particularly affect emerging sensor technologies such as capacitive and ultrasonic designs, for which long-term reliability data remain limited compared to established magnetic sensing approaches. The cost burden forces suppliers to amortize development expenses across larger production volumes, potentially limiting sensor customization for niche applications and constraining market entry for innovative technologies.
EMI/Thermal Issues in 800-V EV Platforms
High-voltage electric vehicle architectures introduce electromagnetic interference challenges that compromise sensor accuracy and require costly shielding solutions. The 800V systems generate switching frequencies up to 20 kHz that can interfere with sensor signal processing, particularly affecting Hall-effect and magnetoresistive designs operating in proximity to power electronics. Thermal management becomes critical as power electronics generate heat loads exceeding 85°C in confined engine bay environments, approaching the operational limits of standard automotive sensor specifications. These challenges drive the adoption of silicon carbide-based power electronics that operate at higher efficiencies but require sensor designs capable of withstanding increased electromagnetic stress and temperature cycling.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Automotive Steering Sensor Market Segment Analysis
By Sensor Type:
Torque Sensors Lead Market TransformationTorque sensors accounted for 46.10% of the automotive steering sensor market share in 2025, a testament to their indispensable role within EPS columns, where real-time driver-effort readings underpin assistance curves. These gauges provide high-resolution analog or digital outputs with latency below 2 ms, enabling a seamless handoff between manual input and motor assist. As cabin layouts evolve toward yoke-style wheels, torque-detection precision remains central to user comfort and perceived steering naturalness in the automotive steering sensor market.
Conversely, capacitive sensors are scaling at a 12.95% CAGR through 2031, driven by contactless electrodes that forgo mechanical parts, thereby improving lifetime in high-duty fleets. Tunnel-magnetoresistance topologies win favor among premium marques for their resilience to stray fields generated by 48 V alternators. At the same time, hybrid modules now bundle TMR and capacitive channels to offer dual-path redundancy. Sensor miniaturization enabled by 65-nm automotive-qualified CMOS enables integration into steering-wheel spokes, freeing up space for airbag modules and touchscreen controls.



By Vehicle Type:
Off-Highway Segment Drives InnovationPassenger cars accounted for 46.85% of the automotive steering sensor market share in 2025, sustained by global light-vehicle volumes and growing ADAS content per unit. Yet off-highway vehicles are advancing at a 9.75% CAGR as construction and agricultural OEMs digitalize field equipment. Bulldozers, excavators, and row-crop tractors integrate GPS-aligned steering automation that requires angle resolution below 0.05 degrees over the full rotation.
These environments impose harsher shock and contamination loads than those on highway cars, accelerating the migration to sealed, contactless sensing stacks. For example, Deere’s latest tractor series integrates dual optical encoders with TMR chips to achieve sub-centimeter pass-to-pass accuracy in autonomous tillage, highlighting cross-sector technology transfer that is now shaping the automotive steering sensor market.
By Technology:
Magnetic Sensors Face Ultrasonic ChallengeMagnetic variants accounted for 42.15% market share in 2025 due to decades-long field reliability and competitive unit cost. Hall-effect and anisotropic MR families remain foundational in EPS torque and angle nodes, but design margins shrink under 800 V harmonic environments. Ultrasonic sensing is expected to grow at a 13.65% CAGR by sidestepping electromagnetic noise through high-frequency acoustic pulses, making it attractive for shieldless EV packaging.
Optical encoders are used in steer-by-wire columns that require sub-millisecond reaction times, though their fragile emitters have historically limited their adoption in high-vibration environments. Capacitive discs are gaining momentum in luxury interiors, where designers value thin profiles and integrated illumination. Contact potentiometers see a gradual sunset due to wear over 100,000 steering cycles. Yet they survive in cost-sensitive emerging-market models where price trumps lifetime in the automotive steering-sensor market.

By Application:
Lane-Keeping Systems Accelerate GrowthSteering angle detection accounted for 38.10% of the automotive steering sensor market in 2025, underpinning both human and machine guidance loops. Automated parking and adaptive front steering further extend addressable demand by requiring continuous angle monitoring at low speeds and dynamic changes in steering ratio.
Lane-keeping assistance is expected to be the fastest-growing application, with a 14.45% CAGR, driven by mandatory safety regulations on both sides of the Atlantic. Triple-redundant angle encoders in Level 3 highway-pilot programs feed model-predictive controllers that supervise trajectory maintenance even during sudden crosswinds. Torque and velocity feedback complement camera-radar data to enforce lateral bounds without abrupt corrections, cementing sensors' role as guardians of occupant comfort and regulatory compliance within the broader automotive steering sensor market.
Geography Analysis
APAC Automotive Steering Sensor Market
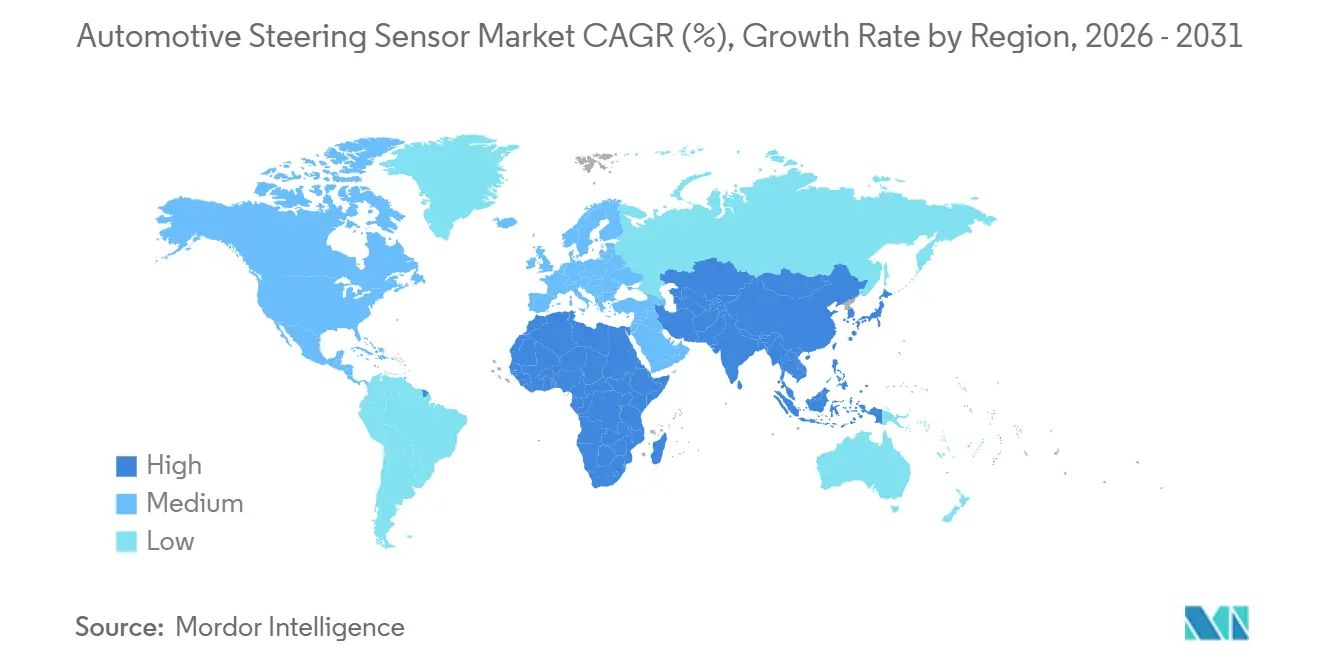
Asia-Pacific dominates the automotive steering sensor market with a 54.25% share in 2025, driven by China's position as the world's largest automotive producer and its aggressive electric vehicle adoption targets. The region benefits from established automotive supply chains and government policies promoting vehicle electrification, creating sustained demand for advanced steering sensor technologies. China's New Energy Vehicle mandate requires 40% of new vehicle sales to be electric by 2030, directly driving EPS and steering sensor adoption across all vehicle segments. India's automotive sector contributes significantly through both domestic consumption and export manufacturing, with companies like Tata Motors and Mahindra integrating advanced steering systems in commercial vehicle platforms. Japan maintains technology leadership through companies like NSK and JTEKT that develop innovative sensor solutions for global automotive markets.
MEA Automotive Steering Sensor Market
The Middle East and Africa represent the fastest-growing regional market at 11.05% CAGR through 2031, reflecting economic diversification efforts and infrastructure development programs that drive commercial vehicle demand. The United Arab Emirates leads regional adoption through its smart city initiatives and autonomous vehicle testing programs that require advanced sensor technologies. Saudi Arabia's Vision 2030 program includes automotive manufacturing development, creating opportunities for steering sensor suppliers to establish local production capabilities. South Africa's automotive industry benefits from established manufacturing infrastructure and preferential trade agreements that support export-oriented production of steering system components.
Europe and North America Automotive Steering Sensor Market
Europe maintains strong market presence through stringent safety regulations and premium vehicle production that demands high-performance steering sensor solutions. The region's focus on autonomous driving development creates demand for redundant sensor architectures and advanced signal processing capabilities. Germany's automotive industry leadership drives innovation in steering sensor technologies, with companies like Continental and ZF developing next-generation solutions for electric and autonomous vehicles. North America demonstrates steady growth driven by regulatory requirements for advanced safety systems and the transition toward electric vehicle platforms that require sophisticated steering control technologies.
Regional Editions
Competitive Landscape
Market Concentration
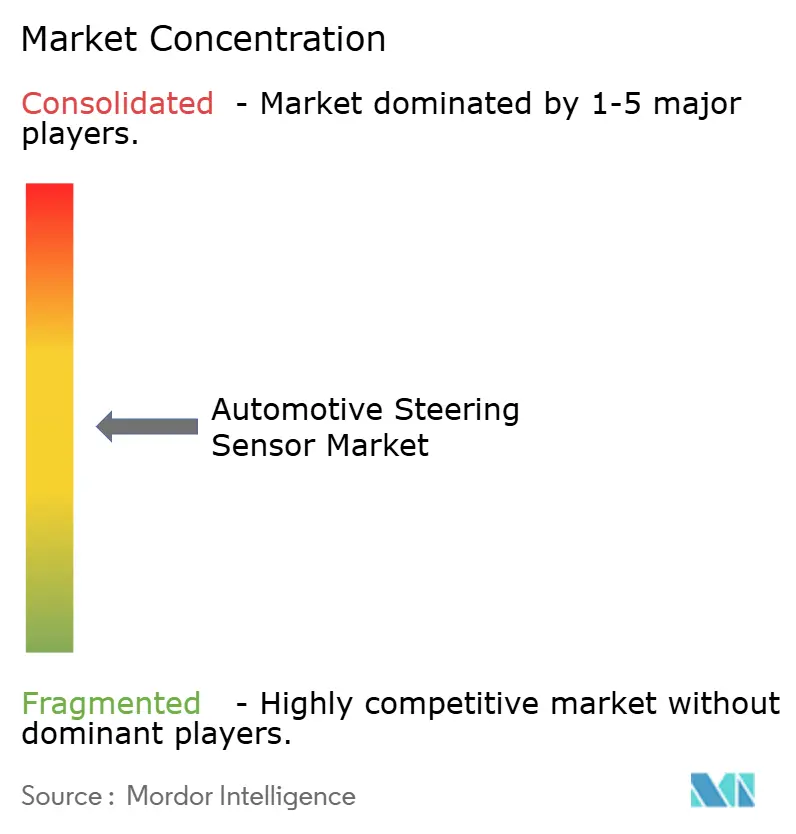
The automotive steering sensor market exhibits moderate fragmentation, with competition spanning traditional automotive suppliers, semiconductor companies, and emerging technology specialists. Market concentration remains distributed across multiple tiers, with established players like JTEKT Corporation and Robert Bosch GmbH leveraging system integration expertise, while semiconductor specialists, including Infineon Technologies and Texas Instruments, focus on sensor IC development and signal-processing solutions. This multi-tier structure creates opportunities for vertical integration and strategic partnerships that combine mechanical engineering capabilities with advanced semiconductor technologies.
Technology differentiation emerges as the primary competitive strategy, with companies investing heavily in contactless sensing technologies, edge-AI integration, and predictive maintenance capabilities that extend beyond traditional sensor functions. The convergence of mechanical and electronic expertise creates white-space opportunities for companies that can bridge hardware and software domains, particularly in applications requiring real-time sensor fusion and adaptive control algorithms.
Patent activity intensifies around tunnel magnetoresistance sensing and capacitive measurement techniques, with Infineon Technologies filing 47 steering-sensor-related patents in 2024. Emerging disruptors focus on software-defined sensor architectures that enable over-the-air updates and customization, challenging traditional hardware-centric approaches to sensor design and manufacturing.
Automotive Steering Sensor Industry Leaders
-
Robert Bosch GmbH
-
DENSO Corporation
-
AISIN CORPORATION
-
NXP Semiconductors N.V.
-
FORVIA HELLA
- *Disclaimer: Major Players sorted in no particular order
Automotive Steering Sensor Market Companies Covered in this Report
- JTEKT Corporation
- Robert Bosch GmbH
- Nexteer Automotive
- NSK Ltd.
- ZF Friedrichshafen AG
- Mitsubishi Electric Mobility Corporation
- Hitachi Astemo Ltd.
- ThyssenKrupp AG
- Hyundai Mobis Co. Ltd.
- HL Mando Corporation
- China Automotive Systems Inc.
- Valeo SA
- Infineon Technologies AG
- Texas Instruments Inc.
- Analog Devices Inc.
- NXP Semiconductors N.V.
- Sensata Technologies
- TE Connectivity Ltd.
- Denso Corporation
- FORVIA HELLA
- Continental AG
Recent Industry Developments in Automotive Steering Sensor Market
- August 2026: Nexteer launched its High Mount Direct Drive Steer-by-Wire Hand-Wheel Actuator (HMDD), a compact architecture designed for software-defined vehicles and flexible steering-wheel packaging. HMDD directly converts the driver’s steering input into an electronic signal, eliminating the conventional mechanical connection between the steering wheel and road wheels.
- April 2026: Mercedes-Benz announced that its new EQS would become available with steer-by-wire technology just a few months after its market launch, making Mercedes-Benz the first German automaker to offer steer-by-wire in a series-production vehicle. The technology is available across the EQS powertrain range and in combination with the vehicle's 10-degree rear-axle steering.
Global Automotive Steering Sensor Market Report Scope
Steering sensors are designed for monitoring and operation of the steering system and driver monitoring purposes. These steering sensors are located in the steering column and help to send crucial data regarding drivers' drowsiness, wheel angle, and wheel positioning to the computer onboard the car.
The Automotive Steering Sensors Market is segmented by Sensor Type (Torque Sensors, Angle/Position Sensors, Velocity Sensors, and Others), Vehicle Type (Passenger Cars, Light Commercial Vehicles, Medium and Heavy Commercial Vehicles, and Off-Highway Vehicles), Technology (Contacting Sensors, Magnetic Sensors, Optical Sensors, Ultrasonic Sensors, Capacitive Sensors, and Others), Application (Steering Angle Detection, Steering Torque Measurement, Steering Position Tracking, Autonomous Emergency Steering, and Adaptive Front Steering), and Geography (North America, South America, Europe, Asia-Pacific, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
By Sensor Type
| Torque Sensors |
| Angle/Position Sensors |
| Velocity Sensors |
| Others |
By Vehicle Type
| Passenger Cars |
| Light Commercial Vehicles |
| Medium and Heavy Commercial Vehicles |
| Off-Highway Vehicles |
By Technology
| Contacting Sensors |
| Magnetic Sensors |
| Optical Sensors |
| Ultrasonic Sensors |
| Capacitive Sensors |
| Others |
By Application
| Steering Angle Detection |
| Steering Torque Measurement |
| Steering Position Tracking |
| Autonomous Emergency Steering |
| Adaptive Front Steering |
By Geography
| North America | United States |
| Canada | |
| Rest of North America | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Spain | |
| Rest of Europe | |
| Asia-Pacific | China |
| India | |
| Japan | |
| South Korea | |
| Rest of Asia-Pacific | |
| Middle East and Africa | United Arab Emirates |
| Saudi Arabia | |
| South Africa | |
| Turkey | |
| Rest of Middle East and Africa |
| By Sensor Type | Torque Sensors | |
| Angle/Position Sensors | ||
| Velocity Sensors | ||
| Others | ||
| By Vehicle Type | Passenger Cars | |
| Light Commercial Vehicles | ||
| Medium and Heavy Commercial Vehicles | ||
| Off-Highway Vehicles | ||
| By Technology | Contacting Sensors | |
| Magnetic Sensors | ||
| Optical Sensors | ||
| Ultrasonic Sensors | ||
| Capacitive Sensors | ||
| Others | ||
| By Application | Steering Angle Detection | |
| Steering Torque Measurement | ||
| Steering Position Tracking | ||
| Autonomous Emergency Steering | ||
| Adaptive Front Steering | ||
| By Geography | North America | United States |
| Canada | ||
| Rest of North America | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Spain | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| India | ||
| Japan | ||
| South Korea | ||
| Rest of Asia-Pacific | ||
| Middle East and Africa | United Arab Emirates | |
| Saudi Arabia | ||
| South Africa | ||
| Turkey | ||
| Rest of Middle East and Africa | ||
Key Questions Answered in the Report
How large is the automotive steering sensors market in 2025?
The automotive steering sensors market size was valued at USD 23.83 billion in 2025.
What CAGR is projected for steering sensors through 2031?
Market value is forecast to grow at a 4.02% CAGR between 2026 and 2031.
Which region currently leads demand for steering sensors?
Asia-Pacific captured 54.25% of global market share in 2025, propelled by China’s EV build-out.
Which sensor type holds the biggest share today?
Torque sensors captured 46.10% market share in 2025 owing to their central role in EPS systems.
Which application segment is growing the quickest?
Lane-keeping assistance is the fastest-expanding application with a 14.45% CAGR through 2031.