
Market Overview
| Study Period | 2021 - 2031 |
|---|---|
| Market Size (2026) | USD 3.17 Billion |
| Market Size (2031) | USD 4.67 Billion |
| Growth Rate (2026 - 2031) | 8.06 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | Asia-Pacific |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Polyphenylene Sulfide (PPS) Composite Market Analysis by Mordor Intelligence
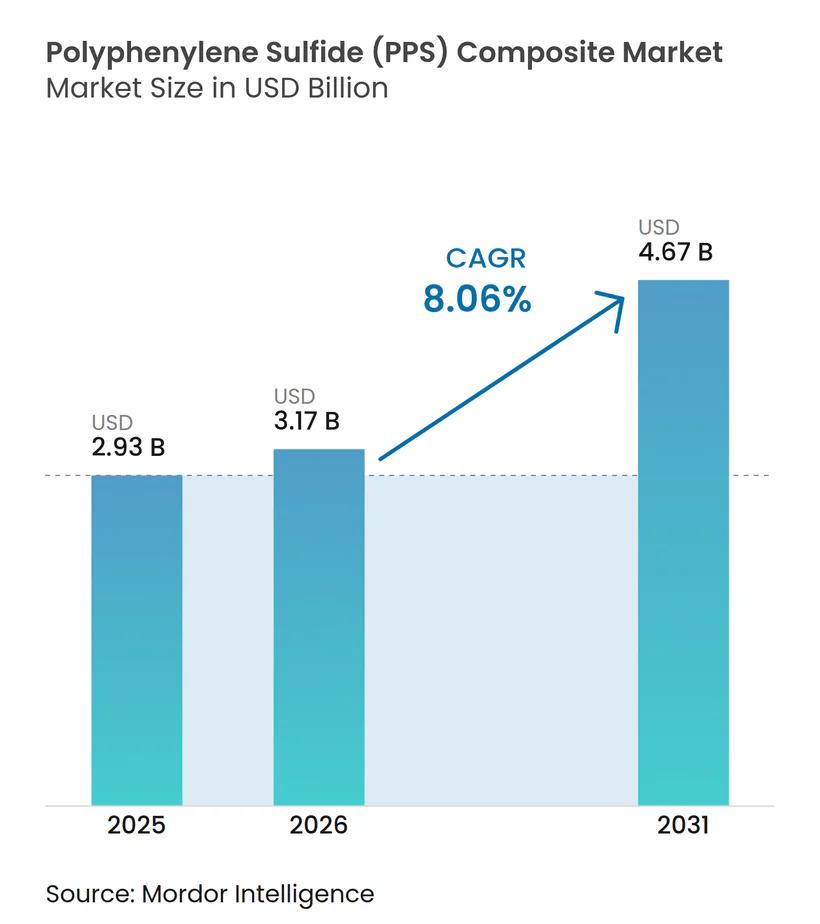
The Polyphenylene Sulfide (PPS) Composite Market size was valued at USD 2.93 billion in 2025 and is estimated to grow from USD 3.17 billion in 2026 to reach USD 4.67 billion by 2031, at a CAGR of 8.06% during the forecast period (2026-2031). Demand is being shaped by electric vehicle battery systems, compact high-frequency electronics, and hydrogen infrastructure, all of which require materials that can tolerate heat, chemicals, and electrical stress through extended service periods. PPS composites offer continuous-use capability at 200 °C to 240 °C, inherent UL 94 V-0 flame retardancy, and resistance to automotive coolants and battery electrolytes, which makes them relevant where a component cannot be redesigned around a lower-performance polymer. The polyphenylene sulfide (PPS) composite market is becoming more dependent on Asian production and consumption networks, since the Asia-Pacific region represented 62.87% of the value in 2025. Resin producers are expanding capacity and developing specialized grades, while compounders are adapting materials for vehicle, electronics, filtration, and energy applications that require distinct combinations of stiffness, electrical performance, and chemical resistance. This creates a business environment across the value chain for customers and suppliers alike in which material selection is linked to component design, production methods, regulatory compliance, and the ability to keep critical systems operating reliably over their planned service life. Cost pressure, equipment corrosion, and competition from high-temperature polyamides continue to influence material selection in applications with lower thermal requirements, especially where manufacturers weigh process economics against long-term component reliability.
Key Report Takeaways
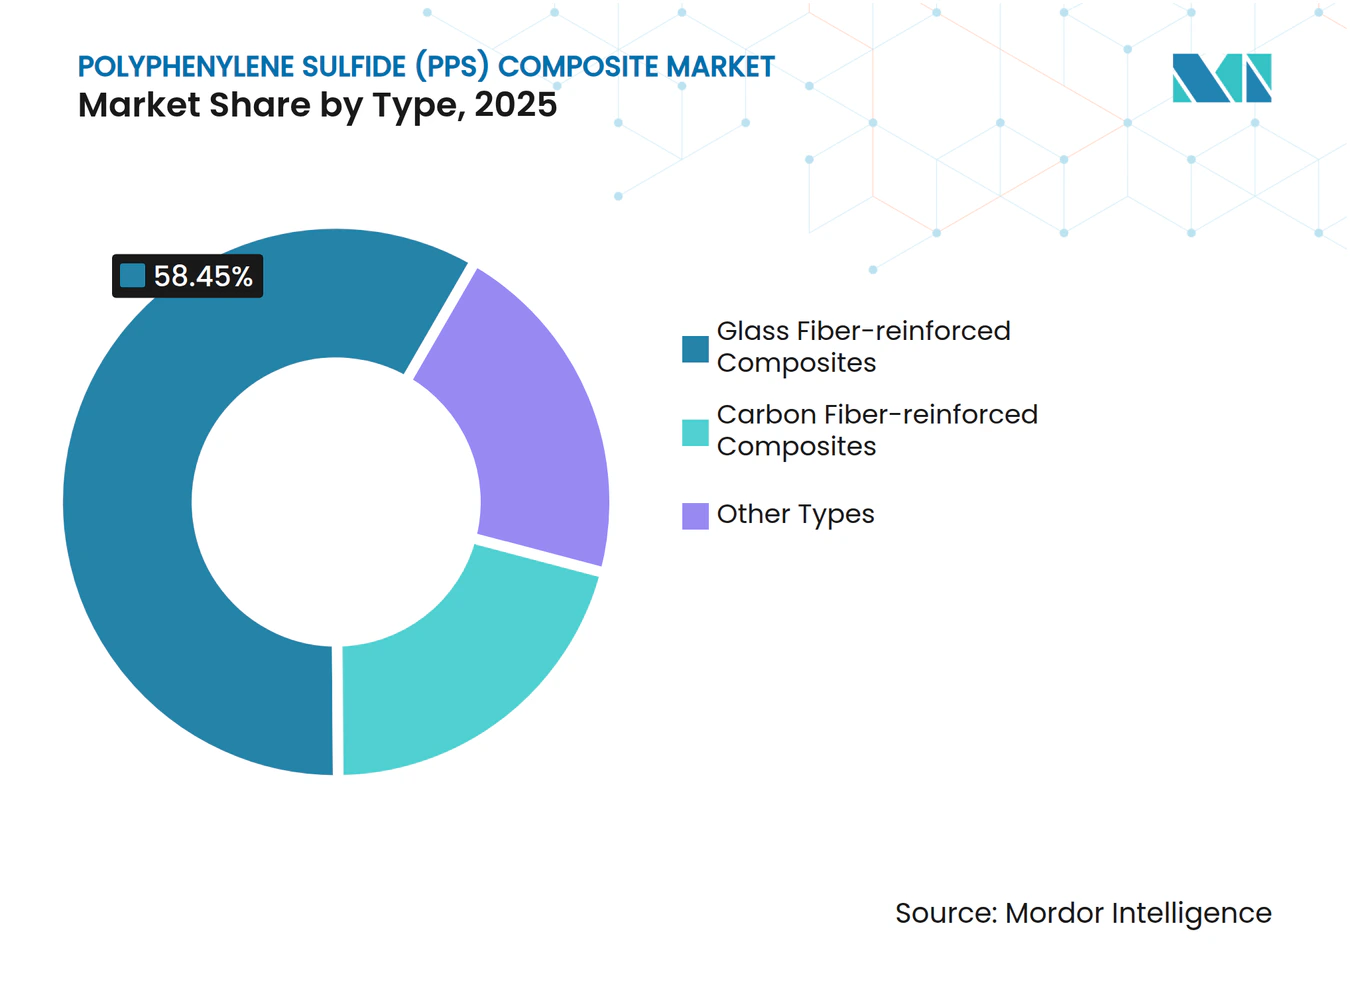
- By type, glass fiber-reinforced composites held 58.45% of the polyphenylene sulfide (PPS) composite market share in 2025, while carbon fiber-reinforced composites are projected to advance at an 8.75% CAGR through 2031.
- By form, molding compounds held 68.03% of the polyphenylene sulfide (PPS) composite market share in 2025, while films are projected to advance at a 9.13% CAGR through 2031.
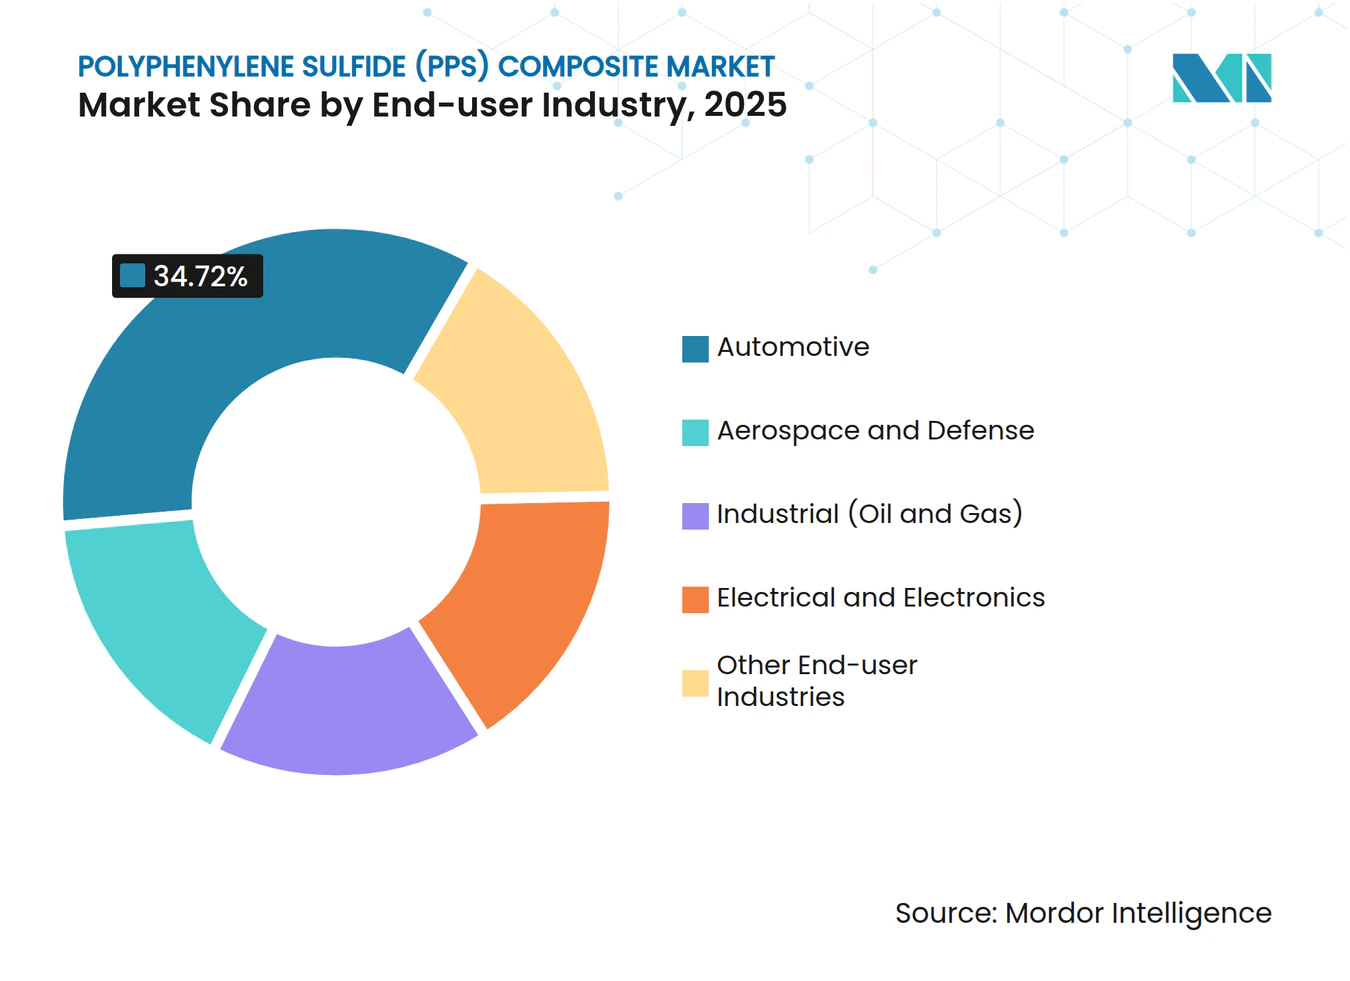
- By end-user industry, automotive held 34.72% of the polyphenylene sulfide (PPS) composite market share in 2025, while aerospace and defense are projected to advance at a 9.36% CAGR through 2031.
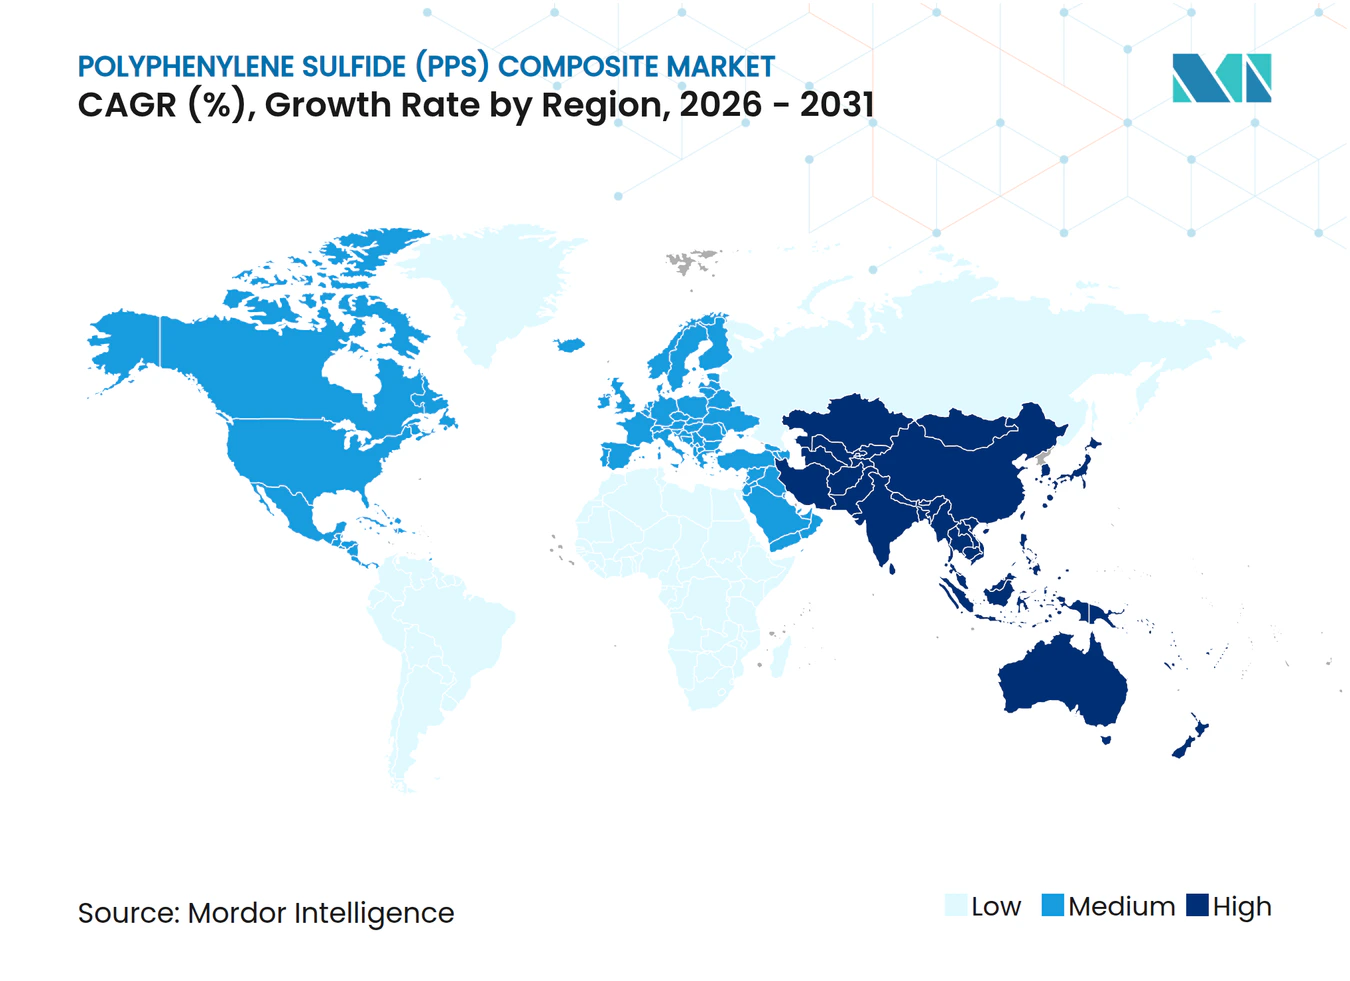
- By geography, Asia-Pacific held 62.87% of the polyphenylene sulfide (PPS) composite market share in 2025 and is projected to advance at a 9.21% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Polyphenylene Sulfide (PPS) Composite Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| EV Battery Thermal Management Integration | +2.3% | Global, with concentration in Asia-Pacific (China, South Korea, Japan) and early momentum in North America and Germany | Short term (≤ 2 years) |
| Metal Replacement and Part Consolidation | +1.8% | Global; strongest in Asia-Pacific automotive OEM clusters and European lightweighting programs | Medium term (2–4 years) |
| Miniaturized High-Frequency Electronics | +1.4% | Asia-Pacific core (China, Japan, South Korea, ASEAN); spillover to North America and Europe data-center supply chains | Medium term (2–4 years) |
| High-Temperature Filtration Upgrades | +0.9% | Asia-Pacific (China, India), Europe; driven by air-quality regulation in coal power and waste incineration | Medium term (2–4 years) |
| Hydrogen Fuel-Cell Balance-of-Plant Adoption | +0.6% | Europe (Germany, NORDIC Countries), Japan, South Korea; expanding to China and North America | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
EV Battery Thermal Management Integration
Thermal management has become a major performance requirement in lithium-ion battery system design. PPS composites are used in coolant pump housings, thermostat bodies, and connector overmolds that operate at 180 °C to 260 °C while contacting water-glycol mixtures in tightly packaged battery systems. Envalior reported in May 2025 that its glass-fiber-reinforced Xytron G4080HR PPS grade showed minimal delamination after 3,000 hours in water-glycol coolant at 135 °C[1]. Each battery pack requires multiple thermally stable polymer parts, including structural brackets, thermal barriers, electrical isolators, and cooling-system components, so that qualification decisions may affect several component families at once. This requirement increases PPS composite content per electric vehicle and supports automotive-grade glass fiber-reinforced composites in the polyphenylene sulfide (PPS) composite market.
Miniaturized High-Frequency Electronics
Fifth-generation (5G) millimeter-wave networks and artificial intelligence inference infrastructure require substrates and connectors with low dielectric loss, reliable signal transmission, and stable properties at high frequencies. PPS derivatives can deliver dielectric constants below 3.0 and dissipation factors below 0.003 at frequencies of 10 gigahertz and above. A 2025 Communications Materials study reported a dissipation factor of 0.00087 at 10 gigahertz and a dielectric constant of 2.80 for poly(2,6-dimethyl-1,4-phenylene sulfide). DIC CORPORATION and Unitika Ltd. announced a PPS film in October 2024 that was engineered to reduce transmission loss at millimeter-wave frequencies from 30 to 300 gigahertz[2]. The material was being prepared for commercial production for next-generation communication devices and automotive radar, where the choice of substrate affects the usable performance window of the finished hardware.
Metal Replacement and Part Consolidation
PPS composites can reduce component weight by 15% to 30% compared with aluminum and steel assemblies while maintaining dimensional stability above 200 °C. A 10% reduction in vehicle weight typically translates into an 8% improvement in fuel economy, which supports the business case for replacing several metal parts with a consolidated polymer component. Molding compounds support part consolidation because injection molding can combine brackets, housings, and functional inserts into a single component. Glass fiber loading of 30% to 40% can provide heat-deflection temperatures approaching 260 °C while retaining usable stiffness and dimensional control. Long-carbon-fiber PPS compounds have enabled 40% to 50% weight savings in some turbocharger applications compared with metal alternatives, expanding the range of parts that can be considered for replacement. These manufacturing and weight benefits support the role of automotive applications in the polyphenylene sulfide (PPS) composite market.
High-Temperature Filtration Upgrades
Industrial filtration supports demand where particulate-emission rules apply to coal power, waste incineration, and cement production. PPS needle-punched filter felts can operate continuously at 190 °C and resist sulfur dioxide, hydrogen chloride, and ammonia in operating conditions that can shorten the service life of less resistant media. They can provide filtration efficiencies above 99.9% for particulate matter with a diameter of 2.5 micrometers. A 2025 study in Environmental Science & Technology reported that a PPS gradient filtration material extended average cleaning cycles by 188.13 seconds and reduced average residual resistance by 41.84 pascals against commercial polytetrafluoroethylene membrane-lamination media. China’s Ultra-Low Emission policy and India’s particulate limits below 30 milligrams per normal cubic meter are supporting baghouse upgrades across heavy industry, where replacement timing can be as important as first-time equipment installations. These replacement cycles broaden the industrial base of the polyphenylene sulfide (PPS) composite market.
Restraints Impact Analysis of Polyphenylene Sulfide (PPS) Composite Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Material and Processing Cost | -1.4% | Global; most acute in North America and Europe where processing equipment retrofits are capital-intensive | Short term (≤ 2 years) |
| Competition from High-Temperature Polyamides | -0.9% | Global; strongest in automotive connector applications in North America, EU, and Japan | Medium term (2–4 years) |
| Corrosion-Sensitive Processing Equipment | -0.5% | Global; disproportionately affects mid-tier compounders in Asia-Pacific and South America | Medium term (2–4 years) |
| Source: Mordor Intelligence | |||
High Material and Processing Cost
PPS composite processing requires melt temperatures above 300 °C and specialized compounding equipment. Stainless-steel or bimetallic barrel-and-screw assemblies are required because PPS can release sulfur compounds that corrode standard steel hardware. Chinese PPS compound prices ranged from USD 3.00 to USD 3.80 per kilogram, compared with USD 1.80 to USD 2.20 per kilogram for polyamide 66 with 30% glass fiber. Retrofitting a standard compounding line with corrosion-resistant tooling can require capital expenditure of millions of USD per line, which increases the cost of serving new or lower-volume programs. Cost-sensitive original equipment manufacturer programs continue to assess other materials where the required performance does not justify PPS processing costs.
Competition from High-Temperature Polyamides
Polyphthalamide grades have reached a Comparative Tracking Index of 600 V and UL 94 V-0 certification at a thickness of 0.4 mm. Their continuous-use temperatures of 150 °C to 160 °C overlap with PPS requirements in some automotive connector applications. Newer grades can be processed at mold temperatures of 90 °C to 110 °C, compared with 130 °C to 160 °C for PPS, which can improve cycle economics for high-throughput molding operations. Celanese Corporation identified high-temperature polyamides as a competitive force in automotive connector procurement in its annual report for the year ended December 31, 2024. The substitution risk is most pronounced below 160 °C, where PPS has less clear thermal differentiation. Polyphthalamide price quotations of USD 6.50 to USD 9.00 per kilogram can become more competitive once energy use, tooling wear, and processing yield are considered.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Polyphenylene Sulfide (PPS) Composite Market Segment Analysis
By Type:
Glass Fiber-reinforced Composites Gain Demand, While Carbon Fiber-reinforced Composites AccelerateGlass fiber-reinforced composites held 58.45% of the polyphenylene sulfide (PPS) composite market share in 2025, supported by established processing practices in automotive, electrical, and industrial filtration applications. Glass fiber loading of 30% to 40% enables heat-deflection temperatures close to 260 °C and helps components retain dimensional stability during coolant or chemical exposure. These grades remain a practical choice for high-volume injection-molded parts because established tooling and material specifications reduce the time needed to introduce a qualified component. They are used in cooling systems, electrical connectors, pump bodies, and other components that require heat resistance with manageable material cost. The broad application base supports continued demand for this type across established end uses and gives suppliers a durable base for grade development.
Carbon fiber-reinforced composites are projected to advance at an 8.75% CAGR through 2031, supported by aerospace qualification activity and demand for lightweight electric vehicle battery enclosures. Continuous carbon fiber PPS composites can be welded, thermoformed, and recycled, unlike thermoset carbon-epoxy materials. This processing flexibility supports manufacturers that are seeking to reduce part counts and production waste without giving up the stiffness required for structural or semi-structural components. It also enables applications that require high stiffness with lower component weight, which broadens the role of continuous-fiber formats in the polyphenylene sulfide (PPS) composite market.



By Form:
Molding Compounds Lead, While Films Support GrowthMolding compounds accounted for 68.03% of the polyphenylene sulfide (PPS) composite market size in 2025, reflecting the scale of injection molding in automotive and electrical manufacturing. Their formulations can vary by glass fiber content from 10% to 65%, mineral filler additions, and flame-retardant packages. This flexibility lets one material platform support multiple parts across a vehicle portfolio, while allowing compounders to tailor a grade to the duty cycle of a specific component. It also reduces the need for procurement teams to qualify unrelated materials under demanding development schedules. Molding compounds remain central to applications that require consistent dimensions, chemical resistance, and efficient production.
Films are projected to advance at a 9.13% CAGR through 2031 as 5G base stations and millimeter-wave radar systems require high-frequency substrates. These applications require low transmission loss and resistance to demanding processing temperatures, which places greater weight on dielectric stability during both manufacturing and use. DIC CORPORATION and Unitika Ltd. announced in October 2024 that their PPS film offered stable dielectric properties from 10 to 1,000 gigahertz, reflow resistance, and sputtering-compatible copper adhesion. Sheets and plates support aerospace and industrial uses that require machined precision.
By End-User Industry:
Aerospace and Defense Advances While Automotive Anchors DemandAutomotive held 34.72% of the polyphenylene sulfide (PPS) composite market share in 2025. Electric vehicle platforms use PPS composites in thermal-management parts, high-voltage connector bodies, and busbar overmolds. These applications need consistent performance above 150 °C in environments that combine heat, vibration, electrical loading, and chemical exposure. Metal replacement and part consolidation also support PPS use in underhood and battery-system components. The automotive base provides predictable demand for glass fiber-reinforced molding grades and remains an important reference point for suppliers expanding vehicle-specific grades.
Aerospace and defense are projected to advance at a 9.36% CAGR through 2031, driven by the continued qualification of continuous carbon fiber PPS laminates in aircraft structures and defense electronics. PPS composites have been qualified for Airbus A350 fuselage connectors and bracket applications, including continuous carbon fiber PPS systems that connect composite frame structures to fuselage wall panels. Testing of Teijin Carbon America's carbon fiber PPS materials supported Supernal LLC's aircraft structure development in 2025. Electrical and electronics demand is supported by PPS moisture absorption below 0.05%, which helps preserve signal stability in high-humidity 5G base-station settings. Industrial oil and gas applications use PPS for resistance to hydrogen sulfide, crude oil, and downhole chemicals in pump components and valve bodies, where material durability affects maintenance requirements.

Geography Analysis
APAC Polyphenylene Sulfide (PPS) Composite Market
Asia-Pacific held 62.87% of the polyphenylene sulfide (PPS) composite market share in 2025 and is projected to advance at a 9.21% CAGR through 2031. China has the largest electric vehicle production base and uses PPS composite thermal barriers, structural brackets, and coolant-system connectors in battery packs. The region combines resin production, compounding capacity, and end-use manufacturing, which shortens supply paths between material qualification and component production. Japan and South Korea remain important sources of high-grade PPS resin through multi-plant systems operated by TORAY INDUSTRIES, INC., DIC CORPORATION, KUREHA CORPORATION, and SK chemicals. This regional production base reinforces Asia-Pacific’s role in the polyphenylene sulfide (PPS) composite market.
China’s expanding capacity is increasing import substitution in mid-grade automotive and industrial composites. NHU PM is targeting a total PPS production of 30,000 metric tons per year through its Phase IV project. Dongtai Qixin began construction of an 80,000-metric-tons-per-year PPS resin project in Huangshan, Anhui Province, in August 2025. The project had a Phase I investment of CNY 1.6 billion (approximately USD 220 million). This capacity expansion is raising competitive pressure on Japanese and Korean producers in downstream applications.
The Americas and EMEA Polyphenylene Sulfide (PPS) Composite Market
North America’s demand is supported by aerospace and defense procurement, automotive thermal management, and industrial filtration. Syensqo expanded its Ryton PPS compounding capability in Augusta, Georgia, in May 2025 at an International Automotive Task Force 16949-certified site. Europe benefits from automotive electrification in Germany and France, and aerospace composites in the United Kingdom and France. South America and the Middle East and Africa are projected to remain modest contributors through 2031, although Saudi Arabia’s energy investment supports demand for refinery and desalination components.
Regional Editions
Competitive Landscape
Market Concentration
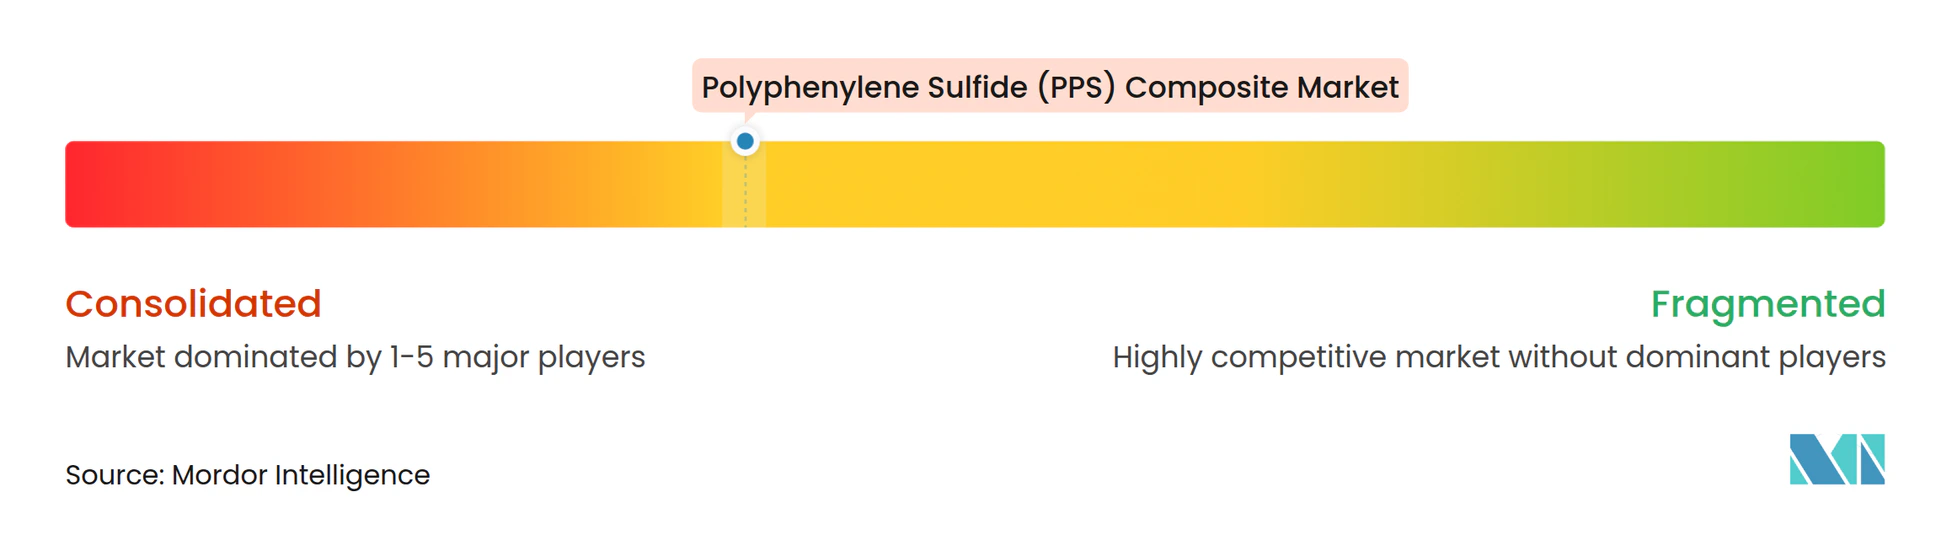
The polyphenylene sulfide (PPS) composite market is moderately concentrated, with the top five players including TORAY INDUSTRIES, INC., Solvay, DIC Corporation, Celanese Corporation, and KUREHA CORPORATION. Competition at the resin level centers on capacity, grade breadth, and original equipment manufacturer qualifications, since qualification history can be difficult to reproduce quickly in high-performance applications. At the compounding level, Chinese producers such as NHU PM, SK Chemicals, and independent specialty compounders compete on local supply and application-specific formulations.
Celanese Corporation launched Fortron PPS ECO-R in October 2025 as an International Sustainability and Carbon Certification PLUS-certified recycled-content grade made through a mass-balance approach. The company also introduced a PPS grade for high-pressure electric vehicle cooling tubes at the same event. These moves show how suppliers are using sustainability claims and application-specific grades to support new customer qualifications, rather than relying solely on a broader base resin offering. They also create opportunities for established producers to build on existing vehicle and electronics relationships. Competition remains active as suppliers balance material performance, qualification requirements, and customer cost targets.
Patent activity in bipolar plates, battery separators, and high-frequency substrate resins is creating new competition in the polyphenylene sulfide (PPS) composite market, particularly where a supplier can combine polymer chemistry with the application knowledge needed to meet narrowly specified performance targets. Smaller participants such as Ensinger and RTP Company compete in precision-machined and specialty-compounded grades, where application engineering, low minimum order quantities, rapid technical support, and the ability to modify a formulation for an individual part can matter more than a broad production footprint. IDEMITSU FINE COMPOSITES CO., LTD. and Teijin Limited supply continuous-fiber aerospace thermoplastic composites that differ from commodity injection-molding grades, reflecting the separation between high-volume parts and the smaller group of applications that need advanced reinforcement formats. The polyphenylene sulfide (PPS) composite market, therefore, includes large resin suppliers and smaller businesses focused on narrowly defined technical requirements, with different customer relationships, production models, qualification cycles, and approaches to product development, giving customers a choice between scale-oriented material platforms and specialized suppliers that work closely with component designers during development.
Polyphenylene Sulfide (PPS) Composite Industry Leaders
-
Celanese Corporation
-
TORAY INDUSTRIES, INC.
-
Solvay
-
DIC CORPORATION
-
KUREHA CORPORATION
- *Disclaimer: Major Players sorted in no particular order
Polyphenylene Sulfide (PPS) Composite Market Companies Covered in this Report
- Avient Corporation
- Celanese Corporation
- DIC CORPORATION
- Ensinger
- IDEMITSU FINE COMPOSITES CO., LTD.
- KUREHA CORPORATION
- LG Chem
- NHU PM
- RTP Company
- SABIC
- SK chemicals
- Solvay
- TEIJIN LIMITED
- TORAY INDUSTRIES, INC.
- Tosoh Corporation
Recent Industry Developments in Polyphenylene Sulfide (PPS) Composite Market
- September 2026: Syensqo announced a new compounding line at its Panoli, India site for high-performance aromatic polymers, including Ryton polyphenylene sulfide (PPS), with operations planned for Q1 2028. The investment will double the site’s compounding capacity and strengthen local PPS compound supply for automotive and other high-performance applications.
- June 2026: TORAY INDUSTRIES, INC. announced plans to establish a 3,000-ton-per-year TORELINA PPS resin compounding facility at its Sri City site in Andhra Pradesh, with operations expected to begin in early 2027. The facility will strengthen localized PPS compound supply for India’s growing automotive and engineering plastics applications.
Global Polyphenylene Sulfide (PPS) Composite Market Report Scope
Polyphenylene sulfide (PPS) composites are high-performance engineering materials that combine PPS resin with reinforcing materials to improve mechanical strength, dimensional stability, thermal resistance, and chemical resistance. They are used where durable and lightweight materials are required to withstand demanding operating conditions.
The Polyphenylene Sulfide (PPS) Composite Market is segmented by type, form, end-user industry, and geography. By type, the market is segmented into glass fiber-reinforced composites, carbon fiber-reinforced composites, and other types. By form, the market is segmented into molding compounds, films, sheets and plates, and other forms. By end-user industry, the market is segmented into automotive, aerospace and defense, industrial (oil and gas), electrical and electronics, and other end-user industries. The report also covers the market size and forecasts for polyphenylene sulfide (PPS) composites across 15 countries. For each segment, the market sizing and forecasts have been done on the basis of value (USD).
Segmentation Overview
By Type
| Glass Fiber-reinforced Composites |
| Carbon Fiber-reinforced Composites |
| Other Types |
By Form
| Molding Compounds |
| Films |
| Sheets and Plates |
| Other Forms |
By End-user Industry
| Automotive |
| Aerospace and Defense |
| Industrial (Oil and Gas) |
| Electrical and Electronics |
| Other End-user Industries |
By Geography
| Asia-Pacific | China |
| India | |
| Japan | |
| South Korea | |
| ASEAN Countries | |
| Rest of Asia-Pacific | |
| North America | United States |
| Canada | |
| Mexico | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| NORDIC Countries | |
| Rest of Europe | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Middle East and Africa | Saudi Arabia |
| South Africa | |
| Rest of Middle East and Africa |
| By Type | Glass Fiber-reinforced Composites | |
| Carbon Fiber-reinforced Composites | ||
| Other Types | ||
| By Form | Molding Compounds | |
| Films | ||
| Sheets and Plates | ||
| Other Forms | ||
| By End-user Industry | Automotive | |
| Aerospace and Defense | ||
| Industrial (Oil and Gas) | ||
| Electrical and Electronics | ||
| Other End-user Industries | ||
| By Geography | Asia-Pacific | China |
| India | ||
| Japan | ||
| South Korea | ||
| ASEAN Countries | ||
| Rest of Asia-Pacific | ||
| North America | United States | |
| Canada | ||
| Mexico | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| NORDIC Countries | ||
| Rest of Europe | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Middle East and Africa | Saudi Arabia | |
| South Africa | ||
| Rest of Middle East and Africa | ||
Key Questions Answered in the Report
What is the size of the polyphenylene sulfide (PPS) composite market?
The polyphenylene sulfide (PPS) composite market stands at USD 3.17 billion in 2026 and is projected to reach USD 4.67 billion by 2031.
What is driving demand for PPS composites?
Electric vehicle thermal management, lightweight metal replacement, high-frequency electronics, industrial filtration, and hydrogen systems support demand.
Which type held the largest share in 2025?
Glass fiber-reinforced composites held 58.45% of the value in 2025, supported by automotive, electrical, and industrial applications.
Which form is projected to grow fastest through 2031?
Films are projected to advance at a 9.13% CAGR through 2031 because of demand for high-frequency electronic substrates.