
North America Pump Rental Market Size and Share
Market Overview
| Study Period | 2022 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
| Base Year Market Size (2026) | USD 5.33 Billion |
| Market Size (2027) | USD 5.64 Billion |
| Market Size (2032) | USD 7.51 Billion |
| Growth Rate (2027 - 2032) | 5.86 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
North America Pump Rental Market Analysis by Mordor Intelligence
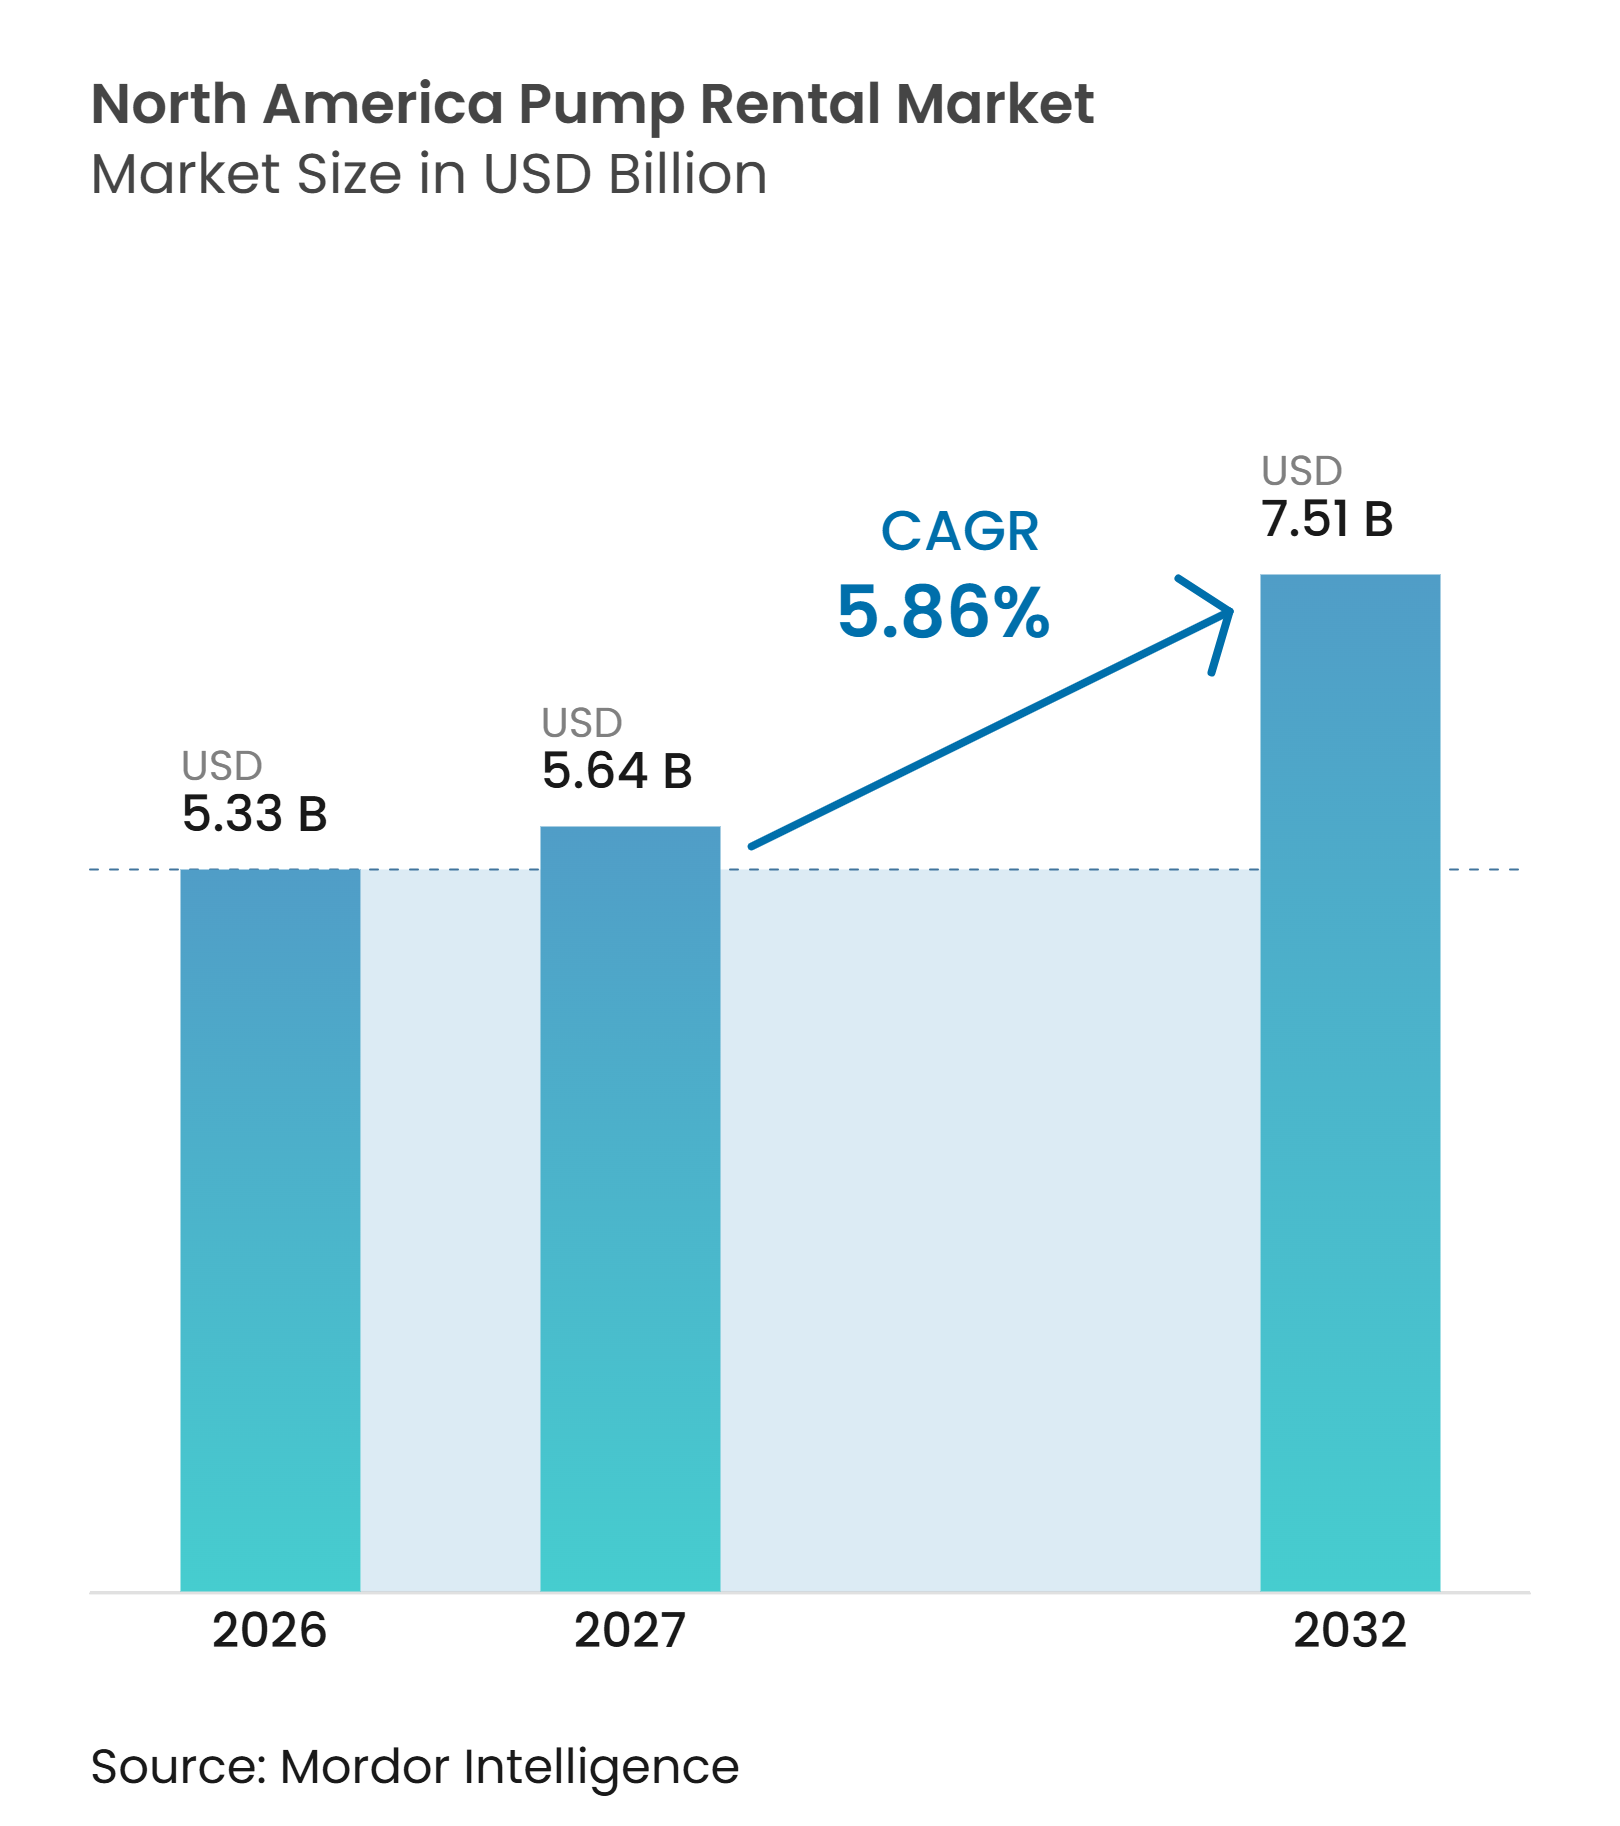
The North America Pump Rental Market size was valued at USD 5.33 billion in 2026 and is estimated to grow from USD 5.64 billion in 2027 to reach USD 7.51 billion by 2032, at a CAGR of 5.86% during the forecast period (2027-2032). Demand is shifting toward rental contracts because temporary pumping needs rarely justify the full cost of owning, storing, servicing, transporting, financing, and replacing equipment. Municipal water and sewer rehabilitation, large construction projects, emergency flood response, and temporary water-transfer requirements are creating repeat demand for bypass, dewatering, and water-management systems. Data center construction is extending the role of rental suppliers from early ground dewatering into chilled-water piping flushing before facilities open, which creates a longer period for specialist equipment and service support. Suppliers are responding with remote monitoring, field engineering, system installation, maintenance, and 24-hour support, which makes managed pumping arrangements more valuable than a simple equipment hire. The North America pump rental market therefore has a broader opportunity to serve projects through several phases while customers seek lower asset commitments, faster deployment, technical support, and the flexibility to adjust capacity as site conditions change.
Key Report Takeaways
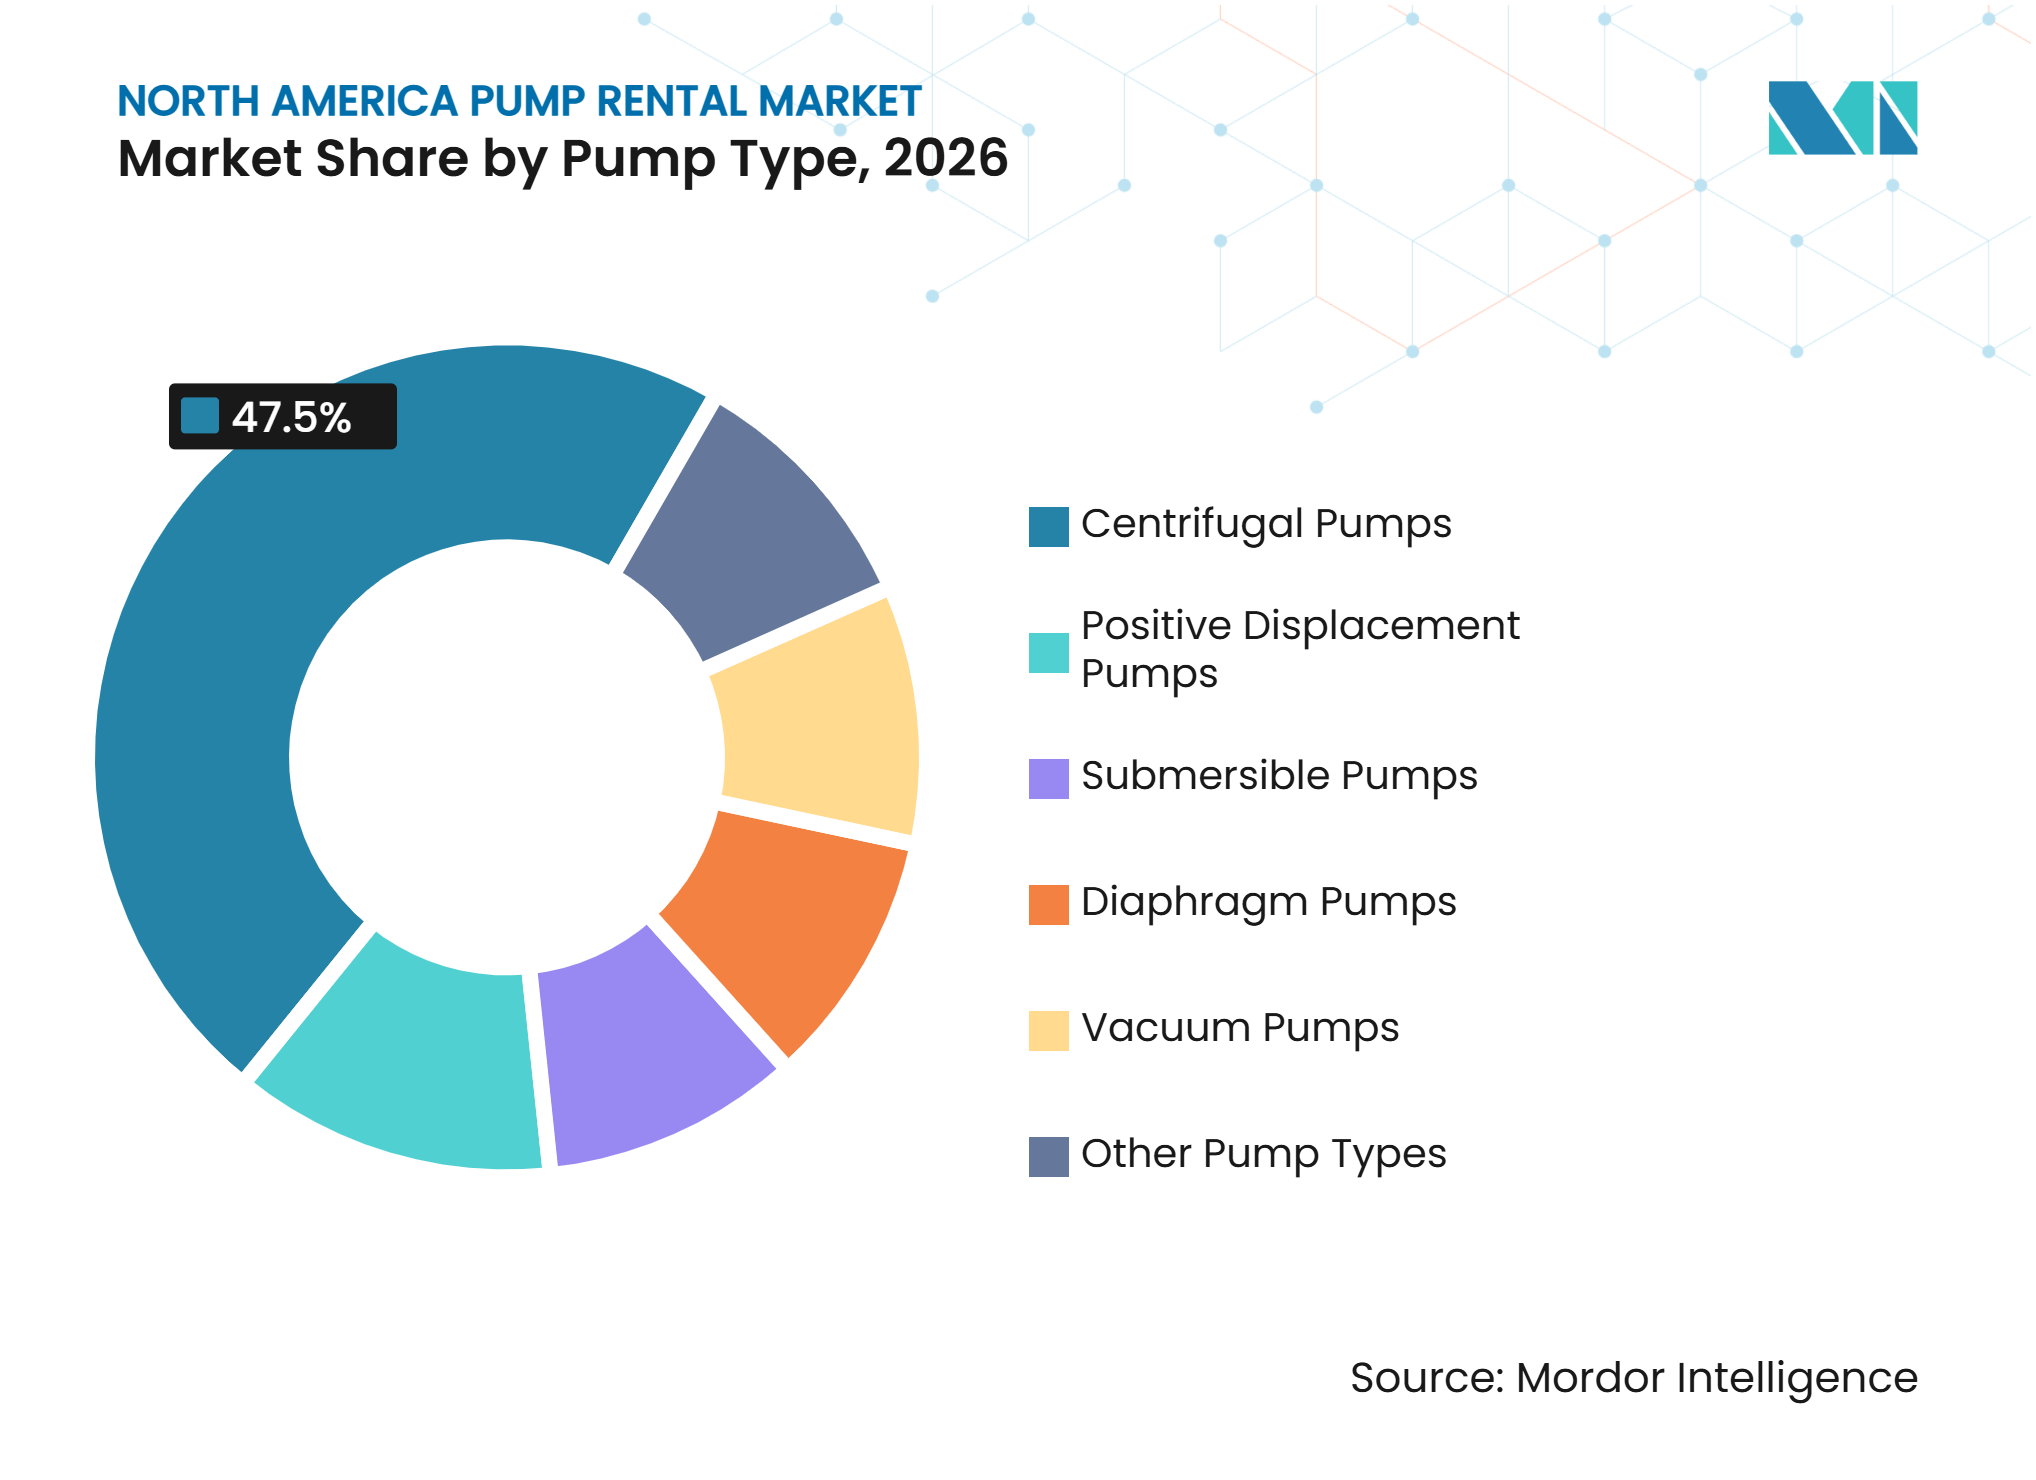
- By pump type, centrifugal pumps held 47.5% of the North America pump rental market share in 2026, while positive displacement pumps recorded the highest projected CAGR at 6.2% through 2032.
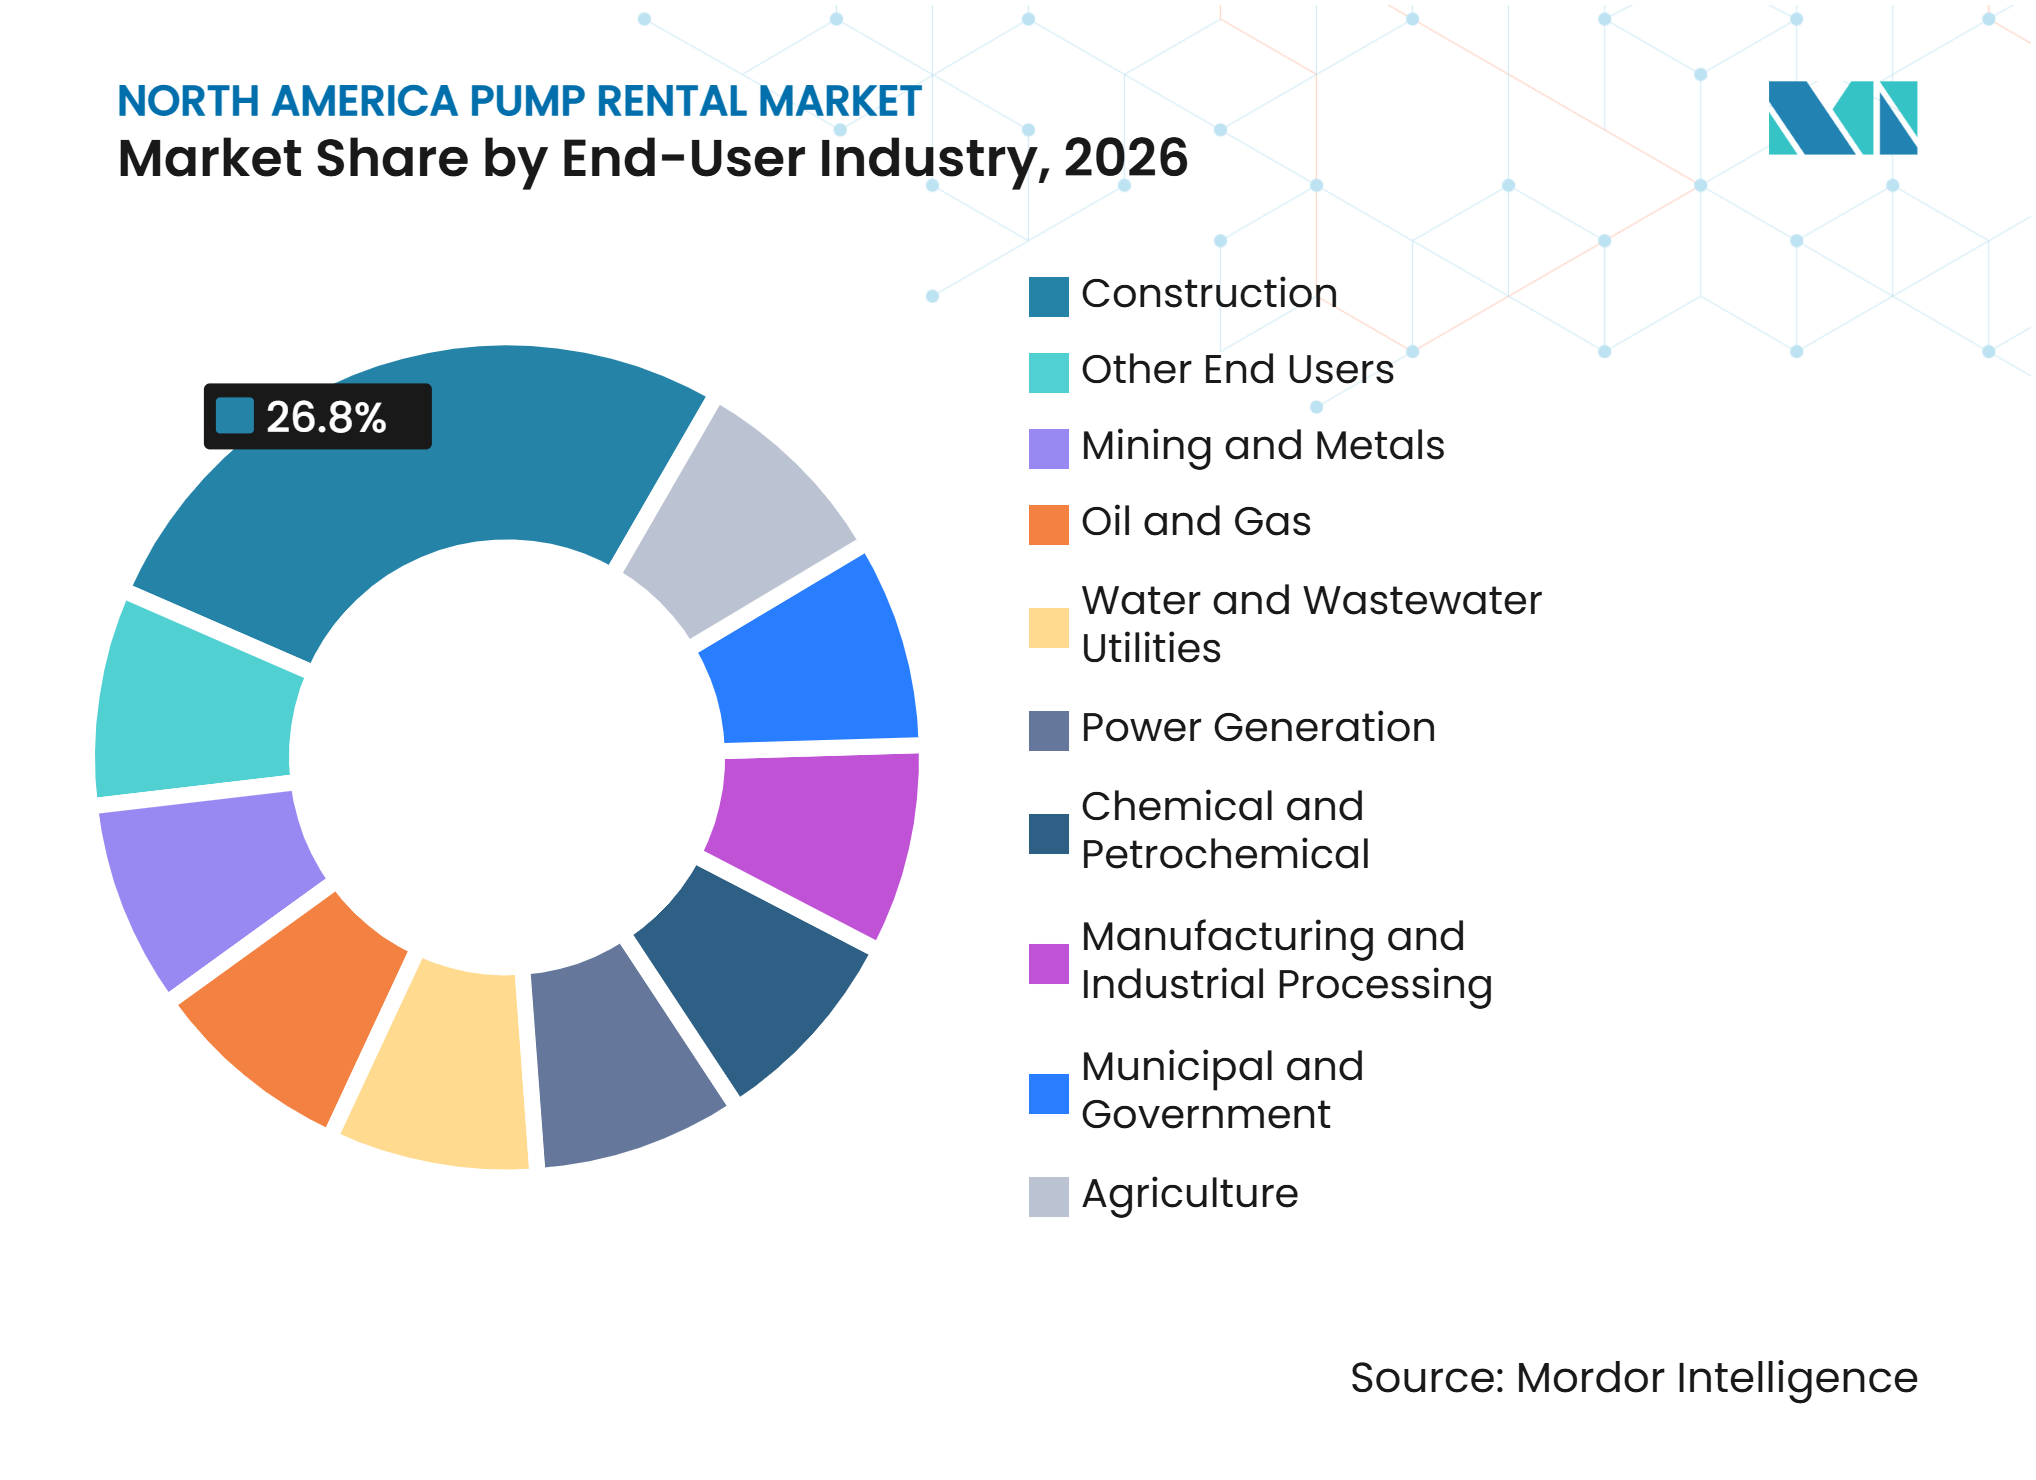
- By end-user industry, construction accounted for 26.8% of the North America pump rental market share in 2026, while mining and metals recorded the highest projected CAGR at 6.4% through 2032.
- By geography, the United States held 81.3% of the North America pump rental market share in 2026, while Mexico recorded the highest projected CAGR at 6.6% through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of North America Pump Rental Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Asset-Light Procurement for Temporary and Peak-Demand Pumping | +1.2% | Global | Medium term (2-4 years) |
| Aging Municipal Sewer and Water Infrastructure Rehabilitation | +1.1% | North America, focus on the United States and Canada | Long term (≥ 4 years) |
| Extreme Rainfall, Flood Response, and Climate-Resilience Spending | +0.8% | U.S. Gulf Coast, Southeast, Pacific Northwest, Canada | Medium term (2-4 years) |
| Infrastructure Megaproject and Data Center Construction Dewatering | +0.9% | U.S. Sunbelt and Mid-Atlantic, with effects in Canada and Mexico | Short term (≤ 2 years) |
| Remote Monitoring and Predictive Maintenance as a Rental Differentiator | +0.5% | Global | Medium term (2-4 years) |
| PFAS Compliance and Advanced Water Treatment Retrofits | +0.7% | United States and Canada, primarily water utilities | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Asset-Light Procurement for Temporary and Peak-Demand Pumping
Construction, industrial, and municipal customers are using rental contracts when pumping requirements are tied to a defined project or a short period of peak demand, rather than a stable operating need that would support an owned fleet. Ownership can leave customers with depreciation, maintenance, storage, transportation, compliance, and idle-fleet costs after work are complete. This matters for highway drainage, bypass work, emergency response, and construction dewatering, where equipment demand can rise quickly and then disappear once a stage of work is finished. United Rentals reported 11% year-over-year specialty rental growth in the third quarter of 2025, and fluid solutions equipment represented 7% of its equipment rental revenue in 2025, showing the established role of outsourced pumping capacity in customer spending.[1] Sunbelt Rentals disclosed that pump-solution rental penetration was 20% of its addressable market against a potential 35%, which leaves room for customers to move from ownership to rental.[2] The North America pump rental market benefits when suppliers combine equipment availability with planning, delivery, maintenance support, and replacement equipment that reduce the operational burden on customers.
Aging Municipal Sewer and Water Infrastructure Rehabilitation
Utilities require bypass pumping when they replace or rehabilitate gravity mains, force mains, and lift stations without interrupting service. These projects can run for weeks or months, making rental arrangements practical for contractors that manage several sites at once. Pennsylvania American Water invested USD 722 million in 2025 to improve water and wastewater systems in 436 communities, illustrating the scale of active rehabilitation work.[3] Illinois American Water also invested more than USD 280 million in statewide infrastructure upgrades during 2025, including a USD 12.6 million pump station upgrade.[4] Canada is directing funding toward water and wastewater infrastructure through the Build Communities Strong Fund, which supports projects that need temporary pumping while systems are upgraded. The North America pump rental market gains recurring work from this long repair cycle because bypass systems are needed before permanent assets return to service.
Infrastructure Megaproject and Data Center Construction Dewatering
Large semiconductors, data center, liquefied natural gas, transport, and utility projects need dewatering systems during excavation and foundation work, particularly when groundwater control cannot be delayed without affecting the construction schedule. Their scale can require high-capacity fleets, wellpoint systems, pipework, monitoring equipment, and technicians that individual contractors may not keep in-house. Data center projects also need high-volume flushing of chilled-water piping before commissioning, which creates a second service window after the initial dewatering work. United Rentals identifies data centers, pharmaceutical facilities, and airports as project categories that are generating demand for fluid solutions during construction and commissioning. The North America pump rental market can capture more project value when it packages pumps, High-Density Polyethylene (HDPE) pipe fusion, installation, monitoring, maintenance, and field support together. This approach is particularly relevant where schedule delays or groundwater control failures can disrupt major project milestones, increase costs, or prevent the safe progression of excavation work.
Per- and Polyfluoroalkyl Substances (PFAS) Compliance and Advanced Water Treatment Retrofits
The U.S. Environmental Protection Agency (EPA) has proposed extending the compliance deadline for the perfluorooctanoic acid (PFOA) and perfluorooctane sulfonic acid (PFOS) maximum contaminant levels to 2031 for eligible public water systems. Water systems that add granular activated carbon, reverse osmosis, or nanofiltration may need temporary pumping and treatment support while permanent equipment is installed, connected, tested, and placed into operation. Bypass pumping allows utilities to maintain service during pipeline connections, plant modifications, commissioning, and the replacement of equipment within active treatment systems. The same EPA notice states that construction material inflation for public water system equipment rose more than 20% between 2024 and 2025, which can lengthen construction schedules and rental periods. Xylem generated USD 2.464 billion in 2025 revenue from Water Solutions and Services, a segment that includes Godwin mobile dewatering rental equipment, emergency response, and municipal service contracts. The North America pump rental market is positioned to serve water treatment retrofits where compliance, service continuity, specialist field work, temporary hydraulic control, and project coordination must be managed at the same time.
Restraints Impact Analysis of North America Pump Rental Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Transport, Mobilization, and Setup Costs for Remote or Short-Duration Jobs | -0.4% | Remote U.S. interior, Northern Canada, rural Mexico | Short term (≤ 2 years) |
| Skilled Technician Shortages for Engineered Pumping Systems | -0.3% | North America-wide | Medium term (2-4 years) |
| Ownership Economics for Predictable, Long-Duration Pumping | -0.4% | U.S. industrial heartland, Alberta energy sector, U.S. Gulf Coast | Long term (≥ 4 years) |
| Fleet Availability, Emissions Compliance, and Equipment Downtime Risk | -0.2% | California and other high-regulation U.S. states, Canadian urban zones | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Skilled Technician Shortages for Engineered Pumping Systems
Engineered dewatering, wellpoint installation, and high-volume bypass work need technicians with practical knowledge of hydraulics, groundwater behavior, soil conditions, and pump curves. This capability takes time to develop and cannot be replaced easily with general construction labor. Retirements among experienced crews and competition for skilled tradespeople can limit the number of complex projects a supplier can support at one time. Mersino Dewatering described a 2025 Barton Dam remediation project that used nine wellpoint zones across a phased schedule, showing the continued need for experienced oversight on complex applications. Poor system configuration can damage equipment, delay projects, or cause compliance issues, so customers may be unwilling to accept inexperienced field teams. This capacity constraint can restrict growth in the North America pump rental market even when the equipment fleet itself is available.
Ownership Economics for Predictable, Long-Duration Pumping
Customers with stable and continuous pumping needs can find that purchasing equipment costs less than multi-year rental when the same equipment is used predictably and utilization remains high. This can apply to permanent lift-station backup, regular mine-water removal, oilfield production dewatering, and recurring agricultural water transfer. When utilization is consistently above 60% to 70%, direct ownership may offer a lower cost per operating hour over a three- to five-year period because the customer can spread capital and maintenance costs across predictable use. Operators in Alberta and the Permian Basin may purchase core positive displacement fleets and reserve rental for surge, maintenance, unusual site conditions, or contingency needs. Rental companies must therefore support their pricing with remote monitoring, system design, maintenance coverage, responsive field service, and service-level commitments. The North America pump rental market remains strongest where demand is variable, uncertain, tied to a limited project duration, or requires specialist capacity that the customer does not maintain internally.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
North America Pump Rental Market Segment Analysis
By Pump Type:
Centrifugal Pumps Lead, Displacement Gains in MiningCentrifugal pumps held 47.5% of the North America pump rental market share in 2026 because they fit municipal bypass pumping and construction dewatering applications that need high flow rates, dependable field maintenance, and fast installation on changing job sites. Their self-priming capability and broad deployment flexibility suit temporary sites where contractors need to begin groundwater control or transfer work without committing capital to a permanent fleet. Centrifugal units also have an established rental base, which helps suppliers redeploy comparable equipment across civil, utility, highway, building, and flood-response projects. Positive displacement pumps are projected to grow at a 6.2% CAGR through 2032 as mining users require systems that handle high-solids slurry, changing flow rates, abrasive materials, and difficult groundwater conditions. The North America pump rental market size for centrifugal equipment remains tied to public works, infrastructure construction, and emergency bypass projects, while displacement equipment has a more specialized growth path linked to technically difficult mine-water applications.
Submersible pumps serve confined-space, underground, tunneling, shaft, and marine construction work where equipment must operate below ground level or within restricted areas. Diaphragm pumps are used when fluid containment and dry-run tolerance matter, particularly in chemical handling and environmental remediation where a contractor must manage variable liquids without continuous operator attention. Vacuum pumps support wellpoint and groundwater-depression systems in shallow coastal and alluvial construction areas, where reducing groundwater pressure can be essential before excavation advances. Thompson Pump stated that its JSC series was designed for sewer bypass and high-head applications, demonstrating ongoing product specialization inside the centrifugal category. Mining operators are also using rental fleets during exploration and expansion stages before they commit capital to permanent dewatering installations, which lets them match equipment selection with actual water conditions. This supports demand for a packaged service that includes pumps, technicians, monitoring, maintenance, pipework, and response support rather than only a single item of equipment.



By End-User Industry:
Construction Anchors Market, Mining AcceleratesConstruction accounted for 26.8% of the North America pump rental market share in 2026, supported by the temporary and site-specific nature of drainage, excavation, groundwater-control, and stormwater-management requirements. Project schedules can change quickly, which makes rental more practical than purchasing a fleet that may sit idle after the job ends or require transfer to another location. Highway, utility, building, and civil works contractors use rental equipment to match capacity with the stage and location of work, including early excavation, utility connection, and final site restoration. Mining and metals is projected to expand at a 6.4% CAGR through 2032 as mines require greater water-management capacity during new development, expansion, and deeper operations that encounter higher groundwater inflows. The North America pump rental market size in construction is supported by its wide range of projects, while mining growth depends more directly on specialized applications, durable equipment, and the need to manage difficult water conditions.
Oil and gas remains an important end user in the Permian Basin, Western Canada, and Mexico, where rentals support produced-water transfer, well-pad dewatering, pipeline hydrostatic testing, maintenance work, and contingency capacity. Water and wastewater utilities create repeat work through main rehabilitation, lift-station maintenance, emergency response, and construction activity that must preserve service for local customers. Power generation, chemical and petrochemical facilities, and industrial manufacturers use rental pumps for planned outages, backup capacity, process-water management, temporary treatment, and equipment replacement periods. Data center development also creates a relevant industrial application because chilled-water piping must be flushed and tested before operation, allowing specialist suppliers to participate in both construction and commissioning. Municipal and government projects are tied to grant cycles and capital programs, while agriculture remains seasonal and price-sensitive in irrigated parts of the United States, Canada, and Mexico, and Safe Drinking Water Act requirements plus nonroad diesel emissions standards shape fleet selection for suppliers that serve regulated utility and construction customers.

Geography Analysis
United States
The United States held 81.3% of the North America pump rental market share in 2026, supported by mature rental use, broad specialty-rental coverage, high infrastructure activity, and a large base of contractors familiar with outsourced pumping solutions. Pennsylvania American Water invested USD 722 million in 2025 across 436 communities, while Illinois American Water invested more than USD 280 million in statewide upgrades, creating work that can require bypass pumping, dewatering, and temporary service management. Data centers, semiconductor facilities, LNG projects, and tunnel work add demand for wellpoint systems, pipe-flushing services, emergency dewatering, and field teams that can manage water on a continuous basis. Parsons was selected in April 2026 as construction manager for a New York City tunnel program that includes a tunnel dewatering pump station, highlighting the need for specialized pumping support in long-duration civil projects. EPA requirements and California rules for in-use off-road diesel fleets affect fleet renewal, engine selection, maintenance planning, and compliance decisions for rental providers.
Mexico
Mexico is projected to grow at a 6.6% CAGR through 2032. Mining development supports demand for construction dewatering and ongoing mine-water management, especially in silver and gold operations where water conditions can vary as development moves underground. Industrial parks and nearshoring-linked manufacturing facilities also need temporary pumping during site preparation, foundation work, utility installation, and construction handover. The North America pump rental market size in Mexico is further supported by urban water and wastewater work in Monterrey, Guadalajara, and secondary cities, where pipe rehabilitation can need temporary bypass capacity to keep systems operating. Mining and industrial growth create opportunities for suppliers that can mobilize specialized pumping equipment, compliant diesel fleets, pipework, and technicians across dispersed locations.
Canada and Mixed Regional Dynamics
Canada is supported by municipal water and wastewater rehabilitation together with energy-sector dewatering in Alberta and British Columbia, where projects can require specialist equipment and field support in demanding conditions. The federal government is funding water and wastewater infrastructure under the Build Communities Strong Fund, which can generate temporary pumping requirements during construction, upgrades, and system connection work. Technosub acquired NCS Fluid Handling Systems in August 2025, extending its coverage in Western Canadian industrial and energy applications and adding a local base for water-management work. Across Canada and Mexico, suppliers with local technicians, compliant fleets, responsive logistics, and the ability to handle mining, municipal, and industrial projects can address areas where specialist coverage is less dense than in the United States.
Competitive Landscape
Market Concentration
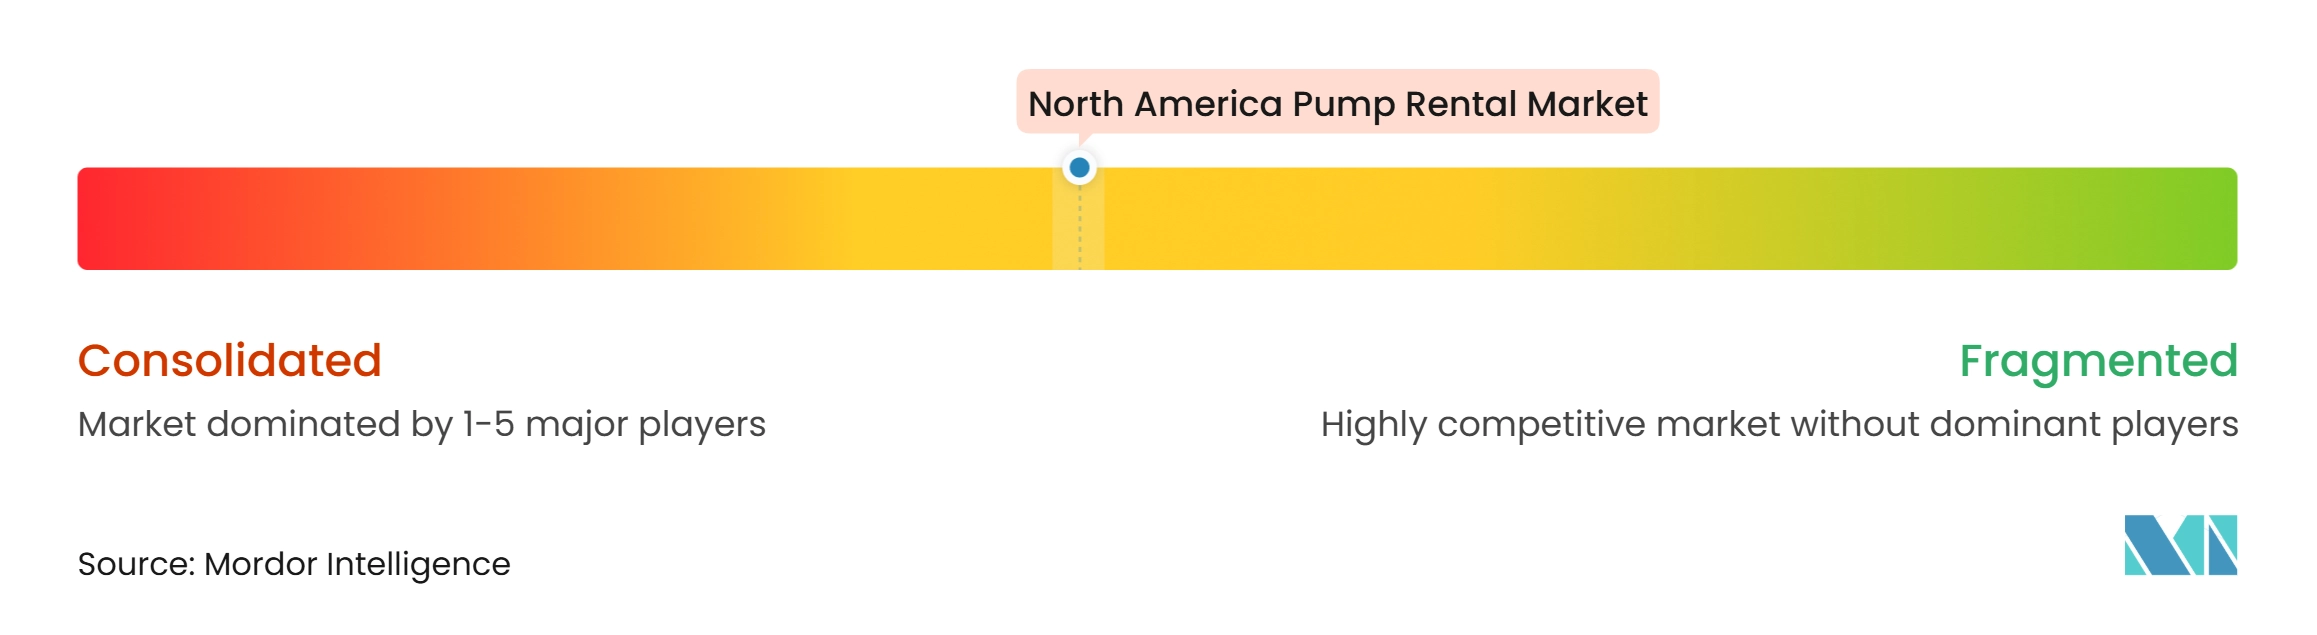
The North America pump rental market is moderately consolidated and includes diversified rental groups and dedicated pump specialists that compete through fleet availability, application expertise, regional coverage, and the ability to solve site-specific water-control problems. United Rentals, Herc Holdings, and Sunbelt Rentals offer pumps within wider specialty-rental portfolios, which gives them access to established customer relationships, distribution networks, and opportunities to provide several equipment categories on one job. United Rentals reported that fluid solutions equipment accounted for 7% of equipment rental revenue in 2025 and offers wellpoint systems, bypass pumping, and High-Density Polyethylene (HDPE) pipe fusion services. Herc completed its acquisition of H&E Equipment Services in June 2025, adding more than 160 locations and expanding the reach of its ProSolutions specialty platform. These providers can cross-sell pumping equipment with power, climate-control, and general equipment rentals, which is useful for customers that need one supplier for temporary site services, but it does not remove the importance of specialized engineering on difficult projects.
Dedicated providers compete by designing systems for complex water-control projects and by supplying personnel who can install, monitor, adjust, and maintain them throughout the rental period. Xylem supports this segment of the North America pump rental market through Godwin mobile dewatering equipment and its Water Solutions and Services business. Specialists in this market include Rain for Rent, Thompson Pump, Griffin Fluid Management, Holland Pump, Technosub, and IRONCLAD Powered by Mersino. Kinderhook Industries launched IRONCLAD Powered by Mersino in April 2026 by combining Ironclad Environmental Solutions, Mersino Water Solutions, and Global Pump into a national water and liquid-solutions platform with more than 70 branches and more than 5,000 specialized pumps. This transaction illustrates how consolidation can bring together equipment, engineering, field-support capabilities, liquid containment assets, and a broader location network to serve municipal and industrial projects that require a coordinated response.
Technology integration, geographic density, and vertically integrated services are becoming practical points of differentiation in the North America pump rental market. Remote monitoring allows providers to move from an equipment-only arrangement toward a managed pumping service with stronger performance accountability, faster response to operating changes, and less need for continuous customer oversight. Holland Pump acquired Atlas Dewatering in September 2025, bringing wellpoint and sock-drain installation capabilities into its operations and expanding its Florida and Southeast offering. EPA Tier 4 Final requirements and California fleet rules can raise replacement costs for smaller operators with older diesel fleets, which may reinforce the advantage of providers with capital, compliant assets, and established maintenance systems.
North America Pump Rental Industry Leaders
-
United Rentals, Inc.
-
Sunbelt Rentals, Inc.
-
Xylem Inc.
-
Herc Holdings Inc.
-
Rain for Rent
- *Disclaimer: Major Players sorted in no particular order
North America Pump Rental Market Companies Covered in this Report
- Barco Pump Company
- Blue Tank and Pump Rental
- Capital Pump & Equipment
- Coastal Pump & Equipment
- DEL Corporation
- Global Pump
- Griffin Fluid Management
- Herc Holdings Inc.
- Holland Pump
- Hydra Service, Inc.
- Mersino Equipment Rental
- Moving Water Industries
- National Trench Safety
- Rain for Rent
- Sage Rental Services
- Sunbelt Rentals, Inc.
- Technosub
- Thompson Pump & Manufacturing Company
- United Rentals, Inc.
- Xylem Inc.
Recent Industry Developments in North America Pump Rental Market
- April 2026: Kinderhook Industries launched IRONCLAD Powered by Mersino, merging Ironclad Environmental Solutions, Mersino Water Solutions, and Global Pump into a single national water and liquid solutions platform with 70-plus branches, 5,000-plus specialized pumps, and 40,000-plus liquid containment assets across the United States, representing a structural consolidation of three complementary specialty operators under one contract and engineering team.
- April 2026: Parsons Corporation was selected as construction manager for the New York City tunnel dewatering pump station program, a 16-year initiative addressing wastewater infrastructure challenges in Brooklyn and Queens, involving a large-diameter storage tunnel and tunnel dewatering pump station with capacity to capture excess combined sewer flows during storm events.
- August 2025: Holland Pump, operating under Workdry International Group, completed the acquisition of Atlas Dewatering of Port Orange, Florida, integrating wellpoint and sock-drain installation capabilities in-house and expanding its Florida and Southeast U.S. dewatering offering to 16 locations.
- June 2025: Thompson Pump and Manufacturing Company renewed its ISO 9001 quality management certification and achieved ISO 45001 occupational health and safety and ISO 14001 environmental management certifications.
North America Pump Rental Market Report Scope
Pump rental is a service that provides temporary or long-term access to specialized pumping equipment without requiring an outright purchase.
North America pump rental market is segmented into pump type, end-use industry, and geography. By pump type, the market is segmented into centrifugal pumps, positive displacement pumps, submersible pumps, diaphragm pumps, vacuum pumps, and other pump types. By end-use industry, the market is divided among construction, mining and metals, oil and gas, water and wastewater utilities, power generation, chemical and petrochemical, manufacturing and industrial processing, municipal and government, agriculture, and other end users. The report also covers the market size and forecasts for the North America pump rental market across 3 countries in key regions. For each segment, the market sizing and forecasts have been provided on the basis of value (USD).
Segmentation Overview
| Centrifugal Pumps |
| Positive Displacement Pumps |
| Submersible Pumps |
| Diaphragm Pumps |
| Vacuum Pumps |
| Other Pump Types |
| Construction |
| Mining and Metals |
| Oil and Gas |
| Water and Wastewater Utilities |
| Power Generation |
| Chemical and Petrochemical |
| Manufacturing and Industrial Processing |
| Municipal and Government |
| Agriculture |
| Other End Users |
| United States |
| Canada |
| Mexico |
| By Pump Type | Centrifugal Pumps |
| Positive Displacement Pumps | |
| Submersible Pumps | |
| Diaphragm Pumps | |
| Vacuum Pumps | |
| Other Pump Types | |
| By End-User Industry | Construction |
| Mining and Metals | |
| Oil and Gas | |
| Water and Wastewater Utilities | |
| Power Generation | |
| Chemical and Petrochemical | |
| Manufacturing and Industrial Processing | |
| Municipal and Government | |
| Agriculture | |
| Other End Users | |
| By Geography | United States |
| Canada | |
| Mexico |
Key Questions Answered in the Report
What is the forecast growth rate for North America pump rentals?
The North America pump rental market is projected to grow at a 5.86% CAGR from 2027 to 2032 and reach USD 7.51 billion by 2032.
Which pump type has the largest share?
Centrifugal pumps held 47.5% share in 2026, supported by municipal bypass and construction dewatering applications.
Which end-user application is growing the fastest?
Mining and metals is projected to grow at a 6.4% CAGR through 2032 because of specialized dewatering needs during mine development and expansion.
Why do contractors rent pumps instead of buying them?
Rental reduces exposure to equipment storage, maintenance, and idle capacity when pumping requirements are temporary or project-specific.
Which country is expected to grow the fastest?
Mexico is projected to record a 6.6% CAGR through 2032, supported by mining, industrial development, and municipal infrastructure needs.
What factors affect supplier competition?
Suppliers compete through fleet coverage, engineering support, remote monitoring, compliant diesel equipment, and the ability to provide installation and service.