
Inland Container Depot and Dry Port Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 32.59 Billion |
| Market Size (2031) | USD 42.5 Billion |
| Growth Rate (2026 - 2031) | 5.45 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Inland Container Depot and Dry Port Market Analysis by Mordor Intelligence
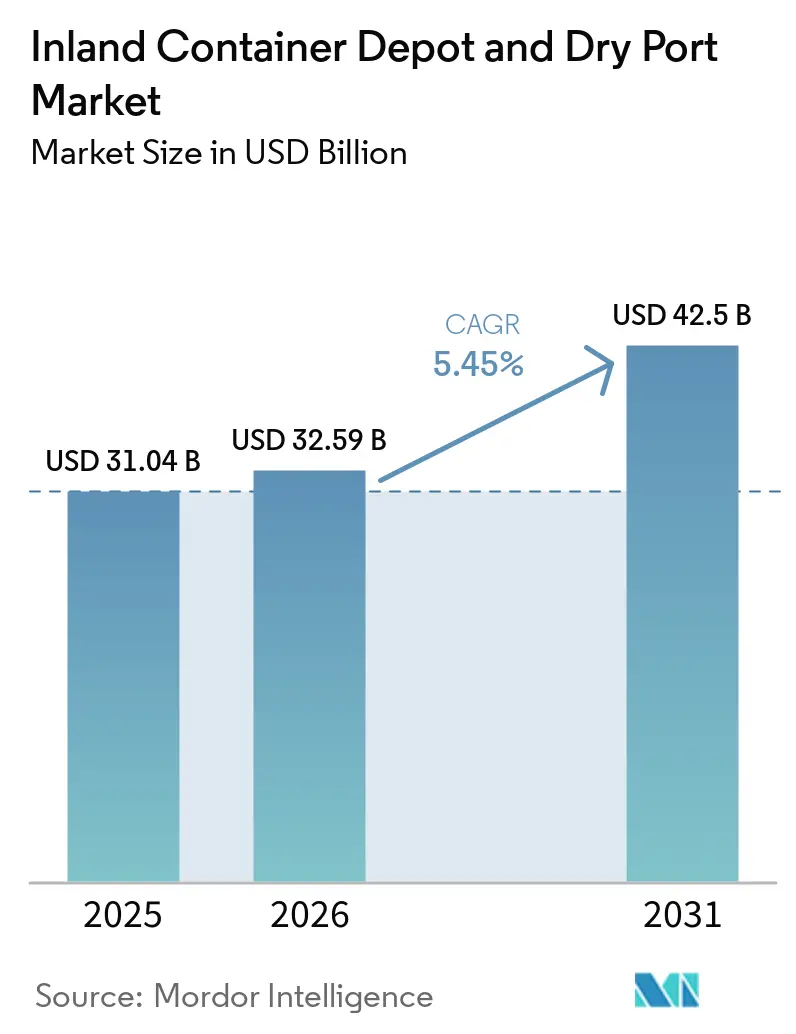
The inland container depot and dry port market size was valued at USD 31.04 billion in 2025, and is estimated to grow from USD 32.59 billion in 2026 to reach USD 42.50 billion by 2031, at a CAGR of 5.45% during the forecast period (2026-2031).
Higher container movements, congestion at coastal terminals, and public investment in rail-linked freight corridors support demand for inland cargo capacity. Global container movements reached 159 million TEUs from January through October 2025, up 4% year-over-year, which increased pressure on hinterland logistics networks. The inland container depot and dry port market is moving beyond empty-container storage as facilities add customs clearance, cold-chain staging, and intermodal transfer services. Operators are responding through rail connections, bonded warehousing, digital customs links, and facilities that can manage refrigerated cargo. Competition reflects a mix of global logistics groups and state-linked operators, while concession terms and national freight policy continue to shape local operating conditions.
Key Report Takeaways
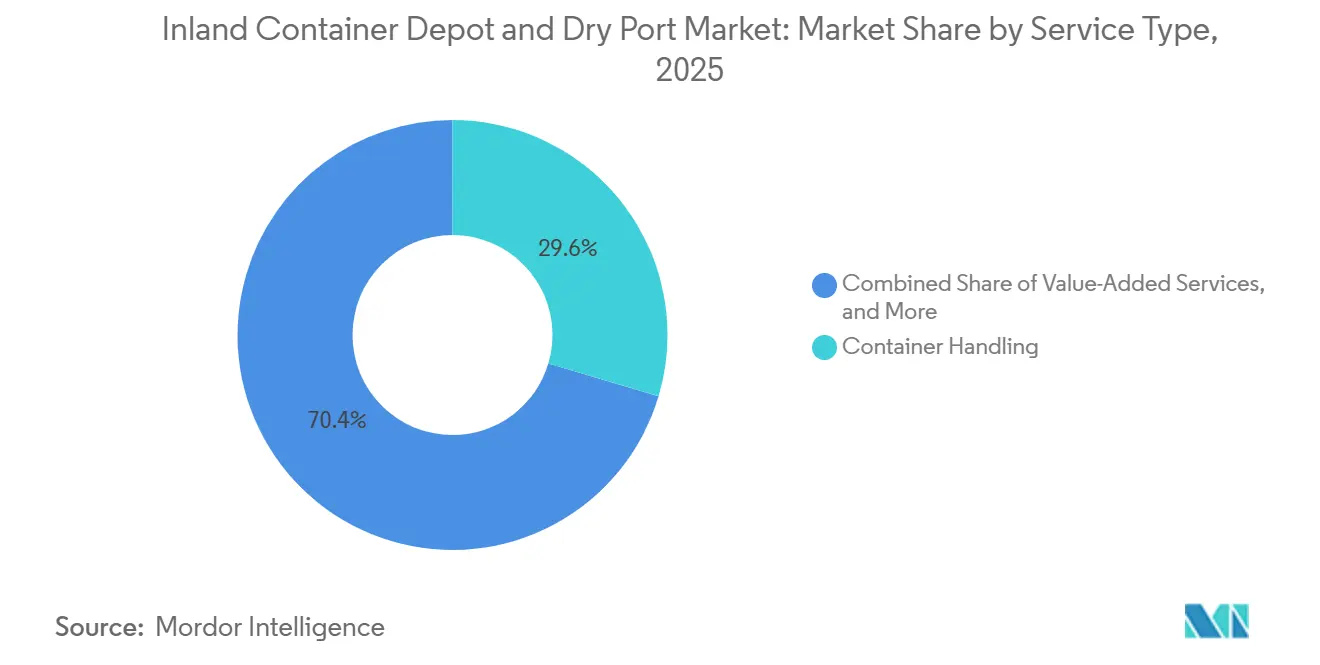
- By service, container handling held 29.60% of the inland container depot and dry port market share in 2025, while other value-added services recorded the highest projected CAGR at 7.16% through 2031.
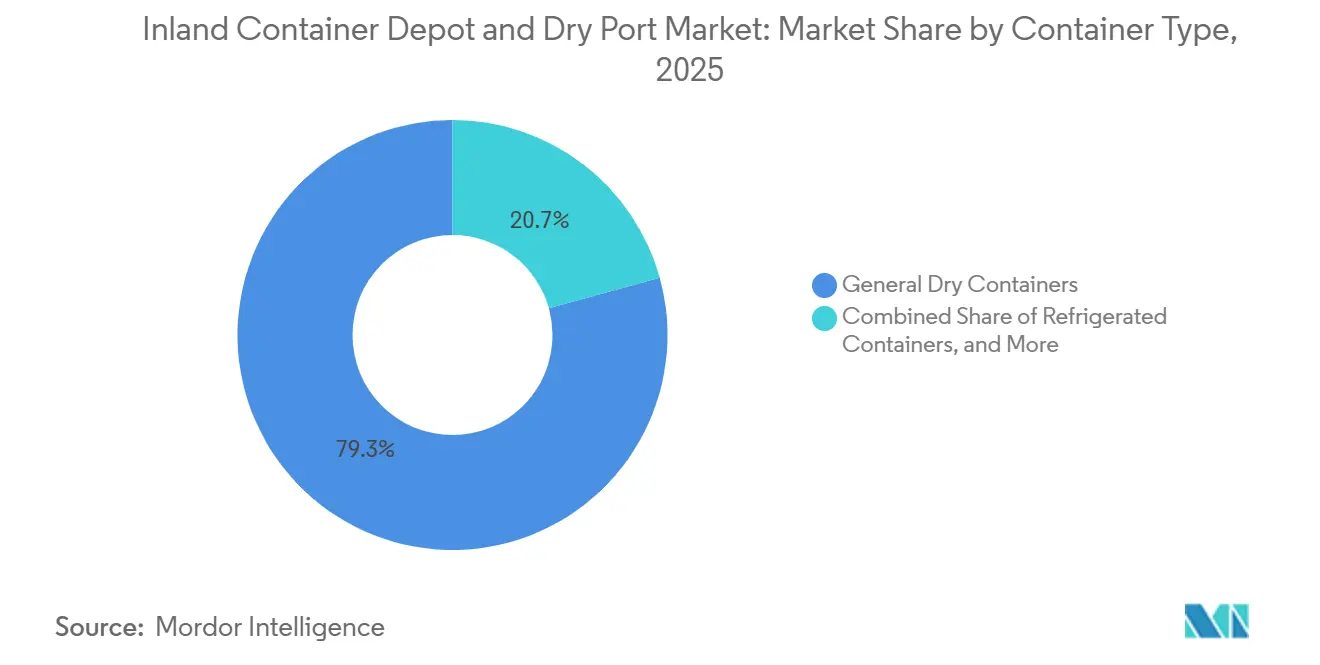
- By container type, general dry containers held 79.25% of the inland container depot and dry port market size in 2025, while refrigerated containers recorded the highest projected CAGR at 7.23% through 2031.
- By ownership and operating model, publicly owned and operated facilities held 45.55% of the inland container depot and dry port market size in 2025, while public-private partnerships recorded the highest projected CAGR at 6.94% through 2031.
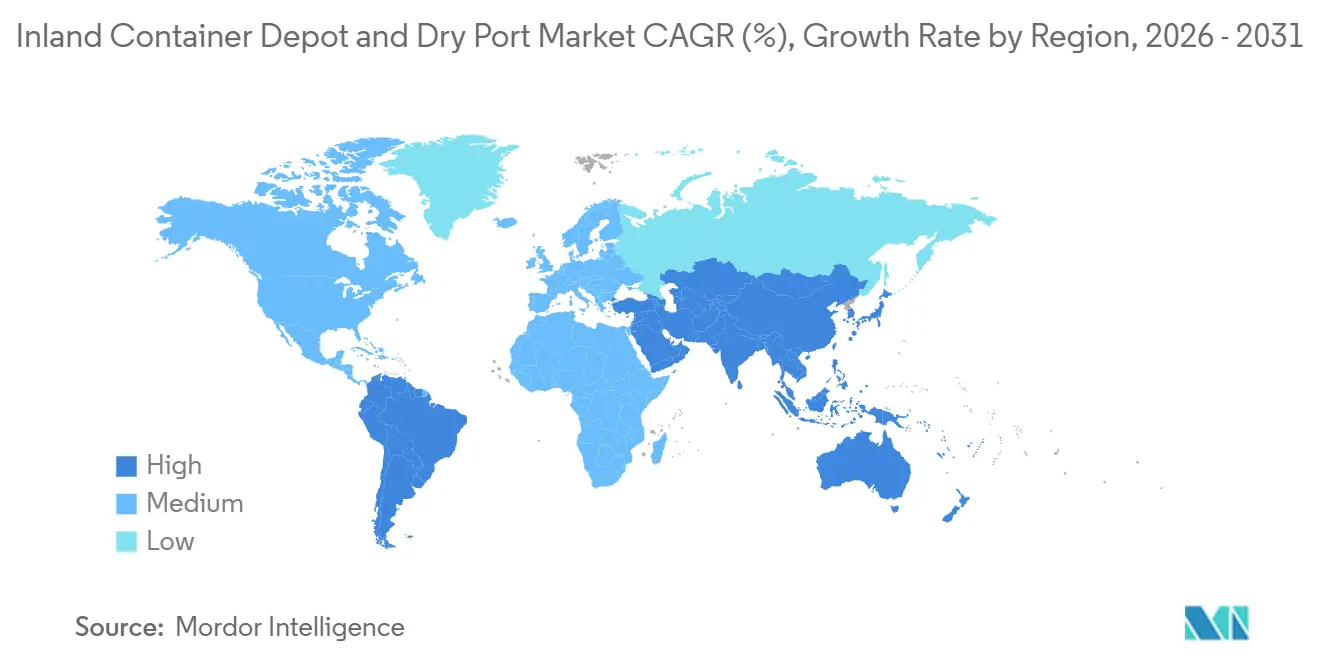
- By geography, North America held 32.10% of the inland container depot and dry port market share in 2025, while Asia-Pacific recorded the highest projected CAGR at 7.48% through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Inland Container Depot and Dry Port Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Expansion of Containerized Trade and Hinterland Cargo Flows | +1.2% | Global, strongest in Asia-Pacific and North America | Medium term (2-4 years) |
| Port Congestion and the Shift to Inland Buffer Capacity | +0.9% | Global, concentrated at major gateway ports in Europe, North America, and East Asia | Short term (≤ 2 years) |
| Government Investment in Rail-Linked Multimodal Corridors | +0.8% | India, China, UAE, Sub-Saharan Africa, Central Asia | Medium term (2-4 years) |
| E-Commerce and Distributed Fulfillment Networks | +0.7% | North America, Western Europe, Asia-Pacific | Short term (≤ 2 years) |
| Digital Customs, Single-Window Clearance and Paperless Trade | +0.5% | South Asia, Southeast Asia, Middle East and Africa, with wider spillover | Medium term (2-4 years) |
| Depot Electrification and Automation Economics | +0.6% | North America, European Union, East Asia, with early mover advantage | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Expansion of Containerized Trade and Hinterland Cargo Flows
Global containerized trade volumes rose 4% year-over-year from January through October 2025, reaching 159 million TEUs. This volume supported demand for the inland container depot and dry port market, where seaports could not stage cargo efficiently. Manufacturing diversification has redirected container flows through Vietnam, India, and Mexico, creating demand in corridors where terminal construction has not kept pace. India’s Gati Shakti Multi-Modal Cargo Terminal policy had mobilized USD 1.19 billion in private investment by July 2026 and had commissioned 142 freight terminals with a combined capacity of 224 million tonnes per annum[1]. The inland container depot and dry port market, therefore, has stronger opportunities along the Central Indian and ASEAN manufacturing routes. These corridors link industrial growth with rail, warehousing, and customs services rather than relying on port expansion alone.
Port Congestion and the Shift to Inland Buffer Capacity
Port congestion has made the inland container depot and dry port market a core operating tool for cargo owners and carriers. Global port congestion approached 4 million TEUs during 2025 and 2026, increasing demand for inland buffer capacity. European terminals also faced higher yard utilization and weaker inland waterway connectivity, which added to delays. Inland facilities can receive loaded containers from rail before port dwell charges accumulate. Maersk reported in June 2026 that its Elwood, Illinois, depot handled overflow from congested Chicago rail ramps through a pre-pull service. This operating role gives the inland container depot and dry port market a revenue source beyond conventional storage charges.
Government Investment in Rail-Linked Multimodal Corridors
State-backed rail and dry port investment is creating long-term capacity for commercial operators. India’s Dadri Multi-Modal Logistics Park spans 105 hectares, has an annual capacity of 1 million TEUs, and connects to the Western and Eastern Dedicated Freight Corridors[2]. Such projects make rail-based container movement more practical for inland cargo owners. South Africa’s Port of Gauteng White Paper, released in September 2025, proposed a USD 2.72 billion inland logistics hub to shift cargo from the N3 road corridor to rail. The proposal included more than 50,000 permanent jobs, subject to the regulatory and investment framework being confirmed. The inland container depot and dry port market benefits where public freight programs provide the corridor backbone and commercial operators supply services within it.
Digital Customs, Single-Window Clearance, and Paperless Trade
Digital customs systems are strengthening the inland container depot and dry port market by improving inland clearance in countries where customs processing was historically concentrated at seaports. India launched SWIFT 2.0 in November 2025 as a unified digital platform for EXIM clearance and planned to onboard more than 60 partner government agencies[3]. The platform reduces document duplication that had slowed inland clearance. Faster electronic processing reduces the location advantage of port-side customs facilities and supports bonded operations at inland sites. Maqta Technologies Group and Pakistan Single Window entered a March 2025 partnership covering digital customs clearance, smart warehousing, and risk-management systems at dry ports. Compliance with the WCO SAFE Framework and relevant customs protocols also remains important for bonded warehouse and free-zone status.
Restraints Impact Analysis of Inland Container Depot and Dry Port Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Land, Equipment and Maintenance Costs | -0.8% | Global, acute in North America and Western Europe where land costs are highest | Long term (≥ 4 years) |
| Road-Rail Connectivity Gaps and First-Last-Mile Friction | -0.6% | Sub-Saharan Africa, South Asia, landlocked Central America, Central Asia | Medium term (2-4 years) |
| Concession, Customs and Cross-Border Regulatory Complexity | -0.5% | Middle East and Africa, Southeast Asia, South America, particularly cross-border depots | Medium term (2-4 years) |
| Volatile Container Imbalances and Underutilized Yard Capacity | -0.4% | Global, notably North America and Europe, and pronounced in landlocked corridors | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
High Land, Equipment and Maintenance Costs
Capital requirements limit the expansion of inland container depots, especially near major consumption centers where land is costly. An automated rubber-tyred gantry crane costs USD 1.5 million to USD 2 million. A new multi-hectare facility in a major North American or European metropolitan area can require land and infrastructure spending above USD 100 million before handling equipment is installed. This cost base favors port authorities and integrated logistics groups that can support large initial investments. Refrigerated container infrastructure also requires continuous power, temperature monitoring, and certified inspection systems that cost USD 150 to USD 300 per reefer unit per month. The inland container depot and dry port market, therefore, has a higher entry barrier for reefer-capable facilities, and smaller operators need high utilization and premium contracts to support the expense.
Road-Rail Connectivity Gaps and First-Last-Mile Friction
An inland depot depends on reliable rail or barge links that can replace long-haul road movement. Kenya Ports Authority’s Naivasha ICD had a capacity of 4,000 TEUs and a direct Standard Gauge Railway link to Mombasa, yet it operated at 19% occupancy in 2025 and 2026 because onward links to Uganda, Rwanda, and the Democratic Republic of the Congo were limited. Similar gaps occur where local roads are inadequate, rail schedules are unreliable, or border paperwork adds days to transit. A depot operator cannot resolve these constraints independently. Rail operators, road agencies, and border authorities all influence whether the facility can operate efficiently. The inland container depot and dry port market remains exposed, where facilities are commissioned before their wider freight network is ready.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Inland Container Depot and Dry Port Market Segment Analysis
By Service:
Value-Added Services Outpace Core Handling RevenueContainer handling held 29.60% of the inland container depot and dry port market size in 2025, making it the largest service category. High-throughput facilities handling 200,000 or more TEUs annually can achieve stronger equipment utilization and crane cycle times than smaller yards. This advantage concentrates volumes at well-capitalized facilities.[4] Storage services and customs clearance and documentation were the second- and third-largest service segments. Both services benefit when bonded cargo remains at a depot during regulatory examination.
Other value-added services recorded the highest growth rate at a 7.16% CAGR through 2031. The category includes container repair and certification, re-packing and relabeling under customs supervision, temperature-controlled pre-trip inspection, and digital inventory management for e-commerce shippers. These activities allow operators to perform work that had previously occurred at factory gates or near-port logistics parks. CONCOR commissioned Dedicated Line No. 7 at MMLP Dadri in July 2026 and flagged off India’s first Double Stack Reefer Container Train on the corridor. The project supports temperature-controlled inland-to-port movement and expands the range of services available at the facility.



By Container Type:
Cold Chain Infrastructure Defines the Next Competitive ThresholdGeneral dry containers held 79.25% of the inland container depot and dry port market size in 2025. Standard 20-foot and 40-foot containers carry much of the manufactured goods, agricultural commodities, and industrial materials moved through container networks. At large depots, dry-box handling faces price competition because many facilities can offer the same basic service. Specialized containers, including open-top, flat-rack, and tank units, serve heavy machinery, project cargo, and liquid bulk trades. Their volumes are smaller, but their specialized handling can carry higher per-unit fees.
Refrigerated containers recorded the highest CAGR at 7.23% through 2031. The International Institute of Refrigeration projected global refrigerated container throughput to increase from 4 million TEUs in 2023 to 7.1 million TEUs by 2030. Depot operators need dedicated plug points, reliable backup power, and continuous monitoring to support this cargo. CONCOR operationalized an Import Loaded Reefer Movement facility at Tughlakabad ICD in 2025 with dedicated reefer plug points and 24-hour real-time temperature monitoring. The inland container depot and dry port market can serve pharmaceutical and perishable imports more effectively when these facilities are in place.

By Ownership and Operating Model:
Public-Private Partnerships Attracting Capital at Fastest RatePublicly owned and operated facilities held 45.55% of the inland container depot and dry port market share in 2025. Government-led infrastructure cycles have supported major inland depot networks in India, China, and Sub-Saharan Africa. CONCOR achieved its highest throughput of 5.58 million TEUs in fiscal year 2025-26. It operates 68 terminals across 194 rail locations and has a target of 100 terminals with more than 500 container rakes by 2028. Private facilities hold a smaller but commercially productive position in markets with established intermodal systems and large manufacturing export bases.
Public-private partnerships recorded the highest growth at a 6.94% CAGR through 2031. In the inland container depot and dry port market, governments provide land, concessions, and rail links while private partners provide equipment, commercial management, and service development. The model is expanding in South Asia and the Middle East through dry ports linked to special economic zones. Uttar Pradesh committed USD 841 million to the Dadri Multi-Modal Logistics Hub under the NICDIT framework. Operators need clear revenue-sharing and renewal terms because major facilities require 20- to 25-year investment horizons.
Geography Analysis
North America Inland Container Depot and Dry Port Market
North America held 32.10% in 2025. The region benefits from the United States’ intermodal rail network, Trans-Pacific cargo volumes, and private logistics operators. Georgia Ports Authority’s Gainesville Inland Port has a capacity for 200,000 containers annually and received USD 134 million in funding within GPA’s USD 5 billion infrastructure program. Canada’s British Columbia and Ontario corridors support Asia-Pacific imports moving toward the United States. Midwest and Northeast distribution networks, while Mexican dry port activity has increased with nearshoring under the United States-Mexico-Canada Agreement.
APAC, Europe and South America Inland Container Depot and Dry Port Market
Within the inland container depot and dry port market, Asia-Pacific recorded the highest regional CAGR at 7.48% through 2031, supported by Indian freight corridors, Southeast Asian manufacturing diversification, and Chinese logistics parks. CONCOR had expanded to 194 rail locations in 2026, Adani Logistics added ICD Malur in 2025, and Vietnam’s major corridors attracted interest from PSA International and APM Terminals, while Australia and South Korea focused on service quality and digital capability. The inland container depot and dry port market in Europe is established and upgrading major intermodal hubs. Duisburg serves North Sea and Mediterranean freight through a 200-kilometer internal rail network, while duisport acquired stakes of 24.9% and 20% in Maxi Terminal Hamm’s infrastructure and operating companies. France, Hungary, and Poland are attracting investment as nearshoring changes freight routes. South America is developing around Brazil’s agricultural exports, container volumes, and rail network, with DP World expanding Santos to 1.7 million TEUs and building agri-export corridors with MRS Logistica. Argentina, Chile, Peru, Colombia, and Ecuador serve regional and Pacific Alliance trade, while rail links remain important to reduce road dependence.
MEA Inland Container Depot and Dry Port Market
The Middle East and Africa show contrasting conditions, with major bonded dry port projects in the United Arab Emirates and persistent road and rail gaps in much of Sub-Saharan Africa. Gulftainer unveiled the 150-hectare Al Dhaid Multi-Modal Trade Corridor in June 2026, with annual capacity of 1.5 million TEUs and Etihad Rail integration, and it provides 2.3 million TEUs of combined capacity with Sajaa Dry Port. Saudi Arabia and Qatar are developing freight connections to industrial zones and special economic areas. South Africa’s proposed Gauteng Inland Port can ease the Durban-Gauteng corridor if its regulatory and investment framework is confirmed.
Competitive Landscape
Market Concentration
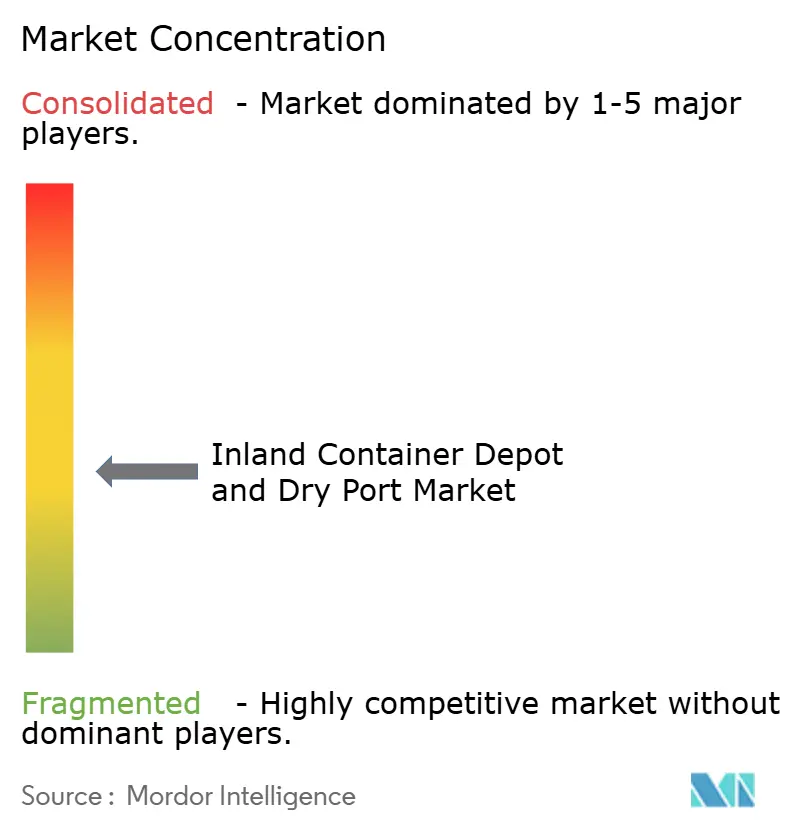
The inland container depot and dry port market is moderately fragmented globally. Maersk, DP World, PSA International, CMA CGM, CONCOR, Hutchison Ports, and Adani Group hold important positions in their home corridors, but no company has a dominant global position. Local conditions can be more concentrated because long concessions and expensive rail connections limit entry. Some landlocked corridors have only 1 or 2 viable facilities. Operators compete through new sites, bonded warehousing, reefer handling, in-depot customs services, real-time tracking, automated gates, and customs data links.
The inland container depot and dry port market is gaining capacity in Uzbekistan and Madhya Pradesh through DP World, while Adani Group has expanded in Rajasthan and Karnataka, India. DP World and Tashkent Invest agreed in October 2025 to develop a USD 288 million logistics terminal in Uzbekistan’s Yangi Avlod Special Industrial Zone. The first phase targets a 150,000-TEU annual rail terminal and a 63,000 m² warehouse complex by the end of 2027. In January 2026, DP World agreed with the Government of Madhya Pradesh to develop the 88.3-acre Powarkheda Logistics Composite Hub. The facility includes EXIM rail connectivity, warehousing, cold storage, and container repair.
Shipping lines are internalizing functions that were previously provided by independent depots. Maersk reached a long-term dry port services agreement with East-West Intermodal Logistics Plc at Fenyeslitke, Hungary, integrating a third-party terminal into its logistics network. CMA CGM agreed in April 2025 to acquire a 35% stake and management rights in Egypt’s October Dry Port, linking Alexandria and Ain Sokhna to Greater Cairo by rail. Hapag-Lloyd signed Letters of Intent with the Government of India in March 2026 that included investment in J M Baxi Ports & Logistics, which handles 3.2 million TEUs annually. WCO SAFE Framework compliance and ISO 9001 certification remain important for bonded status and carrier partnerships.
Inland Container Depot and Dry Port Industry Leaders
-
Container Corporation of India (CONCOR)
-
A.P. Moller - Maersk
-
PSA International
-
DP World
-
Hapag-Lloyd
- *Disclaimer: Major Players sorted in no particular order
Inland Container Depot and Dry Port Market Companies Covered in this Report
- Boasso Global
- Maersk
- Container Corporation of India (CONCOR)
- Hapag-Lloyd
- Hutchison Ports
- GAC
- DP World
- Abu Dhabi Terminals
- Freightliner Group Ltd
- PSA International
- CMA CGM Group(CCIS)
- China COSCO Shipping Corporation Limited
- Sinotrans Limited
- Rail Cargo Group
- GEODIS
- Gati Limited
- Gateway Distriparks Limited
- Adani Logistics Group
- Gulftainer
- Grindrod Logistics
- duisport
- Inland Terminals Group
- Logistics International Limited
- Multiterminais Group
Read Analysis of Inland Container Depot and Dry Port Companies
Recent Industry Developments in Inland Container Depot and Dry Port Market
- July 2026: CONCOR commissioned Dedicated Line No. 7 at its Multi-Modal Logistics Park (MMLP), Dadri, and flagged off India's first Double Stack Reefer Container Train to Jawaharlal Nehru Port Authority (JNPA). The new rail infrastructure enables simultaneous train operations at the 105-hectare Dadri facility, reduces congestion in the yard, and extends temperature-controlled inland-to-port logistics capability to pharmaceutical and perishable exporters in North India.
- June 2026: Gulftainer and the Sharjah Ports, Customs and Free Zones Authority unveiled the Al Dhaid Multi-Modal Trade Corridor, a 150-hectare public-private partnership facility 50 km from Khorfakkan Port, with a planned annual capacity of 1.5 million TEUs and direct Etihad Rail connectivity. The facility, together with the Sajaa Dry Port, creates 2.3 million TEUs of combined inland logistics capacity in Sharjah, positioning the emirate as a dry port hub for the wider GCC region.
- May 2026: AD Ports Group, CMA Terminals Khalifa Port, and CMA CGM Group signed a Memorandum of Understanding to co-develop intermodal solutions and extend CMA CGM's inland logistics reach across the UAE and wider region through AD Ports Group's consolidated rail-linked inland container depot and dry port network. The agreement integrates CMA CGM's carrier services with the inland freight corridor anchored at Khalifa Port.
- April 2026: Maersk announced investments in two Southern Brazil inland logistics facilities, a 70,000 m² multipurpose depot in Rio Grande, Rio Grande do Sul, located 2.5 km from the port and designed for dry and reefer container handling, empty storage, and cross-docking, and a 3,160 m² expansion of its Cargo Services area in Paranagua, Parana, focused on agricultural export and refrigerated cargo flows. Both facilities support the Alianca Navegacao e Logistica cabotage network, deepening Maersk's inland-to-port integration in Southern Brazil.
Global Inland Container Depot and Dry Port Market Report Scope
Segmentation Overview
| Storage Services |
| Container Handling |
| Customs Clearance and Documentation |
| Intermodal Transfer |
| Other Value-added Services |
| General Dry Containers |
| Refrigerated Containers |
| Specialized Containers |
| Publicly Owned and Operated |
| Privately Owned and Operated |
| Public-Private Partnership |
| North America | United States |
| Canada | |
| Mexico | |
| South America | Brazil |
| Argentina | |
| Peru | |
| Chile | |
| Rest of South America | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Spain | |
| Russia | |
| Nordics (Denmark, Finland, Iceland, Norway, and Sweden) | |
| Rest of Europe | |
| Asia-Pacific | China |
| India | |
| Japan | |
| South Korea | |
| Australia | |
| Southeast Asia (ASEAN) | |
| Rest of Asia-Pacific | |
| Middle East and Africa | Saudi Arabia |
| United Arab Emirates | |
| Qatar | |
| South Africa | |
| Nigeria | |
| Egypt | |
| Rest of Middle East and Africa |
| By Service | Storage Services | |
| Container Handling | ||
| Customs Clearance and Documentation | ||
| Intermodal Transfer | ||
| Other Value-added Services | ||
| By Container Type | General Dry Containers | |
| Refrigerated Containers | ||
| Specialized Containers | ||
| By Ownership and Operating Model | Publicly Owned and Operated | |
| Privately Owned and Operated | ||
| Public-Private Partnership | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| South America | Brazil | |
| Argentina | ||
| Peru | ||
| Chile | ||
| Rest of South America | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Spain | ||
| Russia | ||
| Nordics (Denmark, Finland, Iceland, Norway, and Sweden) | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| India | ||
| Japan | ||
| South Korea | ||
| Australia | ||
| Southeast Asia (ASEAN) | ||
| Rest of Asia-Pacific | ||
| Middle East and Africa | Saudi Arabia | |
| United Arab Emirates | ||
| Qatar | ||
| South Africa | ||
| Nigeria | ||
| Egypt | ||
| Rest of Middle East and Africa | ||
Key Questions Answered in the Report
What is driving growth in inland container depots and dry ports?
Higher container volumes, coastal port congestion, rail-linked freight corridors, and digital customs systems support demand for inland facilities.
How large is the inland container depot and dry port market in 2026?
The sector is valued at USD 32.59 billion in 2026 and will reach USD 42.50 billion by 2031 at a 5.45% CAGR.
Which service is growing fastest at inland container depots?
Other value-added services is growing fastest at a 7.16% CAGR through 2031, supported by reefer support, repair, and customs-related activity.
Why are refrigerated containers important for dry port operators?
Refrigerated Containers are growing at a 7.23% CAGR through 2031 and require dedicated power, monitoring, and handling capability.
Which region has the highest growth rate through 2031?
Asia-Pacific records the highest regional CAGR at 7.48%, supported by Indian freight corridors and manufacturing growth in Southeast Asia.
What are the main risks for inland container depot operators?
Major risks include high capital costs, gaps in first- and last-mile links, regulatory complexity, and uneven container availability.