
Carpet Cleaning Products Market Size and Share
Market Overview
| Study Period | 2026 - 2032 |
|---|---|
| Market Size (2027) | USD 2.24 Billion |
| Market Size (2032) | USD 2.89 Billion |
| Growth Rate (2027 - 2032) | 5.23 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Carpet Cleaning Products Market Analysis by Mordor Intelligence
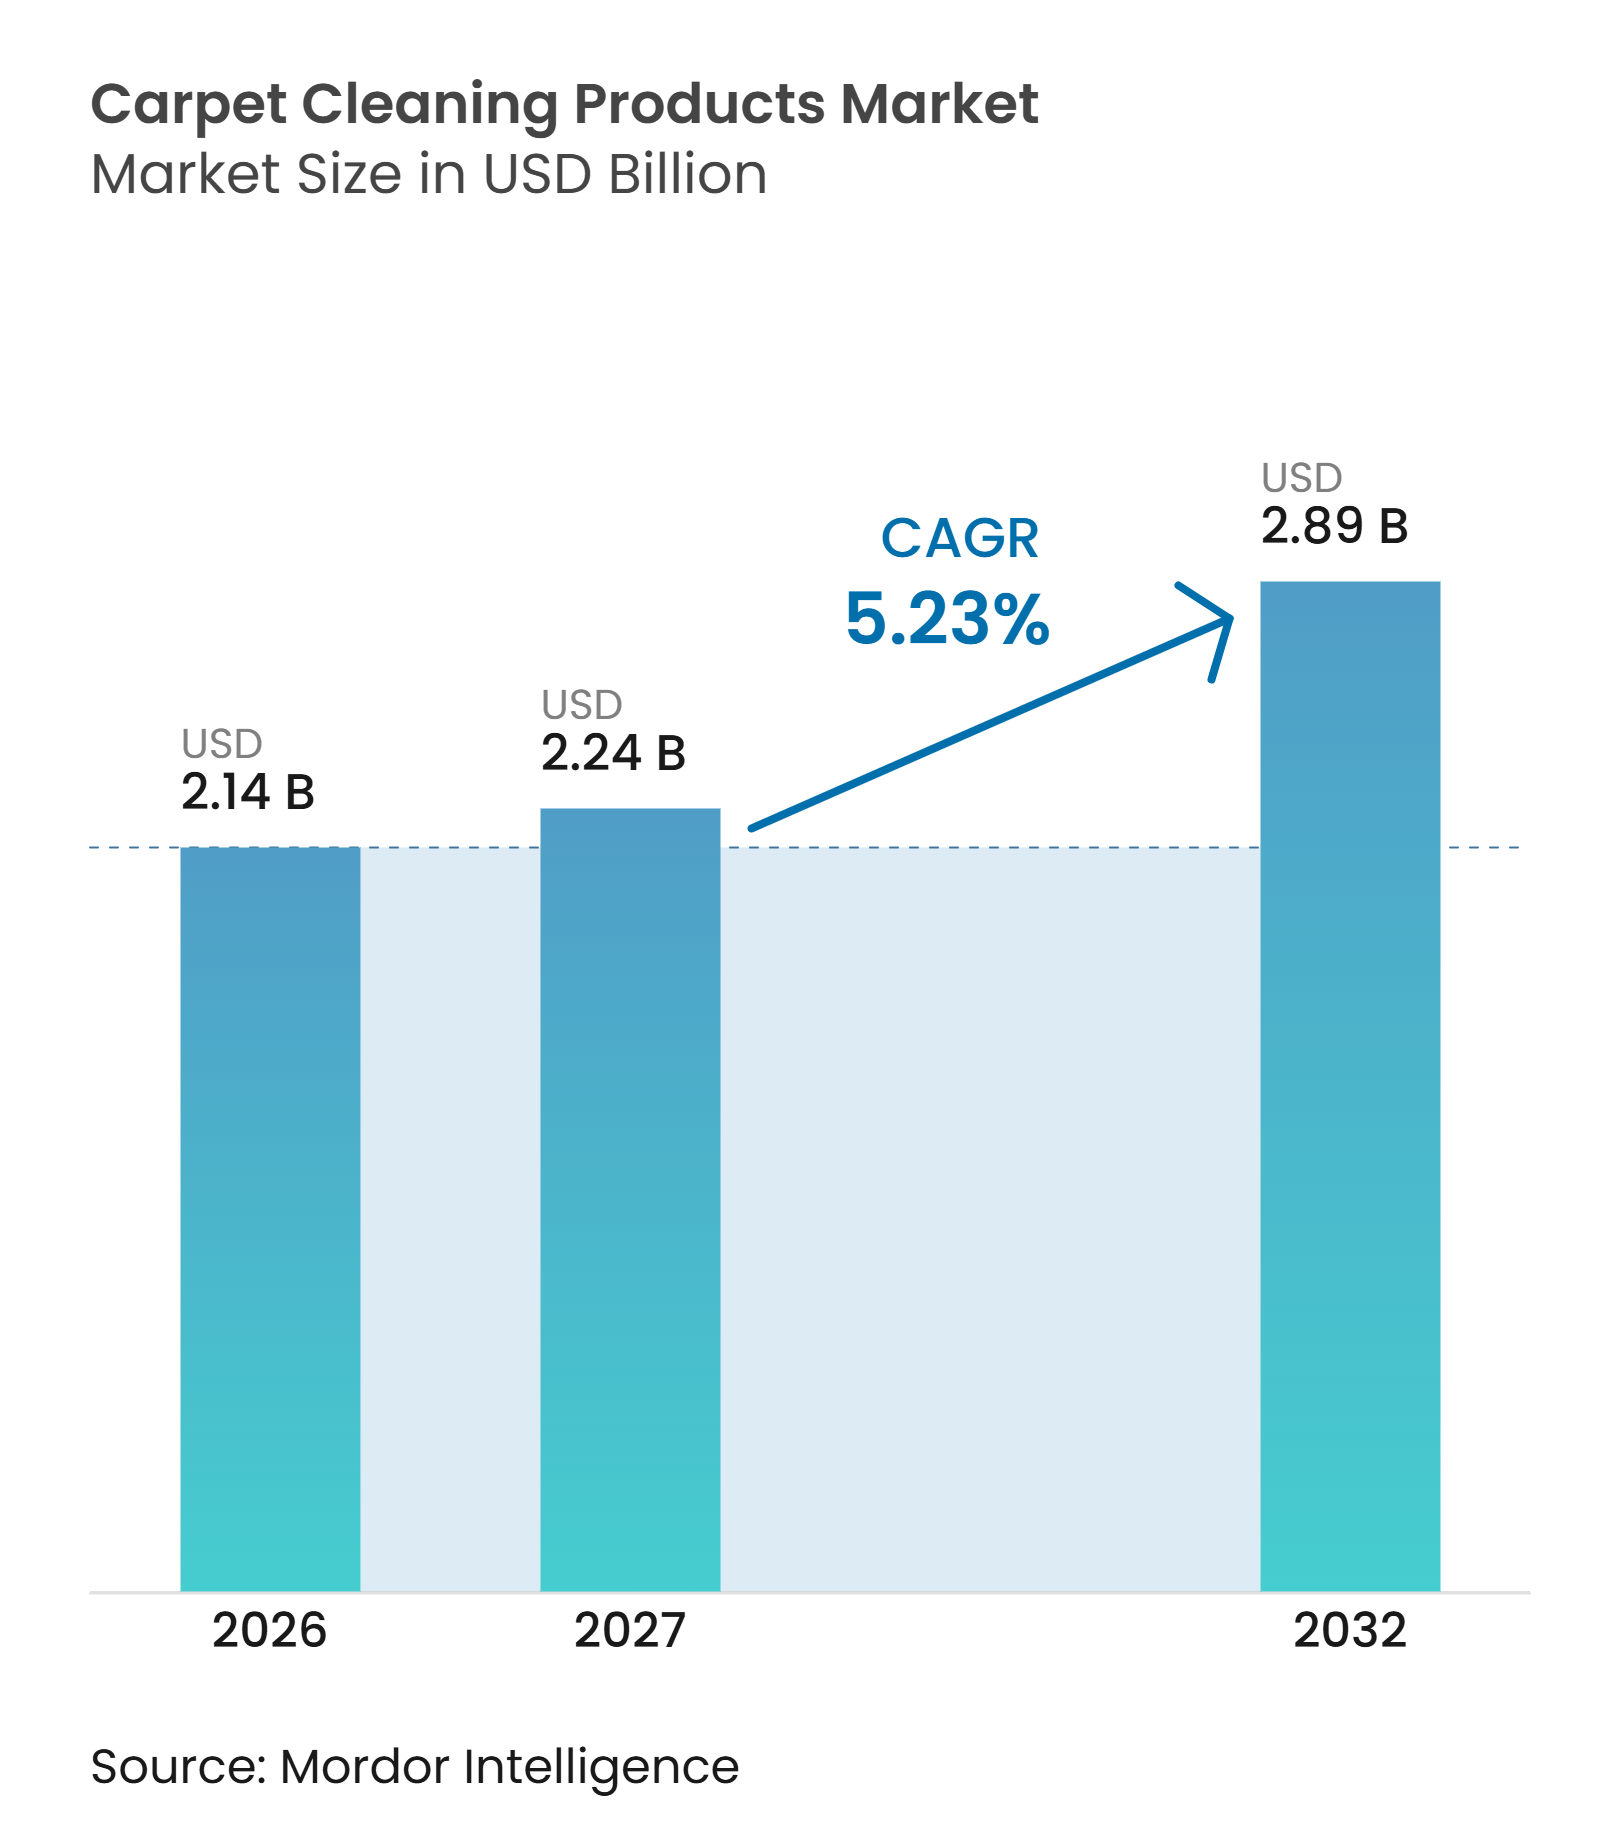
The carpet cleaning products market size is expected to increase from USD 2.14 billion in 2026 to USD 2.24 billion in 2027 and reach USD 2.89 billion by 2032, growing at a CAGR of 5.23% over 2027-2032. The carpet cleaning products market is supported by household attention to hygiene, pet-related cleaning needs, and repeat purchasing by commercial facilities. In a 2025 survey, 97% of U.S. adults said cleaning is important to public health, and 74% reported changing cleaning habits to improve health outcomes, according to the American Cleaning Institute[1]. The category is also moving toward low-residue, low-VOC, and enzyme-based formulations as buyers weigh cleaning performance against indoor-air and ingredient concerns. Commercial buyers continue to favor products that work with their equipment and meet recognized product standards. Hard-flooring substitution remains a constraint, but carpet tile, area rugs, and carpeted hospitality and office spaces continue to require regular cleaning.
Key Report Takeaways
-
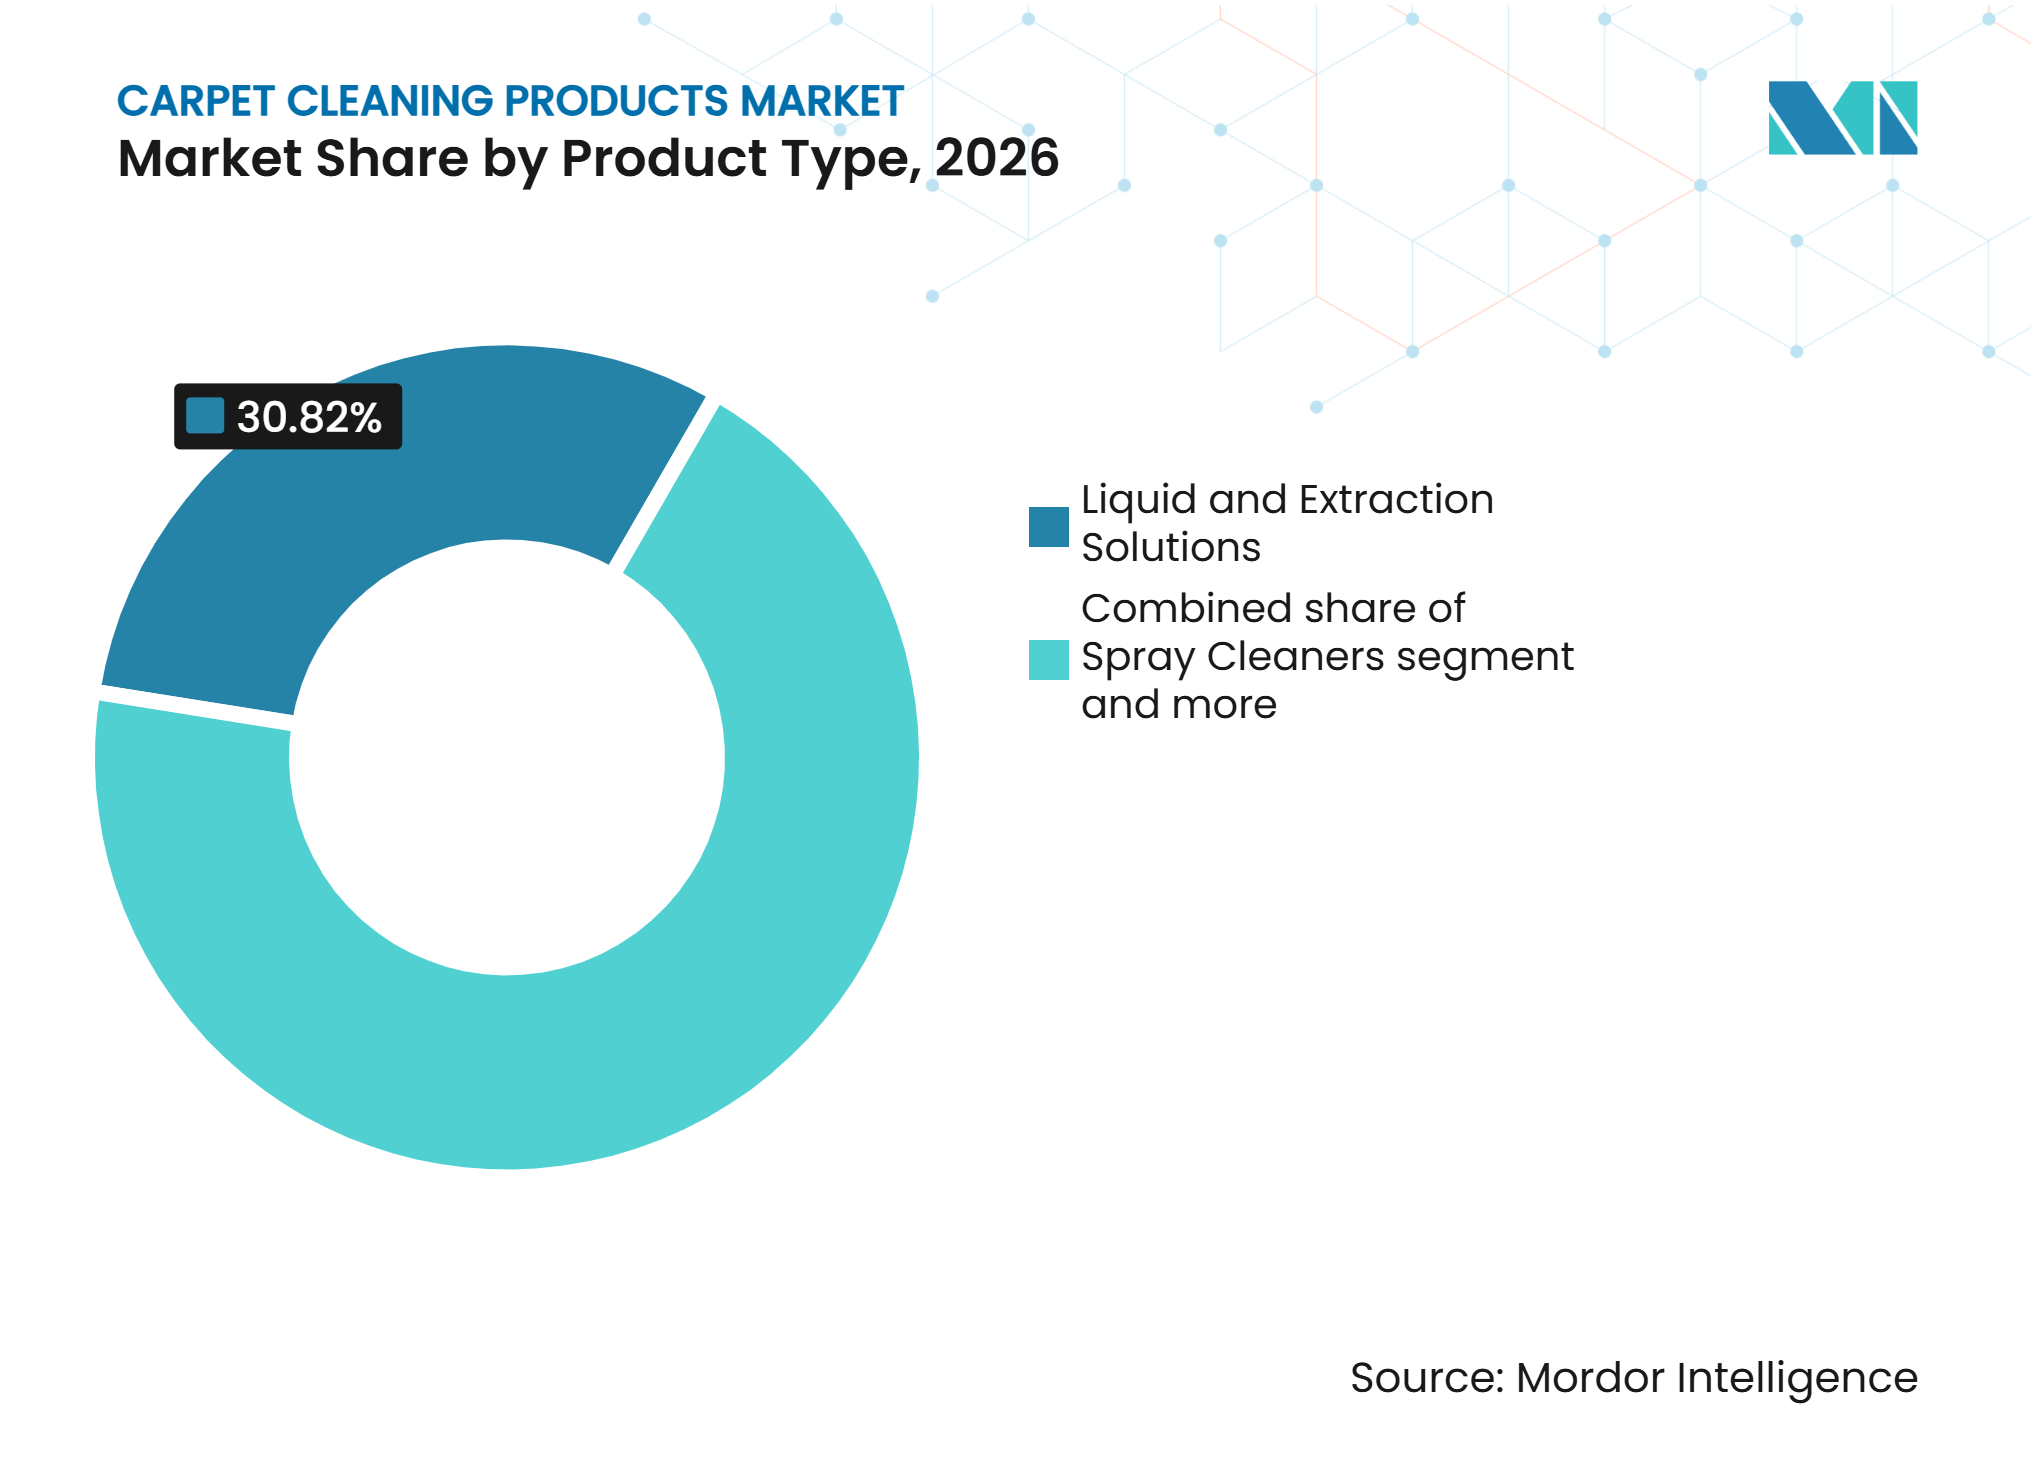
By product type, Liquid and Extraction Solutions accounted for the largest share of the carpet cleaning products market, at 30.82% in 2026, while Spray Cleaners are projected to grow at the fastest CAGR of 6.34% during 2027-2032.
-
By nature, Conventional products accounted for the largest share of the carpet cleaning products market, at 60.36% in 2026, while Organic and Natural products are projected to grow at the fastest CAGR of 7.82% during 2027-2032.
-
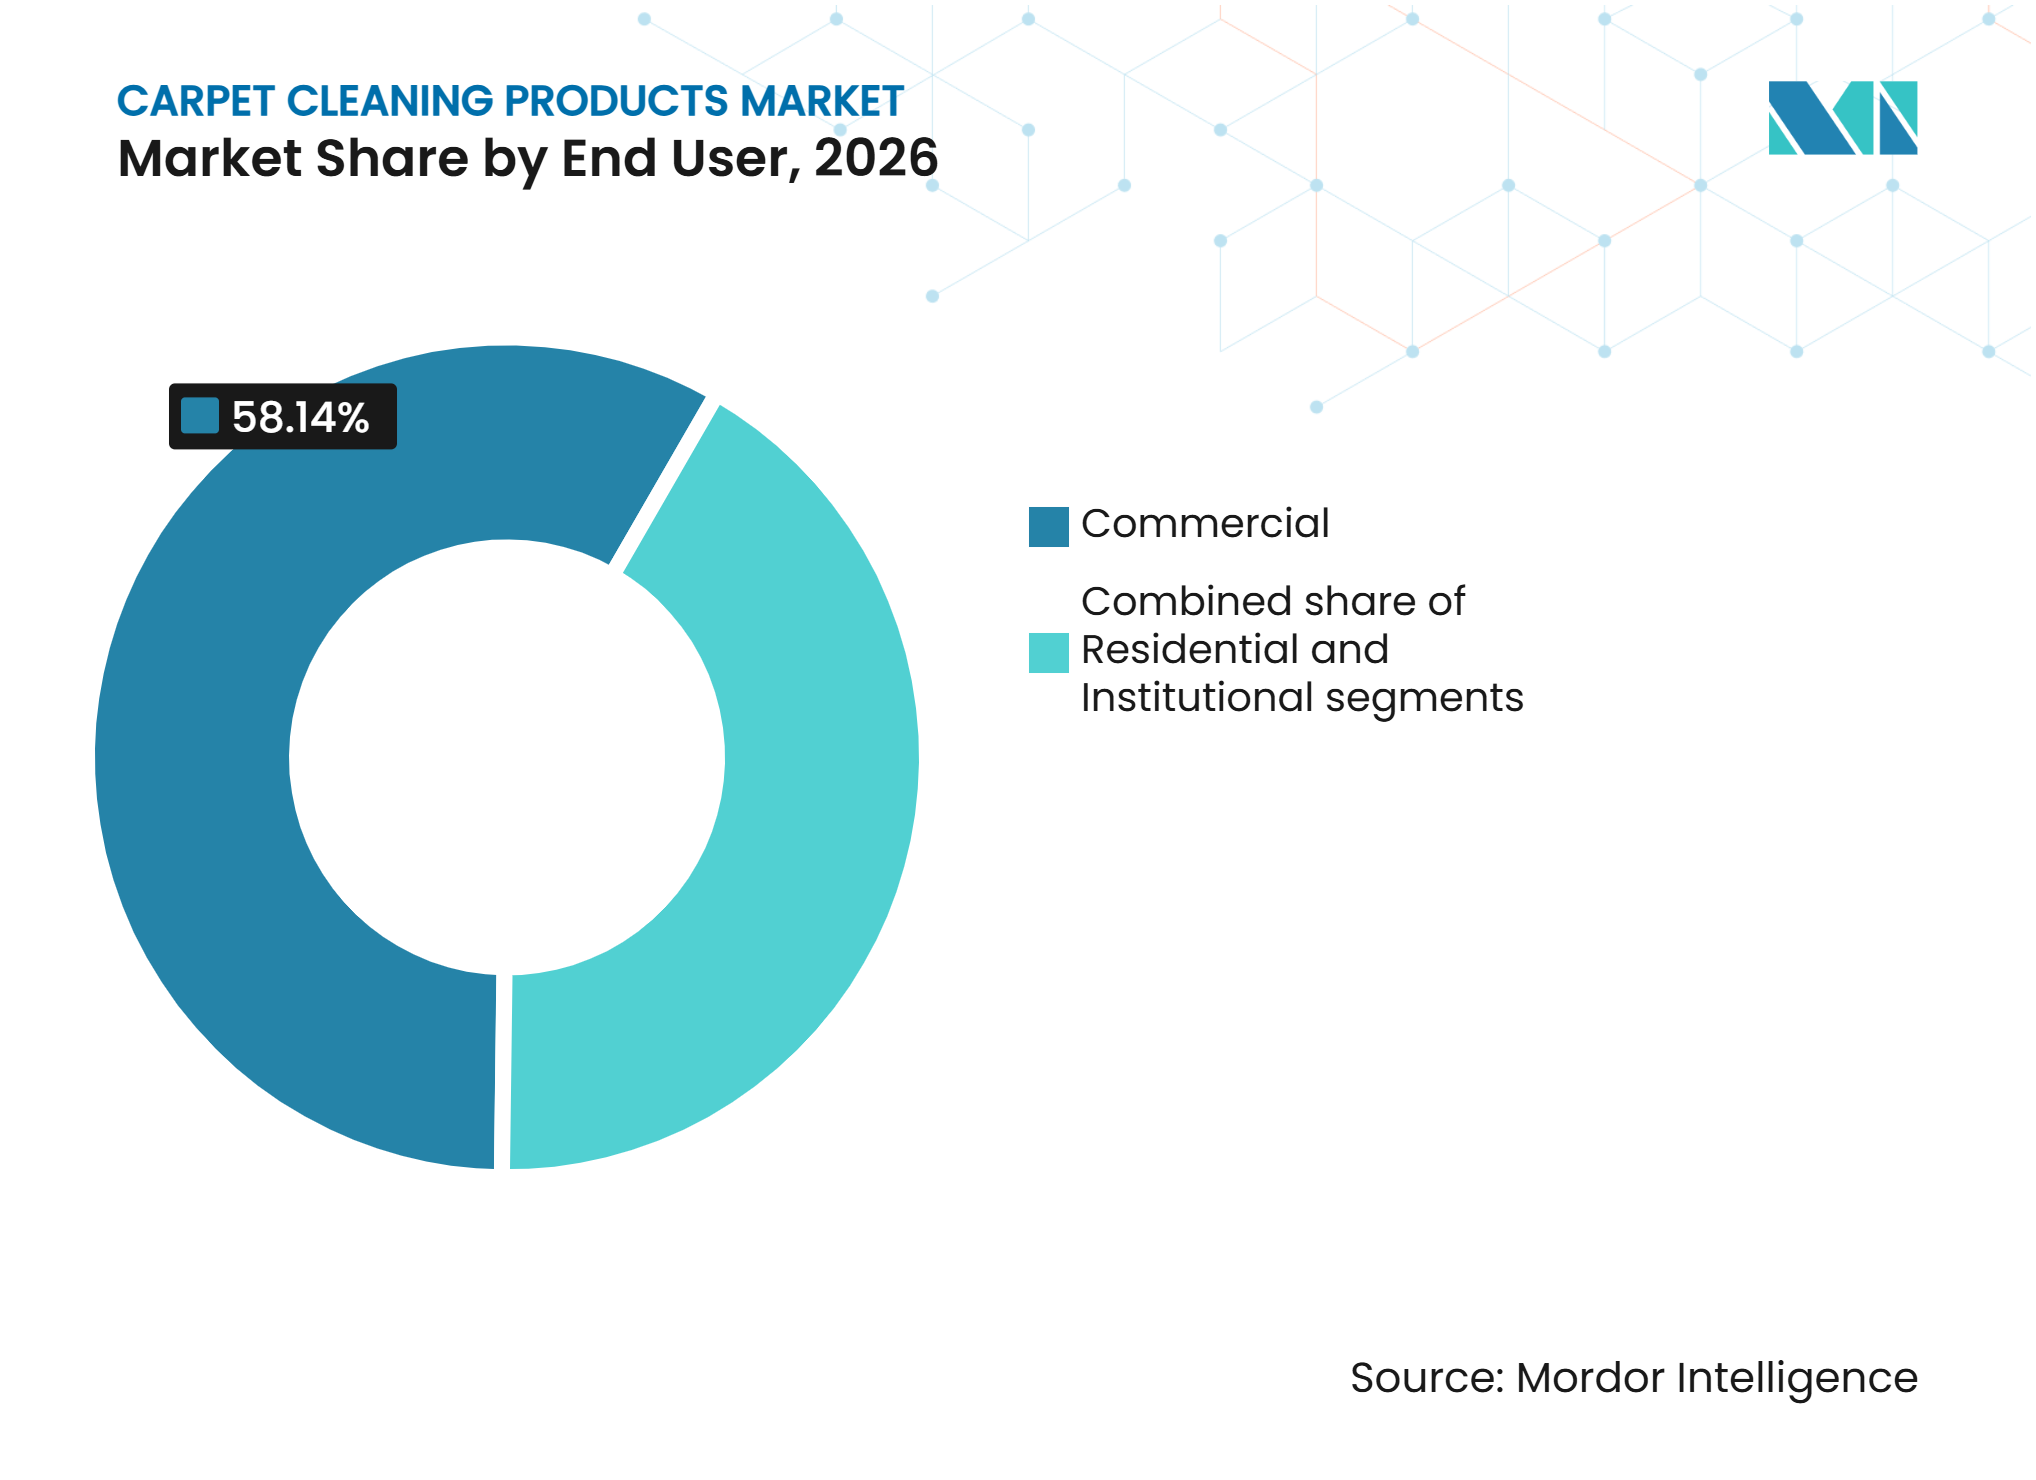
By end user, Commercial users accounted for the largest share of the carpet cleaning products market, at 58.14% in 2026, while Residential users are projected to grow at the fastest CAGR of 6.58% during 2027-2032.
-
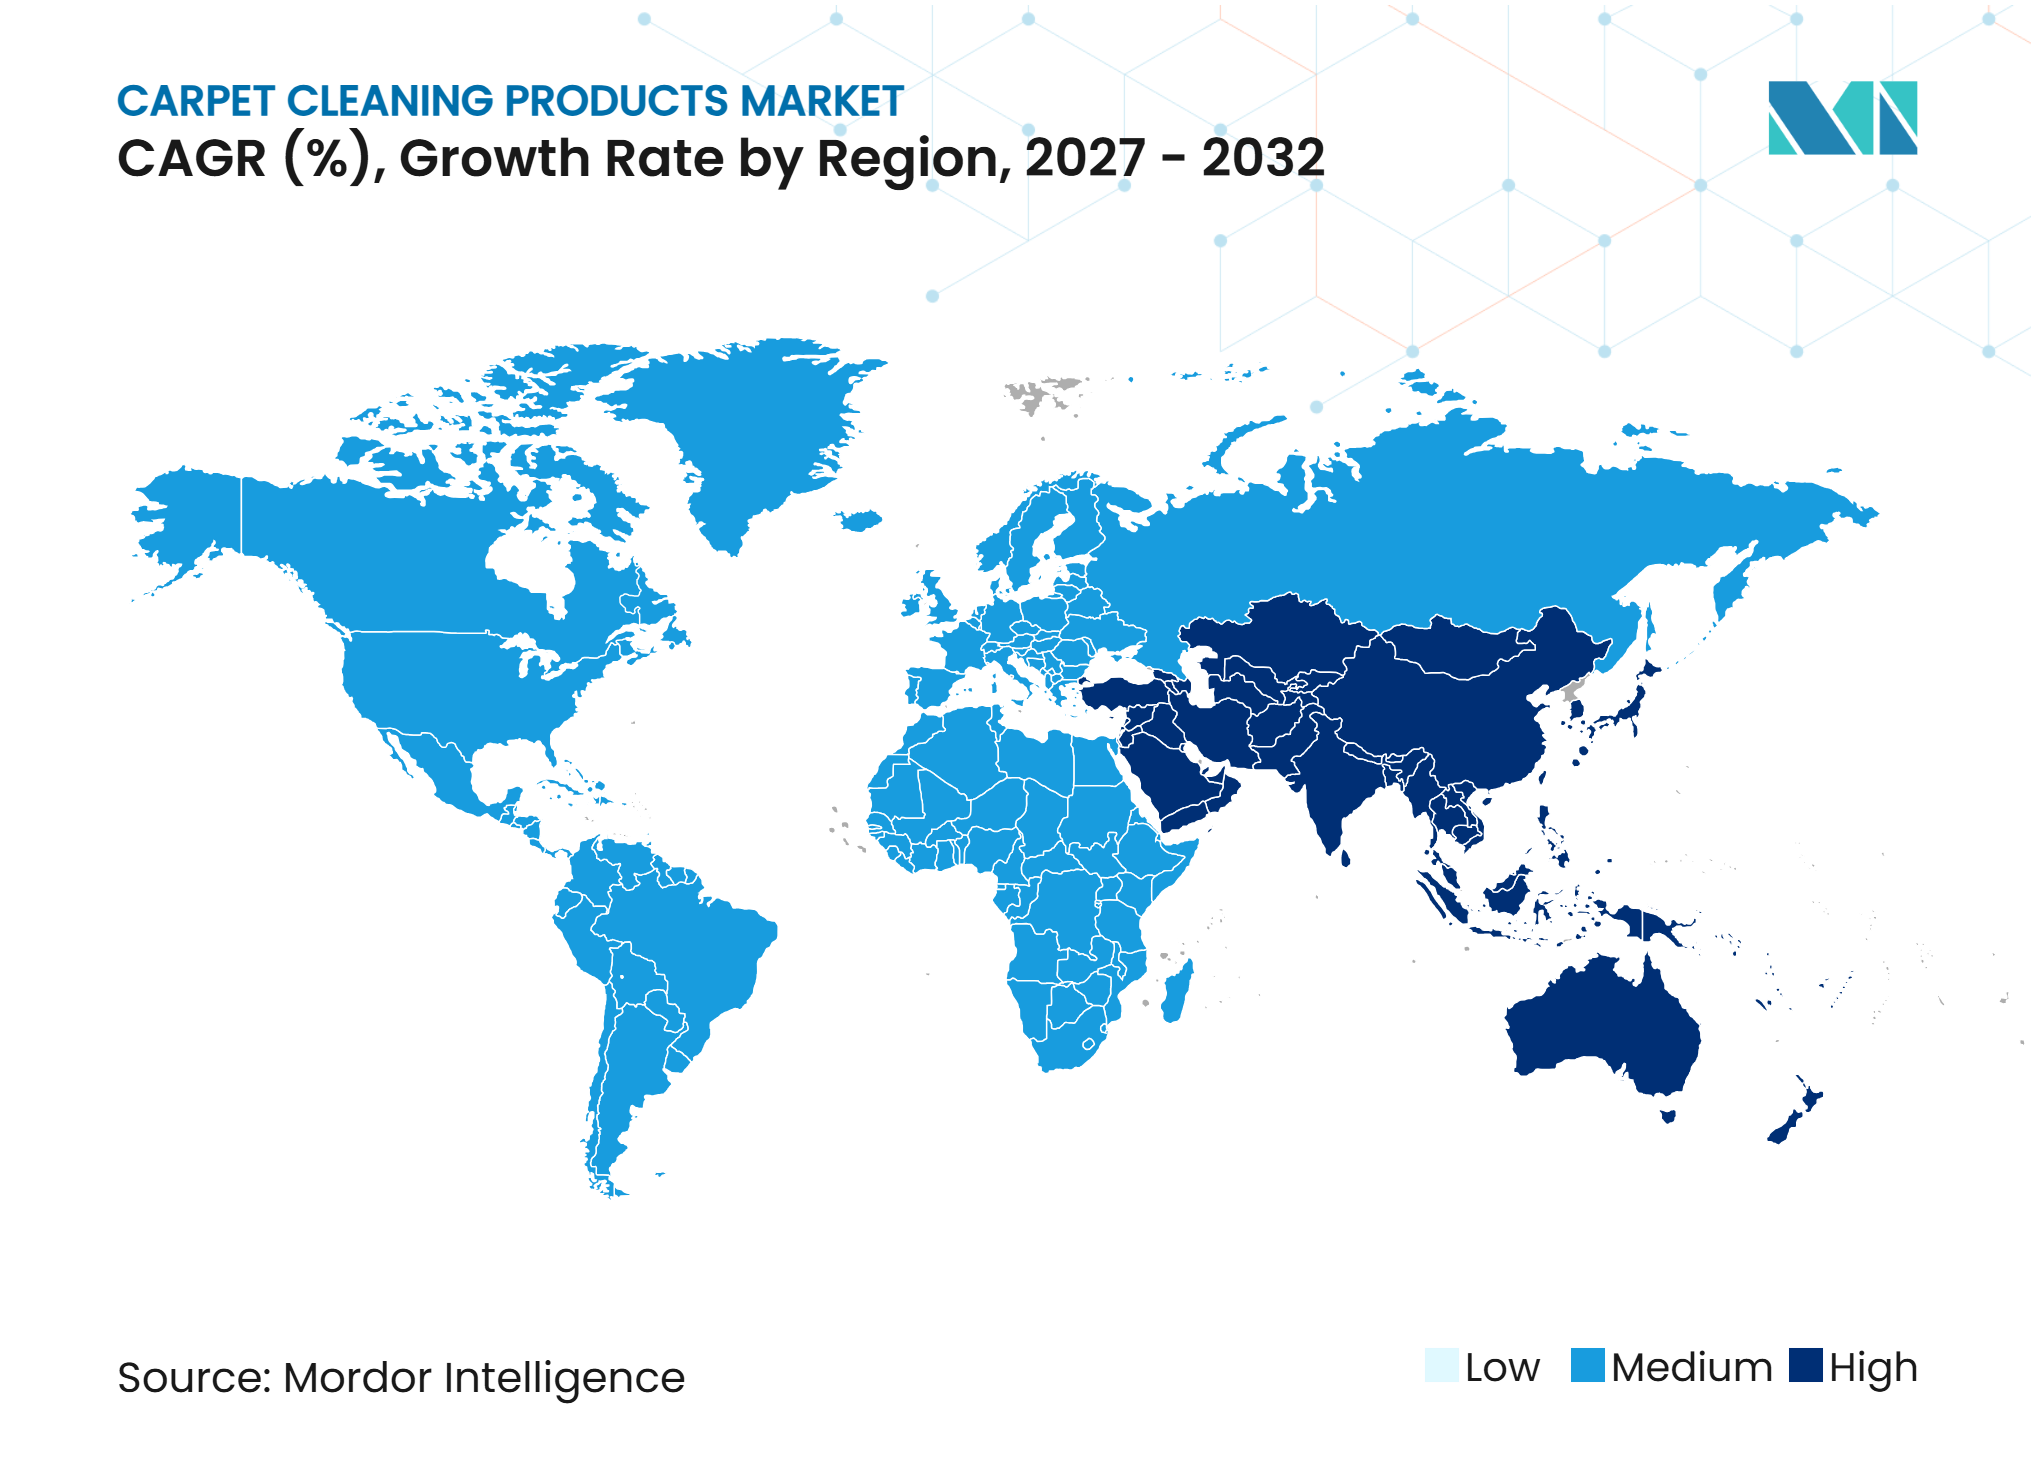
By geography, North America accounted for the largest share of the carpet cleaning products market, at 36.70% in 2026, while Asia-Pacific is projected to grow at the fastest CAGR of 6.78% during 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Carpet Cleaning Products Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Household Hygiene and Indoor Air Quality Awareness | +1.1% | Global, led by North America and Western Europe | Short term (≤ 2 years) |
| Rising Pet Ownership and Pet-Related Stain Events | +1.0% | North America, Western Europe, Australia | Medium term (2-4 years) |
| Hospitality and Commercial Facility Maintenance Demand | +0.9% | Global, strongest in Asia-Pacific and Middle East hospitality corridors | Medium term (2-4 years) |
| E-Commerce Availability and Subscription Replenishment | +0.8% | North America, Europe, East Asia | Medium term (2-4 years) |
| Low-Moisture and Water-Saving Cleaning Adoption | +0.6% | North America, Europe, water-stressed Asia-Pacific markets | Medium term (2-4 years) |
| Enzyme-Based and Multifunctional Formulation Innovation | +0.8% | Global, led by North America and Japan | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Household Hygiene and Indoor Air Quality Awareness
Household hygiene is supporting the carpet cleaning products market because cleaning is increasingly linked with health management rather than appearance alone. The American Cleaning Institute found in 2025 that 91% of Americans associate cleaning with improved physical health outcomes according to American Cleaning Institute. Research published in Environmental Science & Technology found that carpet-cleaner use can emit compounds including 2-butoxyethanol, with higher indoor concentrations persisting for days after cleaning, as per the American Chemical Society. This evidence reinforces demand for formulations that address cleaning needs while limiting residues and volatile emissions. Products with credible low-VOC claims or EPA Safer Choice certification can therefore hold greater appeal for households focused on indoor environments. The carpet cleaning products market benefits when brands make these attributes clear without reducing cleaning efficacy.
Rising Pet Ownership and Pet-Related Stain Events
Pet ownership creates recurring demand for products designed to treat stains and odors on carpets and upholstery. The American Pet Products Association reported that 94 million U.S. households owned at least 1 pet in 2024, compared with 82 million in 2023. The association also reported that Gen Z pet-owning households rose 43.5% year over year, and 70% of Gen Z pet owners had 2 or more pets[2]. Pet stains frequently require more targeted treatment than general surface cleaning. Enzyme-based cleaners use ingredients such as protease, lipase, and urease to break down organic matter rather than merely cover odors. This supports a shift toward specialized, pet-safe formulations that can increase purchase frequency and raise the value of household baskets in the carpet cleaning products market.
Hospitality and Commercial Facility Maintenance Demand
Hotels, offices, health care facilities, and retail spaces require regular carpet maintenance to meet operating and guest-experience standards. Commercial buyers often prefer concentrated formats that work with extraction equipment and can be used consistently across multiple locations. Product certification also matters in these channels because procurement teams may seek recognized performance or material-compatibility standards. The Carpet and Rug Institute Seal of Approval and WoolSafe certification can influence product selection where carpets represent a material asset. In the carpet cleaning products market, this favors suppliers that can combine product chemistry, technical guidance, and dependable distribution. It also allows established suppliers to compete on performance and service rather than price alone.
Enzyme-Based and Multifunctional Formulation Innovation
Enzyme-based innovation is broadening the performance proposition of carpet care products. In 2025, Unilever introduced Cif Infinite Clean, a probiotic-enhanced product range that uses live bacterial cultures to release enzymes on soiled surfaces after application. The product approach shows how cleaning formulations can be designed to provide residual activity after use. Kärcher Japan also introduced RM 764N CarpetPro Natural Cleaning Agent in 2025, combining naturally derived ingredients with biodegradable surfactants and WoolSafe certification. Such launches show that cleaner ingredient profiles and performance claims are becoming more closely connected. The carpet cleaning products market can gain from this shift when innovations meet the needs of both professional operators and households.
Restraints Impact Analysis of Carpet Cleaning Products Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Substitution by Hard Flooring Materials | -0.9% | North America, Europe, and Asia-Pacific urban markets | Long term (≥ 4 years) |
| Chemical, VOC, and Wastewater Compliance Costs | -0.5% | North America, European Union, and global markets | Medium term (2-4 years) |
| Raw-Material and Packaging Cost Volatility | -0.6% | Global, including palm-oil-dependent Asia-Pacific supply chains | Medium term (2-4 years) |
| Performance Trade-Offs in Low-Residue and Bio-Based Formulations | -0.4% | Global | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Substitution by Hard Flooring Materials
Hard flooring remains a long-term restraint because it reduces the installed carpet base that requires recurring cleaning. Luxury vinyl tile and other hard surfaces are attractive to building owners because they can be durable and easier to maintain in high-traffic spaces. The effect is particularly relevant in residential and commercial refurbishment projects where flooring choices can change at replacement. This shift does not eliminate carpet cleaning demand because hospitality, offices, senior living facilities, area rugs, and carpet tile still require specialized maintenance. Carpet also retains practical benefits related to acoustics, thermal comfort, and fall safety in some applications. The carpet cleaning products market therefore faces a gradual change in addressable flooring stock rather than a sudden loss of demand.
Chemical, VOC, and Wastewater Compliance Costs
Compliance requirements can add development, testing, and sourcing costs for cleaning product manufacturers. The U.S. Environmental Protection Agency extended the compliance date for amendments to national VOC emission standards for aerosol coatings to January 17, 2027[3]. International Sanitary Supply Association updated VOC compliance guidance in October 2025 to reflect California's expanded product categories and Oregon's pending Phase V rule. These requirements can be more difficult for smaller formulators that have limited internal product-development resources. Compliance factors may also require reformulation, validation, and changes to supplier relationships. The carpet cleaning products market can see greater competitive pressure when companies must improve environmental profiles while maintaining stain-removal performance.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Carpet Cleaning Products Market Segment Analysis
By Product Type:
Liquid Formats Lead While Sprays Grow FasterLiquid and Extraction Solutions accounted for 30.82% of 2026 revenue. Their position reflects strong demand from professional cleaning contractors and facility managers who use hot-water extraction equipment. Concentrated liquids can offer controlled dosing and lower cost per use for high-volume cleaning programs. They are commonly selected for use across hotels, offices, retail premises, and other locations with repeated carpet cleaning needs. Compatibility with extraction equipment is also important because operators seek products that fit established equipment and maintenance procedures. These operating requirements reinforce the position of liquid formats in the carpet cleaning products market.
Spray Cleaners are forecast to grow at a 6.34% CAGR from 2027 to 2032, the fastest rate among product types. Ready-to-use packaging supports spot treatment and routine maintenance by residential users. The format is well suited to pet stains, spills, and other small cleaning events that require fast action. Spray products also fit e-commerce purchasing because they are easy to understand and use without professional equipment. Brands can use enzyme-based and low-residue claims to differentiate spray offerings for households. Growth in this format is likely to remain linked to convenience, pet ownership, and demand for targeted cleaning.



By Nature:
Conventional Products Retain Scale While Organic and Natural Products AdvanceConventional products accounted for 60.36% of 2026 revenue. Their scale is supported by established efficacy expectations, broad retail availability, and lower formulation costs than many bio-derived alternatives. Professional users may select these products because their performance has been tested in demanding settings. The Carpet and Rug Institute Seal of Approval remains a relevant reference point for products used on carpeted surfaces. Conventional formulas also have an extensive installed base among commercial operators and households. This gives the segment a durable position even as ingredient preferences change.
Organic and Natural products are forecast to grow at a 7.82% CAGR from 2027 to 2032, the highest rate in the nature segmentation. Demand is supported by household interest in lower-residue and pet-safe options, as well as regulatory attention to chemical ingredients. Kärcher Japan launched RM 764N CarpetPro Natural Cleaning Agent in April 2025 as the first carpet cleaning product certified under Japan's Eco Mark Category No. 167 for cleaning materials. The formulation uses more than 99% naturally derived ingredients and 100% biodegradable surfactants, while carrying WoolSafe certification. Its introduction shows how certification can support the professional natural segment. This part of the carpet cleaning products industry is likely to benefit when suppliers match ingredient standards with proven cleaning performance.
By End User:
Commercial Demand Leads While Residential Use ExpandsCommercial users held 58.14% of the carpet cleaning products market share in 2026. Hotels, corporate offices, health care facilities, retail sites, and institutional buildings need recurring cleaning under formal maintenance programs. Large facilities often buy through distributors or supply agreements, which helps maintain regular purchasing patterns. These customers may require concentrated formats, product training, and compatibility with extraction equipment. Certification and product documentation can also affect selection in institutional settings. The commercial segment therefore provides a stable demand base for the carpet cleaning products market.
Residential users are forecast to grow at a 6.58% CAGR from 2027 to 2032, the fastest rate among end users. Pet ownership, allergen concerns, and greater availability of ready-to-use products support repeat household purchases. These households show interest in enzyme-based, pet-safe, and low-residue formulations. The residential channel includes a premium tier of differentiated products and a value tier of mass-market offerings. This segmentation allows brands to serve different needs while preserving broad household access.

Geography Analysis
North America: Installed Carpet Base Supports Regional Leadership
North America held 36.70% of the carpet cleaning products market share in 2026. The region has a large installed base of carpeted residential and commercial interiors, which supports demand for regular cleaning and stain-treatment products. The United States is a mature category where consumers recognize branded carpet care products and professional services. Commercial facilities also purchase concentrated products through distributors and direct supply arrangements. Regulatory influence is becoming more prominent as federal and state requirements encourage lower-VOC product development. The U.S. Environmental Protection Agency's 2025 action on VOC standards and ISSA's 2025 guidance illustrate the compliance factors shaping formulation decisions. Digital retail also gives newer brands a route to reach households alongside established suppliers. The region continues to favor products that combine cleaning efficacy with low-residue and pet-safe positioning.
Asia-Pacific: Construction and Digital Retail Support Faster Expansion
Asia-Pacific is projected to grow at a 6.78% CAGR from 2027 to 2032, making it the fastest-growing regional segment. The carpet cleaning products market size in the region is supported by hotel and office development, urban household formation, and broader retail access in China, India, and Southeast Asia. Hotels and corporate facilities provide a growing professional channel for products compatible with commercial equipment. Demand is also shifting toward water-based and biodegradable formulations in markets where environmental product rules are becoming more visible. Japan, South Korea, and Australia offer premium opportunities where certification and performance standards can support higher-value products. India and Southeast Asia expand the household opportunity as urban incomes and modern retail access grow. These dynamics give the region a broader base for future demand.
Europe, South America, and Middle East and Africa: Distinct Commercial Opportunities
Europe is shaped by chemical compliance, established hospitality demand, and buyer interest in eco-labeled formulations. The European Union's REACH framework is a key compliance factor for suppliers serving the region. Germany, the United Kingdom, France, and the Nordic countries have established professional cleaning channels, while Southern and Eastern Europe offer scope for greater commercial adoption. South American demand is concentrated in Brazil and Argentina, where urban service activity supports cleaning needs but cost volatility can affect purchasing. Middle East and Africa demand is linked to high-specification hospitality and mixed-use developments, especially in Gulf Cooperation Council countries. Hotel and convention infrastructure creates demand for professional products that maintain carpet appearance and drying times. South Africa and Turkey remain relatively established commercial markets within the region. Across these regions, the carpet cleaning products market benefits most when suppliers align product performance with local procurement and compliance requirements.
Competitive Landscape
Market Concentration
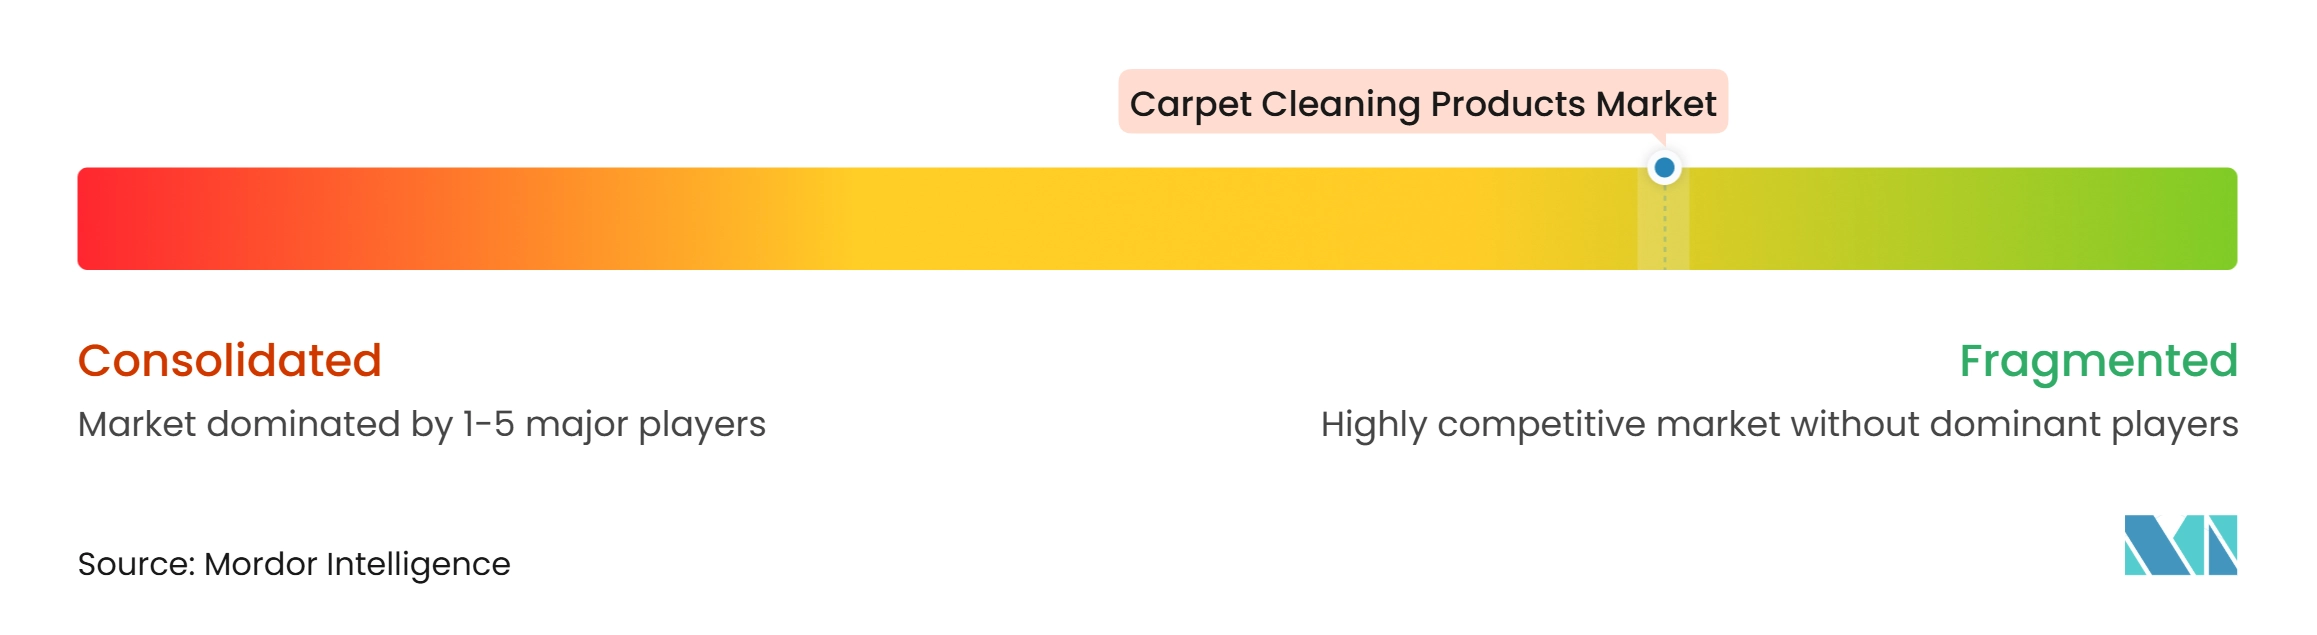
The carpet cleaning products market includes diversified consumer goods companies, professional-channel chemical suppliers, private-label manufacturers, and newer direct-to-consumer brands. BISSELL, Reckitt, Clorox, Ecolab, Church & Dwight, and Diversey compete through brand recognition, product portfolios, formulation capabilities, and channel relationships. The market does not show evidence in the supplied material of a small group controlling a dominant combined share. Large suppliers often compete through performance, format innovation, and distribution rather than price alone. BISSELL connects cleaning solutions with its machine portfolio, which can build repeat use across hardware and chemistry. Ecolab extends professional cleaning credibility across its product range and retail channels.
Product certification can shape competition in professional and institutional channels. The Carpet and Rug Institute Seal of Approval and WoolSafe certification can influence purchasing where operators must protect carpet assets or meet material-care requirements. These standards create a practical advantage for suppliers that can validate product performance. Kärcher Japan's 2025 Eco Mark-certified natural cleaning agent shows how certification can support product differentiation in the professional segment. Low-moisture formats, enzyme-based products, and low-residue formulas remain areas where suppliers can distinguish their offerings. Companies that combine product documentation, technical support, and distribution remain well positioned with commercial buyers.
Strategic activity also shows the value placed on digitally native and specialized cleaning brands. In May 2026, Church & Dwight acquired Miss Mouth's Messy Eater for USD 325 million, adding a fast-acting, non-toxic, multi-surface stain-removal brand to its fabric-care portfolio. In November 2025, Ecolab expanded its Home Depot partnership into Canada, making its Scientific Clean line available in more than 180 stores and online. In September 2026, BISSELL launched the Revolution ExpressClean upright carpet cleaner, emphasizing pet-mess cleaning and a 30-minute dry-time claim. These moves show that companies are investing in product convenience, retail availability, and targeted household needs. The carpet cleaning products market remains open to specialist brands that establish product credibility and distribution reach.
Carpet Cleaning Products Industry Leaders
-
BISSELL Inc.
-
Reckitt
-
The Clorox Company
-
Zep Inc.
-
Techtronic Industries Co. Ltd.
- *Disclaimer: Major Players sorted in no particular order
Carpet Cleaning Products Market Companies Covered in this Report
- BISSELL Inc.
- Reckitt
- The Clorox Company
- Zep Inc.
- Techtronic Industries Co. Ltd.
- Alfred Karcher SE & Co. KG
- Tennant Company
- Nilfisk Holding A/S
- Rug Doctor LLC
- Sprayway Inc.
- Ecolab Inc.
- Church & Dwight Co., Inc.
- ACDOCO LTD
- Cleancare Australia
- Stanley Steemer International, Inc.
- Chem-Dry
- Cleanfix Reinigungssysteme AG
- Koblenz Electrica S.A. de C.V.
- Diversey, Inc.
- Nyco Products Company
Recent Industry Developments in Carpet Cleaning Products Market
- September 2026: BISSELL Inc. launched the Revolution® ExpressClean upright carpet cleaner at a suggested retail price of USD 229.99. The product is available on Amazon.com and BISSELL.com, with distribution expanding to Walmart, Target, and Lowe's. Targeting pet-owning households, the cleaner offers two modes: Max Clean and Express Clean. The Express Clean mode dries carpets in approximately 30 minutes. The product also features an antimicrobial brush roll and a self-cleaning Clean Out Cycle.
- May 2026: Church & Dwight Co., Inc. acquired the Miss Mouth's Messy Eater® brand for approximately USD 325 million. The brand, the No. 1 stain remover on Amazon, targets Millennial and Gen Z parents with fast-acting, non-toxic, multi-surface spot-removal products, complementing Church & Dwight's ARM & HAMMER and OxiClean fabric-care portfolio.
- January 2026: Clorox Company launched the Clorox™ PURE™ Allergen Neutralizer product line, introducing a Fabric & Carpet Spray that neutralizes pet dander, pollen, and dust mite proteins using a plant-based active ingredient with Aller-Fresh™ Technology. The line is available at Walmart and Amazon in 4 fragrances. This product marks Clorox's entry into daily allergen management on soft surfaces, an adjacent position to its traditional disinfection portfolio.
- April 2025: Alfred Kärcher SE & Co. KG, Kärcher Japan, launched the RM 764N CarpetPro Natural Cleaning Agent, the first carpet cleaning product to receive Eco Mark certification under Japan's newly established Category No. 167 Cleaning Materials standard. The formulation comprises more than 99% naturally derived ingredients, 100% biodegradable surfactants, and carries WoolSafe certification. It is designed for use with Kärcher's Puzzi and BRC carpet extraction machines.
Global Carpet Cleaning Products Market Report Scope
Segmentation Overview
| Liquid and Extraction Solutions |
| Spray Cleaners |
| Powders |
| Others (Foams, carpet deodorizers and more) |
| Conventional |
| Organic and Natural |
| Residential |
| Commercial |
| Institutional |
| North America | United States |
| Canada | |
| Mexico | |
| Rest of North America | |
| Europe | Germany |
| United Kingdom | |
| Italy | |
| France | |
| Spain | |
| Netherlands | |
| Belgium | |
| Sweden | |
| Rest of Europe | |
| Asia-Pacific | China |
| India | |
| Japan | |
| Australia | |
| Indonesia | |
| South Korea | |
| Rest of Asia-Pacific | |
| South America | Brazil |
| Argentina | |
| Colombia | |
| Rest of South America | |
| Middle East and Africa | South Africa |
| Saudi Arabia | |
| United Arab Emirates | |
| Turkey | |
| Rest of Middle East and Africa |
| By Product Type | Liquid and Extraction Solutions | |
| Spray Cleaners | ||
| Powders | ||
| Others (Foams, carpet deodorizers and more) | ||
| By Nature | Conventional | |
| Organic and Natural | ||
| By End User | Residential | |
| Commercial | ||
| Institutional | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| Rest of North America | ||
| Europe | Germany | |
| United Kingdom | ||
| Italy | ||
| France | ||
| Spain | ||
| Netherlands | ||
| Belgium | ||
| Sweden | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| India | ||
| Japan | ||
| Australia | ||
| Indonesia | ||
| South Korea | ||
| Rest of Asia-Pacific | ||
| South America | Brazil | |
| Argentina | ||
| Colombia | ||
| Rest of South America | ||
| Middle East and Africa | South Africa | |
| Saudi Arabia | ||
| United Arab Emirates | ||
| Turkey | ||
| Rest of Middle East and Africa | ||